
 Water-Soluble Paints Market | 2026-2036
Water-Soluble Paints Market Size, Share, and Industry Trends Forecast 2026-2036
Water-Soluble Paints Market Outlook
Aftermarket service revenue is reshaping margin capture in the Water-Soluble Paints Market as manufacturers extend beyond product sales into color-matching platforms and applied coating services. Axalta Coating Systems leverages its global refinish network to anchor recurring revenue streams in automotive repair channels. BASF SE differentiates through captive supply of acrylic dispersions, controlling raw material quality from resin synthesis to finished paint. Asian Paints dominates India's decorative coatings segment with deep distribution into tier-two and tier-three cities.
Water-soluble paints are aqueous coating systems where pigment particles remain suspended in a water-based continuous phase, typically incorporating acrylic, alkyd, or polyurethane resin dispersions with volatile organic compound levels below regulatory thresholds; they cure through water evaporation followed by polymer coalescence, delivering adhesion and durability for interior and exterior substrates. Acrylic formulations lead product type demand owing to their balance of weatherability, color retention, and cost efficiency across architectural and industrial end uses. The industrial application segment is expanding fastest as OEMs in automotive and furniture manufacturing convert spray lines from solvent-borne to water-borne systems to comply with emissions mandates.
EPA VOC regulations in the United States, REACH in Europe, and China's MEE emission standards collectively constrain solvent-based formulation, redirecting R&D investment toward water-borne polymer innovation and low-temperature curing technologies. ISO 11890 and ASTM D6886 provide harmonized test methods for VOC content determination, enabling cross-border product certification and reducing technical barriers to trade. Stakeholders must monitor regulatory divergence between jurisdictions while building formulation flexibility that accommodates both current limits and anticipated tightening of allowable emissions thresholds.
Market Dynamics
Regulatory compression on volatile organic compound emissions is forcing wholesale reformulation across coating supply chains, with water-borne resin systems displacing solvent-based architectures in automotive OEM lines and architectural applications.
Growth Catalysts
- China's MEE emission standards:Tightening VOC limits under the dual carbon policy framework are mandating water-borne conversions in industrial coating facilities across the Pearl River and Yangtze River manufacturing belts.
- Automotive OEM spray line conversions:Tier-one suppliers in Germany and Japan are retrofitting solvent-borne application systems to water-borne polyurethane dispersions for vehicle body coating.
- India's urban housing expansion:Government infrastructure programs and tier-two city development are expanding addressable demand for decorative water-based architectural coatings.
Market Restraints
- Petrochemical feedstock volatility:Acrylic acid and styrene monomer price swings compress margin predictability for dispersion manufacturers in the US Gulf Coast and Rotterdam refining clusters.
- Cold-weather curing limitations:Water-borne alkyd systems exhibit extended drying times below 10°C, restricting year-round application in Nordic and North American construction markets.
- Specialty additive import concentration:Rheology modifiers and coalescing aids concentrate among Japanese and German chemical suppliers, creating input bottlenecks during trade friction episodes.
Strategic Opportunities
- India's tier-three distribution penetration:Decorative coating demand in smaller urban centers remains underpenetrated relative to saturation in Mumbai and Delhi metropolitan corridors.
- Low-temperature curing technology convergence:Hybrid UV-thermal curing systems for water-borne industrial coatings enable energy reduction and line speed improvements in furniture manufacturing.
- EU Green Deal renovation wave:Building energy retrofit mandates are accelerating demand for low-VOC exterior architectural coatings across German and French residential stock.
Industry Challenges
- Formulation chemist scarcity:Expertise in water-borne polymer colloid stability and film formation kinetics remains concentrated among aging technical workforces in European and North American coating centers.
- ISO 11890 certification timelines:VOC content verification protocols require extended laboratory turnaround, delaying product launches in jurisdictions with harmonized testing requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Water-Soluble Paints Market |
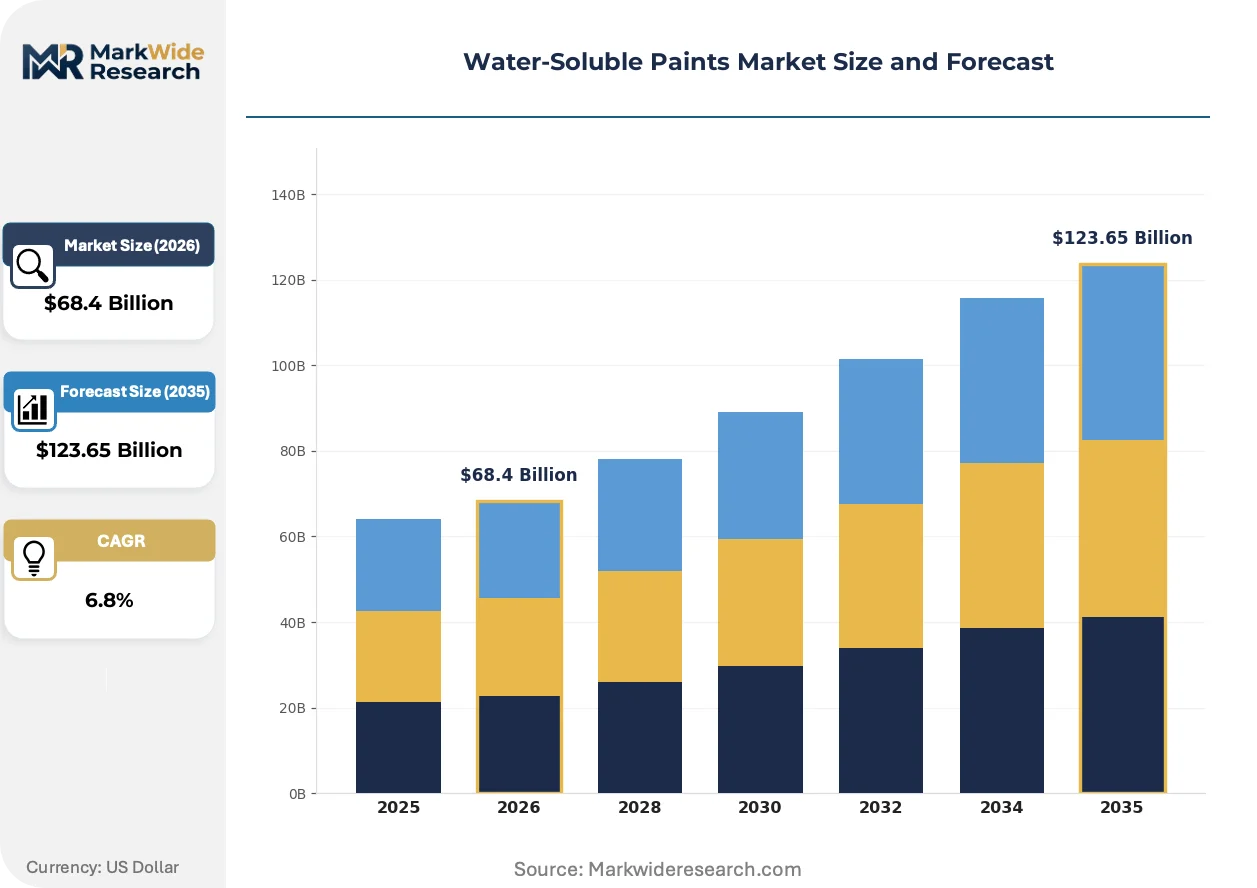
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $123.65 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acrylic, Tempera, Gouache, Watercolor Application: Fine Arts, Crafts, Education, Industrial Packaging Type: Tubes, Jars, Bottles, Pouches End User: Artists, Schools, Hobbyists, Manufacturers |
| Companies Covered | Axalta Coating Systems, Nippon Paint Holdings Co. Ltd., AkzoNobel N.V., Asian Paints, RPM International Inc., PPG Industries Inc., BASF SE, Kansai Paint Co. Ltd., The Sherwin-Williams Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Water-Soluble Paints Market Strategic Shifts
Water-borne coating technology is advancing along three vectors: curing energy reduction, bio-based feedstock integration, and applied service bundling that extends manufacturer-customer relationships beyond product shipment.
Self-crosslinking acrylic dispersion technology is collapsing the performance gap between water-borne and solvent-borne industrial coatings. Automotive OEMs in Stuttgart and Toyota City are qualifying these systems for clearcoat applications previously reserved for 2K polyurethane solvent systems. The technology is collapsing capital requirements for conversion by eliminating separate crosslinker metering equipment.
REACH authorization procedures for chromium-based corrosion inhibitors are restricting formulation options for protective coatings serving European marine and infrastructure sectors. Coating manufacturers are accelerating trivalent chromium and organic inhibitor substitutions in primer formulations. The industrial maintenance segment is absorbing compliance costs through specification upgrades in German offshore wind and Dutch water management infrastructure.
Specification authority is migrating from general contractors to coating applicator networks with certified water-borne system expertise. Large-scale architectural projects in California and New South Wales now require approved applicator status for warranty coverage. The shift concentrates demand among technically qualified contractor networks and compresses spot-market purchasing for undifferentiated product.
Water-Soluble Paints Market Segmentation
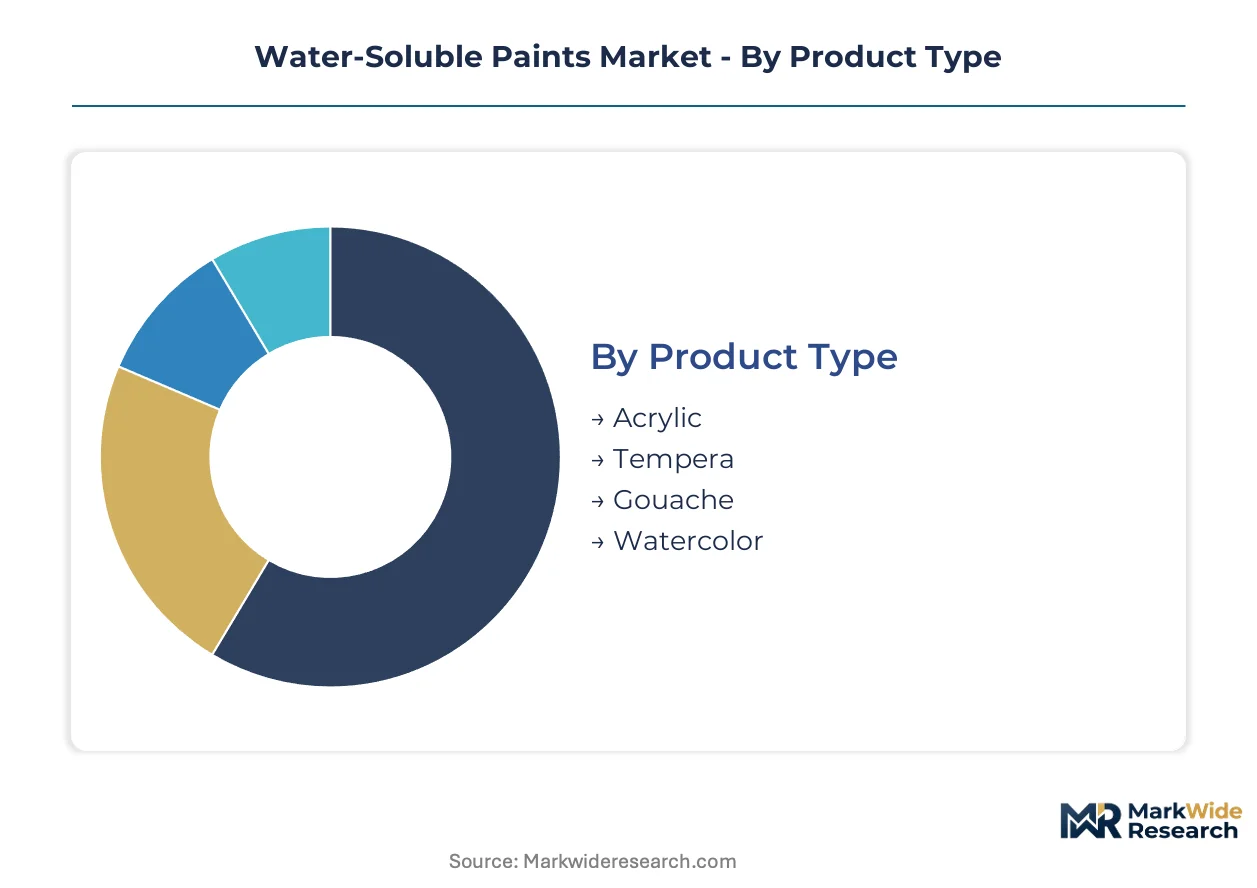
Water-soluble paint segmentation reveals divergent technical requirements between fine arts consumption and industrial coating applications. Product chemistry, packaging format, and procurement channel all reshape margin structures and distribution economics across these distinct demand pools.
Product Type:
Cost tier differentiation separates professional-grade formulations from student and craft-oriented alternatives, with resin quality and pigment load determining price positioning.
- Acrylic:Polymer emulsion systems incorporating acrylic resin dispersions deliver rapid drying and flexible film formation. Demand concentrates in architectural coatings across China's Pearl River manufacturing belt, where MEE emission standards mandate water-borne conversions in industrial facilities.
- Tempera:Egg-based or synthetic emulsion binders yield matte, opaque finishes with excellent color saturation. Fine arts applications in Italian restoration workshops and North American educational institutions sustain specialized pigment sourcing networks.
- Gouache:Opaque watercolor formulations with added chalk or white pigment provide high covering power for illustration and design work.
- Watercolor:Transparent pigment suspensions in gum arabic binders serve traditional painting techniques requiring luminosity and layering control.
Acrylic commands the established base. The steepest expansion runs through industrial-grade acrylic dispersions.
Application:
Volume concentration varies dramatically between intermittent consumer purchases and continuous industrial consumption, reshaping supply chain design and customer relationship economics.
- Fine Arts:Professional-grade pigments with lightfastness ratings and archival stability specifications serve museum-quality production. European ateliers and Japanese nihonga practitioners drive premium pigment demand with exacting color matching requirements.
- Industrial:High-volume coating systems for automotive OEM lines and furniture manufacturing require batch consistency and low-temperature curing compatibility. German automotive suppliers in Stuttgart and Toyota City manufacturing complexes are qualifying water-borne polyurethane clearcoats.
- Crafts:Hobby and decorative applications prioritize cost efficiency over archival performance.
- Education:Institutional procurement through school districts and university art programs emphasizes safety certification and bulk pricing.
Fine arts maintains margin leadership through specification authority. Industrial applications are climbing the fastest as OEM spray line conversions accelerate.
Packaging Type:
Customer type and usage frequency dictate format selection, with professional studios favoring precision dispensing and industrial users prioritizing volume efficiency.
- Tubes:Aluminum or laminated squeeze tubes enable precise color dispensing and air exclusion for professional artists. French and German fine arts suppliers dominate tube manufacturing with specialized sealing technologies.
- Jars:Wide-mouth containers accommodate brush access for heavy-body acrylics and gesso preparations. North American craft retailers and Asian architectural coating distributors both utilize jar formats for distinct viscosity ranges.
- Bottles:Flip-top or pump dispensers serve fluid acrylics and ink formulations.
- Pouches:Flexible laminate packaging reduces shipping cube and material cost for bulk educational and craft supply.
Tubes anchor professional artist loyalty. Pouches are gaining share fastest in institutional procurement channels.
End User:
Geography and procurement authority separate fragmented individual purchasing from concentrated institutional buying, with distinct service requirements and pricing negotiations.
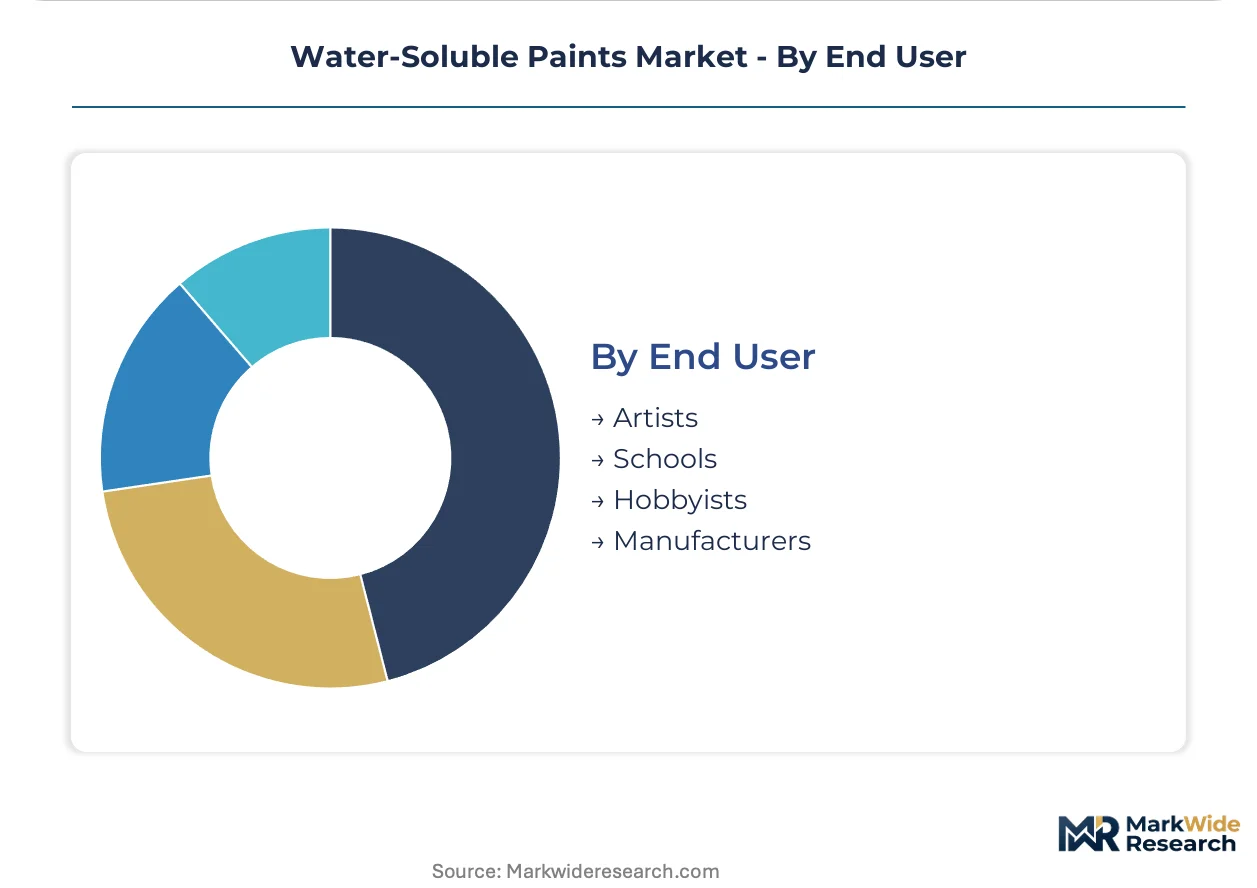
- Artists:Professional and amateur practitioners purchasing through specialty retailers or direct-to-consumer channels demand color consistency and technical support. Mumbai and Delhi metropolitan corridors concentrate India's decorative coating specification authority, while European ateliers drive premium pigment innovation.
- Schools:K-12 and higher education institutions procure through centralized purchasing with safety certification and volume discount requirements. California and New South Wales architectural specifications now mandate approved applicator networks for warranty coverage.
- Hobbyists:Casual craft consumers purchase through mass retail and e-commerce with price sensitivity and impulse-driven selection.
- Manufacturers:Industrial coating operations integrate water-borne systems into automated spray lines with technical service dependencies.
Artists retain specification influence in premium tiers. Manufacturers are expanding most quickly as regulatory mandates drive solvent-to-water conversions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across geographies. India's tier-two and tier-three buyers prioritize cost efficiency in decorative coatings. German automotive OEMs absorb premium pricing for water-borne clearcoats that meet exacting durability specifications.
China
Urban housing expansion and infrastructure investment sustain decorative coating consumption. The Ministry of Ecology and Environment (MEE) enforces tightening VOC emission standards under dual carbon policy frameworks. Manufacturing clusters in the Pearl River Delta and Yangtze River Delta are converting solvent-borne industrial coating lines to water-borne resin systems.
India
Government infrastructure programs and tier-two city development expand addressable demand for architectural coatings. Bureau of Indian Standards (BIS) certification requirements shape product formulation standards. Mumbai and Delhi metropolitan corridors concentrate specification authority, while distribution networks penetrate smaller urban centers.
Germany
Automotive OEM spray line conversions drive industrial-grade water-borne polyurethane demand. REACH authorization procedures restrict chromium-based corrosion inhibitors in protective coatings. Stuttgart manufacturing complexes qualify self-crosslinking acrylic dispersions for vehicle body clearcoat applications.
United States
Residential construction recovery and building energy retrofit mandates sustain architectural coating consumption. EPA VOC regulations constrain solvent-based formulation across coating categories. California architectural specifications now require approved applicator network certification for warranty coverage on large-scale projects.
Japan
Automotive and furniture manufacturing OEMs retrofit spray lines to comply with emissions mandates. METI industrial policy supports low-temperature curing technology development. Toyota City manufacturing complexes are qualifying water-borne polyurethane systems previously reserved for solvent-borne applications.
Water-Soluble Paints Market Competitive Environment
Capability concentration sits with specialty resin manufacturers; scale advantage sits with diversified chemical conglomerates. The market structures around three tiers: integrated resin-to-coating manufacturers, regional formulation specialists, and automotive refinish network operators. Strategic moves center on captive supply chain control and certified applicator network expansion.
Among integrated chemical manufacturers, BASF SE exemplifies the resin-captive archetype through backward integration into acrylic dispersion synthesis. Asian Paints occupies a position as the dominant decorative coating distributor in India's tier-two and tier-three penetration. Axalta Coating Systems anchors the automotive refinish segment through global service network coverage.
| Leading Market Players |
|---|
| Axalta Coating Systems |
| Nippon Paint Holdings Co. Ltd. |
| AkzoNobel N.V. |
| Asian Paints |
| RPM International Inc. |
| PPG Industries Inc. |
| BASF SE |
| Kansai Paint Co. Ltd. |
| The Sherwin-Williams Company |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in China's Yangtze River Delta dispersion plants is compressing spot pricing for acrylic emulsions while simultaneously accelerating supplier consolidation. MEE enforcement tightens operational margins for smaller producers, forcing either technical upgrades or exit and concentrating pricing power among resin-captive majors.
Pricing Analysis
Aftermarket service revenue tiers anchor lifetime value capture in automotive refinish and architectural specification channels. Three-tier pricing structure across premium, standard, and economy levels separates certified-applicator warranty systems from commodity spot purchases. Cost compression in industrial alkyd formulations is intensifying because petrochemical feedstock volatility compresses margin predictability. Tier-three city distributors in India exhibit highest price sensitivity, while German automotive OEMs absorb premium clearcoat pricing for MEE-compliant durability specifications.
Supply Chain Analysis
Contract manufacturing concentration sits with Nippon Paint and Kansai Paint facilities across Osaka and Kobe industrial corridors. Acrylic acid and styrene monomer supply concentrates in US Gulf Coast, Rotterdam, and Singapore refining clusters. The chain draws from Japanese and German specialty additive suppliers for rheology modifiers, creating single-source vulnerability during trade friction episodes. Distribution runs through certified applicator networks in California and New South Wales, compressing spot-market purchasing for undifferentiated product.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Water-soluble paints constitute a high-growth disruption as regulatory compression on VOC emissions forces wholesale solvent-to-water conversions across automotive and architectural end uses. China's dual carbon framework and REACH authorization procedures collectively mandate reformulation investment.
For Market Incumbents: Pre-empt specialty additive supply bottlenecks by securing long-term offtake agreements with Japanese and German rheology modifier suppliers. Capture formulation chemist expertise through targeted acquisition of European coating centers before workforce aging accelerates. MEE compliance timelines threaten smaller competitors unable to fund low-temperature curing R&D.
For New Entrants and Emerging Players: India's tier-three distribution penetration represents the most penetrable entry point, with decorative coating demand in smaller urban centers underpenetrated relative to Mumbai and Delhi saturation. Hybrid UV-thermal curing technology for furniture manufacturing offers technical differentiation without confronting established automotive supply relationships. Direct partnership with Asian architectural specifiers bypasses incumbent distributor lock-in.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among automotive refinish network operators with global service coverage. Long-term viability over the projection horizon favors integrated resin-to-coating manufacturers with captive acrylic dispersion synthesis. Monitor ISO 11890 certification backlog lengths as early signal of formulation pipeline congestion and qualification-driven demand inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylic Dispersion | BASF's resin-captive model controls raw material quality from synthesis to finished paint. |
| Certified Applicator Network Expansion | Axalta's global refinish coverage anchors recurring revenue streams in automotive repair channels. |
| Low-Temperature Curing Technology Development | Toyota City OEMs qualify water-borne polyurethane systems previously reserved for solvent architectures. |
| Tier-Three Distribution Penetration | Asian Paints dominates India's decorative segment through deep penetration of smaller urban centers. |
| Green Manufacturing Transition | German offshore wind and Dutch water infrastructure absorb compliance costs through specification upgrades. |
Study Parameters
A standing panel of coating plant managers, automotive OEM procurement leads, architectural specifier networks, and distribution channel partners provided ongoing calibration throughout the study. Primary interview data combined with secondary validation from customs trade records, SEC 10-K filings, and MEE enforcement disclosures. Bottom-up volume modeling triangulated against top-down resin consumption estimates.
Scenario-bracketing framed analytical approach across the analysis window, with segmentation dimensions covering resin chemistry tier, end-use industry vertical, packaging format, and regional regulatory cluster. CAGRs derived from installed base conversion rates and new construction coating intensity coefficients. Forecast inputs incorporated MEE compliance timeline assumptions and REACH authorization procedure impacts.
Practitioners should monitor feedstock price volatility, certification backlog lengths, and applicator network expansion rates for early signals of demand inflection. Quarterly review of ISO 11890 laboratory turnaround times and MEE enforcement intensity indicators is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paints & Coatings
Asia-Pacific Paint Spray Guns Market
Paints & Coatings
Paint and Coating Stripper Market
Paints & Coatings
Furniture Wood Coatings Market
Paints & Coatings
UAE Architectural Paints and Coatings Market
Paints & Coatings
Saudi Arabia Architectural Paints Market
Paints & Coatings
Global Construction Paints and Coatings Market
Paints & Coatings
Faux Paints and Coatings Market
Paints & Coatings
Solar Paint Market
Paints & Coatings
Nordic Countries Architectural Coatings Market
Paints & Coatings
GCC Paints and Coatings Market
Paints & Coatings
Interior Architectural Coatings Market
Paints & Coatings
Paints and Coatings Additives Market
Paints & Coatings
Industrial Paint Booth Market
Paints & Coatings
Morocco Paints and Coatings Market
Paints & Coatings
Small Paint Pail Market
Paints & Coatings
Road Marking Paint Market