
 Global Cellulose Sponge Market | 2026-2036
Global Cellulose Sponge Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cellulose Sponge Market Intelligence
Expertise in sustainable polymer chemistry and biodegradable material science is rotating the basis of competition from pure manufacturing scale to material innovation. Global conglomerate 3M Company leverages its extensive R&D infrastructure to develop specialized sponge variants. In contrast, Corazzi Fiber S.r.l. specializes in non-woven fiber products for cleaning applications. Meanwhile, Kalle GmbH anchors its position in the food-grade segment through deep process knowledge.
A cellulose sponge is a porous, biodegradable cleaning tool manufactured from wood pulp or cotton fiber through the viscose process. This process creates a highly absorbent structure capable of holding up to 20 times its weight in water, making it ideal for cleaning and wiping tasks. While the household cleaning end-use application continues to generate the largest volume, growth is accelerating in specialized segments. Medical Grade and Cosmetic Grade sponges command higher price points due to stringent purity and safety requirements.
Regulations from the US FDA concerning food contact surfaces and the EU's REACH framework for chemical substances govern material safety. In parallel, China's GB standards impose strict quality controls on consumer goods, influencing manufacturing protocols for market entry. Navigating the trade-offs between production cost, material biodegradability, and compliance with divergent international standards remains the central challenge for manufacturers.
Market Dynamics
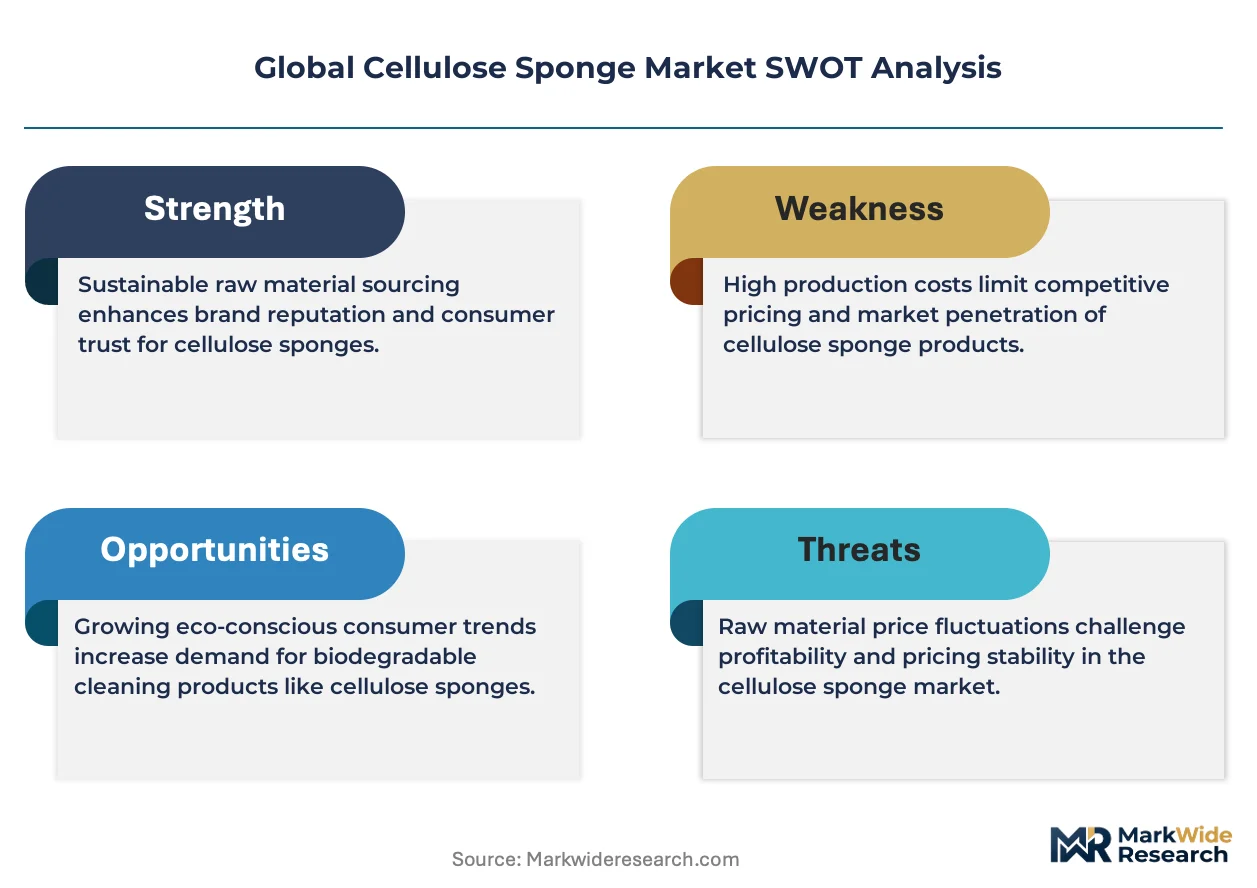
The central dynamic shaping the cellulose sponge market is the tension between escalating global sustainability mandates, exemplified by the EU Green Deal, and the cost pressures inherent in the chemically intensive viscose manufacturing process for wood pulp.
Growth Catalysts
- Healthcare Hygiene Standards:Heightened infection control protocols in healthcare facilities, particularly in rapidly expanding hospital networks in China and India, are driving demand for sterile, single-use cellulose sponges for wound care and surgical preparation.
- Regulatory Push for Biodegradability:Frameworks like the EU Green Deal and similar environmental policies in Japan are creating strong market pull for biodegradable cleaning products, positioning cellulose sponges as a preferred alternative to petroleum-based plastics.
- Food Safety Compliance:Stricter regulations from the US FDA and European Food Safety Authority (EFSA) concerning food contact materials are boosting the adoption of certified food-grade cellulose sponges in food processing and commercial kitchens.
Market Restraints
- Raw Material Price Volatility:The market is exposed to price fluctuations in key inputs like wood pulp and cotton linter, which are subject to global commodity cycles and can compress manufacturer margins. *Substitution by Synthetics: In price-sensitive household segments, lower-cost polyurethane and melamine foam sponges present a significant substitution threat, despite their inferior biodegradability and environmental profile.
- Chemical Process Scrutiny:The traditional viscose process uses hazardous chemicals like carbon disulfide, attracting regulatory scrutiny under frameworks like REACH in Europe, which increases compliance costs and environmental liabilities for producers.
Strategic Opportunities
- Cosmetic and Personal Care Niches:Developing specialized, ultra-pure cellulose sponges for cosmetic applications like makeup removal and exfoliation offers a path to higher margins, leveraging consumer demand for natural and gentle products.
- Industrial Cleaning Applications:There is an opportunity to engineer sponges for specialized industrial tasks, such as cleaning delicate electronic components or absorbing spills in laboratory and manufacturing environments where high purity is critical.
- Emerging Market Penetration:Targeting middle-class consumers in Latin American and Southeast Asian countries with tailored marketing focused on hygiene and environmental benefits can open new volume-driven growth channels.
Industry Challenges
- Navigating Divergent Standards:Manufacturers face the operational challenge of designing and testing products to comply with a complex web of differing international regulations, such as China's GB standards, the EU's REACH, and US FDA rules.
- Certification Timelines and Costs:Obtaining necessary certifications for specialized grades, such as medical device clearance under the EU's MDR or food contact safety approvals, is a time-consuming and expensive process that can delay market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cellulose Sponge Market |
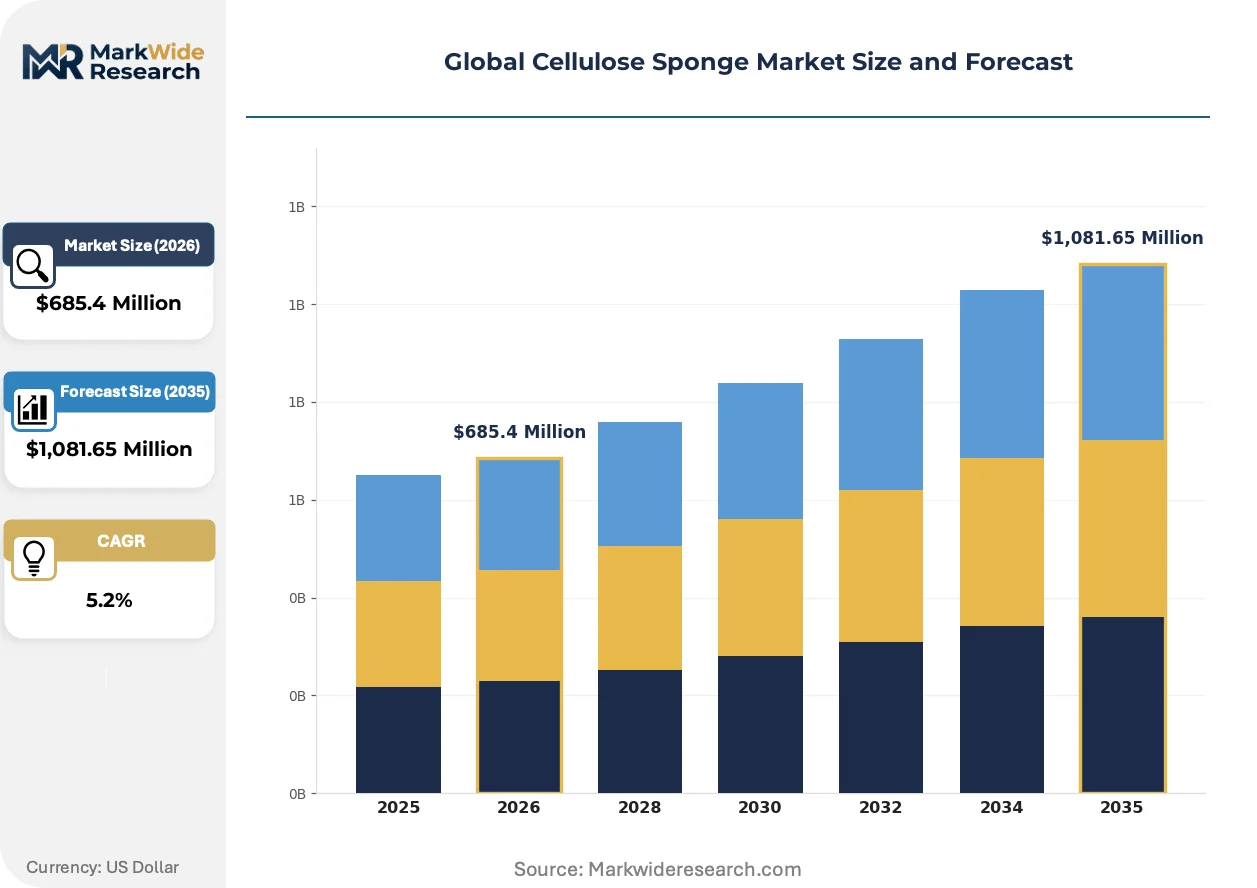
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,081.65 Million |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Kitchen Sponges, Bath Sponges, Industrial Sponges, Cosmetic Sponges, Medical Sponges Material Grade: Food Safe, Cosmetic Grade, Medical Grade, Industrial Grade, Eco-Friendly End Use Application: Household Cleaning, Personal Care, Food Service, Healthcare Facilities, Automotive Cleaning Distribution Channel: Supermarkets, Online Retailers, Specialty Stores, Wholesale Distributors, Institution Suppliers |
| Companies Covered | 3M Company, Americo Manufacturing, Corazzi Fiber S.r.l., Toray Fine Chemicals, Sponge Technology Corporation, Spontex, Armaly Sponge Company, Marian Inc, Kalle GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cellulose Sponge Market Strategic Shifts & Innovations
Material science innovation, driven by a confluence of regulatory pressure and consumer demand for sustainable products, is reshaping the basis of competition. This shift favors producers with deep expertise in biodegradable polymer chemistry over those relying solely on manufacturing scale.
Advanced pore engineering, achieved through modified viscose processes, allows for precise control over a sponge's absorbency, texture, and durability. The cosmetic and medical device sectors are rapidly adopting these customized variants for highly specific functions like drug delivery or delicate surface application. This capability is fragmenting the once-monolithic market into numerous high-margin, application-specific niches.
European Union regulations, particularly the Single-Use Plastics Directive and the broader Green Deal, are establishing strict criteria for product biodegradability and compostability. This forces manufacturers to validate end-of-life claims and reformulate products to eliminate non-biodegradable additives. The household cleaning segment is most affected, now prioritizing compostability certifications to maintain market access in countries like Germany and France.
Buyer preference is shifting from procuring bulk, generic sponges to demanding certified, application-specific products with transparent sourcing. This pattern disrupts traditional distribution through mass-market retailers, creating openings for specialized B2B suppliers and direct-to-consumer online brands. This trend is especially pronounced within the North American food service industry, where proof of compliance with food contact safety standards is paramount.
Global Cellulose Sponge Market Segmentation

The global cellulose sponge market is analyzed through several key segmentation dimensions, revealing varied demand patterns and competitive dynamics across product types, material grades, end-use applications, and distribution channels. Understanding these distinct segments is crucial for manufacturers to tailor product development, marketing strategies, and compliance efforts in a complex regulatory landscape.
Product Type:
Segments within product type face varying degrees of substitution pressure from synthetic alternatives, particularly in price-sensitive categories. This necessitates differentiated product development and positioning strategies to highlight biodegradability and performance advantages.
- Kitchen Sponges:These highly absorbent sponges are typically made from wood pulp, designed for general household cleaning and dishwashing tasks. Demand concentrates in densely populated urban centers across China and India, driven by rising hygiene standards and consumer convenience.
- Medical Sponges:Characterized by high purity and often sterile packaging, these sponges are manufactured for wound care, surgical preparation, and laboratory applications. The healthcare sector in Europe, particularly Germany and France, demonstrates strong demand due to stringent medical device regulations and high per capita healthcare spending.
- Bath Sponges:Designed for personal hygiene, these softer cellulose sponges offer gentle exfoliation and lathering properties.
- Industrial Sponges:These robust sponges are engineered for heavy-duty cleaning and spill absorption in manufacturing and maintenance environments.
- Cosmetic Sponges:Ultra-soft and pure, these sponges are used for makeup application, removal, and facial cleansing routines.
Kitchen Sponges retains volume leadership; Medical Sponges holds the steepest expansion curve.
Material Grade:
Margin profiles differ significantly across material grades, with specialized certifications commanding premium pricing due to rigorous testing and quality assurance requirements. Manufacturers invest heavily in R&D to meet these specific material grade specifications.
- Medical Grade:These sponges meet stringent purity and sterility standards, often requiring biocompatibility testing and regulatory approvals from bodies like the US FDA or Europe's MDR. Healthcare facilities in Japan and Canada are primary consumers, valuing safety and performance in critical applications.
- Food Safe:Manufactured to comply with food contact regulations, such as those from the US FDA and EFSA, these sponges prevent contamination in food processing and commercial kitchens. Demand is particularly strong in the North American food service industry, where compliance is paramount.
- Cosmetic Grade:Characterized by exceptional softness and chemical inertness, these sponges are formulated for direct skin contact in personal care products.
- Industrial Grade:Engineered for durability and chemical resistance, these sponges are used in industrial cleaning and maintenance operations.
- Eco-Friendly:This grade emphasizes enhanced biodegradability and sustainable sourcing, aligning with consumer demand and policies like the EU Green Deal.
High-purity grades, such as Medical Grade, command premium pricing, while Industrial Grade serves broad utility needs.
End Use Application:
Volume distribution across end-use applications highlights the market's foundational demand in traditional sectors, alongside significant expansion in specialized and regulated environments. Each application presents unique requirements for absorbency, durability, and material safety.
- Household Cleaning:This segment represents the largest volume consumption, encompassing general cleaning, dishwashing, and surface wiping in residential settings. The sheer number of households globally, particularly in emerging economies like India and Brazil, drives consistent demand for these versatile cleaning tools.
- Healthcare Facilities:Demand in this segment is accelerating due to heightened infection control protocols and the need for sterile, single-use products in hospitals and clinics. Countries with expanding hospital networks, such as China and Saudi Arabia, are significant growth areas.
- Personal Care:Cellulose sponges are used in various personal care routines, including bathing and facial cleansing, valued for their natural texture.
- Food Service:This application involves cleaning and sanitizing surfaces in restaurants, cafeterias, and food preparation areas, requiring food-safe materials.
- Automotive Cleaning:Sponges are utilized for washing and detailing vehicles, offering effective cleaning without scratching sensitive surfaces.
While Household Cleaning remains the largest segment by volume, Healthcare Facilities is experiencing the most dynamic expansion.
Distribution Channel:
Customer type significantly influences distribution channel strategies, with varying requirements for bulk purchasing, specialized product access, and direct consumer engagement. The shift towards online platforms is reshaping traditional retail paradigms.
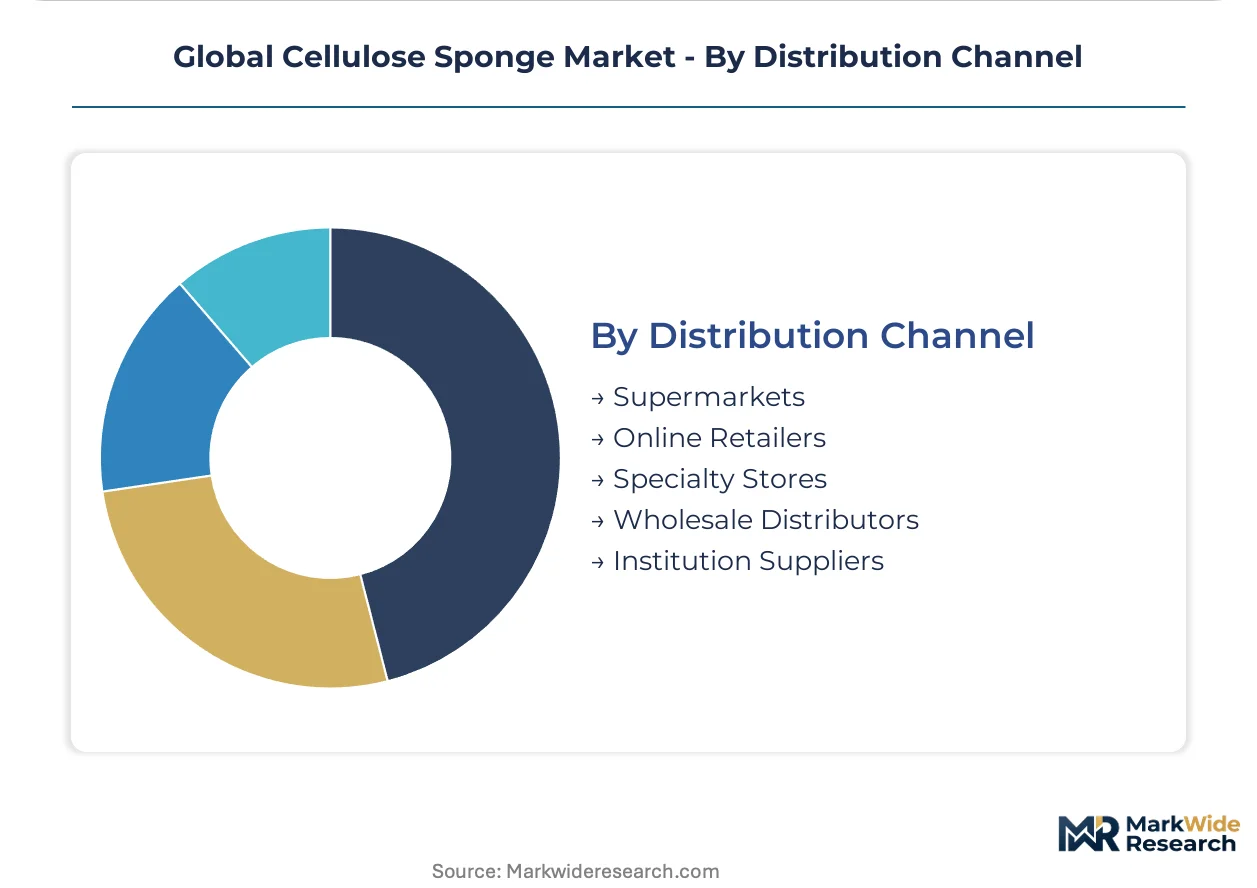
- Online Retailers:This channel facilitates direct-to-consumer sales and broad market reach, offering convenience and a wide selection of specialized cellulose sponge products. Growth is pronounced in markets with high internet penetration, such as the United States and South Korea.
- Wholesale Distributors:These entities manage large-volume procurement and supply to businesses, institutions, and smaller retailers, ensuring efficient supply chain logistics for industrial and commercial users. European markets, particularly Germany, rely heavily on established wholesale networks.
- Supermarkets:Mass-market retail chains provide extensive consumer access to household cellulose sponges through their broad geographic footprint.
- Specialty Stores:These outlets cater to niche markets, offering high-end cosmetic or eco-friendly cellulose sponges with expert advice.
- Institution Suppliers:This channel directly serves large organizations like hospitals, schools, and government agencies with bulk orders of specific grade sponges.
Wholesale Distributors ensure efficient B2B supply, while Online Retailers are rapidly expanding consumer access.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global cellulose sponge market exhibits a varied consumption mix, with demand patterns differing significantly across key geographies. China and India lead in volume for household cleaning applications, while Europe and Japan show strong preferences for specialized medical and cosmetic grades. North America emphasizes food-safe certifications, reflecting distinct regulatory landscapes and consumer priorities.
China
Rapid urbanization and rising consumer hygiene standards drive substantial demand for kitchen sponges in China. The country's GB standards impose strict quality controls, influencing manufacturing protocols. Major manufacturing hubs like the Yangtze River Delta concentrate production, catering to both domestic consumption and export markets.
Germany
Stringent medical device regulations and high per capita healthcare spending fuel demand for medical sponges in Germany. The EU Green Deal and REACH framework push manufacturers towards sustainable and compliant materials. Research and development clusters in cities like Munich focus on advanced material science and specialized variants.
United States
The North American food service industry requires certified food-safe cellulose sponges, driven by US FDA regulations concerning food contact surfaces. Online retailers facilitate broad consumer access, particularly for specialized products. Major metropolitan areas like New York and Los Angeles exhibit high demand for household and commercial cleaning products.
Japan
Heightened infection control protocols in healthcare facilities and strong environmental policies underpin demand for high-purity medical and eco-friendly sponges in Japan. The PMDA regulates medical devices, ensuring stringent safety and performance standards. Tokyo and Osaka serve as key centers for advanced material innovation and product development.
India
Expanding hospital networks and increasing disposable incomes contribute to rising demand for both household and medical cellulose sponges in India. The BIS standards govern product quality and safety for a wide range of consumer goods. Industrial clusters in states like Maharashtra and Gujarat are seeing increased manufacturing activity to meet domestic needs.
Global Cellulose Sponge Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, defining the competitive structure of the global cellulose sponge market. These integrated players often leverage extensive R&D infrastructure to develop specialized material variants and maintain a broad product portfolio. Specialist manufacturers, in contrast, focus on niche applications like medical or cosmetic grades, emphasizing material innovation. Dominant competitive moves include strategic investments in R&D for biodegradable materials and geographic expansion into high-growth emerging markets.
Within the integrated leader archetype, 3M Company, a US-based conglomerate, leverages its extensive R&D infrastructure to develop diverse and specialized sponge variants, indicating a broad market presence. Corazzi Fiber S.r.l., an Italian entity, exemplifies specialized material innovators, focusing on non-woven fiber products that cater to specific cleaning applications and material properties. Kalle GmbH, a German company, anchors its position within the food-grade segment, demonstrating deep process knowledge and adherence to stringent safety requirements for specialized end-use applications.
| Leading Market Players |
|---|
| 3M Company |
| Americo Manufacturing |
| Corazzi Fiber S.r.l. |
| Toray Fine Chemicals |
| Sponge Technology Corporation |
| Spontex |
| Armaly Sponge Company |
| Marian Inc |
| Kalle GmbH |
| Others |
Cost & Logistics Intelligence
The EU Green Deal and its stringent biodegradability criteria gate supply qualification, simultaneously driving price differentiation for compliant materials. This framework pushes manufacturers to invest in material innovation, impacting both production costs and market pricing. The global cellulose sponge market navigates these dynamics to balance sustainability mandates with cost pressures.
Pricing Analysis
Contract-based long-term offtake agreements dominate for specialized medical and industrial grades, providing stability for both buyers and suppliers. Price differentiation stems from certification levels, such as Medical Grade or Food Safe approvals, and the degree of pore engineering customization. Pricing softness affects household segments due to the presence of lower-cost synthetic substitutes. Healthcare facilities exhibit the least price sensitivity, prioritizing performance and safety over cost.
Supply Chain Analysis
Port congestion and container availability impact inbound logistics for key raw materials like wood pulp and cotton linter. Supply concentration for cellulose sponges centers on manufacturing hubs in China and specialized production facilities across Europe. The market relies heavily on consistent access to wood pulp and cotton linter, exposing it to commodity price volatility. Regulatory scrutiny of viscose process chemicals under frameworks like Europe's REACH framework presents a structural supply chain risk. Wholesale distributors manage efficient B2B supply, while online retailers expand direct-to-consumer access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The global cellulose sponge market is poised for a cyclical recovery, driven by renewed emphasis on hygiene standards post-pandemic and evolving sustainability mandates.
For Market Incumbents:Fortify market share by investing in advanced pore engineering for specialized segments like medical and cosmetic applications. Secure long-term contracts for sustainably sourced raw materials to mitigate price volatility and enhance environmental credentials. This strategy defends against substitution by synthetics in price-sensitive segments and leverages R&D in biodegradable polymers.
For New Entrants and Emerging Players:Differentiate on transparent sustainability claims and application-specific performance in underserved niches. Target eco-friendly household products in markets with strong environmental awareness, such as Germany and Japan. A direct-to-consumer online sales model can effectively reach conscious consumers and establish brand presence.
For Investors and Strategic Acquirers:Capital-intensity ratios are inflecting upwards across specialized medical and food-grade production due to stringent certification requirements. The market offers sustained value over the next decade, particularly in high-purity and sustainable segments. Target vertically integrated specialists with proprietary material science expertise or strong regional distribution networks in emerging markets. Increased M&A activity for biodegradable polymer chemistry firms signals a key inflection point.
| Strategic Initiative | Industry Significance |
|---|---|
| R&D in Biodegradable Polymers | Enhances product appeal to environmentally conscious consumers and regulators. |
| Medical Grade Certification | Unlocks access to high-margin healthcare facilities in Europe and Japan. |
| Geographic Expansion (China/India) | Captures volume growth from rising hygiene standards in emerging economies. |
| Advanced Pore Engineering | Delivers customized absorbency and texture for cosmetic and medical applications. |
| Sustainable Sourcing Partnerships | Mitigates raw material price volatility and strengthens environmental credentials. |
Research Approach
Desk research of industry journals, company annual reports, and regulatory filings from the US FDA, EU REACH, and China GB standards preceded structured interviews with industry stakeholders. This included R&D directors, procurement managers at healthcare facilities, product development leads, and sustainability officers. The approach combined primary insights with secondary validation through bottom-up and top-down triangulation.
Variance decomposition isolated demand drivers and supply constraints across the analysis window. Segmentation dimensions modeled included product type, material grade, end-use application, distribution channel, and regional regulatory compliance. CAGR values were derived from historical data analysis and projected market dynamics, incorporating key forecast inputs such as wood pulp commodity prices and healthcare expenditure growth.
Material uncertainties — unforeseen shifts in global trade policies or rapid breakthroughs in synthetic materials — sit outside the modeled envelope. Forecasts reflect assumptions documented through extensive primary and secondary research. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper Products
Industrial Paper Shredder Machine Market
Paper Products
Medical Grade Paper Market
Paper Products
Stone Paper Market
Paper Products
Saturated Kraft Paper Market
Paper Products
Office Printing Papers Market
Paper Products
Clay Coated Paper Market
Paper Products
Heat Transfer Paper Market
Paper Products
Paper Machine Systems Market
Paper Products
Tissue Paper Market
Paper Products
Americas Stone Paper Market
Paper Products
Solid Bleached Sulfate (SBS) Board Market
Paper Products
GCC Stone Paper Market
Paper Products
GCC Paper Products Market
Paper Products
White Line Chipboard Market
Paper Products
Leatheroid Paper Market
Paper Products
Functional and Barrier Coatings for Paper Market