
 Polyelectrolyte Market | 2026-2036
Polyelectrolyte Market Size, Share, and Industry Trends Forecast 2026-2036
Polyelectrolyte Market Outlook
Buyer concentration among municipal wastewater utilities is consolidating across North America and Western Europe, reducing vendor count per procurement cycle. SNF Floerger leverages its integrated monomer-to-polymer manufacturing footprint to sustain supply security for large utility contracts. Dow Chemical Company anchors its position through backward integration into acrylic acid feedstocks. Kemira Oyj differentiates via bio-based polyelectrolyte R&D programs targeting European pulp and paper mills.
Polyelectrolytes are water-soluble polymers bearing ionizable functional groups along their backbone, with molecular weights ranging from thousands to millions of Daltons and charge densities dictating flocculation efficiency in aqueous systems. Cationic grades dominate municipal sludge dewatering applications where positive charge neutralizes negatively charged biological solids, while anionic variants lead industrial wastewater clarification due to superior performance with inorganic suspended particles. The powder form category occupies the largest volume share in bulk water treatment procurement, though liquid emulsion formats are gaining traction in automated dosing systems across European environmental agencies.
EPA effluent limitation guidelines and REACH polymer registration requirements shape product formulation standards and market access conditions for suppliers operating across the United States and European Union. China's MEE discharge permits and GB standards for industrial wastewater are tightening polymer dosage specifications in the country's manufacturing belts. Japan's METI chemical substance reporting framework adds compliance layers for imported polyelectrolyte formulations. Stakeholders must monitor regulatory divergence between jurisdictions to align product portfolios with divergent toxicity testing and biodegradability thresholds.
Market Dynamics
Municipal wastewater utilities are consolidating procurement volumes into fewer, larger contracts, compressing vendor margins while demanding guaranteed supply security and technical service bundling from polyelectrolyte suppliers.
Growth Catalysts
- EPA Effluent Limitation Guidelines:Tightened discharge standards across United States municipal systems are mandating higher-performance cationic polymers for sludge dewatering, expanding specification-grade procurement volumes.
- China's MEE discharge permits:State-led environmental enforcement in the Yangtze and Pearl River manufacturing belts is driving bulk cationic polymer consumption for industrial wastewater clarification.
- Automated dosing systems:European environmental agencies are adopting liquid emulsion formats with integrated polymer feed controls, displacing manual powder handling in large treatment facilities.
Market Restraints
- Acrylic acid feedstock volatility:Anionic polyelectrolyte production depends on petroleum-derived monomer supply subject to refining capacity constraints and energy price swings.
- REACH polymer registration:European Chemicals Agency toxicity testing and biodegradability documentation requirements create multi-year compliance timelines and registration cost barriers for new market entrants.
- Aluminum sulfate substitution:Inorganic coagulants retain cost advantage in price-sensitive municipal segments with less stringent performance requirements, limiting polymer penetration in developing systems.
Strategic Opportunities
- Bio-based polymer R&D:European pulp and paper mills are piloting starch-derived and chitosan-based flocculants to meet EU Green Deal carbon intensity targets and brand sustainability commitments.
- India's industrial water corridor:State pollution control board enforcement in Gujarat and Maharashtra chemical clusters is opening specification-grade polymer demand previously served by commodity chemicals.
- Performance-based service contracts:North American utilities are contracting polymer supply tied to measured dry solids capture rates, shifting vendor compensation from volume to outcome metrics.
Industry Challenges
- Polymer characterization expertise:Utilities lack in-house capability to validate charge density and molecular weight specifications against supplier certificates, creating acceptance disputes and dosing optimization failures.
- Legacy SCADA integration:Automated polymer feed systems require retrofitting analog-era treatment plant control architectures, extending implementation timelines and capital recovery periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyelectrolyte Market |
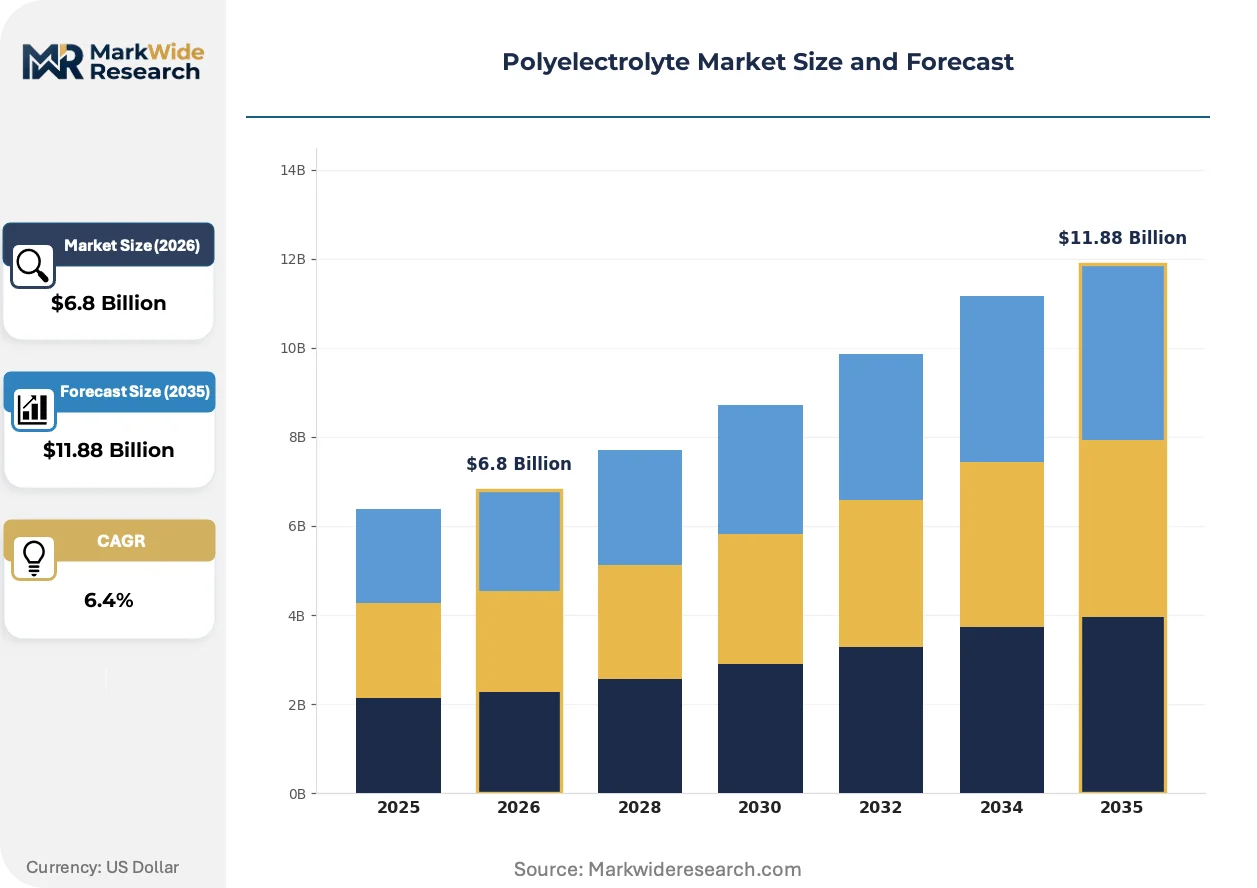
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.88 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cationic, Anionic, Zwitterionic, Non-ionic Application: Water Treatment, Coagulation, Drug Delivery, Textile Processing End User: Pharmaceuticals, Environmental Agencies, Food Industry, Pulp & Paper Form: Powder, Liquid, Granule, Emulsion |
| Companies Covered | Dow Chemical Company, Ashland Global Holdings Inc., SNF Floerger, AkzoNobel, Ecolab Inc., Kemira Oyj, Solenis LLC, Thermax Limited, BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyelectrolyte Market Strategic Shifts
Polyelectrolyte formulation science is pivoting toward bio-derived feedstocks and intelligent dosing systems, while regulatory chemistry is fragmenting across jurisdictions with divergent toxicity testing protocols.
Structured polymer architectures with branched rather than linear chain configurations are absorbing higher shear forces in high-speed centrifuge dewatering applications. German and Dutch municipal utilities are adopting these grades for combined heat and power sludge digestion facilities. The technology is absorbing market share from conventional linear cationics in European procurement cycles where energy recovery efficiency determines contract awards.
REACH polymer registration requirements are tightening biodegradability documentation for acrylamide-based formulations entering European Union markets. Suppliers must submit enhanced aquatic toxicity dossiers to ECHA, extending product launch timelines by eighteen to thirty-six months. Anionic variants for industrial clarification face the steepest compliance burden, diverting R&D investment toward bio-based alternatives.
Specification-grade procurement is displacing spot purchasing in North American municipal wastewater contracts. Large utilities in California, Texas, and Ohio are consolidating annual polymer volumes into single-source agreements with technical service obligations. The shift is most visible in sludge dewatering applications where guaranteed dry solids capture rates have become contract terms rather than performance aspirations.
Polyelectrolyte Market Segmentation
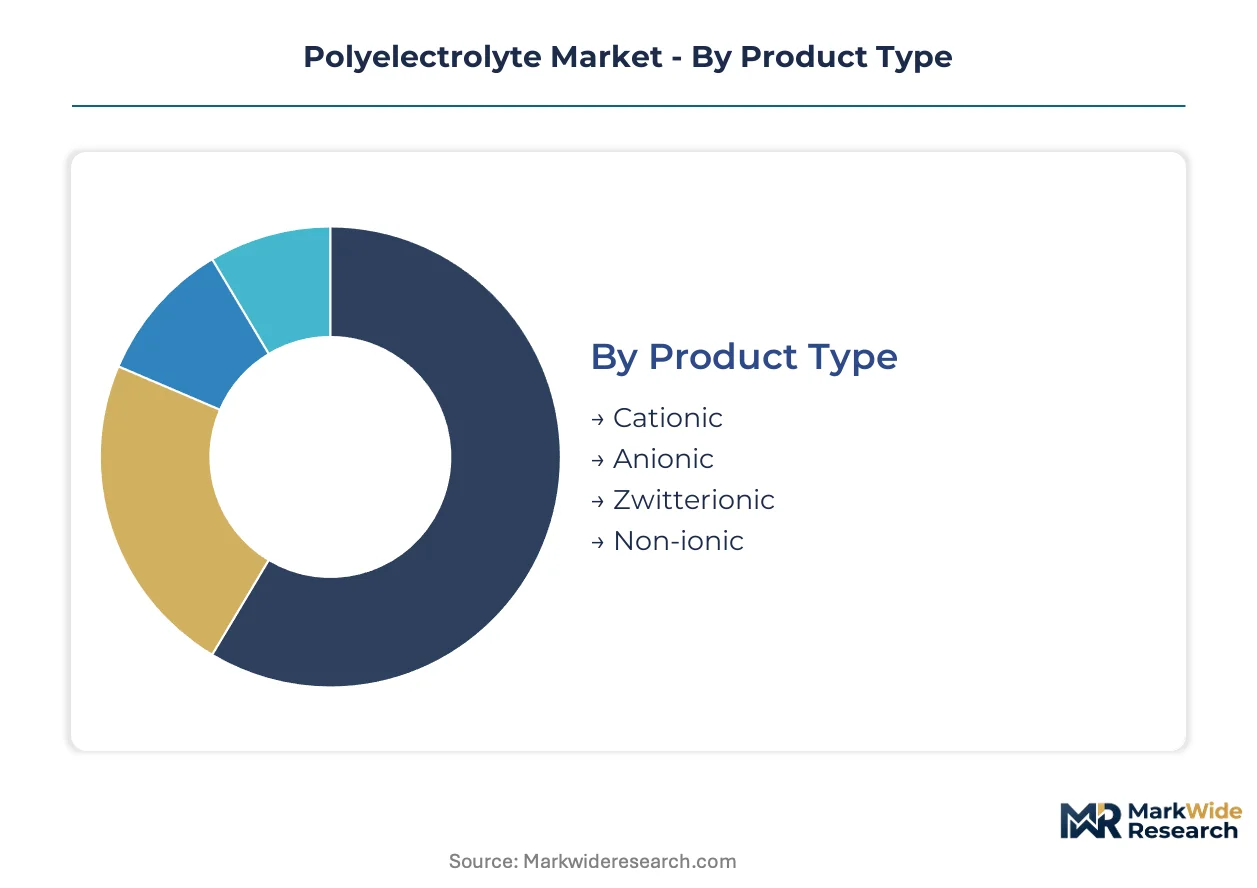
Polyelectrolyte procurement patterns diverge sharply across charge chemistry, physical form, and end-use specifications. Suppliers must align molecular architecture and delivery format with distinct operational constraints in municipal utilities, pharmaceutical manufacturing, and industrial processing environments.
Product Type:
Cationic and anionic grades operate as standalone flocculating systems, while zwitterionic and non-ionic variants embed into multi-polymer formulations or specialized pharmaceutical matrices.
- Cationic:Positively charged polymers bearing quaternary ammonium or amine functional groups deliver superior charge neutralization against negatively charged biological solids. Municipal wastewater utilities in California and Texas specify high-molecular-weight cationics for centrifuge dewatering operations where dry solids capture rates determine contract awards. EPA effluent limitation guidelines are tightening dosage specifications, pushing procurement toward premium-grade specifications with guaranteed molecular weight distributions.
- Anionic:Carboxylate or sulfonate-functionalized chains excel at bridging inorganic suspended particles in industrial clarification. China's MEE discharge permit enforcement across the Yangtze River manufacturing belt is expanding specification-grade anionic consumption for metal finishing and mineral processing effluent treatment. Acrylic acid feedstock volatility constrains margin stability for suppliers without backward integration into monomer production.
- Zwitterionic:Amphoteric charge distributions enable pH-responsive behavior for pharmaceutical encapsulation and controlled-release formulations. CDSCO registration requirements in India shape import specifications for drug delivery applications.
- Non-ionic:Polyacrylamide backbones without ionizable substituents provide shear stability in high-turbulence papermaking wet-end systems. European pulp and paper mills evaluate non-ionics against bio-based starch alternatives under EU Green Deal carbon intensity benchmarks.
Volume placements concentrate in Cationic; the faster expansion belongs to Anionic.
Application:
Water treatment applications absorb bulk procurement volumes, while drug delivery and textile processing command premium pricing tiers based on regulatory compliance burdens.
- Water Treatment:Municipal and industrial effluent clarification represents the dominant consumption channel, spanning sludge dewatering, primary coagulation, and tertiary filtration. REACH polymer registration requirements and EPA effluent standards are fragmenting formulation specifications across Atlantic supply corridors. Powder formats dominate bulk procurement; liquid emulsions gain share in automated European installations.
- Coagulation:Rapid-mix basin applications demand precise charge density matching to raw water turbidity profiles. Aluminum sulfate substitution pressure limits polymer penetration in price-sensitive developing systems.
- Drug Delivery:Chitosan and synthetic polyelectrolyte complexes enable nanoparticle encapsulation for oral and parenteral formulations. FDA and EMA chemistry, manufacturing, and controls documentation requirements extend development timelines.
- Textile Processing:Dye fixation and wastewater color removal applications in Gujarat and Maharashtra chemical clusters are opening specification-grade demand previously served by commodity coagulants.
Water Treatment commands the largest procurement volumes; Drug Delivery climbs the fastest on pharmaceutical pipeline expansion.
End User:
Environmental agencies consolidate purchasing power through multi-year framework agreements, while pharmaceutical and food industry buyers fragment across specialized formulation requirements.
- Environmental Agencies:Municipal wastewater utilities in Ohio and Ontario are consolidating annual polymer volumes into single-source contracts with technical service obligations. Guaranteed dry solids capture rates have become enforceable contract terms rather than performance aspirations.
- Pharmaceuticals:Parenteral and oral dosage form manufacturers specify ultra-low residual monomer grades with comprehensive extractables and leachables documentation.
- Food Industry:Potable water treatment and processing effluent clarification applications require NSF/ANSI 60 certification for coagulant aids in North American markets.
- Pulp & Paper:Retention and drainage aids in Kraft and mechanical pulping operations face bio-based substitution pressure from European mills targeting EU Green Deal commitments.
Environmental agencies anchor volume demand; Pharmaceuticals posts the steepest expansion trajectory on regulatory filing activity.
Form:
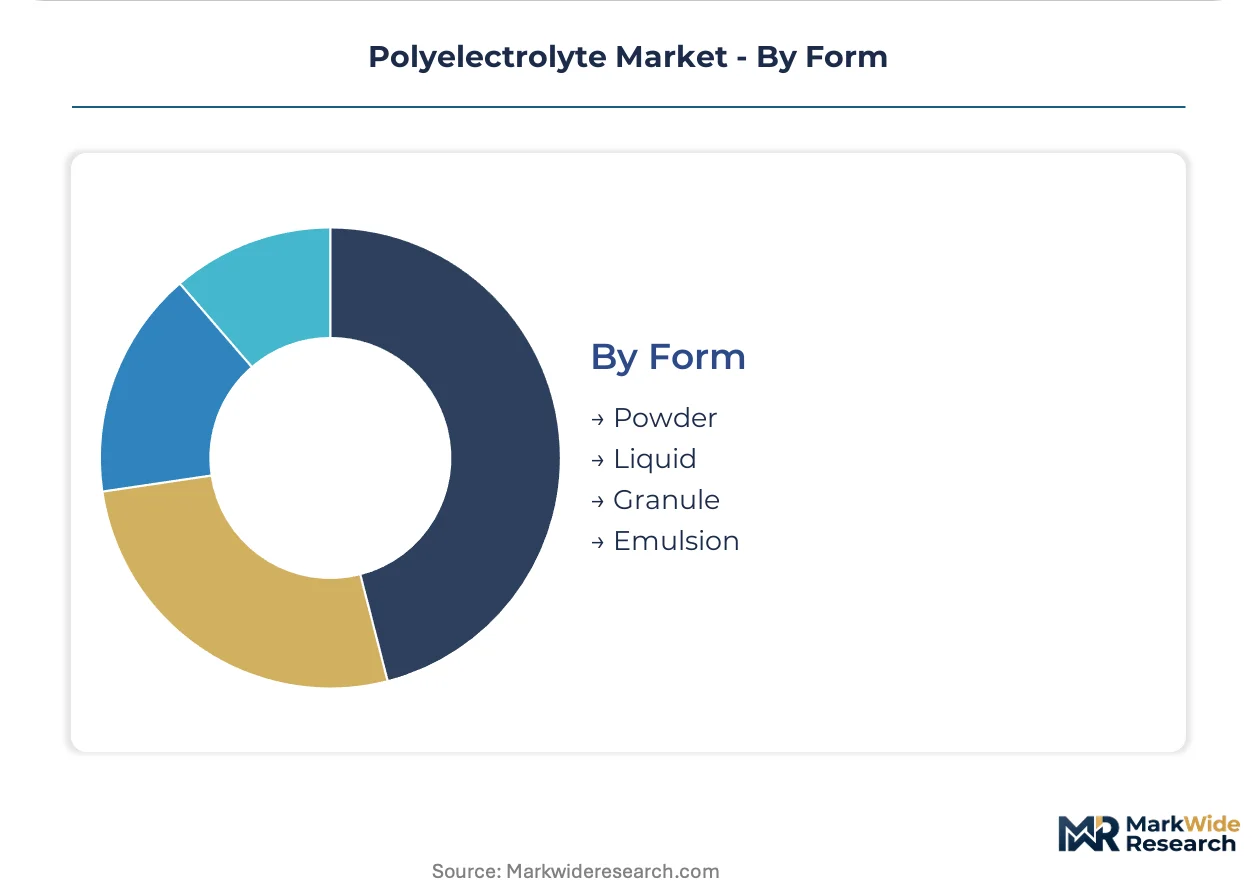
Powder and liquid formats split procurement between manual handling systems and automated feed infrastructure, with emulsion and granule variants serving niche operational constraints.
- Powder:Spray-dried beads with controlled particle size distribution dominate bulk water treatment procurement for cost-sensitive municipal segments. Dust exposure and dissolution tank maintenance requirements drive conversion toward liquid alternatives in European environmental agencies.
- Liquid:Emulsion and solution formats integrate with SCADA-controlled dosing skids, enabling real-time polymer feed adjustment based on influent turbidity. Retrofit capital requirements extend implementation timelines at legacy treatment plants.
- Granule:Low-dust handling characteristics suit confined-space installations and remote mining camp operations with limited technical staffing.
- Emulsion:Inverse emulsion polymers with rapid inversion kinetics enable high-concentration dosing without extended maturation periods.
Powder retains volume leadership; Liquid gains share fastest on automation adoption in German and Dutch municipal utilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for polyelectrolytes concentrates in industrial corridors where wastewater discharge enforcement has tightened. China's manufacturing belts, Germany's chemical clusters, and the US municipal utility sector anchor procurement volumes. Regulatory divergence across these markets fragments formulation specifications and compliance timelines.
United States
California and Texas municipal utilities consolidate annual polymer volumes into single-source contracts with technical service obligations. EPA effluent limitation guidelines mandate higher-performance cationic polymers for sludge dewatering operations. Ohio wastewater authorities specify guaranteed dry solids capture rates as enforceable contract terms rather than performance aspirations.
China
Yangtze and Pearl River manufacturing belts drive bulk cationic polymer consumption for industrial wastewater clarification. MEE discharge permit enforcement tightens polymer dosage specifications across metal finishing and mineral processing operations. State-led environmental campaigns in Jiangsu and Guangdong provinces displace commodity coagulants with specification-grade formulations.
Germany
Rhineland and Bavarian municipal utilities adopt structured polymer architectures with branched chain configurations for combined heat and power sludge digestion. REACH polymer registration requirements tighten biodegradability documentation for acrylamide-based formulations entering EU markets. Dutch and German environmental agencies lead automation adoption with liquid emulsion formats and SCADA-controlled dosing skids.
India
Gujarat and Maharashtra chemical clusters open specification-grade polymer demand previously served by commodity coagulants. State pollution control board enforcement tightens discharge standards for textile processing and dye fixation applications. CDSCO registration requirements shape import specifications for pharmaceutical encapsulation applications in Mumbai-Pune corridor.
Japan
Kanto and Kansai industrial zones maintain stringent polymer performance standards for high-turbulence papermaking wet-end systems. METI chemical substance reporting frameworks add compliance layers for imported polyelectrolyte formulations. Osaka-based pulp and paper mills evaluate non-ionic variants against bio-based starch alternatives under carbon intensity benchmarks.
Polyelectrolyte Market Competitive Environment
European producers anchor the premium formulation tier; Asian manufacturers hold cost-optimized supply positions. The vendor base splits between integrated petrochemical conglomerates and specialized water treatment chemical firms. Three archetypes dominate: backward-integrated monomer producers, bio-based R&D specialists, and regional distribution-focused compounders. Capacity expansion and strategic partnerships represent the dominant competitive moves across all tiers.
Within the integrated chemical tier, Dow Chemical Company and BASF SE exemplify upstream control over acrylic acid feedstocks. SNF Floerger anchors the specialized water treatment segment with captive monomer-to-polymer manufacturing. Kemira Oyj occupies a distinct position among bio-based formulation developers targeting European pulp and paper sustainability mandates.
| Leading Market Players |
|---|
| Dow Chemical Company |
| Ashland Global Holdings Inc. |
| SNF Floerger |
| AkzoNobel |
| Ecolab Inc. |
| Kemira Oyj |
| Solenis LLC |
| Thermax Limited |
| BASF SE |
| Others |
Value Chain & Pricing Dynamics
Acrylic acid price indices cascade through polyelectrolyte manufacturing into three distinct procurement tiers, with petroleum-derived monomer volatility compressing margins for non-integrated suppliers while concentrating pricing power among backward-integrated producers serving municipal wastewater utilities.
Pricing Analysis
Volume procurement splits from margin capture across the polyelectrolyte value chain, with bulk municipal contracts trading at thin spreads while pharmaceutical-grade formulations command certification premiums. Pricing stratifies across premium NSF/ANSI 60 certified grades for potable water, standard industrial clarification polymers, and economy-tier commodity coagulants competing with aluminum sulfate. Cost compression in anionic grades is intensifying because acrylic acid feedstock volatility exposes non-integrated compounders to margin erosion. Municipal wastewater utilities in Ohio and Texas exhibit highest price sensitivity, while pharmaceutical encapsulation buyers absorb premium pricing for ultra-low residual monomer documentation.
Supply Chain Analysis
REACH polymer registration and EPA effluent compliance certifications gate market access, fragmenting supplier qualification timelines across Atlantic supply corridors. Manufacturing concentrates in the United States, Germany, and China, with captive monomer-to-polymer integration anchoring supply security for large utility contracts. Production draws from petroleum-derived acrylamide, bio-based starch feedstocks, and chitosan-derived biopolymers. Single-source vulnerability persists for acrylic acid supply subject to refining capacity constraints. Distribution runs through regional chemical distributors and direct technical service agreements with consolidated municipal procurement authorities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Polyelectrolyte supply remains constrained by REACH registration bottlenecks and acrylamide monomer capacity limitations, with qualified supplier scarcity propping pricing power for integrated manufacturers across European and North American procurement cycles.
For Market Incumbents: Extend technical service bundling into performance-based contracts with guaranteed dry solids capture rates, locking out commodity competitors. Deepen backward integration into acrylic acid feedstocks to defend margin position against petrochemical volatility. Prioritize bio-based R&D investment targeting EU Green Deal carbon intensity benchmarks for European pulp and paper mill procurement. For New Entrants and Emerging Players: Capture specification-grade demand in Gujarat and Maharashtra chemical clusters where state pollution control board enforcement displaces commodity coagulants. Target India's pharmaceutical encapsulation corridor with CDSCO-registered chitosan formulations. Lead with automated dosing system integration to bypass entrenched powder-format incumbents. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap compounders with captive monomer supply in the US Gulf Coast or Rhine-Ruhr corridor, positioned for municipal procurement consolidation. Long-term viability hinges on bio-based formulation pipelines and regulatory qualification depth. Watch for MEE enforcement intensity in Jiangsu province as inflection signal for Chinese industrial polymer demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylic Acid | Secures margin stability against petrochemical volatility for municipal utility contracts. |
| Bio-Based Polymer R&D Program | Aligns formulation portfolios with EU Green Deal carbon intensity targets for pulp mills. |
| Performance-Based Service Contract | Shifts vendor compensation from volume metrics to measured dry solids capture outcomes. |
| REACH Registration Acceleration | Compresses ECHA compliance timelines to capture specification-grade European procurement. |
| Automated Dosing System Partnership | Integrates liquid emulsion supply with SCADA-controlled feed infrastructure in Dutch utilities. |
Study Parameters
Independent corroboration across municipal procurement officers, water treatment plant engineers, and polymer R&D directors underwrites the qualitative findings, validated against customs trade data, EPA effluent guideline filings, and ECHA registration dossiers. Primary fieldwork with distribution channel partners and technical service managers informed supply chain mapping, while SEC 10-K disclosures and Cefic chemical industry reports anchored secondary triangulation. Bottom-up segment sizing and top-down macroeconomic cross-checks converged on volume and value estimates.
Rate-of-change decomposition across charge chemistry, physical form, end-use application, and regional regulatory cluster shaped the analytical framework. Modeled segmentation spans cationic/anionic/zwitterionic grades, powder/liquid/granule delivery formats, municipal/industrial/pharmaceutical end users, and country-level enforcement intensity variations. CAGRs were derived from trend extrapolation against documented procurement cycle data and capacity expansion announcements. Forecast inputs incorporated MEE discharge permit enforcement trajectories and REACH polymer registration completion rates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to acrylic acid feedstock volatility, regulatory divergence between EPA and ECHA standards, and bio-based substitution acceleration in European markets. Forecasts reflect documented assumptions on procurement consolidation velocity and automation adoption curves. A model refresh is warranted upon material change in China's MEE enforcement intensity or REACH biodegradability documentation requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Global High Temperature Resin Market
Polymers & Resins
Circular Polymers Market
Polymers & Resins
Polyethylene Terephthalate (PET) Foam Market
Polymers & Resins
Phenolic Resin Market
Polymers & Resins
Poly Propylene Glycol Market
Polymers & Resins
South America Polymer Emulsion Market
Polymers & Resins
Polyglycerol Polyricinoleate Market
Polymers & Resins
North America Geopolymer Market
Polymers & Resins
Polyetherketone Market
Polymers & Resins
Polystyrene Market
Polymers & Resins
Chlorinated Polyvinyl Chloride (CPVC) Market
Polymers & Resins
Conditioning Polymers Market
Polymers & Resins
Nylon-6 Market
Polymers & Resins
Caprolactam (Nylon 6 Fiber and Nylon 6 Resin) Market
Polymers & Resins
Sustainable Polymers Market
Polymers & Resins
Europe Polyvinylpyrrolidone (PVP) Market