
 Asia-Pacific Epoxy Resins Market | 2026-2036
Asia-Pacific Epoxy Resins Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Epoxy Resins Market Outlook
GB/T 13657 certification for epoxy resins is bifurcating the competitive landscape into qualified suppliers and marginal participants. Kukdo Chemical Co., Ltd. leverages its integrated bisphenol-A feedstock position to sustain cost leadership across Korean and Chinese markets. Nan Ya Plastics Corporation anchors volume supply through its Taiwan-based chlorohydrin-to-epoxy pipeline, while Aditya Birla Chemicals competes on specialty grades for electrical encapsulation applications.
Epoxy resins are thermosetting polymers formed through the reaction of epichlorohydrin with bisphenol-A or bisphenol-F, yielding prepolymers that crosslink with amine or anhydride hardeners to form chemically resistant matrices with glass transition temperatures typically spanning 120–180°C. These materials serve primarily as structural adhesives, protective coatings, and fiber-reinforced composite matrices where mechanical strength and environmental durability outweigh thermoplastic alternatives. Liquid epoxy formulations dominate volume throughput in coatings and adhesive applications, while solid epoxy grades command premium positioning in powder coating systems for automotive and appliance finishes. The bisphenol-A formulation category retains the largest share of production capacity, though novolac-based epoxies are gaining traction in high-temperature electrical encapsulation segments where thermal performance requirements are tightening.
China's MEE enforces VOC content limits in industrial coatings that directly constrain solvent-based epoxy formulations and redirect procurement toward water-based and high-solids alternatives. South Korea's MFDS and Japan's METI coordinate chemical substance reporting under aligned frameworks that affect import compliance costs for non-domestic suppliers. India's BIS certification mandates for construction-grade adhesives create additional market access thresholds that regional producers must navigate. Stakeholders should monitor formulation registration timelines and hardener chemistry substitutions as regulatory pressure on aromatic amines intensifies across multiple Asia-Pacific jurisdictions.
Market Dynamics
China's dual carbon goals and MEE enforcement of VOC content limits in industrial coatings are restructuring formulation requirements, forcing manufacturers to abandon solvent-based systems and redirect R&D toward water-based and high-solids alternatives.
Growth Catalysts
- Wind turbine blade fabrication:Chinese OEMs are scaling nacelle assembly lines, driving demand for structural epoxy matrices in rotor construction.
- MEE emission standards:Stricter VOC limits in industrial coatings are redirecting procurement toward compliant low-solvent formulations.
- Eastern China industrial corridor:Coastal provinces host dense clusters of electronics and automotive production consuming specialty epoxy grades.
Market Restraints
- Bisphenol-A feedstock volatility:Petrochemical price swings compress margin stability for formulation houses lacking captive phenol supply.
- Korean chlorohydrin concentration:Integrated producers in South Korea control critical epichlorohydrin pipeline capacity, creating import dependency for smaller Chinese blenders.
- Thermoplastic substitution in automotive:Polyamide and PBT compounds are displacing epoxy-based underhood electrical components where thermal cycling demands moderate.
Strategic Opportunities
- India construction adhesives:BIS certification mandates for infrastructure-grade bonding systems create first-mover advantage for compliant regional producers.
- High-voltage electrical encapsulation:Novolac-based epoxies are penetrating transformer and switchgear applications where thermal performance requirements exceed standard bisphenol-A grades.
- Japan METI substance reporting alignment:Coordinated chemical notification frameworks with South Korea's MFDS reduce compliance friction for cross-border suppliers.
Industry Challenges
- GB/T 13657 certification timelines:Testing and approval cycles for epoxy resin quality standards extend 12-18 months, freezing product launch schedules.
- Aromatic amine hardener substitution:Regulatory pressure across multiple Asia-Pacific jurisdictions forces reformulation of curing systems with unfamiliar aliphatic alternatives.
- Legacy coating line retrofit costs:Water-based epoxy transitions require spray booth modifications and dryer capacity expansion that strain mid-tier applicator capital budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Epoxy Resins Market |
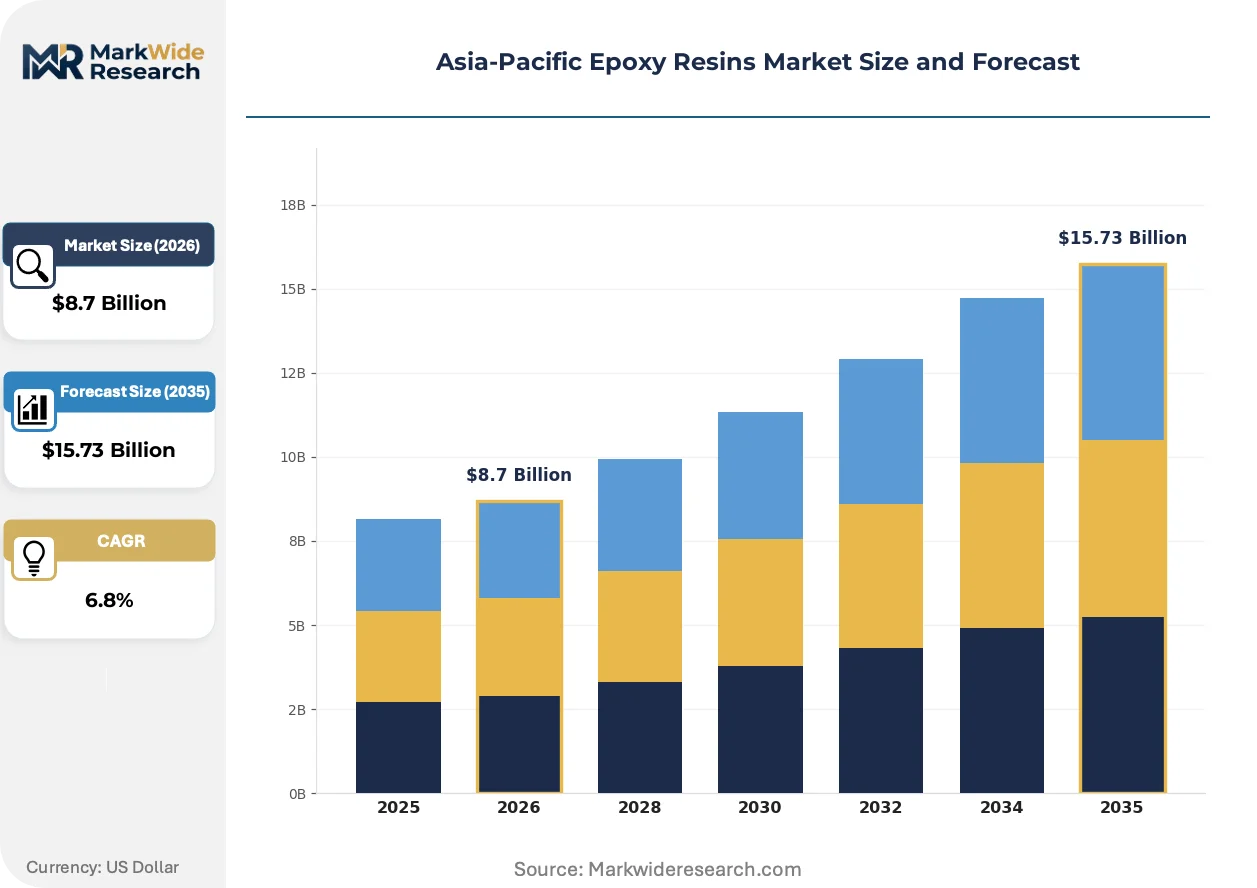
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Epoxy, Solid Epoxy, Water-Based Epoxy, Epoxy Powder Application: Coatings, Adhesives, Composites, Electrical Encapsulation End User: Automotive, Aerospace, Construction, Marine Formulation: Bisphenol A, Bisphenol F, Novolac, Others |
| Companies Covered | Nan Ya Plastics Corporation, Kukdo Chemical Co., Ltd., Chang Chun Petrochemical, Huntsman International LLC, Covestro AG, Mitsubishi Chemical, Aditya Birla Chemicals, 3M, Hexion, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Epoxy Resins Market Strategic Shifts
Formulation chemistry is pivoting toward bio-based feedstocks and low-carbon curing systems as energy-intensive thermoset production faces carbon accounting pressure from downstream customers.
Bio-based epichlorohydrin derived from glycerol is decomposing the fossil-dependent raw material structure of conventional epoxy supply chains. Wind turbine manufacturers in China are qualifying these alternatives for blade shell laminates. The shift is compressing premium pricing power for petrochemical-integrated incumbents.
China's GB standards for VOC content in industrial coatings are eliminating solvent-based epoxy formulations from state-procured infrastructure projects. Coatings applicators in Jiangsu and Zhejiang provinces are converting spray lines to high-solids systems. Automotive OEMs are accelerating water-based primer specifications to maintain supplier qualification status.
Specification engineers at electronics assemblers are consolidating adhesive vendors around certified low-halogen epoxy grades. Taiwan-based PCB fabricators are driving this consolidation through blanket purchase agreements with tier-one chemical distributors. The pattern concentrates procurement leverage with qualified suppliers possessing integrated testing laboratories.
Asia-Pacific Epoxy Resins Market Segmentation
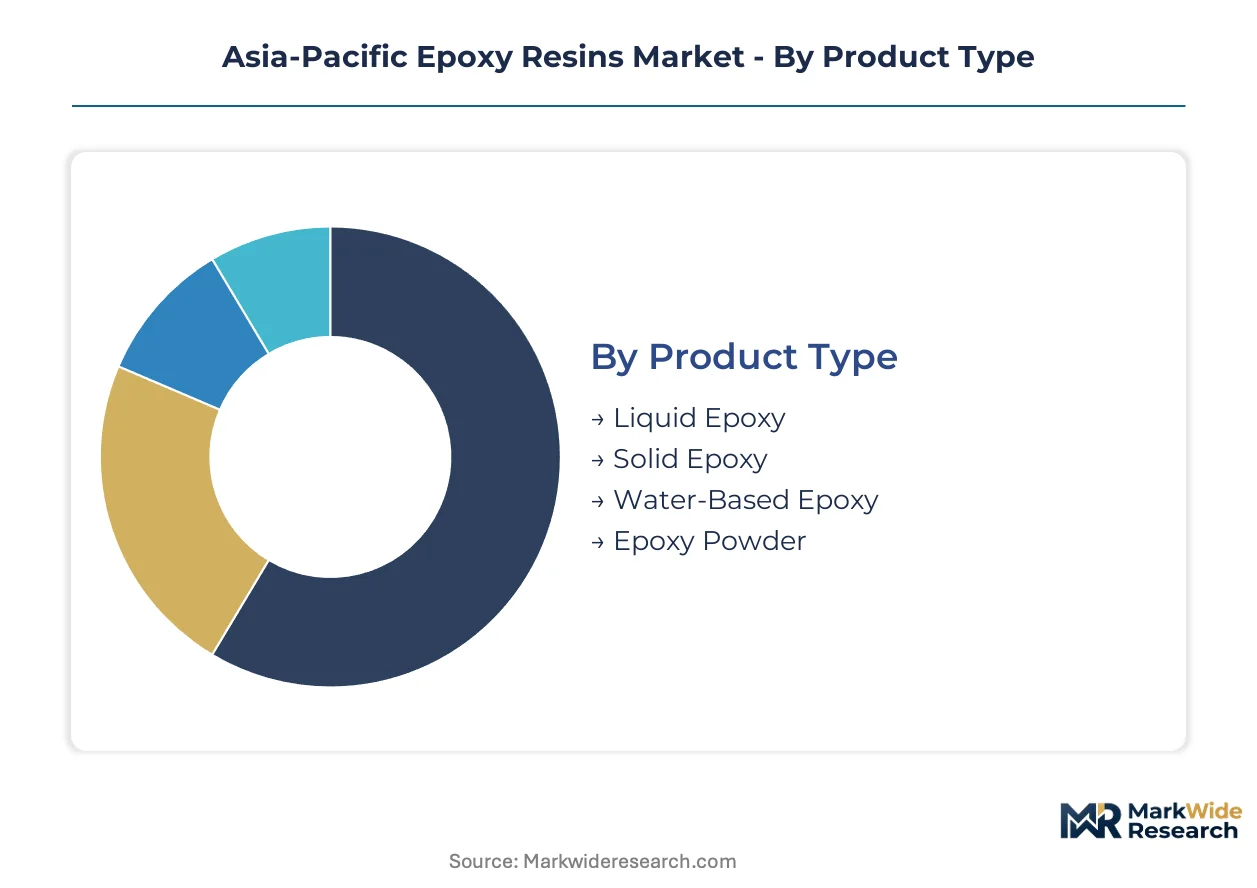
Epoxy resin segmentation in the Asia-Pacific region reflects divergent compliance burdens across formulation chemistries and end-use specifications. Product differentiation now hinges on VOC content thresholds and carbon accounting requirements rather than purely technical performance.
Product Type:
China's MEE enforces divergent VOC limits that stratify product viability across solvent content levels.
- Liquid Epoxy:Low-viscosity prepolymers formulated with reactive diluents dominate high-throughput coating operations in Jiangsu and Zhejiang provinces. Wind turbine blade manufacturers in eastern China specify these grades for vacuum infusion processes where flow characteristics control laminate quality.
- Solid Epoxy:Higher molecular weight grades with elevated glass transition temperatures serve powder coating systems for automotive OEMs navigating GB standards compliance. These formulations eliminate solvent emissions entirely but require elevated cure temperatures that strain energy budgets at mid-tier applicators.
- Water-Based Epoxy:Emulsified systems with reduced volatile content address state-procured infrastructure projects where solvent-based alternatives face disqualification.
- Epoxy Powder:Pre-reacted solid resins for electrostatic spray applications command premium positioning in appliance and architectural metal finishes.
Liquid epoxy handles the majority of throughput; water-based epoxy is the fastest mover on share.
Application:
Cost tier differentiation separates commodity coating volumes from specialty electrical grades.
- Coatings:Protective and decorative film-forming applications consume the largest volume share across marine, industrial, and automotive substrates. China's state-owned infrastructure procurement now mandates water-based or high-solids systems exclusively.
- Adhesives:Structural bonding formulations for construction and transportation applications face BIS certification requirements in India that create market access thresholds.
- Composites:Fiber-reinforced matrices for wind turbine blades and aerospace components concentrate demand in China's coastal manufacturing corridors.
- Electrical Encapsulation:Novolac-based grades penetrate transformer and switchgear applications where thermal performance requirements exceed standard bisphenol-A capabilities.
Coatings absorbs the greatest volume; electrical encapsulation is climbing the fastest on specification intensity.
End User:
Customer type concentration varies sharply between state-directed infrastructure and export-oriented manufacturing.
- Automotive:OEM specifications in Japan and South Korea drive qualification requirements for underhood electrical components and body-in-white adhesives.
- Aerospace:Certification-intensive applications in Japan and Australia demand traceable supply chains with integrated testing documentation.
- Construction:India's infrastructure investment creates demand for BIS-certified structural adhesives and protective coatings.
- Marine:Shipbuilding clusters in South Korea and China specify corrosion-resistant coating systems for newbuild and maintenance cycles.
Construction leads on volume pull; automotive is gaining share fastest on electrification-driven adhesive specifications.
Formulation:
Feedstock integration depth determines margin sustainability across chemistry families.
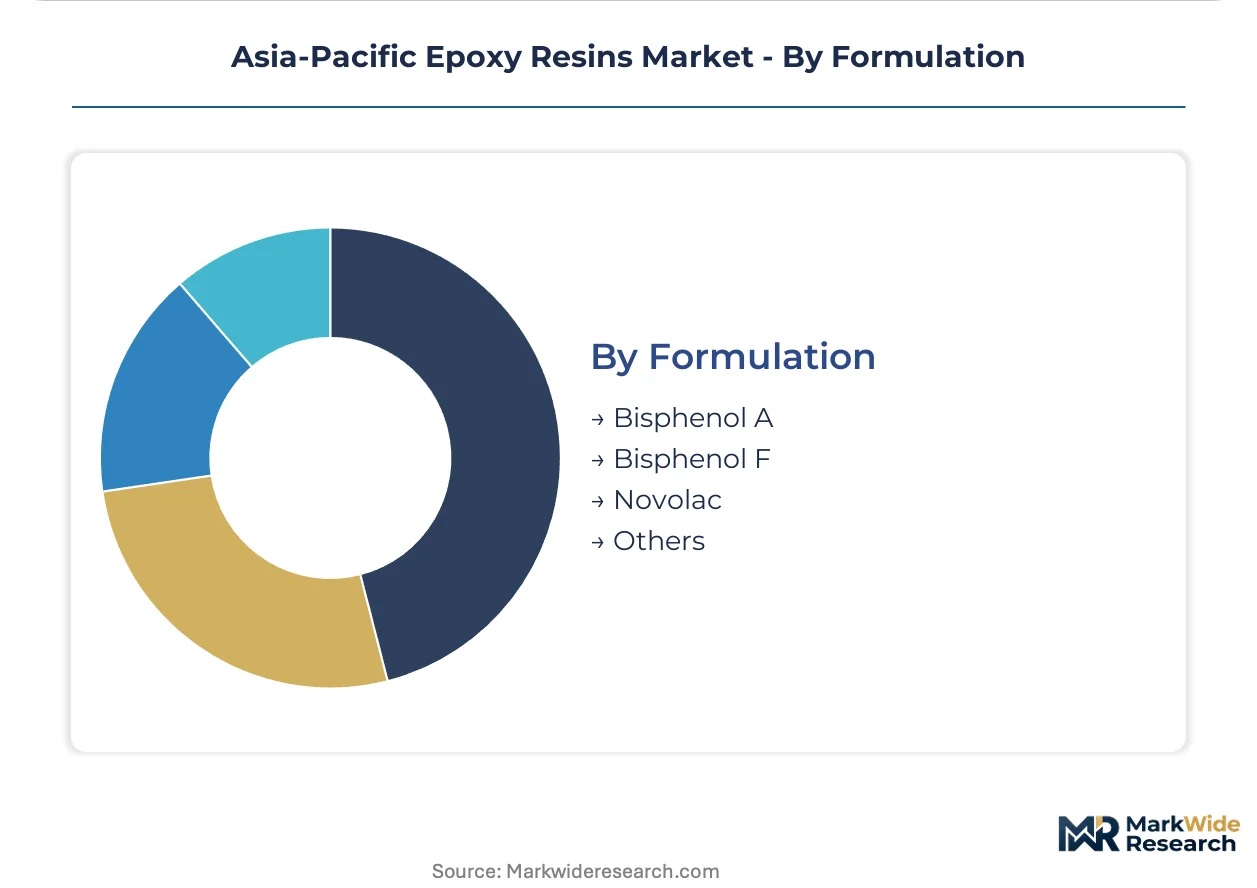
- Bisphenol A:The dominant feedstock category leverages established phenol-acetone supply chains with integrated producers sustaining cost leadership. China's dual carbon goals are pressuring carbon-intensive bisphenol-A production routes.
- Bisphenol F:Lower viscosity alternatives with improved chemical resistance serve high-performance coating and adhesive segments where application speed matters.
- Novolac:Phenol-formaldehyde derived epoxies with elevated crosslink density penetrate high-temperature electrical encapsulation where thermal degradation limits constrain bisphenol alternatives.
- Others:Specialty grades including hydrogenated bisphenol-A and bio-based epichlorohydrin derivatives address niche sustainability requirements.
Bisphenol A retains the dominant share; novolac is expanding most quickly on thermal performance premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wind turbine blade manufacturers and electronics fabricators concentrate procurement leverage across eastern coastal provinces, while automotive OEMs in Japan and South Korea drive specialty grade qualification requirements.
China
MEE enforcement of VOC content limits redirects coating procurement toward water-based and high-solids formulations. The dual carbon goals pressure carbon-intensive bisphenol-A production routes. Jiangsu and Zhejiang provinces host dense clusters of epoxy-consuming electronics and automotive production converting spray lines to compliant systems.
Japan
Electronics assemblers consolidate adhesive vendors around certified low-halogen epoxy grades for PCB fabrication. METI coordinates chemical substance reporting with South Korea's MFDS to reduce cross-border compliance friction. Tokyo and Osaka industrial corridors concentrate demand for high-voltage electrical encapsulation in transformer applications.
South Korea
Integrated producers control critical epichlorohydrin pipeline capacity, creating import dependency for smaller Chinese blenders. MFDS substance reporting alignment with Japan reduces regulatory friction for regional suppliers. Ulsan and Yeosu petrochemical complexes anchor captive feedstock positions for epoxy resin production.
India
Infrastructure investment creates demand for BIS-certified structural adhesives and protective coatings in construction applications. BIS certification mandates for construction-grade adhesives establish market access thresholds. Maharashtra and Gujarat industrial corridors concentrate procurement for specialty electrical encapsulation grades.
Taiwan
PCB fabricators drive vendor consolidation through blanket purchase agreements with tier-one chemical distributors. Chlorohydrin-to-epoxy pipeline integration supports volume supply positioning. Hsinchu and Taichung science parks concentrate demand for high-purity grades in semiconductor packaging applications.
Asia-Pacific Epoxy Resins Market Competitive Environment
Player mix skews toward integrated petrochemical conglomerates with captive bisphenol-A and epichlorohydrin positions. Three structural tiers separate feedstock-integrated majors, regional formulation specialists, and import-dependent blenders. Capacity expansion and hardener chemistry substitution represent the dominant competitive vectors as regulatory pressure on aromatic amines intensifies.
Within the integrated feedstock tier, Nan Ya Plastics Corporation and Kukdo Chemical Co., Ltd. represent archetypes of chlorohydrin-to-epoxy pipeline control. Aditya Birla Chemicals occupies a position among specialty-grade suppliers focused on electrical encapsulation applications. These three exemplify how backward integration into phenol-acetone or chlorohydrin feedstocks determines margin sustainability across formulation chemistry families.
| Leading Market Players |
|---|
| Nan Ya Plastics Corporation |
| Kukdo Chemical Co., Ltd. |
| Chang Chun Petrochemical |
| Huntsman International LLC |
| Covestro AG |
| Mitsubishi Chemical |
| Aditya Birla Chemicals |
| 3M |
| Hexion |
| Others |
Value Chain & Pricing Dynamics
GB/T 13657 certification gates both supplier qualification and price differentiation simultaneously, creating a bifurcated market where certified producers command premium positioning while uncertified blenders compete on spot pricing. This regulatory threshold compresses margins for non-compliant participants and concentrates procurement leverage with integrated majors possessing in-house testing laboratories.
Pricing Analysis
Cost-plus contracts with phenol-acetone indexation dominate long-term offtake agreements between integrated producers and wind turbine OEMs in eastern China. Price differentiation rests on certification tier and captive feedstock position, with GB/T 13657-qualified suppliers extracting premiums over import-dependent blenders. Cost compression in the spot market intensifies as bio-based epichlorohydrin alternatives erode traditional petrochemical pricing power. Volume buyers in the electronics segment exhibit lowest price sensitivity due to traceability requirements, while mid-tier coating applicators face acute margin pressure from spray line retrofit costs.
Supply Chain Analysis
Inventory cycles for liquid epoxy grades extend 8-12 weeks at coastal blending facilities, reflecting just-in-time delivery patterns to Jiangsu and Zhejiang coating operations. Supply concentrates in South Korea, China, and Taiwan, with Ulsan and Yeosu complexes anchoring regional epichlorohydrin availability. Raw material flows draw from phenol-acetone crackers and glycerol-derived bio-routes, with chlorohydrin pipeline capacity constraining smaller Chinese blenders. Single-source vulnerability runs through Korean chlorohydrin producers. Distribution feeds through tier-one chemical distributors holding blanket agreements with Taiwan-based PCB fabricators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against thermoplastic displacement in automotive underhood applications, where polyamide and PBT compounds erode epoxy's thermal cycling position. Incumbents must fortify feedstock integration and certification moats to preserve margin structure.
For Market Incumbents: Secure captive bisphenol-A positions through phenol-acetone integration or long-term supply anchoring to neutralize feedstock volatility. Accelerate GB/T 13657 certification coverage across specialty grades to widen the compliance gap against uncertified competitors. Defend against thermoplastic substitution by qualifying novolac-based formulations for high-temperature electrical encapsulation where bisphenol alternatives degrade.
For New Entrants and Emerging Players: Lead with BIS-certified construction adhesives for India's infrastructure corridor, where certification mandates create first-mover advantage before incumbent qualification cycles complete. Target water-based epoxy formulations for state-procured Chinese infrastructure projects facing solvent-based disqualification under MEE standards. Establish technical service partnerships with mid-tier coating applicators in Jiangsu and Zhejiang unable to fund independent spray line conversions.
For Investors and Strategic Acquirers: China's dual carbon goals reshaping the acquisition landscape toward bio-based feedstock capabilities and low-carbon curing system portfolios. Long-term viability centers on producers with demonstrated glycerol-to-epichlorohydrin technology maturation and carbon accounting transparency. Acquisition target archetype: regional formulation houses with GB/T 13657 certification progress and underutilized blending capacity in eastern China. Watch aromatic amine hardener substitution timelines as the inflection signal for reformulation capex cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phenol-Acetone | Kukdo Chemical's captive feedstock position sustains cost leadership across Korean and Chinese markets. |
| GB/T 13657 Certification Investment | Testing laboratory accreditation concentrates procurement leverage with qualified suppliers in wind turbine blade supply chains. |
| Bio-Based Epichlorohydrin Scale-Up | Glycerol-derived routes decompose fossil-dependent supply structures and compress premium pricing for petrochemical incumbents. |
| Water-Based Formulation Transition | Emulsified systems capture state-procured infrastructure volumes where solvent-based alternatives face MEE disqualification. |
| Long-Term Supply Agreement with Wind OEMs | Indexed contracts with Chinese nacelle assemblers lock in structural epoxy matrix volumes across turbine scaling cycles. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of customs trade data, ACC regional reports, and SEC filings from listed chemical producers. Interviews with plant managers at integrated epoxy facilities, procurement leads at wind turbine OEMs, distribution channel partners in Taiwan and South Korea, and technical R&D directors at formulation houses inform demand-side validation. Bottom-up volume estimates from end-use consumption patterns triangulate against top-down production capacity assessments across the Asia-Pacific chlorohydrin-to-epoxy pipeline.
Segmentation dimensions modeled include formulation chemistry (bisphenol-A, novolac, bio-based), physical form (liquid, solid, water-based, powder), application category (coatings, adhesives, composites, electrical encapsulation), and end-use industry concentration across the projection horizon. CAGRs derive from regression analysis of historical consumption patterns against capacity expansion announcements and regulatory compliance timelines. Forecast inputs incorporate MEE VOC enforcement trajectories and dual carbon policy implementation pacing.
The analysis sits within stated boundaries; outcomes outside sustained Chinese wind turbine installation rates or accelerated aromatic amine regulatory restrictions would require recalibration. Forecasts reflect documented assumptions regarding feedstock price correlation and certification timeline stability. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Global Bio Based Polyurethane Market
Polymers & Resins
Methacrylate Monomers Market
Polymers & Resins
Resin Cement for Luting Market
Polymers & Resins
HDPE Large Blow Molded Products Market
Polymers & Resins
Global One Component Polyurethane Foam Market
Polymers & Resins
Poly Alpha Olefin (PAO) Market
Polymers & Resins
Casting Resin Market
Polymers & Resins
BMI Resins Market
Polymers & Resins
Polystyrene Market
Polymers & Resins
Bio-Based Polypropylene in Medical Devices Market
Polymers & Resins
Polyacrylic Acid Market
Polymers & Resins
Germany Polymer Emulsion Market
Polymers & Resins
Acrylonitrile Butadiene Styrene (ABS) Market
Polymers & Resins
Global Anti-Vibration Polymer Market
Polymers & Resins
Polyethersulfone (PES) Market
Polymers & Resins
Germany Engineering Plastics Market