
 Foamed Plastics Market | 2026-2036
Foamed Plastics Market Size, Share, and Industry Trends Forecast 2026-2036
Foamed Plastics Market Intelligence
Skilled polyurethane formulator availability is collapsing across European chemical hubs, tightening capacity expansion timelines for specialty grades. BASF SE leverages integrated polyol production at Ludwigshafen to secure captive feedstock for rigid foam systems. Covestro AG anchors its position through MDI technology leadership in high-performance insulation panels. Huntsman Corporation competes on spray foam formulation depth tied to North American construction retrofit cycles.
Foamed plastics are cellular polymer structures created by dispersing gas bubbles within a thermoplastic or thermoset matrix, typically achieving densities below 0.05 g/cm³ for rigid insulation grades and 0.02–0.06 g/cm³ for flexible variants, with cell architecture determining compressive strength and thermal conductivity. The primary industrial purpose centers on weight reduction combined with cushioning, thermal insulation, or barrier protection across manufactured goods. Polyurethane foam dominates value generation due to its versatility across temperature ranges and bonding chemistry, while polystyrene foam retains volume leadership in disposable packaging despite sustainability headwinds. Polyethylene foam is carving faster expansion in protective packaging for electronics and medical devices where closed-cell moisture resistance commands premium positioning.
EPA Significant New Alternatives Policy program and REACH Annex XVII restrictions on hydrofluorocarbon blowing agents are forcing reformulation roadmaps across foam producers serving North American and European markets. China's GB standards on building energy efficiency and SAMR product quality certifications are tightening market access for imported insulation systems. India's BIS certification requirements for construction materials are raising compliance thresholds for regional foam converters. Stakeholders must monitor blowing agent transition economics and regional certification divergence to avoid stranded formulation investments.
Market Dynamics
REACH Annex XVII restrictions on hydrofluorocarbon blowing agents are forcing a complete reformulation of rigid foam systems across European converter networks, compressing margins while accelerating investment in CO2 and water-based alternatives.
Growth Catalysts
- Automotive lightweighting mandates:Polyurethane foam penetration in vehicle seating and insulation panels is deepening as OEMs pursue gram-per-kilometer reduction targets under EU CO2 fleet standards.
- Building energy efficiency codes:China's GB standards on thermal performance are mandating thicker insulation layers in new construction, pulling demand for high-R-value rigid foam systems.
- Circular feedstock integration:Chemical recycling of post-consumer polyurethane into repolyols is gaining technical validation, opening alternative raw material pathways for formulators.
Market Restraints
- Feedstock concentration risk:MDI supply clusters in the US Gulf Coast and Rotterdam-Antwerp corridor, exposing converters to single-point disruption from hurricanes or port congestion.
- Reformulation cost compression:Transition from HFC to hydro-olefin blowing agents requires capital-intensive equipment retrofits at extrusion and molding facilities.
- Polystyrene substitution pressure:Molded pulp and corrugated fiber protective packaging is capturing electronics and appliance segments where expanded polystyrene previously dominated.
Strategic Opportunities
- India construction certification gap:BIS standards for insulation materials remain underdeveloped versus EU and Chinese benchmarks, creating first-mover positioning for certified foam system suppliers.
- Medical device protective packaging:Closed-cell polyethylene foam is penetrating sterilizable barrier systems for implantable devices where gamma stability and particulate control command premium pricing.
- EU F-Gas Regulation phase-down:The 2030 GWP reduction targets are creating guaranteed demand pull for next-generation blowing agent technologies with sub-150 GWP profiles.
Industry Challenges
- Polyurethane formulator talent scarcity:European chemical engineering programs are producing fewer specialists in isocyanate handling and reaction injection molding, extending recruitment cycles for technical service roles.
- Multi-certification compliance burden:Foam converters serving multinational appliance manufacturers must maintain parallel testing protocols for UL, CE marking, and SAMR registrations, duplicating quality assurance overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Foamed Plastics Market |
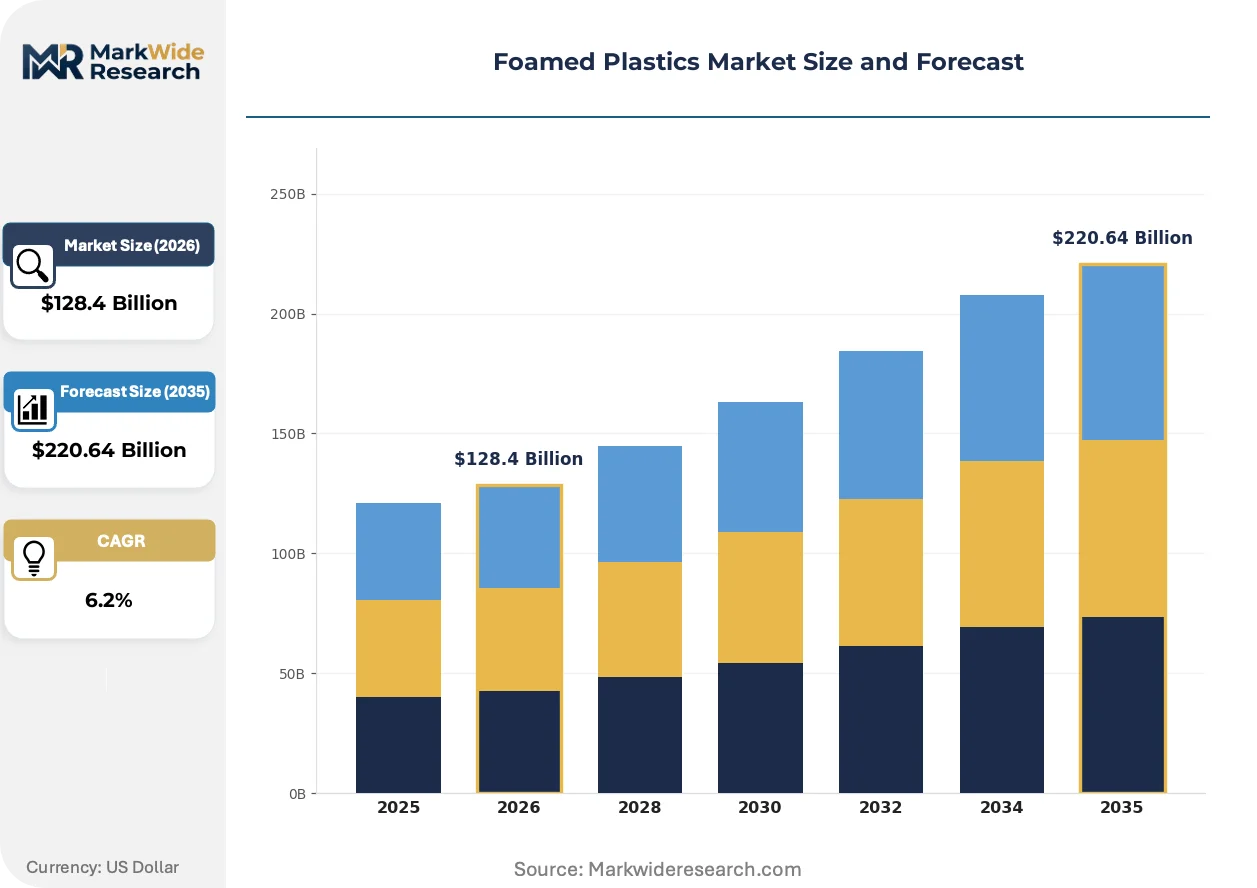
| Market Size in 2026 | $128.4 Billion |
| Market Size in 2035 | $220.64 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyurethane Foam, Polystyrene Foam, Polyethylene Foam, PVC Foam End Use Industry: Construction, Automotive, Packaging, Consumer Goods Foaming Agent: Water, Chemical Blowing Agents, Hydrocarbons, CO2 Form: Flexible Foam, Rigid Foam, Spray Foam, Foam Sheets |
| Companies Covered | BASF SE, Covestro AG, Huntsman Corporation, Dow Inc., Armacell International S.A., Sealed Air Corporation, Carpenter Co., Berry Global Inc., Wanhua Chemical Group Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Foamed Plastics Market Strategic Shifts & Innovations
Bio-based polyol feedstocks, next-generation blowing agent chemistry, and digital formulation platforms are converging to reshape competitive differentiation in foam system supply. These developments are compressing traditional R&D cycles while raising the technical threshold for market participation.
CO2-blown rigid polyurethane foam is displacing legacy HFC-365mfc systems in European appliance insulation manufacturing. Whirlpool and BSH Hausgeräte have completed production line conversions at Polish and German plants. The technology is displacing incumbent blowing agent suppliers while forcing equipment manufacturers to redesign high-pressure mixing heads for lower-viscosity formulations.
EPA Significant New Alternatives Policy program approvals for trans-1-chloro-3,3,3-trifluoroprop-1-ene and other low-GWP alternatives are accelerating US regulatory alignment with EU F-Gas phase-down schedules. Spray foam contractors in Texas and Florida are retrofitting rigs for hydro-olefin compatibility. The construction retrofit segment is absorbing compliance costs through extended financing terms rather than price premiums.
Direct-to-facility technical service contracts are replacing distributor-mediated formulation support in North American automotive seating programs. Lear Corporation and Adient are embedding polyurethane specialists at Tier 1 molding operations to compress development cycles for new vehicle platforms. Michigan and Ohio converter clusters are centralizing this procurement evolution through co-located engineering centers.
Foamed Plastics Market Segmentation
Foam system specification varies sharply across end-use applications, with regulatory pressure on blowing agents and density requirements driving category-level divergence in formulation investment. Understanding segment boundaries helps converters align technical capabilities with certification demands.
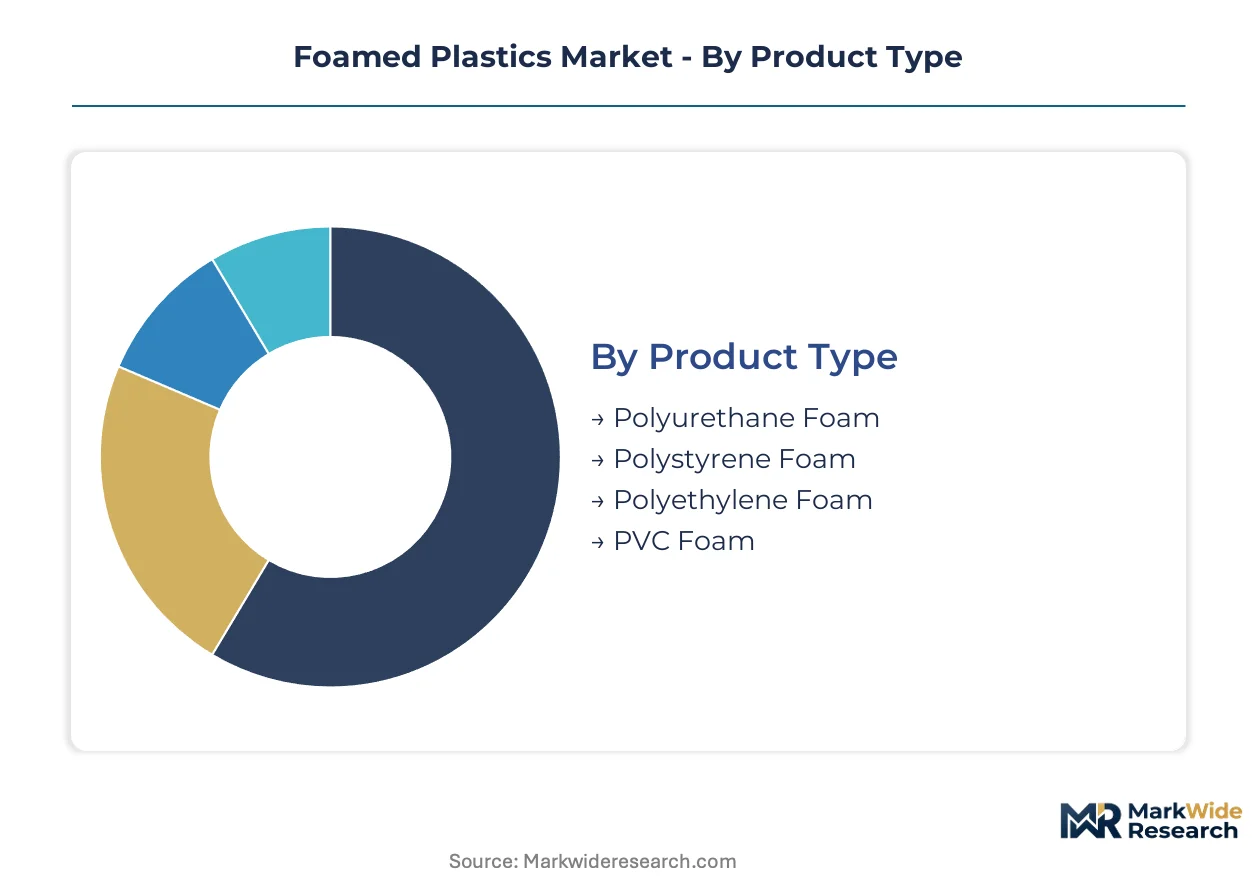
Product Type:
REACH Annex XVII and EPA SNAP program restrictions on high-GWP blowing agents are fragmenting competitive positioning across polymer chemistries, favoring systems compatible with CO2 and water-based expansion.
- Polyurethane Foam:Thermoset cellular structures formed through isocyanate-polyol reaction chemistry achieve density ranges from 0.02 g/cm³ for flexible cushioning grades to 0.05 g/cm³ for rigid insulation panels. Automotive seating programs in Germany and appliance manufacturing in China concentrate demand, with OEMs specifying MDI-based systems for gram-per-kilometer and energy efficiency compliance. REACH restrictions on legacy HFC blowing agents are forcing complete reformulation roadmaps for European converters.
- Polystyrene Foam:Expanded and extruded thermoplastic cellular structures derived from styrene monomer polymerization retain cost leadership in protective packaging and building insulation despite sustainability headwinds. Disposable food service applications face substitution pressure from molded pulp in California and EU markets, while construction-grade XPS retains share in below-grade waterproofing where moisture resistance is non-negotiable.
- Polyethylene Foam:Closed-cell thermoplastic structures manufactured through cross-linked or non-cross-linked extrusion processes deliver gamma stability and particulate control for medical device barrier systems.
- PVC Foam:Cellular polyvinyl chloride structures offer flame-retardant characteristics and weathering resistance for marine and transportation applications.
Polyurethane foam handles the majority of throughput; polyethylene foam is the fastest mover on share.
End Use Industry:
Customer procurement patterns split between specification-driven OEM programs and price-sensitive merchant markets, with certification burden varying accordingly.
- Construction:Rigid insulation panels, spray foam sealants, and below-grade waterproofing systems dominate volume, with China's GB energy efficiency standards mandating thicker thermal barriers in new builds. BIS certification requirements in India are raising compliance thresholds for regional converters, while EU F-Gas Regulation phase-downs are redirecting specification toward low-GWP blowing agent systems.
- Automotive:Seating foam, interior trim, and acoustic insulation panels are deepening polyurethane penetration as OEMs pursue lightweighting targets under EU CO2 fleet standards.
- Packaging:Protective cushioning for electronics and appliances faces substitution from corrugated fiber and molded pulp in sustainability-sensitive segments.
- Consumer Goods:Bedding, furniture cushioning, and recreational equipment represent fragmented demand with shorter specification cycles.
Construction absorbs the largest volume base; automotive applications are expanding most quickly on specification intensity.
Foaming Agent:
Environmental regulator timelines are compressing technology transition windows, with capital equipment decisions locking in agent selection for decade-long horizons.
- Chemical Blowing Agents:Azodicarbonamide and similar exothermic decomposing compounds generate gas through thermal activation in polyolefin and PVC processing. Regulatory scrutiny on residual decomposition products is tightening in EU and US food-contact applications, pushing investment toward physical blowing alternatives.
- CO2:Supercritical carbon dioxide systems are displacing legacy HFC-365mfc in European appliance insulation manufacturing, with Whirlpool and BSH Hausgeräte completing production line conversions at Polish and German plants.
- Hydrocarbons:Cyclopentane and isobutane blends dominate Asian refrigerator insulation production, with flammability handling requirements shaping facility investment.
- Water:Reaction-generated CO2 from isocyanate-water chemistry provides zero-GWP expansion for polyurethane systems, though dimensional stability trade-offs limit application scope.
Chemical blowing agents retain the largest installed base; CO2 systems are climbing the fastest on regulatory alignment.
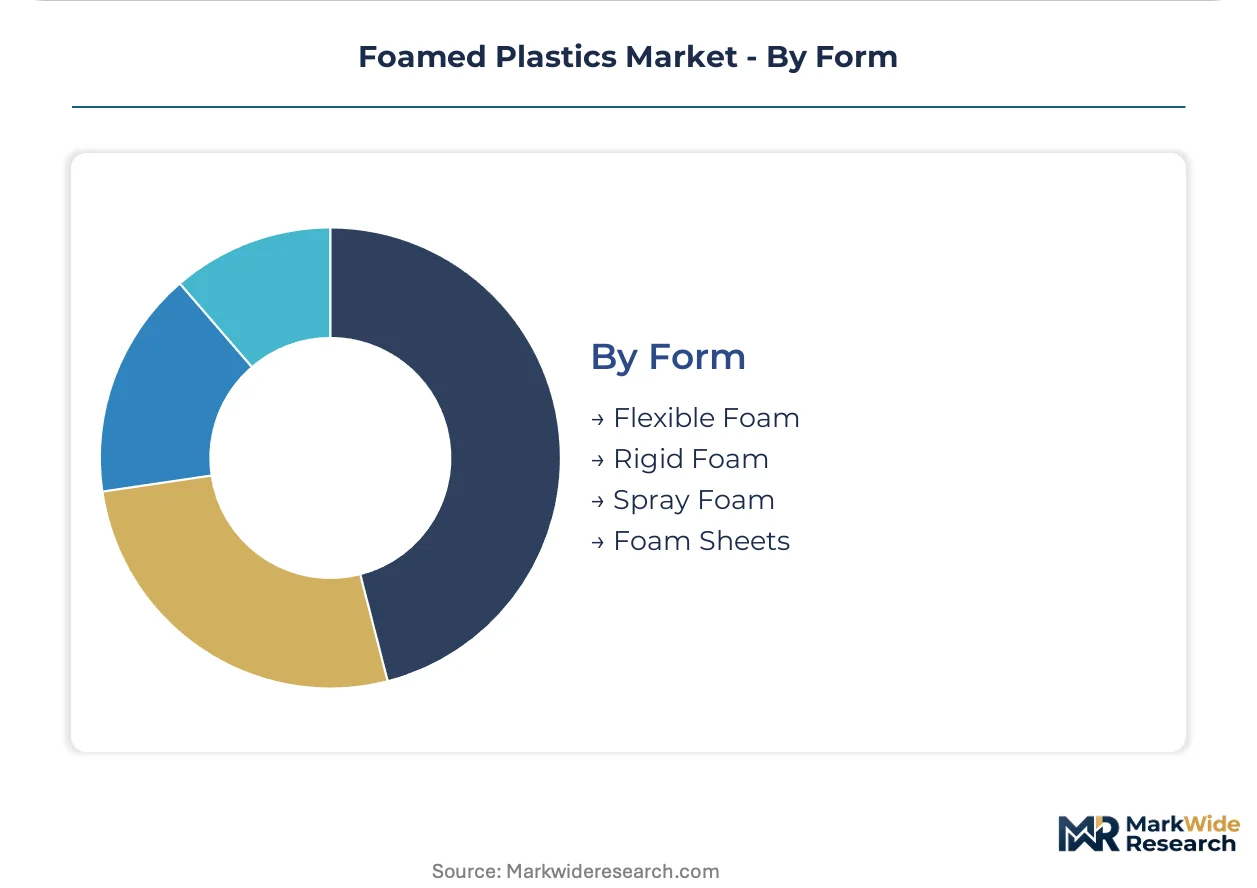
Form:
Processing technology and end-use installation requirements determine form selection, with equipment specialization creating segment boundaries.
- Rigid Foam:Closed-cell thermoset or thermoplastic structures with compressive strength above 100 kPa serve structural insulation and buoyancy applications. European building retrofit programs and Chinese new construction codes are pulling demand for high-R-value panels, with spray-applied and board-stock formats competing on labor cost and thermal bridging performance.
- Flexible Foam:Open-cell structures with compression set resistance below 10% dominate seating and bedding applications, with density and indentation force deflection specifications varying by comfort tier.
- Spray Foam:On-site reaction and application systems enable complex geometry coverage in building envelopes and industrial insulation.
- Foam Sheets:Roll-stock and cut-to-size formats serve packaging and gasket fabrication with shortest lead times.
Rigid foam commands the greatest value concentration; spray foam is gaining share fastest on building envelope performance standards.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across major economies. China deploys foamed plastics primarily for construction insulation and appliance manufacturing, while Germany concentrates on automotive lightweighting and high-performance building envelopes. The United States splits demand between construction retrofit cycles and protective packaging for e-commerce logistics.
China
GB standards on building energy efficiency mandate thicker thermal barriers in new residential and commercial construction. SAMR product quality certifications tighten market access for imported insulation systems, favoring domestic converters with established compliance pathways. The Yangtze River Delta cluster around Shanghai hosts dense networks of appliance manufacturers and polyol distributors serving rigid foam demand.
Germany
EU CO2 fleet standards drive polyurethane penetration in automotive seating and interior trim at BMW, Mercedes-Benz, and Volkswagen supply chains. REACH Annex XVII restrictions on hydrofluorocarbon blowing agents force complete reformulation of rigid foam systems across converter networks. The Ludwigshafen chemical complex anchors captive polyol production for BASF SE's integrated foam system supply.
United States
EPA SNAP program approvals for low-GWP hydro-olefin blowing agents accelerate regulatory alignment with EU phase-down schedules. Construction retrofit cycles in Texas and Florida absorb compliance costs through extended contractor financing terms. The US Gulf Coast concentration of MDI production exposes converters to hurricane-related supply disruptions.
India
BIS certification requirements for construction materials raise compliance thresholds for regional foam converters serving building envelope applications. Bureau of Energy Efficiency building codes create incremental demand pull for high-R-value insulation in commercial real estate development. Maharashtra and Gujarat host emerging converter clusters targeting appliance and automotive Tier 1 supply chains.
Japan
METI energy efficiency standards for residential buildings specify performance thresholds that favor rigid polyurethane panels over legacy insulation materials. JIS certification protocols for construction products maintain quality differentiation in premium building segments. The Kansai region around Osaka concentrates specialty foam fabricators serving electronics protective packaging and medical device barrier systems.
Foamed Plastics Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier in foamed plastics supply. European and North American chemical conglomerates control upstream polyol and isocyanate production, while regional converters compete on formulation service and application engineering. Three archetypes dominate: integrated chemical producers with captive feedstock, independent foam system formulators with technical service depth, and packaging-focused material specialists with extrusion scale. Capacity expansion and blowing agent transition partnerships constitute the primary competitive vectors as regulatory deadlines compress.
Among integrated chemical producers, BASF SE and Covestro AG exemplify the upstream-control archetype through Ludwigshafen and Leverkusen manufacturing positions. Huntsman Corporation occupies a position within the North American formulation tier. Wanhua Chemical Group Co., Ltd. represents the scale-driven Asian producer segment. These three anchors illustrate how geographic feedstock access and regulatory proximity shape competitive positioning across the industry structure.
| Leading Market Players |
|---|
| BASF SE |
| Covestro AG |
| Huntsman Corporation |
| Dow Inc. |
| Armacell International S.A. |
| Sealed Air Corporation |
| Carpenter Co. |
| Berry Global Inc. |
| Wanhua Chemical Group Co., Ltd. |
| Others |
Cost & Logistics Intelligence
Capacity utilization at integrated polyol-isocyanate complexes in Ludwigshafen and the US Gulf Coast shapes both supply concentration and price floors for specialty foam grades. Scale economies in captive feedstock production insulate BASF SE and Covestro AG from raw material volatility that compresses margins at merchant formulators.
Pricing Analysis
Long-term offtake contracts dominate procurement between automotive OEMs and Tier 1 foam molders, with three-year agreements locking in volume commitments for seating programs. Price differentiation rests on REACH-compliant blowing agent certification and MDI grade purity, with standard formulations facing compression from CO2-blown alternatives. Pricing pressure stems from reformulation costs as converters retire HFC-365mfc systems. Appliance manufacturers exhibit highest price sensitivity due to thin margins on mass-market refrigerator lines, while medical device barrier packaging commands premium stability.
Supply Chain Analysis
Just-in-time inventory strategies prevail at European automotive seating plants, while Asian appliance manufacturers maintain strategic polyol stockpiles ahead of cyclical demand surges. MDI supply concentrates in Germany, the United States, and China, with feedstock anchored in naphtha crackers and imported benzene derivatives. Supply chain risk centers on hurricane exposure at US Gulf Coast isocyanate production hubs. Distribution runs through converter networks co-located with OEM assembly plants in Michigan, Lower Saxony, and the Yangtze River Delta.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment around REACH-compliant blowing agent formulations creates defensive moats for incumbents with validated conversion roadmaps. Switching costs rise as automotive OEMs embed technical service teams at Tier 1 molding operations.
For Market Incumbents: Compound certification depth by securing parallel UL, CE marking, and SAMR registrations for next-generation CO2-blown systems. Extend captive polyol capacity at Leverkusen or Ludwigshafen to offset merchant feedstock vulnerability. Defend against specialty chemical entrants by embedding formulation specialists at Lear Corporation and Adient engineering centers.
For New Entrants and Emerging Players: Technical service gaps in Indian BIS certification support create white-space openings for foam system suppliers with compliance expertise. Target Maharashtra and Gujarat converter clusters where appliance and automotive Tier 1 supply chains concentrate. Penetrate through direct-to-facility engineering contracts rather than distributor-mediated sales.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated chemical producers with captive isocyanate supply and long-term automotive offtake agreements. Five-to-ten-year viability favors backward-integrated specialists with validated low-GWP blowing agent platforms. Monitor EPA SNAP program approval velocity for hydro-olefin alternatives as inflection signal for North American retrofit demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polyol Production | Captive feedstock supply insulates BASF SE from benzene derivative volatility at Ludwigshafen. |
| CO2 Blowing Agent Conversion | Whirlpool and BSH Hausgeräte completion validates equipment retrofit economics for appliance insulation. |
| Direct Technical Service Embedding | Lear Corporation and Adient co-location compresses development cycles for new vehicle platforms. |
| BIS Certification Pre-Positioning | First-mover compliance in Maharashtra and Gujarat captures Indian appliance manufacturing expansion. |
| Long-Term Automotive Offtake Agreements | Three-year contracts with BMW and Volkswagen supply chains lock in volume against spot price erosion. |
Research Approach
Cross-validation between primary interviews with polyurethane plant managers, automotive Tier 1 procurement leads, and appliance manufacturing engineers anchors the qualitative findings. Secondary validation draws from ECHA REACH registration databases, EPA SNAP program approval records, and SEC 10-K disclosures from integrated chemical producers. Customs and trade data from Germany, China, and the United States triangulate volume estimates against bottom-up converter capacity assessments.
Sensitivity analysis around blowing agent transition timelines and automotive lightweighting penetration rates shapes the analytical framework. Segmentation dimensions span polymer chemistry, foaming agent technology, end-use industry, and regional regulatory cluster. CAGRs derive from elasticity-adjusted demand modeling across construction retrofit cycles and appliance replacement rates. Industry-specific inputs include MDI price series and GB standard implementation schedules for building energy efficiency.
Forecasts assume regulatory continuity in EU F-Gas Regulation phase-downs and EPA SNAP program trajectories; material policy shifts would require re-modeling. Specific risks encompass hurricane disruption at US Gulf Coast isocyanate production and accelerated polystyrene substitution in electronics packaging. Revision becomes warranted when CO2-blown foam dimensional stability performance crosses commercial viability thresholds for rigid insulation panels.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Polyolefin Compound Market
Polymers & Resins
Global Fluoropolymer Market
Polymers & Resins
Waterborne Polyurethane Dispersions for Automotive Synthetic Leather Market
Polymers & Resins
Modified Alkyd Resin Market
Polymers & Resins
Mixed-Mode Chromatography Resin Market
Polymers & Resins
Microcellular Plastics Market
Polymers & Resins
Polymer Modifiers Market
Polymers & Resins
Metallocene Polyolefin Market
Polymers & Resins
North America Plastic Compounding Market
Polymers & Resins
Bio-Based and Synthetic Polyamide Market
Polymers & Resins
Bio Based Resin Market
Polymers & Resins
Middle East Polyethylene Terephthalate (PET) Market
Polymers & Resins
Soft PVC Sealing Strip Market
Polymers & Resins
Polycyclohexylenedimethylene Terephthalate (PCT) Market
Polymers & Resins
Synthetic Polymer Waxes Market
Polymers & Resins
Global Impregnating Resins Market