
 Carboxymethyl Cellulose Market | 2026-2036
Carboxymethyl Cellulose Market Size, Share, and Industry Trends Forecast 2026-2036
Carboxymethyl Cellulose Market Analysis
Project finance for greenfield cellulose ether plants is tilting competitive dynamics toward firms with balance-sheet capacity to fund multi-year capacity builds. Nouryon Chemicals Holding B.V. leverages its integrated pulp-to-ether supply chain across Northern Europe to sustain margin stability. Ashland Global Holdings, Inc. anchors its position through pharmaceutical-grade specialization and US-based FDA-registered production. CP Kelco competes via controlled fermentation and botanical feedstock expertise in Asia-Pacific manufacturing.
Carboxymethyl cellulose is a water-soluble cellulose ether produced by alkali-catalyzed reaction of cellulose with chloroacetic acid, with degrees of substitution typically ranging from 0.4 to 1.5 that govern viscosity and solubility performance in aqueous systems. It functions primarily as a rheology modifier, stabilizer, and film-former across food, pharmaceutical, and industrial formulations. Food Grade CMC dominates volume throughput as clean-label thickening demand from processed food manufacturers expands, while Pharmaceutical Grade commands premium positioning due to USP-NF and EP compliance burdens. Industrial Grade applications in oilfield drilling and textile sizing represent mature, price-sensitive offtake where powder form factors anchor procurement specifications.
FDA 21 CFR 182.1745 governs food-grade CMC safety thresholds, while REACH registration requirements in Europe constrain import access for non-compliant Asian producers. China's NMPA and GB standards for pharmaceutical excipients are tightening purity specifications for domestic and imported CMC alike. Stakeholders must monitor evolving biopolymer substitution regulations and excipient prequalification timelines across multiple jurisdictions to anticipate demand shifts.
Market Dynamics
Pharmaceutical-grade purity mandates are compressing substitution thresholds for synthetic thickeners, forcing cellulose ether producers to recalibrate process control systems and captive pulp sourcing strategies.
Growth Catalysts
- Controlled-release drug formulations:Pharmaceutical manufacturers in China and India are expanding excipient prequalification programs to secure USP-NF and EP compliance for CMC binders in tablet matrices.
- REACH registration barriers:ECHA's tightened purity specifications for imported cellulose ethers are displacing non-compliant Asian suppliers from European food and pharma channels.
- Clean-label processed food demand:Food manufacturers across North America and Western Europe are reformulating with Food Grade CMC to replace modified starches and synthetic gums on ingredient panels.
Market Restraints
- Chloroacetic acid feedstock volatility:Petrochemical-derived etherifying agents expose CMC producers to crude-linked input cost swings that compress margin stability at standard-grade price points.
- Northern European pulp concentration:Dissolving-grade cellulose supply clusters in Sweden and Finland create geographic chokepoints for integrated ether producers without backward integration into pulp.
- Biopolymer substitution pressure:Xanthan gum and microbial cellulose alternatives are displacing Industrial Grade CMC in oilfield drilling fluid applications where thermal stability requirements have relaxed.
Strategic Opportunities
- Indian pharmaceutical cluster expansion:CDSCO's accelerating excipient prequalification timelines for domestic CMC producers creates first-mover positioning in generic API formulation supply chains.
- Fermentation-derived cellulose convergence:Controlled bacterial cellulose production combined with enzymatic etherification is opening pharmaceutical-grade pathways independent of wood pulp supply constraints.
- Direct procurement platforms:Specialty chemical distributors are building digital excipient marketplaces that compress procurement cycles for mid-sized pharmaceutical formulators in Asia-Pacific.
Industry Challenges
- Multi-jurisdictional compliance timelines:Simultaneous FDA 21 CFR, REACH, and NMPA registration requirements for pharmaceutical-grade CMC extend certification cycles and strain regulatory affairs staffing.
- Degree-of-substitution precision engineering:Tightening viscosity specifications for controlled-release applications demands process analytical technology investments that smaller ether producers struggle to fund.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carboxymethyl Cellulose Market |
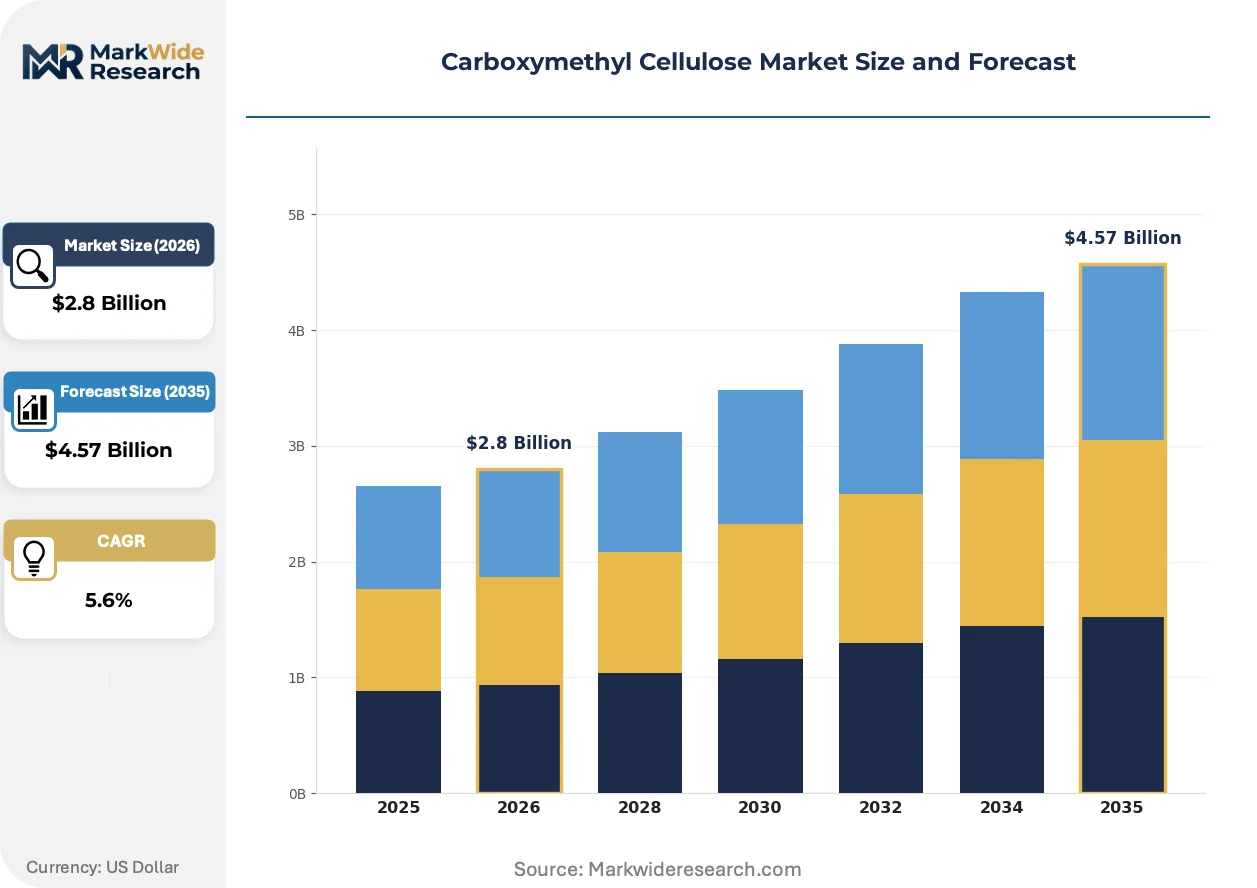
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.57 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food Grade, Pharmaceutical Grade, Industrial Grade, Cosmetic Grade End Use Industry: Food & Beverage, Pharmaceuticals, Cosmetics, Paints Form: Powder, Granules, Liquid, Gel Application: Thickening Agent, Stabilizer, Additive, Filler |
| Companies Covered | Nouryon Chemicals Holding B.V., Ashland Global Holdings, Inc., Dow Chemical Company, CP Kelco, Daicel Corporation, Akzo Nobel N.V., Nippon Paper Industries Co., Ltd., Shandong Head Co., Ltd., Lamberti S.P.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carboxymethyl Cellulose Market Emerging Trajectories
Process analytical technology and enzymatic etherification methods are compressing the cost-performance gap between synthetic and bio-based rheology modifiers across pharmaceutical and food formulation sectors.
Inline spectroscopic monitoring systems are digitizing real-time degree-of-substitution control in continuous cellulose ether reactors. Pharmaceutical excipient manufacturers in Germany and Switzerland are deploying these systems to reduce batch-to-batch viscosity variation. This capability is digitizing quality assurance workflows and enabling just-in-time release protocols that compress inventory holding costs for CMC buyers.
REACH Annex XIV authorization requirements for chloroacetic acid derivatives are tightening process safety documentation burdens for European CMC producers. The regulation is forcing capital allocation toward closed-loop etherification systems with vapor recovery. Food Grade CMC supply chains serving EU member states are most affected, with producers accelerating substitution toward alternative etherifying chemistries.
Formulators are consolidating excipient supplier panels to reduce qualification overhead and secure volume commitments. Mid-sized pharmaceutical companies in India and China are shifting from spot procurement of pharmaceutical-grade CMC toward multi-year offtake agreements with registered producers. This pattern is most visible in oral solid dosage manufacturing clusters around Mumbai and Shanghai, where buyer concentration is compressing spot market liquidity.
Carboxymethyl Cellulose Market Segmentation
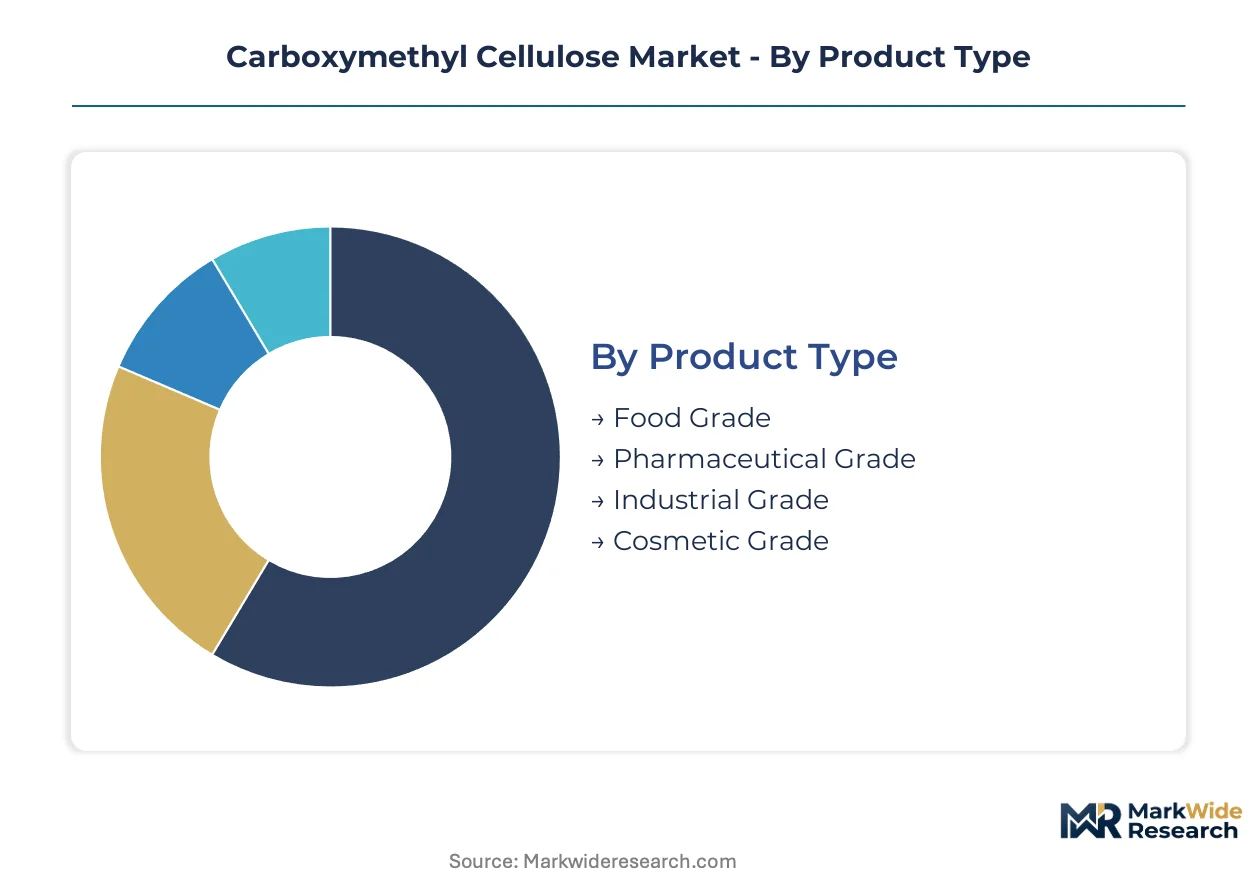
CMC grade purity thresholds and form-factor specifications dictate procurement workflows across pharmaceutical, food, and industrial channels. Segmentation reveals where margin compression meets compliance burden, and where formulation flexibility creates supplier stickiness.
Product Type:
After-sales service intensity escalates with regulatory documentation burdens — pharmaceutical-grade buyers demand batch-specific CoA support and deviation investigation protocols that commodity-grade offtake rarely triggers.
- Pharmaceutical Grade:USP-NF and EP compliance mandates residual solvent limits below 50 ppm and endotoxin thresholds that constrain etherification chemistry choices. Indian generic API manufacturers in Hyderabad and Ahmedabad are expanding excipient prequalification programs to secure CDSCO registration for tablet binder applications.
- Food Grade:FDA 21 CFR 182.1745 governs maximum usage levels in processed foods, with clean-label reformulation in the United States and Germany driving substitution away from modified starches. FSSAI in India and EFSA in Europe are tightening heavy metal specifications simultaneously.
- Industrial Grade:Oilfield drilling fluid applications in Texas and Alberta specify powder form factors with degree-of-substitution ranges optimized for high-salinity tolerance.
- Cosmetic Grade:INCI nomenclature compliance and preservative-free claims in French and South Korean personal care formulations drive low-ash specifications.
By volume, Industrial Grade leads. By growth pace, Pharmaceutical Grade is ahead.
End Use Industry:
Cost tier stratification separates excipient-grade procurement from commodity-volume offtake, with pharmaceutical channels absorbing premium pricing for documentation depth.
- Pharmaceuticals:Controlled-release matrix tablets and ophthalmic formulations in Germany, Switzerland, and the United States demand viscosity grades from 1,000 to 150,000 cP with tight batch-to-batch variation limits. NMPA in China is accelerating domestic excipient prequalification timelines.
- Food & Beverage:Dairy alternatives and gluten-free baked goods in California and the Netherlands specify Food Grade CMC for mouthfeel modulation without allergen labeling triggers.
- Cosmetics:Sheet mask formulations in South Korea and Japan utilize low-viscosity grades for film-forming without tack residue.
- Paints:Waterborne architectural coatings in Germany and the United States specify Industrial Grade for sag resistance and pigment suspension.
Pharmaceuticals commands the steepest price premiums. Food & Beverage delivers the broadest volume base.
Form:
Application requirements dictate powder versus liquid selection, with dissolution kinetics and dust exposure regulations driving form-factor preferences across manufacturing environments.
- Powder:Dominates industrial and food processing for shelf stability and freight efficiency, with instant-dispersible grades gaining share in ready-mix beverage applications.
- Granules:Reduces dust exposure in pharmaceutical tableting operations, with direct-compressible grades eliminating pre-hydration steps in Mumbai and Shanghai manufacturing clusters.
- Liquid:Pre-hydrated solutions serve small-batch cosmetic formulators in France and Italy where equipment constraints limit in-house dispersion capacity.
- Gel:High-concentration semisolids target topical pharmaceutical and personal care applications requiring precise viscosity without dilution steps.
Powder retains volume dominance. Liquid and gel formats are expanding most quickly in cosmetic and specialty pharmaceutical niches.
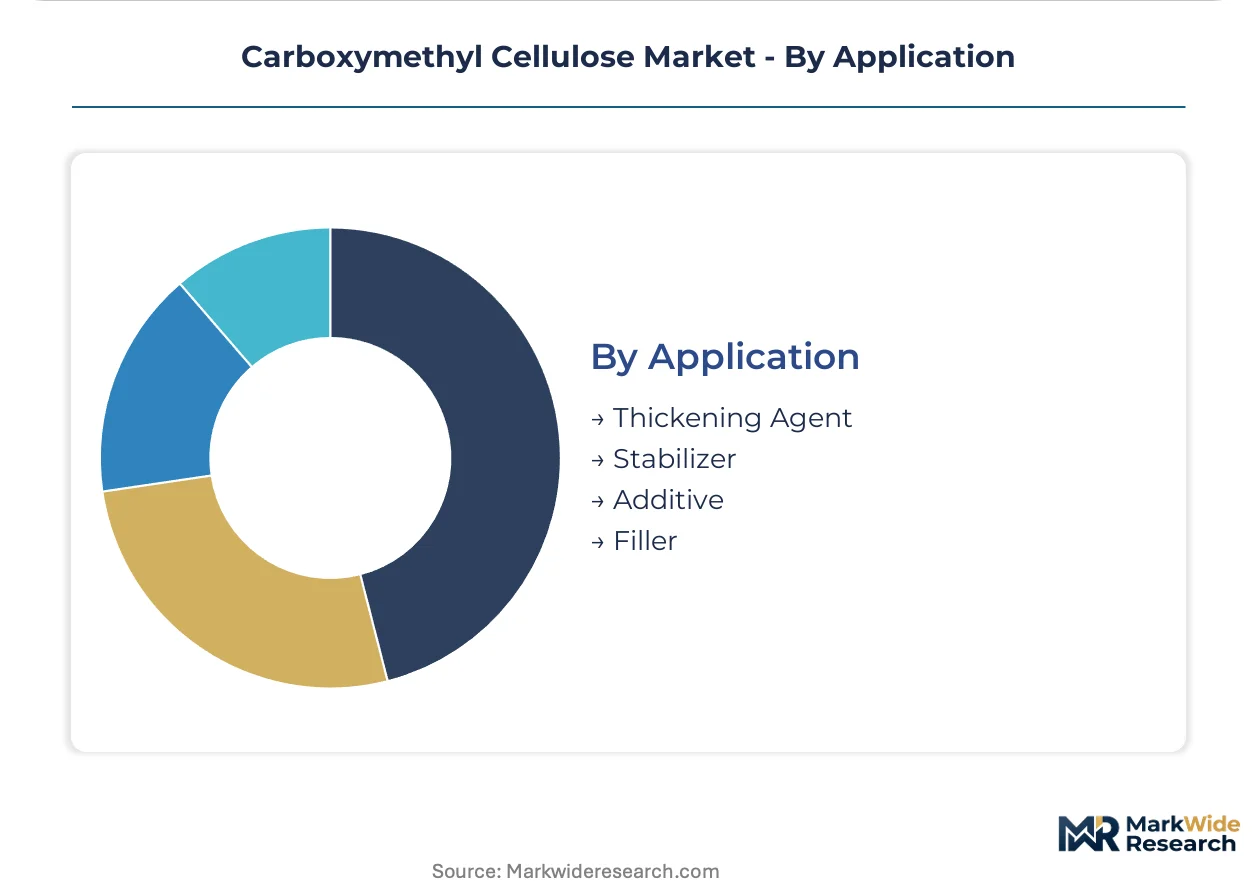
Application:
Functional performance requirements separate thickening from stabilization applications, with synergistic gum combinations in food systems demanding grade-specific compatibility testing.
- Thickening Agent:Viscosity development in aqueous systems drives specification across all grades, with pseudoplastic flow behavior critical for pourable salad dressings and suspension syrups.
- Stabilizer:Protein-polysaccharide interactions in dairy alternatives and emulsion systems require precise degree-of-substitution matching to prevent phase separation.
- Additive:Binder and disintegrant functions in oral solid dosage forms compete with microcrystalline cellulose and starch derivatives on compression performance metrics.
- Filler:Low-cost Industrial Grade serves as inert diluent in construction materials and agricultural formulations where rheology control is secondary.
Thickening Agent captures the largest volume share. Stabilizer applications are gaining share fastest in plant-based food system formulations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's NMPA excipient prequalification acceleration and India's CDSCO registration streamlining are redirecting pharmaceutical-grade CMC procurement toward domestic producers in both markets. Germany's ECHA REACH enforcement and the United States FDA 21 CFR compliance burdens are raising import barriers for non-registered Asian suppliers. These regulatory divergences are fragmenting regional supply strategies.
China
Pharmaceutical manufacturers in Shanghai and Suzhou are expanding CMC binder qualification for controlled-release tablet exports to regulated markets. NMPA's tightened GB standards for residual solvents and endotoxin limits are forcing domestic ether producers toward USP-NF alignment. The Yangtze River Delta pharmaceutical cluster is consolidating excipient supplier panels to reduce multi-site audit burdens.
India
Generic API formulators in Hyderabad and Ahmedabad are scaling pharmaceutical-grade CMC consumption for oral solid dosage contract manufacturing. CDSCO's accelerated domestic excipient prequalification timelines are displacing unregistered imports from spot procurement channels. Mumbai's formulation hub is shifting toward multi-year offtake agreements with CDSCO-registered producers.
Germany
Food-grade CMC demand from clean-label reformulation in dairy alternatives and gluten-free baking is concentrating procurement through EFSA-compliant channels. ECHA's REACH Annex XIV authorization requirements for chloroacetic acid derivatives are forcing capital allocation toward closed-loop etherification systems. The Rhine-Ruhr industrial corridor hosts integrated cellulose ether producers with captive pulp supply from Nordic dissolving-grade sources.
United States
Pharmaceutical-grade CMC consumption in controlled-release matrix tablets anchors demand from FDA-registered production facilities. FDA 21 CFR 182.1745 maximum usage levels govern food-grade applications, with clean-label substitution away from modified starches accelerating in California and Illinois processing plants. The Gulf Coast oilfield drilling fluid segment specifies Industrial Grade powder for high-salinity tolerance.
Japan
Cosmetic-grade CMC demand from sheet mask and topical formulation manufacturers in Osaka and Tokyo specifies low-ash, preservative-free grades. PMDA's pharmaceutical excipient registration requirements align with USP-NF and EP standards for export-oriented production. The Kansai region's personal care cluster sources viscosity grades optimized for film-forming without tack residue.
Carboxymethyl Cellulose Market Vendor Landscape
Channel-controlling players compete with product-specialist players across tiered certification boundaries. The vendor base clusters around three strategic archetypes: integrated pulp-to-ether producers with Nordic supply chain control, pharmaceutical-grade specialists with multi-jurisdictional registration depth, and regional standard-grade fabricators serving price-sensitive industrial offtake. Consolidation pressure is concentrating among registered pharmaceutical-grade suppliers while industrial-grade channels fragment. Dominant competitive moves include backward integration into dissolving-grade cellulose supply and multi-year offtake contracting with pharmaceutical formulators.
Among Northern European integrated producers, Nouryon Chemicals Holding B.V. exemplifies the pulp-captive archetype with supply chain control across etherification inputs. Ashland Global Holdings, Inc. occupies a position within the pharmaceutical-grade specialist tier, anchoring US-based FDA-registered production capabilities. CP Kelco represents the fermentation-derived botanical feedstock approach, with Asia-Pacific manufacturing positioning for regional pharmaceutical cluster access.
| Leading Market Players |
|---|
| Nouryon Chemicals Holding B.V. |
| Ashland Global Holdings, Inc. |
| Dow Chemical Company |
| CP Kelco |
| Daicel Corporation |
| Akzo Nobel N.V. |
| Nippon Paper Industries Co., Ltd. |
| Shandong Head Co., Ltd. |
| Lamberti S.P.A. |
| Others |
Supply Flow & Price Mechanics
Baltic Sea freight corridors linking Nordic dissolving-grade pulp terminals to etherification plants in Germany and the Netherlands transmit cost volatility directly into pharmaceutical-grade CMC premiums. Buyers in India and China absorb elevated landed costs when sourcing from REACH-registered European producers, while regional fabricators compete on standard-grade spot pricing.
Pricing Analysis
Certification level creates the primary spread between pharmaceutical and industrial tiers. Three-tier pricing structure across USP-NF/EP-registered, food-grade, and industrial-grade levels reflects compliance documentation burdens and captive pulp sourcing. Cost compression in standard-grade powder runs through chloroacetic acid feedstock volatility and Asian import competition. Industrial oilfield buyers exhibit highest price sensitivity; pharmaceutical formulators in Germany and Switzerland absorb premiums for batch-specific CoA support.
Supply Chain Analysis
Contract manufacturing concentration rests with Nouryon's integrated Nordic facilities, Ashland's FDA-registered US plants, and CP Kelco's Asia-Pacific fermentation operations. Raw material dependencies center on Swedish and Finnish dissolving-grade cellulose, petrochemical-derived etherifying agents, and botanical feedstocks for bacterial cellulose alternatives. Single-source vulnerability concentrates in Nordic pulp supply clusters. Distribution runs through specialty chemical distributors building digital excipient marketplaces for mid-sized pharmaceutical formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward pharmaceutical formulators consolidating supplier panels around multi-jurisdictional registration depth. Mumbai and Shanghai manufacturing clusters are reducing qualified vendor lists from spot-market breadth to contracted narrowness.
For Market Incumbents: Pre-empt biopolymer substitution in oilfield applications by accelerating fermentation-derived cellulose pathways independent of wood pulp constraints. Deepen backward integration into dissolving-grade cellulose supply through Nordic pulp partnerships or captive plantation development. Defensive certification investments in NMPA and CDSCO prequalification timelines secure positioning against emerging Asian producers. For New Entrants and Emerging Players: Pursue CDSCO-registered pharmaceutical-grade production for Indian generic API supply chains where domestic excipient prequalification is displacing unregistered imports. Target cosmetic-grade low-ash specifications for South Korean sheet mask and French preservative-free personal care formulations. Direct-to-formulator digital platforms compress procurement cycles for mid-sized buyers lacking in-house dispersion equipment. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors fermentation-derived cellulose specialists with enzymatic etherification capabilities that bypass pulp supply chokepoints. Five-to-ten year viability hinges on regulatory prequalification asset depth rather than commodity scale. Watch CDSCO and NMPA excipient registration acceleration as inflection signal for domestic producer valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Dissolving-Grade Pulp | Nordic pulp supply control insulates margin stability from geographic chokepoint risk. |
| Multi-Jurisdictional Registration Investment | Simultaneous FDA, REACH, and NMPA compliance opens pharmaceutical-grade premium channels. |
| Fermentation-Derived Cellulose Scale-Up | Bacterial cellulose production bypasses wood pulp constraints for pharmaceutical-grade pathways. |
| Digital Excipient Marketplace Development | Direct procurement platforms compress cycles for mid-sized Asia-Pacific formulators. |
| Closed-Loop Etherification System Deployment | Vapor recovery systems satisfy ECHA REACH Annex XIV chloroacetic acid authorization requirements. |
Methodological Framework
Cross-validation between primary interviews with plant managers at cellulose ether facilities and secondary validation through customs trade data, SEC 10-K filings, and Cefic industry reports anchors the qualitative findings. Technical R&D directors at pharmaceutical excipient manufacturers, procurement leads at downstream food processing OEMs, and distribution channel partners in specialty chemicals provided operational perspective. Bottom-up capacity modeling and top-down demand triangulation across grade tiers, end-use industries, and regional production hubs ensured segmentation integrity.
Calibration against historical price series and capacity utilization rates across the analysis window informs trajectory assumptions. Segmentation dimensions modeled include grade purity tier, end-use industry channel, form factor specification, and regional regulatory cluster. CAGRs derive from elasticity-adjusted demand projections and supply-side capacity buildout timelines. Chloroacetic acid feedstock cost curves and excipient prequalification velocity serve as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in crude-linked petrochemical input costs or pulp commodity indices would shift the trajectory. Forecasts reflect documented assumptions about regulatory timeline acceleration and substitution elasticity in oilfield applications. Quarterly review of CDSCO and NMPA registration approval velocities, REACH authorization enforcement actions, and Baltic Sea freight rate indices is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Water-Borne Coating Additives Market
Additives
Global Polyurethane Additives Market
Additives
Calcium Stearate Market
Additives
North America Citric Acid Market
Additives
Fluoropolymer Additives Market
Additives
Russia Sodium Reduction Ingredient Market
Additives
Global Cement and Concrete Additives Market
Additives
Global Corrosion Inhibitor Market
Additives
Antiknock Agents Market
Additives
Plasticizer Concrete Admixtures Market
Additives
Global Silica-Based Matting Agents Market
Additives
Isopropyl Acetate Market
Additives
Phthalic Anhydride Derivatives Market
Additives
Tartaric Acid Market
Additives
Global Scale Inhibitors Market
Additives
Material Shrinkage-reducing Agents Market