
 Middle East Polymer Market | 2026-2036
Middle East Polymer Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East Polymer Market Foresight
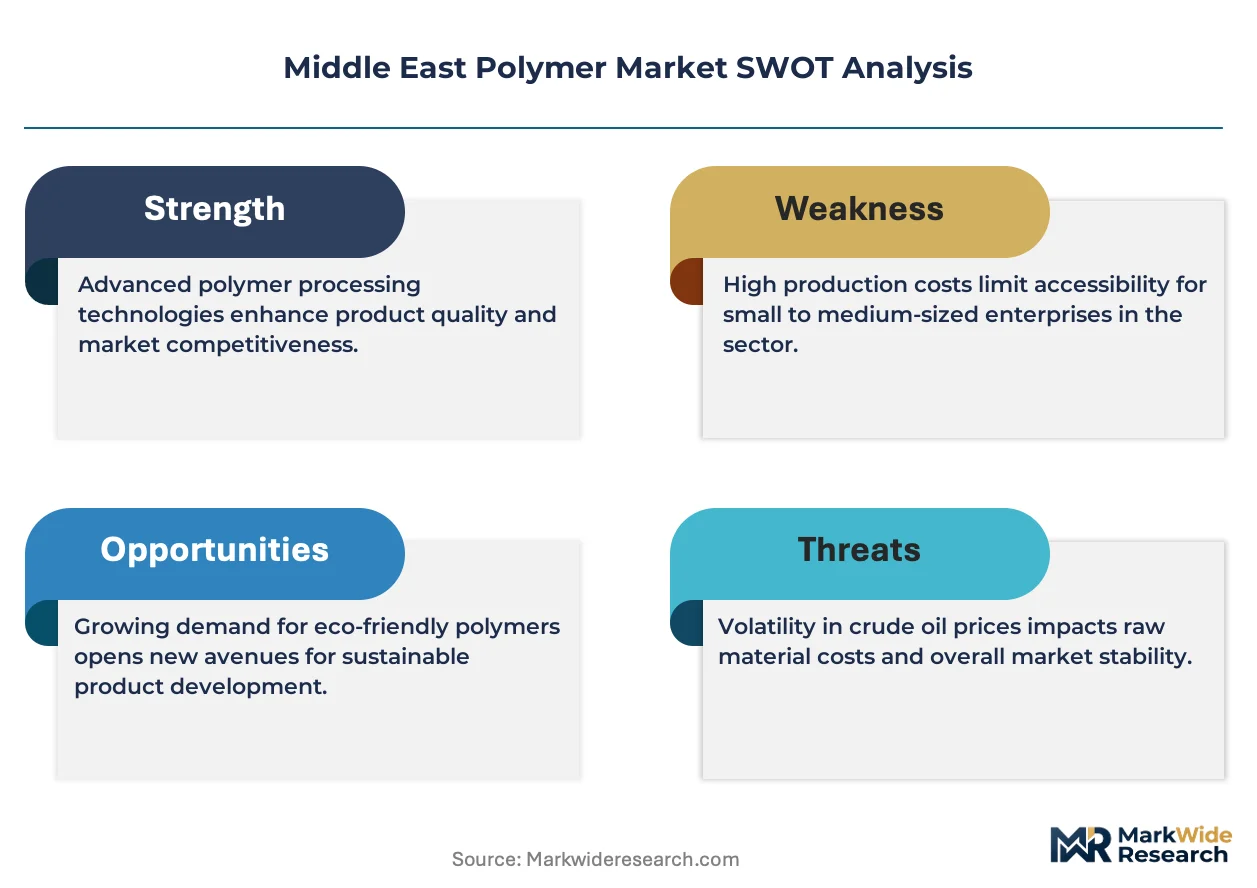
Recycled polyethylene terephthalate is recalibrating virgin resin economics across Gulf conversion industries. SABIC leverages its Yanbu and Jubail integrated complexes to sustain cost leadership in high-density polyethylene exports. Borouge differentiates through its Abu Dhabi Ruwais facility, which controls bimodal polyethylene technology for infrastructure pipe applications. Farabi Petrochemicals specializes in linear low-density films serving Saudi domestic flexible packaging converters.
Polymers are macromolecular compounds formed through polymerization of monomer units, with molecular weights typically exceeding ten thousand daltons, processed via extrusion, injection molding, or blow molding into shaped articles. Polyethylene dominates Middle East output volumes due to abundant ethane feedstock from associated gas fields, while polypropylene captures expanding margins in automotive and appliance compounds. Specialty grades represent the fastest-growing margin pool as regional producers seek to reduce commodity dependence. Packaging applications anchor demand through food-contact films and rigid containers serving intra-GCC trade routes.
Saudi Standards, Metrology and Quality Organization (SASO) mandates halogen-content limits in electrical conduit applications, while UAE's Emirates Authority for Standardization and Metrology (ESMA) enforces food-contact migration standards for polyethylene packaging. Gulf petrochemical regulators are aligning product certification with EU REACH pre-registration requirements to preserve European export access. Stakeholders must monitor feedstock cost spreads between naphtha and ethane cracking economics to time capacity investment decisions.
Market Dynamics
Construction-grade polypropylene demand accelerates across Gulf megaprojects, reshaping regional capacity allocation as producers pivot from commodity exports to domestic infrastructure supply.
Growth Catalysts
- Halogen-content limits:SASO mandates for electrical conduit applications are pulling specialty compound volumes toward Saudi domestic wire and cable manufacturers seeking compliant formulations.
- Food-contact migration standards:ESMA enforcement across UAE packaging converters is upgrading polyethylene film specifications for intra-GCC trade routes.
- Automotive lightweighting:Specialty grade polymer specifications from Qatar and UAE vehicle assembly plants are concentrating regional compounder investment in high-flow polypropylene.
Market Restraints
- Ethane feedstock concentration:Associated gas field dependence tiescracker economics to Saudi Aramco and ADNOC production schedules, limiting supply flexibility.
- REACH pre-registration alignment:Gulf petrochemical regulators' synchronization with EU chemical safety protocols imposes documentation burdens on small-batch specialty exporters.
- Recycled PET displacement:Post-consumer flake availability from UAE and Saudi collection infrastructure is compressing virgin polyethylene terephthalate margins in bottle applications.
Strategic Opportunities
- Qatar specialty automotive grades:Underpenetrated local compounding capacity for electric vehicle battery housings and interior panels offers first-mover positioning.
- Bimodal polyethylene infrastructure:Abu Dhabi Ruwais technology licensing for large-diameter pipe resin creates export pathways to East African water infrastructure projects.
- EU Green Deal chemical recycling:Gulf producers with pyrolysis-ready feedstock streams can access premium offtake contracts under emerging circular economy mandates.
Industry Challenges
- Process control engineering talent:Bimodal reactor operation and metallocene catalyst management require skills scarce in regional technical institutes.
- Dual certification timelines:Simultaneous SASO and ESMA approval processes for cross-border packaging suppliers extend product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East Polymer Market |
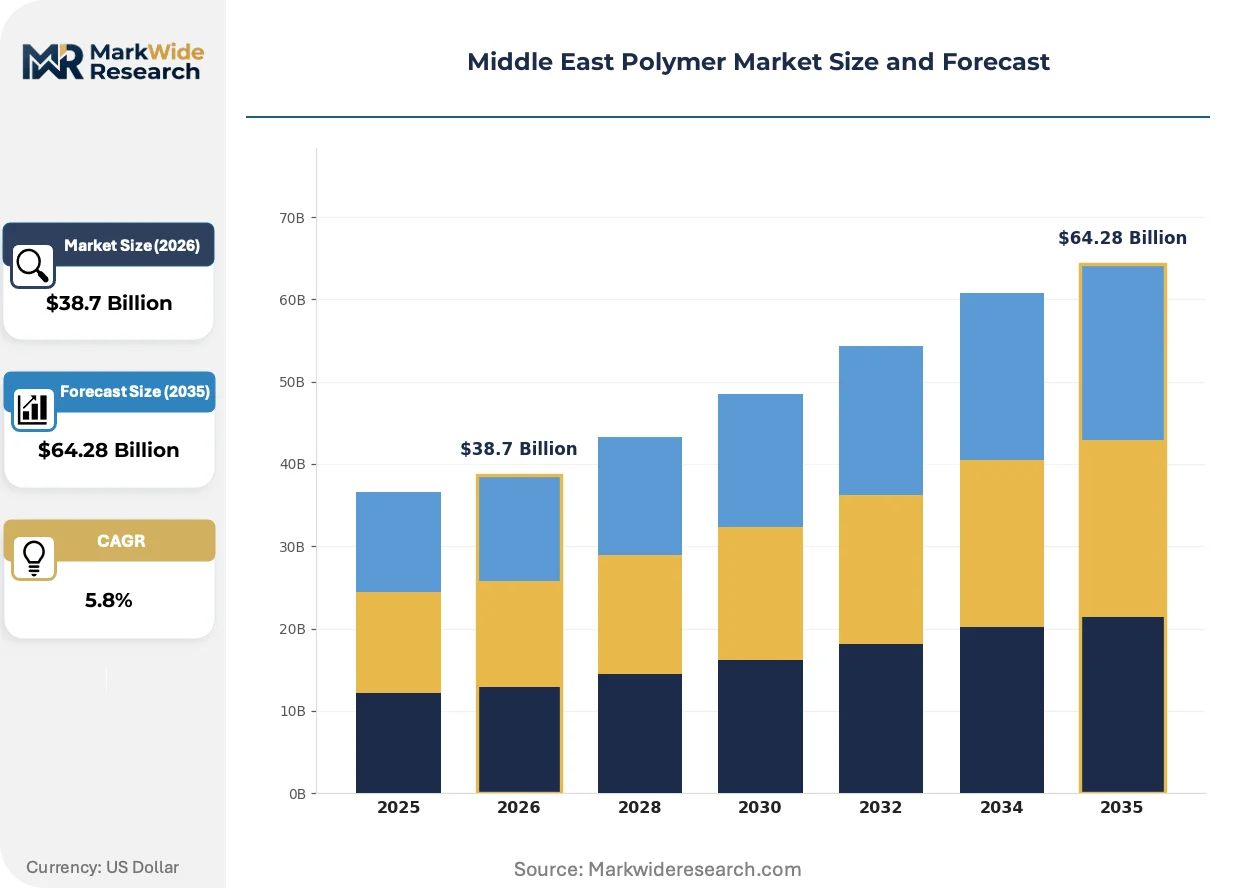
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $64.28 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polypropylene, Polyvinyl Chloride, Polystyrene Grade: High Density, Low Density, Linear Low Density, Specialty Application: Packaging, Construction, Automotive, Consumer Goods End User: Manufacturers, Retailers, Distributors, Exporters |
| Companies Covered | Qatar Petrochemical Company (QAPCO), Saudi Kayan Petrochemical Company, SABIC, Farabi Petrochemicals Company, Yansab, Borouge, Petro Rabigh, BASF Middle East, Sipchem, Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East Polymer Market Shifts & Advancements
Regional producers are engineering specialty-grade escape routes from commodity polyethylene margins, deploying advanced catalyst systems and circular feedstock integration to capture premium pricing in automotive and infrastructure applications.
Metallocene linear low-density polyethylene is consolidating conventional Ziegler-Natta film resin positions in Saudi flexible packaging markets. Domestic converters serving halal food export chains are adopting the technology for enhanced seal integrity and downgauging potential. This transition is consolidating commodity LLDPE producers into undifferentiated bulk supply roles while rewarding catalyst technology licensors with per-ton royalty streams.
EU REACH pre-registration requirements are compressing Gulf petrochemical export windows into European polymer markets. Regional certification bodies are establishing testing protocols aligned with ECHA substance evaluation timelines. Specialty compounders with existing EU representative offices are capturing disproportionate share of medical and electrical grade offtake as smaller commodity exporters defer registration investments.
Long-term offtake contracting is displacing spot-trading dominance in polyethylene resin procurement. Major Saudi construction consortia executing megaproject pipelines are securing five-year polypropylene supply agreements directly with SABIC and advanced regional compounders. This pattern concentrates volume commitments among integrated producers while marginalizing independent traders previously serving smaller Gulf converter accounts.
Middle East Polymer Market Segmentation
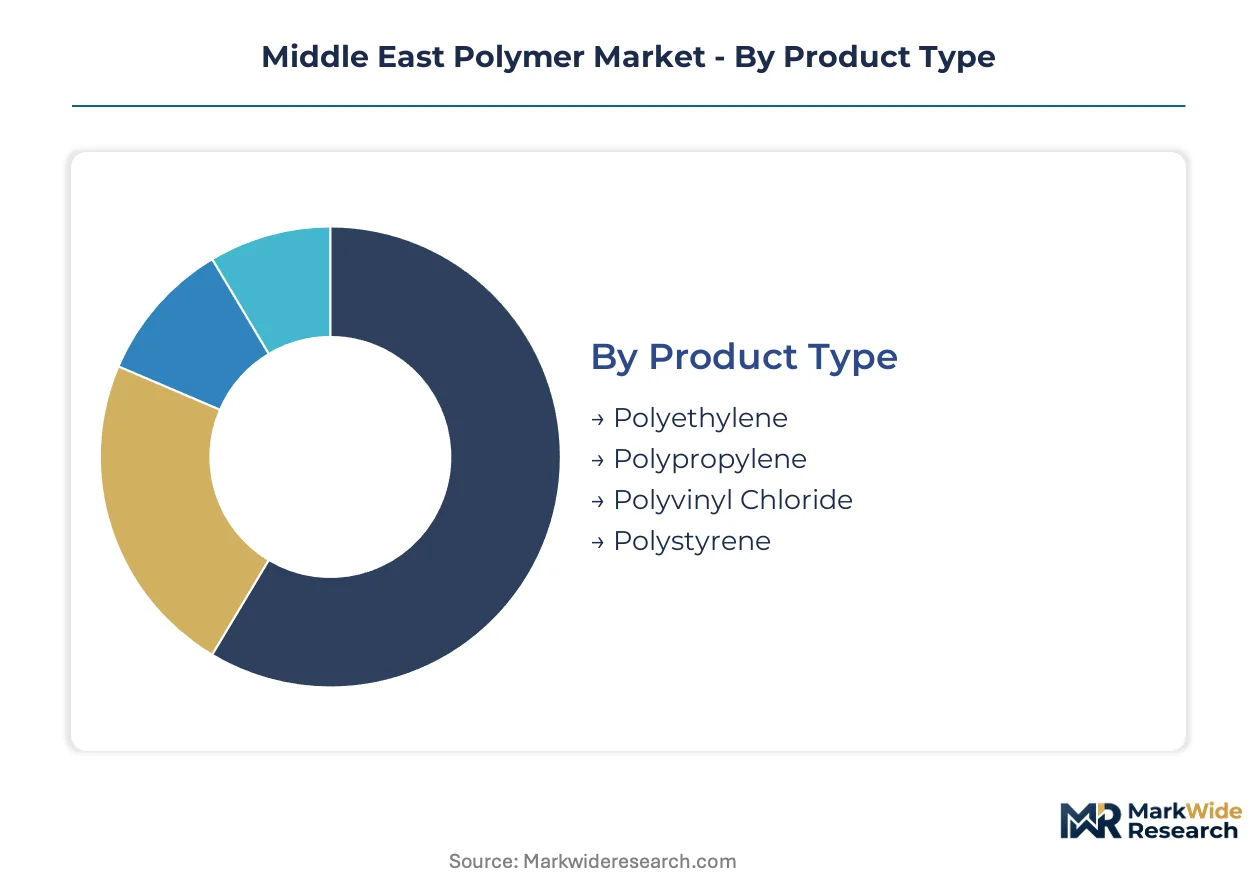
Segmentation reveals how certification burdens and feedstock economics concentrate margin capture across polymer value chains. Distinct approval pathways for packaging, construction, and automotive grades create tiered competitive barriers that reshape producer positioning.
Product Type:
SASO halogen-content mandates apply differentially across polymer families, with electrical conduit specifications favoring certain chemistries over others in Saudi project procurement.
- Polyethylene:Dominates regional output through ethane cracking economics tied to Saudi Aramco and ADNOC associated gas production. Construction-grade high-density resin concentrates demand in UAE and Saudi megaproject pipelines, while film-grade linear low-density serves GCC food-contact packaging converters upgrading to ESMA migration standards.
- Polypropylene:Specialty automotive compounds for Qatar and UAE vehicle assembly require SASO material compliance certificates distinct from commodity grades. High-flow formulations for battery housings and interior panels command premium positioning as regional automakers localize supply chains.
- Polyvinyl Chloride:Electrical conduit applications face SASO halogen-content ceilings that restrict formulation flexibility for Saudi wire and cable manufacturers.
- Polystyrene:Consumer goods and insulation board demand tracks UAE construction activity and Saudi retail packaging conversion.
Leading the category by volume: Polyethylene. Growing fastest: Polypropylene.
Grade:
Cost tier stratification separates commodity producers from specialty compounders capturing automotive and infrastructure premiums.
- High Density:Bimodal reactor technology at Abu Dhabi Ruwais enables large-diameter pipe resin for East African water infrastructure exports. SABIC Yanbu and Jubail complexes sustain cost leadership through integrated ethane feedstock.
- Specialty:Metallocene-catalyzed grades consolidate conventional film positions as Saudi halal food exporters adopt enhanced seal integrity specifications. Catalyst technology licensors extract per-ton royalties while commodity producers retreat to bulk supply roles.
- Low Density:Conventional film and coating applications serve Gulf flexible packaging converters with undifferentiated margin profiles.
- Linear Low Density:Farabi Petrochemicals concentrates domestic Saudi supply while regional converters downgauge to meet ESMA food-contact standards.
Dominating volume: High Density. Steepest expansion trajectory: Specialty.
Application:
End-use concentration determines which producers absorb REACH pre-registration costs for European market access versus retreating to GCC domestic supply.
- Packaging:ESMA-enforced migration standards for polyethylene film reshape intra-GCC trade flows. Recycled PET flake availability from UAE and Saudi collection infrastructure compresses virgin resin margins in bottle applications.
- Construction:Five-year polypropylene offtake agreements between Saudi megaproject consortia and integrated producers displace spot-trading dominance. SABIC and advanced regional compounders capture volume commitments while independent traders lose smaller converter accounts.
- Automotive:Qatar and UAE assembly plants concentrate specialty polymer demand for lightweighting programs.
- Consumer Goods:Appliance compounds track Saudi and UAE retail market expansion with moderate specification intensity.
Capturing largest volume share: Packaging. Climbing the fastest: Construction.
End User:
Customer type determines procurement power and certification burden distribution across value chain tiers.
- Manufacturers:Integrated polypropylene compounders serving Saudi automotive and construction sectors manage dual SASO-ESMA approval timelines for cross-border supply. Direct mill relationships with SABIC and Borouge secure feedstock cost transparency.
- Exporters:REACH pre-registration alignment requirements compress European market windows for smaller commodity producers. Specialty compounders with EU representative offices capture disproportionate medical and electrical grade offtake.
- Retailers:Private-label packaging converters in UAE and Saudi Arabia upgrade specifications to meet halal food chain requirements.
- Distributors:Independent traders face margin compression as long-term contracting concentrates volume among integrated producers.
Highest procurement volume: Manufacturers. Gaining share fastest: Exporters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Construction-grade polypropylene demand concentrates in Saudi Arabia and the UAE, where megaproject pipelines reshape regional capacity allocation. Qatar and Kuwait emerge as specialty automotive compound destinations as vehicle assembly localizes.
Saudi Arabia
SABIC's Yanbu and Jubail integrated complexes anchor high-density polyethylene export volumes. SASO halogen-content mandates for electrical conduit applications pull specialty compound volumes toward domestic wire and cable manufacturers. The Eastern Province concentrates bimodal reactor operations serving infrastructure pipe specifications.
United Arab Emirates
Borouge's Ruwais facility controls bimodal polyethylene technology for large-diameter pipe resin targeting East African water projects. ESMA food-contact migration standards reshape intra-GCC packaging trade flows. Dubai and Abu Dhabi clusters upgrade polyethylene film specifications for halal food export chains.
Qatar
Specialty grade polymers for electric vehicle battery housings and interior panels concentrate demand from Qatar-based vehicle assembly plants. The country's national petrochemical regulator aligns product certification with EU REACH pre-registration requirements. Ras Laffan industrial zone hosts underpenetrated local compounding capacity offering first-mover positioning.
Kuwait
Domestic construction activity drives polypropylene consumption for infrastructure applications. The country's central petrochemical authority enforces quality standards for imported polymer grades. Shuaiba industrial area houses conversion facilities serving regional flexible packaging demand.
Oman
Strategic location advantages position Sohar port as a polyethylene transshipment hub for East African markets. The Sultanate's national standards body develops technical regulations for construction polymer applications. Duqm Special Economic Zone attracts downstream conversion investments targeting specialty film exports.
Middle East Polymer Market Competitive Landscape
Capacity expansion dominates the current landscape as integrated producers scale ethane-based polyethylene output. The market structure concentrates around state-affiliated petrochemical majors with captive feedstock access. Three archetypes define competitive positioning: integrated upstream-downstream operators, technology-licensed specialty compounders, and regional conversion specialists. Geographic expansion and strategic partnerships represent the dominant competitive vectors as players secure long-term offtake agreements with construction consortia.
Within the integrated operator tier, SABIC and Borouge exemplify scale-driven positioning through ethane cracking economics and bimodal reactor technology. Farabi Petrochemicals occupies a specialist position in linear low-density film supply for Saudi domestic converters. These three entities anchor the competitive structure, with SABIC representing feedstock-integrated volume leadership, Borouge exemplifying technology-differentiated infrastructure positioning, and Farabi Petrochemicals illustrating domestic market specialization.
| Leading Market Players |
|---|
| Qatar Petrochemical Company (QAPCO) |
| Saudi Kayan Petrochemical Company |
| SABIC |
| Farabi Petrochemicals Company |
| Yansab |
| Borouge |
| Petro Rabigh |
| BASF Middle East |
| Sipchem |
| Others |
Supply & Pricing Matrix
Captive ethane supply from Saudi Aramco and ADNOC associated gas fields anchors both feedstock security and pricing power for integrated polyethylene producers. This backward integration into upstream hydrocarbons insulates SABIC and Borouge from naphtha-cracking volatility while compressing margins for non-integrated compounders forced to procure at spot-linked terms.
Pricing Analysis
Volume leadership in commodity polyethylene trades against margin capture in specialty grades. Three-tier pricing structure across metallocene-catalyzed premium, bimodal pipe-grade standard, and commodity film economy levels reflects certification intensity and catalyst royalty burdens. Pricing pressure stems from recycled PET flake availability compressing virgin resin economics in bottle applications. Spot-trading converters serving smaller GCC accounts exhibit highest price sensitivity, while automotive compounders with SASO material compliance certificates absorb premiums for qualified supply.
Supply Chain Analysis
Qualification gating through dual SASO-ESMA approval timelines segments suppliers into certified and non-certified tiers. Production concentrates in Saudi Arabia, UAE, and Qatar, with ethane feedstock drawing from associated gas fields tied to national oil company production schedules. Raw material dependencies center on ethane, metallocene catalysts licensed from technology providers, and specialty additive packages for automotive compounds. Single-source vulnerability runs through catalyst technology licensors controlling bimodal reactor operations. Distribution runs through direct mill relationships with integrated producers for megaproject offtake, supplemented by regional traders serving spot-demand converters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH pre-registration alignment functions as a cost-of-compliance moat, concentrating European export access among compounders with existing EU representative offices while excluding smaller commodity producers from premium medical and electrical grade offtake.
For Market Incumbents: Deepen metallocene catalyst partnerships to secure royalty-rate advantages as halal food exporters adopt enhanced seal integrity specifications. Expand bimodal polyethylene capacity at Ruwais-class facilities to capture East African water infrastructure demand. Defensive positioning against recycled PET displacement requires pyrolysis-ready feedstock integration for EU Green Deal circular economy contracts. For New Entrants and Emerging Players: Begin with Qatar specialty automotive compounding for electric vehicle battery housings, where underpenetrated local capacity offers first-mover positioning absent entrenched supplier relationships. Target infrastructure pipe resin supply to East African markets through Abu Dhabi technology licensing partnerships. Go-to-market leverage rests on SASO material compliance certification as a qualification wedge against unqualified regional traders. For Investors and Strategic Acquirers: Exit pathways concentrate in technology-licensed specialty compounders with captive feedstock arrangements and established EU representative offices. Long-term viability favors producers with backward integration into ethane supply and metallocene catalyst access. Watch for pyrolysis capacity announcements as inflection signal for circular economy premium capture.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ethane Supply | Captive feedstock from Saudi Aramco and ADNOC insulates SABIC and Borouge from naphtha price volatility. |
| Metallocene Catalyst Technology Licensing | Per-ton royalty streams reward technology licensors as halal food exporters adopt enhanced seal integrity films. |
| Long-term Supply Agreement with Construction Consortia | Five-year polypropylene offtake contracts between Saudi megaproject developers and integrated producers displace spot-trading dominance. |
| Dual SASO-ESMA Certification Investment | Cross-border packaging suppliers reduce product launch cycle extension through parallel approval process management. |
| Pyrolysis-ready Feedstock Integration | Gulf producers access premium offtake contracts under EU Green Deal chemical recycling mandates. |
Research Methodology
Independent corroboration across plant managers at SABIC and Borouge complexes, procurement leads at Saudi automotive compounders, and distribution channel partners serving GCC flexible packaging converters underwrites the qualitative findings. Secondary validation drew from customs and trade data, Gulf petrochemical association reports, and SEC filings of listed regional producers. Bottom-up volume estimates from individual facility capacities triangulate against top-down demand assessments from end-use sector consumption patterns.
Comparable-period anchoring to historical ethane-naphtha spread dynamics and construction pipeline announcement timelines structured the projection horizon. The analytical framework modeled segmentation across grade tier, end-use industry, and regional production hub dimensions. CAGRs were derived from elasticity-adjusted demand curves incorporating feedstock cost scenarios and regulatory compliance burden trajectories. Forecast inputs included megaproject procurement schedule reliability and EU REACH pre-registration timeline adherence rates.
Feedstock cost volatility, regulatory approval delays, and recycled PET substitution acceleration are the dominant revision risks to modeled outputs. Forecasts reflect assumptions regarding ethane supply continuity from Saudi Aramco and ADNOC production schedules and construction project execution timelines. A model refresh is warranted upon material change in EU circular economy mandate implementation pace or GCC halogen-content standard enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Beverage Processing Polymers Market
Polymers & Resins
Linear Low Density Polyethylene Lldpe Market
Polymers & Resins
PA66 Market
Polymers & Resins
Asia-Pacific Geopolymer Market
Polymers & Resins
Global Polymer Dispersion Market
Polymers & Resins
North America Geopolymer Market
Polymers & Resins
1-Hexene Based Polyethylene Market
Polymers & Resins
Polychlorotrifluoroethylene (PCTFE) Market
Polymers & Resins
Middle East LLDPE Market
Polymers & Resins
Saudi Arabia Engineering Plastics Market
Polymers & Resins
Bio-Based Polypropylene in Medical Devices Market
Polymers & Resins
Styrene Acrylonitrile (SAN) Resins Market
Polymers & Resins
Polymer Modified Bitumen (PMB) Market
Polymers & Resins
South America Polyvinyl Chloride (PVC) Market
Polymers & Resins
Polyvinylpyrrolidone (PVP) Market
Polymers & Resins
Global Structural Foam Market