
 Bio-Based Polymer Market | 2026-2036
Bio-Based Polymer Market Size, Share, and Industry Trends Forecast 2026-2036
Bio-Based Polymer Market Intelligence
Petroleum-derived polyethylene is realigning cost structures as bio-based polyethylene from sugarcane ethanol achieves parity in select packaging grades. Braskem leverages its Brazilian sugarcane supply chain to anchor global production of bio-based polyethylene. NatureWorks specializes in polylactic acid fermentation technology and dominates North American capacity for food-service applications.
Bio-based polymers comprise macromolecules synthesized wholly or partially from renewable biomass sources such as corn starch, sugarcane, or cellulose, with melt temperatures ranging from 130°C to 180°C depending on crystallinity and monomer composition. These materials serve primarily as drop-in or performance-alternatives to fossil-based plastics in applications requiring biodegradability, reduced carbon intensity, or compliance with renewable content mandates. Polylactic acid occupies the largest volume position due to mature fermentation infrastructure and broad thermoforming compatibility, while polyhydroxyalkanoates represent the fastest-expanding category as marine biodegradability standards tighten. Starch blends retain cost leadership in single-use disposables though margin pools concentrate in pharmaceutical-grade polylactic acid for medical devices.
The European Chemicals Agency enforces REACH registration for novel bio-based monomers, while the EU Green Deal's packaging waste directive mandates minimum recycled and renewable content thresholds. The US Department of Agriculture administers the BioPreferred program which confers federal procurement preference on certified bio-based products. Stakeholders must monitor how fermentation yield improvements interact with agricultural commodity volatility to determine capacity expansion timing.
Market Dynamics
Fermentation-based production routes are compressing cost structures for polylactic acid and polyhydroxyalkanoates as agricultural feedstock integration matures in Brazil and Germany. Brand owners now face binding extended producer responsibility frameworks that mandate renewable content minimums in packaging.
Growth Catalysts
- EU Green Deal packaging mandates:Minimum recycled and renewable content thresholds are forcing converters to certify biodegradability for shelf access in France and the Netherlands.
- Food-contact certification pull:Biodegradability certifications determine procurement decisions for single-use food service items across European retail chains.
- Sugarcane ethanol parity:Agricultural feedstock economics in Brazil now match petroleum-derived polyethylene costs in select packaging grades.
Market Restraints
- Corn starch price volatility:Agricultural commodity swings directly compress margins for fermentation-based polylactic acid producers.
- REACH registration friction:The European Chemicals Agency's novel monomer approval timelines delay commercialization of next-generation bio-based polyesters.
- Petrochemical substitution threat:Mechanical recycling infrastructure improvements in Germany reduce the cost gap with fossil-based alternatives.
Strategic Opportunities
- Marine biodegradability standards:Tightening ocean-plastic regulations in the European Union create first-mover advantage for polyhydroxyalkanoates in fishing gear and maritime applications.
- USDA BioPreferred procurement preference:Federal purchasing mandates in the United States open institutional channels for certified bio-based products.
- Pharmaceutical-grade polylactic acid:Medical device applications command premium pricing as sterilization compatibility requirements intensify.
Industry Challenges
- Bioprocess engineering talent scarcity:Industrial microbiology and metabolic pathway optimization expertise concentrates in academic clusters rather than manufacturing operations.
- Multi-certification complexity:Simultaneous compliance with food-contact safety, compostability, and carbon footprint standards extends product launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bio-Based Polymer Market |
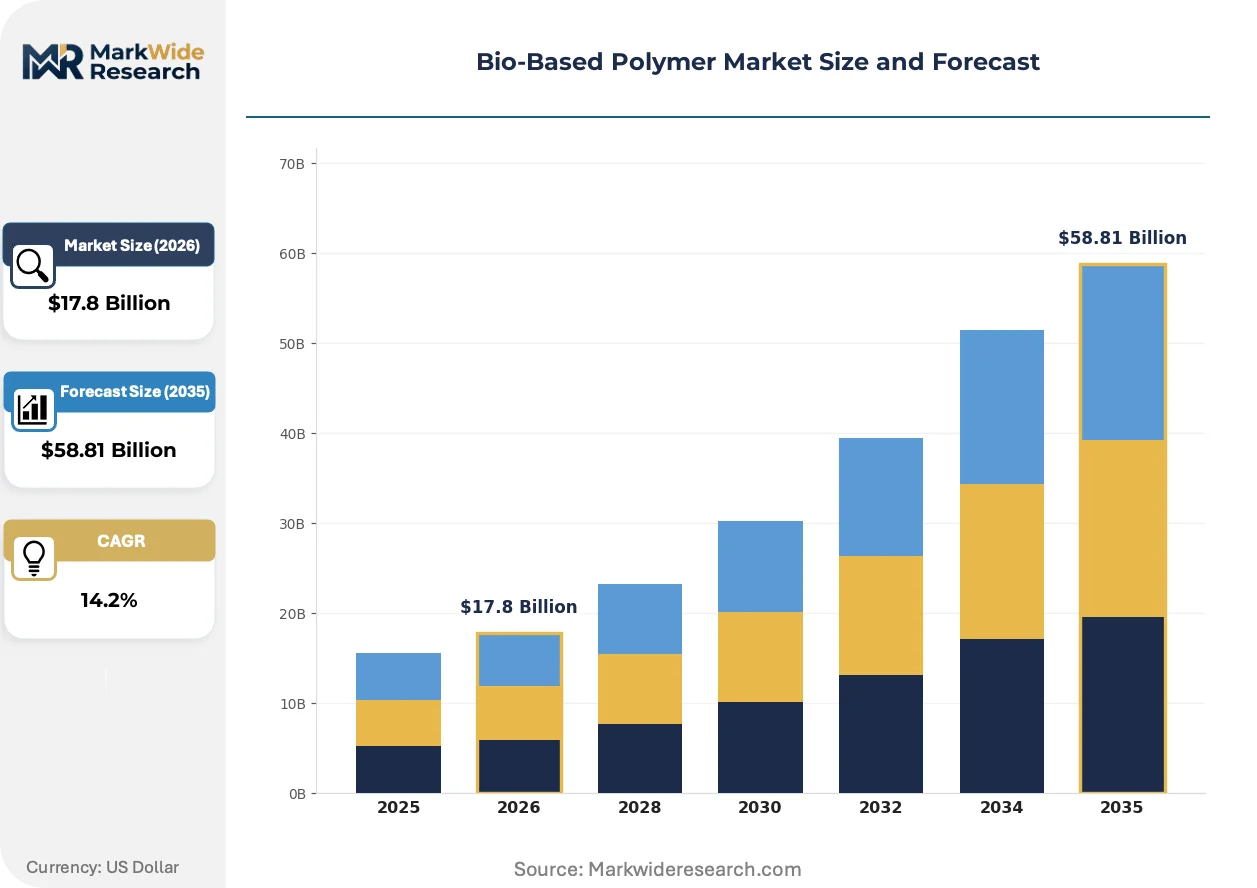
| Market Size in 2026 | $17.8 Billion |
| Market Size in 2035 | $58.81 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polylactic Acid, Polyhydroxyalkanoates, Starch Blends, Bio-Based Polyethylene Application: Packaging, Textiles, Automotive, Consumer Goods End User: Aerospace, Food Industry, Healthcare, Agriculture Distribution Channel: Online Sales, Distributors, Direct Sales, Retail |
| Companies Covered | Mitsubishi Chemical Corporation, Braskem, NatureWorks, Teijin Limited, Arkema, BASF, Novamont, Kuraray, Corbion, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bio-Based Polymer Market Strategic Shifts & Innovations
Second-generation fermentation technologies are unlocking lignocellulosic feedstocks that bypass food-crop competition. These advances are compressing the agricultural land intensity of bio-based polymer production.
Enzymatic depolymerization combined with precision fermentation is rewriting the economics of polylactic acid recycling. Packaging converters in the Netherlands are piloting closed-loop systems that return post-industrial waste to virgin-grade resin. This technology is collapsing the traditional separation between mechanical recycling and chemical synthesis.
The EU Green Deal's packaging waste directive is mandating minimum recycled and renewable content thresholds that reshape converter procurement. Brand owners must now document renewable feedstock provenance through mass-balance certification. Food-contact applications in France face the strictest compliance timelines.
Buyer concentration among European retail chains is consolidating specification power over biodegradability standards. Smaller converters are losing access to shelf space without third-party compostability certification. This pattern is most pronounced in the Netherlands where supermarket chains coordinate packaging requirements.
Bio-Based Polymer Market Segmentation
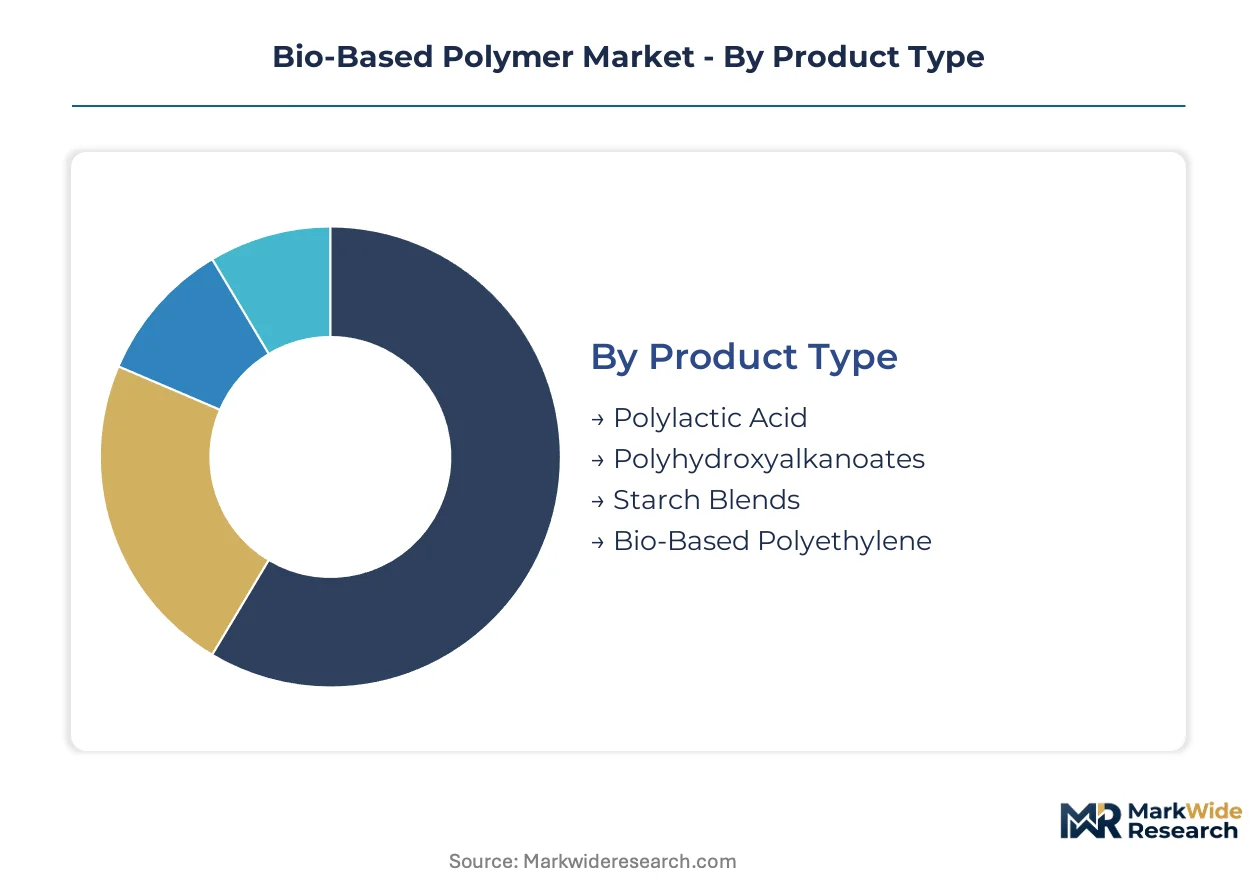
Segmentation in the bio-based polymer market reveals how feedstock economics, certification requirements, and end-use performance specifications fragment procurement patterns across converters. Understanding these divisions exposes where margin pools concentrate and which technology platforms face substitution pressure from adjacent materials.
Product Type:
Volume concentration sits with fermentation-established platforms, while premium positioning belongs to performance polymers commanding marine biodegradability or medical-grade certifications.
- Polylactic Acid:Derived from corn starch or sugarcane fermentation, this polyester exhibits melt temperatures between 130°C and 150°C with crystallinity tunable through copolymerization. Food-contact thermoforming in France and the Netherlands concentrates procurement, where EU Green Deal packaging mandates require documented renewable content through mass-balance certification.
- Polyhydroxyalkanoates:Bacterial fermentation produces these intracellular polyesters with broader biodegradation profiles including marine environments. Fishing gear and maritime applications in the European Union drive specification pull as ocean-plastic regulations tighten compliance timelines for synthetic net disposal.
- Starch Blends:Thermoplastic starch compounded with synthetic polymers delivers cost leadership in single-use disposables where compostability certification suffices.
- Bio-Based Polyethylene:Sugar ethanol dehydration produces drop-in polyethylene identical to fossil-derived grades, with Braskem's Brazilian supply chain anchoring global availability for flexible packaging.
Today's leader: Polylactic Acid. Tomorrow's challenger: Polyhydroxyalkanoates.
Application:
Application segmentation tracks how regulatory pressure intensity varies by product lifecycle exposure to waste management infrastructure.
- Packaging:Flexible films, rigid trays, and beverage bottles dominate volume, with extended producer responsibility rules in Germany and France mandating minimum renewable content thresholds that reshape converter procurement specifications.
- Textiles:Fiber applications for apparel and nonwovens face performance gaps in dye affinity and thermal stability that limit substitution rates for fossil-based polyester.
- Automotive:Interior trim and under-hood components specify bio-based polyamides and polyesters where heat resistance requirements exceed polylactic acid capabilities.
- Consumer Goods:Durable electronics housings and appliance components represent emerging specification territory where carbon footprint disclosure drives brand positioning.
Packaging absorbs the regulatory pressure. Textiles await technical breakthroughs in fiber processing.
End User:
End user segmentation distinguishes between compliance-driven procurement and performance-critical material selection where sterilization or chemical resistance requirements dominate.
- Food Industry:Single-use serviceware and fresh produce packaging in European retail chains concentrates demand, with Netherlands supermarket consortiums coordinating biodegradability certification requirements that determine shelf access.
- Healthcare:Sutures, drug delivery systems, and orthopedic implants command premium pricing for pharmaceutical-grade polylactic acid with validated sterilization compatibility and degradation kinetics.
- Aerospace:Interior paneling and cabin components explore bio-based composites where flammability standards and smoke toxicity regulations constrain material substitution.
- Agriculture:Mulch films and controlled-release matrices leverage soil biodegradability to eliminate retrieval costs, with Italian and Spanish horticulture operations piloting polyhydroxyalkanoate formulations.
Food Industry drives certification standardization. Healthcare captures margin premiums through technical barriers.
Distribution Channel:
Channel segmentation reflects converter scale and specification complexity, with bulk commodity grades separating from engineered resins requiring technical service support.
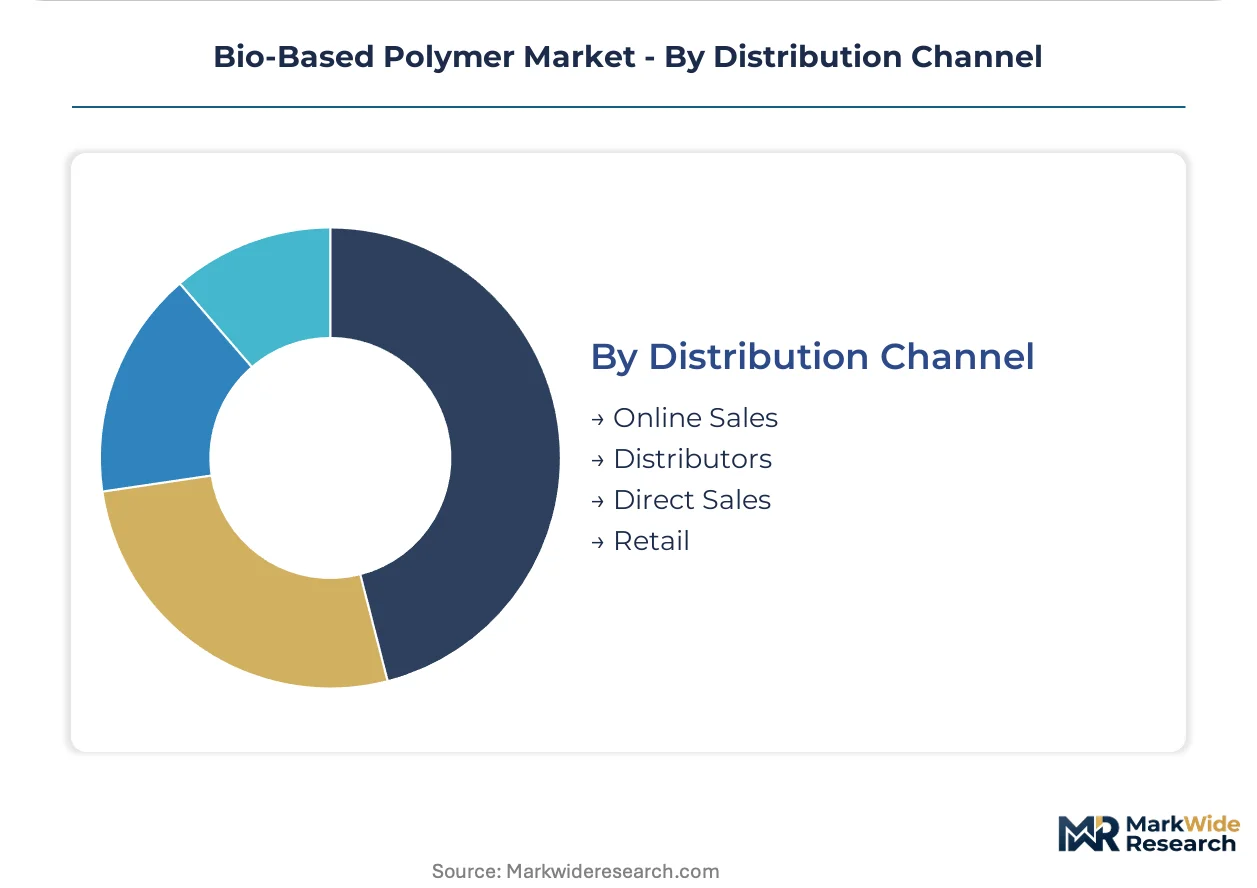
- Distributors:Regional polymer distributors stock standard polylactic acid and bio-based polyethylene grades for mid-size packaging converters lacking direct mill relationships.
- Direct Sales:NatureWorks and Braskem maintain dedicated account teams for multinational brand owners requiring customized formulation development and carbon footprint documentation.
- Online Sales:E-procurement platforms serve research institutions and startup manufacturers sampling small volumes for product development.
- Retail:Limited availability through industrial supply retailers addresses emergency replenishment for maintenance repair operations.
Distributors intermediate commodity flows. Direct relationships capture specification influence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's sugarcane belt anchors fermentation capacity for bio-based polyethylene, with Braskem's Triunfo complex processing agricultural feedstock into drop-in resins. European converters source certified renewable grades from this supply hub while domestic demand concentrates in flexible packaging applications.
Germany
Automotive and industrial packaging converters in Baden-Württemberg and North Rhine-Westphalia specify bio-based polyamides for under-hood components. The country's national chemicals regulator enforces REACH registration timelines for novel bio-based monomers that delay commercialization of next-generation polyesters. Industrial biotechnology clusters around Leipzig and Jena concentrate metabolic pathway optimization expertise for fermentation yield improvements.
United States
Food-service distributors and federal procurement channels pull certified bio-based products through the USDA BioPreferred program's purchasing mandates. The FDA oversees food-contact safety validation for polylactic acid thermoforming applications in retail packaging. NatureWorks maintains production presence in Blair, Nebraska, supplying North American converters with fermentation-derived resin grades.
France
Supermarket chains in the Île-de-France and Auvergne-Rhône-Alpes regions coordinate biodegradability certification requirements that determine shelf access for single-use packaging. ANSM enforces food-contact safety standards that extend product launch timelines for compostable serviceware. The country's national environmental agency administers extended producer responsibility frameworks with binding renewable content minimums.
Netherlands
Packaging converters in the Randstad cluster pilot closed-loop enzymatic recycling systems that return post-industrial polylactic acid waste to virgin-grade resin. Retail consortiums standardize compostability specifications across fresh produce and food-service categories. Eindhoven's industrial biotechnology infrastructure supports precision fermentation scale-up for polyhydroxyalkanoate production.
Japan
Automotive and electronics manufacturers in the Kanto and Kansai regions specify bio-based polyesters for interior components where carbon footprint disclosure drives brand positioning. METI coordinates national biomass utilization targets that incentivize agricultural feedstock integration. Osaka-based chemical conglomerates license fermentation technology to Southeast Asian joint ventures.
Bio-Based Polymer Market Key Industry Players
Global majors compete with regional champions across feedstock integration and certification depth. The market structures around three tiers: agricultural conglomerates with captive sugarcane or corn supply, specialized fermentation technology licensors, and diversified chemical majors with polymerization assets. Strategic moves concentrate on backward integration into agricultural sourcing and technology licensing partnerships that accelerate geographic expansion without greenfield capital deployment.
Within the agricultural-integrated tier, Braskem and NatureWorks exemplify contrasting geographic anchoring strategies. Braskem's Brazilian corporate structure reflects sugarcane belt proximity, while NatureWorks' US-based limited liability positioning concentrates North American food-service market access. European specialists including Novamont and Corbion occupy positions between regional feedstock optimization and pharmaceutical-grade certification depth.
| Leading Market Players |
|---|
| Mitsubishi Chemical Corporation |
| Braskem |
| NatureWorks |
| Teijin Limited |
| Arkema |
| BASF |
| Novamont |
| Kuraray |
| Corbion |
| Others |
Cost & Logistics Intelligence
Backward integration into agricultural feedstock sourcing anchors both supply security and margin control for fermentation-based polymer producers. Braskem's captive sugarcane supply in Brazil and NatureWorks' corn starch partnerships in the US Midwest exemplify how upstream control insulates against commodity volatility while supporting long-term offtake pricing.
Pricing Analysis
Input-cost pass-through from corn starch and sugarcane ethanol movements dominates pricing structures for polylactic acid and bio-based polyethylene. Three-tier pricing structure across pharmaceutical-grade, food-contact certified, and industrial commodity levels reflects certification depth and volume scale. Pricing pressure stems from mechanical recycling cost improvements in Germany that narrow the gap with fossil-based alternatives. Small and mid-size packaging converters exhibit highest price sensitivity, while healthcare device manufacturers accept premium tiers for validated sterilization compatibility.
Supply Chain Analysis
Dual-sourcing requirements from European retail chains and automotive OEMs mandate multi-supplier qualification for bio-based resin procurement. Geographic supply concentration centers on Brazil for sugarcane-ethanol polyethylene, the US Midwest for corn-derived polylactic acid, and Germany for polyamide compounding. Raw material dependencies include agricultural feedstocks, fermentation nutrients, and polymerization catalysts. Single-source vulnerability runs through Brazilian sugarcane harvest variability. Distribution runs through direct mill relationships for multinational brand owners and regional distributors for mid-size converters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EU Green Deal packaging mandates with binding renewable content minimums create structural demand pull. The analysis window favors stakeholders who align capacity expansion with certification standardization timelines.
For Market Incumbents: Anticipate margin compression from mechanical recycling infrastructure improvements in Germany by deepening fermentation yield advantages and securing mass-balance certification ahead of French and Dutch compliance deadlines. Prioritize pharmaceutical-grade capacity additions where sterilization validation creates technical barriers. Defend against sugarcane-ethanol parity erosion through backward integration into agricultural sourcing.
For New Entrants and Emerging Players: Distributor partnerships in the Netherlands and Germany offer the fastest path to specification influence with mid-size packaging converters facing EU Green Deal procurement pressure. Target marine biodegradability applications for polyhydroxyalkanoates where ocean-plastic regulations tighten fastest. Lead with closed-loop enzymatic recycling pilots that collapse mechanical and chemical recycling distinctions.
For Investors and Strategic Acquirers: Roll-up economics work for regional fermentation technology specialists because certification fragmentation and multi-standard compliance complexity favor scaled platforms with dedicated regulatory affairs capabilities. Long-term viability hinges on lignocellulosic feedstock transition timelines. Watch for agricultural commodity volatility spikes as inflection indicators for margin stress and consolidation triggers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock | Captive sugarcane or corn supply secures cost position against agricultural commodity swings. |
| Fermentation Yield Optimization | Industrial biotechnology clusters in Germany and Brazil compress unit economics for polylactic acid. |
| Mass-Balance Certification Investment | EU Green Deal documentation requirements determine shelf access in France and Netherlands retail. |
| Pharmaceutical-Grade Capacity Expansion | Medical device sterilization compatibility commands premium pricing with validated degradation kinetics. |
| Enzymatic Recycling Partnership | Netherlands pilot systems return post-industrial waste to virgin-grade resin for closed-loop packaging. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to capture both volume flows and specification dynamics. Primary interviews engaged plant managers at fermentation facilities, procurement leads at European packaging converters, distribution channel partners, and technical R&D directors for polymerization process development. Secondary validation drew from EU ECHA REACH registration databases, USDA BioPreferred certified product listings, customs trade data for bio-based resin imports, and SEC filings for agricultural-integrated chemical majors. Bottom-up capacity modeling and top-down demand segmentation were cross-referenced for triangulation.
Comparable-period anchoring tied projection assumptions to historical fermentation yield improvements and regulatory implementation timelines across the analysis window. The forecast framework modeled segmentation across product type, application, end user, and distribution channel dimensions, with additional granularity for certification tier and feedstock origin. CAGRs were derived from supply-demand balance modeling incorporating agricultural commodity price scenarios and capacity expansion announcements. Industry-specific inputs included EU Green Deal compliance timeline assumptions and marine biodegradability standard adoption curves.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to lignocellulosic feedstock technology maturation and agricultural land-use competition. Forecasts reflect documented assumptions about fermentation yield trajectories and regulatory enforcement intensity. Specific risk factors include REACH registration delays for novel monomers and sugarcane harvest volatility from climate patterns. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Agar Resin Market
Polymers & Resins
Rigid Colored PU Foam Market
Polymers & Resins
Polar Polymers Market
Polymers & Resins
Bio-Based Emulsion Polymers Market
Polymers & Resins
Bio-Based Polycarbonate Market
Polymers & Resins
Global One Component Polyurethane Foam Market
Polymers & Resins
Styrene Acrylonitrile (SAN) Resins Market
Polymers & Resins
Global Injection Molding Plastic Market
Polymers & Resins
South Korea Engineering Plastics Market
Polymers & Resins
Automotive Thermoplastic Polymer Composites Market
Polymers & Resins
Synthetic Polymer Waxes Market
Polymers & Resins
Polyacrylate Market
Polymers & Resins
Poly (1-Decene) Market
Polymers & Resins
Polysulfide Resin Market
Polymers & Resins
Polyacrylamide Market
Polymers & Resins
Polymer Resin Market