
 Sugar Polymers Market | 2026-2036
Sugar Polymers Market Size, Share, and Industry Trends Forecast 2026-2036
Sugar Polymers Market Analytics
Specialized polymer chemistry expertise is collapsing across European and North American manufacturing hubs, constraining capacity expansion for complex polysaccharide derivatives. Archer Daniels Midland Company leverages its agricultural feedstock infrastructure to secure cost-advantaged dextrose streams for polymer synthesis. Roquette Group anchors its position through backward integration into pea and potato starch processing, controlling raw material quality for pharmaceutical-grade excipients. Cargill competes via global origination networks that stabilize supply for cellulose and pectin precursor crops.
Sugar polymers comprise long-chain carbohydrate structures—typically with molecular weights exceeding 10,000 Daltons—derived from plant, algal, or fungal biomass through extraction, enzymatic modification, or fermentation processes, serving primarily as biodegradable thickeners, film formers, encapsulants, and structural matrices across formulated goods. Alginate dominates marine-sourced segments due to established gelling chemistry and food safety clearances, while chitosan from crustacean waste streams represents the fastest-expanding category as antimicrobial and mucoadhesive properties attract pharmaceutical formulators. Cellulose derivatives maintain the deepest margin pools in controlled-release drug applications where regulatory dossiers create formulation stickiness.
FDA excipient guidelines, EMA quality standards for drug delivery systems, and REACH registration requirements for novel biopolymer chemistries collectively elevate barriers for unqualified suppliers while steering investment toward documented safety profiles. The EU Green Deal's packaging waste directives and USDA bio-preferred procurement programs further channel commercial demand toward certified biodegradable sugar polymer grades. Stakeholders must monitor evolving pharmacopeial monographs and polymer purity thresholds as these standards increasingly determine contract eligibility with multinational food and pharmaceutical manufacturers.
Market Dynamics
EU Green Deal packaging waste directives and REACH registration requirements are compressing petroleum-derived polymer capacity while redirecting capital toward documented bio-based alternatives with validated safety dossiers.
Growth Catalysts
- EU Green Deal packaging mandates:Binding reduction targets for single-use plastics are pulling food manufacturers toward certified biodegradable alginate and cellulose films.
- Pharmaceutical controlled-release applications:FDA excipient guidelines favoring documented biopolymer safety profiles are locking in demand for high-purity chitosan matrices.
- German industrial biotech clustering:Concentrated contract manufacturing capabilities in Hamburg and Heidelberg are enabling scaled chitosan and alginate output for European formulators.
Market Restraints
- Feedstock cost volatility:Pea and potato starch prices fluctuate with agricultural yield cycles, compressing margins for excipient-grade polymer producers.
- Specialized polymer chemistry scarcity:Collapsing expertise across European and North American manufacturing hubs constrains capacity expansion for complex polysaccharide derivatives.
- REACH registration friction:Novel biopolymer chemistries face multi-year dossier preparation timelines, delaying market entry for unqualified suppliers.
Strategic Opportunities
- USDA bio-preferred procurement:Federal purchasing mandates are creating certified demand channels for domestic sugar polymer producers serving institutional foodservice.
- Antimicrobial pharmaceutical coatings:Chitosan's mucoadhesive properties are opening formulation white space in nasal and buccal drug delivery systems.
- Marine waste stream valorization:Crustacean processing byproduct recovery is converging with enzymatic modification technology to lower chitosan production costs.
Industry Challenges
- Pharmacopeial monograph compliance:Evolving polymer purity thresholds in USP and EP standards require continuous analytical method upgrades for contract eligibility.
- Multi-jurisdiction dossier management:Simultaneous FDA, EMA, and Health Canada excipient filings strain regulatory affairs capacity at mid-scale producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sugar Polymers Market |
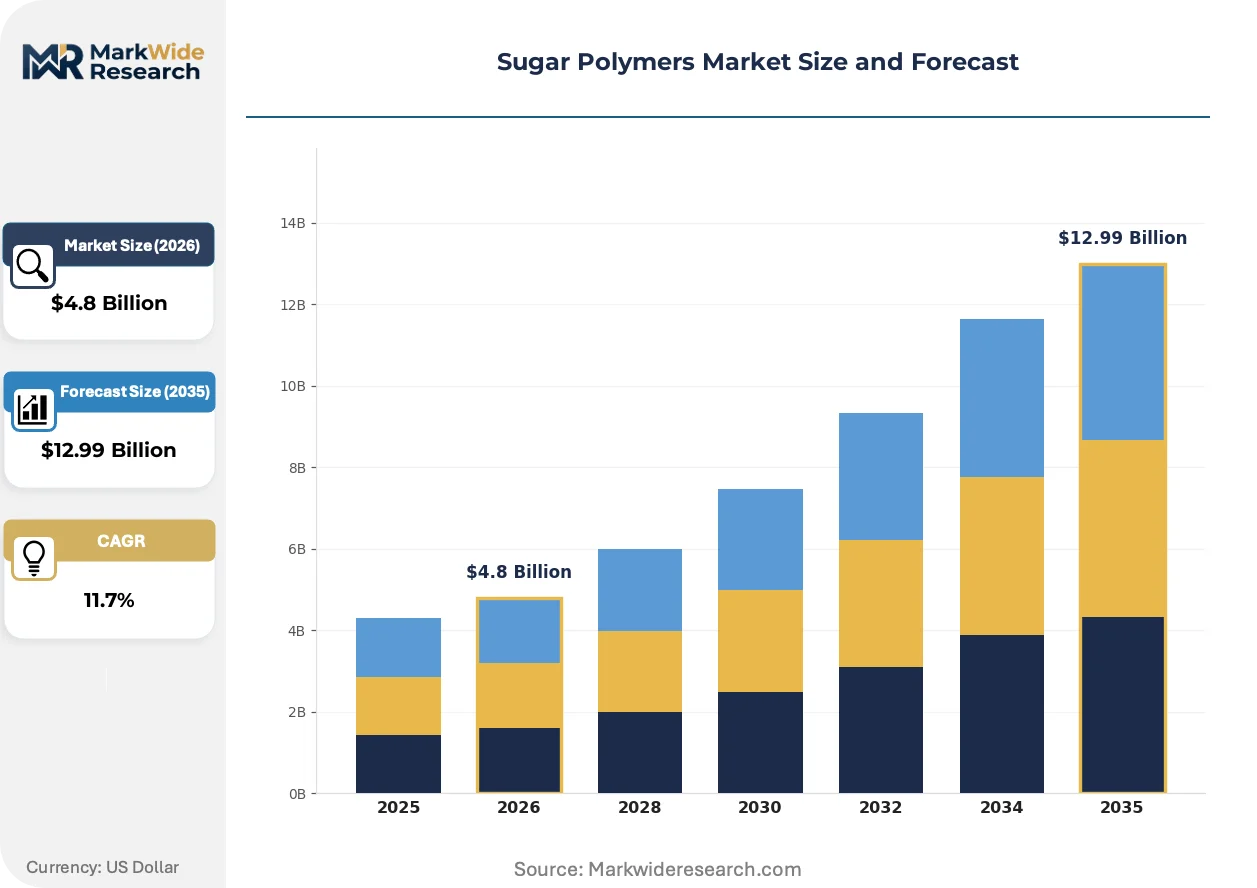
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Alginate, Chitosan, Cellulose, Pectin Application: Food & Beverage, Pharmaceuticals, Agriculture, Biodegradable Plastics End User: Food Manufacturers, Pharmaceutical Companies, Agricultural Firms, Cosmetic Brands Form: Powder, Granules, Gel, Liquid |
| Companies Covered | Archer Daniels Midland Company, Roquette Group, Cargill, Ashland, The Lubrizol Corporation, DFE Pharma, BASF SE, Meggle AG, Ingredion, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sugar Polymers Market Evolving Landscape
Enzymatic modification and precision fermentation are displacing conventional extraction methods, compressing molecular weight distribution tolerances and enabling tailored functionality for pharmaceutical formulators.
Precision fermentation of tailored polysaccharide structures is miniaturizing batch-to-batch variability that has historically plagued plant-extracted cellulose derivatives. Pharmaceutical formulators in Switzerland and Massachusetts are qualifying these bioengineered inputs for narrow-release-profile oral dosage forms. The technology is miniaturizing quality control overhead while accelerating regulatory dossier preparation timelines.
REACH registration requirements for novel biopolymer chemistries are elevating capital barriers for unqualified suppliers while steering investment toward documented safety profiles. Industrial biotech clusters in Germany and the Netherlands are consolidating polymer chemistry expertise to serve multinational food and pharmaceutical manufacturers. The regulation is compressing supplier fragmentation and favoring backward-integrated producers with captive analytical capabilities.
Certification-driven procurement is replacing commodity purchasing in European food packaging, with buyers demanding third-party biodegradable validation for alginate and pectin films. Multinational manufacturers in France and Italy are unbundling traditional supplier relationships to source through audited bio-preferred channels. The shift is most visible in ready-meal and fresh-produce segments where retail chains face Extended Producer Responsibility liability under EU packaging waste directives.
Sugar Polymers Market Segmentation
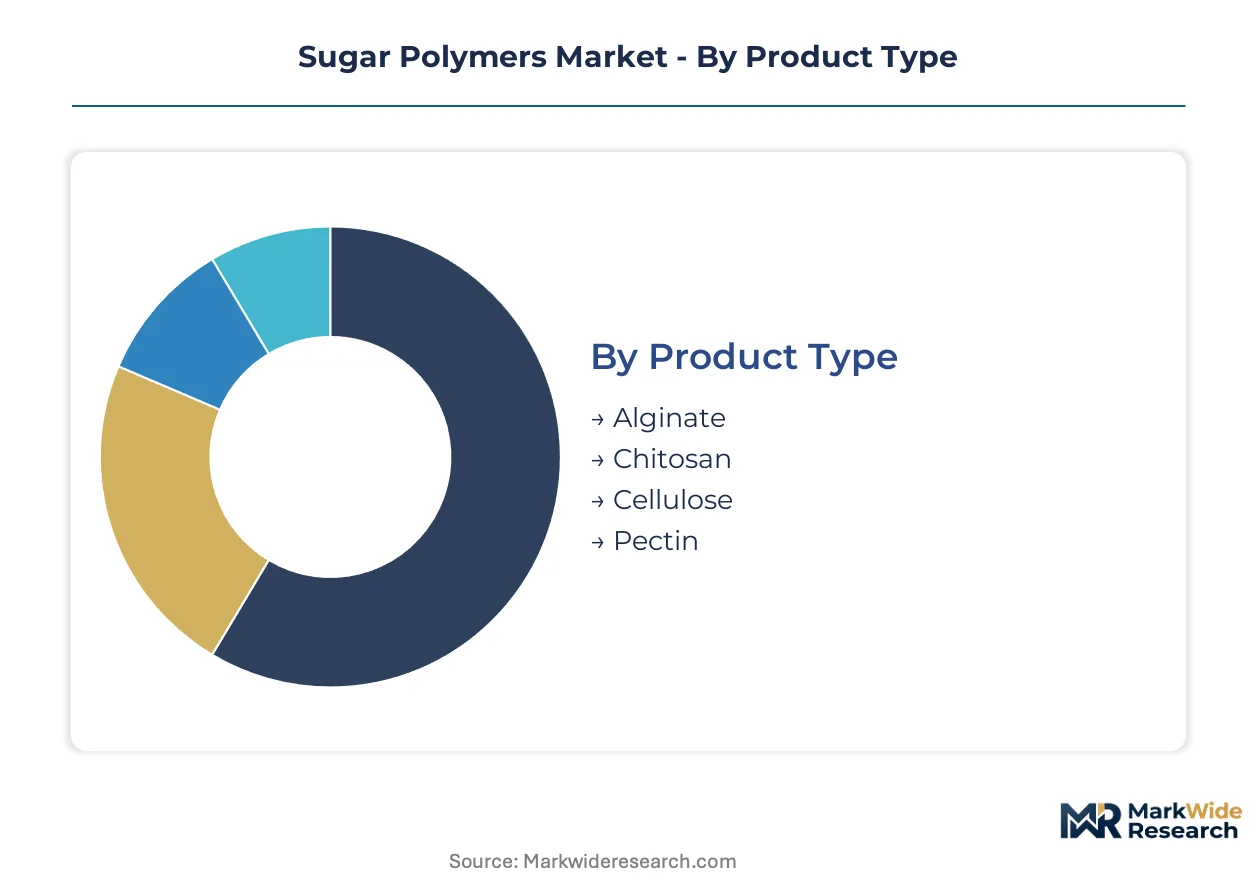
Sugar polymers derive commercial value from molecular architecture and purity grade, not commodity positioning. Segmentation reveals where formulation stickiness and regulatory dossiers protect margin pools against feedstock volatility.
Product Type:
Margin pools concentrate in pharmaceutical-grade derivatives where USP and EP monograph compliance creates supply scarcity.
- Alginate:Linear copolymer of β-D-mannuronic and α-L-guluronic acids extracted from brown seaweed. Food-grade alginate dominates gelling applications in Germany and France under EU packaging waste directives, while pharmaceutical-grade variants command premium positioning in controlled-release matrices.
- Chitosan:Deacetylated chitin from crustacean shells with antimicrobial and mucoadhesive functionality. Swiss and Massachusetts formulators are qualifying chitosan for nasal and buccal drug delivery systems, driving fastest expansion among marine-sourced polymers.
- Cellulose:β-1,4-linked glucose polymer modified for film-forming and thickening. Derivatives maintain deep margin pools in oral dosage forms where regulatory dossiers create formulation lock-in.
- Pectin:Heteropolysaccharide from citrus peel and apple pomace with gelling properties. Low-methoxyl grades serve reduced-sugar food applications in France and Italy.
Cellulose holds installed capacity. Chitosan is rotating up the share rankings.
Application:
Volume concentrates in food processing, but value migrates toward pharmaceutical controlled-release where purity thresholds elevate pricing power.
- Food & Beverage:Thickening, gelling, and film-forming across dairy, confectionery, and plant-based meat analogues. German and Italian manufacturers source certified biodegradable alginate and pectin films to meet Extended Producer Responsibility liability under EU Green Deal mandates.
- Pharmaceuticals:Excipient matrices for controlled-release oral dosage, wound dressings, and mucoadhesive delivery systems. FDA excipient guidelines and EMA quality standards favor documented biopolymer safety profiles, locking in demand for high-purity chitosan and cellulose derivatives.
- Agriculture:Seed coatings, controlled-release fertilizers, and soil conditioners. Pea and potato starch-based polymers serve this segment through Roquette's backward-integrated supply chain.
- Biodegradable Plastics:Film and packaging applications competing with petroleum-derived alternatives. REACH registration requirements compress unqualified supplier participation while favoring producers with validated safety dossiers.
Food & Beverage holds installed capacity. Pharmaceuticals is rotating up the share rankings.
End User:
Procurement sophistication varies sharply—multinational pharmaceutical companies demand batch-level traceability while agricultural firms prioritize cost position.
- Food Manufacturers:Ready-meal and fresh-produce packagers in France and Italy unbundle traditional supplier relationships to source through audited bio-preferred channels. Third-party biodegradable validation is replacing commodity purchasing.
- Pharmaceutical Companies:Formulators in Switzerland, Massachusetts, and Heidelberg qualify precision-fermented polysaccharides for narrow-release-profile dosage forms. Simultaneous FDA, EMA, and Health Canada excipient filings strain regulatory affairs capacity at mid-scale producers.
- Agricultural Firms:Seed and crop protection companies utilizing starch-based encapsulants. Demand fluctuates with agricultural yield cycles, compressing margins for excipient-grade polymer suppliers.
- Cosmetic Brands:Film formers and thickeners for skincare and haircare formulations. This segment represents the fastest-expanding demand channel for marine-derived polymers with clean-label positioning.
Food Manufacturers hold installed capacity. Pharmaceutical Companies is rotating up the share rankings.
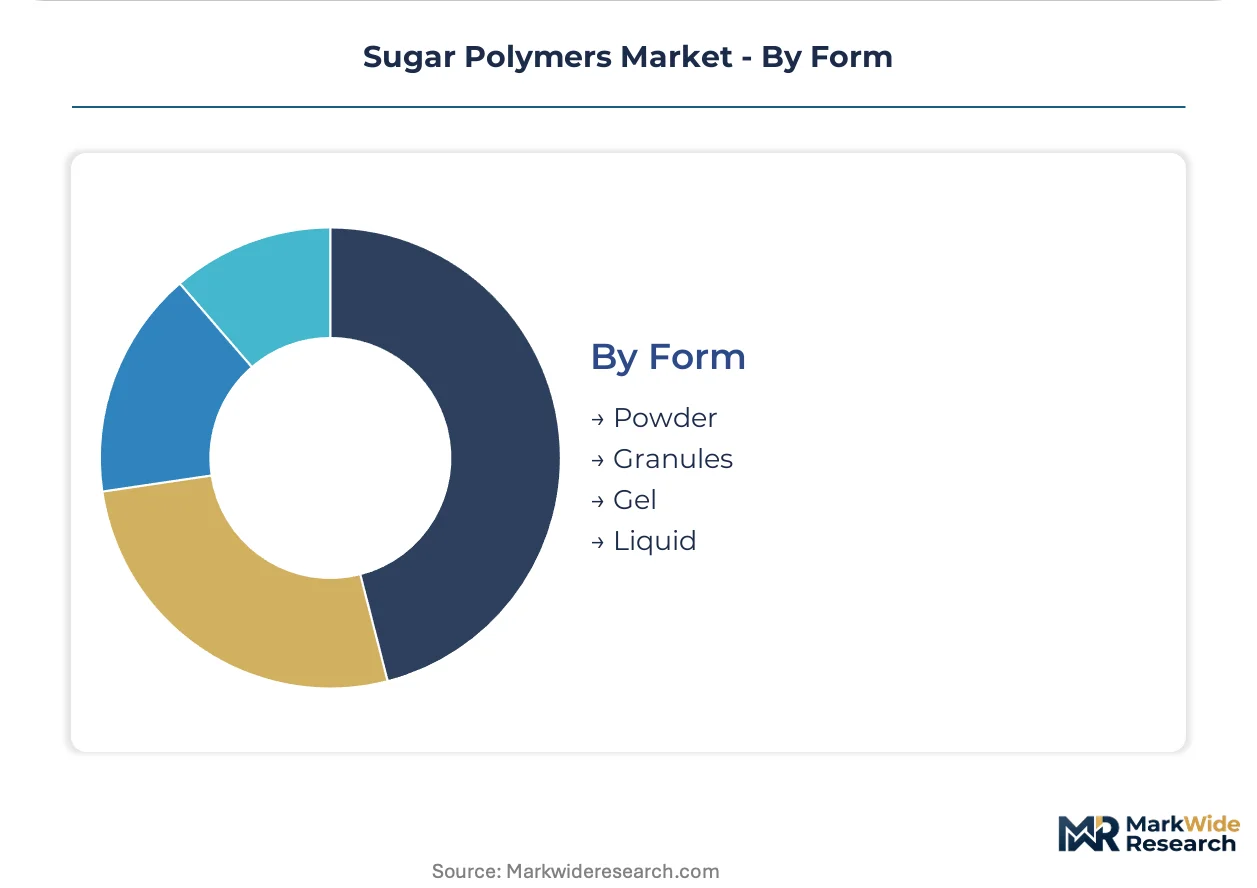
Form:
Physical form determines handling economics and dissolution kinetics, with powder and gel formats commanding distinct supply chain configurations.
- Powder:Dried and milled polysaccharides with extended shelf stability. Standard input for food thickening and pharmaceutical tableting, with Hamburg and Heidelberg contract manufacturers scaling output for European formulators.
- Granules:Agglomerated particles for controlled dissolution in agricultural and industrial applications. Lower dust generation improves handling economics for bulk fertilizer coatings.
- Gel:Hydrated polymer networks with immediate functional activation. Alginate gels serve wound care and food restructuring applications where instant gelling chemistry is required.
- Liquid:Pre-dispersed solutions eliminating hydration time. Preferred by cosmetic brands and beverage manufacturers for process efficiency, though transportation costs limit geographic reach.
Powder holds installed capacity. Gel is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EMA excipient guidelines and EU Green Deal mandates anchor European demand for pharmaceutical-grade sugar polymers, while FDA quality standards and USDA bio-preferred procurement channel North American investment toward documented biopolymer safety profiles.
Germany
Industrial biotech clusters in Hamburg and Heidelberg concentrate contract manufacturing capabilities for chitosan and alginate production. REACH registration requirements compress unqualified supplier participation while favoring producers with validated safety dossiers. The country's pharmaceutical formulators source high-purity excipients under EMA quality standards for controlled-release drug delivery systems.
United States
FDA excipient guidelines lock in demand for documented biopolymer safety profiles across Massachusetts and New Jersey pharmaceutical corridors. USDA bio-preferred procurement programs create certified demand channels for domestic producers serving institutional foodservice. Precision fermentation startups in Boston and San Francisco are qualifying tailored polysaccharides for narrow-release-profile oral dosage forms.
Switzerland
Swissmedic regulations and proximity to Basel-based pharmaceutical headquarters drive demand for batch-level traceability in excipient sourcing. Swiss formulators lead qualification of chitosan for nasal and buccal drug delivery systems. The Lake Geneva biotech corridor concentrates polymer chemistry expertise serving multinational drug manufacturers.
France
Extended Producer Responsibility liability under EU packaging waste directives pulls ready-meal and fresh-produce packagers toward certified biodegradable alginate and pectin films. ANSM quality standards govern pharmaceutical-grade polymer imports. Lyon and Paris industrial zones unbundle traditional supplier relationships to source through audited bio-preferred channels.
China
NMPA excipient registration requirements and dual carbon goals redirect investment from petroleum-derived polymers toward bio-based alternatives. Coastal processing hubs valorize crustacean waste streams for chitosan production. Shandong and Zhejiang provinces concentrate alginate extraction capacity serving domestic food and pharmaceutical manufacturers.
Sugar Polymers Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with agricultural conglomerates leveraging feedstock control against chemical firms with formulation expertise. The structure rewards backward integration into starch and cellulose precursor supply chains. Three archetypes dominate: crop-processing giants with captive raw material access, pharmaceutical excipient specialists with regulatory dossier depth, and industrial biotech innovators with precision fermentation capabilities. Competitive moves concentrate on strategic partnerships for novel biopolymer development and capacity expansion in German industrial clusters.
Among agricultural conglomerates, Archer Daniels Midland Company, Cargill, and Roquette Group exemplify the integrated archetype through upstream control over dextrose and starch feedstock streams. These entities anchor supply stability for downstream polymer synthesis. Within the chemical and pharmaceutical tier, BASF SE and Ashland occupy positions shaped by regulatory dossier capabilities and excipient formulation heritage. The competitive field compresses around documented safety profiles as FDA, EMA, and REACH standards elevate barriers for unqualified participants.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Roquette Group |
| Cargill |
| Ashland |
| The Lubrizol Corporation |
| DFE Pharma |
| BASF SE |
| Meggle AG |
| Ingredion |
| Others |
Value Network & Pricing Analysis
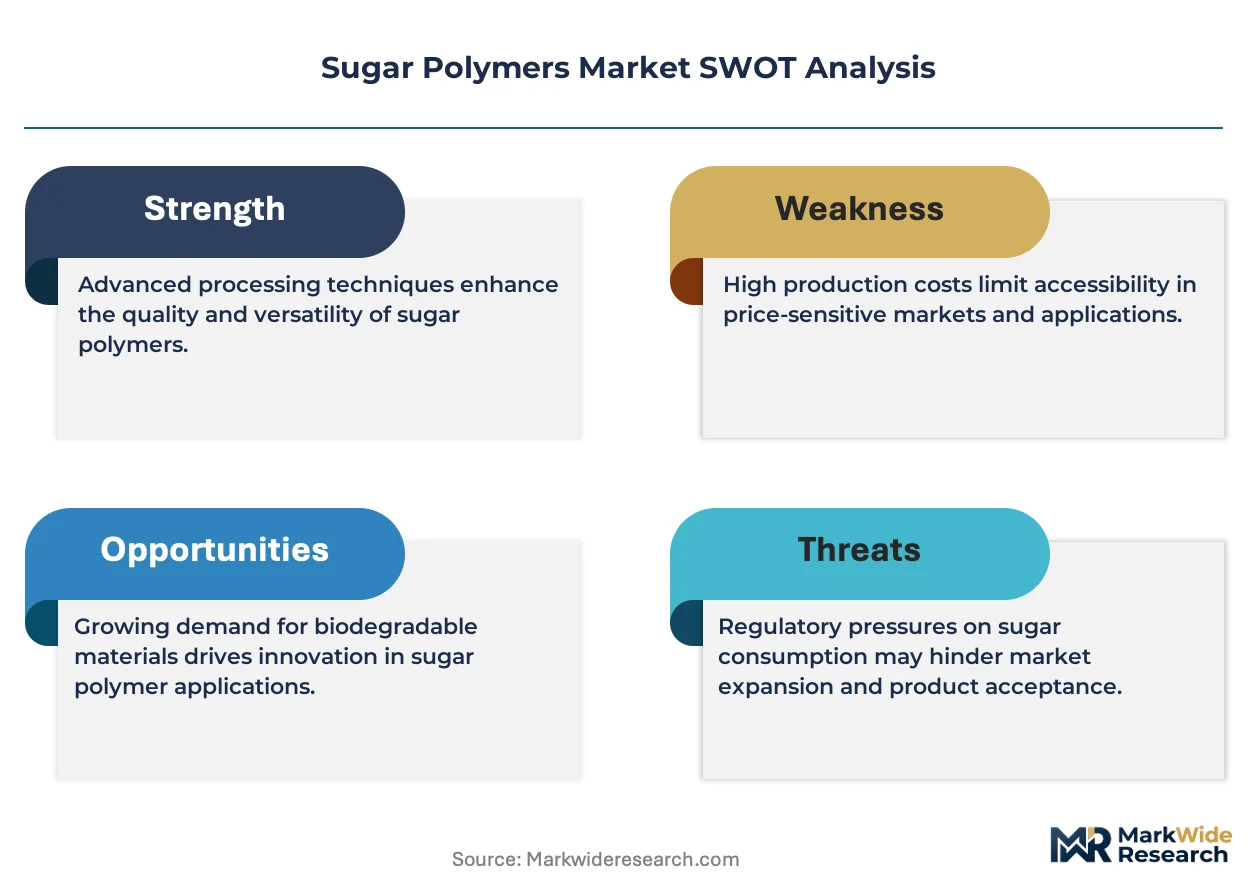
REACH registration requirements for novel biopolymer chemistries gate both supplier qualification and price differentiation simultaneously, compressing unqualified participants while rewarding documented safety profiles with premium positioning in pharmaceutical-grade segments.
Pricing Analysis
Pharmaceutical-grade chitosan commands spreads of 40-60% above food-grade alginate across Hamburg and Heidelberg contract manufacturing hubs. Three-tier pricing structure across pharmaceutical-grade excipients, food-grade films, and industrial thickeners stratifies by USP monograph compliance and batch-level traceability. Cost compression in food-grade tiers is intensifying because agricultural yield cycles destabilize pea and potato starch feedstock costs. Agricultural firms exhibit highest price sensitivity, while Swiss and Massachusetts pharmaceutical formulators prioritize regulatory dossier depth over unit economics.
Supply Chain Analysis
Inventory lead times for pharmaceutical-grade cellulose derivatives stretch 8-12 weeks due to analytical method validation requirements at Heidelberg contract manufacturers. Supply concentrates in Germany, China, and the United States, with Shandong and Zhejiang provinces anchoring alginate extraction capacity. The chain draws from crustacean waste streams, brown seaweed harvests, and enzymatically modified starch precursors. Single-source vulnerability runs through German industrial biotech clusters where polymer chemistry expertise has collapsed. Distribution runs through audited bio-preferred channels replacing traditional supplier relationships in French and Italian packaging markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The sugar polymers market sits in early-cycle expansion as precision fermentation technologies displace conventional extraction methods and open formulation white space in narrow-release-profile drug delivery systems.
For Market Incumbents: Shield formulation lock-in in controlled-release oral dosage segments by deepening USP and EP monograph dossiers before precision-fermented alternatives achieve regulatory parity. Prioritize backward integration into crustacean waste stream recovery to neutralize feedstock cost volatility threatening alginate and chitosan margins. Capacity expansion in Hamburg and Heidelberg industrial clusters captures German pharmaceutical formulator concentration under EMA quality standards.
For New Entrants and Emerging Players: Differentiate on enzymatic modification capabilities that compress molecular weight distribution tolerances for Swiss and Massachusetts pharmaceutical formulators. Target antimicrobial pharmaceutical coatings in nasal and buccal drug delivery systems where chitosan's mucoadhesive properties remain underpenetrated by established suppliers. Pursue USDA bio-preferred certification as the primary go-to-market credential for institutional foodservice channels.
For Investors and Strategic Acquirers: EU Green Deal packaging mandates reshape the acquisition landscape by certifying demand channels and elevating capital barriers for unqualified biopolymer suppliers. Five-to-ten-year viability hinges on regulatory dossier depth rather than commodity scale. Target mid-scale producers with captive analytical capabilities and validated REACH registrations. Monitor evolving pharmacopeial monographs as the signal for which contract manufacturers will retain multinational eligibility.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Crustacean Waste Recovery | Roquette Group's captive supply of chitosan precursors neutralizes agricultural yield volatility compressing competitor margins. |
| Precision Fermentation Scale-Up | Boston and San Francisco startups miniaturize batch-to-batch variability plaguing plant-extracted cellulose derivatives for pharmaceutical formulators. |
| REACH Registration Dossier Investment | Documented safety profiles under ECHA requirements lock out unqualified suppliers from EU pharmaceutical and food packaging procurement. |
| USDA Bio-Preferred Certification | Federal purchasing mandates create audited demand channels for domestic alginate and pectin film producers serving institutional foodservice. |
| Joint Venture in German Industrial Clusters | Hamburg and Heidelberg contract manufacturing partnerships concentrate polymer chemistry expertise depleted across North American hubs. |
Research Methodology
A standing panel of pharmaceutical formulators, excipient procurement managers, regulatory affairs directors, and contract manufacturing executives provided ongoing calibration across the analysis window. Primary interviews with these stakeholders combined with secondary validation from EMA quality standards documentation, FDA excipient guidelines, REACH registration databases, and EU Green Deal packaging waste directive filings. Bottom-up capacity assessments at German industrial biotech clusters triangulated against top-down demand modeling from pharmaceutical and food manufacturer procurement patterns.
Consistency checks validated volume and value outputs against customs data for alginate and chitosan trade flows, SEC filings from agricultural conglomerates with polymer divisions, and Cefic reports on European biopolymer capacity. The analytical framework segmented by product type, application, end user, and physical form across the projection horizon. CAGRs derived from installed capacity growth rates, regulatory-driven substitution elasticities for petroleum-derived polymers, and penetration assumptions for precision-fermented alternatives. Feedstock cost models incorporated agricultural yield cycle volatility for pea and potato starch inputs.
The analysis sits within stated boundaries; outcomes outside sustained EMA and FDA excipient guideline enforcement, or disruptions to crustacean and seaweed supply chains, would require recalibration. Forecasts reflect assumptions about regulatory timeline adherence and polymer purity threshold evolution. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
High-Solids Acrylic Polyol Resins for Low-VOC Industrial Coatings Market
Polymers & Resins
C9 Resin Market
Polymers & Resins
Global Polyurethane Dispersions Market
Polymers & Resins
Ethylene Vinyl Acetate (EVA) Market
Polymers & Resins
Asia-Pacific Thermoplastics Market
Polymers & Resins
US Acrylic Solid Surface Market
Polymers & Resins
Copolyesters Market
Polymers & Resins
Expanded Polypropylene Market
Polymers & Resins
HDPE Large Blow Molded Products Market
Polymers & Resins
Bio-Based and Synthetic Polyamide Market
Polymers & Resins
Green Polyols Market
Polymers & Resins
Flame Retardant Polyester Resins Market
Polymers & Resins
Global Thermosetting Polymer Market
Polymers & Resins
Styrenic Block Copolymer (SBC) Market
Polymers & Resins
Resin Dispersion Market
Polymers & Resins
Global Bio Polyamide Market