
 Global Picture Archiving Communications System Market | 2026-2036
Global Picture Archiving Communications System Market Size, Share, and Industry Trends Forecast 2026-2036
Global Picture Archiving Communications System Market Intelligence
Procurement power concentration within large hospital networks and integrated delivery networks is shifting the vendor selection process for imaging informatics. GE HealthCare leverages its extensive installed base in imaging hardware to bundle PACS solutions. Siemens Healthineers differentiates through its AI-enhanced diagnostic software integrations, while Sectra competes on the basis of its enterprise imaging platform's scalability and security features.
A Picture Archiving Communications System is a medical imaging technology providing economical storage and convenient access to images from multiple modalities. These systems use the DICOM standard to store, retrieve, and present images, effectively replacing physical film archives. While hospitals remain the dominant end-user, the adoption of cloud-based deployment models is accelerating across both hospitals and specialized diagnostic centers due to lower capital expenditure and improved data accessibility.
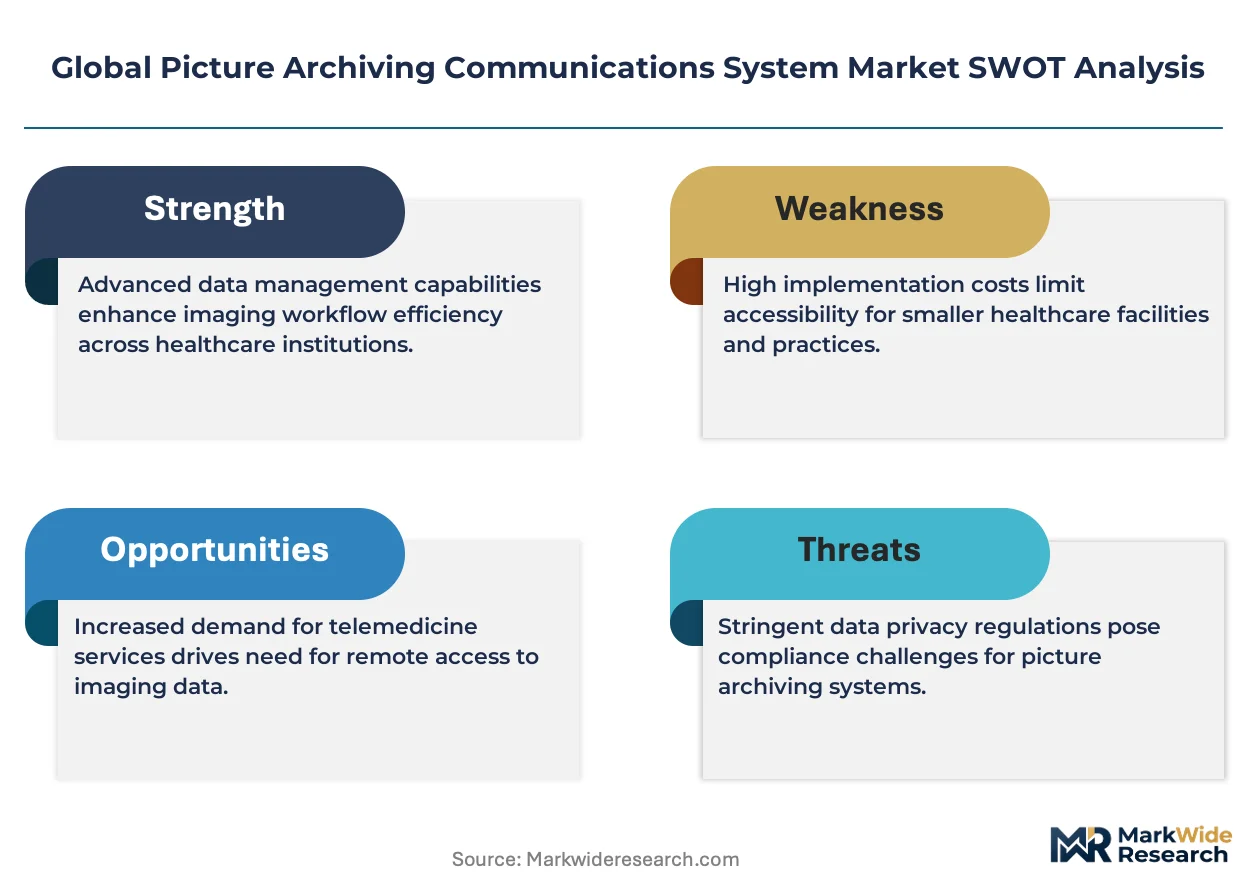
Data security and patient privacy regulations, such as HIPAA in the United States and GDPR in Europe, mandate stringent data handling protocols. In parallel, market access in countries like China is governed by NMPA oversight on medical device software. Vendor success depends on navigating these complex regional compliance landscapes while delivering interoperable, AI-ready platforms that meet evolving clinical needs.
Market Dynamics
The convergence of artificial intelligence with diagnostic workflows and the regulatory demand for enhanced data interoperability are the central forces shaping the PACS market. These pressures compel healthcare providers to modernize legacy imaging informatics infrastructure.
Growth Catalysts
- AI-Powered Analytics:The integration of artificial intelligence for image analysis and workflow optimization is a primary catalyst, enabling faster diagnostics in radiology departments.
- Increasing Diagnostic Volumes:A sustained rise in the volume of diagnostic imaging procedures, particularly in hospitals, necessitates more efficient and scalable image storage and retrieval systems.
- Healthcare IT Mandates:Government initiatives in countries like the United States promoting electronic health record interoperability create a strong pull for modern PACS that can integrate with other clinical systems.
Market Restraints
- High Implementation Costs:The significant upfront capital expenditure required for on-premise PACS hardware, software licensing, and system integration remains a substantial barrier for smaller hospitals and clinics.
- Data Migration Challenges:Migrating vast archives of legacy imaging data from older systems to new platforms is a complex, time-consuming, and expensive process, often delaying upgrade decisions.
- Regulatory Compliance Burden:Adherence to stringent patient data privacy regulations like HIPAA in the US and GDPR in Europe adds significant complexity and cost to system design and operation.
Strategic Opportunities
- Cloud-Native Platforms:Developing truly cloud-native PACS solutions offers opportunities to serve smaller diagnostic centers with scalable, opex-based models that bypass high initial costs.
- Expansion in Developing Economies:Healthcare infrastructure modernization in countries across Southeast Asia and Latin America presents a significant opportunity for vendors offering cost-effective imaging solutions.
- Enterprise Imaging Consolidation:Expanding beyond radiology to create enterprise-wide platforms that manage images from cardiology and pathology represents a major growth vector for vendors.
Industry Challenges
- System Interoperability:Ensuring seamless data exchange between new PACS and a hospital's diverse ecosystem of existing EHRs, RIS, and legacy imaging modalities is a persistent technical challenge.
- Skilled Personnel Shortage:A lack of IT professionals with specialized expertise in both medical imaging informatics and modern cloud security creates implementation bottlenecks for healthcare providers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Picture Archiving Communications System Market |
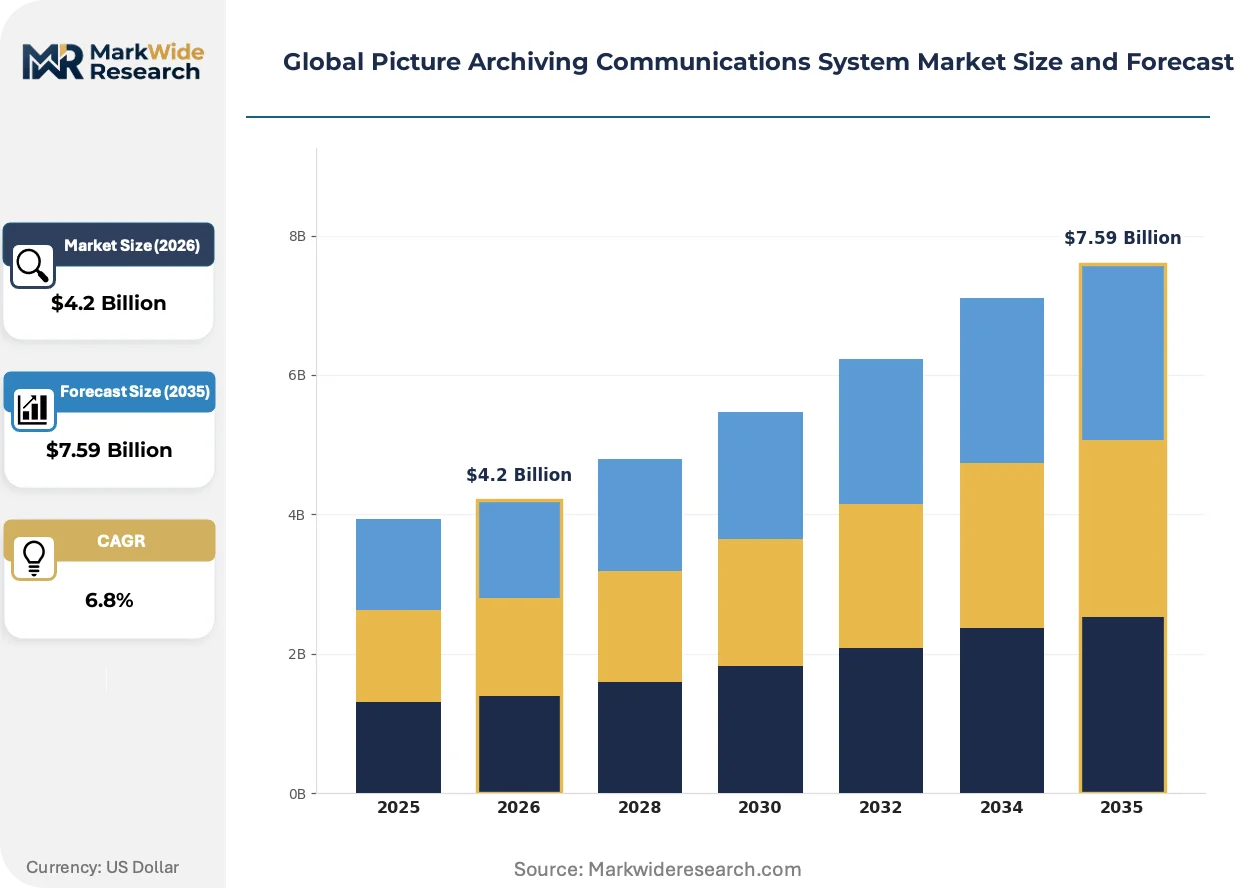
| Market Size in 2026 | $4.2 Billion |
| Market Size in 2035 | $7.59 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hardware, Software, Services, Network Solutions Deployment: On-premise, Cloud-based, Hybrid, Virtual Application: Diagnostic Imaging, Telemedicine, Surgical Planning, Clinical Research, Education End User: Hospitals, Diagnostic Centers, Research Institutes, Academic Institutions |
| Companies Covered | GE HealthCare, Philips Healthcare, FUJIFILM Healthcare, Agfa HealthCare, Siemens Healthineers, Sectra, Intelerad, Carestream, Change Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Picture Archiving Communications System Market Strategic Shifts & Innovations
The evolution of PACS technology is defined by the move from siloed, on-premise archives to integrated, intelligent enterprise platforms. This transition prioritizes data liquidity, AI-readiness, and secure, remote accessibility for clinicians.
Cloud-based deployment models provide scalable storage and computational power for medical imaging without large upfront capital investments. Healthcare providers, from large hospitals to specialized diagnostic centers, are increasingly adopting this approach. The operational expenditure model of cloud PACS is overtaking the traditional capital expenditure model for new system deployments.
Data security and privacy mandates, including GDPR in Europe and HIPAA in the United States, are shaping system architecture. These regulations require vendors to implement robust encryption, access controls, and audit trails for all patient data. Consequently, security-by-design principles are now a standard requirement in evaluations, particularly for cloud-based systems.
A significant behavioral shift is the move from departmental purchasing of radiology-specific PACS to a centralized, enterprise imaging strategy. This approach consolidates imaging data from multiple clinical specialties like cardiology and pathology into a single, unified archive. Large integrated delivery networks in North America and Europe are leading this consolidation to improve clinical collaboration.
Global Picture Archiving Communications System Market Segmentation
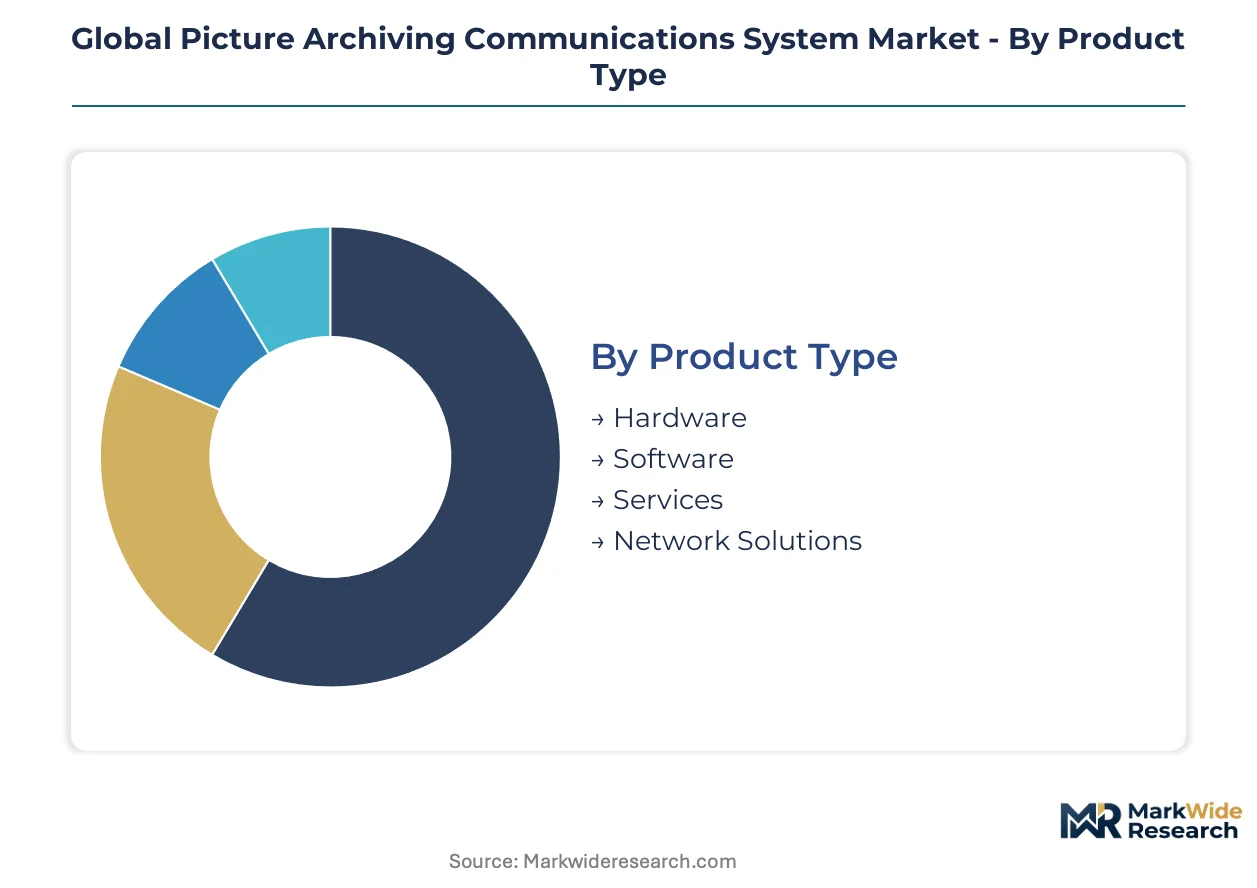
The Picture Archiving Communications System market is categorized by distinct product offerings, deployment models, applications, and end-user types. Understanding these segments reveals how healthcare providers procure and utilize imaging informatics solutions. This granular view highlights areas of innovation and demand across the global landscape.
Product Type:
The continuous upgrade and replacement cycle for imaging informatics drives demand across various product types within the PACS market. Healthcare facilities constantly seek to modernize their infrastructure for efficiency.
- Software:These core platforms manage image storage, retrieval, and display, often integrating advanced features like AI-powered analytics. Demand concentrates in hospitals and diagnostic centers upgrading legacy systems for enhanced interoperability and diagnostic speed.
- Services:This segment includes implementation, maintenance, training, and consulting for PACS solutions, critical for complex system deployments. Demand concentrates in large hospital networks in the United States, where providers require comprehensive support for enterprise-wide rollouts.
- Hardware:Physical components such as servers, workstations, and storage devices form the foundational infrastructure for PACS installations.
- Network Solutions:These enable secure and efficient transmission of imaging data across different departments and remote locations.
Volume placements concentrate in Software; the faster expansion belongs to Services.
Deployment:
Deployment models reflect varied capital expenditure strategies and operational preferences among healthcare organizations. Providers choose based on their IT infrastructure, security requirements, and budget constraints.
- Cloud-based:These platforms offer scalable storage and computational power hosted by third-party providers, reducing upfront capital investment for healthcare facilities. Demand is strong among specialized diagnostic centers and smaller hospitals seeking operational expenditure models.
- On-premise:These traditional systems are installed and managed within the healthcare facility's own data centers, providing maximum control over data security. Large integrated delivery networks often prefer on-premise solutions for their established IT environments.
- Hybrid:This model combines elements of both on-premise and cloud deployments, allowing for flexible data management and storage strategies.
- Virtual:Virtualized PACS solutions utilize software-defined infrastructure to enhance flexibility and resource utilization within existing hardware.
The market share for On-premise solutions remains significant, while Cloud-based deployment models exhibit the steepest expansion trajectory.
Application:
The diverse applications of PACS technology underscore its critical role in various clinical and administrative workflows. Each application addresses specific needs within the healthcare ecosystem.
- Diagnostic Imaging:This primary application involves the storage, retrieval, and display of images from modalities like X-ray, MRI, and CT for radiological interpretation. Demand is universal across hospitals and diagnostic centers due to rising diagnostic volumes.
- Telemedicine:PACS facilitates remote access to medical images for consultations and diagnoses, enabling specialists to provide care across geographical distances. This application experiences strong demand in developing economies and rural areas for improved access.
- Surgical Planning:PACS aids surgeons in pre-operative planning by providing detailed anatomical visualization from various imaging studies.
- Clinical Research:Researchers utilize PACS for archiving and analyzing large datasets of medical images to advance medical knowledge and treatment protocols.
- Education:Academic institutions leverage PACS for teaching medical students and residents about diagnostic imaging interpretation and clinical cases.
Diagnostic Imaging represents the foundational utility, with Telemedicine gaining share fastest due to remote care initiatives.
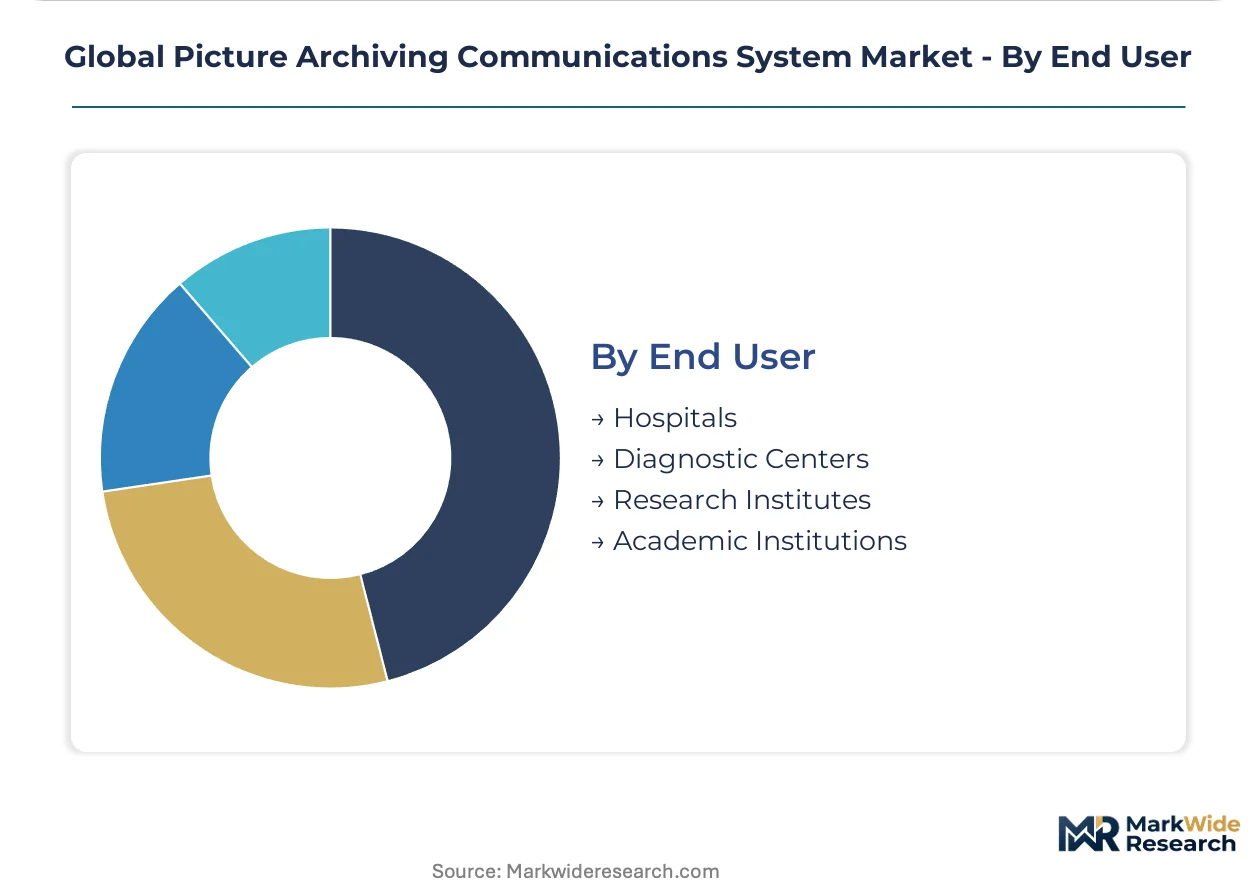
End User:
End-user segmentation reflects the varying procurement power and specific operational requirements of different healthcare entities. Each type of organization has distinct needs for PACS functionality and scale.
- Hospitals:These institutions are the largest end-users, requiring comprehensive PACS solutions to manage high volumes of imaging data across multiple departments. Procurement power concentrates within large hospital networks in the United States and Europe.
- Diagnostic Centers:Specialized facilities focusing solely on imaging procedures demand efficient, often cloud-based, PACS for rapid image processing and sharing with referring physicians. These centers often prioritize cost-effective, scalable solutions.
- Research Institutes:These entities use PACS for managing extensive image archives for clinical trials and scientific investigations, often requiring advanced analytics capabilities.
- Academic Institutions:Universities and medical schools employ PACS for educational purposes, providing students with access to real-world patient imaging data for learning.
Hospitals account for the largest volume of PACS deployments, while Diagnostic Centers are drivers of cloud-native platform innovation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for Picture Archiving Communications Systems concentrates significantly in established healthcare markets. The United States exhibits strong demand as providers upgrade legacy systems to enhance interoperability and efficiency. This modernization drive is mirrored in other advanced economies and emerging markets.
United States
The United States drives significant PACS demand as healthcare providers modernize legacy imaging informatics infrastructure. HIPAA regulations enforce strict patient data privacy, requiring robust security features in new system deployments. Major healthcare systems in regions like the Northeast Corridor are consolidating imaging data across multiple facilities for improved clinical collaboration.
Germany
Germany maintains strong demand for advanced PACS solutions, particularly with increasing diagnostic imaging volumes and AI integration. GDPR mandates comprehensive data protection for patient records, influencing system architecture and vendor selection. Major medical centers in regions such as Bavaria are adopting enterprise imaging platforms to enhance scalability and security.
China
China's PACS market experiences rapid expansion driven by extensive healthcare infrastructure modernization initiatives. NMPA regulations dictate stringent approval processes for medical device software, shaping vendor market entry strategies. Major medical facilities across the Yangtze River Delta are adopting advanced imaging systems to manage growing diagnostic volumes.
India
India presents a significant opportunity for PACS vendors due to increasing healthcare digitalization and diagnostic center expansion. The country's national health data management policies are promoting electronic health record interoperability, influencing PACS integration requirements. Growing medical hubs in regions like Karnataka are adopting cost-effective imaging solutions to cater to rising patient demand.
Global Picture Archiving Communications System Market Key Industry Players
North American producers anchor one tier of the PACS market; European specialists hold significant influence in enterprise imaging. The market exhibits a tiered structure, with large diversified healthcare technology conglomerates competing alongside specialized imaging informatics vendors. These players differentiate through AI-enhanced diagnostic software integrations and scalable enterprise imaging platforms. Strategic partnerships and portfolio diversification are common competitive moves to address evolving clinical needs and stringent regulatory demands.
Within the diversified healthcare technology tier, GE HealthCare exemplifies a strategy leveraging its extensive installed base in imaging hardware to bundle comprehensive PACS solutions. Siemens Healthineers, a German-based entity, represents a focus on AI-enhanced diagnostic software integrations, significantly differentiating its offerings in the market. Sectra AB, a Swedish company, occupies a strong position emphasizing enterprise imaging platforms known for their scalability, security features, and broad clinical applicability. These companies collectively anchor the market's premium segment, responding to demand from large hospital networks for comprehensive, interoperable, and AI-ready solutions.
| Leading Market Players |
|---|
| GE HealthCare |
| Philips Healthcare |
| FUJIFILM Healthcare |
| Agfa HealthCare |
| Siemens Healthineers |
| Sectra |
| Intelerad |
| Carestream |
| Change Healthcare |
| Others |
Cost & Logistics Intelligence
GDPR and HIPAA regulations, as critical data privacy mandates, gate both qualified vendor supply and premium-tier pricing access for compliant PACS solutions. These stringent requirements necessitate significant investment in secure system architecture and operational protocols.
Pricing Analysis
Volume-based licensing models drive significant revenue for on-premise PACS, while cloud-based subscriptions increasingly shape margin structures for new deployments. Price differentiation stems from advanced AI integration capabilities and robust cybersecurity features. Pricing softness reflects the shift towards operational expenditure models, particularly for smaller diagnostic centers. Large integrated delivery networks, however, exhibit lower price sensitivity, prioritizing comprehensive feature sets and enterprise-wide scalability.
Supply Chain Analysis
Logistics and freight costs for physical server hardware components impact on-premise PACS deployments, particularly for global installations. The supply chain for PACS primarily draws from software development hubs in the United States and Europe, alongside hardware manufacturing concentrated in Asia. Key component dependencies include high-performance server hardware, specialized imaging processors, and secure cloud infrastructure services. Cybersecurity threats and data center outages represent a significant structural supply chain risk. Distribution runs through direct sales channels for large hospital networks and value-added resellers for smaller clinics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The PACS market is witnessing a vertical-integration race, with vendors aggressively pursuing in-house AI development capabilities as a core downstream lever.
For Market Incumbents: Deploy AI-enhanced diagnostic software integrations to fortify existing customer bases against emerging cloud-native competitors. Expand enterprise imaging platforms beyond radiology to consolidate imaging data from cardiology and pathology, addressing the threat of departmental-specific solutions. Leverage extensive installed bases in imaging hardware to bundle comprehensive, interoperable PACS solutions, reinforcing market position.
For New Entrants and Emerging Players: Cloud-native platforms offer a technology-first wedge into underserved market segments like specialized diagnostic centers and developing economies. Target underpenetrated rural areas with cost-effective, scalable solutions that bypass high upfront capital expenditure. A subscription-based, operational expenditure go-to-market angle facilitates rapid adoption and reduces financial barriers for smaller providers.
For Investors and Strategic Acquirers: Accelerated cloud adoption rates across hospital networks is the leading indicator that the PACS market is transitioning towards a predominantly opex-driven model. Long-term viability favors providers of integrated, AI-ready enterprise imaging solutions over the next decade. Seek acquisition targets with proven expertise in AI-driven analytics, cloud infrastructure, or strong regional market access in high-growth areas.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Consolidates disparate imaging data sources into unified systems for enhanced clinical collaboration. |
| Strategic Partnership | Leverages complementary technologies, like AI algorithms, to expand product capabilities and market reach. |
| Acquisition of Specialist Firm | Gains access to niche expertise in areas such as cybersecurity or advanced image analytics. |
| Geographic Expansion | Captures demand in emerging economies with modernizing healthcare infrastructure. |
| Product Launch (Cloud-Native PACS) | Addresses the growing preference for operational expenditure models among diagnostic centers. |
Research Approach
Document review covered regulatory filings, clinical guidelines, and industry whitepapers, complemented by interviews with radiology department heads and IT procurement specialists. Primary research also engaged medical imaging software engineers and healthcare administrators to gather qualitative insights. This comprehensive approach ensured a balanced perspective, triangulating information from diverse industry stakeholders and secondary validation sources like SEC filings and healthcare IT market reports. Bottom-up and top-down data validation refined market size and growth estimates.
Historical adoption trends were cross-referenced with expert panel input to construct the market forecast across the analysis window. The analytical framework modeled segmentation dimensions including product type, deployment model, application, end-user, and regional adoption patterns. Compound annual growth rates were derived from regression analysis of historical data and projected market growth factors. Key forecast inputs included diagnostic imaging procedure volumes and healthcare IT spending trends over the projection horizon.
Several conditions sit outside the modeled scope, including unforeseen global health crises and major geopolitical shifts impacting healthcare spending. Forecasts reflect assumptions regarding technological advancements and stable regulatory environments throughout the forecast period. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Fluoroscopy Devices Market
Medical Imaging
Portable Cardiology Ultrasound Systems Market
Medical Imaging
Mexico Digital Radiology Market
Medical Imaging
Diagnostic X-Ray System Market
Medical Imaging
United Kingdom Mammography Market
Medical Imaging
US Imaging Services Market
Medical Imaging
Asia-Pacific Intraoperative Imaging Market
Medical Imaging
Digital Pathology Market
Medical Imaging
Magnetic Resonance Imaging (MRI) Equipment Market
Medical Imaging
China Digital Radiology Market
Medical Imaging
Germany Magnetic Resonance Imaging Market
Medical Imaging
Medical Imaging Informatics Market
Medical Imaging
Contrast Media Market
Medical Imaging
Japan Computed Tomography Market
Medical Imaging
Fluoroscopy C-Arms Market
Medical Imaging
China Digital X-Ray Market