
 Healthcare Cloud Picture Archiving and Communications System Market | 2026-2036
Healthcare Cloud Picture Archiving and Communications System Market Size, Share, and Industry Trends Forecast 2026-2036
Healthcare Cloud Picture Archiving and Communications System Market Intelligence
Modular subscription bundling is rebalancing procurement patterns across hospital procurement departments. Konica Minolta Healthcare Americas leverages its installed base of diagnostic hardware to anchor hybrid cloud transitions. Ambra Health competes through API-first architecture that integrates with existing electronic health record ecosystems. Koninklijke Philips sustains technology leadership in enterprise imaging platforms that unify cardiology, radiology, and pathology workflows.
Healthcare Cloud Picture Archiving and Communications Systems comprise software solutions, storage infrastructure, and viewer applications that transmit, store, and retrieve digital medical images using DICOM standards and HL7 FHIR protocols for interoperability. These systems replace film-based radiology workflows with centralized digital repositories accessible across clinical departments. Software Solutions capture the dominant margin pool as vendors embed AI-assisted diagnostic tools into native platforms. Hybrid Cloud delivery models are expanding fastest among mid-sized hospital networks seeking cost flexibility without surrendering data sovereignty. Hospitals remain the anchor end-user segment, though Imaging Centers represent the fastest-growing buyer category as outpatient consolidation accelerates.
FDA oversight of software as a medical device and HIPAA security rule enforcement shape vendor R&D priorities and customer compliance spending. The European Medical Device Regulation and GDPR data-localization requirements create divergent certification burdens for multinational suppliers. Stakeholders must monitor how ONC interoperability mandates and emerging state-level patient data privacy laws reshape cloud deployment architectures and vendor qualification criteria.
Market Dynamics
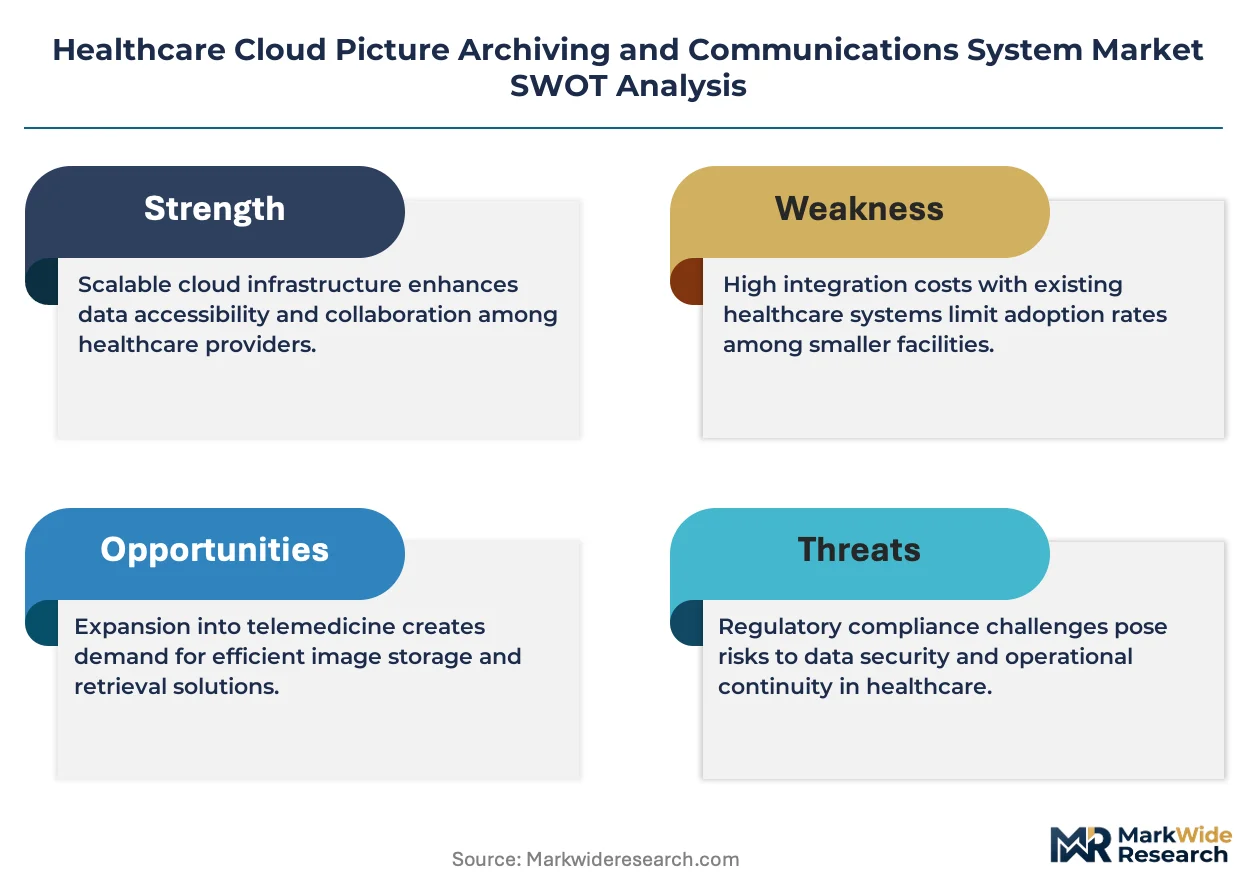
Enterprise imaging consolidation across US hospital networks is compressing vendor selection cycles and forcing cloud-native architectures to displace legacy on-premise PACS installations. HIPAA security rule enforcement and FDA software-as-medical-device guidance are accelerating cybersecurity investment as qualification criteria harden.
Growth Catalysts
- ONC Interoperability Mandates:US health systems must demonstrate HL7 FHIR compliance to maintain federal reimbursement eligibility, forcing cloud PACS upgrades that embed native interoperability protocols.
- AI-Assisted Diagnostic Integration:Radiology departments are demanding embedded machine learning tools for lesion detection and workflow prioritization, pulling software solution margins upward.
- Outpatient Imaging Center Consolidation:Ambulatory networks across the United States are centralizing image storage to reduce capital expenditure and enable multi-site radiologist coverage.
Market Restraints
- Data Sovereignty Requirements:GDPR localization rules in Europe and emerging state-level patient privacy laws in the United States fragment cloud architecture design and multiply compliance costs.
- Hybrid Cloud Integration Complexity:Mid-sized hospital networks lack internal expertise to synchronize on-premise DICOM archives with public cloud tiers, extending deployment timelines.
- Cybersecurity Insurance Escalation:Ransomware targeting healthcare infrastructure has driven cyber liability premiums upward, consuming IT budgets that would otherwise fund PACS migration.
Strategic Opportunities
- Cardiology-Pathology Convergence:Enterprise imaging platforms that unify radiology, cardiology, and pathology workflows into single cloud repositories command premium positioning in US academic medical centers.
- API-First Ecosystem Expansion:Electronic health record integration layers that enable third-party diagnostic tool deployment create recurring revenue streams beyond core storage subscriptions.
- State-Level Privacy Law Arbitrage:Vendors architecting flexible data residency controls can capture health systems in California, Texas, and New York as patchwork regulations proliferate.
Industry Challenges
- DICOM-FHIR Mapping Expertise Scarcity:Health systems struggle to hire integration engineers capable of bridging legacy imaging formats with modern interoperability standards.
- Software-as-Medical-Device Validation Timelines:FDA premarket submission requirements for AI-enabled diagnostic features extend product release cycles by 12-18 months.
- Multi-Cloud Orchestration Complexity:Hospital IT departments lack operational maturity to manage workloads across AWS, Azure, and Google Cloud simultaneously.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Healthcare Cloud Picture Archiving and Communications System Market |
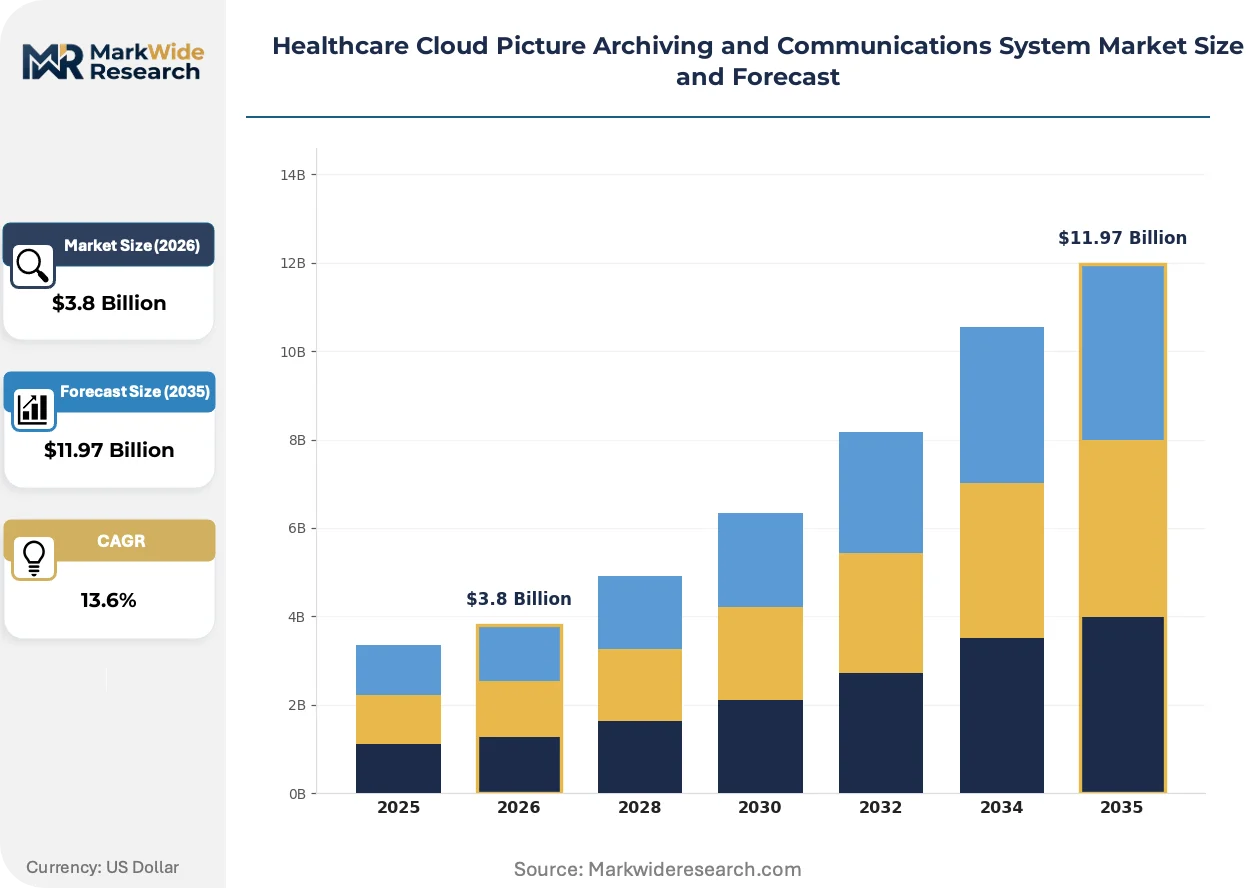
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $11.97 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software Solutions, Storage Systems, Viewer Applications, Analytics Tools Delivery Model: Public Cloud, Private Cloud, Hybrid Cloud, On-Premises End User: Hospitals, Imaging Centers, Research Institutions, Clinics Deployment: Remote Access, Mobile Access, Integrated Systems, Standalone Solutions |
| Companies Covered | Konica Minolta Healthcare Americas, NADICO, Ambra Health, Koninklijke Philips, UltraLinq, VEPRO AG, Telemis, RamSoft, INFINITT North America, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Healthcare Cloud Picture Archiving and Communications System Market Strategic Shifts & Innovations
Cloud-native containerization is restructuring how medical imaging workloads deploy, enabling elastic scaling that matches radiology study volume fluctuations. This architectural shift is compressing hardware refresh cycles and redirecting vendor R&D toward software-defined infrastructure.
Edge computing nodes positioned within hospital networks are electrifying image preprocessing workflows by enabling local AI inference before cloud transmission. Radiology departments at US academic medical centers are deploying these nodes to reduce latency for emergency stroke and trauma protocols. The technology is electrifying competitive positioning for vendors that bundle edge hardware with subscription licensing.
FDA guidance on predetermined change control plans for machine learning-enabled devices is tightening validation requirements for diagnostic algorithm updates. Device manufacturers must now submit protocols for anticipated modifications before initial clearance, extending regulatory timelines. Radiology AI vendors are responding by freezing model architectures longer and shifting investment toward post-market surveillance infrastructure.
Subscription bundling that unifies storage, viewer licenses, and AI tool access is displacing perpetual licensing across US hospital procurement departments. Chief information officers are consolidating vendor relationships to simplify contract management and reduce integration overhead. This pattern is most visible in large integrated delivery networks across the Midwest and Southeast United States.
Healthcare Cloud Picture Archiving and Communications System Market Segmentation
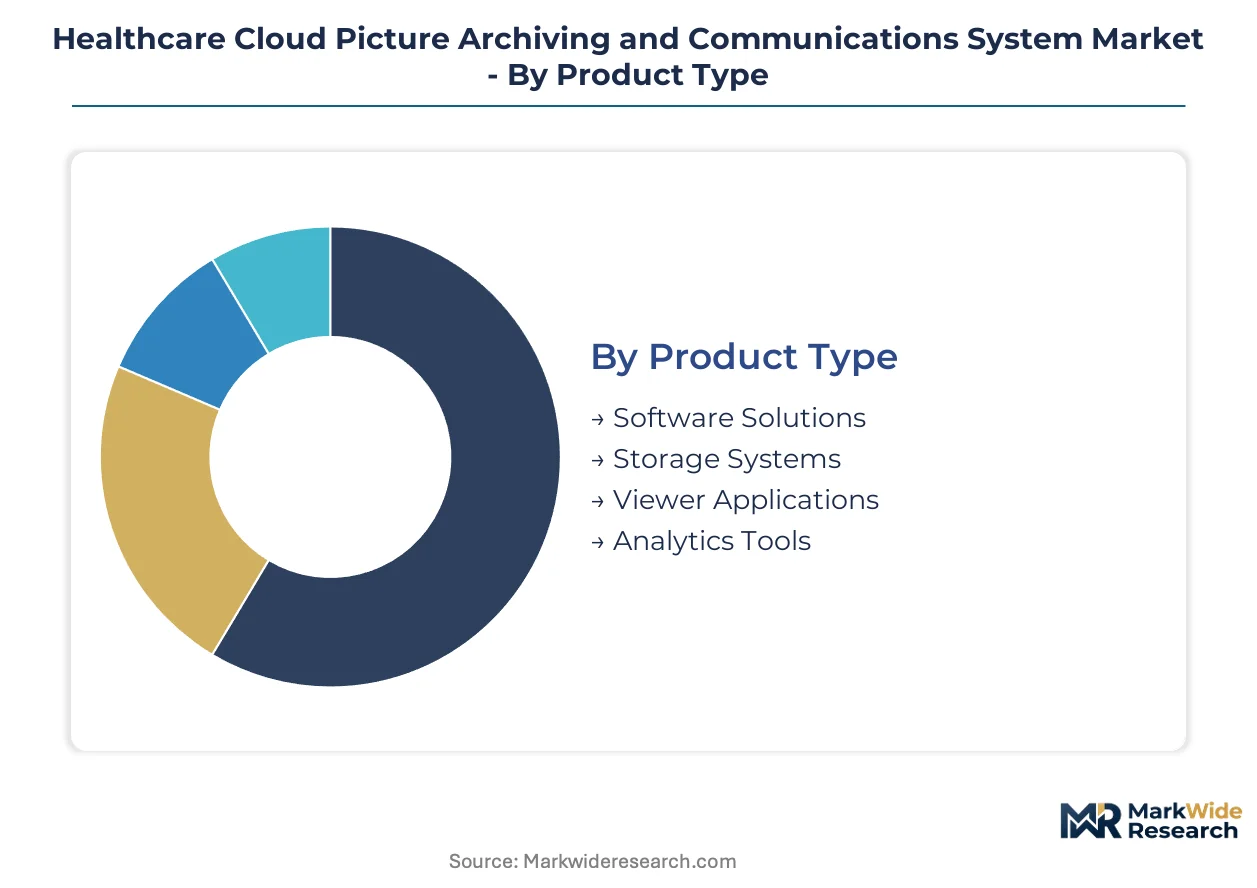
Healthcare Cloud PACS procurement decisions cascade through multiple technical and commercial dimensions. Hospital IT departments evaluate product architecture, delivery economics, and deployment flexibility in sequence before vendor selection.
Product Type:
Purchase committees prioritize margin contribution and integration complexity when allocating budgets across software and hardware categories.
- Software Solutions:Native platforms embed DICOM routing engines and HL7 FHIR interfaces for interoperability compliance. US academic medical centers concentrate procurement here to unify cardiology and radiology workflows under single vendor contracts.
- Storage Systems:Object storage architectures tier hot and cold imaging data across flash and disk media. Large integrated delivery networks in the Midwest prioritize petabyte-scale capacity with sub-second retrieval for emergency departments.
- Viewer Applications:Zero-footprint web viewers enable diagnostic interpretation without local software installation.
- Analytics Tools:Embedded dashboards track radiologist productivity and equipment utilization rates.
Software Solutions leads on scale; Analytics Tools leads on momentum.
Delivery Model:
Capital availability and data sovereignty requirements shape infrastructure deployment preferences across hospital networks.
- Hybrid Cloud:Workload orchestration splits DICOM archives between on-premise storage and public cloud burst capacity. Mid-sized hospital networks across the Southeast United States adopt this model to preserve data control while containing capital expenditure.
- Public Cloud:Fully managed SaaS platforms eliminate hardware ownership and shift spending to operational budgets. Imaging center chains expanding through acquisition favor this approach for rapid site onboarding.
- Private Cloud:Dedicated infrastructure meets HIPAA security rule requirements for organizations with strict data residency policies.
- On-Premises:Legacy installations persist where regulatory uncertainty delays cloud migration approvals.
Hybrid Cloud dominates current deployment value; Public Cloud is climbing the fastest as outpatient consolidation accelerates.
End User:
Organizational scale determines feature requirements and pricing tolerance across buyer categories.
- Hospitals:Enterprise imaging consolidation mandates drive procurement of multi-department platforms spanning radiology, cardiology, and pathology. Large health systems in California and Texas anchor category volume through multi-year subscription commitments.
- Imaging Centers:Ambulatory networks centralize storage to enable teleradiology coverage across distributed sites. Outpatient consolidation in Florida and Arizona is expanding this segment most quickly.
- Research Institutions:Academic medical centers require de-identification pipelines and multi-site data federation for clinical trial imaging.
- Clinics:Small practices prioritize mobile access and simplified viewer licensing over advanced analytics capabilities.
Hospitals anchor absolute spending; Imaging Centers show the steepest expansion trajectory.
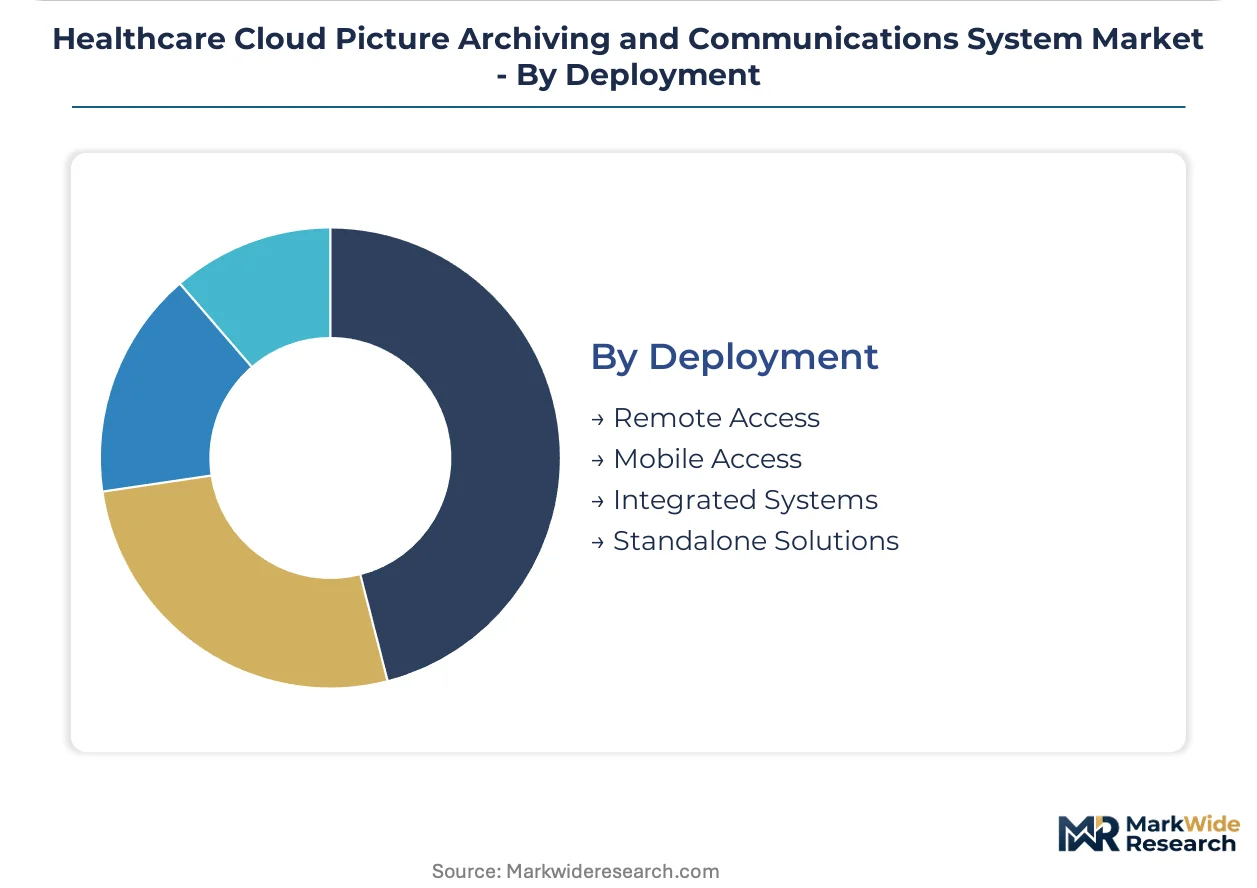
Deployment:
Access modality selection reflects clinical workflow patterns and security risk tolerance.
- Integrated Systems:Native EHR embedding through APIs eliminates context switching for ordering physicians. Epic and Cerner installations across US hospital networks concentrate demand for this architecture.
- Remote Access:VPN-secured connections enable radiologists to interpret studies from home or satellite offices. Post-pandemic workforce flexibility policies sustain category momentum.
- Mobile Access:Tablet-optimized viewers support emergency consultation and surgical planning.
- Standalone Solutions:Disconnected deployments persist in correctional health and military field settings with air-gapped security requirements.
Integrated Systems commands the largest installed base; Mobile Access is gaining share fastest among emergency medicine departments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cloud-based medical imaging infrastructure originated in the United States during the early 2010s, with academic medical centers pioneering DICOM-to-cloud migration to replace film-based radiology workflows. This foundational deployment established the architectural templates now diffusing across hospital networks worldwide.
United States
Large integrated delivery networks in Texas and California are consolidating enterprise imaging platforms across radiology, cardiology, and pathology departments. HIPAA security rule enforcement and FDA software-as-medical-device guidance are accelerating cybersecurity investment as qualification criteria harden. The Mayo Clinic cluster in Rochester, Minnesota anchors multi-site teleradiology deployment.
Germany
University hospitals in Bavaria and North Rhine-Westphalia are adopting hybrid cloud architectures to preserve data sovereignty while enabling burst capacity for emergency stroke protocols. The European Medical Device Regulation and GDPR localization requirements create certification burdens for multinational suppliers. The Berlin-Brandenburg health region concentrates vendor qualification activity.
United Kingdom
NHS trusts across London and the Midlands are centralizing image storage to enable radiologist workforce flexibility and reduce capital expenditure. The UK Medicines and Healthcare products Regulatory Agency enforces software-as-medical-device standards parallel to FDA frameworks. The Greater Manchester health system exemplifies multi-site cloud PACS consolidation.
Japan
Metropolitan hospital networks in Tokyo and Osaka are deploying edge computing nodes for local AI inference before cloud transmission. The Pharmaceuticals and Medical Devices Agency tightens validation requirements for machine learning-enabled diagnostic updates. The Nagoya medical device cluster supports regional PACS integration engineering.
India
Corporate hospital chains in Maharashtra and Karnataka are leapfrogging legacy infrastructure with public cloud-native deployments to support rapid geographic expansion. The Central Drugs Standard Control Organization is developing software medical device guidance aligned with international standards. The Bangalore health-tech corridor concentrates diagnostic AI development partnerships.
Healthcare Cloud Picture Archiving and Communications System Market Key Industry Players
Premium-margin players sit above commodity-margin players across software solution bundling and AI integration depth, with the market consolidating around three structural tiers. Diagnostic hardware incumbents anchor the top tier through installed base leverage, while API-first specialists compete on interoperability speed. Hybrid cloud orchestration capability and FDA premarket clearance velocity represent the dominant competitive moves reshaping vendor positioning.
Within the diagnostic hardware incumbent tier, Konica Minolta Healthcare Americas and Koninklijke Philips occupy positions defined by enterprise imaging platform breadth. Among API-first specialists, Ambra Health exemplifies the interoperability-native archetype. These three companies represent the strategic poles—hardware-anchored consolidation versus cloud-native ecosystem openness—around which procurement decisions at US academic medical centers and European university hospitals increasingly organize.
| Leading Market Players |
|---|
| Konica Minolta Healthcare Americas |
| NADICO |
| Ambra Health |
| Koninklijke Philips |
| UltraLinq |
| VEPRO AG |
| Telemis |
| RamSoft |
| INFINITT North America |
| Others |
Cost & Logistics Intelligence
HIPAA security rule enforcement gates qualified supply access and premium-tier pricing power for cloud PACS vendors serving US hospital networks. Vendors lacking FedRAMP authorization or HITRUST certification face exclusion from enterprise procurement shortlists, compressing margins for non-compliant competitors while enabling certified suppliers to sustain subscription premiums.
Pricing Analysis
Subscription bundling across storage, viewer licenses, and AI tool access stratifies pricing across premium, standard, and economy tiers. Price differentiation rests on FDA software-as-medical-device clearance status and HL7 FHIR interoperability certification depth. Cost compression in the standard tier intensifies because mid-sized hospital networks negotiate volume discounts across multi-site deployments. Imaging centers exhibit highest price sensitivity due to capital constraints, while academic medical centers prioritize premium tiers for enterprise imaging consolidation.
Supply Chain Analysis
Regional distribution centers in the United States, Germany, and Japan anchor hub-and-spoke fulfillment patterns for edge computing hardware bundled with cloud PACS subscriptions. Component sourcing draws from Taiwan for GPU accelerators, South Korea for flash storage arrays, and domestic US facilities for HIPAA-compliant server assembly. Single-source vulnerability concentrates in specialized DICOM-FHIR mapping chipsets. Distribution runs through value-added resellers with clinical workflow expertise and direct enterprise sales teams at major health systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in healthcare cloud PACS rests on AI-assisted diagnostic integration pulling software solution margins upward, offsetting storage commoditization pressure.
For Market Incumbents: Hedge against API-first specialists by embedding interoperability layers deeper into native platforms and acquiring edge computing hardware capabilities to bundle with subscription licensing. FDA premarket clearance velocity represents the priority defensive investment. Channel control through diagnostic hardware installed base leverage sustains pricing power against cloud-native entrants. For New Entrants and Emerging Players: Radiology group purchasing organizations offer the most penetrable channel partnership type for market entry. White-space targets concentrate in outpatient imaging center chains across Florida and Arizona undergoing consolidation. De-identification pipeline specialization for research institutions provides a defensible beachhead before expanding into clinical workflows. For Investors and Strategic Acquirers: Roll-up economics work for regional PACS specialists with established hospital system relationships because enterprise imaging consolidation mandates favor vendors with proven multi-site deployment track records. Long-term viability frames around FDA software-as-medical-device clearance portfolios as competitive moats. The signal to watch is ONC interoperability mandate compliance timelines as inflection indicators for vendor qualification windows.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Software-as-Medical-Device Submission | Clearance enables embedded AI diagnostic tools that command premium subscription tiers. |
| Hospital System Partnership | Multi-year enterprise imaging contracts with Texas and California health systems anchor recurring revenue. |
| HL7 FHIR Platform Integration | Native interoperability protocols satisfy ONC mandates and maintain federal reimbursement eligibility. |
| Edge Computing Hardware Bundling | Local AI inference nodes reduce latency for emergency stroke protocols at academic medical centers. |
| Reimbursement Strategy Development | Radiology AI coding alignment with CMS pathways accelerates clinical adoption and utilization. |
Research Approach
Multiple input streams — hospital procurement database analysis, GPO contract review, CMS Medicare reimbursement data, and hyperscaler healthcare vertical disclosures — were reconciled across primary interviews with hospital CIOs, radiology department chairs, biomedical engineers, and GPO contracts managers. Secondary validation drew from FDA 510(k) filings, ONC interoperability certification records, hospital capital expenditure surveys, and trade association procurement trend reports. Bottom-up site-level deployment estimates and top-down vendor revenue analysis were triangulated to anchor market sizing.
Historical growth trajectories were cross-referenced against expert panel input to construct projection frameworks across the analysis window. Segmentation dimensions modeled include delivery model, end-user organization scale, deployment architecture, and regional regulatory cluster. CAGRs were derived from weighted average growth assumptions calibrated to interoperability mandate compliance deadlines and outpatient consolidation velocity. AI integration penetration curves and cybersecurity insurance cost trajectories informed scenario-weighted outcomes.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA software-as-medical-device guidance evolution and state-level patient data privacy law proliferation. Forecasts reflect documented assumptions around interoperability mandate enforcement timelines and hospital network consolidation pace. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Asia-Pacific Digital Radiology Market
Medical Imaging
Nuclear Magnetic Resonance Spectroscopy Market
Medical Imaging
Global 3D Laparoscopy Imaging Market
Medical Imaging
CT Guided Intervention Market
Medical Imaging
Brazil Digital Radiology Market
Medical Imaging
Imaging Agents Market
Medical Imaging
Spain Digital Radiology Market
Medical Imaging
AI-Assisted Digital Radiography Equipment Market
Medical Imaging
Global Contrast-Enhanced Ultrasound Market
Medical Imaging
PSMA-PET Imaging Market
Medical Imaging
India Magnetic Resonance Imaging Market
Medical Imaging
Spain Nuclear Imaging Market
Medical Imaging
Global Picture Archiving Communications System Market
Medical Imaging
Preclinical Brain Imaging Market
Medical Imaging
Specimen Radiography Systems Market
Medical Imaging
Cryo-Electron Microscopy Market