
 US Imaging Services Market | 2026-2036
US Imaging Services Market Size, Share, and Industry Trends Forecast 2026-2036
US Imaging Services Market Intelligence
Radiology group consolidation in the Southeast is shifting how independent practices compete for hospital contracts. RadNet leverages its coast-to-coast imaging center network to sustain volume density in metropolitan markets. Sonic Healthcare anchors its position through pathology-imaging integration across multi-site health systems. Akumin specializes in outpatient musculoskeletal diagnostics, occupying a narrow but defensible service niche.
US imaging services encompass the acquisition, interpretation, and reporting of diagnostic images using ionizing radiation, magnetic resonance, acoustic energy, or radiopharmaceutical tracers, with spatial resolution thresholds ranging from sub-millimeter CT to whole-body PET sensitivity. These services enable disease detection, treatment planning, and therapeutic monitoring across acute and ambulatory care settings. MRI and CT scan modalities command the deepest margin pools due to capital intensity and specialized staffing requirements. Digital imaging technology leads in replacement velocity as legacy analog systems face obsolescence. Oncology applications generate the most complex read volumes, driving demand for subspecialized radiologist labor.
FDA oversight of device 510(k) clearances and CMS reimbursement coding under the Physician Fee Schedule shape capital deployment and service line expansion decisions. HIPAA security rules and state-level certificate-of-need regulations constrain network configuration and patient data exchange architectures. Stakeholders must monitor how artificial intelligence diagnostic algorithms navigate FDA software-as-medical-device pathways and reshape radiologist workflow economics.
Market Dynamics
Hospital systems are consolidating outpatient imaging networks while the FDA's 21st Century Cures Act provisions force digital interoperability upgrades, compressing margins for independent radiology groups locked into legacy PACS architectures.
Growth Catalysts
- Texas population surge:Medicare enrollment growth in Dallas-Fort Worth and Houston corridors outpaces national benchmarks, pulling imaging volume into ambulatory settings.
- AI-enabled workflow tools:FDA-cleared software-as-medical-device algorithms reduce radiologist read times for chest X-ray and mammography screening programs.
- Certificate-of-need liberalization:Florida and Arizona state legislatures have relaxed CON restrictions on outpatient MRI and CT capacity expansion.
Market Restraints
- Helium supply concentration:MRI magnet cooling depends on Qatar and Russia helium exports subject to export quota volatility.
- Radiologist labor scarcity:Fellowship-trained neuroradiologists and interventional radiologists cluster in coastal metropolitan markets, leaving rural markets underserved.
- CMS reimbursement compression:Physician Fee Schedule cuts to technical component payments constrain capital recovery timelines for CT and PET-CT systems.
Strategic Opportunities
- Interoperability mandates:CMS Promoting Interoperability programs incentivize cloud-based image exchange platforms connecting hospital and outpatient settings.
- Musculoskeletal subspecialization:Sports medicine and orthopedic group practices in Sun Belt retirement corridors seek dedicated MRI capacity for joint and spine diagnostics.
- Teleradiology network expansion:Night-hawk coverage models allow rural hospitals to access subspecialized reads without on-site radiologist employment.
Industry Challenges
- PACS migration complexity:Legacy DICOM archive systems resist seamless integration with cloud-native vendor-neutral archives, forcing costly data normalization projects.
- AI validation bottlenecks:FDA 510(k) clearance pathways for diagnostic algorithms require extensive clinical validation cohorts that stretch development timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Imaging Services Market |
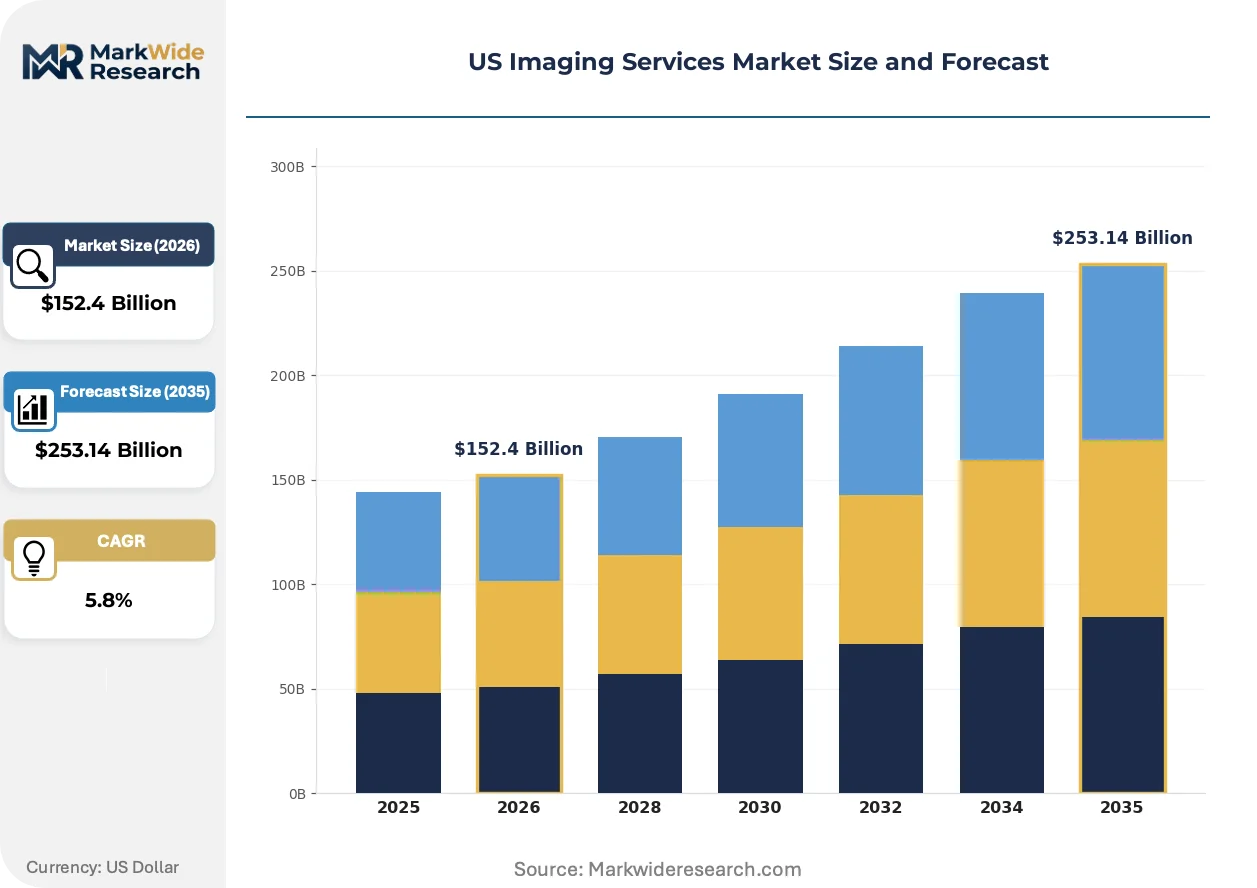
| Market Size in 2026 | $152.4 Billion |
| Market Size in 2035 | $253.14 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: X-ray, MRI, Ultrasound, CT Scan End User: Hospitals, Clinics, Diagnostic Centers, Research Facilities Technology: Digital Imaging, Analog Imaging, Hybrid Imaging, 3D Imaging Application: Oncology, Neurology, Cardiology, Orthopedics |
| Companies Covered | RadNet, Inc., Akumin, Inc., Rayus Radiology, Sonic Healthcare, Alliance Medical, Dignity Health, Novant Health, Inhealth Group, Simonmed Imaging, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Imaging Services Market Strategic Shifts & Innovations
Digital imaging infrastructure is undergoing forced modernization as analog systems face obsolescence and artificial intelligence tools reshape radiologist workflow economics across outpatient and acute care settings.
Photon-counting CT detector technology is electrifying cardiac and pulmonary imaging by delivering spectral resolution at lower radiation dose. Academic medical centers in Boston and Cleveland are replacing energy-integrating detectors at accelerated replacement cycles. The technology is compressing the diagnostic yield per scan while extending hardware depreciation schedules.
FDA software-as-medical-device guidance is clarifying validation requirements for AI diagnostic algorithms while tightening post-market surveillance obligations. Radiology AI vendors must now demonstrate real-world performance monitoring protocols beyond initial 510(k) clearance. California and Massachusetts health systems are demanding algorithmic transparency documentation before procurement.
Hospital-employed radiologists now outnumber independent group practitioners in major metropolitan markets, reversing decades of private practice dominance. Health systems in Atlanta and Phoenix are acquiring community radiology groups to secure exclusive professional services agreements. The shift is most visible in Medicare Advantage-heavy markets where vertical integration controls referral leakage.
US Imaging Services Market Segmentation
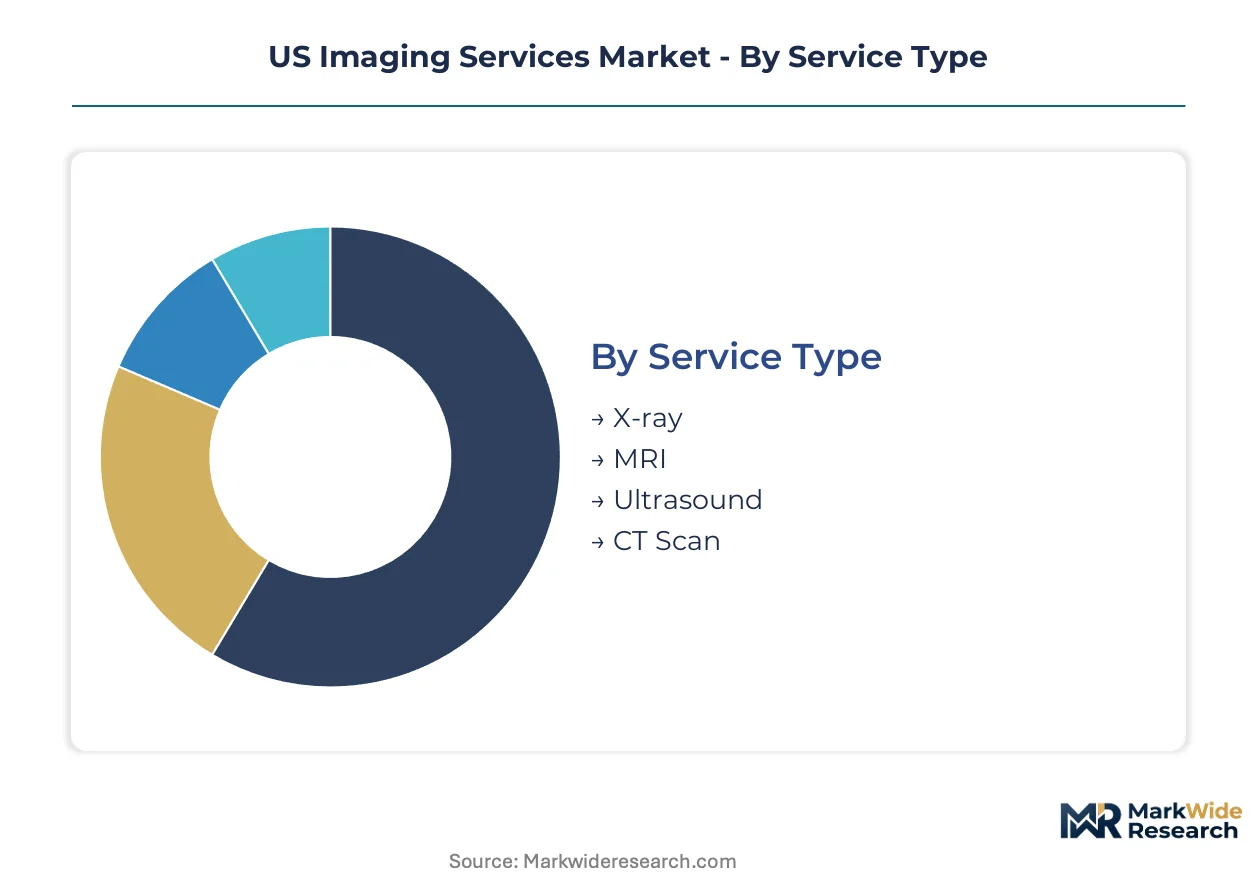
Imaging service segmentation reveals how capital intensity, reimbursement structures, and clinical workflow requirements partition demand across modalities and care settings. Service type and technology choices determine margin profiles, while end-user concentration shapes network configuration strategies.
Service Type:
Replacement cycles vary sharply across modalities, with digital X-ray systems turning over every 7-9 years while MRI platforms extend to 12-15 years given magnet longevity and shielding costs.
- X-ray:The foundational modality employs ionizing radiation with detector sensitivity measured in detective quantum efficiency. Volume concentrates in orthopedic urgent care centers across Texas and Florida where sports injury and aging-related fracture demand surge. CMS technical component reimbursement compression is accelerating consolidation among independent X-ray operators.
- MRI:Magnetic resonance imaging exploits nuclear magnetic resonance in hydrogen atoms, requiring superconducting magnets cooled by liquid helium. Demand clusters in suburban Dallas-Fort Worth corridors where Medicare Advantage penetration drives outpatient joint and spine diagnostics. Helium supply volatility from Qatar and Russian export quotas is extending equipment lease terms.
- Ultrasound:Acoustic imaging using piezoelectric transducers enables real-time visualization without ionizing radiation.
- CT Scan:Computed tomography reconstructs cross-sectional images through rotating X-ray source-detector arrays.
X-ray sits at the top of the volume ranking, with MRI climbing the fastest.
End User:
Customer concentration patterns reflect how vertical integration and certificate-of-need regulations fragment procurement authority across care settings.
- Hospitals:Acute care systems maintain captive imaging departments with 24/7 interventional capabilities. Demand concentrates in Phoenix and Atlanta health systems acquiring community radiology groups to secure professional services agreements. Medicare Advantage risk contracts are forcing capital deployment into outpatient satellites.
- Diagnostic Centers:Freestanding facilities operate outside hospital cost structures with dedicated throughput optimization. Volume clusters in Sun Belt retirement corridors where musculoskeletal and cardiovascular screening demand outpaces hospital capacity. Florida CON liberalization is permitting greenfield MRI and CT expansion.
- Clinics:Physician office-based imaging serves point-of-care diagnostics with limited modality range.
- Research Facilities:Academic medical centers deploy imaging for clinical trial endpoints and biomarker validation.
Hospitals command the deepest revenue pool, with diagnostic centers expanding most quickly.
Technology:
Technology tiering separates replacement-velocity decisions, with digital platforms commanding premium pricing against legacy analog installations facing obsolescence pressure.
- Digital Imaging:Detector arrays with direct or indirect conversion eliminate chemical processing, enabling PACS integration and AI algorithm deployment. Demand concentrates in hospital systems modernizing under CMS Promoting Interoperability mandates. Massachusetts and California health systems now require algorithmic transparency documentation before procurement.
- 3D Imaging:Volumetric reconstruction from multi-detector CT or digital breast tomosynthesis creates isotropic voxel datasets. Volume clusters in academic medical centers replacing energy-integrating detectors with photon-counting CT for cardiac and pulmonary applications. Spectral resolution at reduced radiation dose is compressing diagnostic yield per scan.
- Hybrid Imaging:PET-CT and PET-MRI fusion combines functional and anatomical data in single acquisition sessions.
- Analog Imaging:Film-based radiography persists in cost-constrained rural settings with limited IT infrastructure.
Digital imaging dominates installed base value, with 3D imaging gaining share fastest.
Application:
Clinical application segmentation tracks subspecialist labor scarcity and reimbursement complexity, with oncology and neurology commanding premium reads.
- Oncology:Staging and response assessment drives PET-CT and multiparametric MRI utilization with complex read protocols. Demand concentrates in Cleveland and Boston academic centers deploying photon-counting CT for treatment planning. AI validation bottlenecks through FDA 510(k) pathways are stretching algorithm development timelines.
- Orthopedics:Joint replacement planning and sports medicine trauma requires high-resolution musculoskeletal MRI. Volume clusters in Arizona and Florida retirement communities where active aging demographics sustain outpatient capacity expansion. Dedicated MRI for orthopedic group practices is creating defensible service niches.
- Cardiology:Coronary CT angiography and cardiac MRI assess structural and ischemic disease.
- Neurology:Fellowship-trained neuroradiologist reads for stroke, tumor, and degenerative conditions face coastal metropolitan clustering.
Oncology sits at the top of the complexity ranking, with orthopedics climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Certificate-of-need liberalization in Florida and Texas is accelerating outpatient imaging capacity expansion, while CMS reimbursement compression in California and New York is forcing hospital systems toward Medicare Advantage risk contracts that demand vertical control over referral networks.
Texas
Medicare enrollment growth in Dallas-Fort Worth and Houston corridors outpaces national benchmarks, pulling imaging volume into ambulatory settings. State CON regulations remain permissive for outpatient MRI and CT expansion in suburban corridors. Helium supply constraints from Qatar export quotas are extending equipment lease terms at Texas Medical Center facilities.
Florida
Retirement demographics sustain musculoskeletal and cardiovascular screening demand across Tampa and Orlando metropolitan areas. State legislature relaxed CON restrictions on outpatient imaging capacity in 2023, permitting greenfield diagnostic center expansion. Sonic Healthcare anchors pathology-imaging integration across multi-site health systems in South Florida.
California
Health systems in Los Angeles and San Francisco now require algorithmic transparency documentation before AI diagnostic procurement under state-level procurement policies. FDA 510(k) clearance pathways for software-as-medical-device algorithms face extended validation timelines at Stanford and UCSF academic centers. Photon-counting CT replacement cycles are accelerating at Cedars-Sinai and UCLA Medical Center.
Arizona
Sun Belt retirement corridors drive dedicated MRI capacity for joint and spine diagnostics in Phoenix and Scottsdale markets. State CON liberalization permits independent radiology groups to compete for hospital professional services agreements. Akumin specializes in outpatient musculoskeletal diagnostics, occupying narrow but defensible service niches in suburban Phoenix.
Georgia
Hospital-employed radiologists now outnumber independent group practitioners in Atlanta metropolitan markets, reversing decades of private practice dominance. Health systems are acquiring community radiology groups to secure exclusive professional services agreements under Medicare Advantage risk contracts. Night-hawk teleradiology coverage models allow rural hospitals in Macon and Augusta corridors to access subspecialized neuroradiologist reads.
US Imaging Services Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue AI-enabled workflow specialization and cloud-native PACS architectures. Hospital systems consolidating outpatient networks favor vendors with coast-to-coast density and interoperability certification. Three archetypes dominate: national imaging center chains with metropolitan volume concentration, health system-employed radiology groups with captive referral control, and subspecialty-focused outpatient operators in retirement corridors. Competitive moves center on horizontal consolidation of community radiology practices and backward integration into teleradiology night-hawk coverage networks.
Among national imaging center operators, RadNet leverages its coast-to-coast network to sustain volume density in metropolitan markets, representing the scale-driven consolidation archetype. Sonic Healthcare anchors its position through pathology-imaging integration across multi-site health systems, exemplifying the clinical laboratory convergence model. Akumin occupies a narrow but defensible position in outpatient musculoskeletal diagnostics, sitting within the subspecialty-focused tier targeting Sun Belt retirement demographics.
| Leading Market Players |
|---|
| RadNet, Inc. |
| Akumin, Inc. |
| Rayus Radiology |
| Sonic Healthcare |
| Alliance Medical |
| Dignity Health |
| Novant Health |
| Inhealth Group |
| Simonmed Imaging |
| Others |
Cost & Logistics Intelligence
Captive helium sourcing arrangements anchor MRI equipment financing structures while simultaneously determining regional pricing power for outpatient imaging networks. Hospital systems with long-term magnet cooling contracts through Qatar and Russian suppliers command lease-rate advantages that independent diagnostic centers cannot match, compressing margins for non-integrated operators.
Pricing Analysis
Direct-to-hospital professional services agreements carry zero distributor markup, while independent diagnostic centers absorb 15-25% revenue leakage through teleradiology night-hawk coverage fees. Three-tier pricing structure across premium subspecialty reads, standard diagnostic interpretations, and economy bulk-screening contracts separates neuroradiology and interventional procedures from routine chest X-ray programs. Cost compression in the technical component tier is intensifying because CMS Physician Fee Schedule reductions outpace equipment depreciation schedules. Medicare Advantage risk-contract health systems exhibit lowest price sensitivity due to captive referral control, while cash-pay orthopedic clinics in Sun Belt markets face highest elasticity.
Supply Chain Analysis
Regional distribution centers for liquid helium concentrate in Texas and Louisiana hub-and-spoke patterns serving the Dallas-Fort Worth and Houston medical corridors. Superconducting magnet manufacturing draws from Japan, Germany, and the United States for precision cryogenic components, while gadolinium-based contrast agents source from Ireland, China, and India pharmaceutical plants. Single-source vulnerability in Qatar helium export quotas creates equipment deployment delays extending MRI installation timelines. Distribution runs through hospital system-owned captive logistics networks for high-value modalities, with third-party medical device distributors handling X-ray and ultrasound point-of-care systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
US imaging services constitute a late-cycle quality story justified by Medicare Advantage penetration pulling demand toward subspecialized neuroradiology and interventional reads that command premium professional fees.
For Market Incumbents: To counter radiologist labor scarcity in coastal metropolitan markets, RadNet and Sonic Healthcare should deepen backward integration into fellowship training pipeline partnerships while deploying AI-enabled workflow tools to compress read times for screening mammography and chest X-ray programs. For New Entrants and Emerging Players: Begin with teleradiology night-hawk coverage models targeting rural Georgia and Arizona hospitals underserved by neuroradiologist clustering, then expand into musculoskeletal subspecialization for Sun Belt orthopedic group practices seeking dedicated MRI capacity. For Investors and Strategic Acquirers: Roll-up economics work for regional diagnostic center chains because certificate-of-need liberalization in Florida and Arizona permits greenfield expansion without regulatory delay. Target platforms with Medicare Advantage risk-contract density and monitor FDA 510(k) clearance velocity for AI diagnostic algorithms as inflection indicator for radiologist workflow economics.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Exclusive professional services agreements with Phoenix and Atlanta health systems lock in captive referral volume under Medicare Advantage risk contracts. |
| AI Software Companion Development | FDA-cleared algorithms for mammography and chest X-ray screening reduce radiologist read times and expand night-hawk coverage capacity. |
| Reimbursement Strategy | Technical component coding optimization under CMS Physician Fee Schedule preserves capital recovery timelines for CT and PET-CT systems. |
| Backward Integration into Helium Supply | Long-term Qatar and Russian export contracts secure MRI magnet cooling continuity and lease-rate advantages over independent competitors. |
| Geographic Expansion | Greenfield MRI and CT deployment in Florida CON-liberalized corridors captures musculoskeletal demand from Tampa and Orlando retirement demographics. |
Research Approach
Multiple input streams — radiology group practice administrators, hospital purchasing committee members, biomedical equipment engineers, and GPO contracts managers — were reconciled against CMS Medicare claims data, FDA 510(k) device clearance databases, state certificate-of-need filings, and hospital procurement records. Bottom-up imaging volume estimates by modality and geography were triangulated with top-down health system capital expenditure disclosures and equipment manufacturer shipment reports.
Historical utilization trends were cross-referenced against expert panel assessments of AI adoption velocity and helium supply volatility. Segmentation dimensions modeled encompass service type, end-user concentration, technology tier, and clinical application complexity across the projection horizon. CAGRs were derived from regression analysis of Medicare enrollment growth, population aging patterns, and replacement cycle dynamics for digital imaging platforms.
Caveats apply where FDA software-as-medical-device guidance changes, CMS reimbursement rulemaking, or Qatar helium export quota disruptions could materially shift the outlook. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Magnetic Resonance Imaging Market
Medical Imaging
United States Mammography Market
Medical Imaging
Spinal Imaging Market
Medical Imaging
Spain Nuclear Imaging Market
Medical Imaging
3D Medical and Surgical Imaging Platform Market
Medical Imaging
Fluoroscopy and Mobile C-Arms Market
Medical Imaging
Canada Nuclear Imaging Market
Medical Imaging
Europe Medical Imaging Market
Medical Imaging
Radio-Fluoroscopy Systems Market
Medical Imaging
AI-Assisted Digital Radiography Equipment Market
Medical Imaging
Asia-Pacific Intraoperative Imaging Market
Medical Imaging
France Diagnostic Imaging Equipment Market
Medical Imaging
Global Technetium-99M Market
Medical Imaging
Enterprise Medical Image Viewers Market
Medical Imaging
Digital Pathology Market
Medical Imaging
Brazil Digital X-Ray Market