
 North America Contract Research Organization Market | 2026-2036
North America Contract Research Organization Market Size, Share, and Industry Trends Forecast 2026-2036
North America Contract Research Organization Market Insights
ISO 14155 certification for clinical investigation of medical devices is bifurcating the vendor pool into audit-ready incumbents and excluded challengers. Fortrea Inc leverages its spin-off infrastructure to sustain global site networks across complex therapeutic areas. Charles River Laboratories anchors its position through laboratory services integration that extends downstream into clinical execution. IQVIA Inc dominates real-world evidence generation, competing on data asset scale that smaller rivals cannot replicate.
A Contract Research Organization delivers outsourced pharmaceutical, biotechnological, and medical device development services spanning preclinical through post-market surveillance, operating under protocols governed by ICH-GCP E6(R2) guidelines for trial conduct, data integrity, and subject protection. Clinical Trials services capture the largest revenue share as sponsors push novel modalities through accelerated approval pathways, while Pharmacovigilance grows fastest driven by FDA's strengthened post-market safety mandates under FDAAA. Electronic Data Capture technology underpins margin pools as platforms consolidate eCRF, ePRO, and risk-based monitoring into unified subscriptions that lock in multi-year client relationships.
FDA's ICH E6(R3) modernization and EPA Good Laboratory Practice standards shape operational compliance costs across preclinical and clinical phases, forcing CROs to retool quality management systems ahead of enforcement timelines. Health Canada's ICH-aligned Clinical Trial Framework creates parallel certification demands for cross-border studies. Stakeholders must monitor FDA's draft guidance on artificial intelligence in drug development as algorithm-enabled trial design threatens to displace traditional site selection and patient recruitment economics.
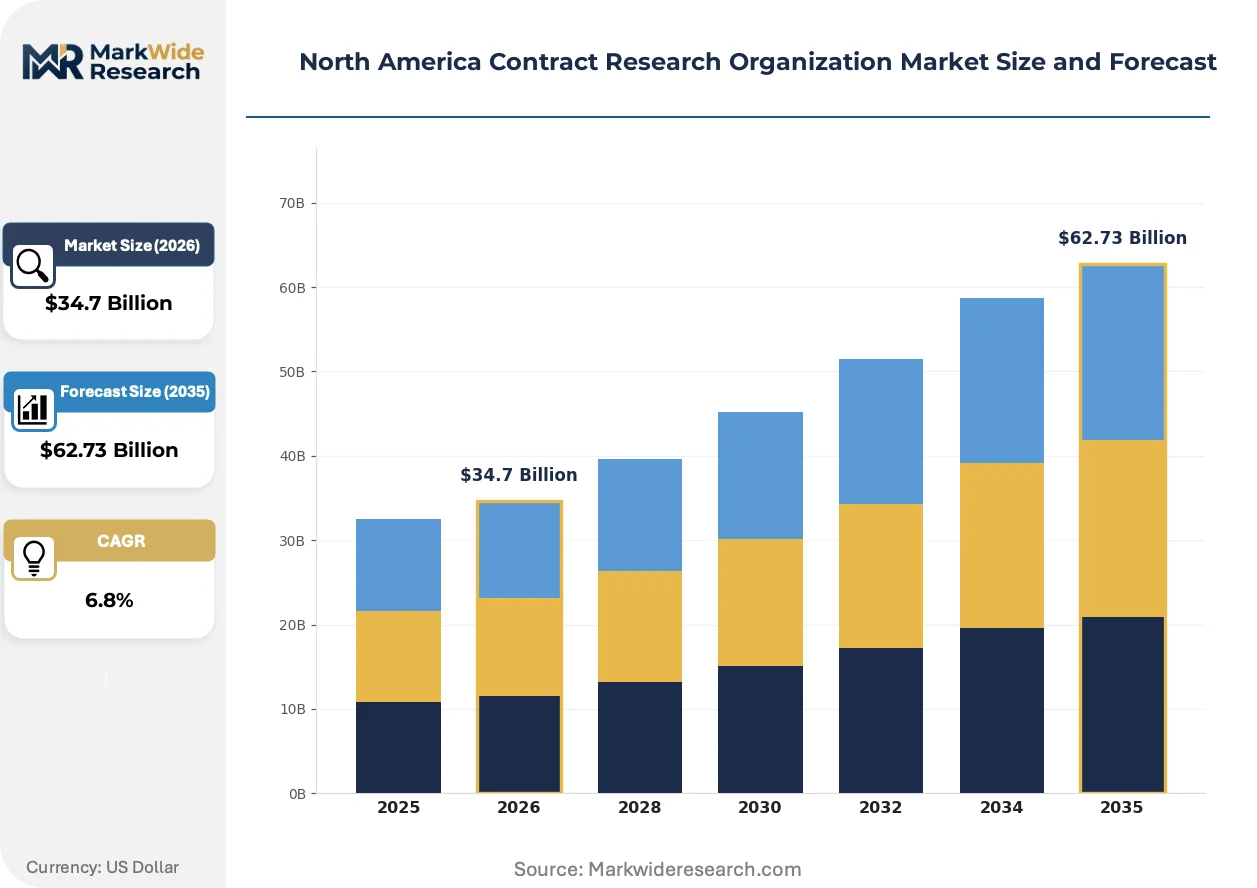
Market Dynamics
FDA's ICH E6(R3) modernization is compressing quality management system upgrade cycles across North American CROs, forcing simultaneous retooling of clinical monitoring infrastructure and data governance protocols ahead of enforcement timelines.
Growth Catalysts
- Oncology trial complexity:Biopharmaceutical sponsors now outsource Phase III immuno-oncology studies requiring specialized site networks and biomarker integration capabilities.
- FDAAA post-market mandates:FDA's strengthened pharmacovigilance requirements are expanding safety surveillance outsourcing volumes beyond clinical trial phases.
- Electronic Data Capture consolidation:Unified eCRF-ePRO-risk-based monitoring platforms are locking sponsors into multi-year subscription relationships.
Market Restraints
- Specialized talent scarcity:Clinical data scientists and regulatory biostatisticians command premium compensation in Boston-Cambridge and New Jersey corridor markets.
- ISO 14155 certification bifurcation:Medical device CROs without audit-ready quality systems face exclusion from sponsor vendor pools.
- Site concentration risk:Northeast United States site density creates geographic vulnerability to regional regulatory inspection backlogs.
Strategic Opportunities
- Decentralized trial technology:Direct-to-patient models and remote monitoring platforms open site-agnostic patient recruitment across underserved U.S. regions.
- Real-world evidence services:FDA's draft guidance on AI-enabled drug development creates demand for algorithmic trial design and synthetic control arm construction.
- Cross-border Canadian studies:Health Canada's ICH-aligned Clinical Trial Framework offers parallel certification pathways for U.S. sponsors seeking regulatory diversity.
Industry Challenges
- ICH E6(R3) implementation timelines:CROs must retrain monitoring staff and rebuild SOP libraries while maintaining ongoing trial compliance.
- Legacy EDC integration friction:Sponsor-mandated platform migrations disrupt established data workflows and require expensive middleware development.
- Competing quality system standards:Simultaneous FDA, EPA GLP, and ISO 14155 audits strain QA resource allocation across preclinical and clinical divisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Contract Research Organization Market |
| Market Size in 2026 | $34.7 Billion |
| Market Size in 2035 | $62.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Clinical Trials, Pharmacovigilance, Data Management, Regulatory Affairs End User: Pharmaceutical Companies, Biotechnology Firms, Medical Device Manufacturers, Academic Institutions Technology: Electronic Data Capture, Clinical Trial Management Systems, Lab Automation, Project Management Tools Application: Oncology, Cardiovascular, Neurology, Infectious Diseases |
| Companies Covered | Fortrea Inc, Parexel International, ICON plc, Thermo Fisher Scientific Inc, Syneos Health, Charles River Laboratories, Medpace Holdings, Inotiv, IQVIA Inc, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Contract Research Organization Market Trends and Innovations
Algorithmic trial design and decentralized execution models are displacing traditional site-centric recruitment economics, compressing study timelines while redistributing capability requirements across vendor ecosystems.
Artificial intelligence-enabled patient matching is displacing conventional site selection and manual recruitment screening. Mid-tier biopharmaceutical sponsors are adopting these platforms fastest, driven by pressure to accelerate enrollment in competitive oncology indications. The technology is displacing geographic proximity as the primary vendor selection criterion, enabling sponsors to engage specialized CROs regardless of physical site presence.
FDA's draft guidance on artificial intelligence in drug development is reshaping computational modeling requirements for regulatory submissions. The agency's risk-based framework for algorithm validation is forcing CROs to build internal AI governance committees and model documentation protocols. Early-phase oncology and rare disease sponsors face the steepest compliance curve, as these therapeutic areas rely most heavily on synthetic control arms and predictive enrollment modeling.
Biopharmaceutical procurement teams are unbundling full-service CRO contracts into functional components—data management, monitoring, medical writing, and biostatistics—awarded to specialized vendors. Large sponsors in the Northeast corridor are leading this fragmentation, using competitive bidding to compress functional unit costs. The disintermediation is most visible in Phase I-II studies, where speed and flexibility outweigh single-accountability preferences.
North America Contract Research Organization Market Segmentation
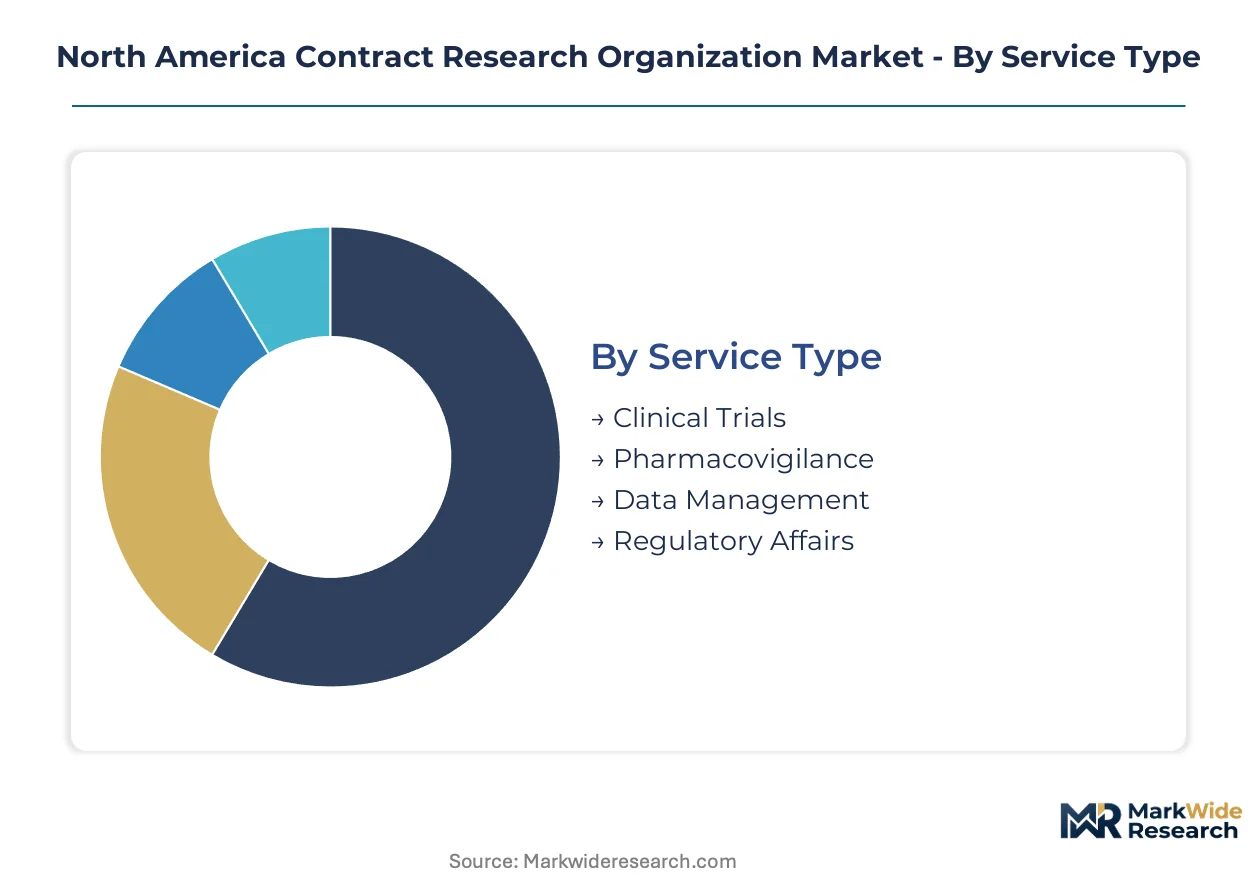
Service differentiation determines vendor selection in the North America Contract Research Organization Market. Sponsors unbundle contracts across functional specialties, creating distinct competitive arenas for clinical execution, safety surveillance, and regulatory navigation.
Service Type:
Domestic demand concentrates in clinical execution capabilities, while pharmacovigilance and data services increasingly serve cross-border sponsor portfolios from U.S. delivery centers.
- Clinical Trials:Phase III oncology studies requiring biomarker-integrated site networks anchor revenue concentration. Northeast corridor sponsors in Boston-Cambridge and New Jersey corridor clusters drive demand for complex therapeutic execution.
- Pharmacovigilance:Post-market safety surveillance expands under FDA's strengthened FDAAA mandates. U.S.-based delivery centers process adverse event reporting for global sponsor portfolios.
- Data Management:Electronic database build and statistical programming support trial execution across all phases.
- Regulatory Affairs:FDA submission preparation and Health Canada parallel filings guide cross-border market access strategies.
Clinical Trials commands the established base. The steepest expansion runs through Pharmacovigilance.
End User:
Customer scale dictates contract structure, with large pharmaceutical sponsors fragmenting procurement across specialized vendors while mid-tier biotechnology firms seek integrated partnerships.
- Pharmaceutical Companies:Top-tier sponsors unbundle full-service contracts into functional components awarded through competitive bidding. Procurement teams in the Northeast corridor lead this disintermediation.
- Biotechnology Firms:Venture-backed innovators prioritize speed and flexibility over single-accountability structures. Phase I-II study outsourcing concentrates among specialized execution vendors.
- Medical Device Manufacturers:ISO 14155 certification requirements bifurcate vendor pools into audit-ready incumbents and excluded challengers.
- Academic Institutions:Investigator-initiated trials generate sporadic demand for protocol development and regulatory navigation support.
Pharmaceutical Companies anchor contract volume. Biotechnology Firms are climbing the fastest.
Technology:
Platform consolidation locks sponsors into multi-year subscription relationships, with unified systems displacing point solutions across data capture and trial management functions.
- Electronic Data Capture:Unified eCRF-ePRO-risk-based monitoring platforms consolidate margin pools through subscription retention. EDC infrastructure underpins multi-year client lock-in across sponsor portfolios.
- Clinical Trial Management Systems:Site activation and patient enrollment tracking modules compress study timelines through workflow automation.
- Lab Automation:Preclinical bioanalytical services integrate downstream into clinical sample processing for Charles River Laboratories and comparable integrated vendors.
- Project Management Tools:Budget forecasting and milestone tracking capabilities support sponsor visibility across decentralized trial execution.
Electronic Data Capture holds the technology revenue base. Real-world evidence integration is gaining share fastest.
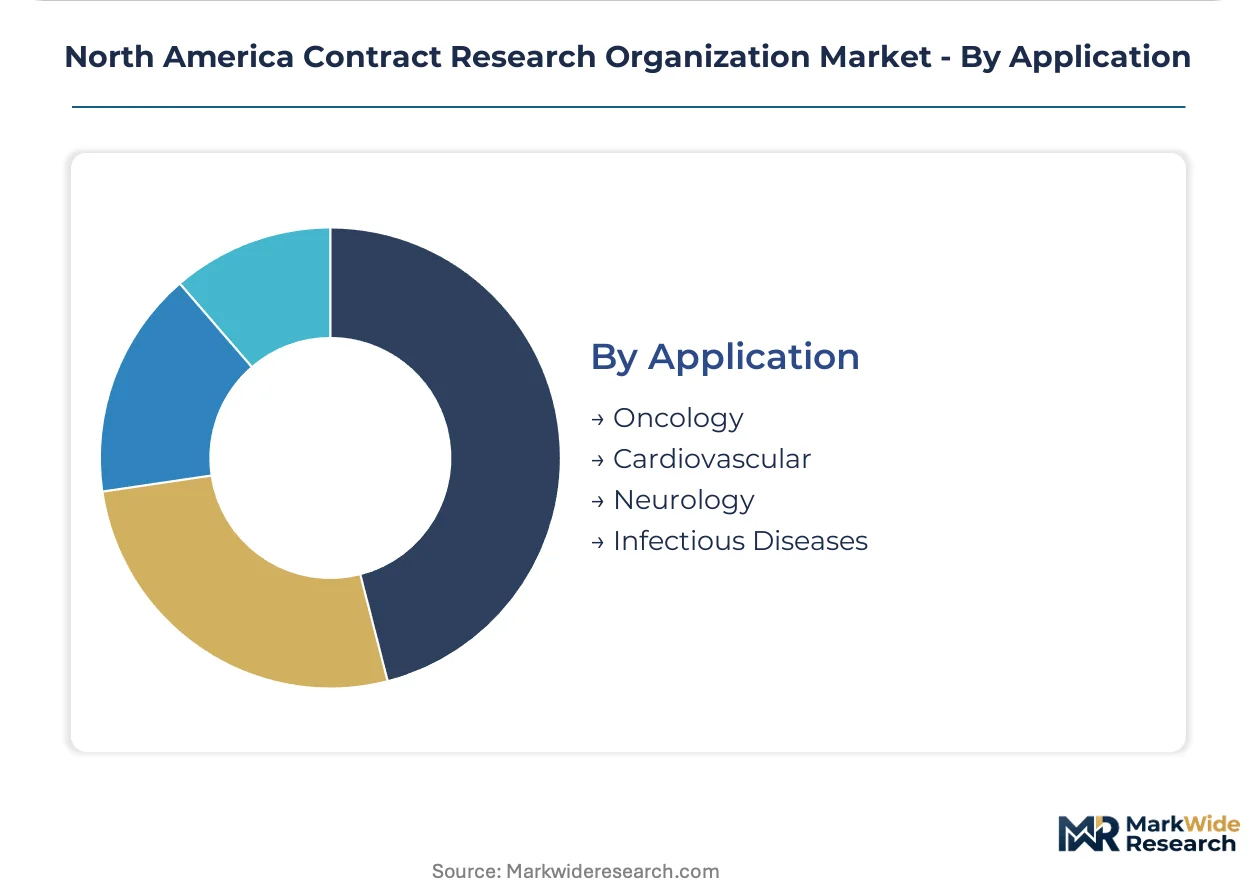
Application:
Therapeutic complexity determines capability requirements, with oncology demanding specialized site networks and biomarker integration that reshape vendor economics.
- Oncology:Immuno-oncology Phase III trials require specialized investigator networks and companion diagnostic coordination. FDA's accelerated approval pathways compress enrollment timelines.
- Cardiovascular:Large outcome studies with hard endpoints demand extensive site infrastructure and long-term patient retention capabilities.
- Neurology:CNS trials face recruitment challenges that algorithmic patient matching and decentralized monitoring technologies address.
- Infectious Diseases:Vaccine development and antimicrobial resistance programs generate episodic demand surge capabilities.
Oncology dominates the therapeutic revenue base. Neurology shows the steepest capability investment trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Interstate 95 pharmaceutical corridor underwrites North America's dominance in contract research services, linking Boston's biotech cluster to New Jersey's headquarters concentration through high-bandwidth logistics and specialized talent pipelines.
United States
FDA's ICH E6(R3) modernization and Risk-Based Monitoring guidance are compressing quality system upgrade cycles across domestic CROs. The Boston-Cambridge cluster anchors Phase III oncology trial execution, while the New Jersey corridor concentrates sponsor headquarters and vendor procurement functions. Site density in the Northeast creates geographic vulnerability to regional inspection backlogs.
Canada
Health Canada's ICH-aligned Clinical Trial Framework offers parallel certification pathways for U.S. sponsors seeking regulatory diversity. Toronto and Montreal delivery centers process adverse event reporting for North American sponsor portfolios. Cross-border study expansion is accelerating as FDA inspection timelines lengthen.
Mexico
Cost arbitrage in clinical monitoring and data management functions is drawing mid-tier sponsor contracts to Mexico City and Guadalajara delivery centers. COFEPRIS regulatory alignment with FDA standards enables integrated North American trial protocols. Language capabilities and time-zone proximity support real-time collaboration with U.S. sponsor teams.
North America Contract Research Organization Market Competitive Landscape
Listed leaders compete with private specialists across capital access and strategic flexibility dimensions, creating a tiered structure where scale-driven incumbents battle niche execution vendors for sponsor contracts. The vendor pool bifurcates between audit-ready quality systems and excluded challengers under ISO 14155 and ICH-GCP standards. Three archetypes dominate: integrated laboratory-to-clinical platforms, decentralized trial technology specialists, and real-world evidence data aggregators. M&A consolidation and technology licensing partnerships represent the dominant competitive moves as sponsors unbundle full-service contracts.
Within the integrated platform tier, Thermo Fisher Scientific Inc and Charles River Laboratories exemplify laboratory services integration that extends downstream into clinical execution. IQVIA Inc anchors the data-centric archetype, competing on real-world evidence asset scale that smaller rivals cannot replicate. These three listed entities represent contrasting strategic positions—equipment and consumables leverage, preclinical-to-clinical continuity, and information infrastructure dominance—each capturing distinct margin pools across the trial lifecycle.
| Leading Market Players |
|---|
| Fortrea Inc |
| Parexel International |
| ICON plc |
| Thermo Fisher Scientific Inc |
| Syneos Health |
| Charles River Laboratories |
| Medpace Holdings |
| Inotiv |
| IQVIA Inc |
| Others |
Pricing and Supply Chain Analysis
Site network density in the Northeast corridor generates scale economies that compress per-patient monitoring costs while establishing price floors for specialized oncology execution. FDA's Risk-Based Monitoring guidance and ICH E6(R3) compliance timelines concentrate supply among audit-ready incumbents, reinforcing tiered pricing power across the vendor pool.
Pricing Analysis
Volume-discount tiering structures separate full-service CRO contracts from functional component awards, with large pharmaceutical sponsors capturing 15-25% unit cost reductions through competitive bidding across data management, monitoring, and biostatistics. Price differentiation hinges on ISO 14155 certification grade and biomarker-integrated site network depth. Cost compression in mid-tier execution services is intensifying as biotechnology sponsors unbundle Phase I-II studies. Biotechnology firms exhibit highest price sensitivity; integrated platform vendors with captive laboratory services command lowest.
Supply Chain Analysis
Specialized talent pipelines through Boston-Cambridge and New Jersey corridor academic medical centers create human capital chokepoints that constrain monitoring staff expansion. Clinical data scientists and regulatory biostatisticians draw from MIT, Harvard, and Rutgers training pipelines. Supply chain risk centers on single-source vulnerability to regional FDA inspection backlogs. Distribution runs through sponsor headquarters concentration in New Jersey with satellite delivery centers in Toronto and Montreal for cross-border regulatory diversity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America CRO market represents a service-attach opportunity where pharmacovigilance and real-world evidence subscriptions expand faster than traditional clinical execution revenue. Recurring-revenue platforms for safety surveillance and algorithmic trial design now outpace project-based site activation growth.
For Market Incumbents: Fortify quality management system investments ahead of ICH E6(R3) enforcement timelines to exclude audit-challenged competitors. Deepen backward integration into laboratory services to capture margin pools from preclinical bioanalytical through clinical sample processing. Charles River Laboratories exemplifies this upstream-to-downstream continuity. Defend against decentralized trial technology specialists by embedding remote monitoring capabilities into existing site networks. For New Entrants and Emerging Players: Differentiate on algorithmic patient matching and synthetic control arm construction for early-phase oncology and rare disease sponsors. White-space targets include neurology trials with recruitment challenges addressable through AI-enabled site selection, and cross-border Canadian studies leveraging Health Canada's ICH-aligned framework. Target venture-backed biotechnology firms in Boston-Cambridge seeking speed over single-accountability structures. Go-to-market angle: outcome-based enrollment guarantees with risk-sharing fee structures. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among pharmacovigilance and real-world evidence data aggregators with multi-year sponsor subscriptions. Long-term viability over the next decade favors vendors with proprietary data assets and AI governance infrastructure. Acquisition target archetype: decentralized trial technology specialists with FDA-validated remote monitoring platforms. Signal to watch: FDA final guidance on artificial intelligence in drug development as inflection indicator for algorithmic trial design adoption rates.| Strategic Initiative | Industry Significance |
|---|---|
| Quality Management System Upgrade | ICH E6(R3) compliance investments exclude non-audit-ready competitors from sponsor vendor pools. |
| Laboratory-to-Clinical Integration | Preclinical bioanalytical services anchor downstream clinical execution relationships through sample processing continuity. |
| Pharmacovigilance Platform Expansion | FDAAA-mandated post-market safety surveillance locks sponsors into multi-year adverse event reporting subscriptions. |
| Decentralized Trial Technology Deployment | FDA Risk-Based Monitoring guidance enables site-agnostic patient recruitment across underserved U.S. regions. |
| Real-World Evidence Asset Acquisition | IQVIA-scale data aggregation creates synthetic control arm capabilities that smaller rivals cannot replicate. |
Research Methodology
The analysis maps clinical trials, pharmacovigilance, data management, and regulatory affairs service segments, each validated through drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers. Primary interviews with C-suite sponsors and vendor procurement teams combined with secondary validation against FDA filings, ClinicalTrials.gov, Health Canada submissions, and SEC 10-K disclosures. Bottom-up service-type modeling and top-down end-user demand estimation triangulated market sizing across the projection horizon.
Consistency checks validated volume and value outputs against external benchmarks including formulary database trends and GPO contract volumes. The analytical framework modeled service type, end user scale, technology platform, and therapeutic application dimensions throughout the forecast period. CAGRs derived from enrollment velocity assumptions, outsourcing penetration rates, and regulatory mandate expansion timelines. Industry-specific inputs included FDA inspection backlog projections and Health Canada parallel certification uptake curves.
The analysis sits within stated boundaries; outcomes outside sustained biopharmaceutical R&D expenditure growth and stable FDA-Health Canada regulatory alignment would require recalibration. Forecasts reflect documented assumptions regarding outsourcing penetration, platform consolidation rates, and compliance timeline adherence. Practitioners should keep alternative scenarios live as ICH E6(R3) enforcement rigor and AI-enabled trial design adoption curves evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Clinical Research
Clinical Trials Outsourcing Market
Clinical Research
Global Clinical Trial Support Services Market
Clinical Research
Clinical Trial Logistics Market
Clinical Research
Real World Evidence Linkage Services Market
Clinical Research
Clinical Trials Site Management Organizations Market
Clinical Research
Europe Clinical Trials Market
Clinical Research
Healthcare Europe Clinical Data Analytics Market
Clinical Research
Ecoa, Esource & Clinical Trials Market
Clinical Research
Synthetic Clinical Trial Data Market
Clinical Research
Pharmacovigilance Outsourcing Market
Clinical Research
AI-Assisted Clinical Trial Protocol Design Market
Clinical Research
Global Clinical Trial Supply Market
Clinical Research
Clinical Data Analytics Market
Clinical Research
HIV Clinical Trials Market
Clinical Research
Generative AI in Clinical Trials Market
Clinical Research
Non-Alcoholic Steatohepatitis Clinical Trials Market