
 Nonerosive Reflux Disease Treatment Market | 2026-2036
Nonerosive Reflux Disease Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Nonerosive Reflux Disease Treatment Market Analytics
Specialty clinics is restructuring the patient pathway for nonerosive reflux disease management, shifting volume away from hospital-based gastroenterology departments toward outpatient settings. AstraZeneca leverages its established proton pump inhibitor portfolio to sustain formulary dominance across European and North American markets. Takeda Pharmaceutical anchors its position through differentiated potassium-competitive acid blocker technology. Johnson & Johnson competes via broad channel control spanning retail pharmacy, hospital procurement, and direct-to-provider distribution networks.
Nonerosive reflux disease treatment encompasses pharmacological and non-pharmacological interventions targeting symptomatic gastroesophageal reflux without endoscopic mucosal damage, typically involving acid suppression through proton pump inhibitors that achieve gastric pH above four for twelve to twenty hours daily. The primary purpose centers on symptom resolution and quality-of-life restoration for patients with normal esophageal mucosa on endoscopy. Proton pump inhibitors command the largest revenue pool among product types due to superior efficacy in acid suppression and extensive generic availability that compresses margins. Home healthcare represents the fastest-expanding end user segment as self-administered oral therapies and telehealth follow-up protocols reduce dependency on facility-based care.
The FDA maintains stringent requirements for NDA and ANDA submissions of acid-suppressing agents, while the EMA's pharmacovigilance framework mandates ongoing safety surveillance for long-term proton pump inhibitor exposure across European markets. These regulatory structures elevate barriers for new entrants and compel incumbents to invest in post-marketing evidence generation. Japan's PMDA imposes additional gastrointestinal safety benchmarks that shape regional product development priorities. Stakeholders must monitor evolving cardiovascular and renal safety signals associated with chronic acid suppression therapy as these data streams increasingly influence payer coverage determinations and prescribing guidelines.
Market Dynamics
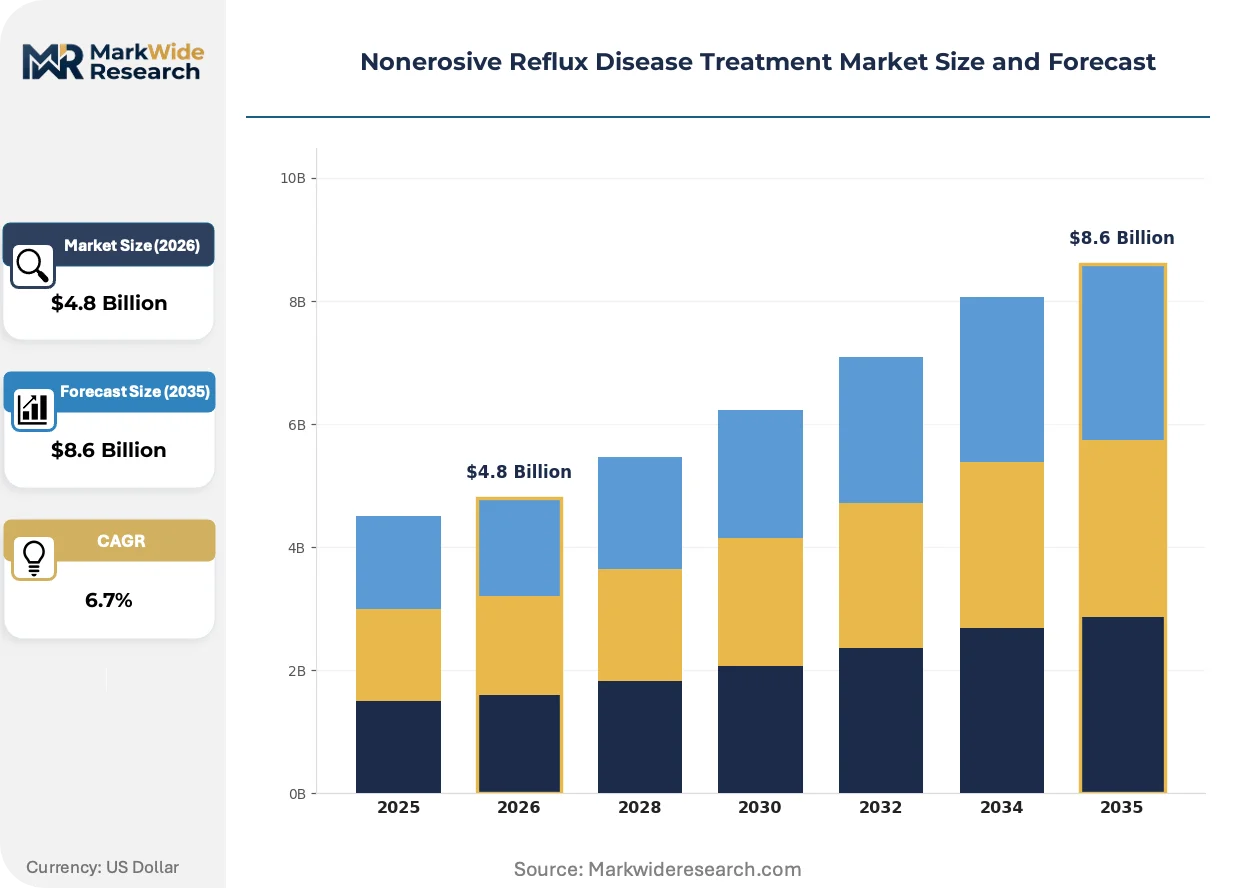
Specialty clinics are consolidating patient volume from hospital gastroenterology departments, driven by ambulatory reimbursement advantages and telehealth integration that enables remote symptom monitoring without endoscopic confirmation.
Growth Catalysts
- EMA pharmacovigilance framework:Ongoing safety surveillance mandates for long-term proton pump inhibitor exposure generate demand for differentiated acid suppression therapies with cleaner cardiovascular profiles.
- Home healthcare:Self-administered oral therapies and remote follow-up protocols reduce facility dependency and expand addressable patient populations beyond urban hospital catchments.
- Germany ambulatory protocols:Broad clinical adoption of outpatient reflux management creates template for specialty clinic expansion across European markets.
Market Restraints
- Generic proton pump inhibitor saturation:Extensive generic availability compresses margins and limits pricing power for originator molecules across retail pharmacy channels.
- FDA labeling evolution:Changing guidance on long-term acid suppression safety creates prescribing uncertainty and elevates liability exposure for chronic therapy initiation.
- Active pharmaceutical ingredient concentration:Supply chain reliance on Asian manufacturers for omeprazole and esomeprazole intermediates exposes formulation networks to geopolitical disruption.
Strategic Opportunities
- Japan PMDA gastrointestinal benchmarks:Additional safety requirements for regional approval create incentive for novel potassium-competitive acid blocker development with differentiated profiles.
- Direct-to-provider distribution:Bypassing traditional wholesale channels enables formulary negotiation directly with specialty clinic networks and integrated delivery systems.
- Telehealth symptom tracking:Digital therapeutics integration allows pharmaceutical sponsors to demonstrate real-world effectiveness beyond clinical trial endpoints.
Industry Challenges
- Post-marketing evidence generation:Regulatory demands for cardiovascular and renal safety data require sustained investment in observational studies and registry maintenance.
- Legacy hospital system integration:Electronic health record interoperability between ambulatory specialty clinics and referral hospitals complicates care coordination.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nonerosive Reflux Disease Treatment Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Proton Pump Inhibitors, H2 Receptor Antagonists, Antacids, Prokinetics End User: Hospitals, Specialty Clinics, Home Healthcare, Pharmacies Treatment Approach: Pharmacological Therapy, Lifestyle Modifications, Dietary Changes, Surgery Distribution Channel: Online Pharmacy, Retail Pharmacy, Hospital Pharmacy, Direct Sales |
| Companies Covered | AstraZeneca, Eisai, GlaxoSmithKline, Takeda Pharmaceutical, Johnson & Johnson, Ironwood Pharmaceuticals, Daewoong Pharmaceutical, SFJ Pharmaceuticals Group, SRS Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nonerosive Reflux Disease Treatment Market Evolving Landscape
Potassium-competitive acid blockers are disrupting established proton pump inhibitor paradigms through faster onset and reversible binding kinetics, while regulatory scrutiny of chronic acid suppression intensifies evidence requirements across all therapeutic classes.
Potassium-competitive acid blocker technology achieves more rapid gastric acid suppression than traditional proton pump inhibitors by reversibly binding to the potassium site of the H+,K+-ATPase enzyme. Specialty clinics in Germany and Japan are adopting these agents for patients with incomplete symptom control on standard therapy. This mechanism is expanding into markets previously dominated by generic proton pump inhibitors by offering differentiated on-demand and flexible dosing protocols.
The FDA's evolving guidance on proton pump inhibitor cardiovascular and renal safety labeling is reshaping prescribing patterns in the United States. Clinicians face heightened documentation requirements for long-term therapy continuation beyond eight weeks. Gastroenterology practices are responding by implementing mandatory medication reviews and deprescribing protocols for stable patients.
Patients with nonerosive reflux disease are prioritizing symptom resolution speed over endoscopic mucosal healing as the primary treatment goal. This preference shift elevates therapies with rapid onset profiles regardless of mucosal protection claims. Germany's ambulatory care networks report highest visibility of this behavioral change, with patient-reported outcome measures now dominating formulary access negotiations.
Nonerosive Reflux Disease Treatment Market Segmentation
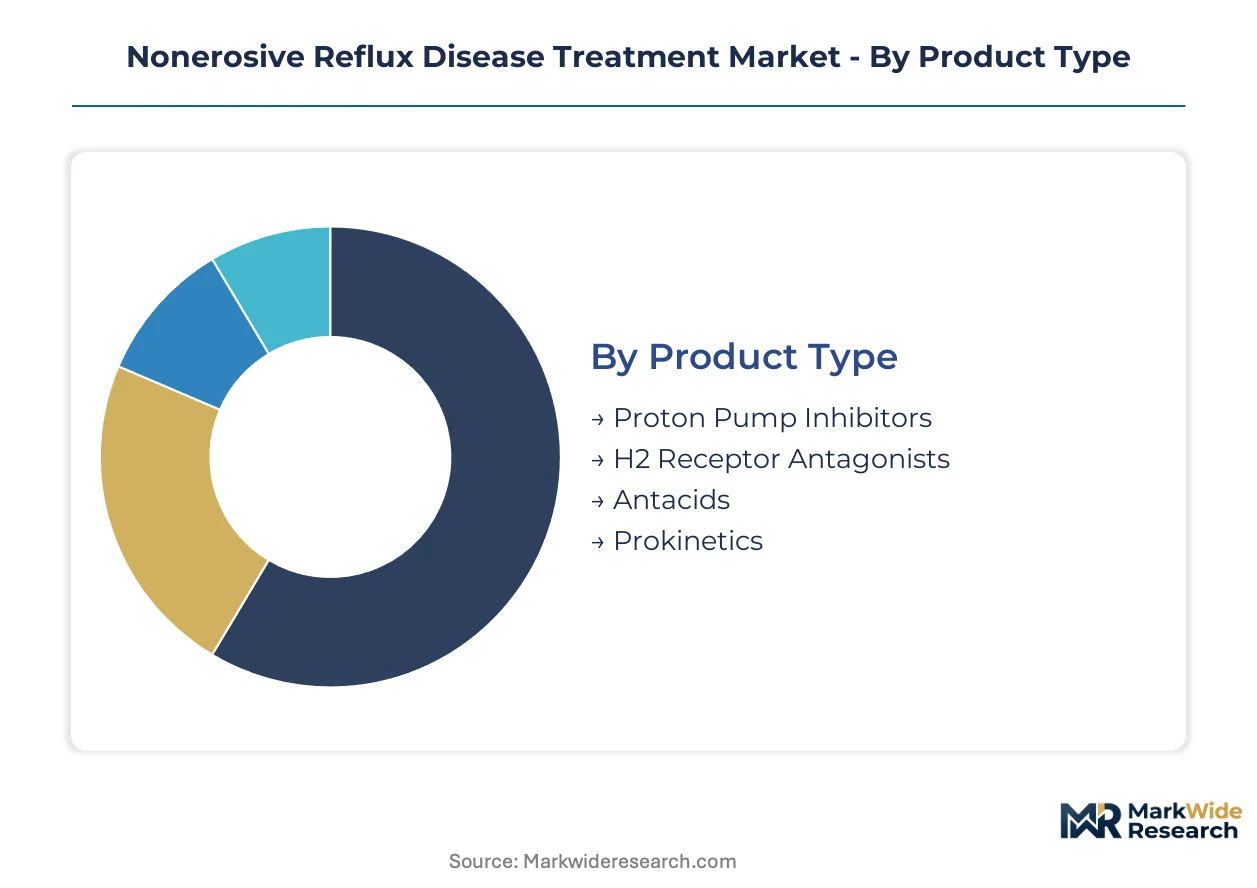
Nonerosive reflux disease treatment segments by mechanism of action, care setting, and patient autonomy level. Each dimension reveals distinct margin structures and regulatory exposure profiles that shape commercial strategy.
Product Type:
Cost tier separates chronic maintenance prescriptions from acute symptom relief purchases, with reimbursement depth varying by therapy class.
- Proton Pump Inhibitors:Irreversible H+,K+-ATPase inhibition delivers sustained gastric pH elevation above four for twelve to twenty hours. Volume concentrates in Germany where ambulatory protocols favor once-daily oral administration, though generic saturation compresses originator margins across retail channels.
- H2 Receptor Antagonists:Competitive histamine blockade at parietal cell H2 receptors provides shorter-duration acid suppression suitable for intermittent symptoms. Demand clusters in Japan where PMDA gastrointestinal safety benchmarks have slowed novel proton pump inhibitor uptake, preserving competitive space for established H2 agents.
- Antacids:Rapid chemical neutralization of gastric acid through calcium carbonate or magnesium hydroxide formulations addresses breakthrough symptoms without prescription requirements.
- Prokinetics:Dopamine D2 receptor antagonism or 5-HT4 agonism accelerates gastric emptying and lower esophageal sphincter tone for patients with motility-predominant presentations.
Volume sits with proton pump inhibitors; growth tilts toward prokinetics as refractory symptom recognition expands.
End User:
Patient acuity and reimbursement mechanism determine where prescribing authority resides across the care continuum.
- Specialty Clinics:Gastroenterology-focused ambulatory settings combine diagnostic capability with therapeutic initiation for patients requiring endoscopic evaluation. Germany's outpatient reflux management protocols have achieved broad clinical adoption here, shifting volume from hospital departments.
- Home Healthcare:Self-administered oral therapies with telehealth monitoring enable remote symptom tracking without facility dependency. This segment climbs the fastest as remote follow-up protocols reduce urban hospital catchment constraints and expand rural access.
- Hospitals:Inpatient gastroenterology departments manage severe or complicated presentations requiring endoscopic intervention or surgical consultation.
- Pharmacies:Community and retail dispensaries handle prescription fulfillment and over-the-counter transitions for maintenance therapy.
Revenue concentrates in specialty clinics; patient volume migrates fastest toward home healthcare.
Treatment Approach:
Clinical philosophy divides interventionist pharmacology from patient-directed behavioral modification.
- Pharmacological Therapy:Systemic acid suppression through prescribed agents remains the dominant intervention for symptom resolution and quality-of-life restoration. EMA pharmacovigilance frameworks for long-term proton pump inhibitor exposure elevate demand for differentiated agents with cleaner cardiovascular profiles.
- Lifestyle Modifications:Elevation of head-of-bed, weight reduction, and smoking cessation protocols address behavioral contributors without pharmaceutical exposure.
- Dietary Changes:Elimination of trigger foods including caffeine, alcohol, and high-fat meals reduces symptom frequency in mild presentations.
- Surgery:Fundoplication or magnetic sphincter augmentation reserved for refractory cases with confirmed pathologic reflux despite optimized medical management.
Prescription volume dominates pharmacological therapy; patient preference shifts steepest toward dietary changes as safety concerns mount.
Distribution Channel:
Channel control determines formulary access speed and margin capture for manufacturers.
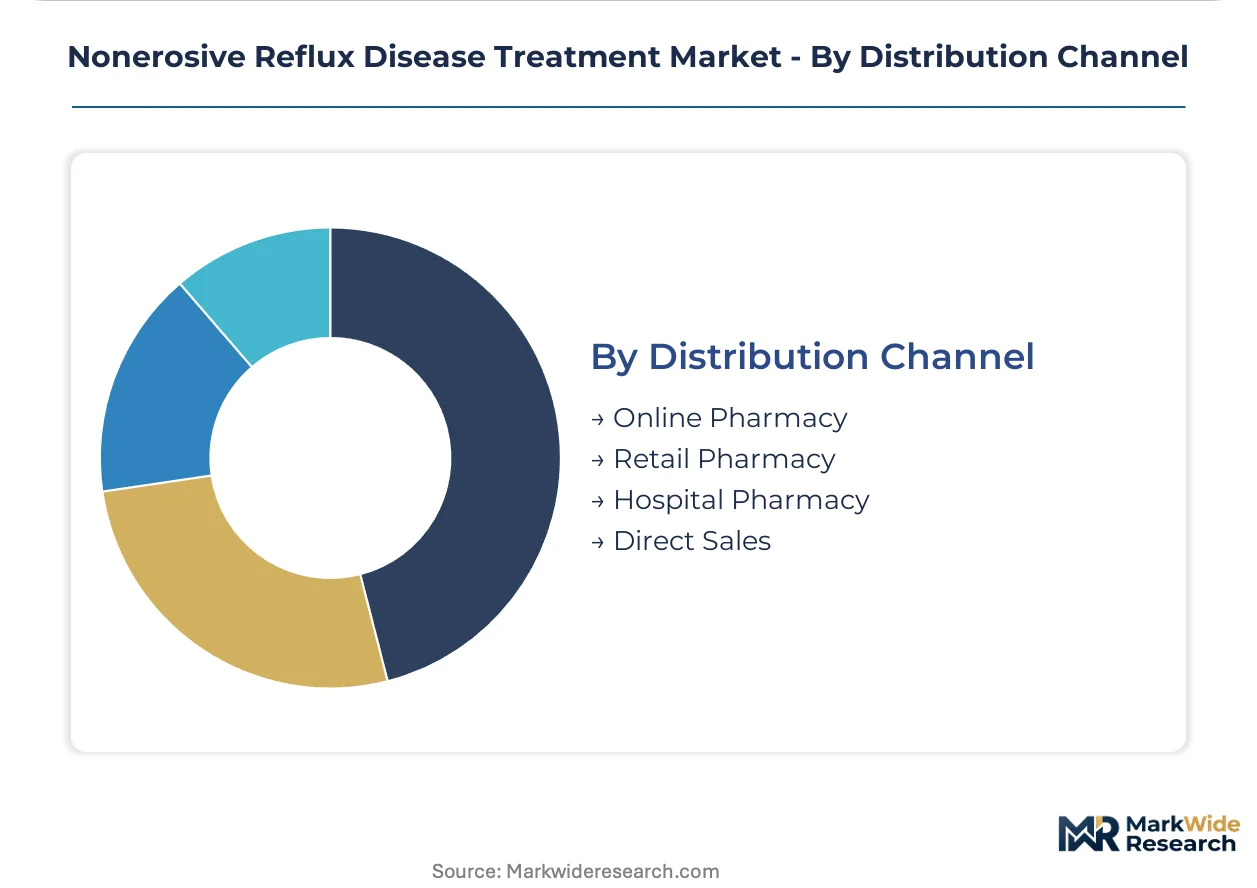
- Retail Pharmacy:Brick-and-mortar dispensaries maintain formulary relationships with regional pharmacy benefit managers and handle both generic substitution and prior authorization processing. Volume concentrates in the United States where FDA labeling evolution on long-term acid suppression safety has elevated pharmacist counseling requirements.
- Direct Sales:Manufacturer-to-provider distribution bypasses wholesale markups and enables formulary negotiation directly with specialty clinic networks and integrated delivery systems. This channel gains share fastest as consolidated clinic systems seek procurement efficiencies.
- Online Pharmacy:Digital dispensaries with mail-order fulfillment serve maintenance therapy patients prioritizing convenience over immediate access.
- Hospital Pharmacy:Captive dispensaries within acute care facilities manage inpatient prescribing and discharge medication reconciliation.
Prescription volume flows through retail pharmacy; margin expansion tilts toward direct sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Formulation manufacturing concentrates in Asian supply clusters while prescription volume and clinical protocol development concentrate in Western European and North American markets. Consumption patterns diverge sharply between established ambulatory care networks and emerging direct-to-patient channels.
United States
Specialty clinic consolidation and telehealth reimbursement expansion drive ambulatory volume migration from hospital gastroenterology departments. FDA labeling evolution on long-term proton pump inhibitor cardiovascular and renal safety elevates documentation requirements for chronic therapy beyond eight weeks. Boston and New York metro areas host the densest concentrations of integrated delivery systems piloting mandatory medication review protocols.
Germany
Ambulatory reflux management protocols achieve broad clinical adoption through statutory health insurance reimbursement frameworks favoring outpatient specialist care. EMA pharmacovigilance mandates for long-term acid suppression exposure generate sustained demand for differentiated therapeutic profiles. The Rhine-Ruhr and Bavarian medical clusters concentrate specialty clinic networks that have shifted diagnostic and therapeutic volume away from university hospital departments.
Japan
PMDA gastrointestinal safety benchmarks for novel acid suppression agents preserve competitive space for established H2 receptor antagonists and slow novel proton pump inhibitor uptake. Aging demographics expand the addressable patient population for maintenance therapy. The Kanto region around Tokyo anchors regulatory submission activity and clinical trial infrastructure for potassium-competitive acid blocker development programs.
United Kingdom
NHS England prescribing guidelines emphasize stepped-care algorithms that reserve proton pump inhibitors for refractory cases, elevating antacid and H2 antagonist utilization in primary care. Cost-effectiveness thresholds for formulary inclusion compress margins for originator molecules. The Greater Manchester and West Midlands health systems pilot direct-to-provider distribution models that bypass traditional pharmacy wholesale channels.
India
Domestic generic manufacturing capacity for omeprazole and esomeprazole intermediates exposes formulation networks to API supply concentration risks. CDSCO regulatory pathways for fixed-dose combinations attract regional development investment. The Mumbai-Pune pharmaceutical corridor and Hyderabad bulk drug clusters concentrate active pharmaceutical ingredient production for export markets.
Nonerosive Reflux Disease Treatment Market Competitive Landscape
Top-tier vendors anchor originator molecule portfolios with established formulary relationships, while mid-tier generic manufacturers compete on cost position and regional regulatory expertise. Market structure tilts toward consolidation at the innovation end and fragmentation at the commodity formulation end. Three strategic archetypes dominate: multinational pharmaceutical conglomerates with proton pump inhibitor legacy franchises, Japanese and Korean innovators advancing potassium-competitive acid blocker platforms, and regional generic houses with API backward integration. Competitive moves concentrate on direct-to-provider distribution channel capture and telehealth platform partnerships for remote patient monitoring.
Within the multinational conglomerate tier, AstraZeneca and Johnson & Johnson occupy positions defined by broad channel control spanning retail pharmacy, hospital procurement, and specialty clinic networks. Takeda Pharmaceutical exemplifies the innovation-focused archetype through its differentiated acid suppression technology portfolio. Daewoong Pharmaceutical represents the Asia-Pacific regional specialist model with concentrated presence in Korean and Japanese regulatory environments.
| Leading Market Players |
|---|
| AstraZeneca |
| Eisai |
| GlaxoSmithKline |
| Takeda Pharmaceutical |
| Johnson & Johnson |
| Ironwood Pharmaceuticals |
| Daewoong Pharmaceutical |
| SFJ Pharmaceuticals Group |
| SRS Pharmaceuticals |
| Others |
Value Network & Pricing Analysis
Formulation chemists concentrated in the Mumbai-Pune pharmaceutical corridor and Hyderabad bulk drug clusters feed labor-cost differentials into pricing-tier spreads across originator molecules and generic substitutes. EMA pharmacovigilance mandates for long-term acid suppression therapies elevate documentation burdens that compress margins on standard proton pump inhibitor formulations while preserving premium positioning for differentiated potassium-competitive acid blocker platforms.
Pricing Analysis
Margin tightening in generic proton pump inhibitor tiers reflects extensive availability of omeprazole and esomeprazole substitutes across retail pharmacy channels. Three-tier pricing structure across premium, standard, and economy levels separates originator molecules with cardiovascular safety dossiers from unbranded generics and over-the-counter antacid alternatives. Pricing pressure stems from statutory health insurance reimbursement ceilings in Germany and NHS England cost-effectiveness thresholds. Hospital procurement committees demonstrate highest price sensitivity; specialty clinic networks with direct-to-provider distribution arrangements show lowest.
Supply Chain Analysis
Direct-to-provider channels handle consolidated specialty clinic demand while retail pharmacy networks manage fragmented patient prescriptions. Active pharmaceutical ingredient production concentrates in India and China for proton pump inhibitor intermediates, with formulation finishing distributed across Germany, Japan, and the United States. Supply chains draw from omeprazole, esomeprazole, and lansoprazole chemical precursors with limited alternative sourcing. Single-source vulnerability in Asian API manufacturing exposes networks to geopolitical disruption. Distribution runs through wholesale pharmacy benefit managers with growing direct sales bypass.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Generic saturation and regulatory documentation burdens are forcing consolidation among mid-tier manufacturers without backward integration into active pharmaceutical ingredient production.
For Market Incumbents: To counter margin compression from generic proton pump inhibitor substitution, AstraZeneca and Takeda Pharmaceutical should deepen captive supply of esomeprazole and vonoprazan intermediates through Hyderabad and Mumbai-Pune manufacturing partnerships. Channel control through direct-to-specialty-clinic distribution networks offers defensive positioning against retail pharmacy formulary substitution. For New Entrants and Emerging Players: Telehealth-integrated home healthcare delivery offers the most penetrable route for potassium-competitive acid blocker platforms seeking formulary access outside established hospital procurement systems. Japan's PMDA gastrointestinal safety benchmarks create regulatory white space for novel acid suppression mechanisms. Direct-to-patient digital therapeutics partnerships enable bypass of traditional pharmacy wholesale markups. For Investors and Strategic Acquirers: The window for entry favors API-backward-integrated generic houses with CDSCO regulatory expertise and concentrated presence in Indian pharmaceutical corridors. Long-term viability rests on consolidation plays capturing formulation capacity with established EMA and FDA submission track records. Monitor EMA cardiovascular safety signal updates as inflection indicator for proton pump inhibitor portfolio revaluation.| Strategic Initiative | Industry Significance |
|---|---|
| API Backward Integration | Captive omeprazole intermediate production insulates margins from Asian supply disruption. |
| Direct-to-Provider Distribution | Bypassing wholesale channels accelerates formulary negotiation with German specialty clinic networks. |
| Potassium-Competitive Acid Blocker Development | Reversible H+,K+-ATPase binding kinetics differentiate from generic proton pump inhibitor saturation. |
| Telehealth Platform Partnership | Remote symptom tracking enables real-world effectiveness demonstration beyond clinical trial endpoints. |
| EMA Pharmacovigilance Compliance Investment | Cardiovascular safety registry maintenance preserves originator molecule premium positioning. |
Research Methodology
Document review covered FDA New Drug Application filings, EMA periodic safety update reports, and ClinicalTrials.gov protocol registries, complemented by interviews with drug development executives at proton pump inhibitor originators, regulatory affairs leads navigating PMDA gastrointestinal benchmarks, formulary directors at German statutory health insurers, and hospital procurement managers in NHS England integrated care systems. Secondary validation drew from pharmacovigilance databases, pharmaceutical customs records, and SEC 10-K disclosures. Bottom-up prescription volume modeling and top-down therapeutic class revenue estimates underwent cross-triangulation.
Market sizing outputs reflect patient population projections, treatment persistence rates, and pricing tier distributions across the projection horizon. Segmentation dimensions encompass mechanism of action, care setting, patient autonomy level, and regional regulatory cluster. CAGRs were derived from log-linear trend fitting to historical prescription data with adjustment for generic entry timing and EMA safety labeling revisions. Forecast inputs include ambulatory protocol adoption curves in Germany and telehealth reimbursement policy evolution in the United States.
The model holds under stable EMA pharmacovigilance frameworks and continued statutory health insurance reimbursement for outpatient reflux management; deviation in FDA cardiovascular safety labeling or API supply disruption would shift volume and value trajectories. Forecasts reflect documented assumptions regarding patient diagnosis rates and therapy continuation patterns. Periodic stress-testing of base assumptions is recommended against emerging renal safety signals and potassium-competitive acid blocker regulatory approval timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Monoclonal Antibody Therapy Market
Specialty Medicine
Radioimmunotherapy (RIT) Market
Specialty Medicine
Bleeding Disorders Treatment Market
Specialty Medicine
Bullous Pemphigoid Treatment Market
Specialty Medicine
Brain Metastasis Therapeutics Market
Specialty Medicine
Multiple Endocrine Neoplasia Market
Specialty Medicine
North America Cancer Therapy Market
Specialty Medicine
Solid Tumor Therapeutics Market
Specialty Medicine
Global Melanoma Diagnostics and Therapeutics Market
Specialty Medicine
Global Cancer Biological Therapy Market
Specialty Medicine
Global Nephropathic Cystinosis Treatment Market
Specialty Medicine
Alport Syndrome Treatment Market
Specialty Medicine
Global Cough Hypersensitivity Syndrome Treatment Market
Specialty Medicine
Hemochromatosis Treatment Market
Specialty Medicine
US Mobile Physician Practice Market
Specialty Medicine
Acute Myeloid Leukemia Therapeutics Market