
 Poultry Diagnostics Market | 2026-2036
Poultry Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Poultry Diagnostics Market Intelligence
Brazil is rewriting capacity dynamics across poultry diagnostics as integrated producers expand in-house laboratory networks to meet export health standards. IDEXX Laboratories dominates molecular platform deployment across Latin American processing corridors. Zoetis anchors vaccine-diagnostic bundling strategies that lock in long-term veterinary clinic relationships. Thermo Fisher Scientific competes through reagent supply contracts with government reference laboratories.
Poultry diagnostics encompasses laboratory and field-based analytical methods for detecting avian pathogens, genetic traits, and nutritional deficiencies in commercial and breeder flocks, with polymerase chain reaction achieving sensitivity thresholds below 10 copies per reaction for targeted nucleic acid identification. The primary purpose is to enable rapid flock health decisions that prevent catastrophic disease losses and satisfy importer country certification requirements. Molecular diagnostics leads product type revenue due to premium pricing on multiplexed pathogen panels, while lateral flow assay technology sustains the fastest growth trajectory through point-of-use deployment on poultry farms with limited laboratory infrastructure. Enzyme-linked immunosorbent assay applications in infectious disease detection occupy mature margin pools where commoditized reagent competition compresses per-test economics.
USDA APHIS regulations shape United States market access through National Poultry Improvement Program testing mandates, while OIE standards govern international trade certification that Brazilian and Thai exporters must satisfy. ISO 17025 accreditation requirements from laboratory accreditation bodies force diagnostic laboratories to maintain rigorous quality management systems that favor capital-intensive platform investments. Stakeholders must monitor how avian influenza variant emergence and corresponding regulatory response timelines reshape testing volume forecasts and reagent inventory planning cycles.
Market Dynamics
USDA APHIS mandates for avian influenza surveillance are compressing testing turnaround requirements from days to hours, forcing laboratories to abandon culture-based methods and adopt molecular platforms that deliver same-day pathogen identification.
Growth Catalysts
- USDA National Poultry Improvement Program:Mandatory serological testing for pullorum-typhoid and avian influenza in breeder flocks sustains baseline diagnostic volume regardless of commodity price cycles.
- Multiplex PCR panels:Simultaneous detection of ten-plus respiratory pathogens in a single reaction reduces per-test labor costs and accelerates flock management decisions for integrated producers.
- Brazilian export certification requirements:European Union and Saudi Arabian import protocols demand ISO 17025-accredited laboratory documentation, expanding third-party testing demand across São Paulo and Paraná processing corridors.
Market Restraints
- Reagent import dependency:Latin American laboratories rely on temperature-controlled supply chains from North American manufacturers, exposing operations to cold-chain failures and customs clearance delays.
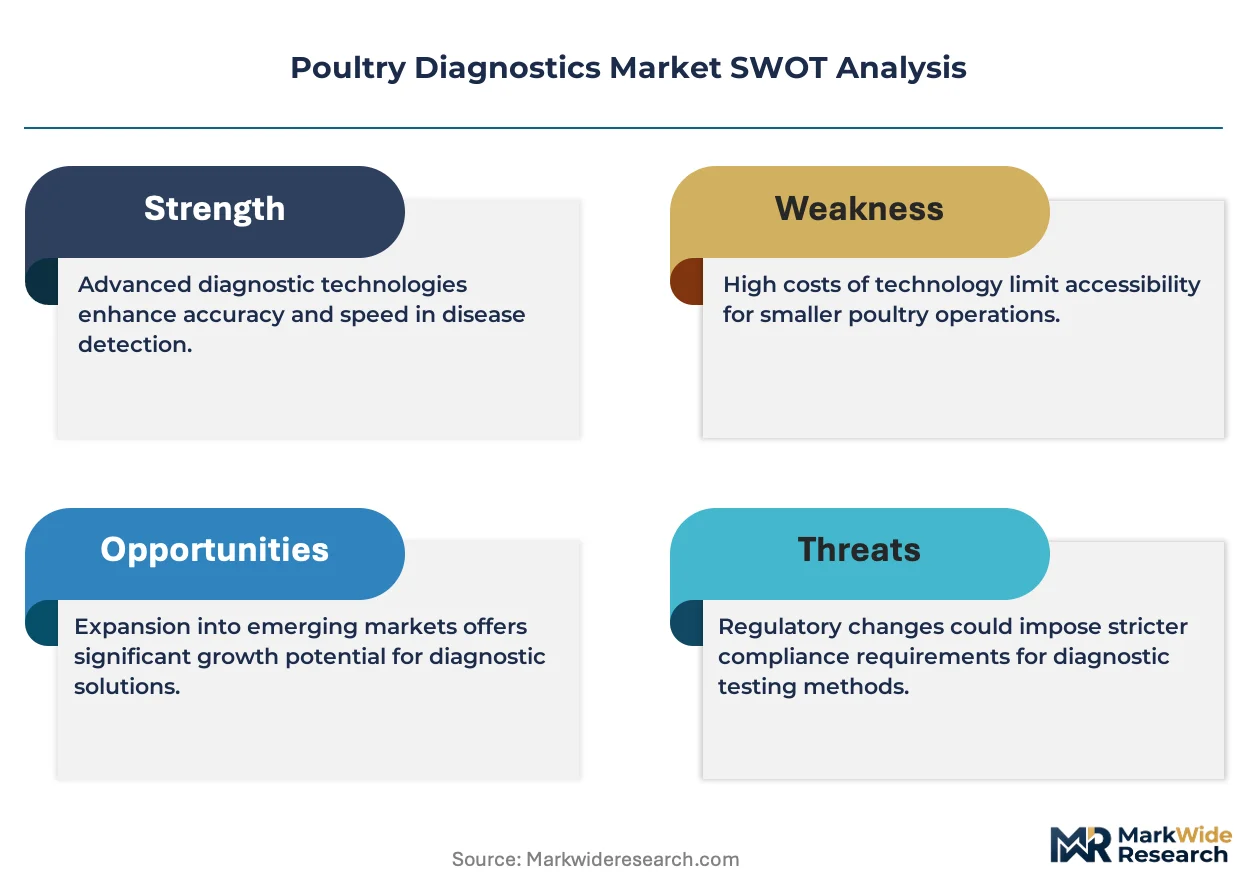
- ISO 17025 capital requirements:Accreditation demands for quality management systems, equipment calibration traceability, and personnel competency assessments impose six-figure investments that exclude small independent laboratories.
- Lateral flow sensitivity ceilings:Immunoassay detection limits at 10³-10⁴ CFU-equivalent prevent early-stage pathogen identification in subclinical infections, restricting use to outbreak confirmation rather than prevention.
Strategic Opportunities
- Penetration of Indonesian smallholder farms:Point-of-care molecular devices with smartphone connectivity address laboratory infrastructure gaps across Java and Sumatra, where 40 percent of production operates outside formal veterinary networks.
- Blockchain-integrated traceability:Immutable diagnostic record storage satisfies emerging importer demands for supply chain transparency, particularly for antibiotic residue and pathogen-free certification.
- CRISPR-based diagnostics convergence:Guide RNA programmable detection platforms reduce assay development timelines from months to weeks, enabling rapid response to variant avian influenza emergence.
Industry Challenges
- Molecular diagnostics technician scarcity:Nucleic acid extraction, thermocycler operation, and contamination control protocols require specialized training that veterinary schools have not scaled to match platform deployment rates.
- Legacy ELISA equipment amortization:Laboratories face sunk-cost pressure to maximize returns on existing plate readers and washer systems, delaying full migration to real-time PCR despite superior analytical performance.
- Reagent lot-to-lot variability:Enzyme and antibody instability across manufacturing batches generates false-negative risks that trigger repeat testing, eroding laboratory throughput and client confidence.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Poultry Diagnostics Market |
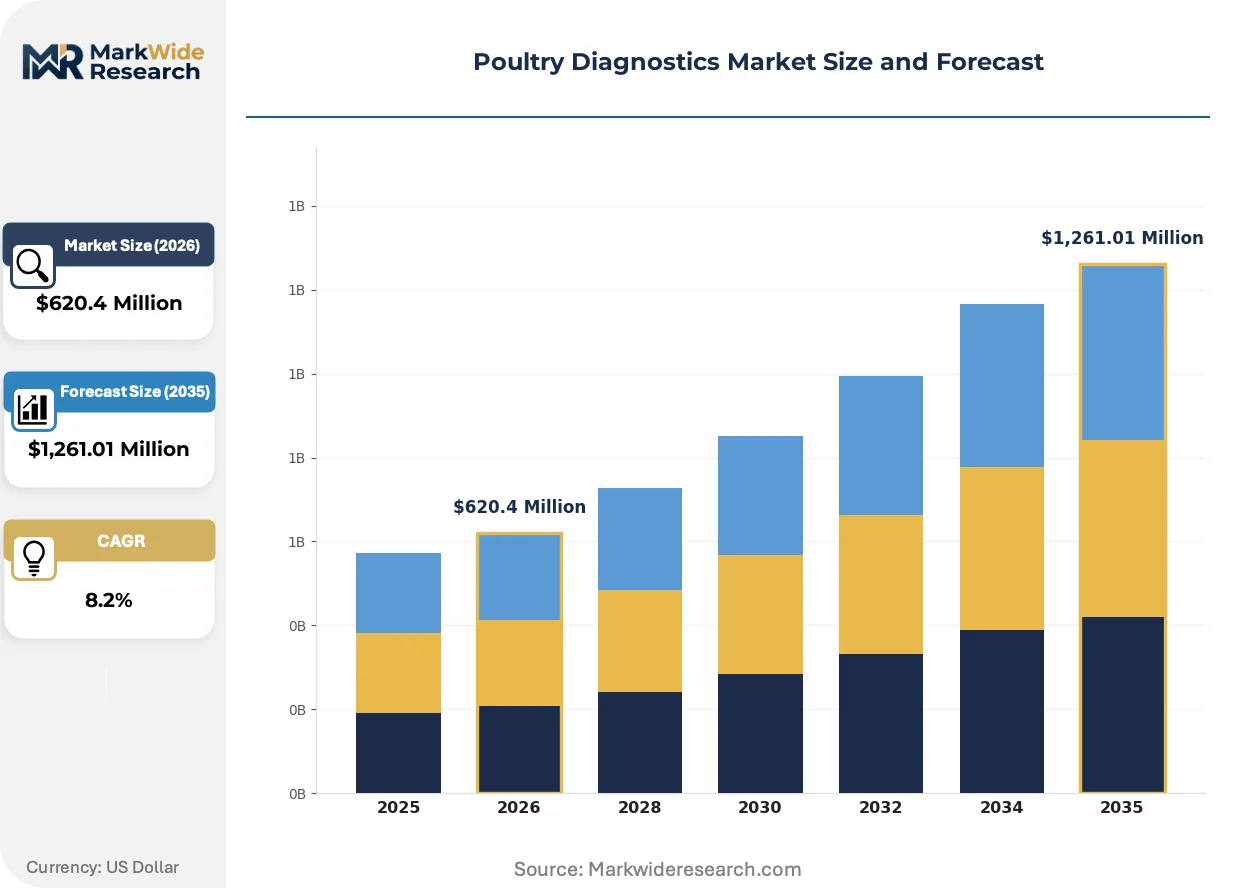
| Market Size in 2026 | $620.4 Million |
| Market Size in 2035 | $1,261.01 Million |
| CAGR (2026 – 2036) | 8.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Serological Tests, Molecular Diagnostics, Immunoassays, Culture-based Tests Application: Infectious Disease Detection, Genetic Screening, Nutritional Assessment, Reproductive Health End User: Veterinary Clinics, Diagnostic Laboratories, Poultry Farms, Research Institutes Technology: Polymerase Chain Reaction, Enzyme-Linked Immunosorbent Assay, Lateral Flow Assay, Next-Generation Sequencing |
| Companies Covered | IDEXX Laboratories, Zoetis, BioChek, Eurofins Ingenasa, Thermo Fisher Scientific, QIAGEN, Bioneer Corporation, Bionote, Gold Standard Diagnostics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Poultry Diagnostics Market Strategic Shifts & Innovations
Cloud-connected diagnostic instruments are collapsing the distance between farm-site sampling and centralized laboratory interpretation, creating real-time epidemiological visibility that was previously impossible across distributed production networks.
Loop-mediated isothermal amplification technology is digitizing pathogen detection workflows for resource-constrained settings. Brazilian integrated producers deploy battery-powered LAMP devices at farm perimeter checkpoints, eliminating sample transport delays. The technology is digitizing field-based decision-making by transmitting amplification curves directly to veterinary epidemiologists for immediate flock segregation commands.
European Commission regulations on antimicrobial resistance monitoring now mandate susceptibility testing integration with routine pathogen surveillance. Diagnostic laboratories must report minimum inhibitory concentration data alongside species identification, doubling analytical workload per sample. Poultry veterinarians in France and Germany are responding by consolidating testing contracts with full-service reference laboratories capable of combined microbiology and molecular workflows.
Subscription-based reagent procurement models are displacing transactional purchasing across Southeast Asian veterinary clinics. Thai and Vietnamese distributors bundle monthly PCR panel allotments with technical support and quality control materials, locking in predictable revenue streams. This shift is most visible among medium-scale layer operations seeking to stabilize per-hen diagnostic costs amid feed price volatility.
Poultry Diagnostics Market Segmentation
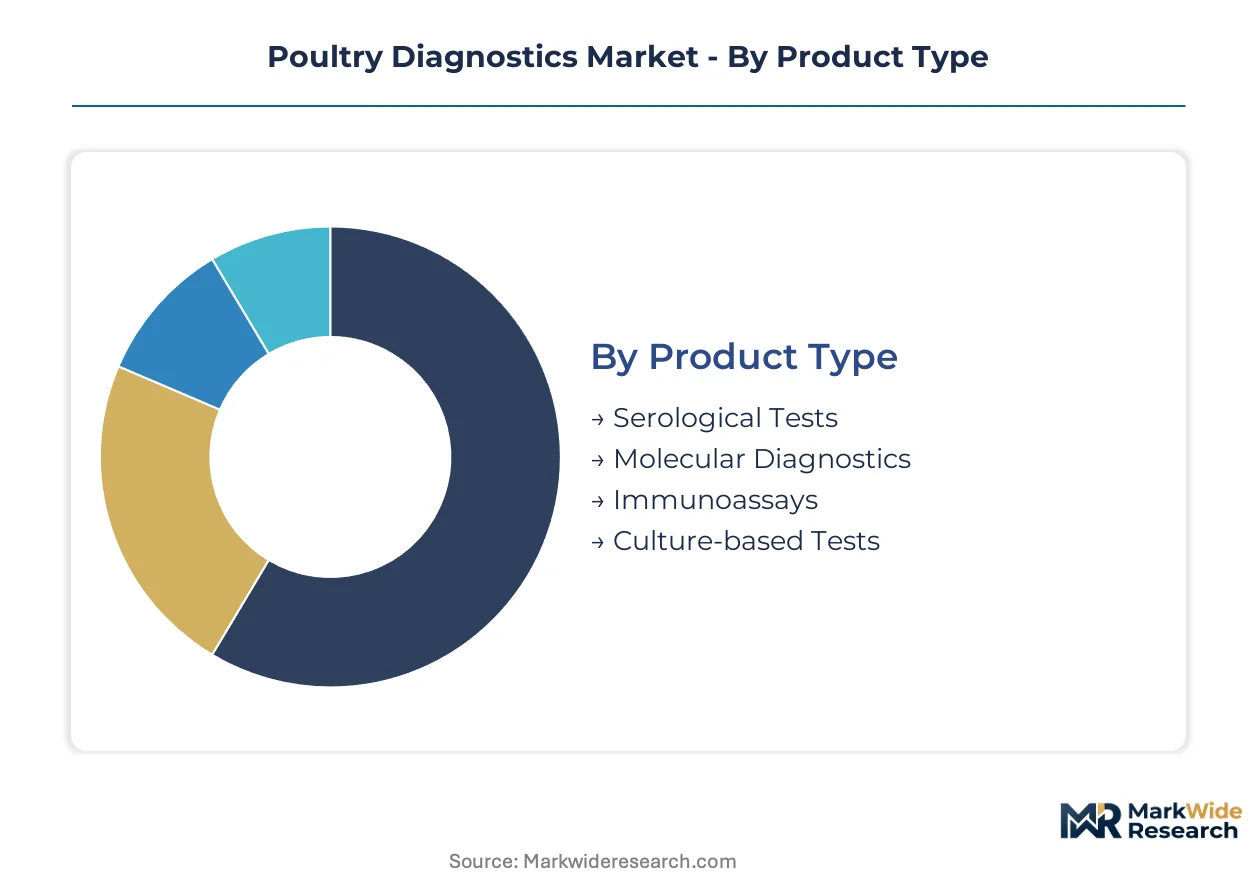
Diagnostic purchasing patterns in poultry operations diverge sharply between integrated producers seeking throughput efficiency and independent farms prioritizing capital flexibility. Segmentation reveals how technology maturity, regulatory compliance burden, and infrastructure availability reshape demand across testing modalities.
Product Type:
Use-case spectrum spans from high-throughput laboratory platforms to field-deployable screening tools, with cost-per-test and sensitivity requirements driving portfolio decisions.
- Molecular Diagnostics:Real-time PCR and isothermal amplification platforms detect nucleic acid targets below 10 copies per reaction. Brazilian integrated producers deploy multiplex panels across São Paulo processing corridors to satisfy EU export certification timelines.
- Serological Tests:Antibody-based detection methods identify prior pathogen exposure through serum agglutination and hemagglutination inhibition. USDA National Poultry Improvement Program mandates sustain baseline volume for pullorum-typhoid surveillance regardless of commodity cycles.
- Immunoassays:Enzyme-linked and fluorescent immunoassay formats deliver batch-processed results for flock-level screening.
- Culture-based Tests:Traditional microbiological isolation remains reference-standard for antimicrobial susceptibility profiling.
Established volume favors serological tests; emerging adoption favors molecular diagnostics.
Application:
Cost tier stratification separates premium-priced genetic services from commoditized infectious disease screening.
- Infectious Disease Detection:Pathogen identification for avian influenza, Newcastle disease, and mycoplasma dominates testing volume. Thai layer operations concentrate demand for respiratory pathogen panels amid European Commission antimicrobial resistance monitoring requirements.
- Genetic Screening:Marker-assisted selection and parentage verification support breeder flock management. Commercial significance concentrates in grandparent stock operations seeking trait optimization for feed conversion efficiency.
- Nutritional Assessment:Metabolic profiling and deficiency screening guide ration formulation adjustments.
- Reproductive Health:Fertility testing and embryonic sexing services support hatchery operations.
Volume concentrates in infectious disease detection; margin expansion favors genetic screening.
End User:
Customer type determines equipment sophistication, with integrated producers internalizing capabilities that independent operations outsource.
- Diagnostic Laboratories:ISO 17025-accredited facilities process third-party samples for export certification documentation. Paraná state laboratories anchor Brazilian testing capacity for Saudi Arabian and EU import protocols.
- Poultry Farms:On-site testing capabilities expand among large-scale integrated producers seeking same-day flock management decisions. Indonesian smallholders remain underserved due to infrastructure gaps across Java and Sumatra.
- Veterinary Clinics:Regional practitioners serve independent growers with point-of-care screening tools.
- Research Institutes:Academic and government facilities develop assay validations and reference materials.
Consolidation favors diagnostic laboratories; penetration gains favor poultry farms.
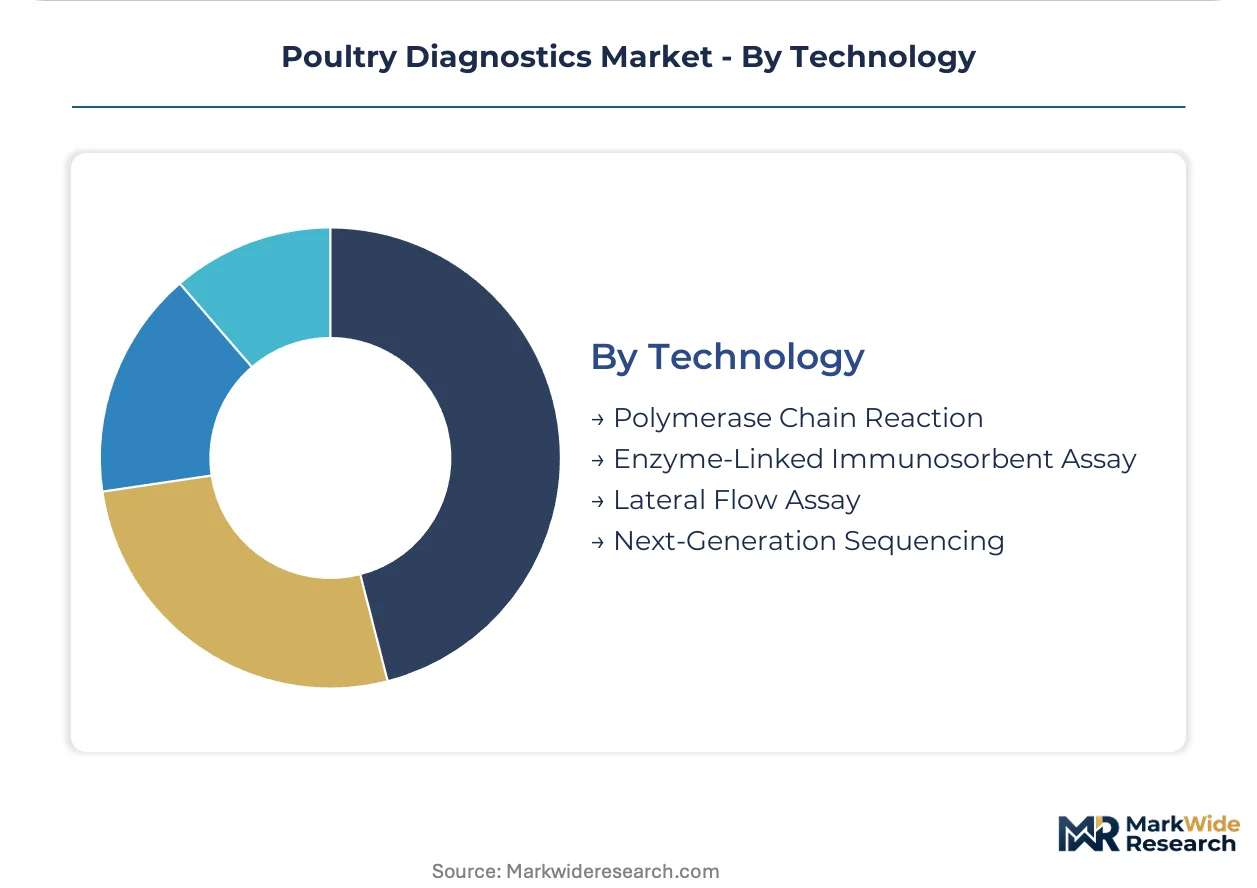
Technology:
Maturity gradients separate legacy enzyme-based methods from emerging sequencing platforms.
- Polymerase Chain Reaction:Thermocycler-based nucleic acid amplification delivers quantitative pathogen load data. USDA APHIS surveillance mandates compress turnaround requirements from days to hours, forcing laboratory platform migrations.
- Lateral Flow Assay:Immuno-chromatographic strips enable point-of-use detection without laboratory infrastructure. Battery-powered devices gain traction at Brazilian farm perimeter checkpoints for immediate flock segregation commands.
- Enzyme-Linked Immunosorbent Assay:Plate-based antibody detection occupies mature margin pools with commoditized reagent competition.
- Next-Generation Sequencing:Whole-genome pathogen characterization supports variant tracking and epidemiological investigation.
Installed base favors enzyme-linked immunosorbent assay; capability investment favors polymerase chain reaction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Santos container terminals underwrite Brazil's dominance in poultry diagnostics, handling temperature-controlled reagent imports and processed sample exports that sustain São Paulo's laboratory networks.
United States
USDA APHIS surveillance mandates for avian influenza compress testing turnarounds from days to hours, forcing laboratories across Iowa and Arkansas to abandon culture-based methods. The National Poultry Improvement Program sustains baseline serological volume for pullorum-typhoid screening regardless of commodity price cycles. Diagnostic platform deployment concentrates in Georgia's poultry processing corridor, where integrated producers operate ISO 17025-accredited facilities for export certification.
Brazil
European Union and Saudi Arabian import protocols demand ISO 17025-accredited laboratory documentation, expanding third-party testing demand across São Paulo and Paraná processing corridors. ANVISA registration requirements for imported diagnostic reagents create regulatory friction that favors domestic supply chain development. Integrated producers in the western Paraná cluster deploy multiplex PCR panels at farm perimeter checkpoints to satisfy same-day flock segregation commands.
China
GB standards for avian pathogen detection align with OIE international trade certification requirements, shaping laboratory equipment procurement across Shandong and Jiangsu poultry belts. NMPA oversight of in-vitro diagnostic reagents imposes registration timelines that favor established platform suppliers. Yangtze River Delta diagnostic service providers consolidate testing contracts from layer operations seeking combined microbiology and molecular workflows.
Thailand
European Commission antimicrobial resistance monitoring mandates double analytical workload per sample, pushing layer operations toward full-service reference laboratories. The country's national agricultural regulator enforces pathogen surveillance protocols that sustain respiratory panel demand across Bangkok metropolitan processing zones. Subscription-based reagent procurement models displace transactional purchasing among medium-scale operations in the Central Plains region.
Germany
EMA-aligned veterinary medicinal product regulations shape diagnostic assay validation requirements for poultry respiratory pathogen panels. Federal state veterinary authorities in Lower Saxony enforce flock health documentation standards that sustain reference laboratory demand. Bavarian diagnostic service clusters integrate susceptibility testing with routine surveillance to satisfy emerging importer transparency requirements.
Poultry Diagnostics Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in reagent and consumable supply. The poultry diagnostics market structures around three layers: multinational life science conglomerates with full-platform portfolios, regional veterinary diagnostics specialists with assay bundling expertise, and niche reagent manufacturers serving government reference laboratories. Consolidation pressures intensify as ISO 17025 accreditation requirements favor capital-intensive quality management systems that exclude smaller independent operators. Strategic moves concentrate on molecular platform licensing agreements and reagent supply contracts with integrated poultry producers.
Among platform-integrated life science conglomerates, IDEXX Laboratories and Thermo Fisher Scientific exemplify the system-tier archetype through Latin American and government laboratory channel dominance respectively. Zoetis occupies a distinct position bridging vaccine and diagnostic bundling strategies that lock in veterinary clinic relationships across production corridors. These three anchors represent divergent competitive vectors: instrument-reagent integration, public sector supply contracting, and therapeutic-diagnostic combination positioning.
| Leading Market Players |
|---|
| IDEXX Laboratories |
| Zoetis |
| BioChek |
| Eurofins Ingenasa |
| Thermo Fisher Scientific |
| QIAGEN |
| Bioneer Corporation |
| Bionote |
| Gold Standard Diagnostics |
| Others |
Cost & Logistics Intelligence
Undercapacity across São Paulo's ISO 17025-accredited laboratory network drives reagent premium pricing and forces integrated producers toward captive in-house testing investments, compressing margins for independent diagnostic service providers dependent on third-party platform access.
Pricing Analysis
Volume-discount tiering structures separate multinational integrated producers capturing 40,000-test annual allotments from independent farms purchasing 200-test minimum orders. Price differentiation rests on ISO 17025 certification grade and multiplex panel customization depth. Cost compression in economy-tier lateral flow assays is intensifying because Brazilian distributors are consolidating procurement pools. Independent veterinary clinics exhibit highest price sensitivity; government reference laboratories demonstrate lowest sensitivity due to budget allocation stability.
Supply Chain Analysis
Upstream feedstock for nucleic acid extraction kits and thermostable polymerases draws from concentrated manufacturing in the United States, Germany, and South Korea. Critical inputs span oligonucleotide primers, fluorescent probe chemistries, and magnetic bead separation media. Single-source vulnerability concentrates in Taq polymerase supply chains anchored to proprietary strain repositories. Distribution runs through temperature-controlled logistics networks from Port of Santos to Paraná processing corridors, with last-mile delivery to farm perimeter checkpoints.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in point-of-care molecular device deployment, as Indonesian smallholder demand for smartphone-connected diagnostics creates serviceable niches outside incumbent platform ecosystems.
For Market Incumbents: Build regulatory certification moats through ANVISA registration acceleration and ISO 17025 scope expansion across São Paulo and Paraná corridors. Consolidate reagent supply contracts with integrated producers before point-of-care device commoditization erodes platform lock-in. Capacity addition in Southeast Asian distribution hubs counters emerging local manufacturers. For New Entrants and Emerging Players: Establish a beachhead in Indonesian smallholder farm networks through battery-powered LAMP devices with cloud connectivity, bypassing laboratory infrastructure gaps across Java and Sumatra. Penetration of underserved layer operations in Vietnam's Mekong Delta offers lowest competitive density. Go-to-market through veterinary cooperative bundling replaces direct sales force requirements. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among reagent subscription providers serving medium-scale Thai and Vietnamese layer operations. Long-term viability favors full-platform molecular diagnostic companies with government laboratory channel anchoring. Watch CRISPR-based assay development timelines as inflection indicator for platform displacement risk.| Strategic Initiative | Industry Significance |
|---|---|
| Multiplex PCR Panel Expansion | Brazilian integrated producers satisfy EU export certification timelines through single-reaction pathogen detection. |
| Point-of-Care Device Launch | Indonesian smallholders gain access to molecular diagnostics outside formal veterinary laboratory networks. |
| Reagent Subscription Model | Thai layer operations stabilize per-hen diagnostic costs amid feed price volatility through predictable procurement. |
| Blockchain Traceability Integration | Immutable diagnostic records satisfy emerging importer demands for antibiotic residue and pathogen-free certification. |
| CRISPR Assay Development | Guide RNA programmable platforms reduce avian influenza variant response timelines from months to weeks. |
Research Approach
Findings reconcile primary fieldwork against secondary review of USDA APHIS surveillance directives, OIE trade certification protocols, and ANVISA registration databases. Primary interviews engaged diagnostic laboratory directors, veterinary epidemiologists at integrated producers, reagent procurement managers, and ISO 17025 accreditation auditors. Secondary sources incorporated customs trade data for temperature-controlled reagent imports, SEC filings from platform-integrated life science conglomerates, and national agricultural regulator surveillance reports. Bottom-up testing volume estimates triangulated against top-down market sizing from equipment installation databases.
Forecast inputs span product type adoption curves, application-specific compliance mandates, end-user infrastructure investment cycles, and technology substitution rates across the projection horizon. Segmentation dimensions modeled include diagnostic modality, pathogen target category, flock scale tier, and regional regulatory cluster. CAGRs derive from logistic diffusion curves fitted to platform deployment rates and reagent consumption intensity per thousand birds. Industry-specific inputs incorporate avian influenza variant emergence patterns and corresponding regulatory response timelines.
Stress conditions across reagent import tariff exposure, cold-chain failure frequency, and technician training pipeline capacity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions regarding ISO 17025 accreditation expansion rates and multiplex panel clinical validation timelines. Disease outbreak frequency and corresponding surveillance mandate intensification represent primary revision risks. Cross-checking against OIE World Animal Health Information Database pathogen notification trends is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Rapid Oral Fluid Screening Device Market
Diagnostics
Asia-Pacific Radioimmunoassay Market
Diagnostics
D-Dimer Market
Diagnostics
Molecular Diagnostics Market
Diagnostics
Animal Diagnostics Market
Diagnostics
Europe in Vitro Diagnostics (IVD) Market
Diagnostics
Influenza Diagnostic Tests Market
Diagnostics
Global Non-Small Cell Lung Cancer Diagnostics Market
Diagnostics
Blood Glucose Testing Devices Market
Diagnostics
Prenatal Diagnostics Market
Diagnostics
Diabetes Testing System Market
Diagnostics
North America Thyroid Cancer Diagnostics Market
Diagnostics
Acute Ischemic Stroke Diagnosis Market
Diagnostics
Global Exocrine Pancreatic Insufficiency (EPI) Therapeutics and Diagnostics Market
Diagnostics
Singleplex Immunoassay Market
Diagnostics
South Korea in Vitro Diagnostics Market