
 UK Healthcare Consulting Market | 2026-2036
UK Healthcare Consulting Market Size, Share, and Industry Trends Forecast 2026-2036
UK Healthcare Consulting Market Insights
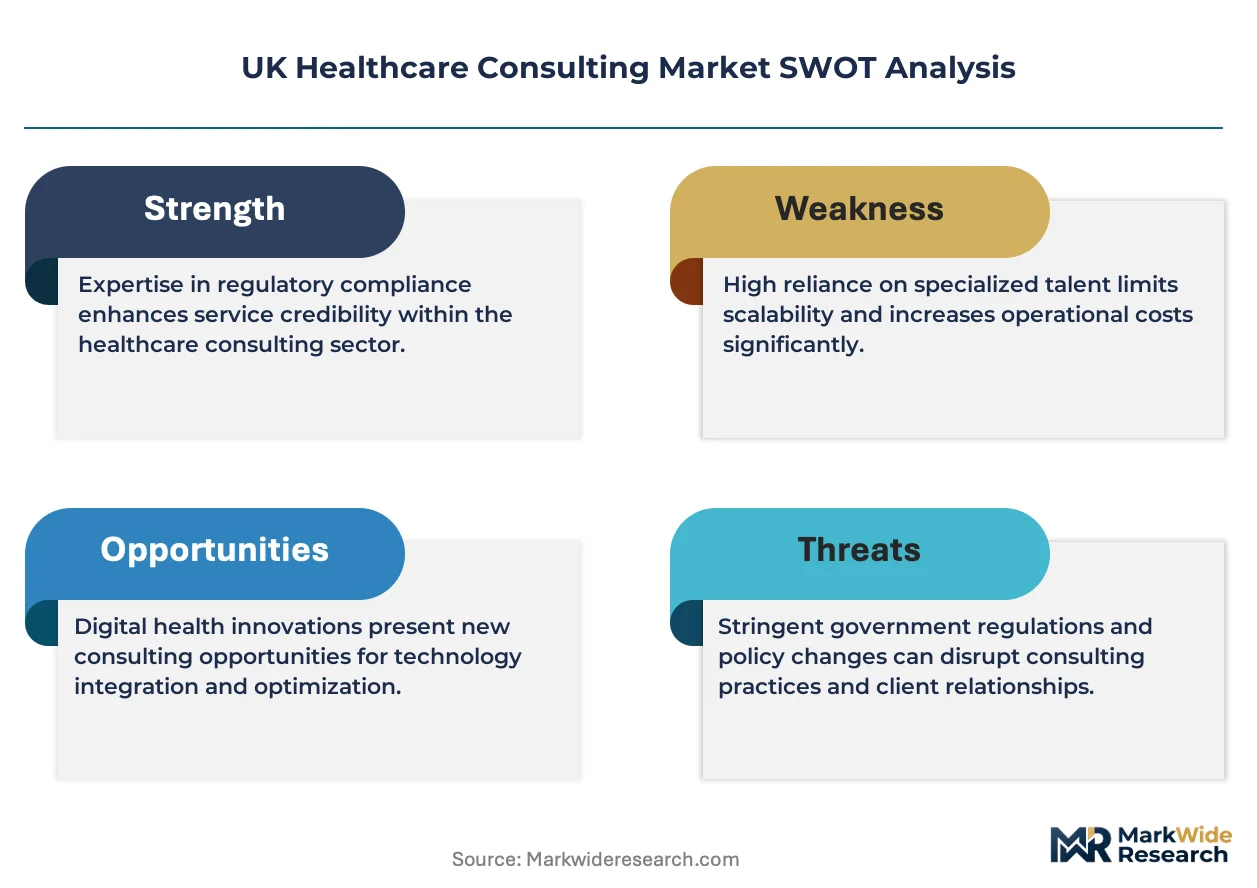
ISO 27001 certification is rotating as the decisive gate for vendor qualification across NHS procurement frameworks. Deloitte Touche Tohmatsu Limited leverages its cybersecurity practice to anchor multi-year digital transformation contracts with integrated care systems. PwC sustains dominance in financial advisory engagements where NHS trusts require turnaround expertise. Carnall Farrar specializes in operational improvement, occupying a distinct niche among UK-based boutique consultancies serving the National Health Service.
Healthcare consulting encompasses advisory services that apply clinical workflow methodologies, health informatics protocols, and regulatory compliance frameworks to improve patient outcomes and operational efficiency within medical institutions. These engagements deploy Lean Six Sigma process mapping, HL7 FHIR interoperability standards, and change management protocols to reduce waiting times and optimize resource allocation across acute and community settings. Digital Transformation commands the largest share of vendor revenue as NHS England accelerates its Federated Data Platform procurement. Strategy Consulting competes for margin pools where private equity-backed hospital groups seek buy-side due diligence. Regulatory Compliance represents the fastest-expanding segment as the Care Quality Commission tightens inspection regimes post-Health and Care Act 2022.
The Care Quality Commission enforces registration standards that mandate external consultancy for providers seeking conditional registration upgrades, while NHS England's procurement frameworks restrict vendor access to firms meeting Cyber Essentials Plus accreditation. The Health and Care Act 2022 shifts commissioning authority to integrated care boards, creating fragmented demand patterns that favor consultancies with established relationships across multiple ICS geographies. Stakeholders must monitor how the NHS Long Term Workforce Plan reshapes talent acquisition consulting requirements as domestic training pipelines expand and international recruitment faces new visa constraints.
Market Dynamics
The Health and Care Act 2022 has restructured commissioning accountability across England, fragmenting purchasing authority from NHS England to 42 integrated care boards and forcing consultancies to rebuild relationship architectures at the sub-regional level.
Growth Catalysts
- Federated Data Platform procurement:NHS England's national data infrastructure program mandates external advisory support for interoperability architecture, HL7 FHIR implementation, and cybersecurity hardening across acute trusts.
- Care Quality Commission inspection tightening:Conditional registration upgrades now require documented external consultancy engagement, creating mandatory demand for operational improvement and compliance remediation services.
- London and South East ICS consolidation:Vendor relationship rationalization in these dense health economies concentrates contract values with established advisory firms possessing multi-ICS coverage.
Market Restraints
- Cyber Essentials Plus accreditation barrier:NHS procurement frameworks restrict vendor access to firms meeting this cybersecurity baseline, excluding smaller boutiques lacking certification investment capacity.
- Talent pipeline constriction:The NHS Long Term Workforce Plan's expansion of domestic clinical training reduces immediate demand for international recruitment consulting as trusts pivot to internal pipeline development.
- Commissioning fragmentation:The shift to integrated care boards creates inconsistent procurement timelines and specification variance across England's 42 ICS geographies, raising bid preparation costs for national players.
Strategic Opportunities
- Midlands and North of England ICS penetration:These regions exhibit lower consultancy saturation than London and the South East, offering first-mover advantages for firms establishing ICS board relationships.
- Private equity hospital buy-side advisory:Financial due diligence and post-acquisition integration services for PE-backed hospital group consolidation represent underdeveloped margin pools outside NHS contracting.
- ISO 27001 certification services:Advisory practices can productize cybersecurity certification preparation for smaller consultancies seeking NHS framework eligibility, creating a services-to-services revenue stream.
Industry Challenges
- HL7 FHIR technical specialist scarcity:Health informatics expertise for interoperability implementation concentrates in a narrow talent pool, constraining project velocity and inflating day-rate costs.
- Legacy EHR integration complexity:Digital transformation engagements require navigation of heterogeneous electronic health record architectures across trusts with divergent procurement histories, extending project timelines.
- Change management resistance:Clinical workflow redesign encounters institutional friction from established practice patterns, demanding extended stakeholder engagement periods that compress project margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Healthcare Consulting Market |
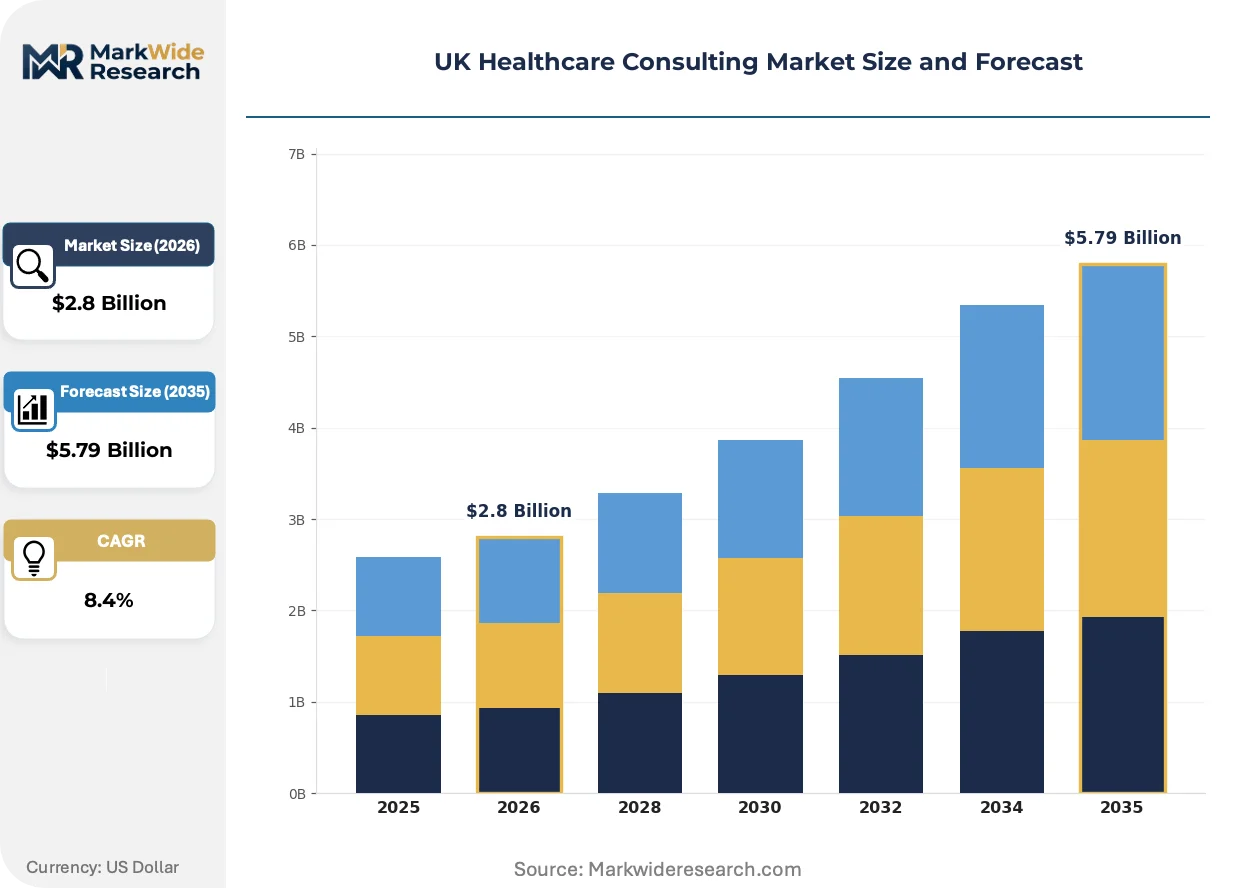
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.79 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Strategy Consulting, Digital Transformation, Regulatory Compliance, Operational Improvement, Risk Management, Financial Advisory Application: Patient Experience Enhancement, Clinical Workflow Optimization, Telemedicine Integration, Data Analytics, Supply Chain Management, Talent Acquisition End User: Hospitals, Diagnostic Laboratories, Pharmaceutical Firms, Biotech Startups, Medical Device Manufacturers, Public Health Agencies Delivery Model: Onsite Consulting, Remote Advisory, Hybrid Engagement, Project-Based, Managed Services, Training & Development |
| Companies Covered | Accenture, Deloitte Touche Tohmatsu Limited, Cognizant, Ernst & Young, International Business Machines Corporation, Bain & Company, Inc., HCL Technologies Limited, PwC, Carnall Farrar, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Healthcare Consulting Market Trends and Innovations
Advisory delivery models are compressing toward embedded, continuous engagement structures as NHS clients abandon discrete project procurement in favor of multi-year transformation partnerships with outcome-linked fee mechanisms.
Remote patient monitoring infrastructure is miniaturizing sensor arrays and connectivity protocols for home-based chronic disease management. Acute trusts in England are deploying these systems to reduce emergency admission volumes. The technology is miniaturizing the traditional hospital-at-home care boundary, creating demand for workflow redesign consultancy that bridges community and acute settings.
The Health and Care Act 2022's integrated care board formation mandates system-level financial planning and population health management capabilities that individual trusts previously outsourced separately. This regulatory consolidation forces consultancies to restructure service lines around ICS geography rather than institutional client boundaries. Operational improvement advisory now requires multi-site delivery expertise spanning primary, community, and acute interfaces.
Outcome-based contracting is displacing time-and-materials pricing in NHS digital transformation procurement. Integrated care boards now specify measurable waiting time reduction, readmission rate improvement, or workforce productivity targets as payment triggers. This shift is most visible in London ICS frameworks, where payment-at-risk mechanisms now exceed 30% of total contract value in major advisory awards.
UK Healthcare Consulting Market Segmentation
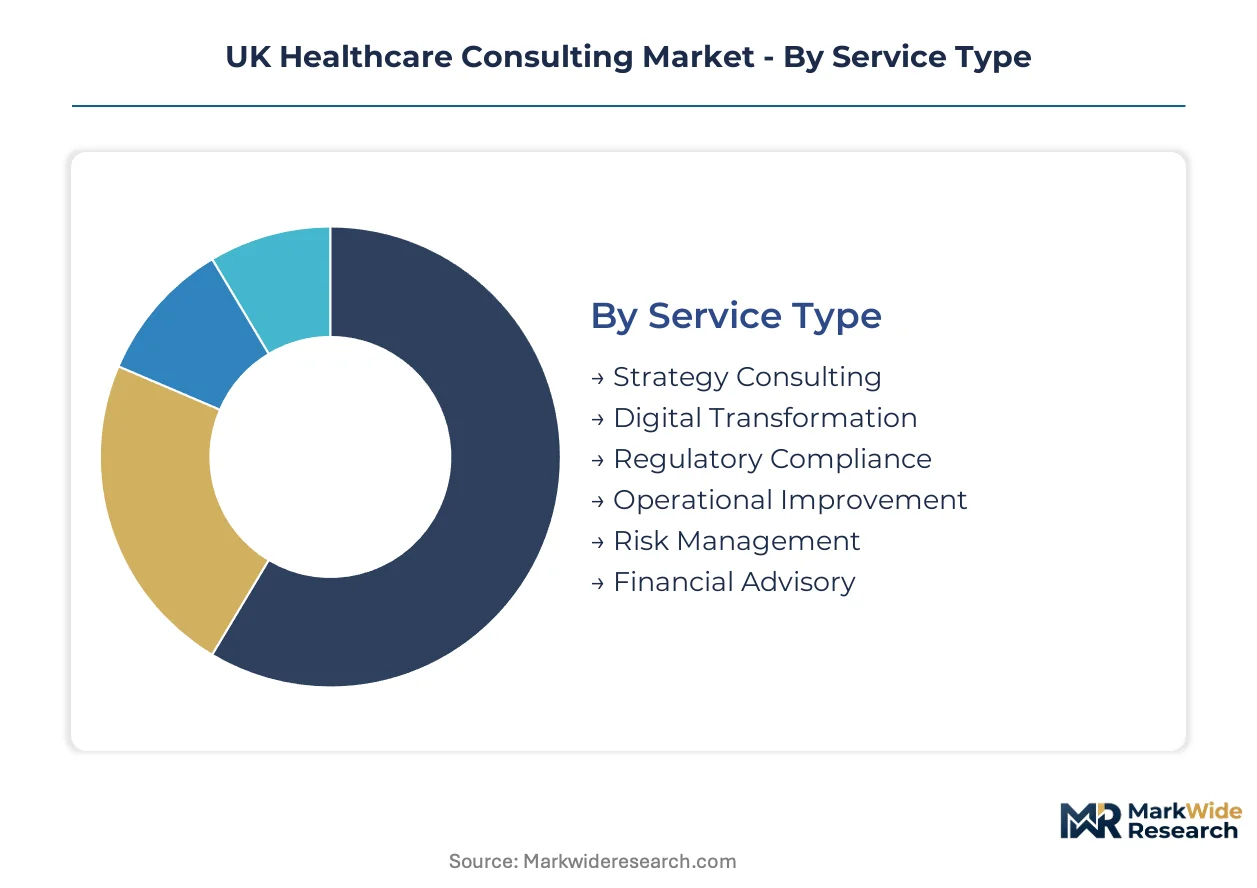
Segmentation reveals how NHS procurement frameworks and integrated care board structures concentrate vendor revenue across distinct service lines. Understanding these divides exposes where consultancies must build credential portfolios to qualify for framework access.
Service Type:
Margin pools concentrate in multi-year digital transformation partnerships where outcome-based fee mechanisms now exceed 30% of contract value in London ICS frameworks.
- Strategy Consulting:Advisory services encompassing market entry planning, merger integration, and portfolio optimization for private equity-backed hospital groups. Demand concentrates among London-based integrated care systems consolidating vendor relationships across acute and community settings.
- Digital Transformation:Federated Data Platform architecture, HL7 FHIR interoperability implementation, and cybersecurity hardening for acute trusts. NHS England's national data infrastructure program mandates external advisory support, concentrating procurement among firms with ISO 27001 certification.
- Regulatory Compliance:Care Quality Commission registration upgrades and conditional remediation documentation.
- Operational Improvement:Lean Six Sigma process mapping and waiting time reduction programs.
- Risk Management:Clinical governance frameworks and patient safety incident response protocols.
- Financial Advisory:Turnaround expertise and system-level financial planning for integrated care boards.
The dominant share belongs to Digital Transformation, while Regulatory Compliance is closing the gap fastest.
Application:
Volume concentrates where clinical workflow redesign intersects with federated data infrastructure deployment.
- Patient Experience Enhancement:Journey mapping and satisfaction metric optimization across primary and acute interfaces. Demand clusters in South East ICS geographies where population density justifies dedicated patient engagement programs.
- Clinical Workflow Optimization:Process re-engineering to reduce emergency admission volumes and optimize resource allocation. Remote patient monitoring infrastructure miniaturization is creating demand for workflow consultancy bridging community and acute boundaries.
- Telemedicine Integration:Virtual consultation platform deployment and reimbursement pathway structuring.
- Data Analytics:Population health management and predictive risk stratification capabilities.
- Supply Chain Management:Procurement rationalization and inventory optimization for medical device flows.
- Talent Acquisition:Workforce planning advisory constrained by the NHS Long Term Workforce Plan's pivot toward domestic pipeline development.
Clinical Workflow Optimization holds the largest engagement volume, with Patient Experience Enhancement gaining share fastest.
End User:
Customer type determines procurement pathway complexity, with NHS trusts requiring Cyber Essentials Plus accreditation while private entities prioritize turnaround speed.
- Hospitals:Acute trusts and foundation trusts consuming the majority of digital transformation and operational improvement advisory. NHS England's procurement frameworks restrict vendor access to certified firms, fragmenting demand across 42 integrated care board geographies.
- Diagnostic Laboratories:Pathology network consolidation and automation advisory for hub-and-spoke reconfigurations.
- Pharmaceutical Firms:Market access strategy and NHS reimbursement pathway navigation.
- Biotech Startups:Regulatory submission support and health technology assessment preparation.
- Medical Device Manufacturers:CE marking transition under EU MDR and UKCA conformity processes.
- Public Health Agencies:Population health management and outbreak response planning.
Hospitals command the dominant procurement volume, though Pharmaceutical Firms are expanding advisory budgets fastest.
Delivery Model:
Maturity differentiates established consultancies with embedded continuous engagement structures from project-based competitors.
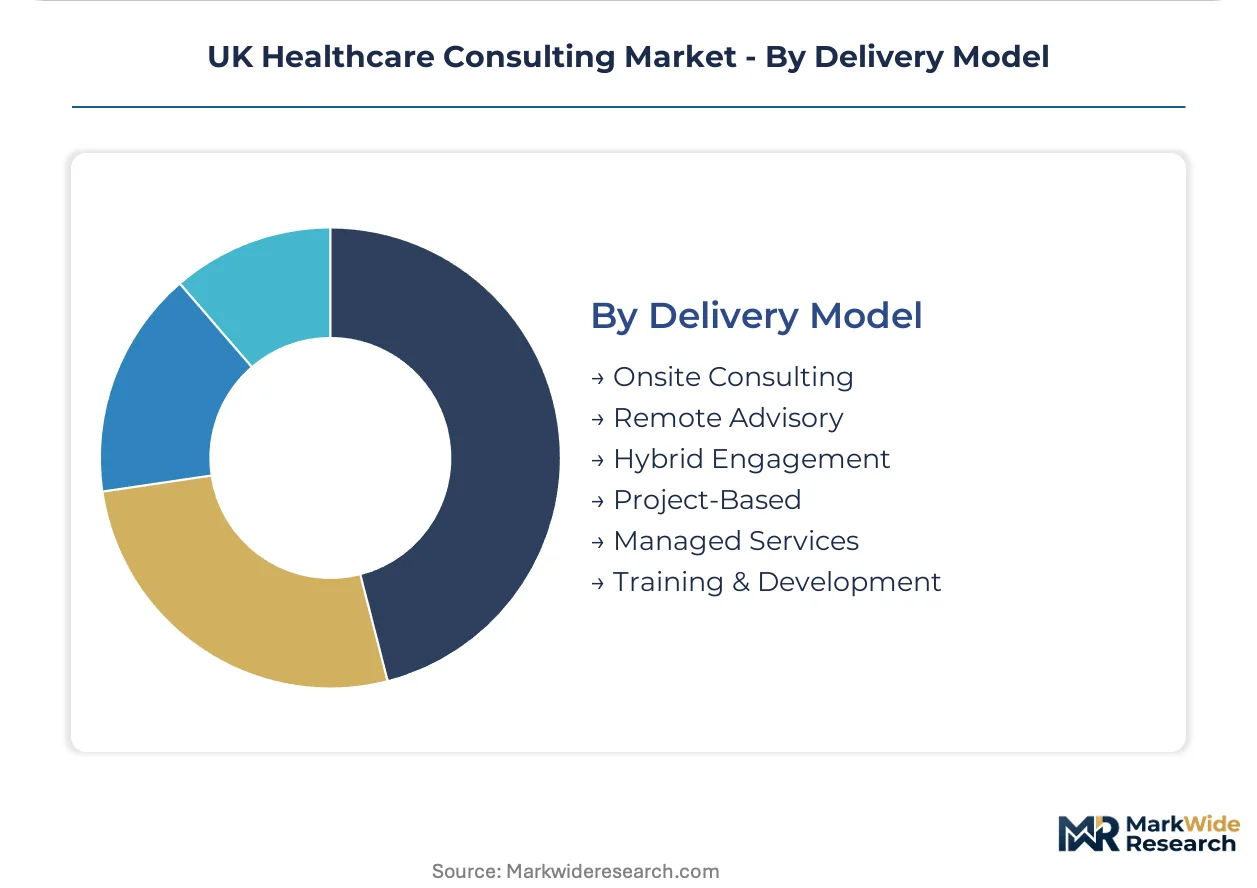
- Onsite Consulting:Embedded advisory teams resident within client facilities for transformation program duration. NHS clients in London and the South East increasingly specify multi-year partnerships over discrete project procurement.
- Remote Advisory:Virtual delivery of regulatory compliance and financial advisory services.
- Hybrid Engagement:Alternating onsite and remote presence calibrated to project phase requirements.
- Project-Based:Discrete scope engagements with defined deliverables and time-and-materials pricing.
- Managed Services:Continuous operational support with outcome-linked fee mechanisms.
- Training & Development:Capability building for internal NHS consulting functions.
Hybrid Engagement captures the largest contract flow, with Managed Services expanding most quickly as outcome-based contracting displaces time-and-materials structures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Health and Care Act 2022 redistributes commissioning authority across England's integrated care systems, reshaping where advisory services concentrate procurement spend.
London and South East
Integrated care systems here consolidate vendor relationships fastest, with outcome-based contracts exceeding 30% at-risk payment structures. NHS England's procurement frameworks restrict access to Cyber Essentials Plus certified firms. The capital's density of acute trusts creates concentrated demand for digital transformation partnerships.
Midlands
Lower consultancy saturation offers first-mover advantages for firms establishing integrated care board relationships. The Care Quality Commission's tightened inspection regimes drive mandatory external advisory for conditional registration upgrades. Birmingham's hospital networks anchor operational improvement contract flows.
North of England
Commissioning fragmentation creates inconsistent procurement timelines across Manchester, Leeds and Newcastle ICS geographies. The NHS Long Term Workforce Plan's domestic training expansion reduces immediate international recruitment consulting demand. Sheffield's teaching hospitals pilot federated data platform architecture.
Scotland
NHS Scotland's separate procurement frameworks operate outside England's integrated care board structures. The country's national health service maintains distinct cybersecurity accreditation requirements. Edinburgh's digital health innovation cluster attracts workflow redesign advisory for remote patient monitoring deployment.
Wales
Smaller integrated care system scale limits contract values compared to English counterparts. Welsh health boards prioritize operational improvement over large-scale digital transformation. Cardiff's university health board partnerships concentrate clinical workflow optimization projects.
UK Healthcare Consulting Market Competitive Landscape
Player mix skews toward diversified professional services networks with established NHS framework access. Tiered competition separates Big Four accounting-derived consultancies from specialized healthcare boutiques and global technology integrators. Strategic archetypes include cybersecurity-certified generalists, NHS-dedicated operational specialists, and cloud-native digital transformation vendors. Competitive moves center on multi-year partnership structures and outcome-linked fee mechanisms displacing time-and-materials pricing.
Within the Big Four tier, Deloitte Touche Tohmatsu Limited and PwC anchor distinct positioning—Deloitte leveraging cybersecurity practice depth for digital infrastructure awards, PwC sustaining financial advisory dominance where trusts require turnaround expertise. Carnall Farrar exemplifies the NHS-specialized boutique archetype, occupying operational improvement niches that global networks cannot replicate. These three represent the competitive spectrum: diversified platform, financial advisory specialist, and domain-focused independent.
| Leading Market Players |
|---|
| Accenture |
| Deloitte Touche Tohmatsu Limited |
| Cognizant |
| Ernst & Young |
| International Business Machines Corporation |
| Bain & Company, Inc. |
| HCL Technologies Limited |
| PwC |
| Carnall Farrar |
| Others |
Pricing and Supply Chain Analysis
Ninety-day certification lead times for Cyber Essentials Plus accreditation concentrate pricing power among established consultancies already credentialed for NHS framework access. This inventory of qualified vendors shapes how integrated care boards negotiate multi-year transformation partnerships across England's fragmented procurement landscape.
Pricing Analysis
Certification level creates the primary spread between day-rate tiers, with ISO 27001-accredited firms commanding premium positioning against uncredentialed competitors. Project-based engagements with time-and-materials structures dominate smaller advisory awards, while outcome-based contracts with payment-at-risk mechanisms now anchor major digital transformation procurements in London ICS frameworks. Pricing pressure stems from commissioning fragmentation across 42 integrated care boards, which extends sales cycles and raises bid preparation costs. Private equity-backed hospital groups exhibit lowest price sensitivity given turnaround urgency, whereas NHS trusts facing fixed budgets negotiate hardest on rate cards.
Supply Chain Analysis
Specialist talent inventory—particularly HL7 FHIR implementation expertise—constrains project velocity and inflates day-rate costs across the advisory value chain. Supply draws from a narrow pool of health informatics practitioners concentrated in London, Manchester, and Edinburgh university clusters. Raw material dependencies include clinical workflow methodologies licensed from US-based improvement institutes, proprietary cybersecurity frameworks from global technology vendors, and change management protocols adapted from manufacturing sector toolkits. Single-source vulnerability sits with the limited cohort of accredited certification bodies capable of delivering Cyber Essentials Plus assessment. Distribution runs through NHS England's procurement frameworks, which gate vendor access and concentrate contract flow among pre-qualified advisory networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UK healthcare consulting market rewards firms possessing scarce certification credentials and established integrated care board relationships, with capability gaps in health informatics and cybersecurity advisory creating structural barriers for unprepared competitors.
For Market Incumbents: Secure multi-year partnership extensions with London and South East integrated care systems before commissioning fragmentation hardens into entrenched vendor relationships. Invest in HL7 FHIR specialist recruitment to address technical talent scarcity constraining project delivery. Deepen ISO 27001 certification services to capture advisory revenue from smaller boutiques seeking NHS framework eligibility. For New Entrants and Emerging Players: Anchor in Midlands and North of England ICS geographies where consultancy saturation remains below London levels and relationship architectures are still forming. Target operational improvement advisory for conditional Care Quality Commission registration upgrades, where mandatory external consultancy creates predictable demand. Pursue ISO 27001 certification preparation as a services-to-services revenue stream rather than competing directly for transformation contracts. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because the Health and Care Act 2022's commissioning fragmentation favors scaled advisory networks capable of covering multiple ICS geographies. Acquisition candidates include NHS-specialized boutiques with embedded operational improvement methodologies and established CQC remediation track records. Monitor Federated Data Platform procurement awards as the signal indicating which advisory networks have secured anchor positioning in national data infrastructure programs.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 27001 Certification Investment | Unlocks NHS England framework access for digital transformation contract eligibility. |
| HL7 FHIR Specialist Recruitment | Addresses technical scarcity constraining Federated Data Platform implementation velocity. |
| ICS Board Relationship Architecture | Captures outcome-based contract flow as commissioning authority fragments regionally. |
| Operational Improvement Methodology Productization | Creates scalable advisory services for Care Quality Commission conditional registration upgrades. |
| Cybersecurity Certification Services Launch | Generates services-to-services revenue from boutiques seeking NHS procurement eligibility. |
Research Methodology
Desk research of NHS procurement frameworks, integrated care board commissioning strategies, and Care Quality Commission inspection protocols preceded structured interviews with NHS trust digital directors, ICS chief finance officers, healthcare consultancy partners, and health informatics specialists. Secondary validation drew from NHS England policy documents, Health and Care Act 2022 statutory instruments, and cybersecurity accreditation body records. Bottom-up engagement sizing across service lines and top-down market reconstruction from framework award values were triangulated to establish volume estimates.
Variance decomposition across service type, application, end user, and delivery model segmentation dimensions drove analytical framework construction over the projection horizon. CAGRs were derived from weighted average growth assumptions calibrated to procurement pipeline visibility and regulatory implementation timelines. Forecast inputs incorporated Federated Data Platform deployment schedules, integrated care board consolidation patterns, and domestic clinical training pipeline expansion trajectories from the NHS Long Term Workforce Plan.
Material uncertainties—Health and Care Act regulatory refinements, cybersecurity accreditation requirement changes, and integrated care board merger activity—sit outside the modeled envelope. Forecasts reflect assumptions about procurement framework stability and talent pipeline development that may shift with policy intervention. Revision becomes warranted when Federated Data Platform implementation delays or ICS restructuring accelerates beyond baseline scenarios.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Consulting
Africa Pharmaceutical Regulatory Affairs Market
Healthcare Consulting
Pharmaceutical Regulatory Affairs Market
Healthcare Consulting
Healthcare ERP Consulting Services Market
Healthcare Consulting
Global Regulatory Affairs Market
Healthcare Consulting
Healthcare Contract Sales Organizations Market
Healthcare Consulting
Global Healthcare IT Consulting Market
Healthcare Consulting
Global Public Sector Consulting and Advisory Services Market
Healthcare Consulting
Global Healthcare Consulting Services Market
Healthcare Consulting
Healthcare Regulatory Affairs Outsourcing Market
Healthcare Consulting
Global Strategic Consulting Services Market
Healthcare Consulting
Global Medical Device Regulatory Affairs Outsourcing Market
Healthcare Consulting
Europe Medical Device Regulatory Affairs Outsourcing Market
Healthcare Consulting
Italy Operations Service Consulting Market
Healthcare Consulting
Consulting Service Market