
 Global Fluorine Carbon Coatings Market | 2026-2036
Global Fluorine Carbon Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Global Fluorine Carbon Coatings Market Intelligence
The European Union's REACH regulation, with its stringent substance evaluation requirements, is consolidating the supply base for fluorine carbon precursors. Major chemical producers like Daikin Industries leverage their deep R&D in fluoropolymers to navigate these complex rules. In contrast, coatings specialists such as AkzoNobel differentiate through formulation expertise and application support for industrial clients. PPG Industries sustains its market position through a vast distribution network serving aerospace and automotive end-users.
Fluorine carbon coatings are high-performance polymer finishes characterized by strong carbon-fluorine bonds, providing exceptional chemical resistance and thermal stability. These materials are applied using methods like spray coating or electrostatic powder coating to protect substrates in harsh environments. Among product types, PVDF coatings lead in architectural applications due to superior UV resistance. In terms of application, the non-stick surfaces segment is a mature market, while anti-corrosion coatings for chemical processing represent a high-margin opportunity.
Regulatory oversight from bodies like the US Environmental Protection Agency (EPA) and China's Ministry of Ecology and Environment (MEE) shapes material formulation. Concurrently, compliance with Europe's RoHS directive restricts specific hazardous substances in finished electrical goods. Stakeholder success will depend on anticipating future restrictions on per- and polyfluoroalkyl substances (PFAS) and investing in next-generation, compliant polymer technologies.
Market Dynamics
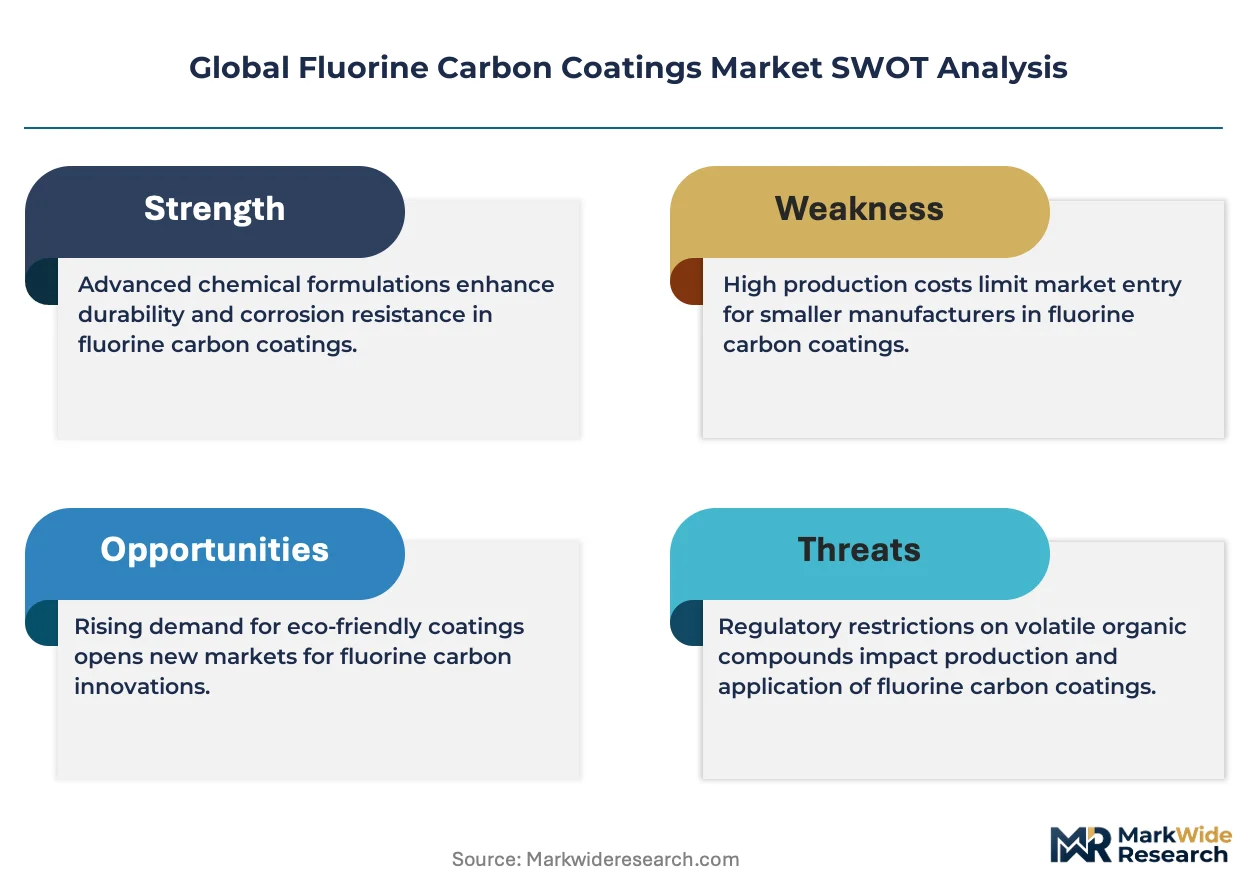
The primary force shaping the fluorine carbon coatings market is the global regulatory pressure on per- and polyfluoroalkyl substances (PFAS). This is creating a fundamental split between legacy formulations and investment in next-generation, compliant polymer technologies to meet future market access requirements.
Growth Catalysts
- Aerospace Sector Demand:The requirement for lightweight, high-performance coatings on aircraft components, such as turbine blades and structural parts, drives adoption for improved fuel efficiency and durability.
- Industrial Corrosion Resistance:Concentrated demand from manufacturing hubs in China and Germany for protecting chemical processing equipment, storage tanks, and pipelines from aggressive chemicals sustains a core market segment.
- Architectural Specifications:The use of PVDF coatings for exterior building facades and roofing is specified for its exceptional UV resistance and color retention, particularly in regions with high solar exposure.
Market Restraints
- Regulatory Scrutiny:Intensifying regulations from bodies like the US EPA and the EU's REACH framework concerning PFAS chemicals create significant compliance costs and threaten to restrict the use of key fluoropolymer precursors.
- High Raw Material Costs:The manufacturing process for fluoropolymers relies on expensive and energy-intensive production of precursors, creating a high-cost basis that limits adoption in price-sensitive applications.
- Substitution from Alternatives:In certain moderate-performance applications, fluorine carbon coatings face competition from lower-cost alternatives such as high-performance epoxy, polyurethane, or silicone-based coatings.
Strategic Opportunities
- Next-Generation Polymers:Developing and commercializing novel, non-PFAS or short-chain fluoropolymers that meet regulatory standards while retaining high-performance characteristics represents a significant growth pathway.
- High-Margin Niche Applications:Expanding into severe-service environments, such as coatings for offshore oil and gas platforms or internal linings for semiconductor manufacturing equipment, offers high-margin opportunities.
- Emerging Economies:Industrialization and infrastructure development in Southeast Asian nations create new demand for anti-corrosion and architectural coatings, representing an underpenetrated geographic market.
Industry Challenges
- Reformulation Complexity:The process of reformulating coating systems to comply with evolving substance restrictions is a major operational hurdle, involving extensive R&D, testing, and customer requalification.
- Specialized Application Skills:Proper application of high-performance systems like electrostatic powder coatings requires trained technicians, and a shortage of skilled labor can lead to performance failures and warranty claims.
- Precursor Supply Concentration:The supply of critical fluorochemical precursors is concentrated among a small number of global producers, exposing coating formulators to potential price volatility and supply chain disruptions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Fluorine Carbon Coatings Market |
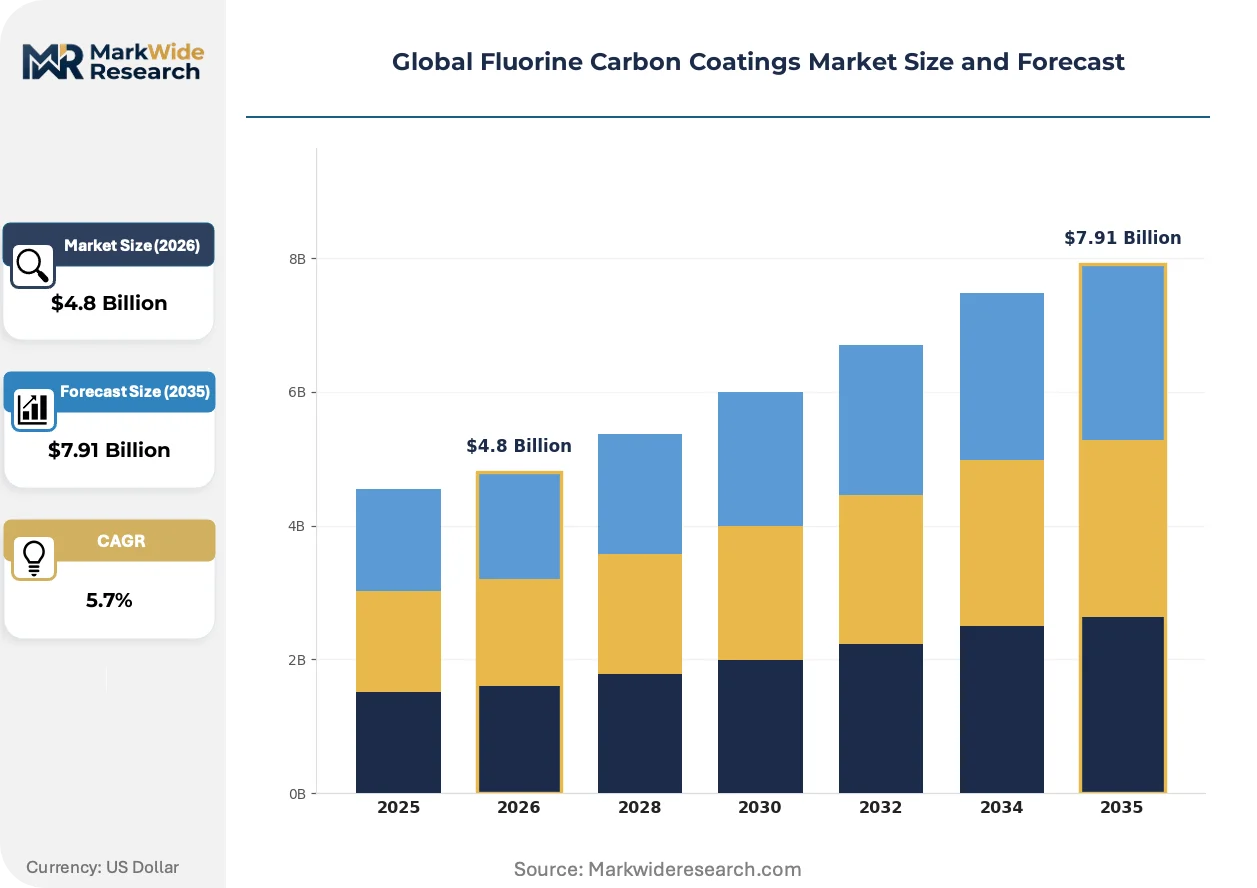
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PTFE, FEP, PFA, ETFE, PVDF, MFA Application: Anti-Corrosion, Non-Stick Surfaces, Electrical Insulation, Chemical Processing, Automotive Components, Aerospace Parts End User: Chemical Manufacturers, Electrical Equipment Producers, Vehicle Assemblers, Aircraft Manufacturers, Packaging Companies, Construction Firms Coating Technology: Spray Coating, Electrostatic Powder Coating, Dip Coating, Roll Coating, Plasma Polymerization, Chemical Vapor Deposition |
| Companies Covered | AGC, AkzoNobel, PPG Industries, Sherwin-Williams, Daikin Industries, Beckers Group, Chengmei Coating, Dongfu Chemical, DuPont, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Fluorine Carbon Coatings Market Strategic Shifts & Innovations
Material science innovation is accelerating, driven by the dual mandate of enhancing performance in harsh environments and complying with a rapidly tightening global regulatory framework for fluorochemicals. This dynamic is pushing development toward more sustainable and specialized formulations.
Bio-based and recycled-content fluoropolymers are emerging as a key innovation area aimed at improving the sustainability profile of coatings. Specifiers in green building projects and consumer electronics are beginning to evaluate these materials, driven by corporate environmental, social, and governance (ESG) targets. This shift toward circularity is absorbing R&D investment that was previously allocated solely to performance enhancement, rebalancing innovation priorities.
The European Union’s proposed universal PFAS restriction under its REACH regulation represents a landmark policy shift. This action compels a full-spectrum re-evaluation of fluoropolymer use, moving beyond specific substances to address the entire chemical class. The semiconductor and medical device sectors are most affected, actively seeking essential-use designations due to the current lack of viable, high-purity alternatives for critical applications.
A notable behavioral shift is occurring where asset owners in infrastructure and energy are specifying coatings based on warranted service life and total cost of ownership. This model displaces traditional transactional sales, creating a preference for suppliers who can offer long-term performance guarantees and integrated inspection services. This trend is most advanced in North American and European markets for critical public works and industrial projects.
Global Fluorine Carbon Coatings Market Segmentation
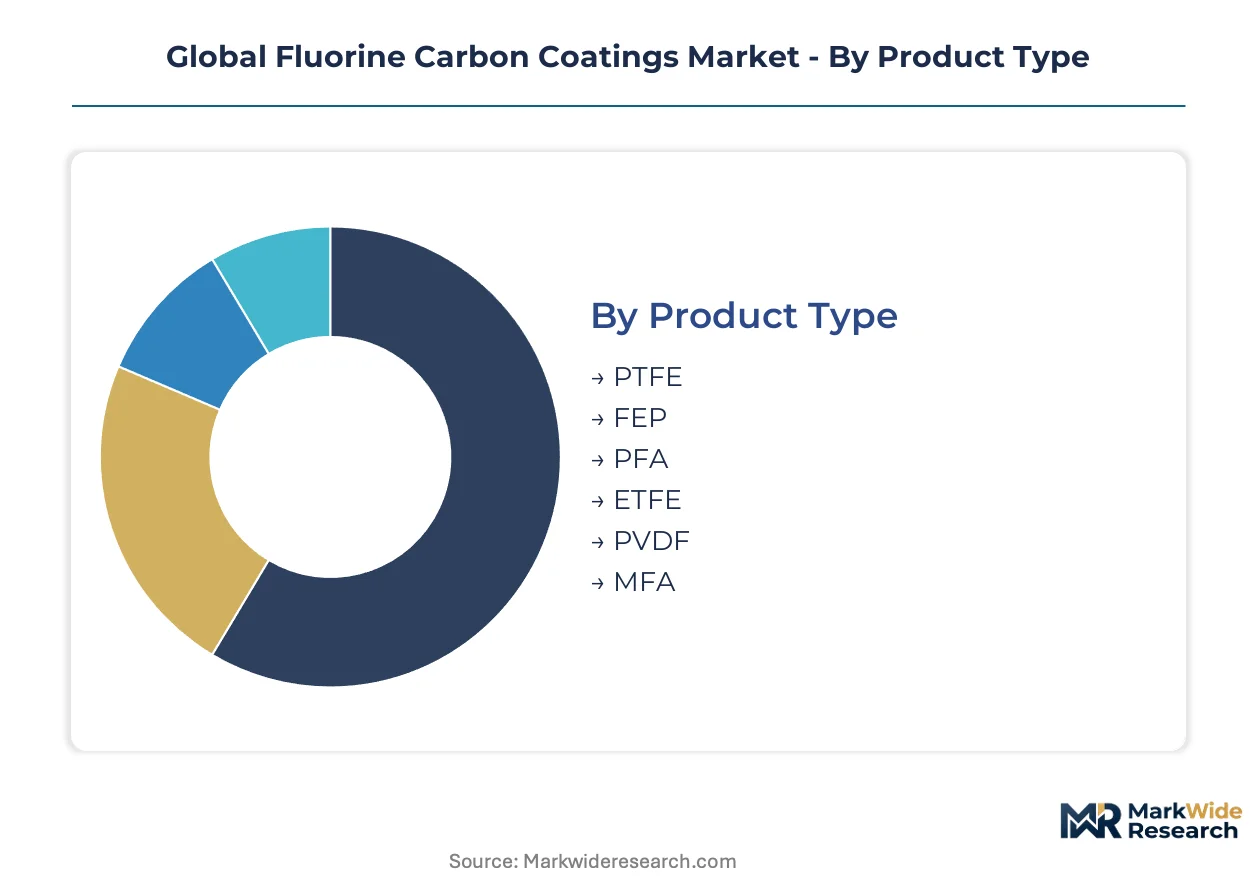
The global fluorine carbon coatings market is analyzed across several critical dimensions, revealing the diverse drivers and specific performance needs influencing material selection. This granular segmentation provides a detailed understanding of where demand concentrates and how specialized requirements shape product development. Stakeholders evaluate coatings based on chemical properties, application methods, and end-use environments.
Product Type:
Buyers of fluorine carbon coatings differentiate their material choices based on specific performance requirements and processing capabilities.
- PTFE (Polytetrafluoroethylene):This fluoropolymer offers exceptional non-stick properties, low friction, and chemical inertness. Demand for PTFE coatings remains strong in the mature non-stick surfaces segment, particularly for consumer cookware and industrial processing equipment.
- PVDF (Polyvinylidene Fluoride):Known for superior UV resistance, weatherability, and color retention, PVDF coatings are widely specified in architectural applications. Construction firms in regions with high solar exposure, like the Middle East and Southeast Asia, drive significant demand.
- FEP (Fluorinated Ethylene Propylene):FEP provides excellent chemical resistance and high-temperature performance, suitable for harsh industrial conditions.
- PFA (Perfluoroalkoxy):PFA offers high continuous service temperature and chemical resistance, often used in semiconductor manufacturing.
- ETFE (Ethylene Tetrafluoroethylene):This material combines strength, transparency, and UV resistance, finding use in architectural membranes and solar panels.
- MFA (Methylfluoroalkoxy):MFA delivers high thermal stability and chemical resistance, positioning it for specialized industrial linings.
Volume sits with PTFE; growth tilts toward PVDF.
Application:
Application segments for fluorine carbon coatings are defined by the functional needs of the substrate and the environmental challenges it faces.
- Anti-Corrosion:These coatings protect metal surfaces from chemical attack and environmental degradation in harsh industrial settings. Concentrated demand from manufacturing hubs in China and Germany for chemical processing equipment drives this high-margin segment.
- Aerospace Parts:High-performance, lightweight coatings for aircraft components, including turbine blades and structural elements, enhance fuel efficiency and durability. Aircraft manufacturers globally prioritize these advanced materials for critical airframe and engine applications.
- Non-Stick Surfaces:This mature segment leverages low friction properties for consumer goods and industrial molds.
- Electrical Insulation:Fluorine carbon coatings provide dielectric strength and thermal stability for wiring and electronic components.
- Chemical Processing:Coatings ensure chemical inertness and corrosion resistance for tanks, pipes, and reactors.
- Automotive Components:These applications require wear resistance and chemical protection for engine parts and chassis elements.
The largest share of demand originates from Anti-Corrosion, while Aerospace Parts exhibits the steepest expansion trajectory.
End User:
End-user industries for fluorine carbon coatings select products based on their operational environment, regulatory compliance needs, and required asset lifespan.
- Chemical Manufacturers:These companies require coatings for tanks, pipes, and reactors that withstand aggressive chemicals and high temperatures. Compliance with environmental regulations, like EU REACH, influences material selection for these critical assets.
- Aircraft Manufacturers:Specialized coatings are essential for aerospace components, providing lightweight, high-performance protection against extreme temperatures and corrosion. This sector demands stringent quality control and long-term performance guarantees for flight safety.
- Electrical Equipment Producers:These firms use coatings for insulation and protection of wires, cables, and electronic devices.
- Construction Firms:Building facades and roofing benefit from UV-resistant and weatherable fluorine carbon coatings.
- Packaging Companies:Non-stick and barrier properties are critical for food and industrial packaging applications.
- Vehicle Assemblers:Coatings protect automotive parts from wear, corrosion, and chemical exposure in engines and chassis.
Volume concentration is observed within Chemical Manufacturers, with Aircraft Manufacturers gaining share fastest.
Coating Technology:
The choice of coating technology for fluorine carbon materials is dictated by the substrate geometry, desired film thickness, and production scale requirements.
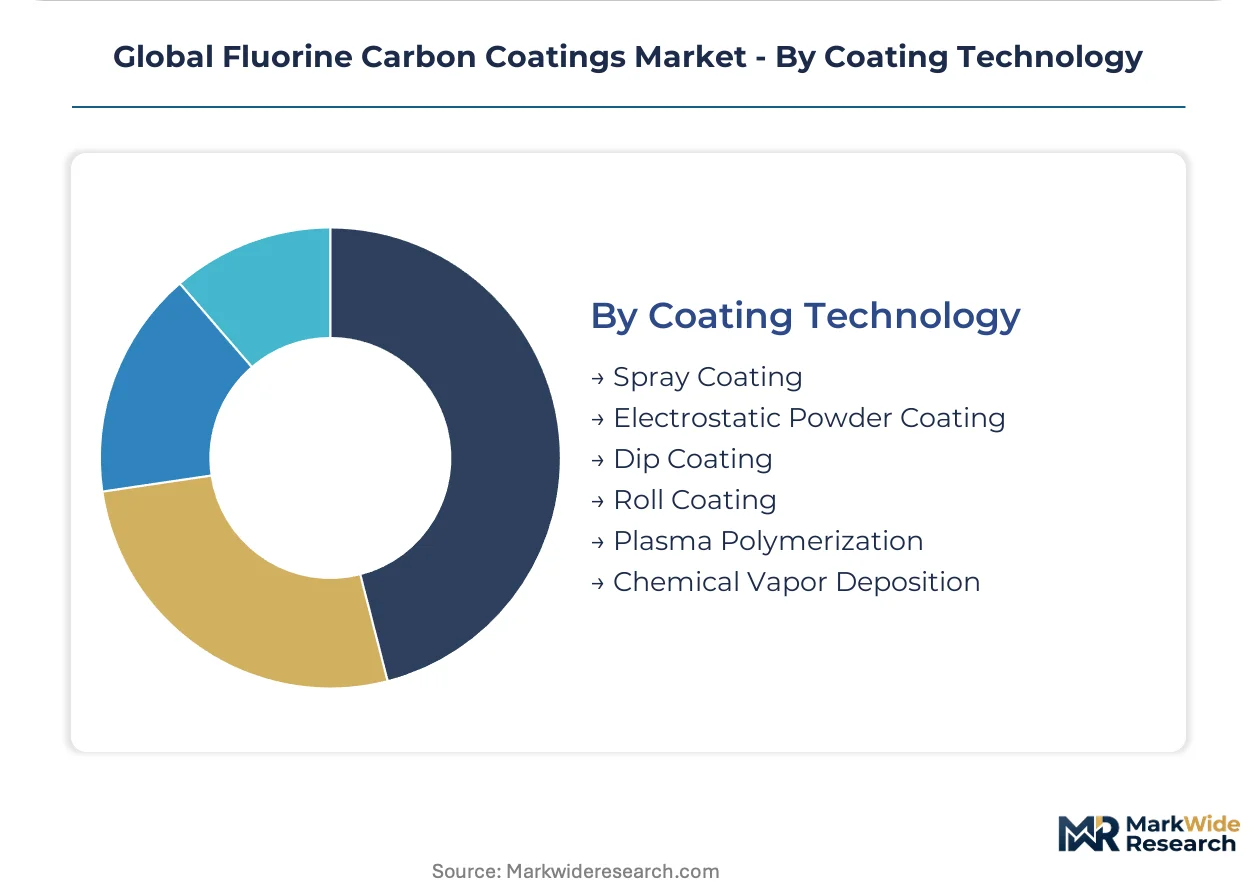
- Spray Coating:This versatile method applies liquid fluoropolymer formulations to complex geometries, offering flexibility in film thickness and coverage. Industrial facilities widely adopt spray coating for large-scale projects and intricate component protection.
- Electrostatic Powder Coating:This method applies dry powder fluoropolymers with high transfer efficiency, reducing waste and VOC emissions. Specialized application skills are necessary for optimal performance and uniform film deposition in industrial settings.
- Dip Coating:Substrates are immersed in a liquid fluoropolymer solution, providing uniform coverage for small, complex parts.
- Roll Coating:This technique applies coatings to flat substrates or continuous coils, suitable for high-volume production of sheets.
- Plasma Polymerization:This advanced method creates ultra-thin, highly adherent fluoropolymer films in a vacuum environment.
- Chemical Vapor Deposition:CVD forms high-purity, conformal fluoropolymer coatings for sensitive applications like semiconductors.
Spray Coating represents the largest volume, whereas Electrostatic Powder Coating is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones across China, particularly coastal manufacturing hubs, concentrate significant demand for anti-corrosion fluorine carbon coatings. These regions attract heavy industry and chemical processing, necessitating robust material protection for critical infrastructure. This focus on industrial growth and asset longevity shapes regional market dynamics.
China
Rapid industrial expansion and extensive infrastructure development in China fuel demand for anti-corrosion and architectural coatings. The Ministry of Ecology and Environment (MEE) implements increasingly stringent regulations on industrial emissions and material safety standards. Manufacturing clusters in the Yangtze River Delta and Guangdong province represent major consumption centers for these high-performance materials in diverse applications.
Germany
Germany's advanced manufacturing sector, especially automotive, aerospace, and chemical processing, drives demand for high-performance fluorine carbon coatings. European Union REACH regulations heavily influence material formulation and ensure supply chain compliance for German chemical producers. Industrial regions like North Rhine-Westphalia and Bavaria exhibit consistent requirements for durable surface protection and functional coatings.
United States
The robust aerospace and chemical manufacturing sectors in the United States require specialized fluorine carbon coatings for critical components. The US Environmental Protection Agency (EPA) closely monitors per- and polyfluoroalkyl substances (PFAS) in industrial processes, pushing for compliant alternatives. Manufacturing centers in Texas, the Pacific Northwest, and the Southeast show strong demand for these advanced protective finishes.
Japan
Japan's high-tech industries, including electronics, precision machinery, and automotive, utilize fluorine carbon coatings for their unique performance properties. The Ministry of Economy, Trade and Industry (METI) actively promotes sustainable manufacturing practices and advanced material innovation. Industrial zones around Tokyo, Osaka, and Nagoya concentrate companies seeking specialized surface solutions for demanding applications.
Global Fluorine Carbon Coatings Market Key Industry Players
North American and European producers anchor one tier of the fluorine carbon coatings market; Asian specialists hold another significant position. The market exhibits a tiered structure, combining large, diversified chemical manufacturers with specialized coating formulators. Global chemical giants, specialized fluoropolymer producers, and regional coating formulators represent key strategic archetypes. Companies actively pursue extensive R&D into compliant formulations, engage in strategic mergers and acquisitions for technology, and expand geographic reach to secure market share.
Among specialized fluoropolymer producers, Japan-based Daikin Industries exemplifies a focus on deep R&D to navigate complex regulatory landscapes and develop next-generation materials. Netherlands-headquartered AkzoNobel, a coatings specialist, differentiates through formulation expertise and application support for a wide array of industrial clients. United States-based PPG Industries sustains its market position through a vast distribution network, effectively serving diverse end-users across aerospace and automotive sectors. These companies collectively illustrate the varied approaches to market leadership, from raw material innovation to broad application support, within the fluorine carbon coatings industry.
| Leading Market Players |
|---|
| AGC |
| AkzoNobel |
| PPG Industries |
| Sherwin-Williams |
| Daikin Industries |
| Beckers Group |
| Chengmei Coating |
| Dongfu Chemical |
| DuPont |
| Others |
Cost & Logistics Intelligence
European Union’s REACH regulation and global PFAS restrictions gate market access for fluorine carbon coatings. This regulatory pressure mandates investment in compliant materials, thereby commanding premium-tier pricing for next-generation formulations.
Pricing Analysis
Premium pricing for short lead times reflects the high-performance demands of critical applications. The dominant pricing model involves contract-based long-term offtake for aerospace and chemical processing, with per-unit transactional pricing for architectural and consumer segments. Price differentiation stems from rigorous quality grade, specialized certification levels, and bundled after-sales application support. Upward pricing pressure results from significant R&D investments in compliant PFAS-free formulations and expensive precursor materials.
Supply Chain Analysis
Single-source vulnerability sits with a limited number of global producers for critical fluorochemical precursors. The supply of these specialized raw materials concentrates in countries like China and Japan, creating a supply chain risk through potential price volatility and disruptions. Downstream distribution runs through vast networks for broad market access, particularly for aerospace and automotive end-users. This is complemented by direct sales and application support channels for specialized industrial clients needing formulation expertise.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The fluorine carbon coatings market is fundamentally a cost-of-compliance story, where stringent regulations like the EU's proposed universal PFAS restriction create a significant barrier-to-entry moat. This mandates substantial R&D investment, favoring established players with compliant material portfolios.
For Market Incumbents:Acquire specialized formulation expertise and next-generation polymer intellectual property to solidify market leadership. Invest heavily in developing and commercializing compliant non-PFAS or short-chain fluoropolymer technologies, mitigating future regulatory threats. Secure long-term supply agreements for critical precursors to reduce exposure to price volatility and supply chain disruptions. This proactive R&D ensures continued access to high-margin niche applications like semiconductor manufacturing.
For New Entrants and Emerging Players:Enter via high-margin niche applications demanding severe-service performance, such as internal linings for semiconductor equipment. Focus on developing and certifying novel, non-PFAS compliant polymer technologies to meet future market access requirements. Target underpenetrated geographic markets in Southeast Asia, leveraging infrastructure development for anti-corrosion and architectural coatings. Differentiate through sustainable formulations, including bio-based or recycled-content fluoropolymers, appealing to ESG-driven specifiers.
For Investors and Strategic Acquirers:Successful commercialization of non-PFAS fluoropolymer alternatives in critical applications is the leading indicator that regulatory transition risks are manageable. Long-term viability for this market remains robust for companies delivering specialized, compliant solutions with verifiable performance guarantees. Target mid-cap specialists possessing proprietary next-generation polymer technologies or strong market access in aerospace and semiconductor manufacturing. Monitor shifts in global regulatory timelines for PFAS restrictions, as these will trigger further consolidation and R&D acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Green Manufacturing Transition | Shifts production processes to reduce environmental footprint, aligning with global sustainability mandates and attracting ESG-conscious buyers. |
| Long-term Supply Agreement | Secures consistent access to critical fluorochemical precursors, mitigating supply chain volatility and ensuring production stability. |
| Capacity Expansion | Increases manufacturing output for compliant fluorine carbon coatings, meeting growing demand from industrial and aerospace sectors. |
| Joint Venture | Combines R&D strengths to accelerate development of novel, non-PFAS polymer technologies, sharing compliance costs and market risks. |
| Technology Licensing | Expands market reach for proprietary fluoropolymer formulations, allowing broader application across diverse end-use environments. |
Research Approach
China's MEE reports, US EPA publications, and EU REACH documents formed the secondary backbone for market sizing and trend analysis. This was complemented by primary interviews with R&D directors, procurement leads at aerospace OEMs, and plant managers in chemical processing facilities. Bottom-up data aggregation from company disclosures and top-down market validation ensured robust data triangulation.
Historical trendline analysis, accounting for market dynamics and regulatory shifts, informed the projection horizon. The forecast framework integrated segmentation across product type, application, end-user, coating technology, and regional regulatory frameworks. Compound annual growth rates derived from regression analysis and expert consensus, considering R&D investment in PFAS-compliant alternatives and new construction starts.
Forecast precision tightens around the base case; tail outcomes carry wider variance under rapid regulatory shifts or unforeseen precursor supply chain disruptions. These forecasts reflect documented assumptions regarding material innovation. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Coating Resins Market
Coatings
North America Superhydrophobic Coating Market
Coatings
Global Metal Coatings Market
Coatings
Asia-Pacific Coil Coatings Market
Coatings
Coated Casing Market
Coatings
Self-Healing Microcapsule Systems for Protective Coatings Market
Coatings
Global Inorganic Antimicrobial Coatings Market
Coatings
E-Coat Market
Coatings
High Performance Coatings Market
Coatings
Australia Industrial Coatings Market
Coatings
Cool Roof Coatings Market
Coatings
Mexico Protective Coatings Market
Coatings
United States Floor Coatings Market
Coatings
Urethane Surface Coatings Market
Coatings
Russia Protective Coatings Market
Coatings
Thailand Architectural Coatings Market