
 Interior Architectural Coatings Market | 2026-2036
Interior Architectural Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Interior Architectural Coatings Market Intelligence
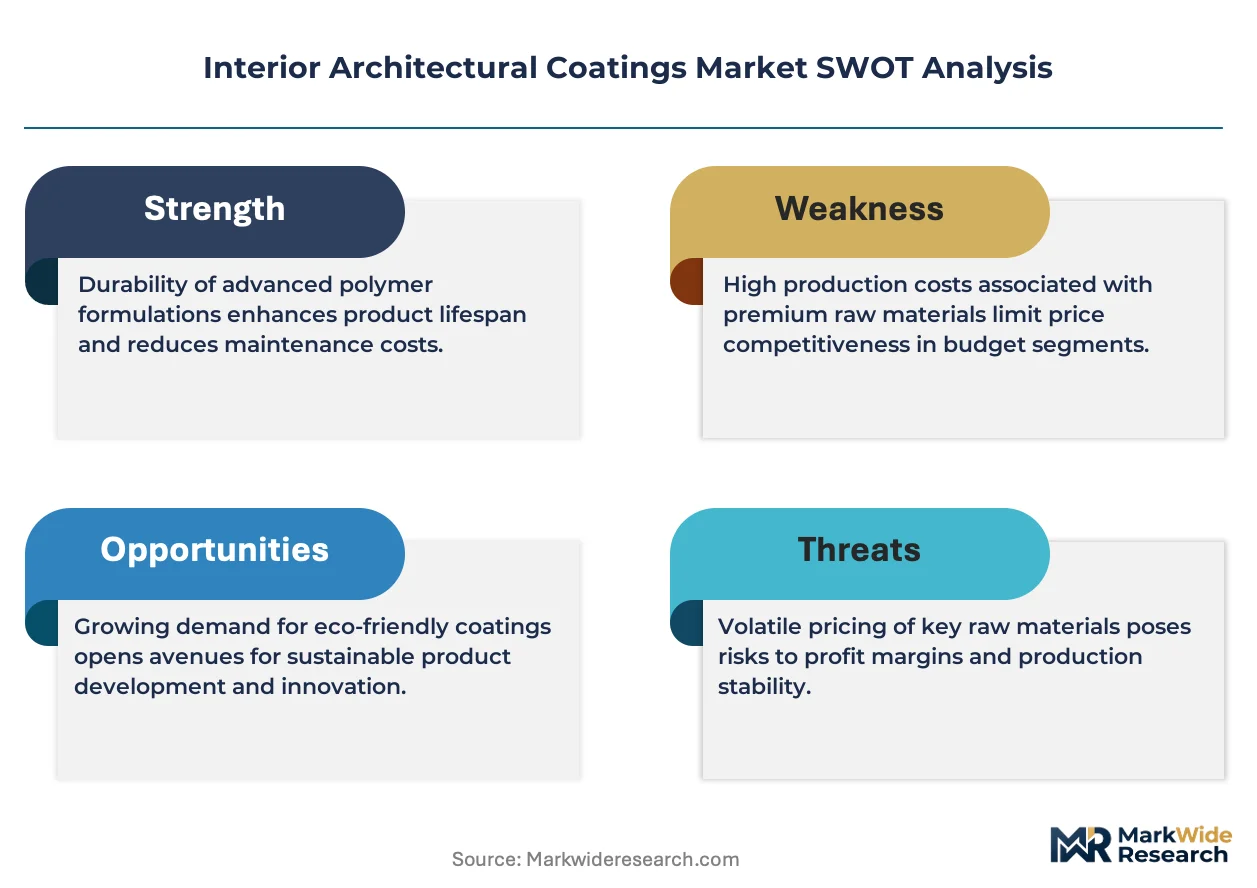
GREENGUARD Gold certification is collapsing the competitive field for interior architectural coatings, as building specifiers and facility managers filter vendor lists to qualified suppliers. The Sherwin-Williams Company leverages its extensive distribution network to maintain specification relationships with national contractors. AkzoNobel N.V. differentiates through waterborne technology leadership in premium commercial segments. PPG Industries, Inc. anchors its position through backward integration into resin and additive production.
Interior architectural coatings are liquid or powder formulations applied to interior walls, ceilings, and trim, typically comprising binders, pigments, solvents, and functional additives that cure to form protective and decorative films with specified scrub resistance and gloss levels. These products serve primarily to enhance durability, hygiene, and aesthetic control in built environments subject to mechanical wear and chemical exposure. Acrylic emulsions command the largest product-type volume due to their balance of performance and ease of application, while alkyd systems retain share in contractor channels where solvent-borne hardness remains specified. The residential application segment generates the broadest base demand, though commercial and institutional projects yield higher per-gallon margins through performance-grade specifications.
The EPA regulates volatile organic compound emissions under 40 CFR Part 59, while OSHA enforces worker exposure limits during application, and LEED v4.1 rewards low-emitting materials with credit points that shape specifier behavior. Europe's ECHA administers REACH restrictions on hazardous substances, and the EU Green Deal's renovation wave targets drive demand for compliant coating systems in building retrofits. Stakeholders must monitor how evolving chemical hazard classifications in multiple jurisdictions reshape raw material availability and reformulation timelines.
Market Dynamics
Low-emission formulation mandates are compressing supplier viability and forcing rapid solvent system transitions across the interior architectural coatings value chain.
Growth Catalysts
- GREENGUARD Gold specification filtering:Building specifiers and facility managers are narrowing vendor lists to certified suppliers, concentrating procurement relationships among qualified coating manufacturers.
- China's tier-one urban renovation wave:Accelerating interior refurbishment projects in Beijing, Shanghai, and Shenzhen are pulling premium waterborne formulations into residential and commercial retrofit applications.
- EU Green Deal renovation targets:The European Commission's building retrofit mandates are expanding demand for REACH-compliant coating systems in institutional and multi-family housing projects.
Market Restraints
- Titanium dioxide feedstock volatility:Pigment cost fluctuations compress margin stability for mid-tier formulation houses lacking long-term supply contracts.
- Alkyd resin supply concentration:Solvent-borne binder production clusters in select European and North American chemical corridors, exposing buyers to geographic disruption risk.
- VOC compliance timeline compression:REACH and EPA 40 CFR Part 59 phase-in schedules demand reformulation cycles that outpace standard R&D cadences.
Strategic Opportunities
- Antimicrobial additive convergence:Silver-ion and quaternary ammonium compound integration into standard interior paints opens healthcare and food-service specification channels previously served by specialized coatings.
- Direct-to-contractor digital platforms:E-procurement portals are bypassing traditional distribution tiers, enabling manufacturers to capture margin and application data simultaneously.
- India's commercial interior buildout:Office and retail space expansion in Mumbai, Bangalore, and Hyderabad creates demand for scrub-resistant, low-odor formulations meeting BIS emission standards.
Industry Challenges
- Formulation chemist talent scarcity:Experienced waterborne polymer specialists command premium compensation, constraining mid-cap manufacturer technical staffing.
- LEED v4.1 documentation burden:Third-party certification timelines and testing costs delay product launches and strain smaller R&D budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Interior Architectural Coatings Market |
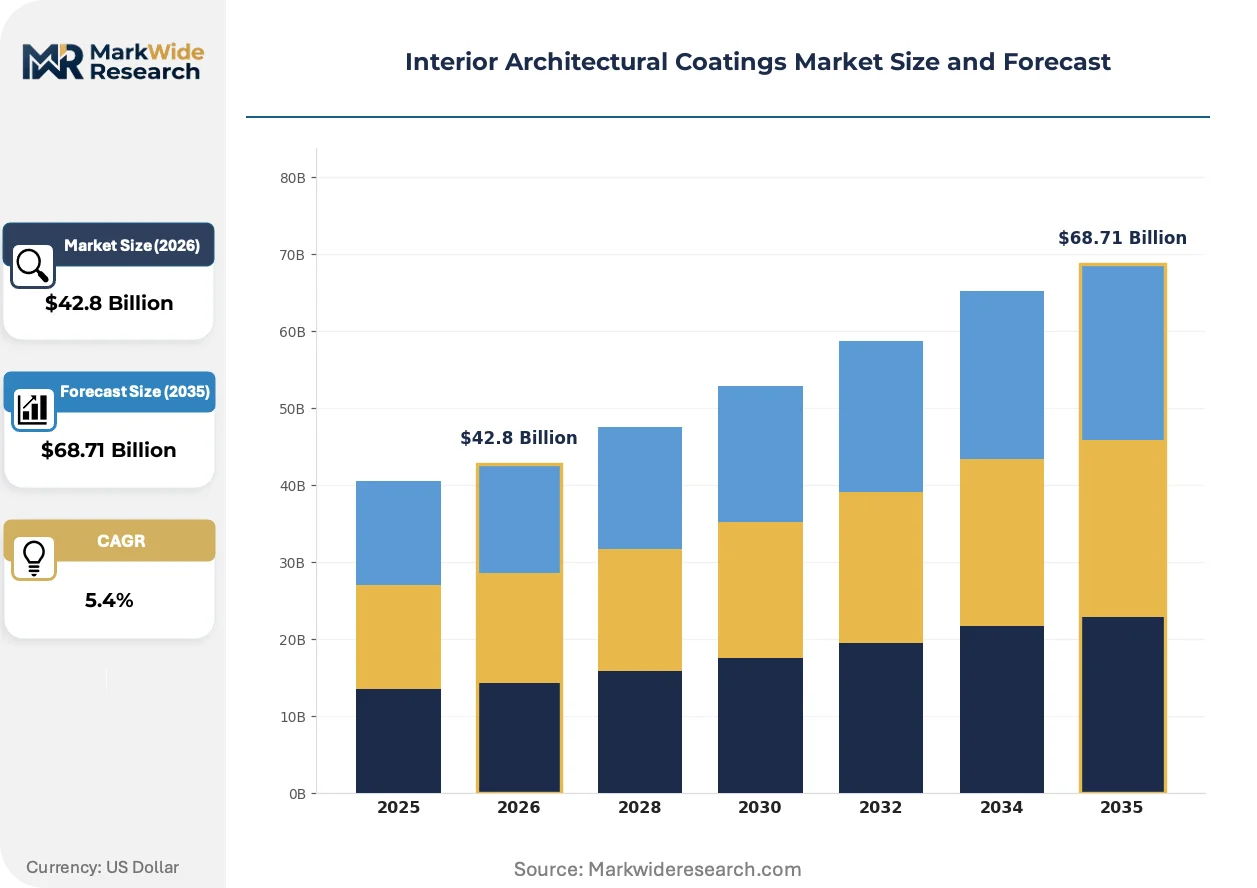
| Market Size in 2026 | $42.8 Billion |
| Market Size in 2035 | $68.71 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Emulsion, Alkyd, Acrylic, Latex Application: Residential, Commercial, Industrial, Institutional End User: Homeowners, Contractors, Facility Managers, Designers Distribution Channel: Retail, Wholesale, Online, Direct Sales |
| Companies Covered | The Sherwin-Williams Company, PPG Industries, Inc, AkzoNobel N.V., BASF SE, Asian Paints Limited, Nippon Paint Holdings Co., Ltd., Kansai Paint Co., Ltd., RPM International, Inc., Jotun A/S, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Interior Architectural Coatings Market Strategic Shifts & Innovations
Formulation chemistry is pivoting toward bio-based binders and self-healing film technologies that extend coating lifecycle performance while satisfying tightening emission protocols.
Photocatalytic titanium dioxide additives are decomposing volatile organic compounds at the coating surface, enabling air-purifying functionality in interior architectural films. Healthcare facility managers and premium residential developers are specifying these formulations for high-traffic zones and enclosed atriums. The technology is decomposing the traditional separation between decorative coatings and building air quality systems, forcing manufacturers to validate performance claims through extended chamber testing.
REACH restriction proposals on microplastic additives are compelling reformulation of textured interior paints and film-forming agents across European supply chains. The European Chemicals Agency's consultation timeline is compressing product development cycles for decorative coating manufacturers serving EU member states. Waterborne acrylic emulsion suppliers are accelerating bio-based alternatives to maintain formulation viscosity and sag resistance without synthetic rheology modifiers.
Building owners are unbundling coating specification from general contractor procurement, establishing direct relationships with certified manufacturers for warranty and performance accountability. National retail and hospitality chains are centralizing coating decisions at corporate headquarters, displacing project-level autonomy previously held by regional construction managers. This concentration is most visible in North American commercial rollouts where LEED compliance and brand consistency override local contractor preferences.
Interior Architectural Coatings Market Segmentation
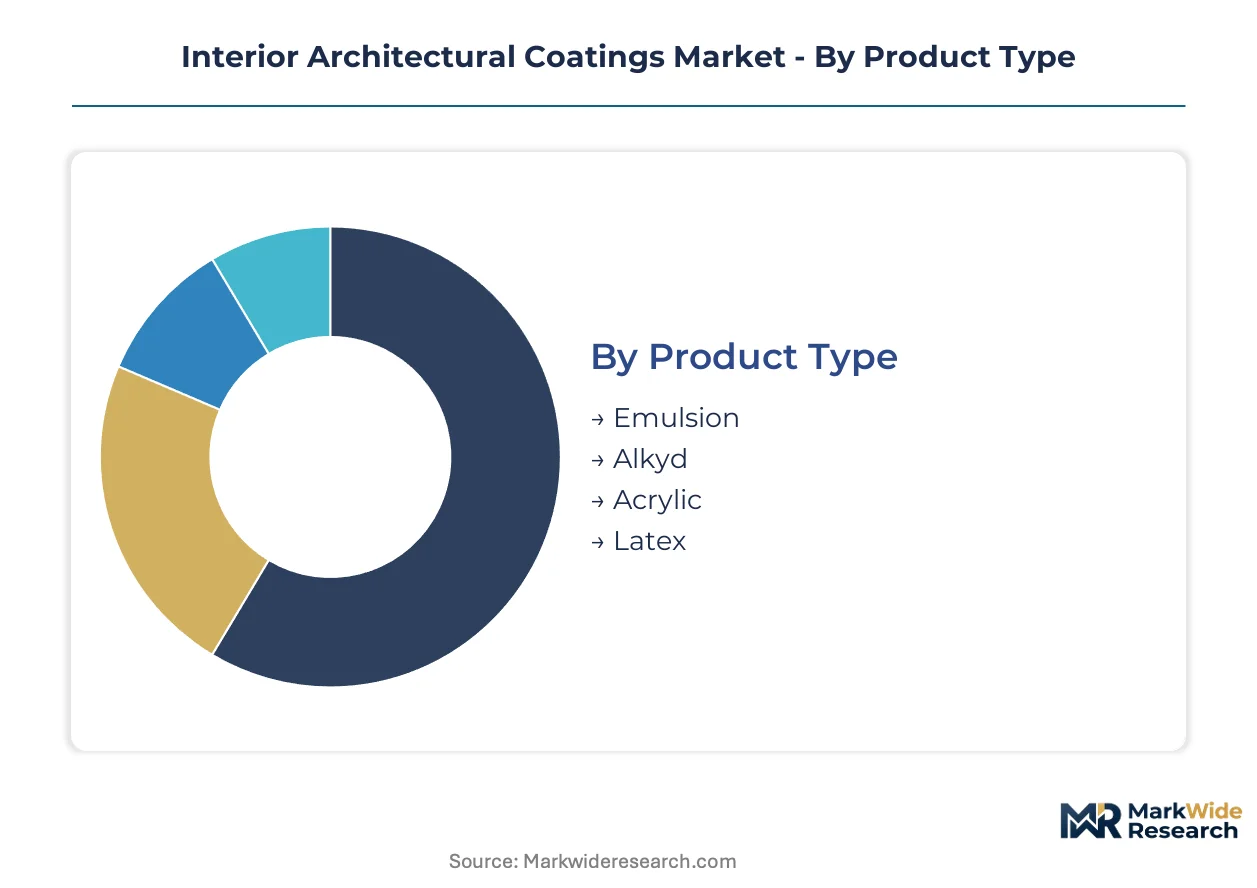
Interior architectural coatings manufacturers calibrate formulation portfolios against distinct performance requirements and procurement behaviors across product chemistry, building type, and channel structure. Segmentation discipline separates volume-driven residential contractors from specification-sensitive commercial facility managers with divergent technical demands and margin tolerance.
Product Type:
Waterborne emulsion systems face substitution pressure from bio-based acrylic alternatives as REACH and EPA 40 CFR Part 59 tighten solvent-borne viability.
- Emulsion:Water-based polymer dispersions dominate residential repaint cycles due to low odor and rapid dry-to-recoat intervals. Demand concentrates in China's tier-one urban renovation projects where MEE emission standards accelerate waterborne specification.
- Acrylic:Thermoplastic and thermoset acrylic resins deliver superior scrub resistance and color retention in high-traffic commercial corridors. LEED v4.1-compliant low-VOC acrylics are displacing alkyd systems in US healthcare and educational facilities.
- Alkyd:Solvent-borne polyester-modified oils retain contractor preference for trim and door applications requiring hardness development.
- Latex:Vinyl acetate copolymer emulsions serve cost-sensitive residential new construction with adequate washability for rental housing turnover cycles.
Emulsion anchors the volume base while acrylic gains share at the steepest rate.
Application:
Margin stratification runs deepest between residential volume plays and commercial specification premiums where certification compliance commands price realization.
- Residential:Single-family and multi-family interior wall and ceiling coatings generate the broadest demand base through repaint and new construction cycles. China's urban interior renovation wave in Beijing, Shanghai, and Shenzhen pulls premium waterborne formulations into high-end residential retrofit.
- Commercial:Office, retail, and hospitality interiors require scrub-resistant, stain-blocking films with extended lifecycle warranties. GREENGUARD Gold certification filters vendor lists to qualified suppliers for national retail chain rollouts.
- Institutional:Healthcare and educational facilities specify antimicrobial additives and air-purifying photocatalytic surfaces.
- Industrial:Light manufacturing and warehouse interiors demand chemical-resistant films for washdown protocols.
Residential commands the volume base while commercial climbs the fastest on per-gallon margin expansion.
End User:
Procurement authority concentration is shifting from project-level contractors to corporate facility managers and centralized design offices.
- Contractors:Professional painting crews prioritize coverage efficiency, touch-up match, and availability through established distribution. Alkyd retention in this channel reflects solvent-borne hardness specifications still prevalent in North American commercial trim applications.
- Facility Managers:Building operations executives specify coating systems for lifecycle cost and warranty accountability. Direct manufacturer relationships are displacing general contractor procurement autonomy in national retail and hospitality chains.
- Homeowners:DIY repaint decisions emphasize color selection tools, low-odor application, and one-coat coverage claims.
- Designers:Interior architects and specification writers filter products through LEED v4.1 and GREENGUARD Gold databases.
Contractors anchor the volume base while facility managers drive the steepest specification premium capture.
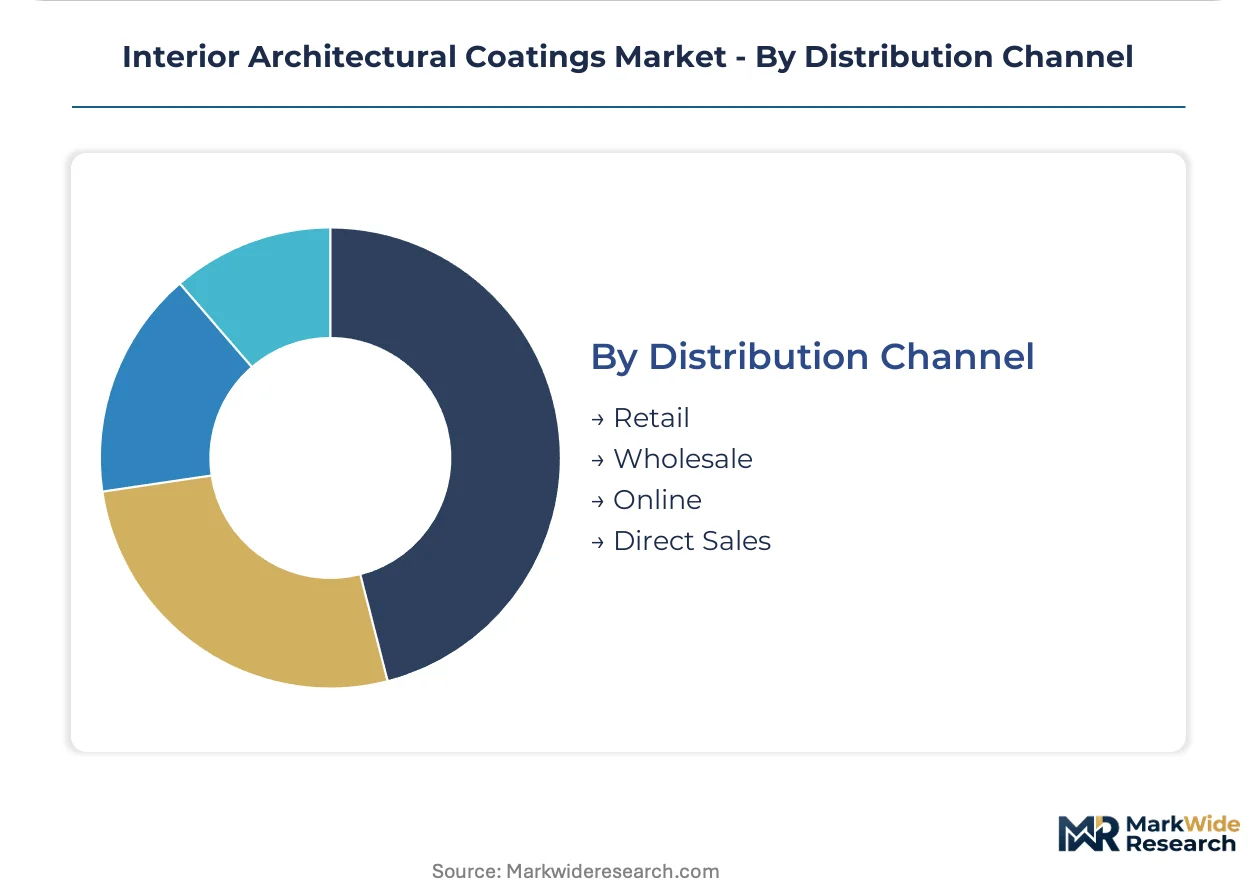
Distribution Channel:
Channel cost structure and data access are restructuring manufacturer margin capture and customer relationship ownership.
- Retail:Big-box home improvement and specialty paint stores serve homeowner DIY and small contractor spot-buy needs. Sherwin-Williams leverages its company-owned store network to maintain specification relationships with national contractors.
- Wholesale:Distributor tiers aggregate contractor volume and extend credit terms for project-based purchasing.
- Direct Sales:Manufacturer-to-contractor and manufacturer-to-facility-manager relationships concentrate in commercial and institutional specification. E-procurement portals enable simultaneous margin capture and application data collection.
- Online:Digital platforms serve color sampling, technical documentation access, and project quantity estimation.
Retail anchors the volume base while direct sales expands most quickly on relationship control and margin retention.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Facility managers and national retail chains concentrate procurement authority in select metropolitan corridors where certification compliance and specification relationships determine vendor selection. Demand clusters in urban renovation zones across multiple continents, with regulatory phase-in timelines compressing formulation transitions.
United States
National retail and hospitality chains centralize coating decisions at corporate headquarters, displacing regional contractor autonomy. EPA 40 CFR Part 59 and OSHA worker exposure limits shape reformulation priorities. The Southeast and Texas corridor sees concentrated commercial rollouts where LEED v4.1 compliance overrides local preferences.
China
Beijing, Shanghai, and Shenzhen drive premium waterborne demand through accelerated interior refurbishment in tier-one urban cores. MEE emission standards tighten faster than standard R&D cycles permit. Yangtze River Delta manufacturing clusters supply reformulated acrylic emulsions for residential retrofit applications.
Germany
Industrial coatings heritage feeds technical expertise into REACH-compliant architectural systems for institutional retrofits. ECHA restriction timelines compress product development for textured paints and film-forming agents. Bavaria and North Rhine-Westphalia anchor formulation R&D responding to EU Green Deal renovation targets.
India
Office and retail expansion in Mumbai, Bangalore, and Hyderabad pulls scrub-resistant, low-odor formulations meeting BIS emission standards. Commercial interior buildout outpaces residential new construction for margin capture. Western and Southern state manufacturing corridors supply waterborne systems to contractor networks.
Japan
Healthcare and educational facility managers specify antimicrobial and air-purifying photocatalytic surfaces for high-traffic interiors. METI guidance on building material emissions shapes premium product development. Kanto and Kansai metropolitan areas concentrate specification authority among facility management professionals.
Interior Architectural Coatings Market Key Industry Players
Player mix skews toward integrated multinational chemical conglomerates with captive resin supply and specification-grade certification portfolios. Mid-cap regional specialists occupy price-sensitive residential segments through distribution scale rather than technical differentiation. Two strategic archetypes dominate: backward-integrated formulators controlling additive supply chains, and certification-focused premium players capturing facility manager procurement. Competitive moves center on e-procurement platform deployment and antimicrobial additive portfolio expansion.
Within the integrated multinational tier, The Sherwin-Williams Company and PPG Industries, Inc. exemplify archetypes combining distribution network scale with specification relationship depth. AkzoNobel N.V. occupies a position representing waterborne technology leadership in premium commercial segments. These three anchors demonstrate how geographic footprint breadth and certification portfolio depth separate specification-viable suppliers from commodity competitors.
| Leading Market Players |
|---|
| The Sherwin-Williams Company |
| PPG Industries, Inc |
| AkzoNobel N.V. |
| BASF SE |
| Asian Paints Limited |
| Nippon Paint Holdings Co., Ltd. |
| Kansai Paint Co., Ltd. |
| RPM International, Inc. |
| Jotun A/S |
| Others |
Cost & Logistics Intelligence
Capacity utilization at integrated resin plants in Germany and the United States shapes margin floors for mid-tier formulators lacking captive supply. Scale advantages at these facilities concentrate pricing power among backward-integrated multinationals while compressing viability for regional coating houses dependent on spot-market binder procurement.
Pricing Analysis
Cost-plus contracts with titanium dioxide indexation dominate raw material procurement for formulation houses lacking long-term supply agreements. Three-tier pricing structure across premium, standard, and economy levels separates GREENGUARD Gold-certified systems from commodity emulsions and contractor-grade alkyd products. Pricing pressure stems from pigment feedstock volatility that outpaces reformulation cost recovery timelines. Residential contractors exhibit highest price sensitivity while facility managers at national retail chains prioritize lifecycle warranty value over per-gallon expenditure.
Supply Chain Analysis
Inventory lead times for specialty acrylic resins extend through European and North American chemical corridors where solvent-borne binder production clusters. China, Germany, and the United States anchor global supply for waterborne polymer dispersions and alkyd modifiers. Formulation chemistry depends on titanium dioxide from Chinese and Australian mineral processors, acrylic acid from Gulf Coast petrochemical complexes, and proprietary additives from Swiss and Japanese specialty chemical houses. Single-source vulnerability concentrates in photocatalytic titanium dioxide for air-purifying coatings. Distribution runs through manufacturer-owned store networks, wholesale distributor tiers, and emerging e-procurement portals serving facility managers directly.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Interior architectural coatings represent a service-attach opportunity where specification support, color matching, and warranty administration generate recurring revenue streams expanding faster than base product sales. Application training programs and digital color visualization tools now command premium positioning alongside physical coating supply.
For Market Incumbents: Secure captive supply of bio-based acrylic resins through joint development agreements with Yangtze River Delta polymer producers. Deepen specification relationships with national retail chains by embedding certified coating consultants within corporate facility management departments. Alkyd resin supply concentration in European chemical corridors poses geographic disruption risk requiring dual-sourcing strategies. For New Entrants and Emerging Players: Specification support gaps in India's commercial interior buildout offer white-space entry where incumbent coverage remains thin. Target scrub-resistant, low-odor formulations for Mumbai and Bangalore office rollouts where BIS emission compliance creates qualification barriers for unproven suppliers. Deploy direct-to-contractor digital platforms with integrated project estimation tools to bypass established wholesale distribution tiers. For Investors and Strategic Acquirers: Regional waterborne technology specialists with GREENGUARD Gold portfolios and established specifier relationships represent priority acquisition targets. Waterborne polymer formulation expertise concentrates among mid-cap players in China's tier-one renovation corridors and Germany's institutional retrofit supply chains. Monitor ECHA restriction timelines on microplastic additives as inflection indicator for bio-based rheology modifier demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Production | Captive acrylic emulsion supply insulates margin from titanium dioxide volatility and REACH reformulation cycles. |
| GREENGUARD Gold Certification Investment | Qualification for national retail chain specifications filters vendor lists to certified suppliers exclusively. |
| Antimicrobial Additive Portfolio Expansion | Silver-ion and quaternary ammonium integration opens healthcare and food-service specification channels. |
| E-Procurement Platform Deployment | Direct manufacturer-to-contractor relationships capture margin and application data simultaneously. |
| Bio-Based Binder Development Partnership | REACH microplastic restrictions accelerate demand for plant-derived alternatives to synthetic rheology modifiers. |
Research Approach
Desk research of customs trade databases, SEC 10-K filings, and ECHA restriction proposals preceded structured interviews with formulation R&D directors, national contractor procurement leads, and facility management executives at retail and hospitality chains. Primary fieldwork with distribution channel partners and color matching service providers validated secondary estimates of regional demand concentration. Bottom-up volume modeling triangulated against top-down macroeconomic indicators across the analysis window.
Variance decomposition separated volume growth from price-mix effects across product chemistry, building application, and procurement channel dimensions. Segmentation modeling captured emulsion, acrylic, alkyd, and latex product types against residential, commercial, institutional, and industrial end-use patterns. CAGRs derived from regression analysis of historical consumption trends, renovation cycle timing, and regulatory phase-in schedules. Forecast inputs incorporated MEE emission standard timelines in China, EU Green Deal renovation targets, and LEED v4.1 adoption curves in North American commercial construction.
Underlying assumptions cover steady regulatory enforcement, intact acrylic resin supply chains, and sustained tier-one urban renovation activity in China, with deviation risk concentrated in titanium dioxide feedstock disruptions and accelerated REACH restriction implementation. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paints & Coatings
Paint Buckets Market
Paints & Coatings
Egypt Paints and Coatings Market
Paints & Coatings
Paint Defoamers Market
Paints & Coatings
Global Antifouling Paints and Coatings Market
Paints & Coatings
Low VOC Paint Market
Paints & Coatings
Europe Paints and Coatings Market
Paints & Coatings
Mexico Paints and Coatings Market
Paints & Coatings
India Automotive Paints and Coatings Market
Paints & Coatings
Global Decorative Coatings Market
Paints & Coatings
Cellulose Paints Market
Paints & Coatings
Asia-Pacific Architectural Coatings Market
Paints & Coatings
Asia-Pacific Paints and Coatings Additives Market
Paints & Coatings
Europe Automotive Paints and Coatings Market
Paints & Coatings
Middle-East and Africa Wood Coatings Market
Paints & Coatings
ASEAN Paints and Coatings Market
Paints & Coatings
Iran Paints and Coatings Market