
 Global Heat Resistant Coatings Market | 2026-2036
Global Heat Resistant Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Global Heat Resistant Coatings Market Foresight
Silicone resin formulations are recalibrating product economics across the heat resistant coatings sector by displacing conventional alkyd systems in applications above 300°C. PPG Industries leverages captive silicone supply chains to sustain margin structures in aerospace component coatings. AkzoNobel N.V. anchors European demand through specialized marine and industrial equipment lines. Jotun A/S dominates Nordic and Middle Eastern energy producer segments with high-build ceramic hybrid systems.
Heat resistant coatings are engineered polymer or ceramic-based films designed to maintain adhesion, color stability, and corrosion protection at continuous operating temperatures from 150°C to over 650°C, typically incorporating silicone resins, aluminum flakes, or inorganic silicates as thermal barriers. Their primary purpose is to extend asset life in environments where standard organic coatings would degrade through thermal oxidation or embrittlement. Silicone-based products occupy the mature volume core of the market, while ceramic formulations capture premium positioning in power generation and aerospace components where peak temperature exposure exceeds 500°C. Intumescent technology segments are expanding fastest among construction firms seeking passive fire protection integration with thermal management.
EPA regulations under the National Emission Standards for Hazardous Air Pollutants constrain solvent-based coating formulations in US manufacturing plants, while REACH and the EU F-Gas Regulation drive reformulation timelines across European supply chains. China's MEE enforces VOC content ceilings that redirect domestic production toward waterborne and high-solids heat resistant systems. Stakeholders must monitor regulatory divergence between North American and European emission frameworks when configuring regional product portfolios and certification investments.
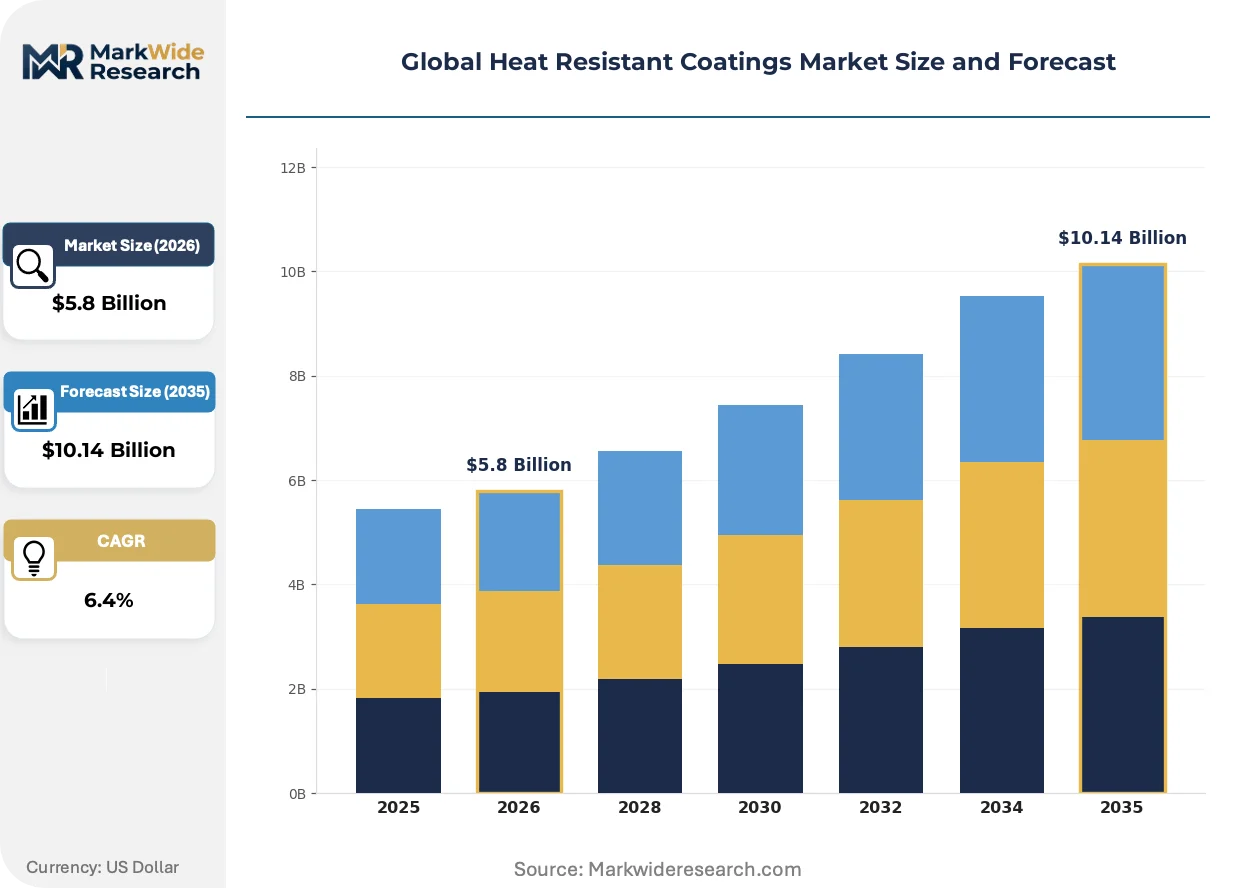
Market Dynamics
Silicone resin supply concentration in Germany and China is compressing formulation economics, forcing coating manufacturers to secure captive feedstock or absorb margin erosion from spot market volatility in organosilicon intermediates.
Growth Catalysts
- EPA NESHAP compliance deadlines:US manufacturing plants face phased solvent reduction mandates, redirecting capital toward high-solids and waterborne heat resistant systems for exhaust stacks and process equipment.
- Gas turbine refurbishment cycles:Energy producers in Saudi Arabia and the UAE are replacing thermal barrier coatings on aging combined-cycle units, creating sustained demand for ceramic hybrid formulations above 600°C.
- Silicone resin thermal performance:Advances in phenyl-modified polysiloxanes enable continuous service at 350°C, displacing alkyd-epoxy hybrids in petrochemical furnace applications.
Market Restraints
- Organosilicon feedstock volatility:Silicone resin prices fluctuate with metallurgical-grade silicon availability from Chinese smelters, compressing blender margins during energy price spikes.
- REACH authorization timelines:ECHA scrutiny of chromium trioxide in anti-corrosive primers delays product recertification for European marine and industrial equipment customers.
- Ceramic precursor cost structure:Aluminum flake and inorganic silicate raw materials carry 40-60% premia over organic alternatives, limiting adoption in cost-sensitive construction applications.
Strategic Opportunities
- India industrial corridor buildout:PLI scheme incentives for domestic manufacturing equipment create first-mover advantage for coating suppliers establishing technical service centers in Gujarat and Tamil Nadu.
- Intumescent-thermal convergence:Construction firms in Singapore and Australia seek single-coat solutions combining passive fire protection with heat resistance, opening specification windows for hybrid chemistries.
- EU F-Gas Regulation phase-down:Refrigeration and HVAC OEMs require coating systems compatible with lower-GWP working fluids, favoring reformulated silicone-epoxy hybrids for compressor housings.
Industry Challenges
- Formulation chemist scarcity:Expertise in high-temperature polymer degradation mechanisms concentrates among retiring specialists at German and Japanese coating houses, creating knowledge transfer gaps.
- Multi-jurisdiction certification complexity:Aerospace suppliers must maintain parallel qualification tracks with FAA, EASA, and CAAC for thermal barrier coatings on turbine components, extending time-to-revenue.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Heat Resistant Coatings Market |
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $10.14 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicone, Epoxy, Ceramic, Acrylic, Polyurethane, Alkyd Application: Metal Surfaces, Automotive Components, Industrial Equipment, Marine Vessels, Aerospace Components, Power Generation Technology: Thermoplastic, Thermoset, Intumescent, Nanocoating, Fluoropolymer, Solvent-Based End User: Construction Firms, Vehicle Assemblers, Shipyards, Flight Manufacturers, Energy Producers, Manufacturing Plants |
| Companies Covered | AkzoNobel N.V., PPG Industries, Inc., The Sherwin-Williams Company, Jotun A/S, Hempel A/S, Kansai Paint Co., Ltd., BASF SE, Axalta Coating Systems LLC, RPM International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Heat Resistant Coatings Market Shifts & Advancements
Reformulation pressures from divergent regulatory frameworks are fragmenting product architectures, with manufacturers maintaining parallel chemistries for VOC-constrained versus performance-maximum markets rather than converging on universal platforms.
Ceramic-metallic composite coatings are expanding into aerospace turbine blade applications, where thermal cycling resistance above 650°C protects nickel superalloy substrates. Pratt & Whitney and Rolls-Royce procurement teams now specify these systems for next-generation engine programs. The technology is expanding into land-based gas turbines as Siemens Energy and GE Vernova seek comparable durability for peaking power plants.
REACH restriction proposals on per- and polyfluoroalkyl substances are forcing reassessment of non-stick heat resistant coatings in food processing equipment across EU member states. German and Italian OEMs are accelerating testing of silicone-ceramic alternatives for baking and frying line components. The regulatory pressure is compressing reformulation timelines from typical 18-24 month cycles toward 12-month emergency substitutions.
Energy sector procurement teams are consolidating vendor relationships from fragmented regional suppliers toward technical-service-integrated partnerships capable of on-site application supervision. Major EPC contractors in the Middle East now require coating applicators co-located with project sites, displacing traditional distributor-only models. This behavioral shift is most visible in Saudi Aramco and ADNOC maintenance contracts, where single-source accountability for performance warranties dominates supplier selection criteria.
Global Heat Resistant Coatings Market Segmentation
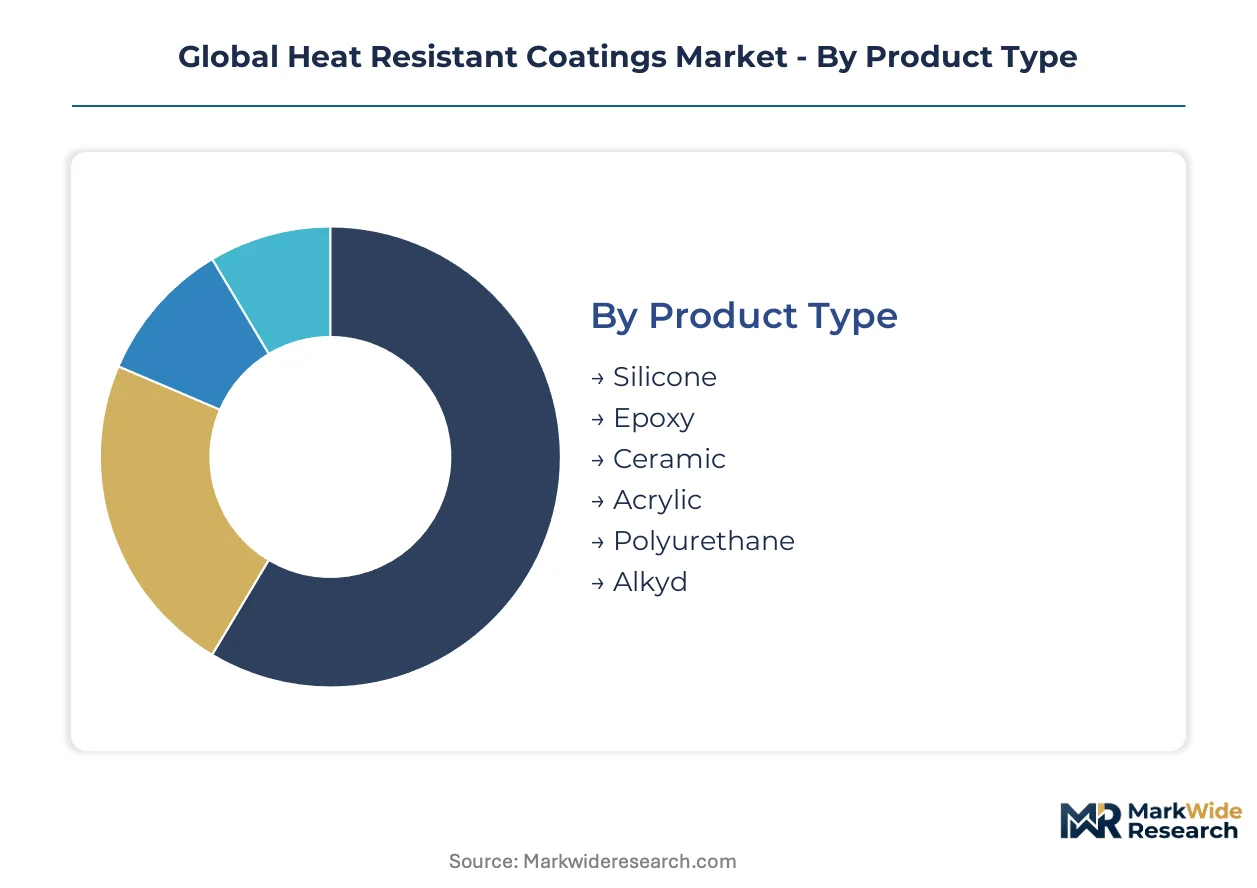
Heat resistant coatings exhibit divergent performance profiles across formulation chemistry and end-use exposure, requiring granular segmentation to align thermal specifications with asset operating conditions. Procurement teams specify coating systems based on continuous service temperature, thermal cycling frequency, and substrate metallurgy rather than generic performance claims.
Product Type:
Silicone resin supply concentration in Germany and China compresses formulation economics, forcing manufacturers toward captive feedstock arrangements or margin absorption from spot market volatility in organosilicon intermediates.
- Silicone:Phenyl-modified polysiloxanes deliver continuous service at 350°C, displacing alkyd-epoxy hybrids in petrochemical furnace applications across Saudi Aramco and ADNOC maintenance contracts. PPG Industries leverages captive silicone supply chains to sustain margin structures in aerospace component coatings.
- Ceramic:Aluminum flake and inorganic silicate composites withstand peak temperatures exceeding 650°C in gas turbine hot sections, commanding 40-60% raw material premia over organic alternatives. Jotun A/S dominates Nordic and Middle Eastern energy producer segments with high-build ceramic hybrid systems.
- Epoxy:Modified formulations bridge 200-300°C service windows for industrial exhaust stacks and process equipment requiring chemical resistance alongside thermal protection.
- Acrylic:Waterborne systems address VOC-constrained construction applications with moderate heat tolerance up to 180°C continuous exposure.
- Polyurethane:Flexible films suit automotive underhood components experiencing intermittent thermal spikes rather than sustained high-temperature operation.
- Alkyd:Cost-positioned coatings retain share in sub-250°C applications where reformulation economics favor incremental performance gains over system replacement.
Silicone absorbs the bulk of installed capacity; ceramic is expanding most quickly in power generation and aerospace procurement specifications.
Application:
Application-driven specification patterns concentrate procurement authority among asset owners rather than general contractors, reshaping distribution toward technical-service-integrated partnerships.
- Power Generation:Combined-cycle gas turbines require ceramic-metallic thermal barrier coatings above 600°C for blade and combustion hardware, with Siemens Energy and GE Vernova procurement teams driving qualification timelines for next-generation peaking plant durability.
- Aerospace Components:Pratt & Whitney and Rolls-Royce specify ceramic-metallic composites for nickel superalloy substrates facing thermal cycling above 650°C, with parallel FAA, EASA, and CAAC certification tracks extending time-to-revenue for coating suppliers.
- Metal Surfaces:Steel fabrication and structural components utilize silicone-epoxy hybrids for corrosion-thermal dual protection in industrial infrastructure.
- Automotive Components:Exhaust manifolds and turbocharger housings drive demand for heat-resistant formulations compatible with EPA NESHAP solvent reduction mandates.
- Industrial Equipment:Furnace linings, heat exchangers, and process vessels specify coatings based on continuous operating temperature and chemical exposure profiles.
- Marine Vessels:Engine room components and exhaust systems require coatings balancing thermal performance with salt spray corrosion resistance.
Power Generation commands the largest addressable equipment base; Aerospace Components is climbing the fastest as engine OEMs refresh thermal management specifications.
Technology:
Technology selection determines capital equipment requirements for applicators and dictates reformulation timelines under divergent regulatory frameworks across manufacturing jurisdictions.
- Intumescent:Expanding char-forming systems integrate passive fire protection with thermal management, capturing specification windows among Singapore and Australian construction firms seeking single-coat solutions for structural steel protection.
- Thermoset:Cross-linked silicone and epoxy chemistries dominate continuous high-temperature applications above 300°C where dimensional stability under thermal load is critical.
- Thermoplastic:Acrylic and fluoropolymer systems suit lower-temperature applications requiring re-workability and repair accessibility.
- Nanocoating:Emerging formulations incorporating ceramic nanoparticles for enhanced thermal barrier performance in specialized aerospace and electronics applications.
- Fluoropolymer:Non-stick heat resistant coatings face REACH restriction pressure on per- and polyfluoroalkyl substances, compressing German and Italian OEM reformulation timelines toward 12-month emergency substitutions.
- Solvent-Based:High-solids variants retain share in performance-maximum markets where VOC constraints are secondary to film build and cure speed requirements.
Thermoset retains the dominant installed application base; Intumescent is gaining share fastest among construction specification authorities.
End User:
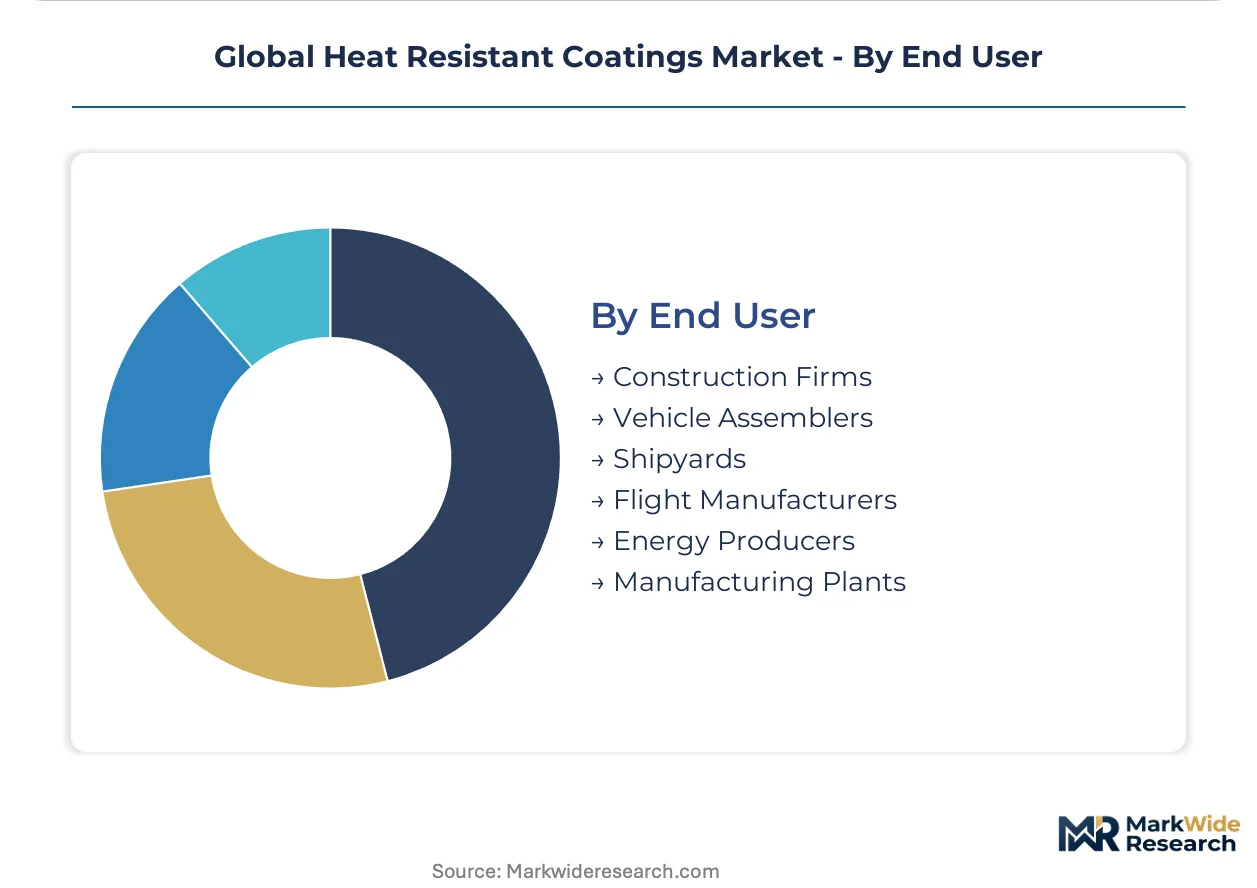
End-user procurement consolidation from fragmented regional suppliers toward technical-service-integrated partnerships is displacing traditional distributor-only models across maintenance and new-build contracts.
- Energy Producers:Saudi Aramco and ADNOC maintenance contracts now require coating applicators co-located with project sites, with single-source accountability for performance warranties dominating supplier selection criteria in combined-cycle turbine refurbishment cycles.
- Flight Manufacturers:Boeing and Airbus supply chains enforce parallel qualification tracks with FAA, EASA, and CAAC for thermal barrier coatings on turbine components, extending certification timelines and favoring incumbent suppliers with established regulatory relationships.
- Construction Firms:Specifiers in Singapore and Australia seek hybrid chemistries combining passive fire protection with heat resistance for structural steel applications.
- Vehicle Assemblers:OEMs specify coatings for exhaust and underhood components compatible with evolving EPA emissions and material content regulations.
- Shipyards:Korean and Chinese builders require marine-qualified heat resistant systems for engine room and exhaust applications.
- Manufacturing Plants:US facilities face EPA NESHAP phased solvent reduction mandates, redirecting capital toward high-solids and waterborne systems for exhaust stacks and process equipment.
Energy Producers represent the largest procurement volume; Flight Manufacturers are scaling specifications fastest as next-generation engine programs enter production.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for heat resistant coatings concentrates in industrial corridors where gas turbine refurbishment cycles intersect with petrochemical capacity expansion. Energy producers in Saudi Arabia and the UAE drive procurement volumes for ceramic hybrid formulations above 600°C. Manufacturing clusters in China, India, and Germany anchor regional supply chains through divergent regulatory compliance frameworks.
United States
Gas turbine operators in Texas and Louisiana execute combined-cycle refurbishment programs requiring thermal barrier coatings for blade hardware. EPA NESHAP phased solvent reduction mandates redirect capital toward high-solids and waterborne systems for exhaust stacks and process equipment. Houston-Galveston corridor coating applicators now co-locate technical service teams at major petrochemical facilities to meet single-source warranty requirements.
Germany
Industrial equipment manufacturers in North Rhine-Westphalia specify silicone-epoxy hybrids for furnace and heat exchanger applications up to 350°C continuous service. REACH authorization timelines for chromium trioxide in anti-corrosive primers delay product recertification for marine and industrial equipment customers. Leverkusen-Düsseldorf chemical cluster houses concentrated silicone resin formulation capacity serving European aerospace and automotive supply chains.
China
Power generation equipment builders in Jiangsu and Shandong provinces procure ceramic-metallic composites for domestic gas turbine programs. MEE enforces VOC content ceilings that redirect domestic production toward waterborne and high-solids heat resistant systems. Yangtze River Delta coating manufacturers absorb margin pressure from metallurgical-grade silicon spot market volatility originating in southwestern smelter regions.
India
PLI scheme incentives for domestic manufacturing equipment create first-mover advantage for coating suppliers establishing technical service centers in Gujarat and Tamil Nadu. Central Electricity Authority efficiency standards accelerate thermal power plant component replacement cycles. Hazira-Vadodara industrial corridor attracts formulation facilities targeting petrochemical and refinery maintenance contracts.
Saudi Arabia
Saudi Aramco maintenance contracts require coating applicators co-located with project sites, displacing traditional distributor-only models. Combined-cycle turbine refurbishment cycles sustain demand for ceramic hybrid formulations above 600°C. Jubail Industrial City concentration of energy processing facilities generates concentrated procurement authority for performance-warranted thermal barrier systems.
Global Heat Resistant Coatings Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with formulation expertise concentrating among established European and North American houses while regional applicators capture on-site service value. The vendor base organizes around three strategic archetypes: captive resin producers with backward integration into organosilicon feedstock, application-integrated technical service providers, and formulation licensors supplying regional blenders. Dominant competitive moves include M&A targeting specialized ceramic precursor capabilities and geographic expansion through technical service center establishment in high-growth industrial corridors.
Among Netherlands-based coating houses, AkzoNobel N.V. exemplifies the European formulation specialist archetype with marine and industrial equipment line concentration. PPG Industries, Inc. represents the vertically integrated North American model leveraging captive silicone supply chains. Jotun A/S occupies a position among Nordic specialists with energy sector focus through high-build ceramic hybrid positioning. These three anchors demonstrate divergent strategic postures: feedstock security versus application integration versus regional segment dominance.
| Leading Market Players |
|---|
| AkzoNobel N.V. |
| PPG Industries, Inc. |
| The Sherwin-Williams Company |
| Jotun A/S |
| Hempel A/S |
| Kansai Paint Co., Ltd. |
| BASF SE |
| Axalta Coating Systems LLC |
| RPM International Inc. |
| Others |
Supply & Pricing Matrix
Performance-grade divergence between ceramic-metallic composites and commodity silicone systems manifests in both pricing premiums and supply chain sourcing strategies. Buyers specifying thermal barrier coatings above 600°C face 40-60% raw material premia for aluminum flake and inorganic silicate inputs, while procurement teams for sub-300°C applications optimize around German and Chinese organosilicon spot markets.
Pricing Analysis
Volume-margin splits concentrate in silicone resin formulations absorbing the mature demand core against ceramic hybrids capturing aerospace and power generation premiums. Price differentiation hinges on certification tier—FAA/EASA qualification for turbine components commands substantial premia over industrial equipment grades—and captive feedstock control at PPG Industries and AkzoNobel. Cost compression in commodity silicone runs through metallurgical-grade silicon volatility from Chinese smelters. Construction firms prove most price-sensitive, while energy producers prioritize performance warranties over unit economics.
Supply Chain Analysis
Multi-jurisdiction certification gating—parallel FAA, EASA, and CAAC tracks for aerospace thermal barriers—extends supplier qualification timelines and concentrates procurement among incumbents. Feedstock production centers on Germany's Leverkusen-Düsseldorf chemical cluster and China's Yangtze River Delta, with formulation economics drawing from southwestern Chinese metallurgical-grade silicon. Single-source vulnerability concentrates in organosilicon intermediates where spot market spikes compress blender margins. Distribution feeds from technical service-integrated partnerships displacing traditional distributor models across Middle Eastern energy contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
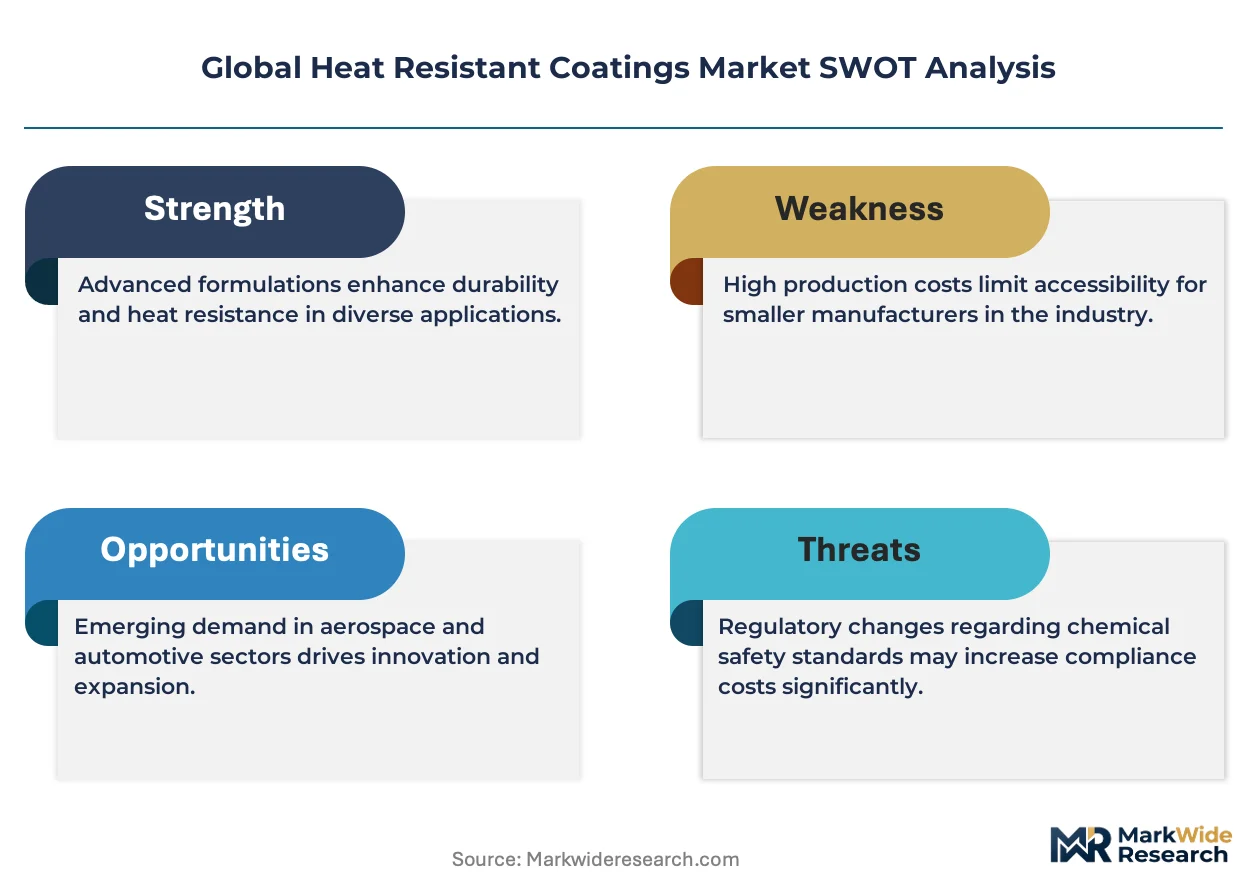
Regulatory divergence between EPA NESHAP solvent mandates and EU REACH authorization timelines is forcing sub-scale formulators toward exit or acquisition, consolidating procurement authority among technical-service-integrated suppliers.
For Market Incumbents: Anchor feedstock security through backward integration into organosilicon intermediates or long-term offtake agreements with German and Chinese resin producers. Threats from REACH chromium trioxide restrictions and ECHA scrutiny of anti-corrosive primers demand accelerated recertification investment to defend European marine and industrial positions. For New Entrants and Emerging Players: Ceramic nanoparticle formulations offer a technology-first wedge into specialized aerospace electronics and next-generation turbine applications underserved by incumbent silicone-epoxy platforms. India's PLI-scheme industrial corridors in Gujarat and Tamil Nadu present the most penetrable white space, with technical service center establishment as the critical go-to-market angle. For Investors and Strategic Acquirers: Exit pathways concentrate in mid-cap specialists with captive ceramic precursor capabilities and established multi-jurisdiction aerospace qualifications. Long-term viability over a 5-10 year window favors targets with demonstrated Siemens Energy or GE Vernova procurement relationships. Watch for Saudi Aramco and ADNOC maintenance contract consolidation signals as inflection indicators for technical-service-integrated model validation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organosilicon Feedstock | PPG Industries' captive silicone supply chains insulate margin structures from Chinese smelter volatility. |
| Technical Service Center Establishment | Co-location with Saudi Aramco and ADNOC project sites satisfies single-source warranty requirements. |
| Ceramic Precursor Capability Acquisition | Aluminum flake and inorganic silicate expertise commands premium positioning above 600°C applications. |
| Multi-Jurisdiction Certification Investment | Parallel FAA, EASA, and CAAC qualification tracks extend time-to-revenue but lock out challengers. |
| Intumescent-Thermal Hybrid Development | Singapore and Australian construction specifications reward single-coat passive fire protection integration. |
Research Methodology
Independent corroboration across coating formulator technical directors, energy sector procurement leads, and aerospace supply chain managers underwrites the qualitative findings. Primary interviews with plant engineers at Saudi Aramco and ADNOC facilities, EPC contractors in Jubail Industrial City, and regulatory affairs specialists at German chemical houses combined with secondary validation from EPA NESHAP filings, ECHA restriction proposals, and customs data on organosilicon intermediate trade flows. Bottom-up asset-level demand modeling and top-down chemical industry consumption patterns were reconciled through iterative triangulation.
Comparable-period anchoring to gas turbine refurbishment cycle data and petrochemical furnace replacement schedules established the forecast framework's historical reference base. The analysis window spans formulation chemistry, application temperature tier, end-use industry, and regional regulatory cluster dimensions. CAGRs were derived from segment-level demand build-ups incorporating Siemens Energy and GE Vernova procurement timelines, PLI scheme incentive trajectories in India, and REACH authorization pipeline delays.
Several conditions sit outside the modeled scope, including unannounced regulatory amendments to EU F-Gas Regulation phase-down schedules and geopolitical disruptions to Chinese metallurgical-grade silicon export flows. Forecasts reflect assumptions about continued EPA NESHAP compliance deadlines and sustained Saudi Aramco maintenance contract structures. A model refresh is warranted upon material change in aerospace engine OEM thermal barrier coating qualification timelines or MEE enforcement intensity on Chinese VOC content ceilings.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Anti-Microbial Nano Coatings Market
Coatings
Epoxy Powder Coatings Market
Coatings
Global Anti-Corrosion Coating Market
Coatings
Egypt Automotive OEM Coatings Market
Coatings
Hull Coatings Market
Coatings
FBE Coatings Market
Coatings
Europe Metal Finishing Market
Coatings
Italy Protective Coatings Market
Coatings
US Concrete Floor Coatings Market
Coatings
North America Thermal Spray Market
Coatings
South Africa Protective Coatings Market
Coatings
Europe Powder Coatings Market
Coatings
Canada Industrial Wood Coatings Market
Coatings
Industrial Liquid Coating Market
Coatings
Noise and Vibration Coatings Market
Coatings
Yacht Coatings Market