
 Industrial Water Treatment Chemicals Market | 2026-2036
Industrial Water Treatment Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Water Treatment Chemicals Market Intelligence
China's chemical manufacturing belt is reconfiguring regional supply dynamics for industrial water treatment inputs. BASF SE leverages its integrated polymer backbone to dominate coagulant and flocculant supply across European industrial zones. Kemira anchors Nordic pulp and paper mill chemical service contracts through on-site technical support models. Ecolab Inc. competes via bundled water-energy-service platforms that lock in multi-year municipal and manufacturing accounts.
Industrial water treatment chemicals comprise formulated additives including polyacrylamide-based flocculants, aluminum and iron salt coagulants, halogenated disinfectants, and sulfuric or caustic pH adjusters, engineered to remove suspended solids, control microbial fouling, and maintain operational integrity in closed-loop and once-through cooling systems. These formulations typically operate within specified dosage ranges of 0.5 to 50 ppm depending on water chemistry and contaminant load. Coagulants and flocculants command the largest product-type position due to universal deployment in primary clarification across power generation and pulp and paper applications. Chemical treatment technology leads membrane filtration and ion exchange in installed base across oil and gas produced water handling, though biological treatment gains traction in pharmaceutical effluent streams with high organic variability.
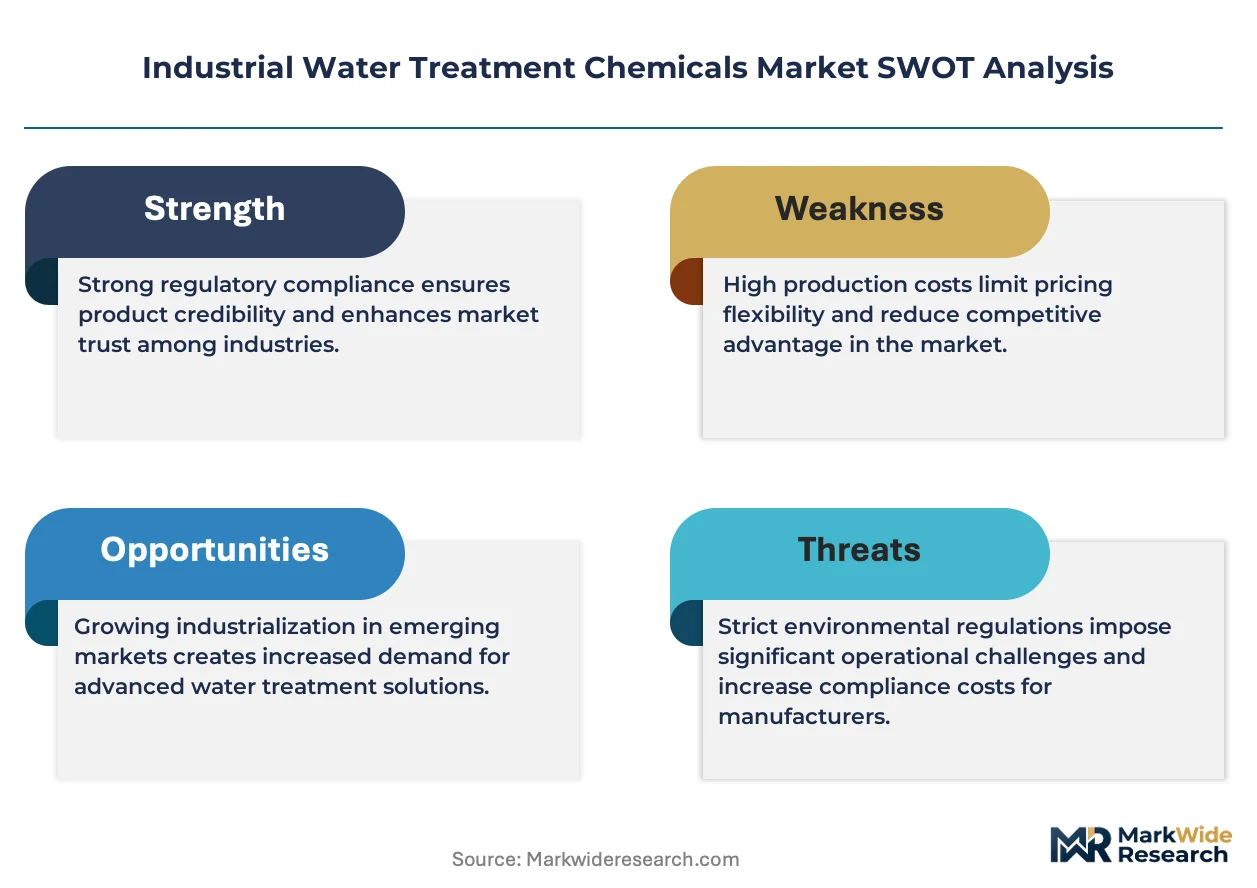
The US EPA enforces National Pollutant Discharge Elimination System permits that mandate specific effluent limits, directly determining coagulant selection and dosing protocols at manufacturing facilities. China's MEE administers dual carbon goals and tightened industrial wastewater standards that compel facilities to upgrade from conventional lime precipitation to advanced polymeric flocculant systems. The EU REACH framework governs chemical registration and hazard communication for biocidal products used in cooling water treatment, creating compliance barriers for non-European suppliers. Stakeholders must monitor regulatory divergence between jurisdictions to align product portfolios with diverging permissible chemistry lists and discharge criteria.
Market Dynamics
Zero-liquid-discharge mandates across China's industrial corridor zones are forcing facilities to abandon conventional lime precipitation for advanced polymeric flocculant systems, compressing chemical selection cycles and elevating technical service requirements.
Growth Catalysts
- US EPA discharge limits:Tightened Clean Water Act enforcement pushes power generation and manufacturing facilities toward high-performance coagulant formulations with lower residual aluminum content.
- Power generation expansion:Cooling tower water conditioning chemical procurement accelerates across Asia-Pacific as new thermal and combined-cycle capacity enters commissioning phases.
- EU REACH biocidal compliance:Registration requirements for halogenated disinfectants create preferential market access for European-formulated products with complete hazard documentation.
Market Restraints
- Acrylamide monomer price volatility:Polyacrylamide backbone costs fluctuate with propylene feedstock and energy pricing, squeezing flocculant producer margins during contract renegotiations.
- China supply concentration:Bulk aluminum sulfate and ferric chloride production clusters in Shandong and Henan provinces, exposing buyers to localized environmental shutdowns and logistics disruptions.
- Membrane filtration substitution:Ultrafiltration and reverse osmosis systems displace chemical-dependent clarification in pharmaceutical and electronics effluent treatment, reducing coagulant volume requirements.
Strategic Opportunities
- India industrial corridor buildout:Gujarat and Tamil Nadu manufacturing zones lack established chemical service infrastructure, creating first-mover advantage for technical support-anchored suppliers.
- Biological-chemical hybrid systems:Convergence of biofilm-based pretreatment with targeted polymer dosing opens pharmaceutical effluent applications with high organic variability.
- China dual carbon policy:MEE carbon intensity targets for industrial facilities incentivize chemical programs that reduce energy-intensive sludge handling and thermal drying requirements.
Industry Challenges
- Water chemistry specialist shortage:Facilities struggle to hire operators capable of optimizing coagulant-flocculant dosing across variable raw water quality and seasonal temperature swings.
- Legacy DCS integration:Chemical feed automation projects stall when programmable logic controllers must interface with decades-old distributed control systems lacking standard communication protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Water Treatment Chemicals Market |
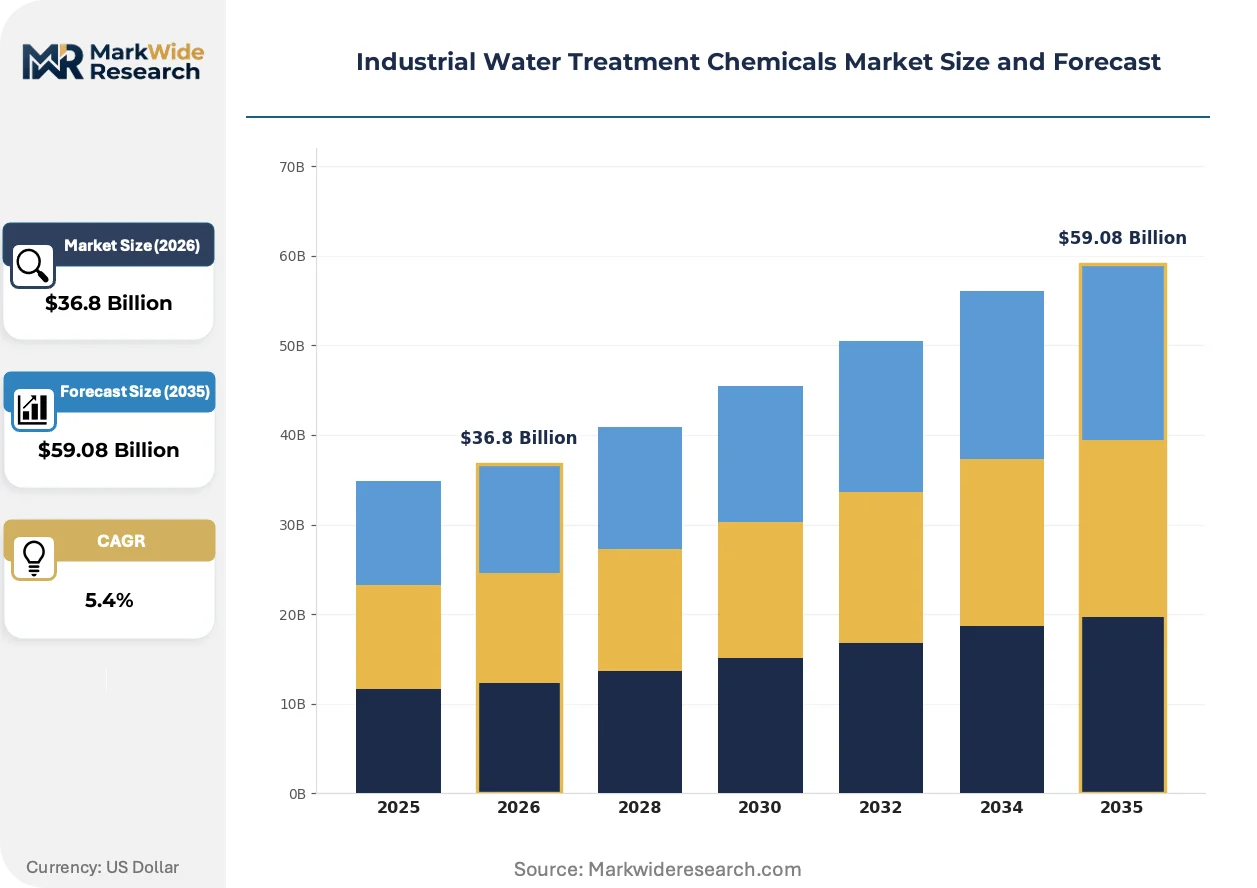
| Market Size in 2026 | $36.8 Billion |
| Market Size in 2035 | $59.08 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coagulants, Flocculants, Disinfectants, pH Adjusters Application: Pulp & Paper, Power Generation, Oil & Gas, Textile End User: Manufacturing, Municipal, Energy, Pharmaceuticals Technology: Membrane Filtration, Ion Exchange, Biological Treatment, Chemical Treatment |
| Companies Covered | Ecolab Inc., BASF SE, Solenis, Kemira, SNF Group, SUEZ, Dow Inc., Kurita Water Industries Ltd., Clariant, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Water Treatment Chemicals Market Strategic Shifts & Innovations
Digital dosing optimization and bio-based polymer development are compressing the traditional chemical supplier value proposition from bulk commodity distribution toward precision-formulated, data-integrated service models.
Structured silica-based coagulants with lower alkalinity demand are rendering obsolete conventional aluminum sulfate in high-pH cooling water applications. Power generation operators in the US Southeast adopt these formulations to reduce acid consumption and simplify pH control loops. The shift compresses commodity chemical volumes while elevating technical service intensity.
China's MEE has tightened GB 31570 and GB 31571 standards for petroleum refining and coal chemical wastewater, mandating lower total nitrogen and suspended solids limits. Facilities respond by upgrading from single-stage lime precipitation to sequential coagulation-flocculation with polymer-assisted dewatering. The regulatory pressure concentrates demand growth in high-molecular-weight cationic flocculants.
Integrated water-energy-service platforms now bundle chemical supply with cooling tower energy optimization and remote monitoring. Municipal and manufacturing accounts in the US Midwest favor these arrangements over transactional procurement, locking in multi-year relationships. The model displaces traditional distributor networks that lack engineering capabilities.
Industrial Water Treatment Chemicals Market Segmentation
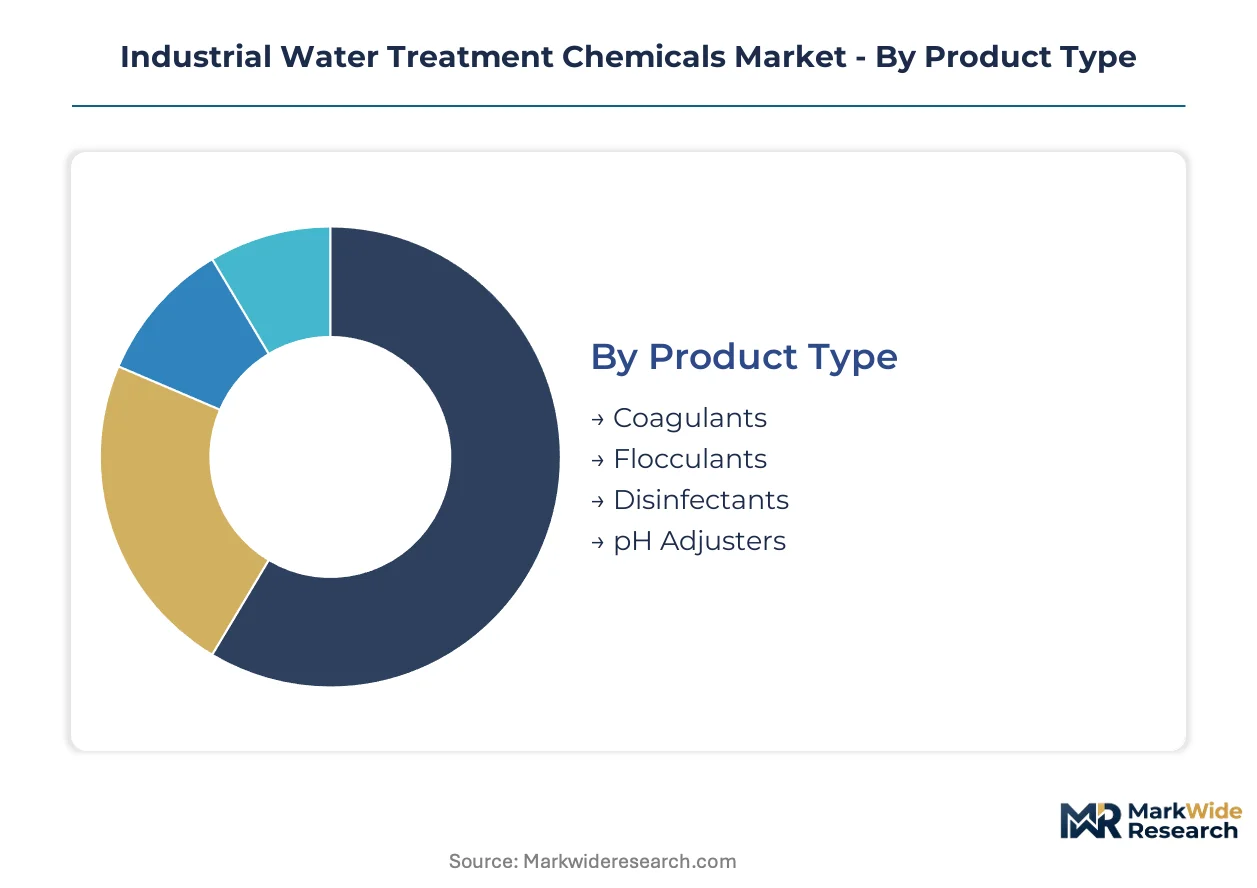
Industrial water treatment chemicals serve distinct operational profiles across power generation cooling loops, pulp mill effluent streams, and oilfield produced water handling. Segment boundaries reflect divergent dosage protocols, regulatory discharge limits, and integration requirements with physical treatment infrastructure.
Product Type:
Formulation chemistry spans mineral salts, synthetic polymers, halogenated oxidizers, and acid-base neutralizers with dosage ranges from sub-ppm to 50 ppm depending on contaminant load.
- Coagulants:Aluminum sulfate, ferric chloride, and structured silica variants destabilize colloidal suspensions through charge neutralization. Power generation operators in the US Southeast favor low-alkalinity-demand silica formulations to reduce acid consumption and simplify pH control loops.
- Flocculants:Polyacrylamide-based polymers with anionic, cationic, or nonionic charge profiles bridge destabilized particles into settleable flocs. China's petroleum refining sector drives demand for high-molecular-weight cationic grades under tightened GB 31570 and GB 31571 discharge standards.
- Disinfectants:Chlorine, bromine, and chlorine dioxide formulations control microbial fouling in cooling towers and once-through systems.
- pH Adjusters:Sulfuric acid, caustic soda, and lime products correct alkalinity excursions and protect infrastructure from corrosion or scaling.
Established volume favors coagulants; emerging adoption favors flocculants.
Application:
End-use sectors impose distinct water chemistry requirements based on effluent variability, temperature regimes, and regulatory scrutiny intensity.
- Pulp & Paper:High organic load effluents with seasonal variability demand robust coagulation-flocculation trains and specialized defoamer compatibility. Nordic mills anchor long-term chemical service contracts through on-site technical support models.
- Power Generation:Cooling tower and boiler water conditioning requires precise halogenated biocide dosing and scale inhibitor programs. Asia-Pacific thermal and combined-cycle capacity expansion accelerates procurement across new commissioning phases.
- Oil & Gas:Produced water handling with high salinity and hydrocarbon content favors chemical-dependent clarification over membrane alternatives.
- Textile:Dyehouse effluents with high color and COD loads drive demand for advanced oxidation pretreatment coupled with polymer-assisted dewatering.
Power generation commands the largest installed base; pulp and paper exhibits the highest service intensity.
End User:
Procurement patterns diverge between capital-intensive manufacturing complexes, rate-regulated municipal utilities, and specialized pharmaceutical clean-water operations.
- Manufacturing:Industrial facilities across China's chemical manufacturing belt reconfigure regional supply dynamics as zero-liquid-discharge mandates reshape chemical selection criteria.
- Municipal:Drinking water and wastewater treatment plants favor bundled water-energy-service platforms that lock in multi-year relationships over transactional procurement.
- Energy:Power utilities prioritize discharge permit compliance under EPA NPDES mandates determining coagulant selection and dosing protocols.
- Pharmaceuticals:High-purity water systems and effluent treatment with variable organic loads drive biological-chemical hybrid system adoption.
Manufacturing concentrates procurement volume; pharmaceuticals show steepest expansion trajectory for advanced polymer systems.
Technology:
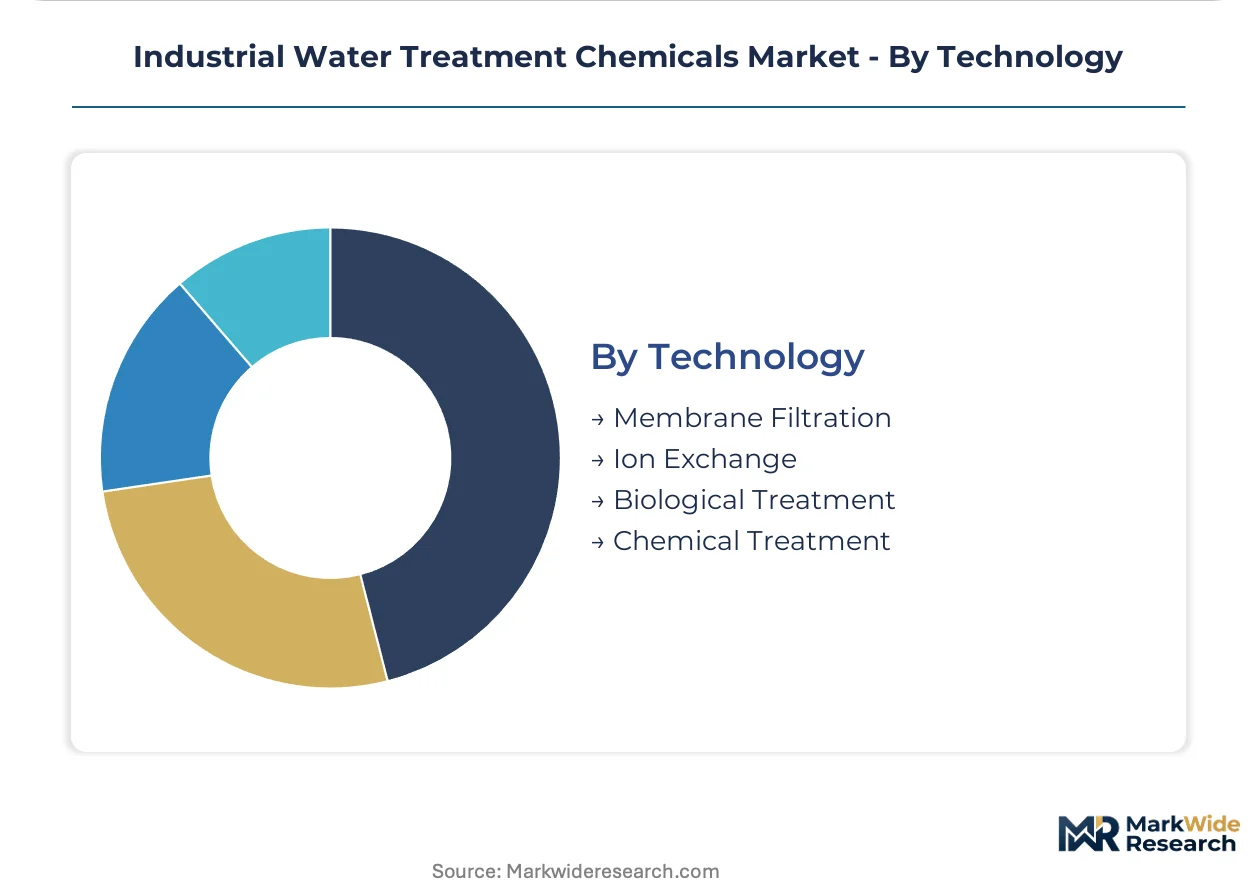
Treatment modality selection hinges on capital availability, footprint constraints, and effluent quality requirements across closed-loop and once-through configurations.
- Chemical Treatment:Coagulation, flocculation, and disinfection processes dominate installed base across oil and gas produced water handling due to operational flexibility and lower capital intensity.
- Membrane Filtration:Ultrafiltration and reverse osmosis systems displace chemical-dependent clarification in pharmaceutical and electronics effluent treatment, reducing coagulant volume requirements.
- Ion Exchange:Resin-based demineralization serves boiler feedwater and high-purity process water applications with stringent conductivity specifications.
- Biological Treatment:Biofilm-based systems gain traction in pharmaceutical effluent streams with high organic variability, often deployed as pretreatment ahead of targeted polymer dosing.
Chemical treatment retains the broadest deployment base; biological systems climb the fastest in specialized pharmaceutical applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yangtze River Delta's integrated chemical logistics network underwrites China's dominance in industrial water treatment chemical manufacturing and consumption.
United States
Power generation operators in the US Southeast adopt structured silica-based coagulants to reduce acid consumption in cooling water applications. EPA tightened National Pollutant Discharge Elimination System permits under the Clean Water Act, mandating lower residual aluminum content in effluent streams. The Gulf Coast petrochemical corridor drives procurement volume for produced water handling chemicals.
China
Zero-liquid-discharge mandates across industrial corridor zones compress chemical selection cycles toward advanced polymeric flocculant systems. Ministry of Ecology and Environment administers dual carbon goals and tightened GB 31570 and GB 31571 standards for petroleum refining wastewater. Shandong and Henan provinces concentrate bulk aluminum sulfate and ferric chloride production, exposing buyers to localized environmental shutdowns.
Germany
Integrated polymer backbone capabilities anchor coagulant and flocculant supply across European industrial zones. EU REACH framework governs chemical registration and hazard communication for biocidal products, creating compliance barriers for non-European suppliers. The Rhine-Ruhr industrial basin maintains dense demand for pulp and paper mill chemical services.
India
Gujarat and Tamil Nadu manufacturing zones lack established chemical service infrastructure, creating first-mover advantage for technical support-anchored suppliers. Central Electricity Authority mandates tighten thermal power plant water discharge standards. The Delhi-Mumbai Industrial Corridor accelerates cooling tower chemical procurement as new capacity enters commissioning.
Japan
High-purity water systems in pharmaceutical and electronics manufacturing drive precision-formulated chemical demand. METI industrial efficiency programs incentivize chemical programs that reduce energy-intensive sludge handling. The Kansai industrial zone around Osaka maintains specialized requirements for biofilm-compatible treatment chemistries.
Industrial Water Treatment Chemicals Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in the supply architecture. The vendor base organizes around three tiers: multinational chemical conglomerates with integrated polymer backbones, regional service-anchored specialists, and commodity bulk distributors. Consolidation pressures concentrate among mid-scale distributors lacking engineering capabilities. Dominant competitive moves include bundled water-energy-service platform rollouts and backward integration into polyacrylamide monomer production.
Within the integrated chemical conglomerate tier, BASF SE and Dow Inc. exemplify platform-scale positioning through captive polymer backbone supply. Ecolab Inc. occupies a distinct service-anchored position, bundling chemical supply with remote monitoring and energy optimization. Kemira represents the Nordic specialist archetype, securing pulp and paper mill contracts through embedded technical support models. SNF Group and Solenis sit within the polymer-focused specialist segment, with geographic naming conventions indicating French and US origins respectively.
| Leading Market Players |
|---|
| Ecolab Inc. |
| BASF SE |
| Solenis |
| Kemira |
| SNF Group |
| SUEZ |
| Dow Inc. |
| Kurita Water Industries Ltd. |
| Clariant |
| Others |
Cost & Logistics Intelligence
Propylene feedstock volatility determines both pricing tier spreads and supply chain shape across polyacrylamide-based flocculant production. Buyers face compressed contract renegotiation windows when monomer costs spike, forcing tiered procurement strategies that separate spot purchasers from long-term offtake partners.
Pricing Analysis
Volume-discount tiering structures separate municipal utilities with multi-year bundled contracts from spot-buying manufacturing facilities. Three-tier pricing stratification across premium performance grades, standard polymeric formulations, and economy mineral salt alternatives reflects certification complexity and technical service bundling. Cost compression in economy-grade aluminum sulfate is intensifying because Shandong province environmental shutdowns constrain bulk supply availability. Municipal procurement teams exhibit highest price sensitivity due to rate-regulated budget constraints, while pharmaceutical clean-water operations prioritize performance over unit economics.
Supply Chain Analysis
Contract-manufacturing concentration among Shandong and Henan province bulk chemical producers anchors global aluminum sulfate and ferric chloride availability. Geographic supply concentration in China, Germany, and the United States shapes regional pricing benchmarks and logistics cost structures. Raw material dependencies on propylene derivatives, bauxite refining byproducts, and sulfuric acid feedstocks create input cost transmission channels. Single-source vulnerability from China's zero-liquid-discharge enforcement campaigns exposes buyers to unplanned production halts. Distribution runs through integrated chemical conglomerates with captive polymer backbone capabilities and technical service-anchored regional specialists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as municipal utilities consolidate procurement through bundled water-energy-service platforms, compressing traditional distributor margins and elevating engineering-capability requirements.
For Market Incumbents: Pre-empt membrane filtration substitution threats by embedding chemical feed automation and remote monitoring into long-term service contracts. Backward integration into polyacrylamide monomer production secures margin control against propylene volatility. Dominant competitive positioning requires locking in multi-year municipal accounts before platform competitors replicate Ecolab's bundled service architecture.
For New Entrants and Emerging Players: India's Gujarat and Tamil Nadu manufacturing zones offer the most penetrable white-space for technical support-anchored market entry. First-mover advantage awaits suppliers establishing on-site chemical service infrastructure ahead of Delhi-Mumbai Industrial Corridor capacity commissioning. Target pharmaceutical effluent applications with biological-chemical hybrid system expertise to bypass entrenched commodity chemical distributors.
For Investors and Strategic Acquirers: EPA NPDES permit tightening and China's GB 31570/31571 standard revisions reshape the acquisition landscape toward polymer-focused specialists with complete hazard documentation. Long-term viability centers on platform integrators with captive polymer backbones and regulatory compliance capabilities across multiple jurisdictions. The signal to watch is MEE enforcement intensity against Shandong province bulk chemical producers as an indicator of supply disruption premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polyacrylamide Monomer | Captive propylene supply insulates BASF and Dow from feedstock volatility compressing flocculant margins. |
| Technical Service Infrastructure Buildout | On-site chemical optimization capabilities lock in Nordic pulp mill contracts for Kemira against commodity distributors. |
| Regulatory Compliance Certification Investment | Complete EU REACH documentation creates preferential biocidal product access blocking non-European suppliers. |
| Digital Dosing Platform Deployment | Remote monitoring and automation integration displaces legacy distributor networks lacking engineering capabilities. |
| Biological-Chemical Hybrid System Development | Convergence expertise opens pharmaceutical effluent applications with high organic variability beyond commodity treatment. |
Research Approach
A standing panel of plant managers, procurement leads at power generation facilities, distribution channel partners, and technical R&D directors provided ongoing calibration across primary interview rounds. Secondary validation drew from customs and trade data, American Chemistry Council and Cefic industry reports, SEC 10-K filings from listed chemical conglomerates, and Ministry of Ecology and Environment enforcement disclosures. Bottom-up segment sizing and top-down macroeconomic cross-checks established analytical consistency.
Scenario-bracketing framed demand projections across the analysis window using conservative, baseline, and accelerated regulatory enforcement assumptions. Segmentation dimensions modeled include product formulation chemistry, end-use industry vertical, service intensity tier, and regional production hub concentration. CAGRs were derived from installed base growth rates, replacement cycle timing, and regulatory-driven upgrade propensity. Forecast inputs incorporated cooling tower commissioning schedules across Asia-Pacific thermal capacity expansion and zero-liquid-discharge compliance timelines.
Practitioners should monitor propylene price volatility, MEE environmental enforcement intensity, and membrane filtration cost curves for early signals of forecast revision. Quarterly review of Shandong province production permit suspensions, EPA NPDES permit issuance rates, and India industrial corridor chemical service infrastructure development is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water & Sludge Treatment
US Water and Wastewater Treatment Market
Water & Sludge Treatment
Enzymes for Water Treatment Market
Water & Sludge Treatment
Sedimentation and Centrifugation Market
Water & Sludge Treatment
Africa Water Treatment Chemicals Market
Water & Sludge Treatment
Global Electrodeionization Market
Water & Sludge Treatment
Water Treatment Polymers Market
Water & Sludge Treatment
Europe Membrane Water Treatment Chemicals Market
Water & Sludge Treatment
North America Membrane Water and Wastewater Treatment (WWT) Market
Water & Sludge Treatment
Global Water Clarifiers Market
Water & Sludge Treatment
India Water Treatment Chemicals Market
Water & Sludge Treatment
Low-Dosage Hydrate Inhibitors (Ldhis) Market
Water & Sludge Treatment
Deionized Water Systems Market
Water & Sludge Treatment
Global Wet Waste Management Market
Water & Sludge Treatment
Aquarium Water Treatment Market
Water & Sludge Treatment
United Kingdom Water Treatment Chemicals Market
Water & Sludge Treatment
Liquid Waste Container Market