
 Plasma Impulse Chemical Vapor Deposition (PICVD) Coating Market | 2026-2036
Plasma Impulse Chemical Vapor Deposition (PICVD) Coating Market Size, Share, and Industry Trends Forecast 2026-2036
Plasma Impulse Chemical Vapor Deposition (PICVD) Coating Market Analytics
ISO 14644 cleanroom certification is reorganizing which equipment suppliers qualify for advanced semiconductor fab contracts. OC Oerlikon Management AG leverages its vacuum technology heritage to dominate European PICVD tool installations. Lam Research Corporation anchors its position through deep integration with etch and deposition process flows. Applied Materials, Inc. competes by extending its materials engineering portfolio into pulsed plasma architectures.
Plasma Impulse Chemical Vapor Deposition applies dielectric and protective layers through temporally separated plasma pulses, enabling sub-50 nanometer conformal coating on complex three-dimensional substrates at temperatures below 200 degrees Celsius. Thin films command the largest revenue pool in the product type dimension due to semiconductor node shrink requirements, while protective coatings represent the fastest-growing application segment as industrial tool wear becomes a cost priority. PVD technology still occupies the majority installed base, though PICVD-specific pulsed plasma configurations are gaining share in logic device manufacturing.
EPA hazardous air pollutant standards and REACH precursor substance restrictions are forcing reformulation of organometallic deposition chemistries across US and European installations. Japan's METI energy efficiency codes for manufacturing equipment are creating additional design constraints for PICVD reactor systems. Stakeholders must monitor how China's GB standards for semiconductor equipment localization intersect with export control frameworks affecting deposition tool sourcing.
Market Dynamics
Pulsed plasma architectures are compressing thermal budgets in advanced node manufacturing, forcing deposition equipment suppliers to requalify process flows around sub-200°C conformality requirements. Taiwan Semiconductor Manufacturing Company and Samsung Foundry procurement specifications now mandate PICVD compatibility for dielectric barrier layers at 3nm and below.
Growth Catalysts
- Logic node shrink requirements:Dielectric barrier films at 3nm and 2nm nodes require atomic-scale conformality that only temporally separated plasma pulses can deliver. Taiwan and South Korean foundries are expanding PICVD tool orders accordingly.
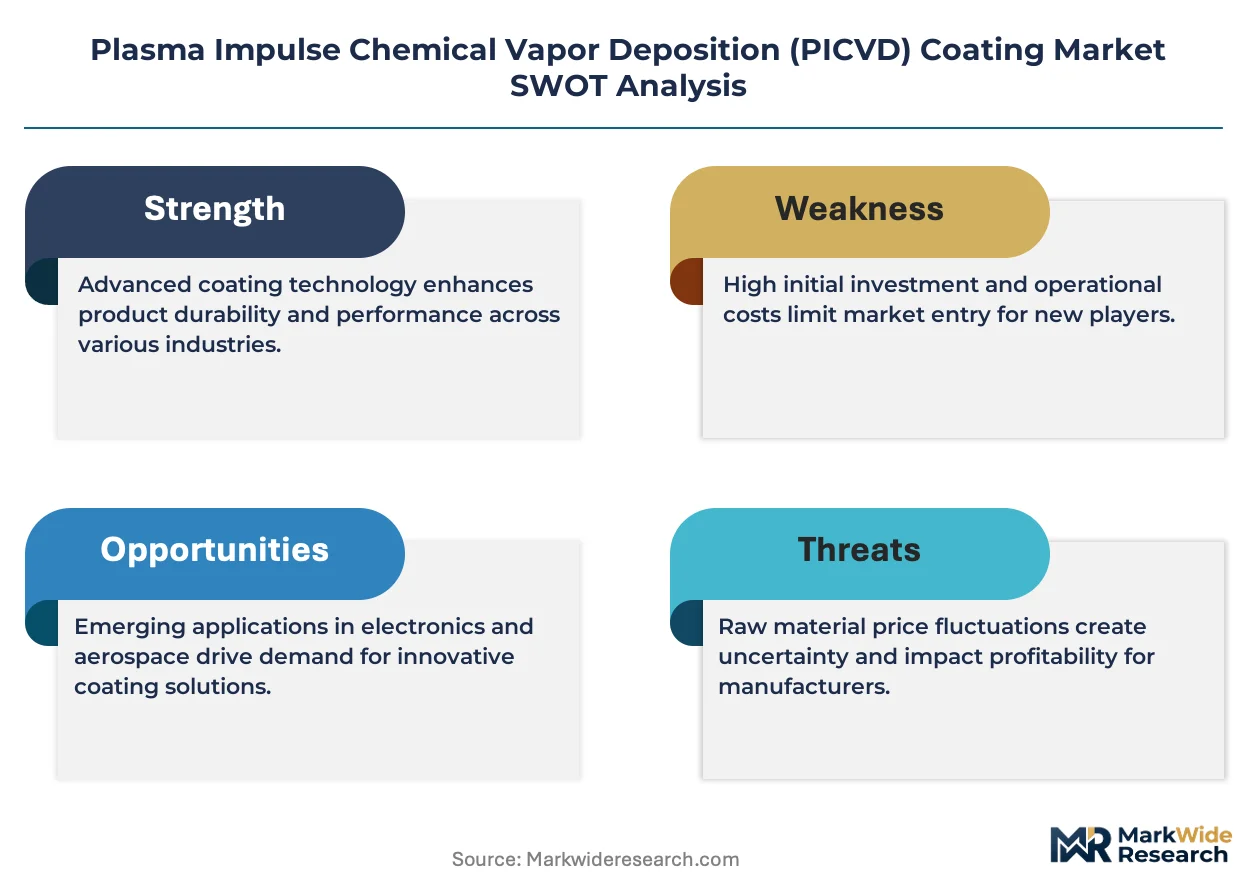
- REACH precursor substance restrictions:ECHA's tightening organometallic chemical handling rules are accelerating reformulation toward PICVD-compatible low-toxicity precursors in European installations.
- Industrial tool wear cost priority:Protective coating applications in cutting tools and molds are shifting from thermal CVD to PICVD to maintain substrate hardness without distortion.
Market Restraints
- Organometallic precursor cost volatility:Tantalum and hafnium organometallic feedstock prices fluctuate with rare earth supply concentration in Chinese processing facilities.
- Equipment supplier concentration:Vacuum chamber and pulsed power supply manufacturing concentrates among German and Swiss precision engineering suppliers, creating single-source vulnerability.
- Plasma uniformity limitations:Three-dimensional high-aspect-ratio structures above 10:1 depth-to-width ratios exhibit thickness variation that thermal ALD still outperforms.
Strategic Opportunities
- India's semiconductor manufacturing incentive scheme:PLI scheme subsidies for domestic fab construction create first-mover advantage for PICVD tool qualification with Tata Electronics and ISMC.
- Automotive power electronics packaging:Silicon carbide module encapsulation requires hermetic dielectric layers that PICVD delivers without thermal damage to solder joints.
- Japan's METI energy efficiency codes:Manufacturing equipment power consumption mandates favor PICVD's pulsed duty cycle over continuous plasma CVD for deposition energy intensity.
Industry Challenges
- Pulsed plasma process engineering talent scarcity:Universities in the United States and Europe produce insufficient plasma physics specialists qualified for reactor design and process integration roles.
- ISO 14644 cleanroom certification timelines:Equipment qualification for Class 1 and Class 10 fab environments requires 18-24 month validation cycles that delay revenue recognition.
- Legacy etch-deposition cluster tool integration:PICVD module retrofits into existing Lam Research and Applied Materials platform architectures demand custom interface engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plasma Impulse Chemical Vapor Deposition (PICVD) Coating Market |
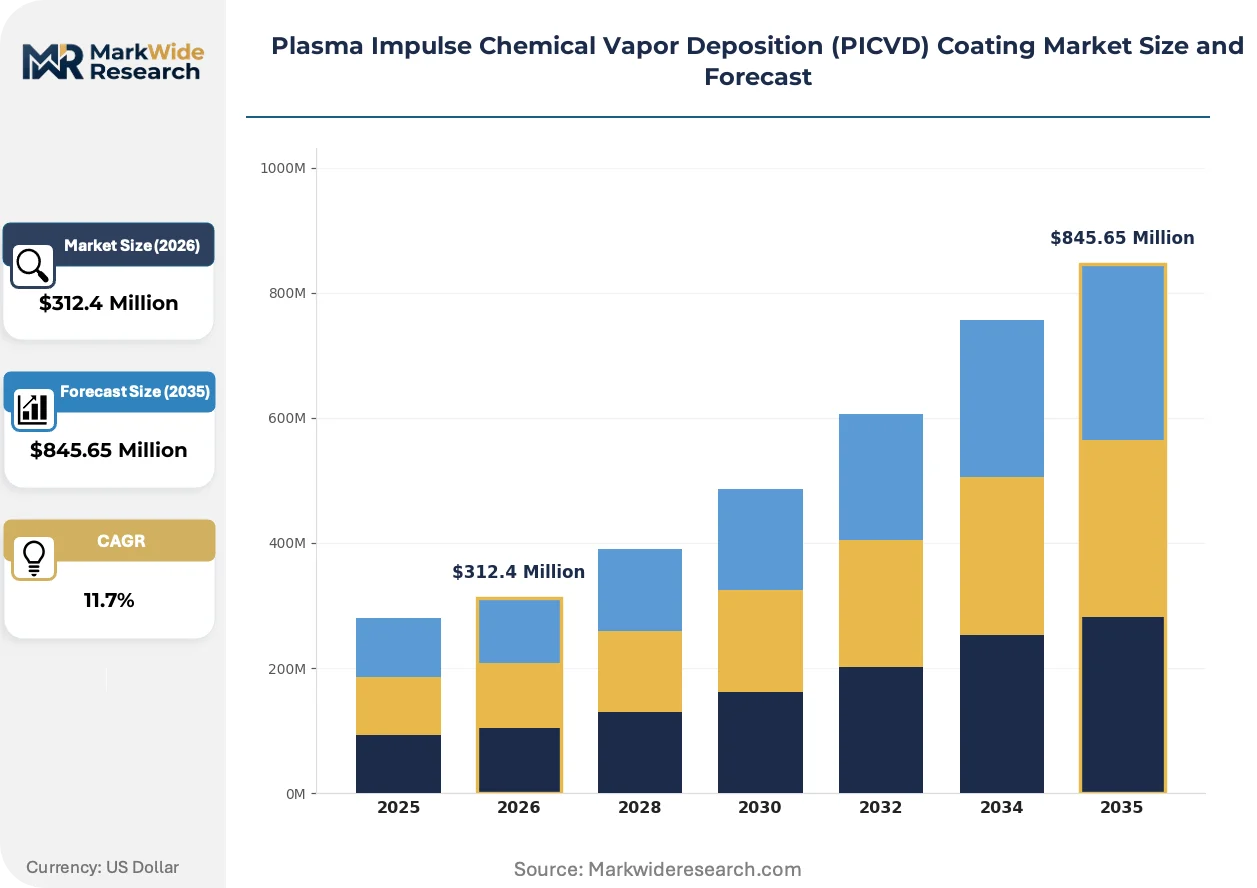
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $845.65 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
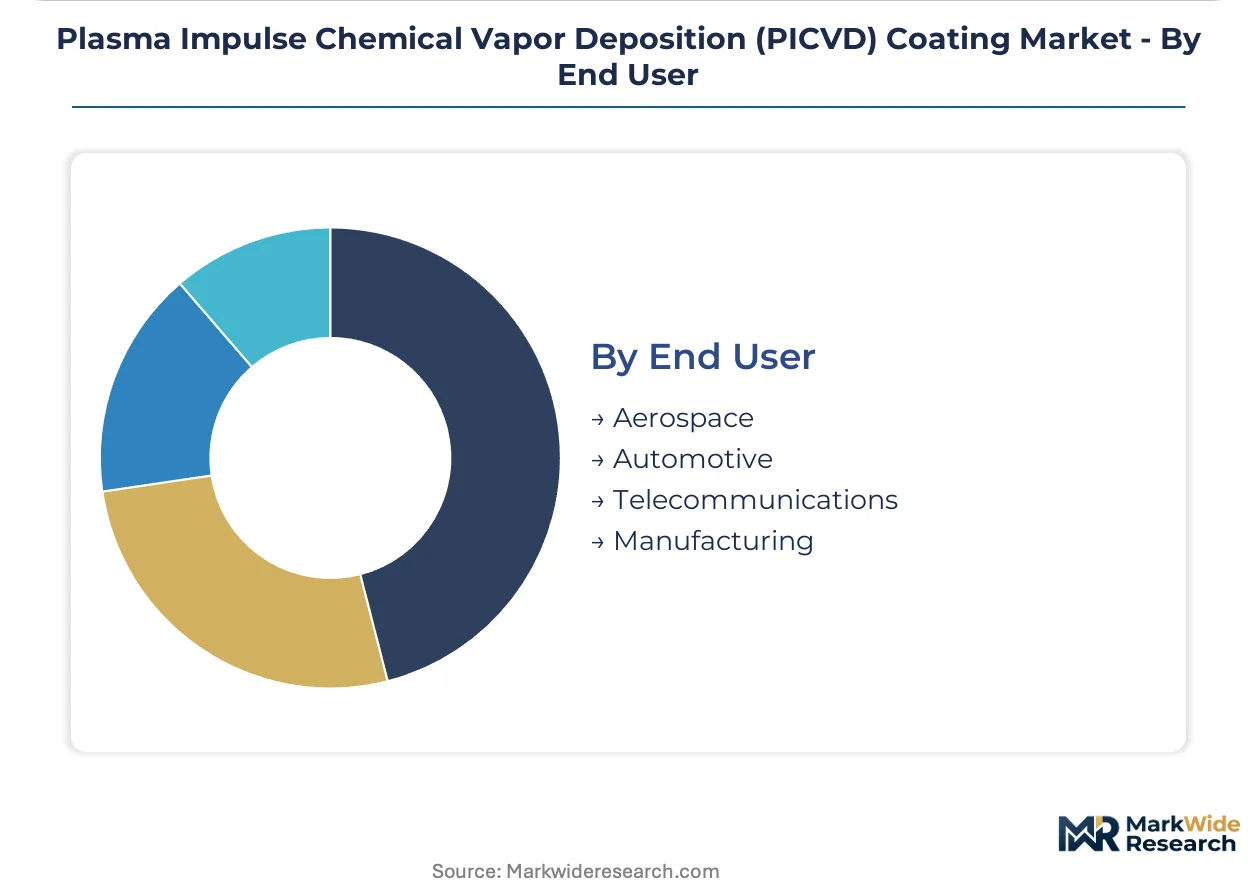
| Segmentation | Product Type: Thin Films, Coatings, Substrates, Adhesives Application: Semiconductors, Electronics, Optical Devices, Protective Coatings Technology: PVD, CVD, Sputtering, Laser Ablation End User: Aerospace, Automotive, Telecommunications, Manufacturing |
| Companies Covered | OC Oerlikon Management AG, Lam Research Corporation, Applied Materials, Inc., Aixtron SE, IHI Ionbond AG, ASM International N.V., ULVAC, CVD Equipment Corporation, Veeco Instruments Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plasma Impulse Chemical Vapor Deposition (PICVD) Coating Market Evolving Landscape
Temporal plasma modulation is displacing continuous-wave deposition across precision coating applications, compressing thermal budgets while expanding conformal coverage. Equipment architecture, precursor chemistry, and buyer procurement specifications are simultaneously recalibrating around this pulsed-energy paradigm.
Sub-50 nanometer conformal coating through temporally separated plasma pulses is decomposing the traditional trade-off between deposition temperature and film density. Memory manufacturers in South Korea are adopting PICVD for 3D NAND stack dielectrics at production scale. The technology is decomposing thermal ALD's monopoly on high-aspect-ratio gapfill, forcing incumbent suppliers to develop hybrid pulse-thermal reactor architectures.
EPA hazardous air pollutant standards for semiconductor manufacturing are compelling precursor reformulation across US-based fabrication facilities. Metal-organic deposition chemistries face stricter emissions monitoring and abatement requirements. Deposition tool buyers in Oregon and Arizona now specify integrated exhaust treatment systems as standard procurement terms.
Contract foundry procurement departments are unbundling deposition equipment purchases from long-term service agreements. Taiwan-based buyers now negotiate reactor hardware and process support as separate line items, compressing vendor margin structures. This pattern is most visible in Hsinchu Science Park procurement specifications, where tool vendors face explicit annual cost-reduction targets.
Plasma Impulse Chemical Vapor Deposition (PICVD) Coating Market Segmentation
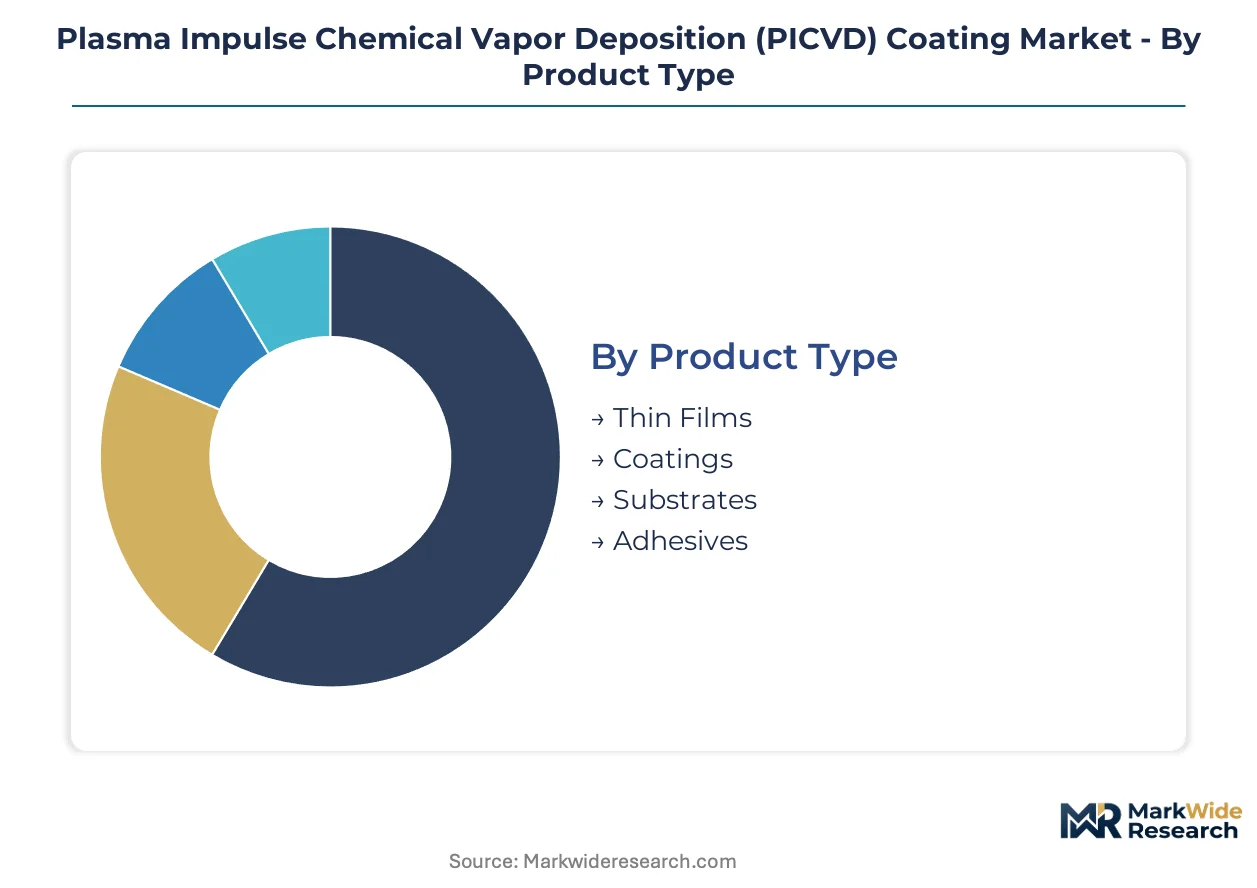
Segmentation in the PICVD coating market reveals how regulatory frameworks, thermal budget constraints, and end-use specifications fragment demand across incompatible technical specifications. Buyers in semiconductor fabrication impose fundamentally different qualification requirements than industrial tool coating purchasers.
Product Type:
REACH precursor substance restrictions and EPA hazardous air pollutant standards create divergent compliance burdens across product categories, with thin films facing the most stringent organometallic handling protocols.
- Thin Films:Dielectric barrier layers deposited at sub-50 nanometer thickness enable 3nm node conformality for Taiwan and South Korean logic foundries. Taiwan Semiconductor Manufacturing Company procurement specifications now mandate PICVD compatibility for these layers, with thermal budgets compressed below 200°C.
- Coatings:Protective layers for cutting tools and molds maintain substrate hardness without thermal distortion, shifting demand from thermal CVD as industrial buyers prioritize wear cost reduction over deposition speed.
- Substrates:Silicon carbide and gallium nitride wafer surface preparation for power electronics packaging.
- Adhesives:Specialized bonding layers for hermetic encapsulation in automotive module assembly.
Established volume favors thin films; emerging adoption favors coatings.
Application:
Application demand concentrates in East Asian contract foundries, with node shrink requirements forcing technology transitions that exclude legacy deposition methods.
- Semiconductors:Atomic-scale conformality for 3nm and 2nm logic nodes requires temporally separated plasma pulses that continuous-wave CVD cannot deliver. Samsung Foundry and Taiwan Semiconductor Manufacturing Company have expanded PICVD tool orders for dielectric barrier films.
- Electronics:Printed circuit board and interconnect protection layers where thermal damage to solder joints must be avoided.
- Optical Devices:Precision lens and mirror coatings demanding uniform thickness across curved surfaces.
- Protective Coatings:Expanding most quickly as manufacturing tool wear costs become a priority for automotive and aerospace supply chains, with PICVD displacing thermal methods for hard coatings on complex geometries.
Semiconductor applications anchor current revenue; protective coatings are climbing the fastest.
Technology:
Technology selection reflects a trade-off between conformality requirements and throughput economics, with pulsed plasma architectures gaining share in precision applications.
- PVD:Physical vapor deposition retains majority installed base in commodity coating applications where conformality requirements remain modest.
- CVD:Chemical vapor deposition variants including PICVD-specific pulsed configurations are displacing continuous-wave systems in logic device manufacturing.
- Sputtering:Magnetron and ion beam methods for metal layer deposition where line-of-sight coverage suffices.
- Laser Ablation:Pulsed laser deposition for specialized ceramic and oxide films in research and prototype settings.
PVD maintains equipment population; CVD variants gain process share.
End User:
End user procurement patterns split between fab-scale volume contracts and specialized industrial tool orders with diverging qualification timelines.
- Aerospace:Turbine blade and engine component coatings requiring thermal barrier properties without substrate distortion.
- Automotive:Silicon carbide power module encapsulation demands hermetic dielectric layers that PICVD delivers without damaging solder joints, with packaging requirements expanding alongside electric vehicle inverter production.
- Telecommunications:Optical fiber and photonic device coatings for signal transmission equipment.
- Manufacturing:Cutting tool, mold, and die protection where wear-related downtime costs drive coating investment decisions.
Manufacturing dominates tool shipments; automotive represents the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Kaohsiung-Taichung high-speed rail corridor underwrites Taiwan's dominance in advanced semiconductor fabrication, connecting Hsinchu Science Park to southern packaging clusters. South Korea's KTX Gyeongbu line similarly binds Seoul's R&D centers to Pyeongtaek's mega-fabs. These transport arteries enable just-in-time precursor delivery and equipment servicing across East Asia's deposition tool networks.
United States
Oregon and Arizona fab construction drives PICVD tool demand for dielectric barrier deposition at advanced nodes. EPA hazardous air pollutant standards compel integrated exhaust treatment systems in all new installations. Hillsboro's Intel campus anchors Pacific Northwest deposition equipment procurement, with tool vendors facing mandatory annual cost-reduction targets.
Taiwan
TSMC and UMC procurement specifications now mandate PICVD compatibility for 3nm logic node dielectric layers. The country's energy efficiency codes for manufacturing equipment favor pulsed duty cycles over continuous plasma CVD. Hsinchu Science Park concentrates the world's densest cluster of PICVD reactor installations, with foundries unbundling hardware and service contracts.
South Korea
Samsung Foundry and SK Hynix expand PICVD adoption for 3D NAND stack dielectrics and advanced logic barrier films. METI-equivalent energy consumption mandates shape equipment selection criteria for domestic fab operators. Pyeongtaek's semiconductor complex hosts the highest concentration of pulsed plasma deposition systems outside Taiwan.
Germany
Precision engineering suppliers in Baden-Württemberg and Bavaria dominate vacuum chamber and pulsed power supply manufacturing for PICVD systems. REACH organometallic precursor restrictions accelerate reformulation toward low-toxicity chemistries in European installations. Dresden's Silicon Saxony cluster anchors continental deposition equipment R&D and process qualification.
Japan
Memory manufacturers adopt PICVD for high-aspect-ratio gapfill applications, displacing thermal ALD in select process steps. METI energy efficiency codes for manufacturing equipment explicitly favor pulsed plasma architectures over continuous-wave deposition. Hiroshima and Yokkaichi fab clusters drive domestic tool qualification cycles.
Plasma Impulse Chemical Vapor Deposition (PICVD) Coating Market Competitive Landscape
Listed leaders compete with private specialists across equipment architecture and service bundling dimensions. The vendor base concentrates around vacuum technology heritage firms and semiconductor process flow integrators, with Swiss-German precision engineering suppliers anchoring critical subcomponent supply. Three archetypes dominate: integrated platform vendors extending etch-deposition clusters, vacuum specialists leveraging heritage reactor designs, and deposition-only challengers unbundling hardware from process support. Competitive moves center on cleanroom certification acceleration and precursor chemistry co-development partnerships.
Within the integrated platform tier, Lam Research Corporation and Applied Materials, Inc. exemplify the dominant archetype of etch-deposition cluster tool vendors extending process flow integration. OC Oerlikon Management AG represents the vacuum heritage specialist model, leveraging Swiss precision engineering roots in European installations. These three occupy positions that span hardware supply, process qualification, and long-term service contracting across divergent procurement specifications.
| Leading Market Players |
|---|
| OC Oerlikon Management AG |
| Lam Research Corporation |
| Applied Materials, Inc. |
| Aixtron SE |
| IHI Ionbond AG |
| ASM International N.V. |
| ULVAC |
| CVD Equipment Corporation |
| Veeco Instruments Inc. |
| Others |
Value Network & Pricing Analysis
Eighteen-month equipment qualification cycles for Class 1 cleanroom certification compress pricing power for PICVD reactor suppliers while amplifying buyer leverage in contract negotiations. Taiwan Semiconductor Manufacturing Company and Samsung Foundry exploit these extended lead times to unbundle hardware purchases from service agreements, forcing vendors into annual cost-reduction commitments.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates ISO 14644 Class 1 certified systems from Class 10 configurations and uncertified industrial coating units. Price differentiation hinges on cleanroom certification grade and after-sales service bundling, with premium tiers commanding substantial markups for integrated process support. Cost compression in standard-tier equipment is intensifying as foundry procurement departments negotiate reactor hardware and maintenance contracts as separate line items. Contract foundries in Hsinchu Science Park exhibit the highest price sensitivity, while aerospace turbine blade coaters prioritize performance over unit economics.
Supply Chain Analysis
Strait of Malacca transit routes underpin precursor chemical flows from German and Swiss organometallic suppliers to East Asian fabrication clusters. Vacuum chamber and pulsed power supply manufacturing concentrates in Baden-Württemberg and Bavaria, creating single-source vulnerability for reactor system assembly. Raw material dependencies encompass tantalum and hafnium organometallic feedstocks, high-purity quartz chambers, and precision-engineered gas delivery manifolds. Tariff exposure on Chinese-processed rare earth elements threatens feedstock cost stability. Distribution runs through direct equipment sales to fab operators, with aftermarket parts and precursor replenishment contracted separately.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Node shrink requirements and regulatory fragmentation across EPA, REACH, and METI jurisdictions fragment procurement specifications, creating specialized niches for deposition technology providers. This dispersion rewards focused specialists alongside integrated platform vendors.
For Market Incumbents: Shield installed base relationships through backward integration into precursor chemistry co-development partnerships, countering emerging deposition-only challengers unbundling hardware from process support. Accelerate ISO 14644 cleanroom certification timelines to 12-15 months through predictive validation protocols, neutralizing buyer leverage over extended qualification cycles. For New Entrants and Emerging Players: Differentiate on automotive power electronics packaging applications, where silicon carbide module encapsulation demands hermetic dielectric layers without thermal damage to solder joints. Target India's PLI scheme semiconductor manufacturing incentives for first-mover PICVD tool qualification with Tata Electronics and ISMC, exploiting unpenetrated domestic fab construction. For Investors and Strategic Acquirers: Long-term, this sits as a process-control consolidation play because pulsed plasma engineering talent scarcity and equipment supplier concentration favor acquirers with vacuum technology heritage and captive service networks. Watch for inflection when Taiwan and South Korean foundries mandate PICVD compatibility at 2nm logic nodes, triggering replacement demand across legacy thermal ALD installations.| Strategic Initiative | Industry Significance |
|---|---|
| Precursor Chemistry Co-Development Partnership | REACH and EPA reformulation mandates force joint R&D between equipment vendors and chemical suppliers. |
| Cleanroom Certification Acceleration Program | Reducing Class 1 validation cycles from 24 to 15 months recaptures pricing power from foundry buyers. |
| Automotive Power Electronics Module Qualification | Silicon carbide inverter packaging requirements open hermetic encapsulation revenue streams outside semiconductor fabs. |
| India PLI Scheme Tool Localization | Domestic fab construction subsidies create captive market for PICVD reactor qualification with Tata Electronics. |
| Pulsed Plasma Process Engineering Talent Acquisition | University pipeline gaps in plasma physics specialization favor acquirers with established training infrastructure. |
Research Methodology
Desk research of SEC 10-K filings, ECHA substance restriction databases, and METI energy efficiency code documentation preceded structured interviews with PICVD reactor design engineers, fab procurement managers at Taiwan and South Korean foundries, organometallic precursor supply directors, and cleanroom certification auditors. Primary fieldwork combined with secondary validation through trade customs data and semiconductor equipment import records. Bottom-up unit shipment estimates triangulated against top-down wafer fab capacity expansion projections.
Variance decomposition across product type, application, technology, and end-user dimensions anchored the analytical framework over the projection horizon. Modeled segmentation captured thin film versus coating demand splits, logic node generation transitions, pulsed versus continuous-wave technology substitution patterns, and regional fab construction pipelines. CAGRs derived from equipment shipment trajectories and average selling price evolution, with inputs from precursor chemical consumption volumes and cleanroom certification backlog observations.
The analysis sits within stated boundaries; outcomes outside sustained East Asian foundry capital expenditure levels or stable rare earth processing access would require recalibration. Forecasts reflect documented assumptions regarding node shrink timelines and regulatory enforcement intensity. Practitioners should keep alternative scenarios live as EPA hazardous air pollutant standards and REACH organometallic restrictions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Saudi Arabia Industrial Coatings Market
Coatings
Automotive Conformal Coatings Market
Coatings
FEVE Fluoropolymer Coatings Market
Coatings
Global Hydrophobic Coating Market
Coatings
Global Low Temperature Powder Coatings Market
Coatings
North America Powder Coatings Market
Coatings
Europe Waterborne Polyurethane Coatings Market
Coatings
Spain Automotive OEM Coatings Market
Coatings
Electrical Appliance Coatings Market
Coatings
Stealth Coating Material Market
Coatings
Food Grade Ceramic Coatings Market
Coatings
United States Industrial Wood Coatings Market
Coatings
Carbon Fiber Coatings Market
Coatings
Global Heat Resistant Coatings Market
Coatings
Coating Market
Coatings
Polyvinylidene Chloride (PVDC) Coated Films Market