
 Soft Touch Polyurethane Coatings Market | 2026-2036
Soft Touch Polyurethane Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Soft Touch Polyurethane Coatings Market Outlook
Aftermarket surface refurbishment is reconfiguring margin pools away from virgin coating sales toward recoating services and touch-up solutions. PPG Industries Ltd sustains technology leadership through proprietary soft-touch resin systems for automotive dashboards. BASF SE leverages its integrated polyurethane precursor chain to control raw material quality and cost positions. Akzo Nobel N.V. anchors European demand through specialized water-based formulations that meet stringent emissions protocols.
Soft touch polyurethane coatings are elastomeric surface finishes formulated with polyol-isocyanate reaction products, typically yielding Shore A hardness values between 30 and 80, designed to provide tactile warmth and scratch resistance on plastic, metal, and wood substrates. Water-based formulations lead volume due to regulatory pressure on volatile organic compound emissions, while UV-cured systems represent the fastest-expanding segment for electronics applications requiring rapid processing and low thermal exposure. Automotive interiors command the largest application share, though consumer electronics is displacing traditional glossy finishes with soft-touch alternatives in premium device housings.
EPA VOC regulations in the United States and REACH chemical restrictions in Europe constrain solvent-based formulation growth, compelling manufacturers toward compliant waterborne and UV technologies. ECHA substance evaluation processes are accelerating substitution of certain isocyanate hardeners, reshaping raw material procurement across the value chain. ISO 9001 and IATF 16949 quality frameworks govern automotive supplier qualification, creating certification barriers for new entrants. Stakeholders must monitor evolving chemical hazard classifications and polymer recycling mandates that will determine which formulation platforms retain long-term viability.
Market Dynamics
Automotive OEMs are consolidating haptic surface specifications across platform architectures, compressing formulation diversity and favoring suppliers with validated water-based systems that satisfy REACH substance restrictions and IATF 16949 quality mandates.
Growth Catalysts
- EU Green Deal compliance deadlines:European furniture manufacturers are accelerating solvent-to-waterborne conversion to avoid production penalties, expanding addressable volume for compliant coating platforms.
- Automotive interior trim standardization:Dashboard and door panel applications now specify soft-touch finishes as default across premium and mid-tier vehicle segments.
- UV-cured processing speed:Electronics contract manufacturers in East Asia are adopting rapid-cure systems to meet compressed handset housing production cycles without thermal damage to sensitive components.
Market Restraints
- Aliphatic isocyanate supply concentration:German and Belgian precursor producers control critical hardener volumes, exposing formulators to input cost volatility and allocation risk.
- REACH authorization timelines:ECHA substance evaluation processes for certain polyol chemistries are extending reformulation cycles beyond typical automotive qualification windows.
- Thermoplastic elastomer substitution:Injection-molded TPE skins are capturing share in cost-sensitive consumer electronics housings where coating adds process steps.
Strategic Opportunities
- India furniture export manufacturing:Uttar Pradesh and Tamil Nadu clusters are expanding capacity for European retail private-label supply, creating demand for REACH-compliant coating systems.
- Medical device housings:ISO 10993 biocompatibility certification is opening diagnostic equipment and wearable monitor applications previously served by hard-coat polycarbonate.
- China dual carbon policy:Provincial MEE enforcement of VOC emissions limits is forcing domestic coating operations toward water-based polyurethane platforms that multinational suppliers dominate.
Industry Challenges
- IATF 16949 certification duration:Automotive supplier qualification timelines extend 18-24 months, freezing out formulation innovators without existing OEM relationships.
- Color-matching precision requirements:Batch-to-batch haptic consistency demands specialized rheology control that strains legacy production equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Soft Touch Polyurethane Coatings Market |
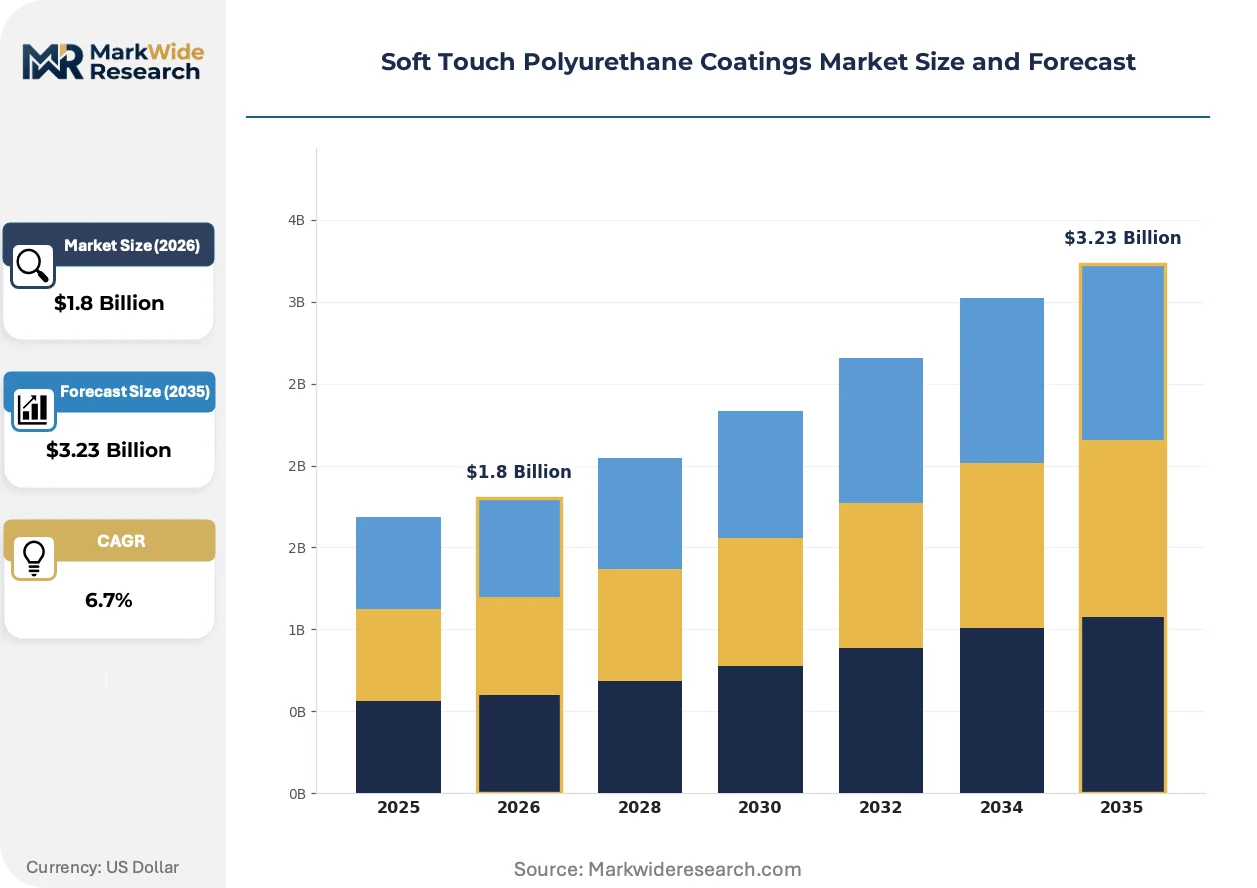
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Water-based, Solvent-based, UV-cured, Two-component Application: Automotive Interiors, Consumer Electronics, Furniture, Building Materials End User: Manufacturers, Retailers, Distributors, Contractors Formulation: Flexible, Rigid, Thixotropic, Non-slip |
| Companies Covered | The Sherwin-Williams Company, Akzo Nobel N.V., PPG Industries Ltd, Axalta Coating Systems, BASF SE, Jotun AS, Rust-Oleum - RPM International Inc., Aexcel Coatings, Sokan New Materials, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Soft Touch Polyurethane Coatings Market Strategic Shifts
Formulation chemistry is converging with digital color-matching systems and accelerated curing platforms to compress development cycles and enable mass-customization of tactile surfaces.
Self-matting polyurethane dispersions are virtualizing the traditional two-coat primer-topcoat architecture by integrating haptic and visual control in single-layer application. Tier-one automotive suppliers in Germany and Japan are validating these systems for dashboard programs launching through 2027. This consolidation is virtualizing capital allocation away from spray-booth expansion toward precision dosing and inline inspection equipment.
REACH restriction proposals targeting specific aromatic isocyanates are forcing hardener substitution toward aliphatic alternatives with higher raw material costs and modified reactivity profiles. Formulators serving European automotive and furniture end-uses are rebuilding supply chain relationships around certified precursor streams. Water-based systems with aliphatic hardeners are capturing specification share previously held by solvent-borne aromatic formulations.
Electronics brand owners are unbundling coating specification from assembly contracts, creating direct procurement relationships with specialized polyurethane suppliers. This disintermediation shifts technical accountability from contract manufacturers to coating formulators and accelerates qualification cycles for new haptic finishes. South Korean and Vietnamese electronics assembly hubs are most advanced in this restructuring, with brand technical teams now co-locating at coating development centers.
Soft Touch Polyurethane Coatings Market Segmentation
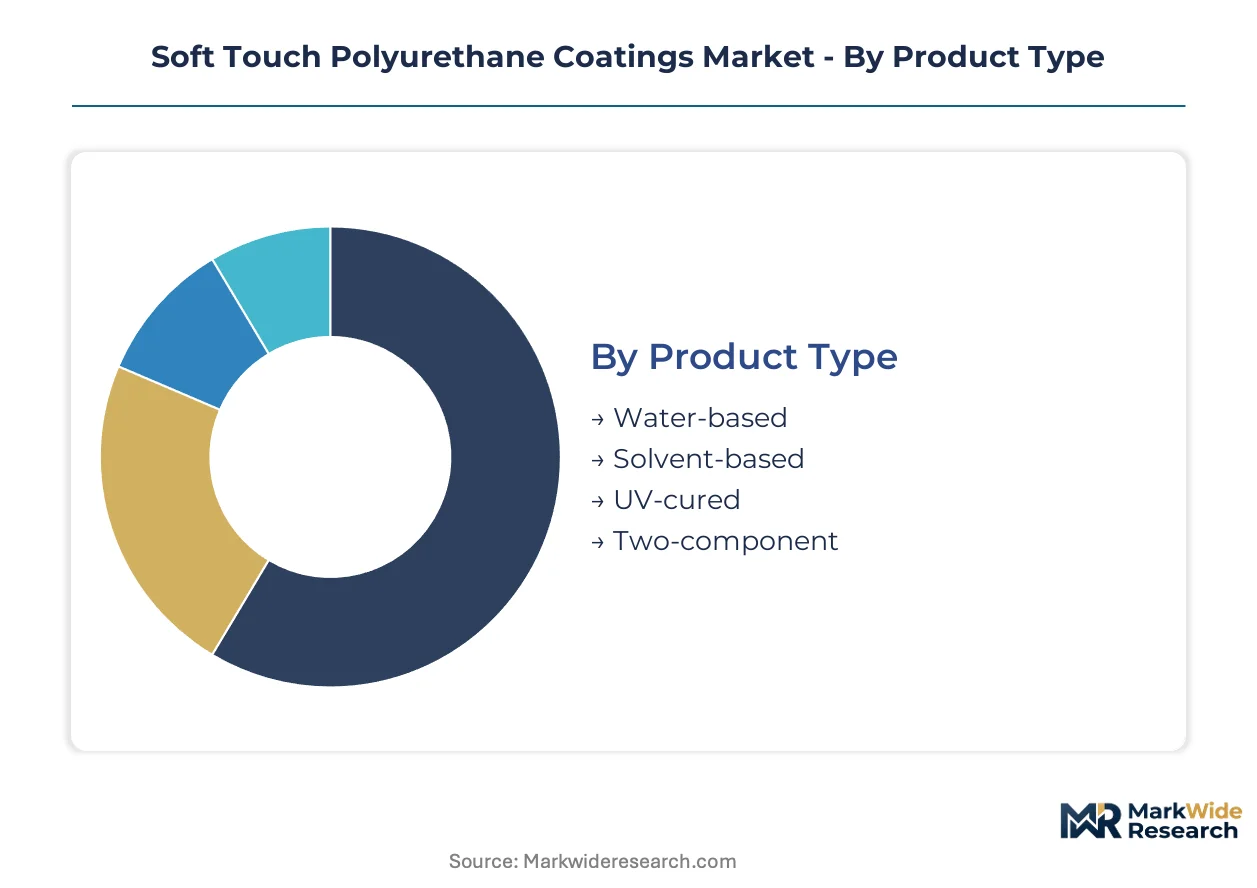
Segmentation in soft touch polyurethane coatings reveals how formulation chemistry, application requirements, and procurement channels intersect to create distinct competitive arenas. Each dimension carries specific technical and commercial imperatives that reshape supplier priorities.
Product Type:
Mature water-based systems dominate regulatory-compliant supply chains, while emerging UV-cured platforms are compressing processing cycles in electronics manufacturing.
- Water-based:Polyurethane dispersions with aliphatic isocyanate hardeners satisfy EPA VOC limits and REACH substance restrictions. German automotive OEMs specify these systems for dashboard programs requiring IATF 16949 certification. Water-based formulations handle the majority of throughput; UV-cured is the fastest mover on share.
- Solvent-based:Aromatic isocyanate-cured systems retain residual share in furniture export manufacturing where curing infrastructure investment lags. Uttar Pradesh clusters in India still specify solvent-borne coatings for cost-sensitive private-label production bound for European retail.
- UV-cured:Rapid polymerization under ultraviolet exposure enables sub-minute processing of handset housings in Vietnamese and South Korean contract manufacturing. Electronics brand owners now procure these systems directly, bypassing traditional assembly intermediaries.
- Two-component:Separated polyol and isocyanate streams mixed at point of application deliver customized hardness profiles for medical device housings requiring ISO 10993 biocompatibility.
Water-based systems anchor volume; UV-cured coatings are climbing the fastest as electronics brands reshore specification control.
Application:
Cost tier differentiation separates premium automotive interior programs from commodity furniture finishing, with consumer electronics occupying a mid-tier position defined by processing speed requirements.
- Automotive Interiors:Dashboard, door panel, and steering wheel applications specify Shore A 40-60 elastomeric finishes that deliver tactile warmth and scratch resistance. German coating clusters around Stuttgart and Wolfsburg validate formulations through 18-24 month OEM qualification cycles. Automotive interiors handle the majority of throughput; consumer electronics is gaining share fastest.
- Consumer Electronics:Premium smartphone and laptop housings displace glossy polycarbonate with soft-touch alternatives. South Korean and Vietnamese assembly hubs drive specification unbundling that accelerates formulator-direct procurement relationships.
- Furniture:European retail private-label demand from German and French distributors enforces REACH compliance across Tamil Nadu and Uttar Pradesh export manufacturing clusters.
- Building Materials:Architectural hardware and fixture applications specify non-slip thixotropic formulations for commercial interior environments.
Automotive interiors command the largest revenue pool; consumer electronics applications are expanding most quickly as brand owners consolidate haptic surface specifications.
End User:
Customer type determines technical accountability placement, with manufacturers retaining formulation specification authority while distributors manage logistics for fragmented contractor demand.
- Manufacturers:Tier-one automotive suppliers and electronics contract manufacturers hold direct relationships with coating formulators. IATF 16949 and ISO 9001 certification requirements freeze out new entrants without existing OEM validation history.
- Retailers:European furniture retail chains enforce REACH-compliant coating specifications across Indian and Chinese export manufacturing through private-label procurement mandates.
- Distributors:Regional coating distributors serve fragmented building materials and refurbishment demand, consolidating small-batch orders from contractors and maintenance operators.
- Contractors:Aftermarket surface refurbishment specialists drive recoating service revenue, shifting margin pools away from virgin coating sales toward touch-up solutions and field application labor.
Manufacturers direct the largest formulation volumes; contractors represent the fastest-expanding channel as aftermarket refurbishment displaces new coating demand.
Formulation:
Volume concentration in flexible systems contrasts with margin concentration in specialized thixotropic and non-slip variants serving safety-critical applications.
- Flexible:Low-modulus elastomeric finishes yielding Shore A 30-50 dominate automotive interior and consumer electronics haptic specifications. Self-matting dispersions are virtualizing traditional primer-topcoat architectures into single-layer application.
- Thixotropic:Shear-thinning rheology enables vertical surface application without sag on architectural hardware and medical equipment housings.
- Non-slip:High-friction surface finishes serve building materials and industrial equipment applications where safety mandates override tactile aesthetics.
- Rigid:Higher hardness formulations retain limited share in decorative furniture applications where scratch resistance outweighs elastomeric feel.
Flexible formulations carry the dominant volume share; thixotropic systems are advancing fastest as medical device and architectural safety specifications proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany consumes soft touch polyurethane coatings primarily for automotive dashboard validation, while China deploys identical chemistries for electronics contract manufacturing speed. India redirects European furniture export demand through Tamil Nadu coating operations. Each geography imposes distinct formulation requirements that reshape supplier priorities.
Germany
Automotive OEMs in Stuttgart and Wolfsburg specify REACH-compliant water-based systems for interior trim programs. ECHA substance evaluations for aromatic isocyanates are accelerating hardener substitution toward aliphatic alternatives. Coating clusters around Wolfsburg validate formulations through 18-24 month IATF 16949 qualification cycles.
China
Provincial MEE enforcement of VOC emissions limits is forcing coating operations toward water-based polyurethane platforms. Electronics assembly in Dongguan and Shenzhen adopts UV-cured systems for sub-minute handset housing processing. Yangtze River Delta chemical parks are consolidating compliant formulation capacity.
United States
EPA VOC regulations constrain solvent-based growth in automotive aftermarket refurbishment. Tier-one suppliers in Michigan and Ohio specify soft-touch finishes for premium truck interior programs. Detroit-area coating operations are rebuilding supply chains around certified aliphatic precursor streams.
India
Uttar Pradesh and Tamil Nadu furniture export clusters are expanding capacity for European retail private-label supply. BIS standards alignment with REACH substance restrictions is redirecting formulation strategies toward waterborne systems. Coimbatore coating operations are qualifying compliant systems for German distributor procurement.
South Korea
Electronics brand owners in Seoul are unbundling coating specification from assembly contracts, creating direct procurement relationships with polyurethane suppliers. MFDS chemical safety assessments are accelerating substitution of legacy hardener chemistries. Busan-area development centers are co-locating brand technical teams with formulator R&D facilities.
Soft Touch Polyurethane Coatings Market Competitive Environment
Capability concentration sits with integrated chemical producers; scale advantage sits with diversified coating specialists. The market structures around three tiers: multinational resin producers with captive precursor supply, regional formulators with validated automotive qualifications, and electronics-focused specialists with rapid-cure platforms. Two competitive moves dominate: backward integration into polyurethane precursor production and direct procurement relationships with electronics brand owners.
Within the integrated chemical tier, BASF SE exemplifies upstream control over polyol-isocyanate reaction products. Among diversified coating specialists, PPG Industries Ltd and Akzo Nobel N.V. occupy positions validated through automotive OEM qualification histories. These three anchors represent distinct strategic archetypes: captive raw material security, automotive specification authority, and European regulatory compliance leadership.
| Leading Market Players |
|---|
| The Sherwin-Williams Company |
| Akzo Nobel N.V. |
| PPG Industries Ltd |
| Axalta Coating Systems |
| BASF SE |
| Jotun AS |
| Rust-Oleum - RPM International Inc. |
| Aexcel Coatings |
| Sokan New Materials |
| Others |
Value Chain & Pricing Dynamics
German and Belgian aliphatic isocyanate producers anchor upstream hardener supply, concentrating margin capture in precursor manufacturing while downstream formulators absorb volatility through indexed contract structures.
Pricing Analysis
Long-term offtake agreements dominate automotive supply relationships, with tier-one suppliers locking 18-24 month pricing indexed to aliphatic isocyanate spot markets. Three-tier pricing structure across IATF 16949-certified premium, ISO 9001-standard, and uncertified economy levels reflects qualification investment recovery. Cost compression in electronics UV-cured segments is intensifying because brand owners unbundle specification control and compress development cycles. Furniture export manufacturers in India exhibit highest price sensitivity due to private-label margin constraints, while automotive OEMs prioritize haptic consistency over unit cost.
Supply Chain Analysis
Electronics contract manufacturers in Vietnam and South Korea hold dominant coating application capacity, driving formulator-direct procurement relationships that bypass traditional assembly intermediaries. Raw material sourcing draws from German polyol producers, Chinese specialty chemical intermediates, and Belgian isocyanate hardener streams. Single-source vulnerability concentrates in aliphatic precursor supply where Belgian and German producers control qualified volumes. Distribution runs through regional coating distributors serving fragmented building materials demand alongside direct manufacturer relationships in automotive and electronics verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aftermarket recoating services and touch-up solutions are expanding faster than virgin coating sales, creating durable recurring revenue streams that outpace hardware volume growth.
For Market Incumbents: Pre-empt thermoplastic elastomer substitution in consumer electronics by accelerating UV-cured platform development cycles and embedding formulator technical teams at brand owner development centers. Secure backward integration into aliphatic isocyanate precursor supply or lock multi-year offtake agreements with Belgian and German hardener producers to defend margin positions against raw material allocation risk. For New Entrants and Emerging Players: Establish a beachhead in medical device housing applications requiring ISO 10993 biocompatibility certification, where incumbent qualification histories are thinner and price sensitivity is lower than automotive. Target Indian furniture export clusters in Tamil Nadu and Uttar Pradesh with REACH-compliant water-based formulations as European retail private-label mandates accelerate solvent-to-waterborne conversion. For Investors and Strategic Acquirers: Capital is best deployed toward regional formulators with validated IATF 16949 automotive qualifications and established OEM relationships, as certification barriers protect incumbent positions through multi-year qualification cycles. Watch ECHA substance evaluation timelines for aromatic isocyanate restrictions as an inflection signal that would force rapid hardener substitution and reshape competitive positioning across European supply chains.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aliphatic Isocyanate Precursors | Captive hardener supply insulates BASF and integrated producers from allocation volatility affecting formulator margins. |
| Direct Procurement Relationship with Electronics Brand Owners | South Korean and Vietnamese brand technical teams co-locating at formulator R&D centers accelerates qualification cycles. |
| REACH-Compliant Water-Based Platform Expansion | European furniture export mandates from German and French distributors enforce compliant coating specifications across Indian manufacturing. |
| Self-Matting Dispersion Technology Validation | Single-layer primer-topcoat virtualization reduces capital requirements for tier-one automotive suppliers in Stuttgart and Wolfsburg. |
| ISO 10993 Biocompatibility Certification Investment | Diagnostic equipment and wearable monitor specifications previously served by hard-coat polycarbonate open polyurethane penetration. |
Study Parameters
A standing panel of automotive tier-one procurement directors, electronics contract manufacturing operations managers, furniture export production heads, and coating formulator R&D directors provided ongoing calibration across primary interview cycles. Secondary validation drew from ECHA substance evaluation databases, EPA VOC regulation filings, customs trade data for polyurethane precursor flows, and IATF 16949 certification registries. Bottom-up segment sizing triangulated against top-down chemical industry production estimates.
Scenario-bracketing across regulatory acceleration, raw material supply disruption, and substitution technology penetration defined the analytical envelope. Segmentation modeling incorporated formulation chemistry, application end-use, procurement channel structure, and regional regulatory cluster dimensions. CAGRs were derived from slope analysis of validated data points across the projection horizon, with automotive production forecasts and electronics assembly volume trends serving as demand-side anchors.
Stress conditions across ECHA authorization timelines, aliphatic isocyanate price volatility bands, and thermoplastic elastomer substitution rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory enforcement consistency and OEM qualification cycle duration. Quarterly review of ECHA substance evaluation progress, provincial MEE enforcement actions in China, and electronics brand owner procurement restructuring announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Global Low Friction Coatings Market
Coatings
Global Radiation Cured Coatings Market
Coatings
Biopolymer Coatings Market
Coatings
Asia-Pacific Anti-Friction Coatings Market
Coatings
United Kingdom Automotive OEM Coatings Market
Coatings
Plasma Impulse Chemical Vapor Deposition (PICVD) Coating Market
Coatings
Global Wood Protection Coating Market
Coatings
Global Antiviral Coatings Market
Coatings
Intumescent Fire Retardant Coating Market
Coatings
Mold Release Coatings Market
Coatings
Color-Shifting Coating Market
Coatings
Japan Architectural Coatings Market
Coatings
US Industrial Coatings Market
Coatings
Ultraviolet (UV) Coatings Market
Coatings
Global Polyaspartic Coatings Market
Coatings
Russia Protective Coatings Market