
 Global Pervious Pavement Market | 2026-2036
Global Pervious Pavement Market Size, Share, and Industry Trends Forecast 2026-2036
Global Pervious Pavement Market Intelligence
A transition from single-source material contracts to multi-source procurement for specialized chemical admixtures is expanding contractor flexibility. LafargeHolcim leverages its extensive network of ready-mix plants to supply permeable concrete for large-scale projects. Sika AG specializes in the admixtures that enhance the performance and durability of these systems. Meanwhile, CEMEX S.A.B. de C.V. competes by offering integrated design and installation support services alongside its material supply.
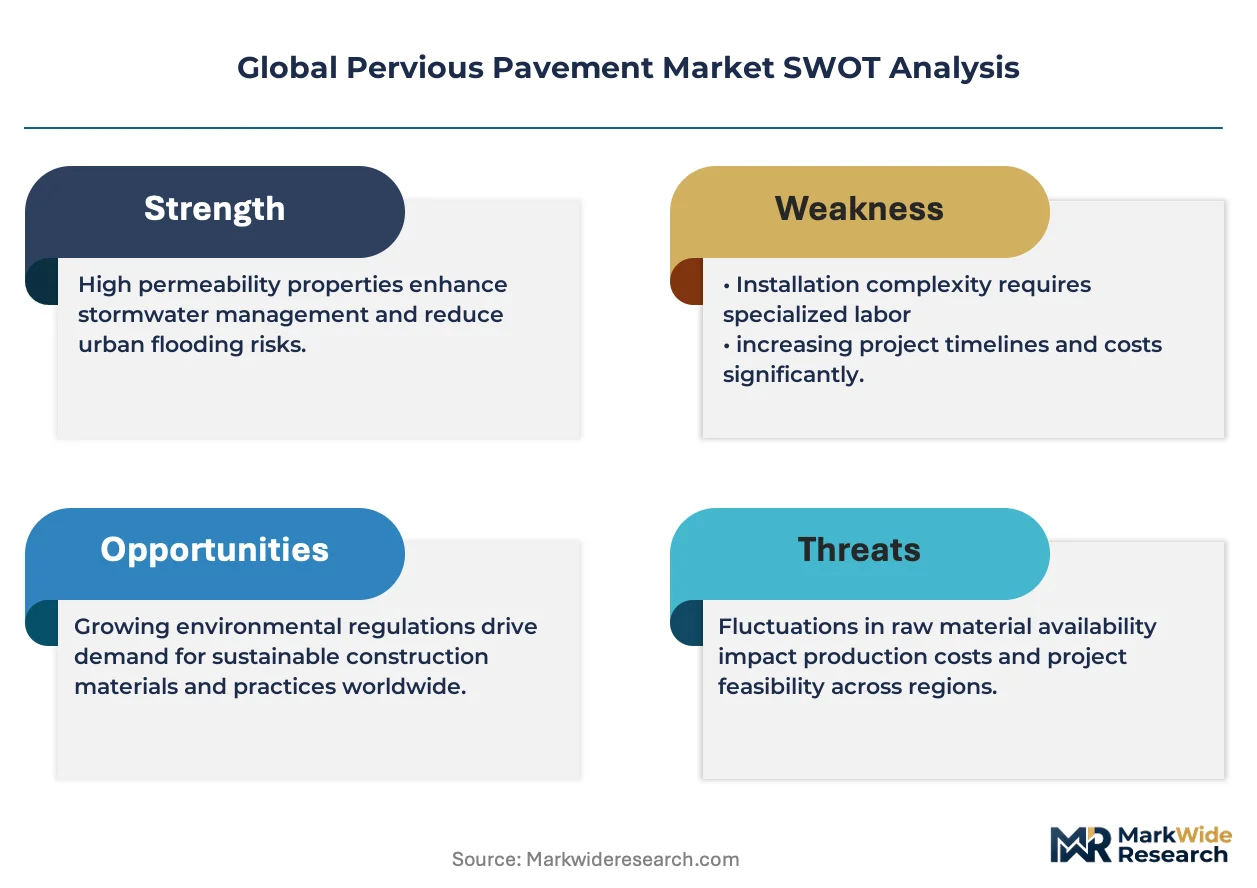
Pervious pavement is an engineered surface containing a network of interconnected voids that allows water to percolate directly through to the sub-base. These systems are designed with a typical porosity of 15% to 35%, facilitating effective on-site stormwater management and groundwater recharge. Permeable concrete and porous asphalt constitute the largest product type segments, valued for their structural integrity in load-bearing applications. Demand from new construction, particularly for parking lots and sidewalks, significantly outpaces retrofit projects due to simpler site preparation requirements.
Regulations are a primary market accelerant, with frameworks like the US Environmental Protection Agency's (EPA) MS4 stormwater rules creating clear mandates. The EU Green Deal promotes sustainable urban drainage systems (SuDS), while China's national "Sponge City" initiative directly specifies permeable surface installation targets. The long-term performance, clogging resistance, and maintenance requirements of different pavement systems are becoming the central consideration for municipal authorities and asset owners.
Market Dynamics
The central force shaping the pervious pavement market is the collision between accelerating urbanization and intensifying regulatory pressure for effective stormwater management. This dynamic compels municipal authorities and commercial developers to seek alternatives to impervious surfaces, creating a direct demand pull.
Growth Catalysts
- Regulatory Mandates:China's national "Sponge City" initiative and the US EPA's MS4 stormwater rules create non-negotiable requirements for developers, directly specifying permeable surfaces to manage urban runoff and reduce pollution in receiving water bodies.
- Material Science Advances:The development of specialized chemical admixtures enhances the porosity, strength, and clogging resistance of permeable concrete and porous asphalt, making them viable for a wider range of load-bearing applications like commercial parking lots.
- Urban Densification:Demand for on-site stormwater solutions is highest in densely populated urban centers and coastal regions where land is scarce and conventional drainage infrastructure, such as retention ponds, is impractical or prohibitively expensive.
Market Restraints
- Higher Initial Costs:The upfront installation cost for pervious pavement systems, including specialized sub-base preparation and materials, is often higher than for conventional, non-permeable asphalt or concrete, posing a barrier for budget-constrained projects.
- Maintenance Complexity:Pervious surfaces require periodic specialized maintenance, such as regenerative air or vacuum sweeping, to prevent clogging of pores with sediment and debris, a requirement that can deter asset owners unfamiliar with the technology.
- Installation Skill Gap:A shortage of contractors with certified training and experience in the specific techniques for placing and compacting pervious pavement can lead to improper installations, premature failure, and reputational damage to the technology.
Strategic Opportunities
- Retrofit Applications:A significant opportunity exists in retrofitting existing impervious surfaces, such as aging parking lots and public plazas, particularly in cities offering grants or stormwater fee credits for such conversions.
- Smart Pavement Integration:Incorporating sensor technology into pervious systems to monitor real-time infiltration rates, temperature, and structural integrity offers a path to data-driven maintenance and performance validation for municipal asset managers.
- Geographic Expansion:Rapidly urbanizing regions in India and Southeast Asia facing acute water scarcity and monsoon flooding represent underpenetrated markets where pervious pavement can address both groundwater recharge and flood mitigation needs.
Industry Challenges
- Performance Standardization:The lack of universally accepted, long-term testing protocols and performance standards for clogging resistance and durability creates uncertainty for specifiers and can hinder broader adoption by conservative public agencies.
- Contractor Education:Overcoming installer error remains a primary operational hurdle, requiring industry associations and material suppliers to invest heavily in certification programs and on-site technical support to ensure successful project outcomes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Pervious Pavement Market |
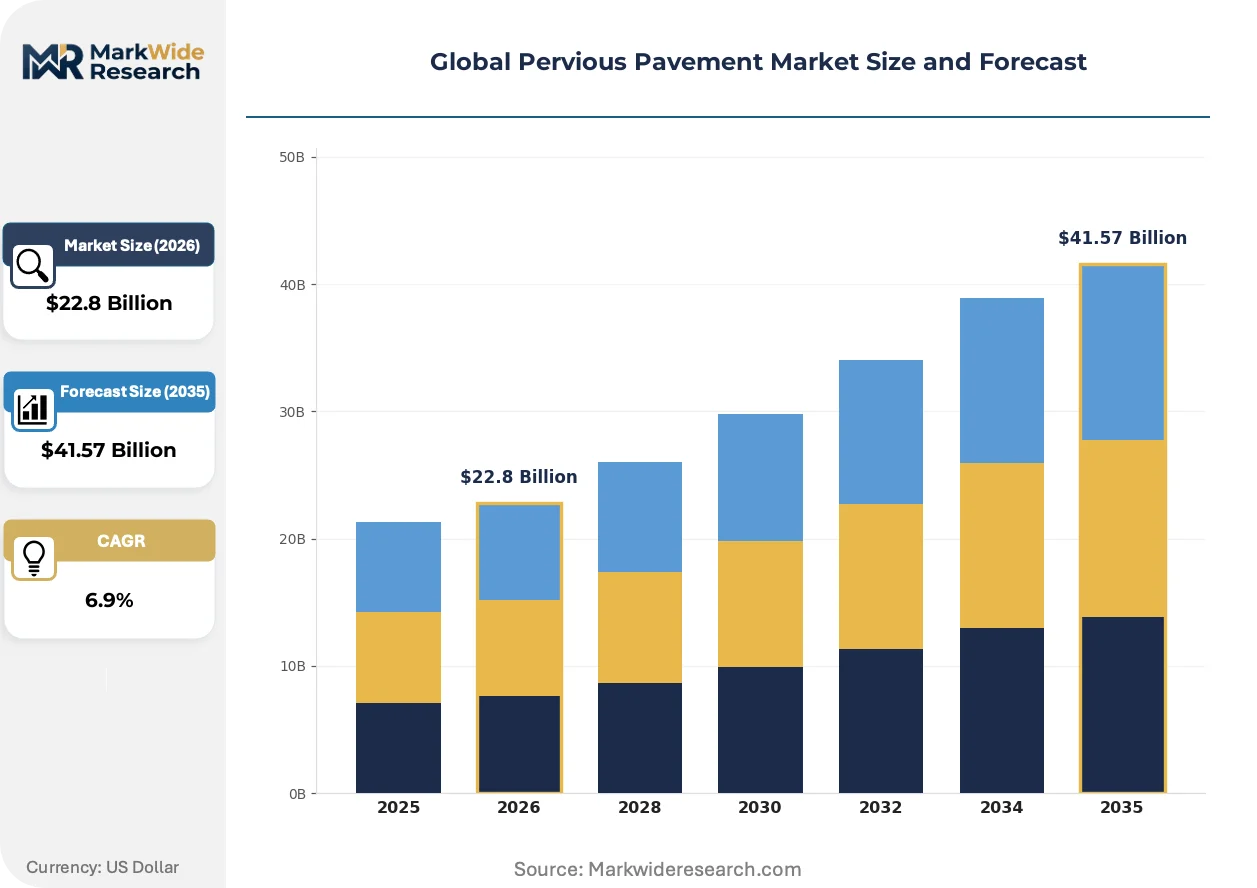
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $41.57 Billion |
| CAGR (2026 – 2036) | 6.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Porous Asphalt, Permeable Concrete, Interlocking Concrete Pavers, Grid Pavers, Plastic Pavers Application: Public Infrastructure, Commercial Complexes, Institutional Campuses, Recreational Parks, Walkways End User: Municipal Authorities, Real Estate Developers, Educational Institutions, Sports Facilities Installation Type: New Construction, Retrofit Projects, Roadways, Parking Lots, Sidewalks |
| Companies Covered | LafargeHolcim Ltd, CEMEX S.A.B. de C.V., CRH plc, BASF SE, Sika AG, Balfour Beatty plc, UltraTech Cement Limited, Boral Limited, Chaney Enterprises, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Pervious Pavement Market Strategic Shifts & Innovations
Product innovation and new service models are transforming pervious pavement from a niche environmental solution into an integrated component of smart city infrastructure. The market is evolving beyond simple material supply toward performance-guaranteed, long-term management of urban water cycles.
Specialized, pre-blended bagged mixes for pervious concrete are gaining traction for smaller-scale applications. These products are being adopted by residential contractors and landscape architects for projects like patios, walkways, and driveways that do not require a large ready-mix truck. The availability of these standardized, easy-to-use materials is decentralizing installation away from large, specialized crews, enabling a wider range of builders to incorporate permeable surfaces.
The European Union's Green Deal framework is formalizing the role of pervious surfaces within sustainable urban drainage systems (SuDS). This policy directly influences municipal building codes and public procurement specifications, often mandating or incentivizing their use to earn environmental credits. Commercial real estate developers in Germany and the Netherlands are most affected, now proactively designing projects with permeable parking and pedestrian areas to meet sustainability targets.
A clear behavioral shift towards lifecycle asset management is altering procurement patterns for large-scale projects. This trend displaces the traditional model of one-time material purchase with comprehensive service contracts that bundle material supply, installation, and multi-year maintenance commitments. This model is most prominent in public infrastructure projects in the United States and Australia, where municipalities seek to transfer long-term performance risk to the vendor.
Global Pervious Pavement Market Segmentation
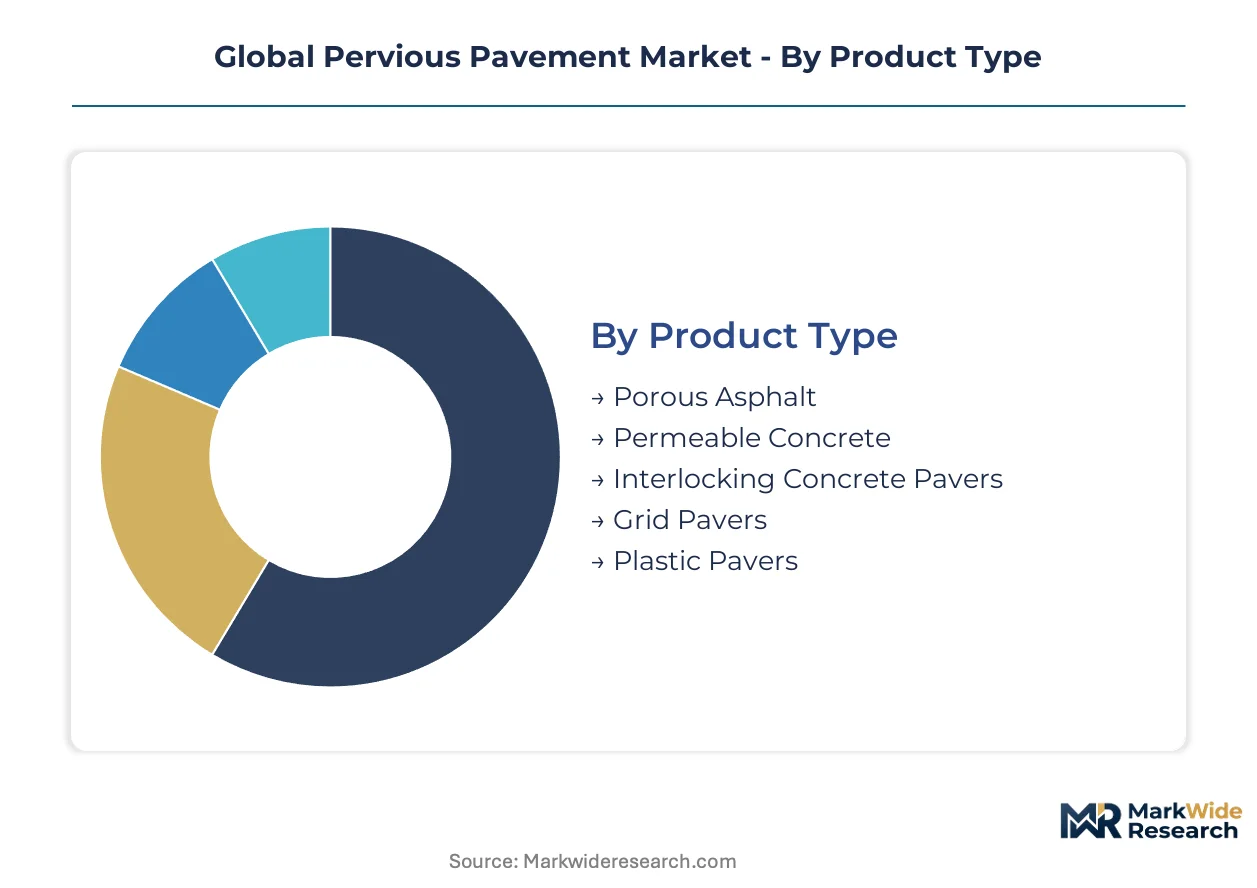
The pervious pavement market is segmented to understand how different material compositions, end-use applications, and installation methodologies influence demand across diverse buyer groups. This granular view reveals specific opportunities for material suppliers and service providers to align offerings with distinct market needs.
Product Type:
Buyers in the pervious pavement market differentiate products based on their load-bearing capacity, porosity, and aesthetic integration into urban designs.
- Permeable Concrete:This product type consists of a specialized concrete mixture with a high void content, typically 15-25%, allowing water to pass through. Demand concentrates in commercial parking lots and public plazas, valued for its structural integrity in heavy traffic applications.
- Porous Asphalt:Engineered with a reduced fine aggregate content, porous asphalt creates interconnected voids that facilitate water infiltration. It is widely used in roadways and large-scale public infrastructure projects across the United States, offering a cost-effective solution for stormwater runoff.
- Interlocking Concrete Pavers:These systems utilize individual concrete units with gaps that are filled with aggregate, allowing water to drain between them. They are preferred for pedestrian zones and residential driveways, offering design flexibility and ease of repair.
- Grid Pavers:Typically made from plastic or concrete, grid pavers create a permeable surface by allowing grass or aggregate to grow within their cells. These are increasingly specified for overflow parking areas and emergency access lanes.
- Plastic Pavers:Lightweight and durable, plastic pavers form a permeable grid system that can be filled with soil and grass or gravel. They find application in green infrastructure projects and landscape architecture.
Permeable Concrete leads volumes today; Porous Asphalt is gaining share fastest.
Application:
The specific requirements of each application dictate the selection of pervious pavement, influencing material choice and system design for optimal performance.
- Public Infrastructure:This segment includes municipal roads, public parking facilities, and stormwater management systems within urban environments. Demand is driven by regulatory mandates from agencies like the US EPA and initiatives such as China's "Sponge City" program.
- Commercial Complexes:Pervious pavements are applied in shopping centers, office parks, and corporate campuses to manage stormwater on-site and meet green building certifications. Developers in Germany increasingly specify these systems to comply with EU Green Deal sustainability targets.
- Institutional Campuses:Educational and healthcare facilities utilize pervious surfaces for parking lots, pathways, and plazas to enhance campus sustainability and reduce runoff. These projects often prioritize long-term durability and minimal maintenance.
- Recreational Parks:Pervious surfaces are installed in parks, sports fields, and public green spaces to improve drainage and reduce standing water. These applications often benefit from the aesthetic integration of permeable materials.
- Walkways:Pedestrian pathways and sidewalks incorporate pervious materials to prevent puddling and recharge local groundwater. Pre-blended bagged mixes are gaining traction for smaller-scale walkway projects.
Public Infrastructure is expanding most quickly; Commercial Complexes also exhibit significant growth.
End User:
End-user procurement priorities and long-term asset management strategies are central to the adoption patterns of pervious pavement systems.
- Municipal Authorities:These entities prioritize regulatory compliance, flood mitigation, and long-term maintenance costs for urban infrastructure. Their decisions are heavily influenced by frameworks like the US EPA's MS4 stormwater rules.
- Real Estate Developers:Focused on project costs, regulatory approvals, and marketability, developers integrate pervious pavements for sustainability credits and stormwater fee reductions. Commercial developers in the Netherlands are proactively designing with permeable surfaces.
- Educational Institutions:Universities and schools invest in pervious solutions to manage campus runoff, enhance environmental stewardship, and provide outdoor learning spaces. These institutions often seek durable systems with low lifecycle costs.
- Sports Facilities:Stadiums, arenas, and training grounds use pervious pavements for parking, access roads, and recreational areas to manage water and reduce maintenance. Performance standardization is a key consideration for these asset owners.
Municipal Authorities exhibit the steepest expansion trajectory; Real Estate Developers are also increasing their adoption.
Installation Type:
Project scope and site preparation demands significantly influence the choice between new construction and retrofit applications, as well as the specific type of installation site.
- New Construction:This category involves installing pervious pavement as part of entirely new development projects, such as residential subdivisions or commercial parks. Demand significantly outpaces retrofit projects due to simpler site preparation requirements.
- Retrofit Projects:These installations replace existing impervious surfaces with pervious systems, often in aging urban areas or for sustainability upgrades. Cities offering grants or stormwater fee credits incentivize these conversions.
- Roadways:Pervious pavements are integrated into public and private roads to manage surface runoff and improve water quality. Porous asphalt is a common choice for these load-bearing applications.
- Parking Lots:This segment represents a primary application for pervious concrete and porous asphalt, addressing stormwater management for commercial and institutional facilities. Material science advances enhance their viability for these load-bearing uses.
- Sidewalks:Pervious materials are used for pedestrian walkways to reduce impervious cover and enhance groundwater recharge. Specialized pre-blended mixes simplify installation for smaller sidewalk projects.
New Construction is climbing the fastest; Parking Lots also show robust growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Densely populated urban centers globally drive demand for pervious pavement solutions, responding to accelerated urbanization and intensifying regulatory pressure. These regions seek effective stormwater management and groundwater recharge capabilities. Policy frameworks like the EU Green Deal and China's "Sponge City" initiative significantly influence market expansion.
United States
The United States market is shaped by the US Environmental Protection Agency's (EPA) MS4 stormwater rules, creating mandates for urban runoff management. Public infrastructure projects, especially for parking lots, utilize permeable concrete and porous asphalt. Coastal regions such as Florida and California prioritize pervious systems for flood mitigation and groundwater recharge.
Germany
Germany's market for pervious pavement expands due to strong environmental regulations and the EU Green Deal, promoting sustainable urban drainage systems. Commercial real estate developers proactively design projects with permeable parking. Cities like Munich and Berlin are seeing increased adoption in public infrastructure projects.
China
China's national "Sponge City" initiative directly specifies permeable surface installation targets, driving significant market volume. This policy aims to enhance urban flood resilience and water resource management. Major urban centers like Shanghai and Beijing are rapidly implementing pervious pavement in new developments.
India
Rapid urbanization in India creates substantial demand for on-site stormwater management and groundwater recharge solutions. The country's infrastructure development plans increasingly integrate sustainable drainage practices. Cities facing acute water scarcity, such as Chennai and Bangalore, explore pervious pavement for flood mitigation.
Netherlands
The Netherlands sees pervious pavement adoption spurred by the EU Green Deal and national water management strategies. Real estate developers integrate these systems to meet sustainability targets for new commercial complexes. Amsterdam and Rotterdam actively promote permeable surfaces in their urban planning initiatives.
Global Pervious Pavement Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue specialized admixture development and integrated service offerings across the value chain. The pervious pavement market exhibits a tiered structure, with large material suppliers, chemical specialists, and integrated solution providers forming distinct archetypes. Dominant competitive moves include strategic partnerships to bundle material and installation services, alongside geographic expansion into rapidly urbanizing regions to capture new infrastructure projects.
Specialists in material supply and integrated solutions, such as LafargeHolcim Ltd, leverage extensive ready-mix plant networks to serve large-scale infrastructure projects. CEMEX S.A.B. de C.V. exemplifies providers offering integrated design and installation support services alongside its core material supply, catering to projects requiring comprehensive solutions. Sika AG, a Swiss-based company, anchors the segment focused on specialized chemical admixtures that enhance the porosity, strength, and long-term durability of both permeable concrete and porous asphalt systems.
| Leading Market Players |
|---|
| LafargeHolcim Ltd |
| CEMEX S.A.B. de C.V. |
| CRH plc |
| BASF SE |
| Sika AG |
| Balfour Beatty plc |
| UltraTech Cement Limited |
| Boral Limited |
| Chaney Enterprises |
| Others |
Cost & Logistics Intelligence
Vertical integration of ready-mix concrete plants anchors LafargeHolcim's supply position, influencing pricing power for permeable concrete across large-scale infrastructure projects. This structure enables cost control and consistent material delivery.
Pricing Analysis
Input cost pass-through for specialized chemical admixtures directly impacts pervious pavement system pricing. Project-based contracts and long-term offtake agreements dominate the market. Price differentiation stems from product performance, such as enhanced clogging resistance or durability, and comprehensive after-sales service bundling. Cost compression in standard materials creates pricing softness in commodity segments due to competition among suppliers. Municipal authorities exhibit high price sensitivity for initial project costs, while commercial developers prioritize long-term performance and sustainability credits.
Supply Chain Analysis
Specialized chemical admixture supply rests on a concentrated base of global producers primarily in Germany and Switzerland. The market draws from key raw materials including specialty polymers, cement, and aggregates. Single-source vulnerability for specific high-performance admixtures presents a structural supply chain risk. Distribution runs through direct sales channels to large contractors and extensive ready-mix plant networks for bulk material delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The pervious pavement market acts as a stable compounder, driven by continuous regulatory mandates for urban stormwater management. This persistent demand ensures consistent, long-term growth.
For Market Incumbents: To counter the threat of improper installations by uncertified contractors, LafargeHolcim and CEMEX should invest in certified installer networks and expand technical support programs. This deepens channel control. Investing in R&D for advanced material science also enhances product durability, meeting municipal authorities' long-term performance requirements.
For New Entrants and Emerging Players: Begin with targeting retrofit applications in US coastal cities, where stormwater fee credits incentivize conversion of existing impervious surfaces. Focus on offering pre-blended bagged mixes for smaller-scale projects, enabling landscape architects and residential contractors to access the technology. This strategy leverages underpenetration in the residential and small commercial segments.
For Investors and Strategic Acquirers: Roll-up economics work for regional material suppliers because local logistics and site-specific expertise create defensible geographic niches. Long-term viability for the market is strong over the next decade, supported by ongoing urbanization and climate resilience initiatives. Watch for increased standardization of performance testing protocols, as this signals broader public agency adoption and reduces project risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Urban Centers | Increases material availability for public infrastructure projects in Germany and China. |
| Certified Installer Program Development | Enhances installation quality and builder confidence in pervious systems for commercial complexes. |
| Integrated Service Offering Bundling | Combines material supply with design and multi-year maintenance for municipal authorities. |
| Specialized Admixture R&D Investment | Improves product performance and durability for load-bearing applications like parking lots. |
| Geographic Expansion into India | Addresses acute water scarcity and flood mitigation needs in rapidly urbanizing regions. |
Research Approach
Direct dialogue with municipal authorities, civil engineers, material suppliers, and commercial developers provided qualitative grounding for market dynamics. Secondary research involved analysis of US EPA reports, EU Green Deal policy documents, national infrastructure spending plans, and corporate financial filings. This approach combined bottom-up market sizing from project data with top-down validation using industry revenue figures.
Market volume and value projections emerged from a robust analytical framework, segmenting demand by product type, application, end-user, and installation type. Compound Annual Growth Rates (CAGRs) were derived using historical growth rates and projected adoption trends influenced by regulatory shifts across the analysis window. Key industry-specific forecast inputs included urbanization rates in China and India, alongside stormwater management infrastructure budgets.
Several conditions sit outside the modeled scope, including unforeseen global economic downturns or major geopolitical events impacting construction materials supply. Forecasts reflect assumptions regarding consistent regulatory enforcement and technological adoption rates. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction and Engineering
Dozer Tire Market
Construction and Engineering
Tower Crane Market
Construction and Engineering
Level Floats Market
Construction and Engineering
Saudi Arabia Transportation Infrastructure Construction Market
Construction and Engineering
Welded Spiral Heat Exchangers Market
Construction and Engineering
Global Portable Sawmills Market
Construction and Engineering
Italy HVAC Market
Construction and Engineering
Electric Single Beam Crane Market
Construction and Engineering
Rotary Indexer Market
Construction and Engineering
Shaft Shredder Market
Construction and Engineering
China Power Tools and Hand Tools Market
Construction and Engineering
Brazil Construction Market
Construction and Engineering
Asia-Pacific Shotcrete Market
Construction and Engineering
Italy Prefab Wood Buildings Market
Construction and Engineering
Hydraulic Spreader Market
Construction and Engineering
HVAC Control System Market