
 Rotary Indexer Market | 2026-2036
Rotary Indexer Market Size, Share, and Industry Trends Forecast 2026-2036
Rotary Indexer Market Analysis
Aluminum alloy housings are pivoting toward carbon-reinforced polymer composites to reduce rotary mass and extend indexing speed limits. Motion Index Drives, Inc. leverages in-house spindle manufacturing to control lead times for custom configurations. WEISS GmbH anchors European supply through its Swabian production campus. Sankyo Automation competes on precision-grade indexers for semiconductor wafer handling applications.
A rotary indexer is a precision motion device that converts continuous input rotation into intermittent, accurately positioned angular displacement, typically achieving repeatability within ±3 arc-seconds through cam-driven or direct-drive mechanisms. Its primary purpose is to synchronize multi-station manufacturing processes where components must pause at fixed angular positions for machining, assembly, or inspection operations. Electric rotary indexers command the dominant share of product type revenue due to servo compatibility and programmable motion profiles, while pneumatic variants retain cost-sensitive packaging lines where speed requirements remain modest. CNC machining applications generate the highest per-unit pricing among application categories, though automated assembly lines represent the largest volume pool.
The EU Machinery Directive and CE marking requirements enforce fail-safe braking and guarding standards on European-sold indexers, elevating engineering costs for non-compliant imports. The EPA's energy efficiency guidelines indirectly shape electric indexer motor specifications in US-bound equipment. Japan's METI safety standards for factory automation equipment mandate torque-limiting protocols that influence design decisions for Asia-Pacific deployments. Stakeholders must weigh regional certification burdens against platform standardization when configuring global product portfolios.
Market Dynamics
Servo motor integration is displacing mechanical cam systems across precision manufacturing, compressing indexing cycle times while elevating repeatability thresholds for multi-station automation.
Growth Catalysts
- Automotive Assembly Expansion:Automated welding and component installation lines in Germany and the United States are deploying high-speed rotary indexers to synchronize multi-station operations.
- REACH Material Compliance:European manufacturers are retrofitting existing equipment with electric indexers to meet RoHS substance restrictions and eliminate hydraulic fluid contamination risks.
- Semiconductor Wafer Handling:Cleanroom-grade indexers with vacuum-compatible seals are capturing demand from chip fabrication facilities in Taiwan and South Korea.
Market Restraints
- Rare Earth Magnet Volatility:Neodymium and dysprosium price swings for servo motor permanent magnets are compressing margins on precision electric indexers.
- Swabian Supply Concentration:German precision component suppliers around Stuttgart control critical cam grinding and spindle manufacturing capacity, creating single-source vulnerability.
- Pneumatic Substitution Ceiling:Compressed air systems retain cost advantage in food packaging lines where indexing speeds below 30 cycles per minute suffice.
Strategic Opportunities
- India PLI Manufacturing Incentives:Production-linked incentive schemes for automotive and electronics manufacturing are attracting indexer OEMs to establish local assembly operations.
- Battery Cell Stacking Automation:Lithium-ion electrode winding and stacking equipment requires precision indexing for layer alignment tolerances.
- ISO 13849 Safety Integration:Machinery safety standards mandating Category 3 PLd performance levels are creating upgrade demand for legacy mechanical systems.
Industry Challenges
- Motion Control Programming Shortage:Factory automation engineers with servo tuning and cam profile optimization expertise command premium compensation and extended recruitment timelines.
- CE Marking Documentation Burden:EU Machinery Directive technical file compilation for custom indexer configurations extends delivery lead times by 6-10 weeks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rotary Indexer Market |
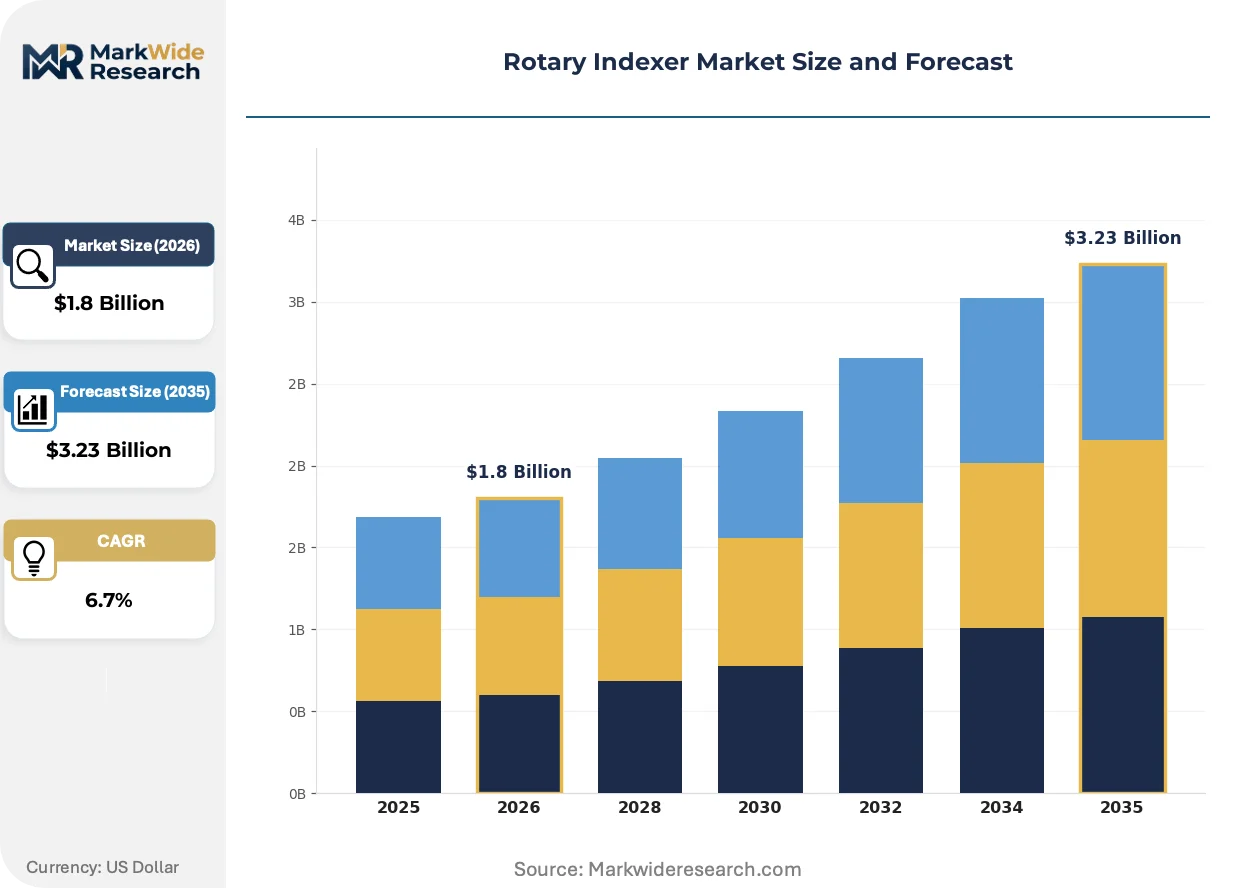
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Rotary Indexers, Hydraulic Rotary Indexers, Pneumatic Rotary Indexers, Mechanical Rotary Indexers Application: Automated Assembly, Material Handling, Packaging, CNC Machining End User: Automotive Industry, Aerospace Sector, Consumer Electronics, Pharmaceutical Manufacturing Installation: On-Site Installation, Factory Pre-Installation, Retrofit Solutions, Custom Integration |
| Companies Covered | Motion Index Drives, Inc., Carl Hirschmann Inc, DESTACO (CAMCO), Nexen Group, Inc., TAKTOMAT GmbH, WEISS GmbH, Colombo Filippetti S.p.A., IntelLiDrives, Inc., Sankyo Automation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rotary Indexer Market Emerging Trajectories
Carbon-reinforced polymer housings and direct-drive torque motors are converging to redefine rotary mass and indexing velocity limits across precision automation.
Direct-drive torque motor technology eliminates mechanical transmission elements including gearboxes, belts, and cams. Medical device manufacturers and semiconductor equipment builders are adopting these systems for sub-arc-second positioning requirements. The technology is automating previously manual calibration procedures while compressing maintenance intervals from quarterly to annual cycles.
EPA energy efficiency guidelines for industrial electric motors are tightening nameplate efficiency requirements for NEMA and IEC frame sizes. Indexer OEMs are redesigning motor specifications to meet premium efficiency tiers, adding engineering cost but opening federal procurement channels. US-bound automated assembly equipment faces the most acute compliance pressure.
Buyer consolidation among tier-one automotive suppliers is compressing vendor qualification timelines and unbundling aftermarket service contracts. Component manufacturers now specify outcome-based availability guarantees rather than discrete spare parts pricing. This pattern is most pronounced in Germany's Baden-Württemberg automotive supplier corridor.
Rotary Indexer Market Segmentation
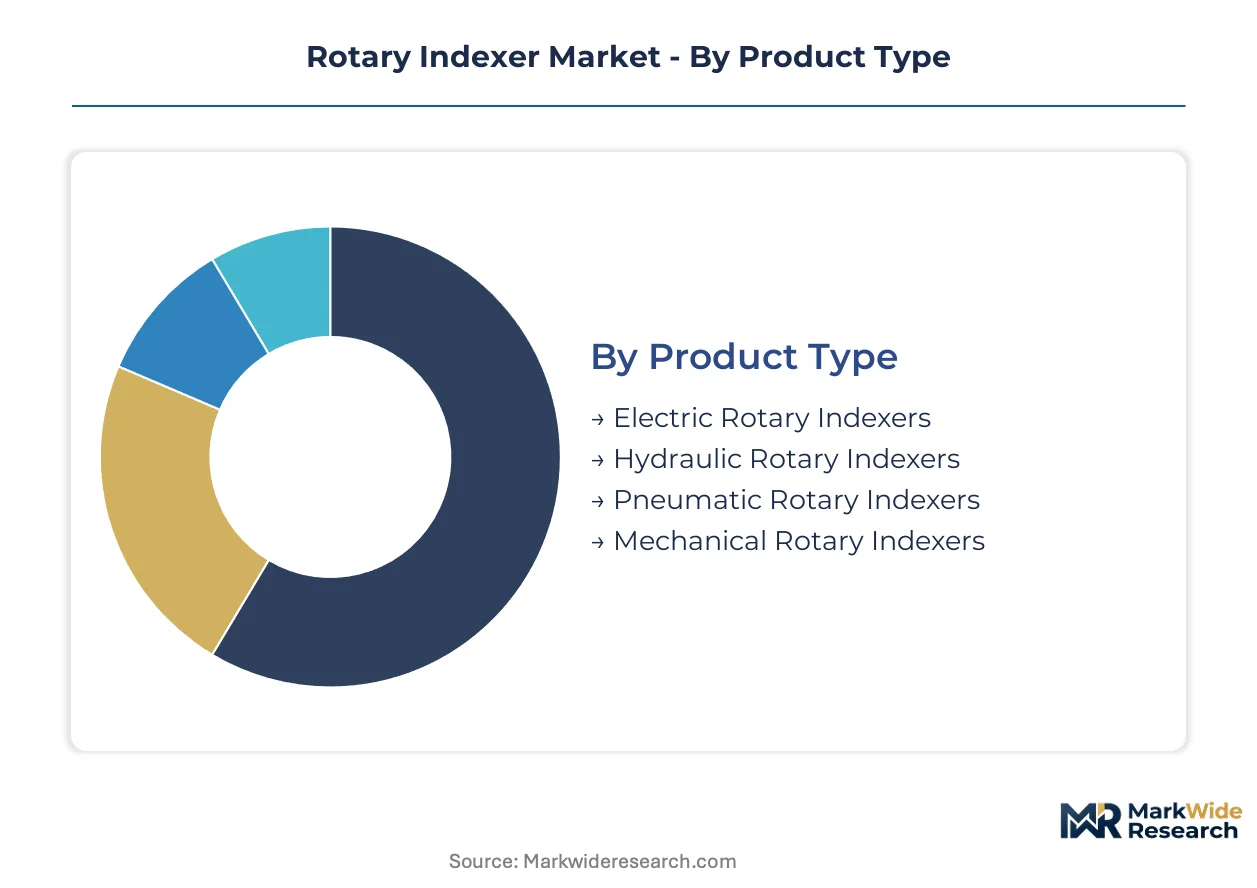
Rotary indexer procurement patterns diverge sharply across motion control architectures, manufacturing processes, and integration complexity. Each segmentation axis reveals distinct buyer priorities—from servo compatibility demands in electric systems to tolerance requirements in semiconductor handling.
Product Type:
Buyers differentiate primarily by motion precision requirements versus total cost of ownership trade-offs.
- Electric Rotary Indexers:Servo motor architectures deliver programmable motion profiles with ±3 arc-second repeatability. Demand concentrates in Germany's automotive precision engineering corridor around Stuttgart, driven by multi-station welding line synchronization requirements. EPA energy efficiency guidelines for NEMA frame motors are compressing supplier margins while opening federal procurement channels.
- Mechanical Rotary Indexers:Cam-driven systems achieve indexing through precision-machined barrel cams and roller followers. Food packaging lines in Italy and Spain retain these units where speeds below 30 cycles per minute render servo investment uneconomical. Maintenance intervals run shorter than electric alternatives.
- Hydraulic Rotary Indexers:High-torque fluid power systems dominate heavy stamping and forging applications. REACH substance restrictions and RoHS compliance burdens are accelerating replacement with electric alternatives across European installations.
- Pneumatic Rotary Indexers:Compressed air actuation serves cost-sensitive packaging operations with modest positioning requirements. Compressed air infrastructure availability determines adoption feasibility more than precision specifications.
Electric rotary indexers lead volumes today; mechanical variants are gaining share fastest in emerging market packaging sectors.
Application:
Process cycle time and component fragility dictate indexer specification intensity across manufacturing stages.
- Automated Assembly:Multi-station synchronization for component installation and welding operations. Automotive tier-one suppliers in Baden-Württemberg specify outcome-based availability guarantees rather than discrete spare parts pricing.
- CNC Machining:Generates highest per-unit pricing through sub-arc-second positioning demands and thermal stability requirements. Medical device manufacturers and semiconductor equipment builders drive specification intensity for direct-drive torque motor configurations.
- Material Handling:Conveyor transfer and palletizing operations prioritize throughput over absolute precision. Distribution center automation in the United States deploys these systems for parcel sortation indexing.
- Packaging:Bottle filling, capping, and labeling lines balance speed with washdown compatibility. Pneumatic variants retain cost advantage where indexing speeds remain modest.
Automated assembly commands the largest volume pool; CNC machining exhibits the steepest expansion trajectory in value terms.
End User:
Regulatory compliance burdens and contamination sensitivity create divergent procurement specifications across manufacturing sectors.
- Automotive Industry:High-volume welding and component installation lines demand millisecond-level cycle consistency. Battery cell stacking automation for lithium-ion electrode winding is emerging as a precision-intensive growth vector.
- Pharmaceutical Manufacturing:Cleanroom-grade indexers with vacuum-compatible seals and torque-limiting safety protocols per METI standards. Sterilization compatibility and batch traceability requirements elevate engineering costs.
- Aerospace Sector:Low-volume, high-mix production of airframe components and turbine assemblies. Tight tolerance composite drilling operations require thermal stability and vibration damping.
- Consumer Electronics:Semiconductor wafer handling and miniature component placement drive demand for compact, high-speed indexing modules. Taiwan and South Korean fabrication facilities specify cleanroom-compatible sealing systems.
Automotive industry leads volumes today; pharmaceutical manufacturing is climbing the fastest on safety integration mandates.
Installation:
Capital deployment timing and production disruption tolerance determine integration approach selection.
- Factory Pre-Installation:OEM-controlled assembly and calibration reduces field commissioning variables. WEISS GmbH leverages its Swabian production campus for European supply consolidation with controlled lead times.
- Custom Integration:Application-specific mechanical interfaces and control architecture adaptation. Motion Index Drives deploys in-house spindle manufacturing to compress delivery timelines for non-standard configurations.
- Retrofit Solutions:Legacy equipment upgrades to meet ISO 13849 Category 3 PLd safety performance levels. CE marking documentation burdens extend delivery lead times by 6-10 weeks for European-bound systems.
- On-Site Installation:Greenfield facility commissioning with full production line integration. Factory automation engineers with servo tuning expertise command premium compensation, extending recruitment timelines.
Factory pre-installation leads volumes today; retrofit solutions are expanding most quickly on safety standard upgrade cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Baden-Württemberg's precision engineering corridor around Stuttgart anchors global rotary indexer demand through automotive multi-station welding lines and battery cell stacking automation. Manufacturing clusters across four additional countries concentrate specialized demand and regulatory compliance burdens.
Germany
Automotive tier-one suppliers in Stuttgart and Munich specify high-speed electric indexers for millisecond-level cycle consistency in welding operations. The EU Machinery Directive and CE marking requirements enforce fail-safe braking standards that elevate engineering costs for non-compliant imports. WEISS GmbH leverages its Swabian production campus to consolidate European supply with controlled lead times for custom configurations.
United States
EPA energy efficiency guidelines for NEMA frame motors are compressing supplier margins while opening federal procurement channels for premium efficiency tiers. Automated assembly equipment in Michigan and Ohio faces acute compliance pressure from tightening industrial motor specifications. Battery electrode winding equipment in the Midwest is emerging as a precision-intensive growth vector for direct-drive torque motor configurations.
Japan
METI safety standards for factory automation equipment mandate torque-limiting protocols that influence design decisions for Asia-Pacific deployments. Semiconductor wafer handling applications in the Chubu region around Nagoya drive demand for cleanroom-grade indexers with vacuum-compatible seals. Sankyo Automation competes on precision-grade systems for chip fabrication facilities requiring sub-arc-second positioning.
South Korea
Chip fabrication facilities in Gyeonggi Province specify cleanroom-compatible sealing systems for miniature component placement and wafer handling operations. The national industrial safety regulator enforces machinery performance standards that parallel ISO 13849 Category 3 PLd requirements. Domestic equipment builders are accelerating servo motor integration to displace legacy mechanical cam systems in multi-station automation.
India
Production-linked incentive schemes for automotive and electronics manufacturing are attracting indexer OEMs to establish local assembly operations in Maharashtra and Tamil Nadu. BIS certification requirements for industrial machinery create compliance entry barriers for non-domestic suppliers. Automotive welding lines in the Pune-Nashik corridor represent the fastest-expanding application segment for electric rotary indexers.
Rotary Indexer Market Vendor Landscape
Global majors compete with regional champions across precision engineering capabilities and regional certification expertise. The vendor base organizes around three distinct tiers: integrated motion control specialists with captive spindle manufacturing, precision cam grinding houses anchored in German industrial clusters, and Asian fabricators competing on cost-adjusted positioning for emerging market packaging lines. Strategic moves concentrate on backward integration into critical component supply and geographic expansion through local assembly partnerships to satisfy domestic content requirements.
Within the integrated motion control tier, Motion Index Drives, Inc. and IntelLiDrives, Inc. occupy positions defined by in-house manufacturing capabilities that compress delivery timelines for non-standard configurations. Among German precision houses, WEISS GmbH and TAKTOMAT GmbH exemplify the Swabian engineering archetype with concentrated production capacity around Stuttgart. Colombo Filippetti S.p.A. represents Italian mechanical indexer traditions serving food packaging lines where pneumatic substitution ceilings persist.
| Leading Market Players |
|---|
| Motion Index Drives, Inc. |
| Carl Hirschmann Inc |
| DESTACO (CAMCO) |
| Nexen Group, Inc. |
| TAKTOMAT GmbH |
| WEISS GmbH |
| Colombo Filippetti S.p.A. |
| IntelLiDrives, Inc. |
| Sankyo Automation |
| Others |
Supply Flow & Price Mechanics
Automotive tier-one supplier consolidation in Germany's Baden-Württemberg corridor is compressing vendor qualification timelines and unbundling aftermarket service contracts, forcing indexer OEMs to absorb engineering costs for outcome-based availability guarantees while repositioning spare parts pricing as subscription bundles.
Pricing Analysis
Rare earth magnet volatility in neodymium and dysprosium feeds directly into servo motor cost structures, compressing margins on precision electric indexers while elevating price differentiation between NEMA premium efficiency tiers and standard motor configurations. Three-tier pricing structure across premium direct-drive torque motors, standard servo-cam hybrids, and economy pneumatic units separates buyers by repeatability requirements and cycle speed demands. Cost compression in the electric tier is intensifying because REACH compliance retrofit demand is accelerating replacement timelines. Food packaging lines in Southern Europe remain most price-sensitive, while semiconductor wafer handling facilities in Taiwan and South Korea exhibit lowest elasticity for sub-arc-second positioning systems.
Supply Chain Analysis
Regional distribution centers in Stuttgart, Nagoya, and Detroit anchor hub-and-spoke fulfillment patterns for precision motion components, with satellite stocking points in Pune and Shanghai serving emerging market assembly operations. Manufacturing gravity centers on Germany for cam grinding and spindle production, Japan for cleanroom-grade sealing systems, and the United States for NEMA-frame motor integration. Critical inputs draw from rare earth magnet processors in China, precision bearing suppliers in Switzerland, and carbon-reinforced polymer compounders in the Netherlands. Single-source vulnerability in Swabian cam grinding capacity creates structural risk for European lead times. Distribution runs through OEM-direct channels for large automotive contracts and specialized motion control distributors for mid-volume CNC machining applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
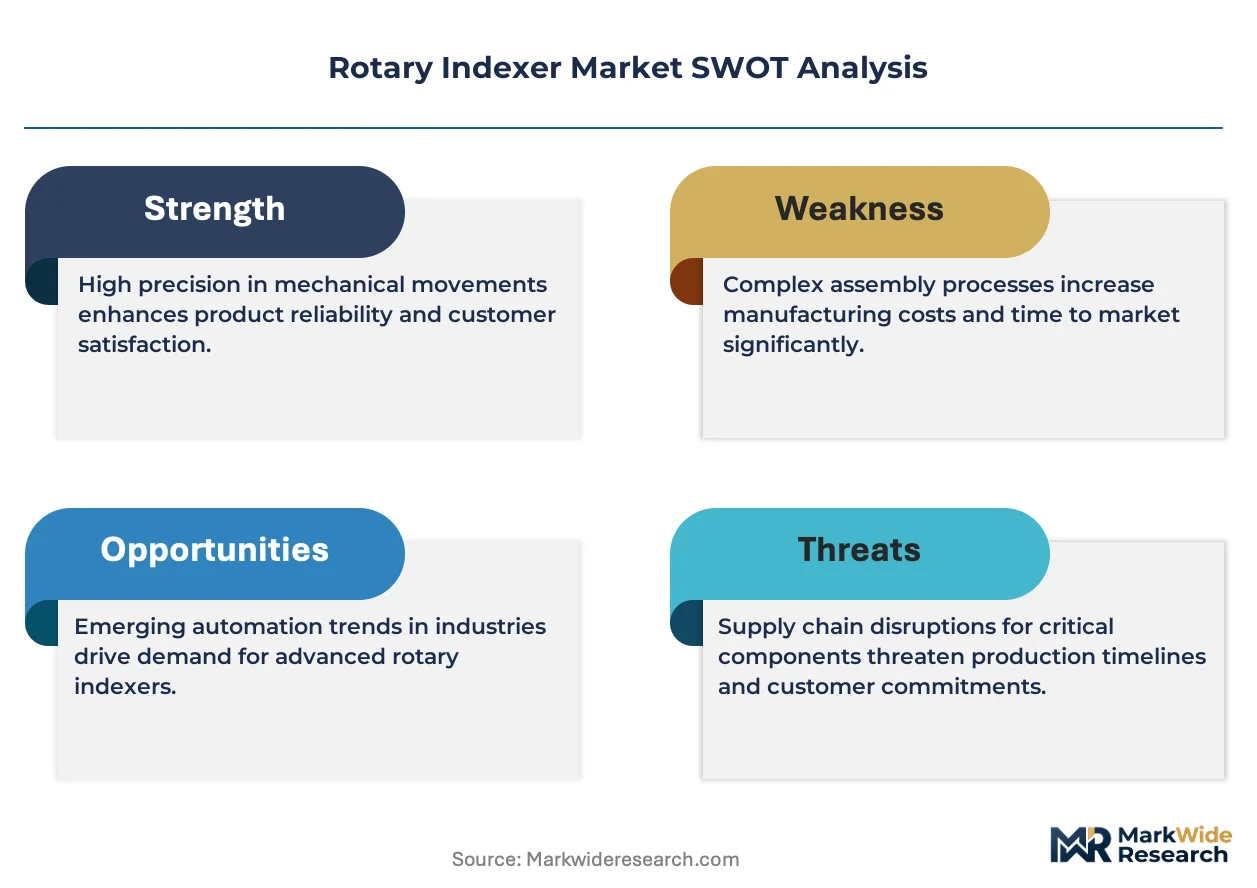
Carbon-reinforced polymer housing adoption and direct-drive torque motor integration are shifting specification premiums upward, creating margin expansion headroom for suppliers who control upstream composite manufacturing and in-house spindle production capabilities.
For Market Incumbents: Deploy backward integration into permanent magnet supply chains to buffer rare earth price volatility and secure NEMA premium efficiency motor allocations ahead of EPA compliance deadlines. Consolidate aftermarket service contracts into outcome-based availability guarantees to defend against unbundling pressure from automotive procurement teams in Stuttgart. Expand Swabian production campus capacity to reduce single-source vulnerability exposure. For New Entrants and Emerging Players: Direct-drive torque motor configurations for battery electrode winding applications represent the most penetrable white-space segment, as lithium-ion cell stacking automation demands precision indexing with layer alignment tolerances unmet by legacy mechanical systems. Target India's PLI manufacturing incentive zones through local assembly partnerships with Maharashtra-based automotive suppliers. Pursue ISO 13849 Category 3 PLd certification as primary go-to-market credential for European retrofit opportunities. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap specialists possessing captive spindle manufacturing and in-house cam grinding capabilities, as these assets compress delivery timelines for custom configurations and resist commoditization pressure. Long-term viability hinges on servo motor integration expertise and cleanroom-grade sealing system portfolios. Monitor rare earth magnet price stabilization indices as inflection signal for margin recovery timing in electric indexer tiers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Magnet Supply | Secures neodymium-dysprosium allocations for NEMA premium efficiency servo motors amid EPA tightening. |
| Carbon-Reinforced Polymer Housing Transition | Reduces rotary mass and extends indexing velocity limits for direct-drive torque motor configurations. |
| ISO 13849 Category 3 PLd Certification | Unlocks European retrofit demand as CE marking documentation burdens delay non-compliant competitor deliveries. |
| Local Assembly Partnership in India | Satisfies PLI scheme domestic content requirements for automotive welding line deployments in Pune-Nashik corridor. |
| Outcome-Based Service Contracting | Aligns pricing with availability guarantees demanded by consolidated automotive tier-one procurement teams in Germany. |
Methodological Framework
Multiple input streams — structured interviews with plant engineers and OEM procurement teams, technical specification audits of servo motor integrations, and trade flow analysis of rare earth magnet supply chains — were reconciled against secondary validation from EPA energy efficiency filings, EU Machinery Directive technical documentation, and semiconductor equipment builder capex disclosures. Bottom-up unit economics for electric, mechanical, hydraulic, and pneumatic indexer configurations were triangulated with top-down demand aggregation across automotive welding lines, CNC machining centers, and cleanroom wafer handling applications.
Data-stream reconciliation anchored volume and value outputs to segmentation dimensions spanning motion control architecture, manufacturing process intensity, and integration complexity across the projection horizon. CAGRs were derived from installed base depreciation curves and replacement demand modeling tied to REACH compliance retrofit cycles and ISO 13849 safety upgrade mandates. Forecast inputs incorporated servo motor penetration rates in multi-station automation and carbon-reinforced polymer adoption trajectories in precision housing applications.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to rare earth magnet price volatility, Swabian supply concentration disruptions, and PLI scheme policy continuity in India. Outputs reflect documented assumptions around EPA efficiency tier enforcement timing and EU Machinery Directive interpretation consistency. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Drive-In Pallet Racking Market
Material Handling Equipment
Wire Pulling and Tensioning Market
Material Handling Equipment
Weighbridge Market
Material Handling Equipment
Gantry Crane Market
Material Handling Equipment
Forklift Rental Market
Material Handling Equipment
India Automated Material Handling (AMH) Market
Material Handling Equipment
Global Bucket Loader Market
Material Handling Equipment
Torque Limiting Couplings Market
Material Handling Equipment
Canada Forklift Market
Material Handling Equipment
Hoist Controller Market
Material Handling Equipment
Japan Conveyor Belt Market
Material Handling Equipment
Heavy Equipment Movers Market
Material Handling Equipment
Firewood Processors Market
Material Handling Equipment
Global Pipe and Tube Bending Machine Market
Material Handling Equipment
Industrial Bag Dust Filter Market
Material Handling Equipment
Portable Forklift Ramps Market