
 Saudi Arabia Transportation Infrastructure Construction Market | 2026-2036
Saudi Arabia Transportation Infrastructure Construction Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Transportation Infrastructure Construction Market Outlook
Multi-source procurement for steel and ready-mix concrete is expanding across major transport corridors as contractors diversify supply risk. Saudi Binladin Group leverages captive quarry and batching-plant networks to sustain cost predictability on megaproject sites. Nesma & Partners anchors its position through marine infrastructure specialization at Red Sea port gateways. China Railway Construction Corp. competes on turnkey rail-electrification packages tied to Riyadh Metro extensions.
Saudi Arabia transportation infrastructure construction encompasses the civil engineering, materials fabrication, and systems integration required to build roads, bridges, airports, and railways capable of handling desert-climate thermal loads exceeding 50°C and seismic Zone 2A requirements. The primary purpose is to enable freight and passenger mobility across a 2.15 million square kilometer territory while supporting Vision 2030 economic diversification targets. Roads and bridges command the largest share of current contract value, reflecting arterial highway upgrades and urban interchange densification around Jeddah and Dammam. Smart Infrastructure is gaining share fastest, driven by IoT-enabled traffic management and predictive maintenance mandates from the Ministry of Transport and Logistics Services.
The National Center for Contracts (NCA) enforces prequalification thresholds that filter out undercapitalized bidders on public-private partnership tenders. SFDA material standards and SASO certification for construction products shape import sourcing decisions for polymer-modified asphalt and high-performance concrete admixtures. The Saudi Building Code governs structural design loads and durability specifications for bridge superstructures in coastal environments. Stakeholders must monitor how NCA prequalification scorecards evolve to weight domestic content ratios against technical capability benchmarks.
Market Dynamics
The Saudi Arabia transportation infrastructure construction market is experiencing intense schedule compression as giga-project timelines compress traditional procurement cycles, forcing contractors to pre-position materials and labor months ahead of physical mobilization.
Growth Catalysts
- NEOM and Red Sea Project Pipelines:The $500 billion NEOM development and Red Sea coastal zone investments are generating concentrated demand for asphalt, steel-reinforced structures, and marine infrastructure.
- SFDA Material Certification Expansion:The Saudi Food and Drug Authority's construction product standards are accelerating import substitution for polymer-modified asphalt and high-performance concrete admixtures.
- Desert-Climate Engineering:Thermal load specifications exceeding 50°C and seismic Zone 2A requirements are creating specialized demand for heat-resistant pavement binders and expansion joint systems.
Market Restraints
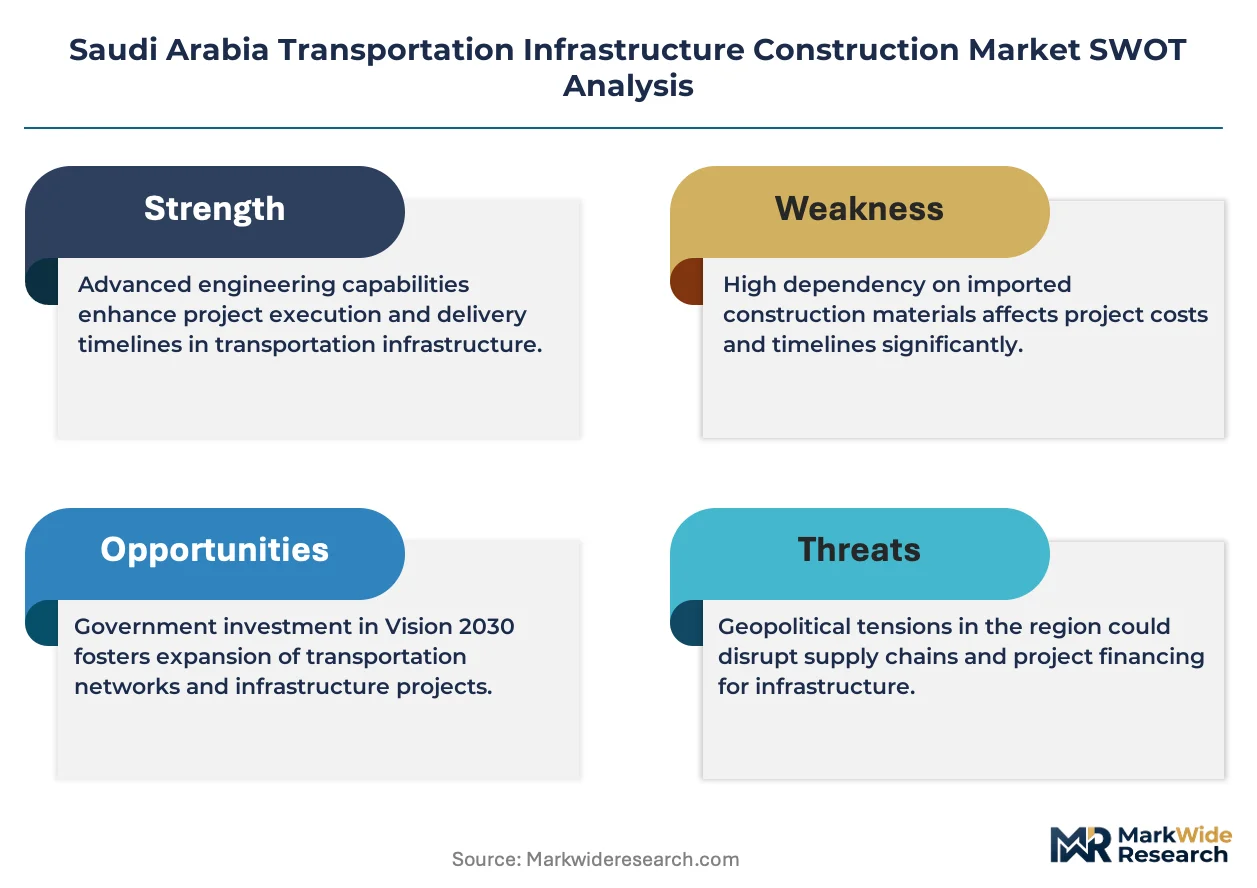
- Steel Import Concentration:Heavy reliance on Asian steel suppliers exposes contractors to freight rate volatility and customs clearance bottlenecks at Jeddah Islamic Port.
- NCA Prequalification Barriers:The National Center for Contracts' capital thresholds filter out mid-tier bidders on public-private partnership tenders, reducing competitive depth.
- Skilled Labor Scarcity:Shortages of certified welders and bridge deck specialists familiar with Saudi Building Code requirements inflate project labor costs.
Strategic Opportunities
- Smart Infrastructure Integration:IoT-enabled traffic management and predictive maintenance mandates from the Ministry of Transport and Logistics Services are opening systems integration contracts.
- Captive Quarry Networks:Contractors with backward integration into aggregate production can secure cost predictability on megaproject sites.
- Marine Infrastructure Specialization:Red Sea port gateway expansions reward firms with dredging, quay wall, and breakwater expertise.
Industry Challenges
- SASO Certification Timelines:Saudi Standards, Metrology and Quality Organization product approval processes delay material imports by 8-14 weeks, disrupting just-in-site delivery schedules.
- Multi-Contractor Coordination:Compressed giga-project timelines require simultaneous mobilization of road, rail, and utility contractors, creating interface management complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Transportation Infrastructure Construction Market |
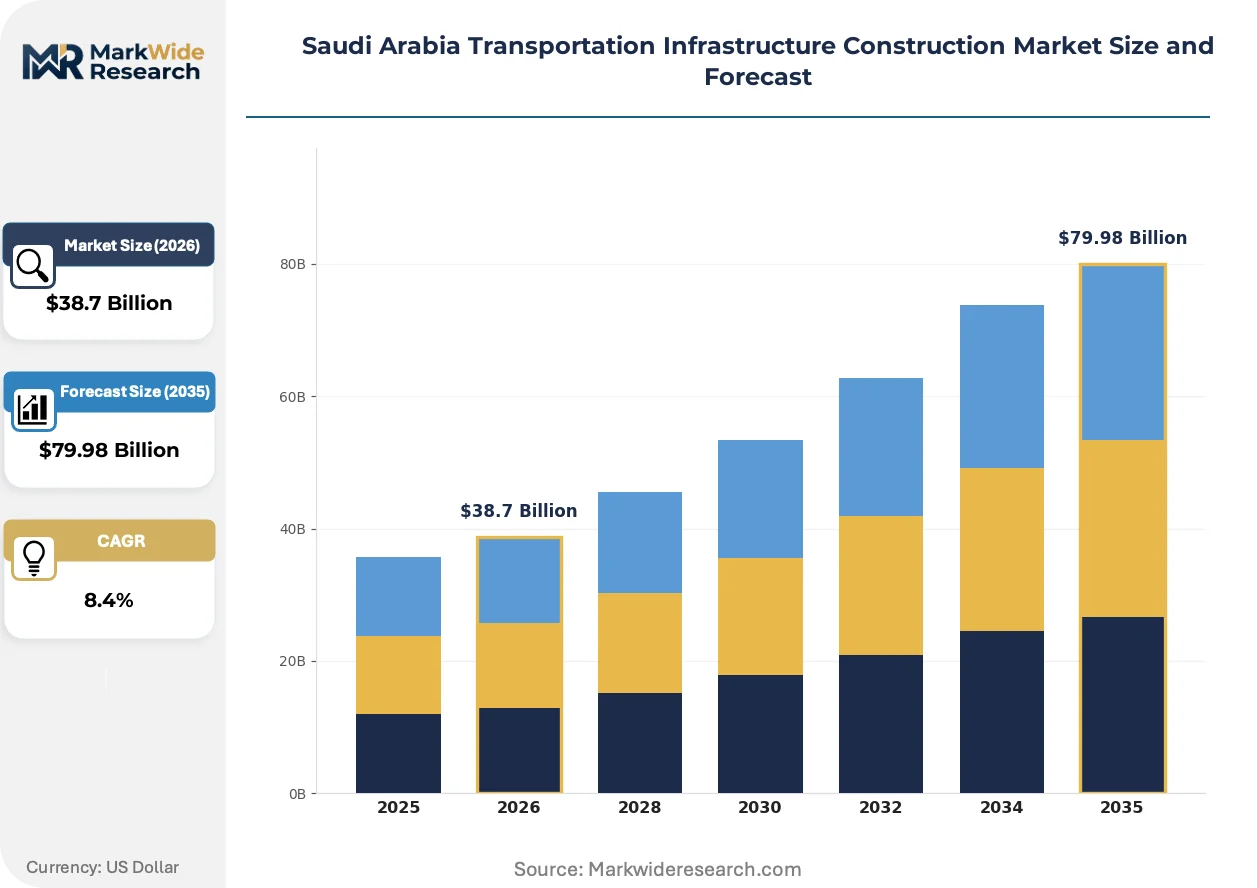
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $79.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Project Type: Roads, Bridges, Airports, Railways Technology: Smart Infrastructure, Conventional Construction, Modular Technology, Prefabrication End User: Government Agencies, Private Sector, Contractors, Consultants Funding Source: Public Funding, Private Investment, Public-Private Partnerships, International Loans |
| Companies Covered | Nesma & Partners, China Railway Construction Corp., Saudi Binladin Group, Fluor Corp, Bechtel, Al-Rashid Trading & Contracting Co., Al-Ayuni Investment & Contracting, Jacobs, Almabani, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Transportation Infrastructure Construction Market Strategic Shifts
Modular construction methods and digital project delivery are reshaping how Saudi contractors execute transport infrastructure, compressing traditional design-bid-build cycles while demanding new technical competencies.
Prefabricated bridge components and modular interchange systems are decentralizing on-site construction activity for the Riyadh-Jeddah corridor upgrades. Contractors are adopting factory-cast deck segments and pre-assembled steel girders to reduce desert-site exposure time. This technology is decentralizing project risk from weather-dependent casting yards to controlled manufacturing environments.
The Saudi Building Code's 2024 durability amendments for coastal bridge superstructures are tightening chloride resistance specifications for reinforced concrete. Contractors must now source low-alkali cement and epoxy-coated rebar for Red Sea zone contracts. Marine infrastructure specialists are responding by qualifying alternative cementitious materials and accelerated curing protocols.
Consortium-based procurement is consolidating contractor selection for megaproject packages, replacing fragmented sub-contracting with integrated design-build-operate teams. The Ministry of Transport and Logistics Services now favors single-point accountability for Riyadh Metro extensions and arterial highway bundles. This pattern is most visible in the Eastern Province, where Dammam-Jubail corridor contracts bundle road, rail, and port access components.
Saudi Arabia Transportation Infrastructure Construction Market Segmentation
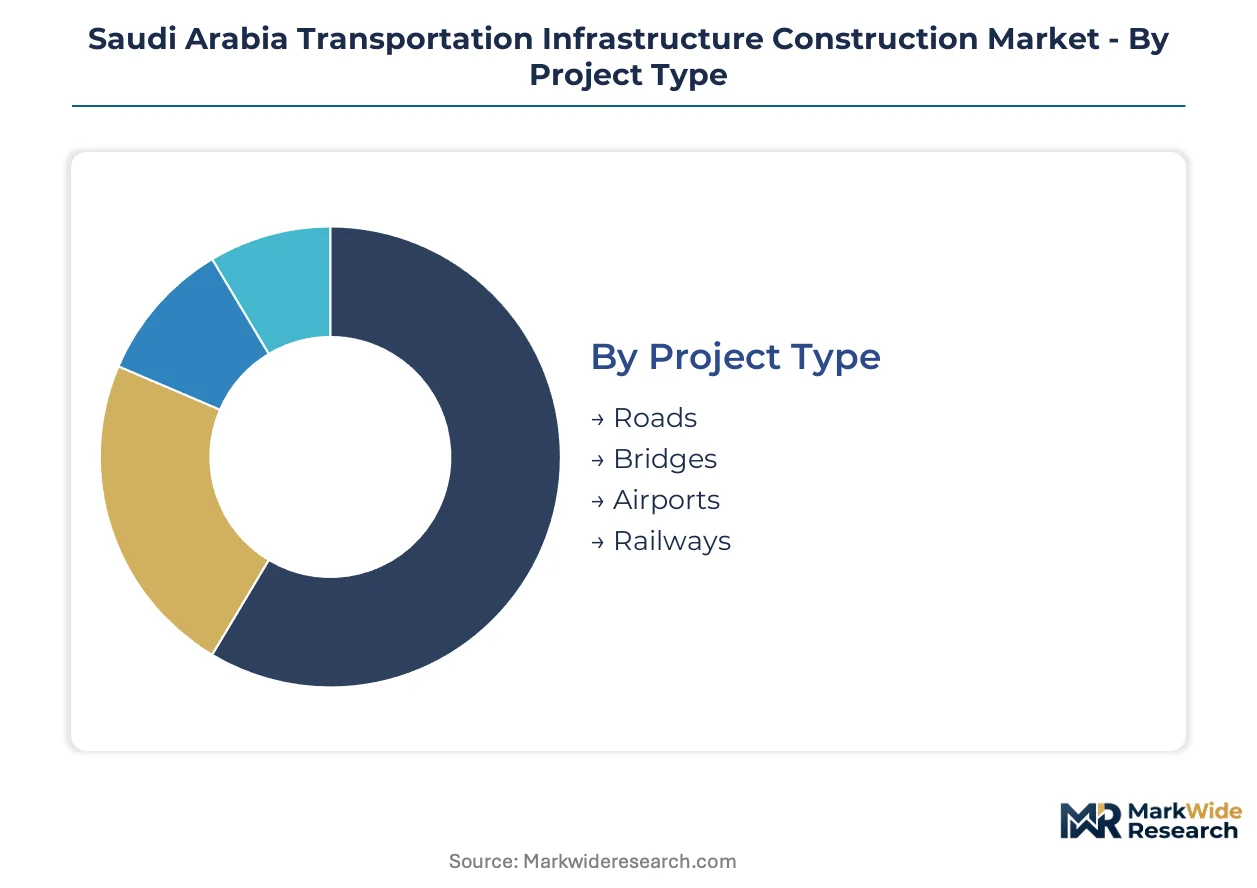
Segmentation in Saudi Arabia's transportation infrastructure construction market reveals how procurement complexity varies by project scale and technical sophistication. Contractors must align capabilities with distinct delivery models across giga-projects, urban corridors, and specialized marine installations.
Project Type:
Standardization dominates arterial highway contracts while bridge and airport work demands bespoke engineering for seismic and thermal specifications.
- Roads:Arterial highway upgrades and urban interchange densification absorb the largest contract volumes. Demand concentrates along the Riyadh-Jeddah corridor where logistics operators are scaling fleet capacity and asphalt procurement cycles are compressing under giga-project timelines.
- Bridges:Superstructure fabrication requires heat-resistant pavement binders and expansion joint systems rated for 50°C thermal loads. The Saudi Building Code's chloride resistance specifications for coastal environments are tightening material certification requirements for Red Sea zone contracts.
- Airports:Runway pavement and terminal integration projects serve Vision 2030 tourism targets.
- Railways:Riyadh Metro extensions and freight corridors demand turnkey rail-electrification packages with specialized signaling integration.
Most installed capacity flows through Roads. Expansion is steepest in Railways.
Technology:
Cost tier separation distinguishes premium smart systems from conventional methods, with modular approaches capturing mid-tier efficiency demands.
- Smart Infrastructure:IoT-enabled traffic management and predictive maintenance systems are gaining share fastest. Ministry of Transport and Logistics Services mandates are opening systems integration contracts for sensor networks and real-time monitoring platforms.
- Conventional Construction:Cast-in-place concrete and on-site steel erection remain the default for remote corridor segments where logistics constrain prefabricated delivery.
- Modular Technology:Factory-cast deck segments are decentralizing project risk from weather-dependent casting yards to controlled manufacturing environments.
- Prefabrication:Pre-assembled steel girders and modular interchange systems reduce desert-site exposure time on compressed schedules.
Conventional Construction retains the largest installed base. Smart Infrastructure is climbing the fastest.
End User:
Customer type determines contract scale and risk allocation, from sovereign procurement to specialized subcontractor niches.
- Government Agencies:Ministry of Transport and Logistics Services and municipal authorities bundle road, rail, and port access components under single-point accountability frameworks. NCA prequalification thresholds filter bidder pools on public tenders.
- Private Sector:Red Sea Development Company and NEOM project vehicles are compressing procurement cycles and demanding accelerated material pre-positioning.
- Contractors:Saudi Binladin Group and Nesma & Partners compete for design-build-operate packages with captive quarry networks or marine specialization.
- Consultants:Engineering advisory firms support Saudi Building Code compliance and SFDA material certification pathways.
Government Agencies command the largest contract flow. Private Sector projects are expanding most quickly.
Funding Source:
Volume concentration sits with sovereign-backed mechanisms while blended structures attract specialized international capital.
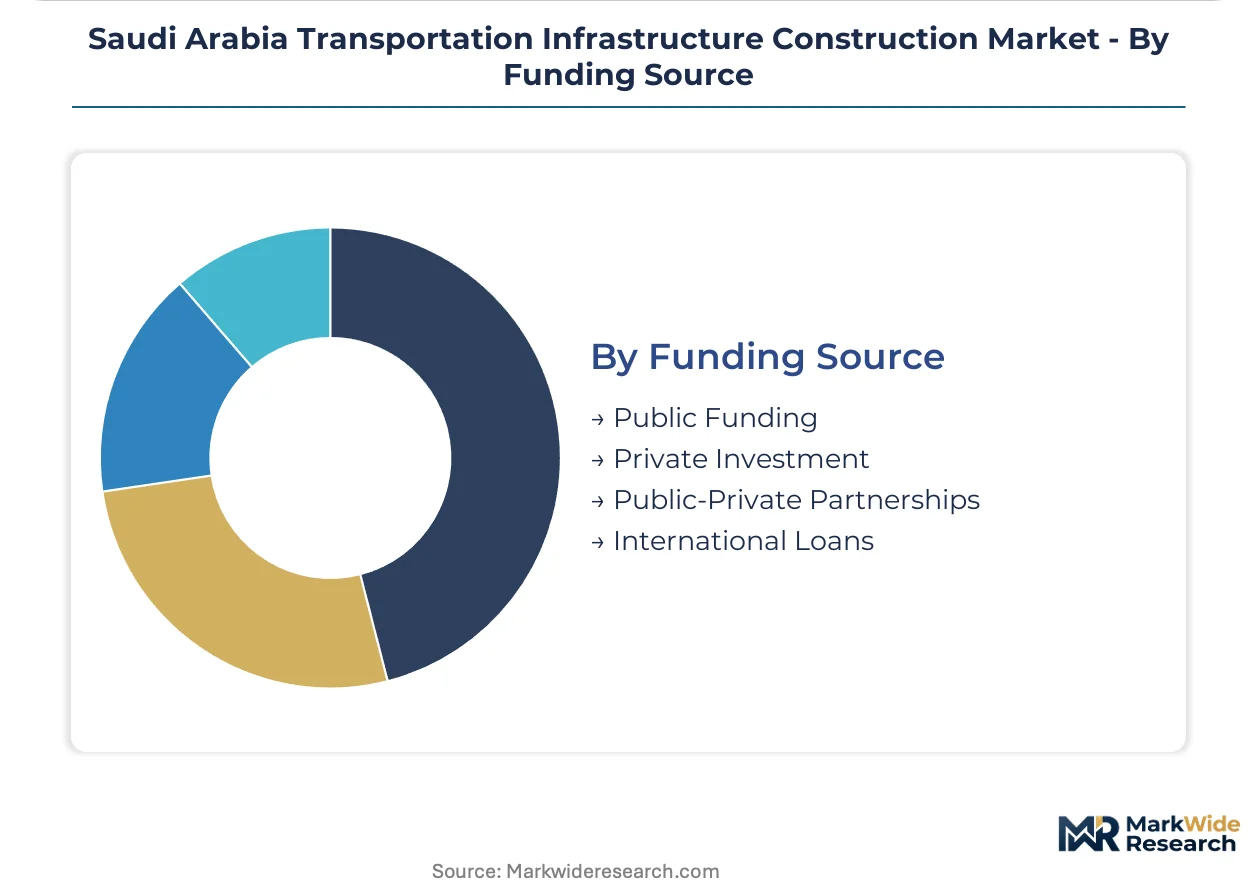
- Public Funding:Central government budgets and sovereign wealth vehicle allocations dominate arterial highway and metro extensions. SFDA and SASO certification requirements shape material sourcing decisions on state-funded contracts.
- Private Investment:Institutional capital targets yield-generating transport assets with operational revenue streams.
- Public-Private Partnerships:NCA-enforced prequalification scorecards weight domestic content ratios against technical capability benchmarks on bundled concessions.
- International Loans:Multilateral development bank financing supports cross-border connectivity corridors.
Public Funding underwrites most installed capacity. Public-Private Partnerships are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
NEOM anchors construction demand across Saudi Arabia's transportation infrastructure sector. Giga-project timelines compress procurement cycles for asphalt and steel-reinforced structures. The Riyadh-Jeddah corridor concentrates logistics fleet expansion and material pre-positioning activity.
Riyadh
Riyadh Metro extensions and arterial highway densification absorb the largest contract volumes in the capital region. The Ministry of Transport and Logistics Services mandates IoT-enabled traffic management systems on new corridors. The Riyadh-Jeddah logistics corridor concentrates fleet scaling by operators requiring expanded asphalt procurement.
Eastern Province
Dammam-Jubail corridor contracts bundle road, rail, and port access components under single-point accountability frameworks. NCA prequalification thresholds filter bidder pools on public tenders in this industrial zone. The Dammam metropolitan area hosts concentrated marine infrastructure specialization for Arabian Gulf port gateways.
Western Region
Jeddah Islamic Port handles steel import flows for bridge and highway contracts across the coastal zone. SFDA material standards and SASO certification requirements shape polymer-modified asphalt sourcing decisions. The Jeddah-Mecca corridor experiences urban interchange densification under compressed giga-project schedules.
NEOM Northwest
The $500 billion NEOM development generates concentrated demand for heat-resistant pavement binders and expansion joint systems rated for 50°C thermal loads. The Saudi Building Code's 2024 durability amendments tighten chloride resistance specifications for coastal bridge superstructures. Oxagon and THE LINE construction sites reward contractors with captive quarry networks and modular fabrication capabilities.
Saudi Arabia Transportation Infrastructure Construction Market Competitive Environment
Global majors compete with regional champions across design-build-operate delivery models in Saudi Arabia's transportation infrastructure sector. The market exhibits tiered consolidation where sovereign-backed contractors anchor megaproject execution while international engineering firms capture specialized systems integration. Three archetypes dominate: domestic conglomerates with backward-integrated material supply, multinational turnkey specialists, and marine infrastructure experts. Competitive intensity centers on prequalification scorecard optimization and captive quarry network expansion.
Within the domestic conglomerate tier, Saudi Binladin Group exemplifies backward-integrated execution through captive quarry and batching-plant networks. Nesma & Partners occupies a specialist position in marine infrastructure at Red Sea port gateways. China Railway Construction Corp. represents the multinational turnkey archetype competing on rail-electrification packages.
| Leading Market Players |
|---|
| Nesma & Partners |
| China Railway Construction Corp. |
| Saudi Binladin Group |
| Fluor Corp |
| Bechtel |
| Al-Rashid Trading & Contracting Co. |
| Al-Ayuni Investment & Contracting |
| Jacobs |
| Almabani |
| Others |
Value Chain & Pricing Dynamics
Government procurement bundling under Ministry of Transport and Logistics Services mandates enforces project-based contract pricing with cost-plus escalation clauses tied to steel and asphalt indices. This buyer concentration shifts pricing power toward contractors with captive quarry networks and pre-positioned material stocks.
Pricing Analysis
Input-cost pass-through mechanisms dominate contract structures, with polymer-modified asphalt and epoxy-coated rebar subject to quarterly price adjustments based on SFDA-certified import benchmarks. Price differentiation separates NCA-prequalified tier-one contractors from mid-tier bidders through domestic content ratio weighting and SASO certification compliance. Pricing pressure stems from freight rate volatility at Jeddah Islamic Port and customs clearance bottlenecks. Government agencies exhibit lowest price sensitivity due to sovereign budget backing, while private sector project vehicles at NEOM and Red Sea Development Company demand aggressive cost predictability guarantees.
Supply Chain Analysis
Reverse-logistics flows for modular bridge components and prefabricated deck segments create secondary refurbishment channels for steel girders and expansion joint systems. Geographic supply concentration draws from China, South Korea, and India for structural steel, with polymer-modified asphalt additives sourced from specialized chemical producers in Germany and the United States. Raw material dependencies center on low-alkali cement, high-performance concrete admixtures, and heat-resistant pavement binders. Single-source vulnerability persists in Asian steel supply chains exposed to shipping lane disruptions. Distribution runs through Jeddah Islamic Port for Red Sea zone projects and Dammam port complexes for Eastern Province corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Saudi Arabia transportation infrastructure construction operates as a stable compounder anchored by Vision 2030 sovereign capital deployment across giga-project pipelines. Contract flow predictability supports sustained capacity utilization for prequalified contractors.
For Market Incumbents: Anticipate margin compression from NCA domestic content ratio escalation by securing backward integration into aggregate production and captive batching-plant networks. Defend prequalification scorecard positioning through accelerated SASO certification pathways for polymer-modified asphalt and high-performance concrete admixtures. Threat vectors include emerging Chinese turnkey specialists competing on rail-electrification packages with state-backed financing. For New Entrants and Emerging Players: Capture white-space in smart infrastructure systems integration where IoT-enabled traffic management mandates outpace incumbent technical capabilities. Target marine infrastructure specialization at Red Sea port gateways where dredging and quay wall expertise faces supply scarcity. Go-to-market angle should emphasize modular fabrication capabilities aligned with compressed giga-project timelines at Oxagon and THE LINE construction sites. For Investors and Strategic Acquirers: Sovereign wealth vehicles and regional construction conglomerates are the most active acquirers in this space, seeking design-build-operate capabilities with NCA prequalification standing. Long-term viability rests on 5-10 year contract backlog visibility from Ministry of Transport and Logistics Services bundling strategies. Acquisition target archetype: mid-tier contractors with captive quarry assets and Red Sea zone project experience. Signal to monitor: NCA prequalification threshold adjustments weighting technical capability benchmarks against domestic content ratios.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Quarry Network Expansion | Saudi Binladin Group secures cost predictability on NEOM megaproject sites through backward-integrated aggregate supply. |
| Smart Infrastructure Systems Integration | IoT-enabled traffic management mandates from Ministry of Transport open contracts for sensor network specialists. |
| Marine Infrastructure Specialization | Red Sea port gateway expansions reward firms with dredging expertise and breakwater construction capabilities. |
| SASO Certification Acceleration | Pre-positioned material stocks reduce 8-14 week import approval delays disrupting just-in-site delivery schedules. |
| Modular Fabrication Capability Buildout | Factory-cast deck segments decentralize project risk from desert weather exposure to controlled manufacturing environments. |
Study Parameters
Coverage spans Riyadh, Eastern Province, Western Region, and NEOM Northwest, with primary inputs from each territory combined with secondary validation. Primary interviews engaged Ministry of Transport and Logistics Services procurement officers, NCA prequalification specialists, EPC contractor project directors, marine infrastructure engineering leads, and SFDA material certification coordinators. Secondary sources included Saudi Building Code amendment documentation, NCA tender announcements, SASO product standards databases, and customs clearance records from Jeddah Islamic Port. Bottom-up project pipeline aggregation and top-down sovereign budget allocation analysis provided triangulation.
Rate-of-change decomposition structured the analytical framework across the analysis window, segmenting by project type, technology tier, end-user category, and funding source. Segmentation dimensions modeled encompass roads, bridges, airports, and railways alongside smart infrastructure, conventional construction, modular technology, and prefabrication approaches. CAGRs derived from historical contract award patterns, giga-project timeline acceleration factors, and material procurement cycle compression. Industry-specific forecast inputs incorporated thermal load specification evolution and seismic Zone 2A engineering standard adoption.
Giga-project timeline slippage, NCA prequalification threshold recalibration, and Asian steel supply disruption are the dominant revision risks to forecast assumptions. Practitioners should monitor NEOM construction pace, domestic content ratio policy shifts, and Jeddah Islamic Port throughput metrics for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Construction
India Commercial Construction Market
Building Construction
China Modular Construction Market
Building Construction
Qatar Construction Market
Building Construction
Indonesia Infrastructure Market
Building Construction
UK Construction Market
Building Construction
Spain Construction Market
Building Construction
Prefabricated Buildings Market
Building Construction
Spain Prefab Wood Buildings Market
Building Construction
Vietnam Construction Market
Building Construction
Tanzania Construction Market
Building Construction
Turkey Commercial Construction Market
Building Construction
France Prefab Wood Building Market
Building Construction
Guatemala Construction Market
Building Construction
Germany Prefabricated Buildings Market
Building Construction
Saudi Arabia Prefab Wood Buildings Market
Building Construction
Poland Construction Market