
 South Korea HVAC Market | 2026-2036
South Korea HVAC Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea HVAC Market Insights
Project-specified distribution is tilting toward contractor-direct and facility-manager procurement channels in South Korea's commercial construction pipeline. Samsung Electronics leverages its domestic manufacturing scale to anchor supply relationships with major chiller installations. LG Electronics differentiates through integrated building management interfaces that appeal to facility managers overseeing large portfolios. Daikin Industries competes on variable refrigerant flow specialization, sustaining technical credibility among architect-specified projects in Seoul's premium commercial segment.
Heating, ventilation, and air conditioning systems encompass electromechanical equipment designed to regulate indoor temperature, humidity, and air quality through vapor-compression refrigeration cycles, typically operating with refrigerants at pressures between 150 and 450 psi for commercial applications. These systems serve primary industrial and commercial purposes including occupant comfort, process cooling for manufacturing, and environmental control for sensitive operations such as semiconductor cleanrooms and pharmaceutical storage. Air conditioners and heat pumps together capture the dominant share of residential and light-commercial value, while chillers command premium positioning in data center and healthcare applications where redundant capacity and precise temperature control justify higher capital outlay. Variable refrigerant flow technology is expanding fastest among technology segments as building owners prioritize zonal control and part-load efficiency in mixed-use developments across Seoul and Incheon.
MFDS oversight of refrigerant safety standards intersects with KEMCO's energy efficiency labeling mandates to shape product certification requirements for equipment sold domestically. METI-aligned efficiency benchmarks and South Korea's national greenhouse gas reduction roadmap are forcing manufacturers to accelerate low-global-warming-potential refrigerant transitions ahead of stricter phase-down schedules. Stakeholders must monitor how Seoul Metropolitan Government's building retrofit ordinances and Gyeonggi Province's industrial zone expansion plans redistribute demand between replacement cycles and new installation opportunities.
Market Dynamics
Data center construction across Gyeonggi Province is compressing procurement cycles for high-capacity chillers while KEMCO's revised energy efficiency labels are forcing refrigerant transitions ahead of manufacturer roadmaps.
Growth Catalysts
- Gyeonggi Province data center clusters:Hyperscale facility investments are generating concentrated demand for redundant cooling capacity with precise temperature control requirements.
- Seoul Metropolitan Government retrofit mandates:Building energy ordinances are accelerating replacement cycles in the capital's aging commercial stock.
- Low-GWP refrigerant transitions:MFDS safety certifications aligned with national greenhouse gas reduction targets are pulling forward equipment upgrade decisions.
Market Restraints
- Copper and aluminum input volatility:Heat exchanger material costs fluctuate with commodity markets, compressing margins on fixed-price installation contracts.
- Refrigerant supply concentration:Domestic production capacity for HFO blends remains limited, creating import dependency for compliant equipment lines.
- Seismic certification requirements:Structural reinforcement standards for rooftop installations add engineering complexity and timeline risk.
Strategic Opportunities
- Busan industrial corridor expansion:Manufacturing zone development is creating greenfield demand for process cooling and ventilation systems.
- VRF-BMS convergence:Integration of variable refrigerant flow with building management platforms opens premium specification channels.
- Chungcheong region logistics hubs:Cold storage and distribution center construction is expanding addressable market for packaged rooftop units.
Industry Challenges
- Refrigerant handling certification:Technician licensing requirements under MFDS standards are constraining qualified installation labor pools.
- Legacy chiller integration:Connecting new high-efficiency equipment with existing district cooling infrastructure requires custom engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea HVAC Market |
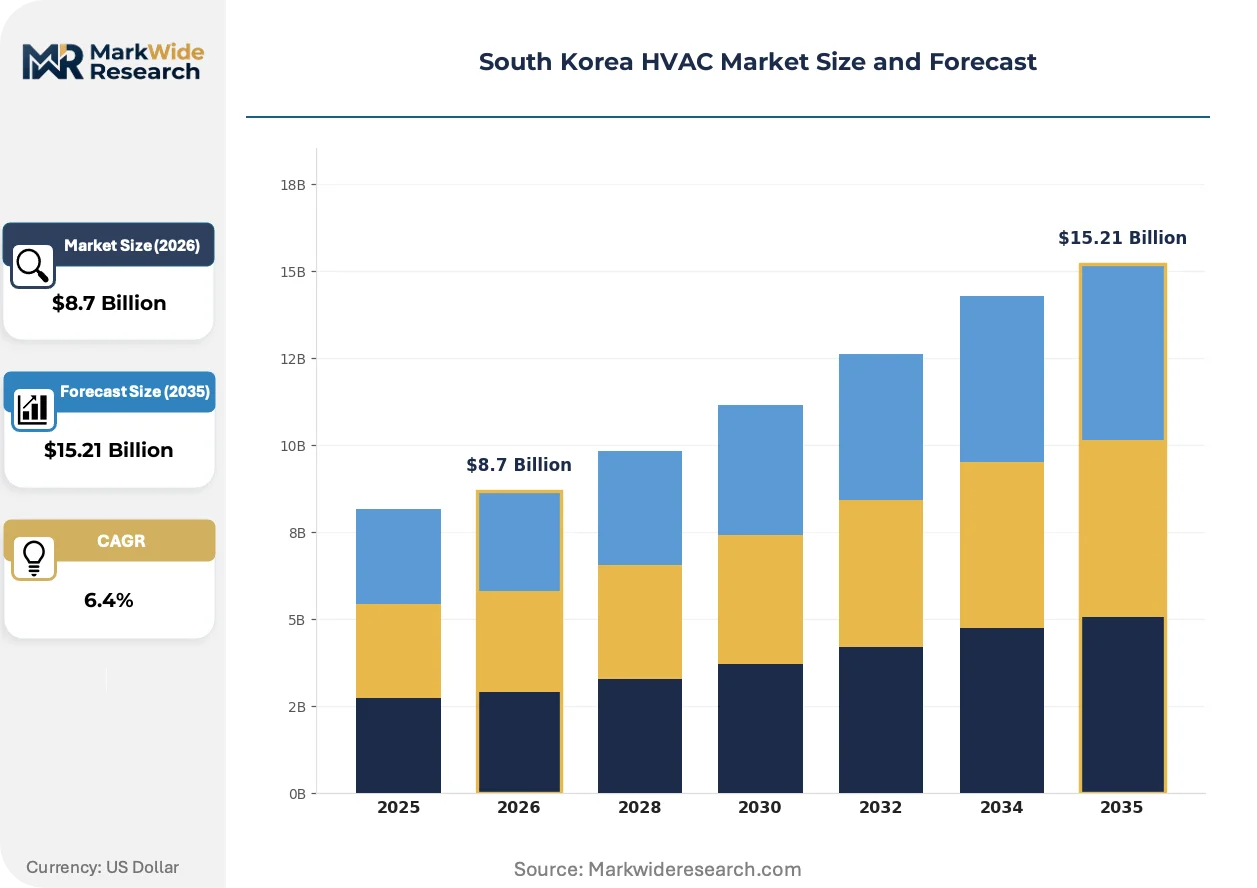
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Heat Pumps, Air Conditioners, Chillers, Furnaces Application: Residential, Commercial, Industrial, Healthcare Technology: Variable Refrigerant Flow, Packaged Units, Ductless Systems, Geothermal End User: Building Owners, Contractors, Facility Managers, Architects |
| Companies Covered | Samsung Electronics, LG Electronics, Trane Technologies, Mitsubishi Electric, Daikin Industries, Carrier Global Corporation, Johnson Controls International, Panasonic Holdings Corporation, Midea Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea HVAC Market Trends and Innovations
Digital twin technology is virtualizing system design workflows while regulatory pressure on refrigerant chemistry is compressing product development timelines. These forces are reshaping how equipment is specified, procured, and maintained across South Korea's commercial built environment.
AI-driven predictive maintenance platforms are virtualizing traditional service relationships. Facility managers in Seoul's premium office segment are adopting cloud-based diagnostics that continuously monitor chiller performance and refrigerant charge levels. This technology is virtualizing the role of on-site maintenance crews, compressing response times while shifting vendor revenue toward subscription-based monitoring contracts.
KEMCO's energy efficiency labeling revisions are tightening minimum performance thresholds for commercial equipment categories. Manufacturers must recertify product lines using updated test procedures that reflect actual operating conditions rather than laboratory benchmarks. Large-format retail and healthcare installations face the steepest compliance adjustments, driving accelerated replacement of equipment installed during the 2015-2018 construction cycle.
Direct procurement relationships between facility managers and original equipment manufacturers are displacing traditional distributor intermediaries. Building owners with multi-site portfolios in Incheon and Seoul are consolidating purchasing through national framework agreements that bundle equipment, installation, and long-term service. This channel compression is most visible in the data center and pharmaceutical verticals, where technical specifications require direct manufacturer engagement.
South Korea HVAC Market Segmentation
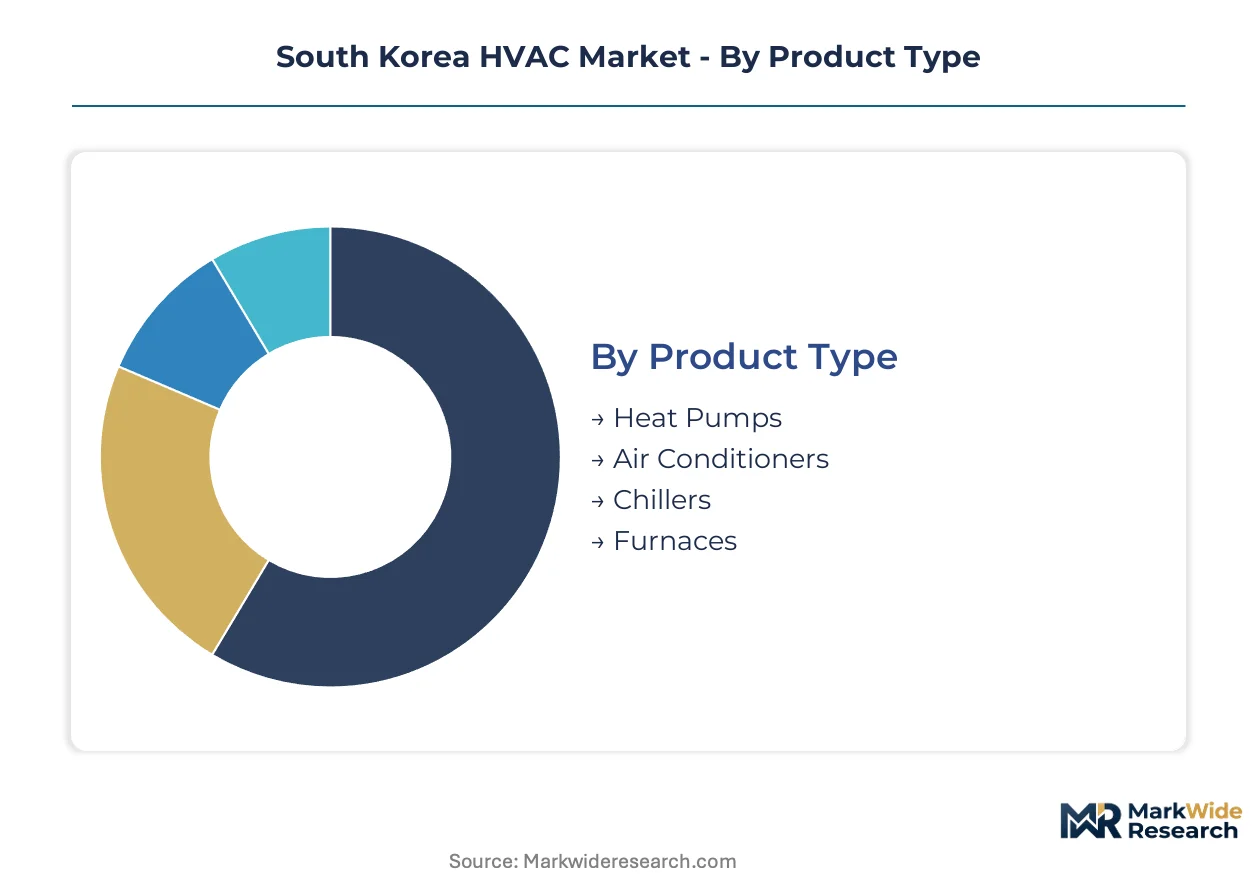
South Korea's HVAC market segments reveal how equipment specifications diverge across building types and procurement channels. Understanding these divisions exposes where technology transitions and regulatory pressures concentrate commercial opportunity.
Product Type:
Mature vapor-compression equipment dominates installed base volumes while emerging thermal technologies capture specification interest in premium new construction.
- Air Conditioners:Split and packaged units utilizing R32 or R410A refrigerants serve the bulk of residential and light-commercial cooling loads across Seoul's dense apartment complexes. Daegu's manufacturing corridors and Gwangju's commercial districts generate replacement demand as KEMCO efficiency labels tighten minimum performance thresholds.
- Chillers:Centrifugal and screw-compression systems with capacities exceeding 100 tons address district cooling networks and hyperscale data centers in Gyeonggi Province. Redundant capacity requirements and precise temperature control specifications justify premium capital outlay for semiconductor cleanroom and pharmaceutical storage applications.
- Heat Pumps:Air-source and water-source configurations deliver combined heating and cooling through reversed refrigeration cycles, gaining specification in Busan's coastal commercial developments where seasonal load variation demands flexible capacity.
- Furnaces:Gas-fired and electric heating equipment retains position in legacy industrial facilities across Ulsan's petrochemical zones where process heating integration outweighs efficiency upgrade incentives.
Air conditioners retain volume leadership; chillers hold the steepest expansion curve.
Application:
Cost tier stratification separates standardized residential equipment from engineered commercial systems requiring custom controls integration.
- Commercial:Office towers, retail complexes, and hospitality developments in Seoul's Gangnam and Yeouido districts specify high-efficiency VRF and chiller systems with building management integration. MFDS refrigerant safety certifications and KEMCO labeling mandates drive equipment replacement ahead of typical depreciation cycles.
- Industrial:Manufacturing facilities in Busan's automotive corridors and Incheon's logistics hubs demand process cooling with contaminant filtration and humidity control for precision assembly operations.
- Residential:Multi-family housing in Suwon and Seongnam represents high-volume standardized demand where apartment developers prioritize first-cost minimization over lifecycle efficiency.
- Healthcare:Hospitals and pharmaceutical storage in Daejeon and Gwangju require redundant HVAC capacity with HEPA filtration and precise temperature-humidity control for sterile environments.
Commercial applications command the highest value per installation; industrial demand is climbing fastest on zone expansion.
Technology:
Customer type differentiation shapes specification authority, with facility managers and architects driving premium technology adoption against contractor-driven standardization.
- Variable Refrigerant Flow:Multi-zone heat recovery systems modulate refrigerant flow to individual indoor units, enabling simultaneous heating and cooling across mixed-use developments in Seoul's Yongsan and Mapo districts. Zonal control and part-load efficiency appeal to building owners with portfolio-scale energy management mandates.
- Ductless Systems:Mini-split and multi-split configurations eliminate ductwork losses in retrofitted commercial spaces and high-rise residential where structural constraints prohibit central air distribution.
- Packaged Units:Factory-assembled rooftop systems integrate compressors, coils, and controls for rapid deployment in Chungcheong region logistics hubs and cold storage facilities.
- Geothermal:Ground-source heat pumps leverage stable subsurface temperatures for efficiency gains, limited by drilling costs and geological suitability to Jeju Island resorts and select government demonstration projects.
Variable Refrigerant Flow dominates new specification value; ductless systems are expanding most quickly on retrofit activity.
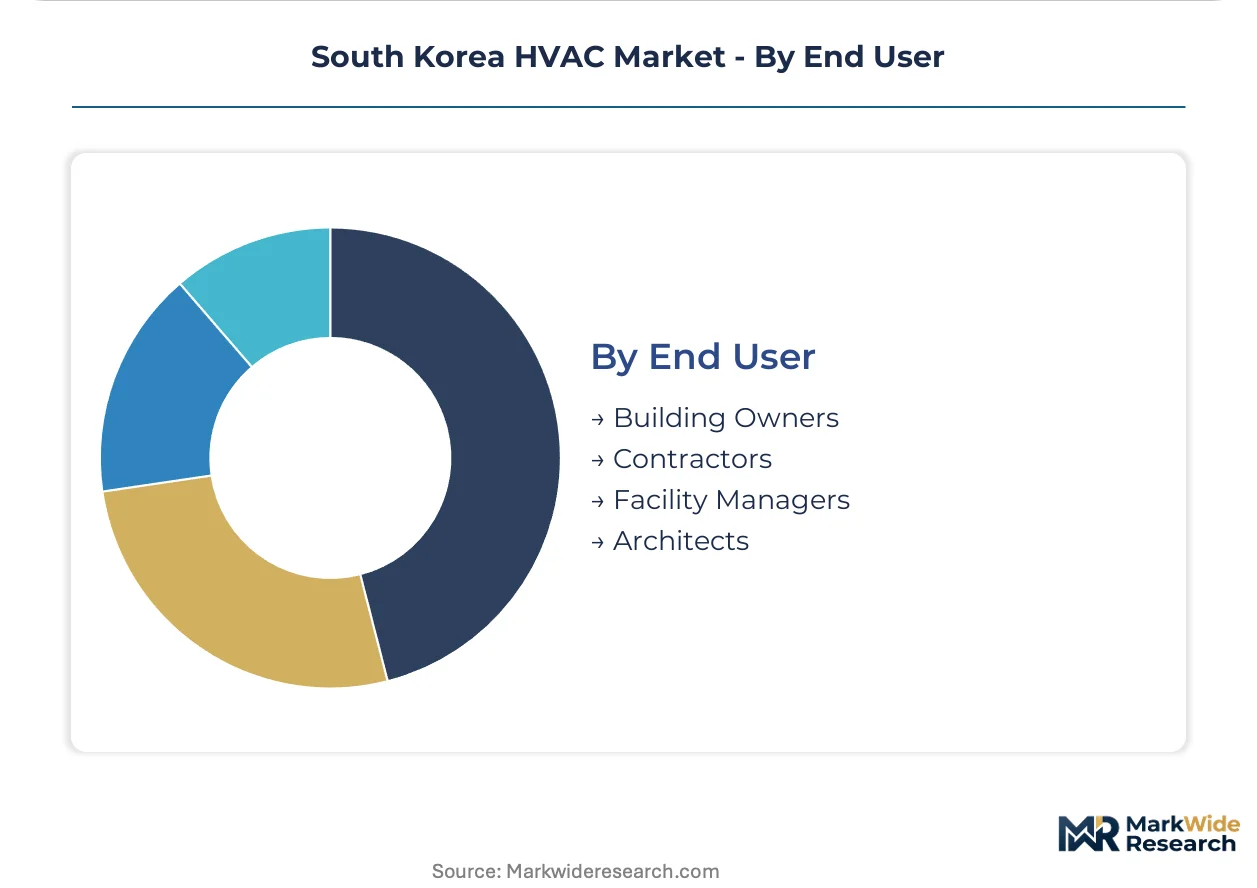
End User:
Supply concentration among domestic manufacturers shapes how procurement channels fragment between direct OEM relationships and traditional distribution.
- Facility Managers:Multi-site portfolio operators in Incheon and Seoul consolidate purchasing through national framework agreements bundling equipment, installation, and predictive maintenance subscriptions. Direct manufacturer engagement replaces distributor intermediaries for technically complex specifications.
- Contractors:Installation firms serving Gyeonggi Province data center construction prioritize high-capacity chiller procurement with compressed delivery timelines and seismic certification compliance.
- Building Owners:Single-asset developers in Busan's emerging industrial zones evaluate lifecycle cost against first-cost constraints for greenfield ventilation and process cooling investments.
- Architects:Design firms specifying Seoul's premium commercial segment prioritize aesthetic integration and building management system compatibility, driving VRF and concealed ductless selections.
Facility managers are capturing procurement authority fastest; contractors retain volume leadership in new construction channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Seoul Capital Area's integrated high-speed rail network and metropolitan subway system compress logistics costs for HVAC equipment distribution across Gyeonggi Province data center clusters. This infrastructure backbone enables rapid deployment of high-capacity chillers to hyperscale facilities while supporting just-in-time procurement for Seoul's commercial retrofit wave.
Seoul Capital Area
Seoul's district cooling zones and Gangnam office towers generate concentrated demand for VRF systems with building management integration. Seoul Metropolitan Government retrofit mandates accelerate replacement cycles in aging commercial stock. Yeouido financial district specifications prioritize redundant chiller capacity for trading floor uptime requirements.
Busan-Ulsan
Busan's automotive manufacturing corridors and Ulsan's petrochemical zones drive process cooling investments with contaminant filtration requirements. MFDS refrigerant safety certifications shape equipment selection for industrial ventilation systems. Busan Port cold storage expansions anchor demand for packaged rooftop units in logistics adjacencies.
Daegu-Gyeongbuk
Daegu's textile and electronics manufacturing bases require precision humidity control for sensitive assembly operations. KEMCO energy efficiency labeling mandates pull forward equipment upgrades in industrial facilities. Gumi industrial complex expansions concentrate procurement of high-efficiency heat pumps for process heating integration.
Daejeon-Sejong
Daejeon's government research complexes and Sejong administrative city construction generate institutional demand for centralized HVAC systems. National greenhouse gas reduction targets force low-GWP refrigerant transitions in public buildings. Daedeok Innopolis technology cluster specifications emphasize predictive maintenance integration.
Gwangju-Honam
Gwangju's automotive parts manufacturing and Honam region agricultural processing create mixed demand for industrial ventilation and cold chain infrastructure. Regional logistics hub development in Naju expands addressable market for packaged units. Jeju Island resort geothermal demonstrations anchor niche heat pump specifications.
South Korea HVAC Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying compressors, heat exchangers, and control modules. Domestic chaebol-affiliated manufacturers anchor supply relationships through captive distribution networks and direct procurement channels with national developers. Three archetypes dominate: vertically integrated electronics conglomerates leveraging manufacturing scale, specialized HVAC pure-plays competing on technical specification, and international system houses penetrating through technology licensing. Competitive intensity concentrates on refrigerant transition speed and predictive maintenance platform development.
Among domestic electronics conglomerates, Samsung Electronics and LG Electronics exemplify platform integrators that compress procurement cycles through in-house component production and direct facility manager engagement. Daikin Industries occupies a position as the specialized pure-play archetype, anchoring architect-specified premium commercial segments through VRF technical credibility. These three companies represent the competitive core around which procurement channel restructuring and refrigerant transition investments orbit.
| Leading Market Players |
|---|
| Samsung Electronics |
| LG Electronics |
| Trane Technologies |
| Mitsubishi Electric |
| Daikin Industries |
| Carrier Global Corporation |
| Johnson Controls International |
| Panasonic Holdings Corporation |
| Midea Group |
| Others |
Pricing and Supply Chain Analysis
Gyeonggi Province's chiller manufacturing clusters concentrate compressor and heat exchanger capacity, translating upstream component availability into pricing leverage for domestic OEMs serving data center procurement cycles. Copper and aluminum input volatility feeds directly into equipment quotations, compressing margins on fixed-price installation contracts while KEMCO efficiency recertification costs add compliance premiums to commercial system pricing.
Pricing Analysis
Volume-discount tiering structures separate national framework agreements from project-specific procurement, with facility managers capturing 15-20% unit cost reductions through multi-site portfolio consolidation against single-asset developers paying standard list rates. Price differentiation rests on KEMCO certification grade and after-sales service bundling, where predictive maintenance subscriptions command 12-18% premiums over transactional equipment-only sales. Cost compression in mid-tier packaged units is intensifying because import-dependent HFO refrigerant supply constrains manufacturer flexibility. Residential apartment developers in Suwon and Seongnam exhibit highest price sensitivity, while Seoul data center operators prioritize redundancy specifications over capital outlay minimization.
Supply Chain Analysis
Supplier-financing facilities from domestic chaebol-affiliated manufacturers extend 90-120 day payment terms to contractor networks, compressing working capital requirements for Gyeonggi Province installation firms. Geographic supply concentration centers on South Korea, China, and Japan for compressor assemblies, control electronics, and refrigerant blends. Raw material dependencies draw from Chilean copper, Australian aluminum, and Chinese rare earth processing for permanent magnet motors. Single-source vulnerability concentrates in HFO-1234yf import channels, where domestic blending capacity remains underdeveloped. Distribution runs through manufacturer-direct procurement for large-format commercial projects and traditional HVAC distributors for residential replacement cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South Korea's HVAC market sits in cyclical recovery phase, with Seoul Metropolitan Government retrofit mandates and Gyeonggi data center construction combining to pull replacement demand forward from typical depreciation cycles.
For Market Incumbents: Insulate margin position through backward integration into refrigerant blending capacity, reducing import dependency exposure as MFDS phase-down schedules tighten. Secure seismic certification pre-approvals for rooftop chiller configurations to compress Gyeonggi data center procurement timelines against competitors lacking pre-qualified equipment lines. For New Entrants and Emerging Players: Pursue specification authority in Busan industrial corridor greenfield developments, where process cooling requirements for automotive manufacturing create entry points against entrenched Seoul-centric suppliers. Target facility manager direct procurement channels with predictive maintenance platform bundling, displacing traditional distributor relationships in multi-site portfolio accounts. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance play because refrigerant transition investments and KEMCO recertification requirements will consolidate procurement authority toward manufacturers with integrated service platforms and domestic production scale. Acquisition target archetype: specialized VRF engineering firms with established architect relationships in Seoul's premium commercial segment. Signal to watch: MFDS acceleration of low-GWP refrigerant mandates beyond current roadmap timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Platform Launch | Subscription revenue models displace transactional service relationships in Seoul facility manager accounts. |
| Refrigerant Blending Capacity Expansion | Domestic HFO production reduces import dependency and compresses lead times for compliant equipment lines. |
| Seismic Certification Pre-Approval | Pre-qualified rooftop systems accelerate Gyeonggi data center procurement cycles against uncertified competitors. |
| VRF-BMS Integration Partnership | Building management system convergence opens architect-specified premium commercial channels in Gangnam towers. |
| Busan Industrial Zone Distribution Agreement | Process cooling specialization captures automotive corridor expansion ahead of incumbent repositioning. |
Research Methodology
Initial hypotheses were tested against primary input from HVAC equipment procurement managers, facility engineering directors, chiller installation contractors, and KEMCO certification specialists and refined through secondary validation against MFDS regulatory filings, KEMCO energy efficiency labeling databases, and Seoul Metropolitan Government building ordinance records. Bottom-up equipment shipment analysis triangulated with top-down construction spending data across commercial, industrial, and residential verticals.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, modeling equipment replacement cycles against new installation demand from data center and logistics hub construction. Segmentation dimensions included product type, application vertical, technology configuration, and procurement channel authority. CAGRs were derived from installed base depreciation curves and efficiency mandate acceleration effects. Forecast inputs incorporated copper price volatility assumptions and refrigerant supply constraint scenarios.
Sensitivities concentrate around MFDS refrigerant phase-down acceleration, KEMCO labeling threshold revisions, and Gyeonggi data center construction timeline shifts. Forecasts reflect documented assumptions regarding regulatory implementation schedules and commodity input trajectories. Macroeconomic deviation, regulatory timing changes, or technological substitution in cooling architectures would prompt forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Ceiling Cassettes Market
HVAC Equipment
Global Smart Vent Market
HVAC Equipment
Heavy Duty Heat Pump Market
HVAC Equipment
Global Fan Coil Unit Market
HVAC Equipment
United States HVAC Equipment Market
HVAC Equipment
France Commercial HVAC Market
HVAC Equipment
Compressor Market
HVAC Equipment
France HVAC Market
HVAC Equipment
United States HVAC Equipment and Services Market
HVAC Equipment
Europe Hydronic Radiators Market
HVAC Equipment
Hybrid Air Conditioner Market
HVAC Equipment
Mexico Compressed Air Treatment Equipment Market
HVAC Equipment
Industrial Boiler Market
HVAC Equipment
North America Industrial Air Chiller Market
HVAC Equipment
Industrial Dehumidifiers Market
HVAC Equipment
Canada Commercial HVAC Market