
 Brazil Construction Market | 2026-2036
Brazil Construction Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Construction Market Analysis
Project finance through infrastructure debentures is fragmenting capital access across Brazil's construction sector, allowing mid-tier firms to bid on assets once reserved for balance-sheet-heavy incumbents. Odebrecht Engineering & Construction anchors its position through deep backward integration into engineering services. Mota-Engil E&C competes aggressively on transport infrastructure, leveraging Portuguese-African project experience to differentiate its bidding. Mills Estruturas e Servicos de Engenharia specializes in equipment rental and temporary structures, occupying a niche that shields it from direct construction risk.
Brazil construction encompasses the physical assembly of buildings and civil works using concrete, steel, wood, and glass composites, with structural concrete typically specified at 20-50 MPa compressive strength for high-rise frames. Its primary purpose is creating durable, regulated spaces for habitation, commerce, manufacturing, and public circulation. Residential construction leads volume absorption as mortgage credit expansion through Caixa Econômica Federal pulls first-time buyers into formal ownership. Infrastructure commands the longest project cycles and deepest capital stacks, with margin pools concentrating in mega-project concessions where risk transfer to private operators is most complete.
ANVISA sets sanitary standards for healthcare and pharmaceutical facility construction, while ABNT technical norms govern material specifications and structural safety coefficients nationwide. The Ministry of Cities coordinates PAC growth acceleration program allocations, directing federal resources toward housing deficits and transit expansion. IBAMA environmental licensing delays routinely reshape project timelines, particularly in Amazon biome-adjacent developments where licensing scrutiny is intensifying. Stakeholders must monitor how the new federal sanitation legal framework reconfigures concession structuring for water and sewage infrastructure.
Market Dynamics
Affordable housing programs through Caixa Econômica Federal are pulling first-time buyers into formal ownership, redistributing cement and steel demand toward São Paulo's transit-oriented corridors while elevating technical standards through ANVISA certification mandates.
Growth Catalysts
- PAC Growth Acceleration Program:Federal allocations through the Ministry of Cities direct capital toward housing deficits and transit expansion, concentrating project pipelines in urban corridors with established contractor ecosystems.
- Transit-Oriented Development:São Paulo state's urban rail and bus rapid transit expansions are absorbing disproportionate shares of structural concrete and reinforcing steel volumes.
- Healthcare Facility Standards:ANVISA sanitary certification requirements for hospitals and pharmaceutical plants are elevating technical specifications across the sector, creating premium contracting tiers.
Market Restraints
- Cement Input Volatility:Domestic clinker production capacity constraints expose contractors to fuel-linked price swings in bulk materials.
- Amazon Licensing Delays:IBAMA environmental scrutiny in biome-adjacent regions routinely extends project timelines beyond contracted completion windows.
- Steel Import Dependence:Flat-rolled structural sections concentrate in a narrow supplier base, amplifying exposure to currency-driven cost shocks.
Strategic Opportunities
- Sanitation Legal Framework:New federal concession rules for water and sewage infrastructure are reconfiguring risk transfer mechanisms to private operators.
- Equipment Rental Specialization:Temporary structures and machinery leasing niches shield service providers from direct construction completion risk.
- Northeast Housing Deficit:Underserved urban populations in Recife and Fortaleza corridors present greenfield development potential outside saturated Southeast markets.
Industry Challenges
- Skilled Concrete Labor Scarcity:Formwork carpentry and rebar placement trades face generational replacement gaps, compressing site productivity.
- ABNT Certification Timelines:Material specification approvals and structural safety coefficient validations extend pre-construction phases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Construction Market |
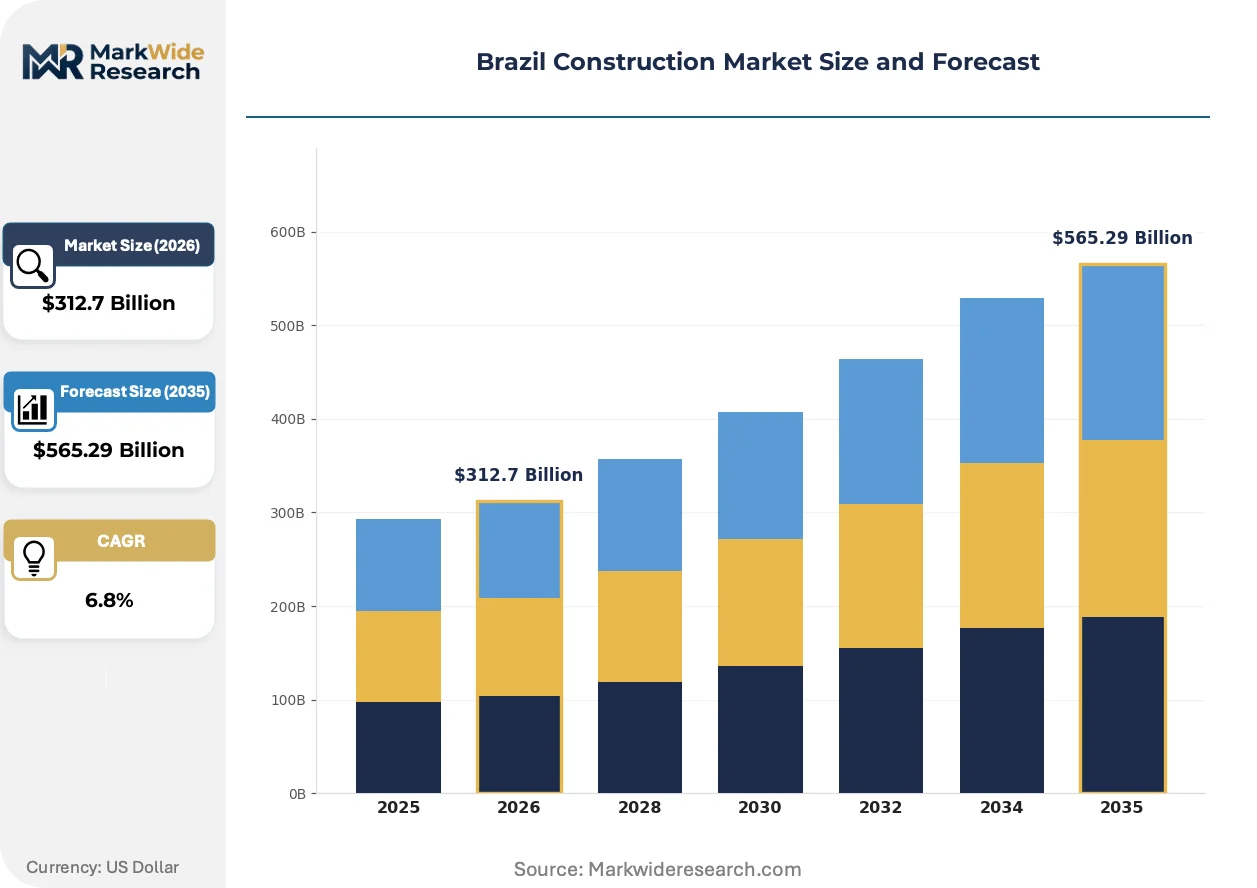
| Market Size in 2026 | $312.7 Billion |
| Market Size in 2035 | $565.29 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Construction Type: Residential, Commercial, Industrial, Infrastructure Material Type: Concrete, Steel, Wood, Glass Project Size: Small Scale, Medium Scale, Large Scale, Mega Projects Workforce Category: Skilled Labor, Unskilled Labor, Project Managers, Engineers |
| Companies Covered | Construtora Barbosa Mello, Azevedo & Travassos, Odebrecht Engineering & Construction, Prefeitura Eficiente, Mota-Engil E&C, Mills Estruturas e Servicos de Engenharia, Priner Servicos Industriais, Conecta Obra, OEC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Construction Market Emerging Trajectories
Digital fabrication and modular assembly are compressing on-site labor requirements while regulatory pressure on embodied carbon intensifies material specification debates.
Building Information Modeling (BIM) coordination platforms are migrating from high-rise commercial towers to mid-scale residential developments. São Paulo-based contractors are adopting clash-detection software at accelerated cadences. The technology is migrating from design-phase visualization tools into procurement and scheduling workflows, collapsing change-order frequencies.
ANVISA's updated healthcare facility construction guidelines mandate antimicrobial surface specifications and air-handling isolation protocols. Pharmaceutical manufacturers must retrofit existing plants or construct greenfield facilities to comply. Rio de Janeiro and Campinas biotech clusters are absorbing the bulk of compliant contractor capacity.
Institutional investors are bypassing traditional general contractors to contract directly with specialized envelope and MEP subcontractors. Pension funds and insurance capital are assembling project-specific consortia rather than delegating to balance-sheet-heavy incumbents. This pattern concentrates in Minas Gerais industrial park developments where single-asset exposure tolerances favor unbundled risk allocation.
Brazil Construction Market Segmentation
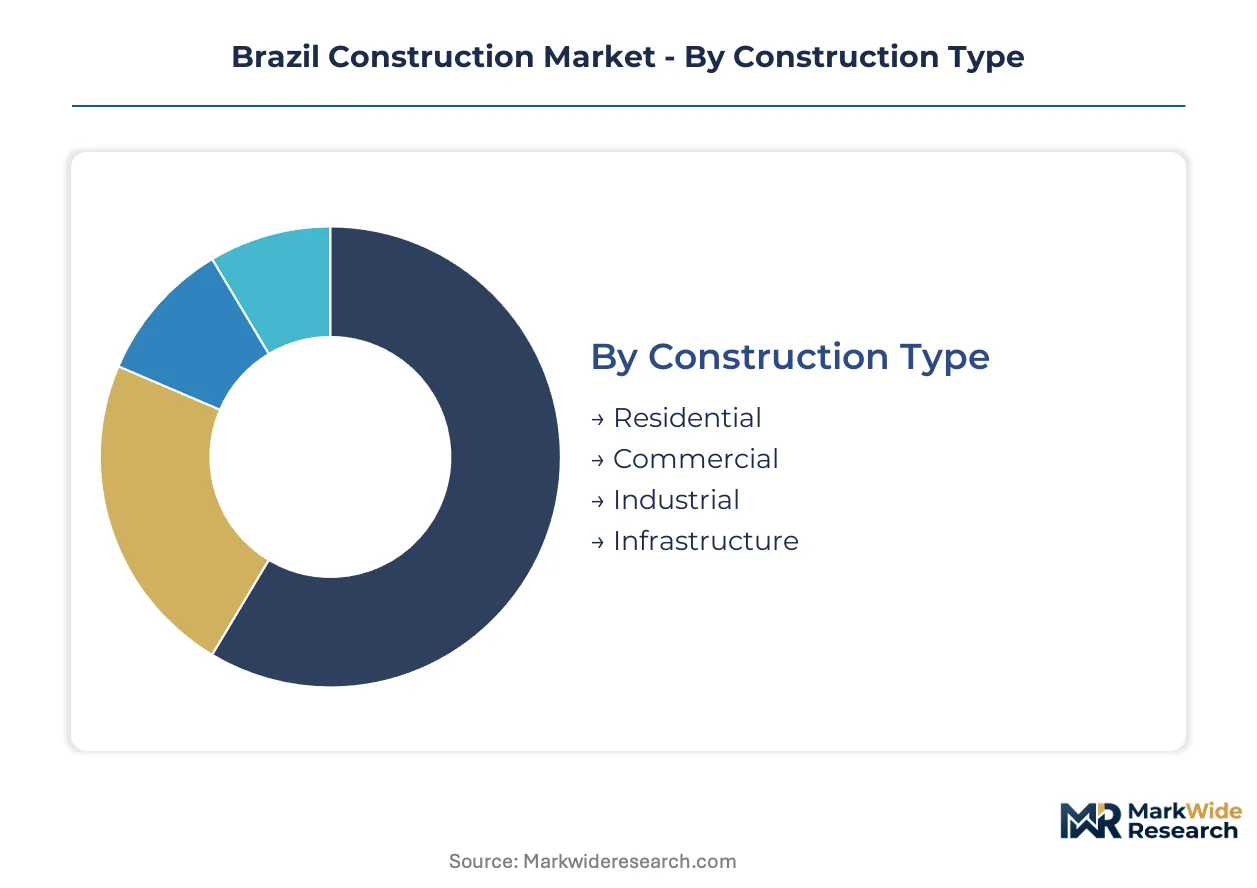
Construction type and material specifications determine capital intensity, regulatory exposure, and contractor specialization across Brazil's built environment. Cycle-time differentials between residential turnover and infrastructure concessions reshape portfolio strategy for developers and equipment lessors alike.
Construction Type:
Residential projects turn inventory fastest while infrastructure locks capital for decades under concession frameworks.
- Residential:Vertical towers and horizontal subdivisions absorb mortgage credit expansion through Caixa Econômica Federal. São Paulo's transit-oriented corridors concentrate demand as first-time buyers formalize ownership in TOD zones.
- Infrastructure:Highway, rail, and water concessions carry the longest project cycles and deepest capital stacks. PAC program allocations through the Ministry of Cities direct federal resources toward housing-adjacent transit expansion.
- Commercial:Office and retail developments track corporate expansion cycles in São Paulo and Rio de Janeiro central business districts.
- Industrial:Manufacturing plants and logistics warehouses cluster in Minas Gerais industrial corridors with established contractor ecosystems.
Residential dominates installed base. Infrastructure is where expansion concentrates.
Material Type:
Cost tiers separate commodity bulk materials from specification-grade inputs demanding certification.
- Concrete:Structural grades of 20-50 MPa compressive strength anchor high-rise frames across São Paulo state. Domestic clinker production constraints expose contractors to fuel-linked price volatility in bulk supply.
- Steel:Flat-rolled structural sections concentrate in a narrow import-dependent supplier base, amplifying currency-driven cost shock exposure.
- Wood:Engineered timber and structural framing serve lower-rise residential and commercial fit-outs in sustainability-focused developments.
- Glass:Curtain wall and fenestration systems specify thermal performance grades for commercial towers in subtropical climate zones.
Concrete commands volume leadership. Steel is climbing the fastest on specification intensity.
Project Size:
Scale thresholds determine financing access, regulatory scrutiny depth, and risk transfer completeness.
- Mega Projects:Concession-based infrastructure exceeding billion-real capital stacks concentrate margin pools where ANTT and ANA regulatory oversight is most intensive.
- Large Scale:Major commercial and industrial developments require multi-source project finance through infrastructure debentures.
- Medium Scale:Mid-tier residential and commercial projects attract fragmented capital access as pension funds bypass balance-sheet-heavy incumbents.
- Small Scale:Single-asset residential renovations and retail fit-outs operate on compressed timelines with minimal regulatory layering.
Mega Projects anchor concession pipelines. Medium Scale is gaining share fastest on capital democratization.
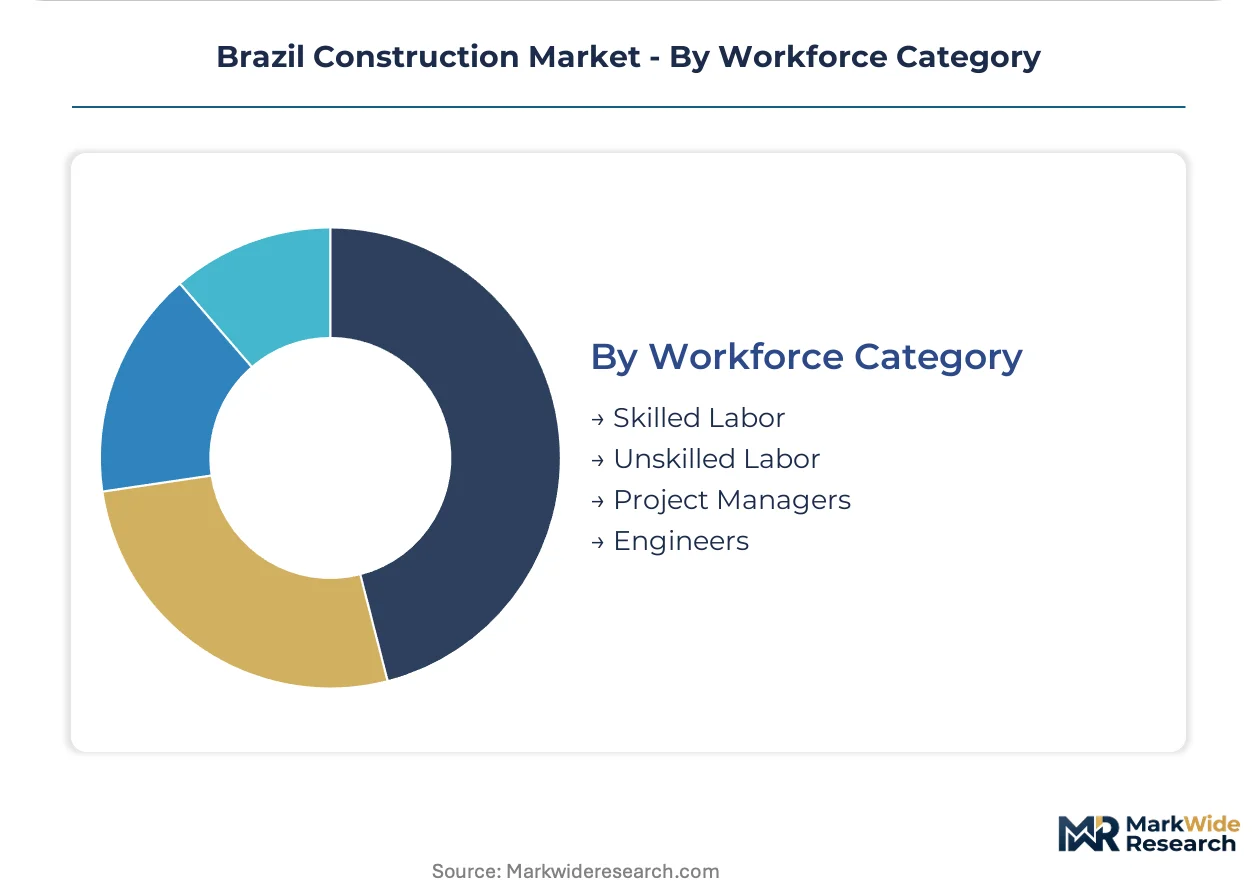
Workforce Category:
Skill scarcity compresses productivity most acutely in trades requiring generational knowledge transfer.
- Skilled Labor:Formwork carpentry and rebar placement trades face replacement gaps that constrain site productivity across Southeast state developments.
- Engineers:Structural and sanitary engineers command premium placement in ANVISA-certified healthcare facility construction.
- Project Managers:Concession-phase oversight specialists manage risk transfer complexity in sanitation and transport public-private partnerships.
- Unskilled Labor:General site support roles absorb workforce entry but face automation pressure from modular assembly adoption.
Skilled Labor dominates productivity constraints. Engineers are where talent competition concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
First-time buyers concentrate in São Paulo's transit-oriented corridors, while institutional capital seeks concession exposure in sanitation and transport infrastructure across Brazil's five dominant state economies.
São Paulo
Vertical towers and horizontal subdivisions absorb mortgage credit expansion through Caixa Econômica Federal. PAC program allocations direct federal resources toward housing-adjacent transit expansion. The São Paulo metropolitan corridor concentrates demand as TOD zones formalize ownership for emerging middle-class households.
Minas Gerais
Industrial park developments cluster manufacturing plants and logistics warehouses with established contractor ecosystems. ANVISA sanitary certification requirements elevate technical specifications for pharmaceutical facility construction. The Belo Horizonte industrial corridor anchors biotech cluster expansion compliant with updated healthcare guidelines.
Rio de Janeiro
Commercial office and retail developments track corporate expansion cycles in central business districts. IBAMA environmental licensing delays reshape timelines for biome-adjacent developments. The Rio-Campinas biotech corridor absorbs compliant contractor capacity for antimicrobial surface retrofit mandates.
Rio Grande do Sul
Equipment rental specialization and temporary structures occupy niches shielding service providers from direct construction completion risk. ABNT technical norms govern material specifications and structural safety coefficients. Porto Alegre metro developments concentrate mid-tier residential projects attracting fragmented capital access.
Bahia
Underserved urban populations in Salvador and surrounding corridors present greenfield development potential outside saturated Southeast markets. The new federal sanitation legal framework reconfigures concession structuring for water and sewage infrastructure. Northeast housing deficits attract pension fund capital assembling project-specific consortia.
Brazil Construction Market Vendor Landscape
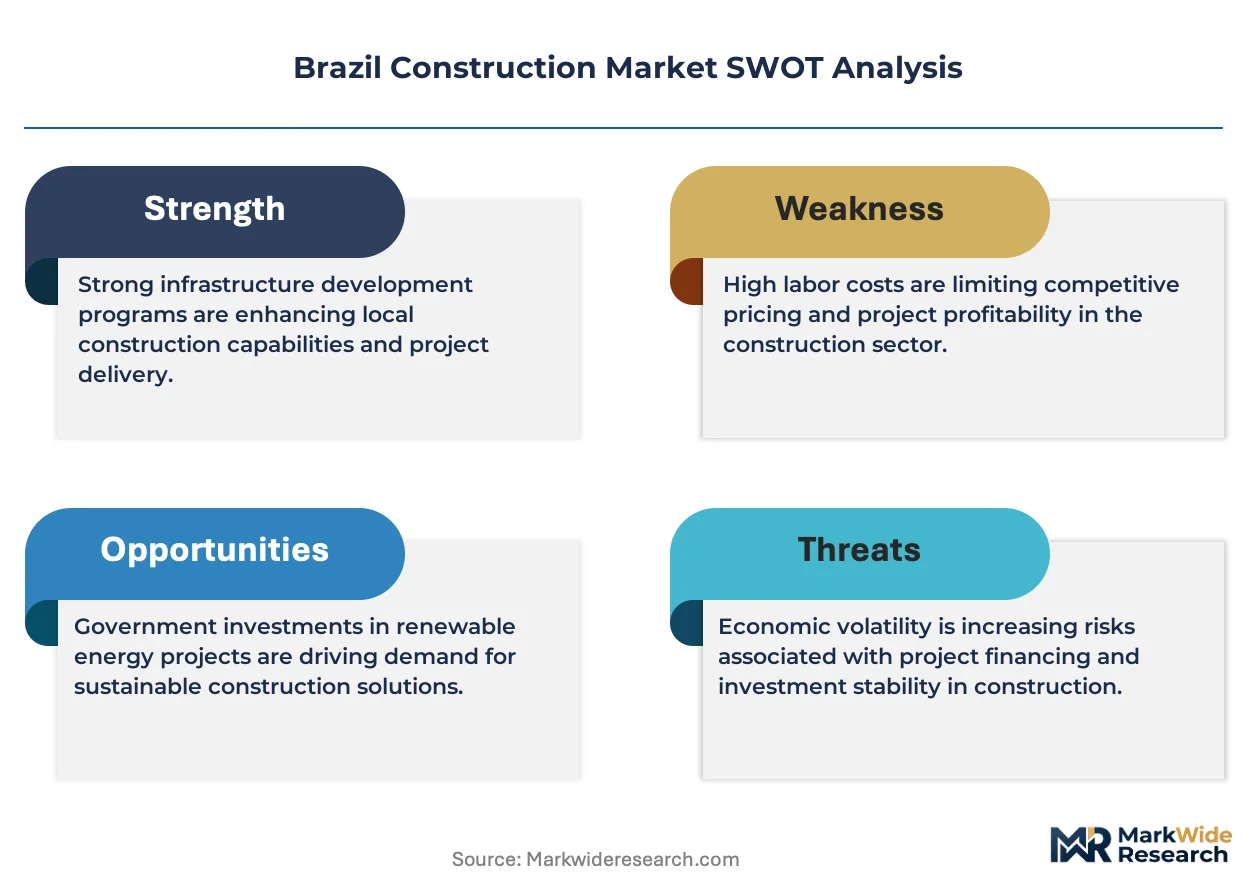
Channel-controlling players compete with product-specialist players across Brazil's construction sector, producing a tiered structure where balance-sheet-heavy incumbents face displacement from mid-tier firms accessing fragmented capital. The vendor base separates into three strategic archetypes: vertically integrated engineering-construction hybrids, transport infrastructure specialists leveraging cross-border experience, and equipment rental operators shielded from completion risk. Dominant competitive moves include backward integration into engineering services and direct institutional contracting that bypasses traditional general contractor hierarchies.
Among Brazil-based integrated constructors, Odebrecht Engineering & Construction and Mota-Engil E&C occupy positions representing distinct strategic vectors. Odebrecht anchors the engineering-construction hybrid archetype through deep backward integration into technical services. Mota-Engil exemplifies transport infrastructure specialization, leveraging Portuguese-African project experience to differentiate bidding positioning. Mills Estruturas e Servicos de Engenharia represents the equipment rental specialization archetype, occupying a niche that insulates service providers from direct exposure to construction completion risk.
| Leading Market Players |
|---|
| Construtora Barbosa Mello |
| Azevedo & Travassos |
| Odebrecht Engineering & Construction |
| Prefeitura Eficiente |
| Mota-Engil E&C |
| Mills Estruturas e Servicos de Engenharia |
| Priner Servicos Industriais |
| Conecta Obra |
| OEC |
| Others |
Supply Flow & Price Mechanics
The Santos-Guarulhos freight corridor's fuel-indexed haulage costs cascade through São Paulo state's cement distribution network, amplifying price spreads between clinker-integrated producers and import-dependent blenders while squeezing margins on specification-grade concrete deliveries to ANVISA-certified healthcare projects.
Pricing Analysis
Cost-plus contracts with fuel-indexed escalation clauses dominate mega-project concessions, transferring bunker and diesel volatility to public-sector counterparties. Price differentiation separates ANVISA-certified healthcare contractors from standard residential builders on technical compliance costs. Pricing pressure stems from currency-driven steel import exposure compressing structural fabrication margins. First-time buyers through Caixa Econômica Federal mortgage programs exhibit highest price sensitivity, while pharmaceutical facility developers absorb premium tiers for antimicrobial specification compliance.
Supply Chain Analysis
Supplier-financing facilities extended by domestic clinker producers lock mid-tier contractors into 90-120 day payment cycles, concentrating working capital risk. Geographic supply concentration draws structural steel from China, Argentina, and domestic Minas Gerais mills. Raw material dependencies center on imported flat-rolled sections, fuel-linked clinker, and specification-grade admixtures. Single-source vulnerability runs through narrow flat-rolled import channels exposed to exchange rate shocks. Distribution runs through contractor-controlled batching plants serving radii under 50 kilometers from urban demand cores.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Equipment rental and temporary structure services represent the fastest-expanding recurring-revenue layer, outpacing hardware margins as contractors outsource completion risk to specialized lessors like Mills Estruturas.
For Market Incumbents: Build engineering-service moats through backward integration into ANVISA certification consulting and BIM coordination platforms. Odebrecht's captive engineering capabilities demonstrate how technical service control defends margin pools against mid-tier debenture-financed competitors. Cement producers should deepen captive clinker supply to offset import-parity pricing volatility. For New Entrants and Emerging Players: Pursue sanitation concession specialization under Brazil's new federal legal framework, where risk transfer mechanisms favor operators with project finance structuring experience. The Northeast housing deficit in Bahia and Pernambuco presents the most penetrable geography outside São Paulo's saturated contractor ecosystem. Lead with equipment-light modular assembly to bypass skilled labor scarcity constraints. For Investors and Strategic Acquirers: Specialized envelope and MEP subcontractors with ANVISA healthcare credentials command scarcity premia as pension funds assemble direct-contracting consortia. Long-term viability hinges on exposure to recurring-revenue service layers rather than lump-sum construction completion. Monitor IBAMA licensing velocity in Amazon-adjacent regions as an inflection indicator for infrastructure pipeline timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Engineering Services | Odebrecht's captive technical capabilities anchor premium positioning in ANVISA-certified healthcare construction. |
| Equipment Rental Specialization | Mills Estruturas shields revenue from completion risk through temporary structure and machinery leasing. |
| Sanitation Concession Structuring | New federal legal framework reconfigures risk transfer to private operators in water and sewage infrastructure. |
| BIM Coordination Platform Adoption | São Paulo contractors deploy clash-detection software to collapse change-order frequencies in mid-scale residential. |
| Cross-Border Transport Infrastructure Bidding | Mota-Engil leverages Portuguese-African project experience to differentiate positioning in PAC program allocations. |
Methodological Framework
Desk research of ABNT technical norm repositories, ANVISA regulatory filings, and Ministry of Cities PAC program disbursement records preceded structured interviews with project finance directors at infrastructure debenture issuers, procurement leads at Caixa Econômica Federal, and equipment rental operations managers. Secondary validation drew from cement industry association production statistics, steel import customs data, and IBAMA environmental licensing timelines. Bottom-up project pipeline aggregation triangulated against top-down construction value-add estimates from federal accounts.
Assumptions held PAC program allocation continuity and ANVISA certification timeline stability fixed, while varying mortgage credit expansion velocity and clinker import parity scenarios across the analysis window. Segmentation modeling incorporated construction type, material specification grade, project scale tier, and workforce skill category dimensions. CAGRs derived from structural concrete volume absorption patterns in São Paulo transit-oriented corridors and equipment rental fleet utilization rates. Forecast inputs included Caixa Econômica Federal mortgage origination trajectories and IBAMA licensing velocity indices.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese steel traders or modular assembly technology providers would shift outcomes. Macroeconomic deviation in exchange rate stability, regulatory acceleration in Amazon biome licensing, or technological disruption in digital fabrication would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Construction
India Pre-Engineered Buildings Market
Building Construction
Sweden New Construction Market
Building Construction
GCC Advanced Buildings Materials Market
Building Construction
United States Commercial Construction Market
Building Construction
GCC Prefabricated Housing Market
Building Construction
GCC Green Buildings Market
Building Construction
Cold Storage Construction Market
Building Construction
India Construction Market
Building Construction
UAE Facade Market
Building Construction
Malaysia Construction Market
Building Construction
Bangladesh Construction Market
Building Construction
El Salvador Construction Market
Building Construction
GCC Construction Market
Building Construction
Modular and Prefabricated Construction Market
Building Construction
Global Dry Construction Market
Building Construction
Saudi Arabia Infrastructure Sector Market