
 Pavement Tester Market | 2026-2036
Pavement Tester Market Size, Share, and Industry Trends Forecast 2026-2036
Pavement Tester Market Outlook
Project finance and equipment leasing models are tilting competitive dynamics toward asset-light operators that avoid heavy capital deployment. Controls Group leverages its vertical integration across mechanical and electronic testing platforms to sustain pricing power in European infrastructure tenders. PaveTesting Ltd. anchors its position through specialized shear testing systems for airport runway applications. Interlaken Technology Company differentiates via hydraulic technology leadership in high-load pavement simulation equipment.
Pavement testers are mechanical, electronic, hydraulic, or pneumatic instruments designed to measure load-bearing capacity, surface uniformity, and structural integrity of paved surfaces, typically applying forces from 10 kN to 300 kN to simulate traffic stress and assess rutting, fatigue, or skid resistance. Static load testers dominate mature road construction budgets where agencies prioritize proven compliance methods, while dynamic load testers represent the fastest-expanding product category as accelerated pavement testing protocols gain regulatory traction. Surface profilers command concentrated margin pools in airport runway applications where FAA and ICAO surface regularity standards enforce precision measurement requirements.
The Federal Highway Administration mandates pavement condition reporting under MAP-21 provisions, while ASTM International maintains D4694 and D6084 standards for static and dynamic load testing protocols that shape equipment specification requirements. Germany's KBA enforces DIN standards for road surface assessment that filter market access for non-compliant instrumentation. Stakeholders must monitor evolving performance-based contracting models where government agencies transfer pavement lifecycle risk to construction firms, fundamentally altering tester procurement criteria toward predictive analytics integration.
Market Dynamics
Performance-based contracting is compressing equipment procurement cycles as highway agencies transfer pavement lifecycle risk to construction firms, fundamentally altering how testers are specified and validated.
Growth Catalysts
- MAP-21 Reporting Mandates:The Federal Highway Administration requires systematic pavement condition documentation, forcing state transportation departments to expand testing equipment fleets and standardize data collection protocols.
- Accelerated Pavement Testing Protocols:Dynamic load simulation technology is displacing static methods in rehabilitation projects across Germany and Japan, creating replacement demand for aging equipment bases.
- Airport Infrastructure Modernization:FAA and ICAO surface regularity standards for runway maintenance are concentrating procurement authority among specialized testing contractors serving aviation authorities.
Market Restraints
- Precision Sensor Cost Volatility:Load cell and accelerometer components face supply concentration among Japanese and German component suppliers, exposing equipment manufacturers to input price shocks.
- DIN Standard Compliance Barriers:Germany's KBA enforces stringent road surface assessment protocols that filter market access for non-compliant instrumentation, raising R&D costs for foreign entrants.
- Portable Handheld Substitution:Smartphone-mounted profilometer applications are capturing low-accuracy spot-check applications, compressing addressable volume for entry-grade stationary equipment.
Strategic Opportunities
- Indian Highway Expansion:The country's national highway development program under its transport ministry is creating first-time equipment demand among regional construction consortia unfamiliar with automated testing protocols.
- Predictive Analytics Integration:Machine learning algorithms processing tester output data are enabling equipment vendors to offer subscription-based pavement lifecycle forecasting services.
- Equipment-as-a-Service Models:Leasing arrangements with embedded calibration and software updates are penetrating municipal procurement channels previously dominated by capital purchase budgets.
Industry Challenges
- Embedded Systems Engineering Talent Scarcity:The convergence of mechanical testing platforms with real-time data acquisition requires firmware developers experienced in industrial IoT architectures, a skill set concentrated among automotive and aerospace sectors.
- Multi-Standard Certification Complexity:ASTM D4694, DIN, and JIS protocol compliance must be maintained simultaneously for equipment serving cross-border infrastructure projects, extending validation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pavement Tester Market |
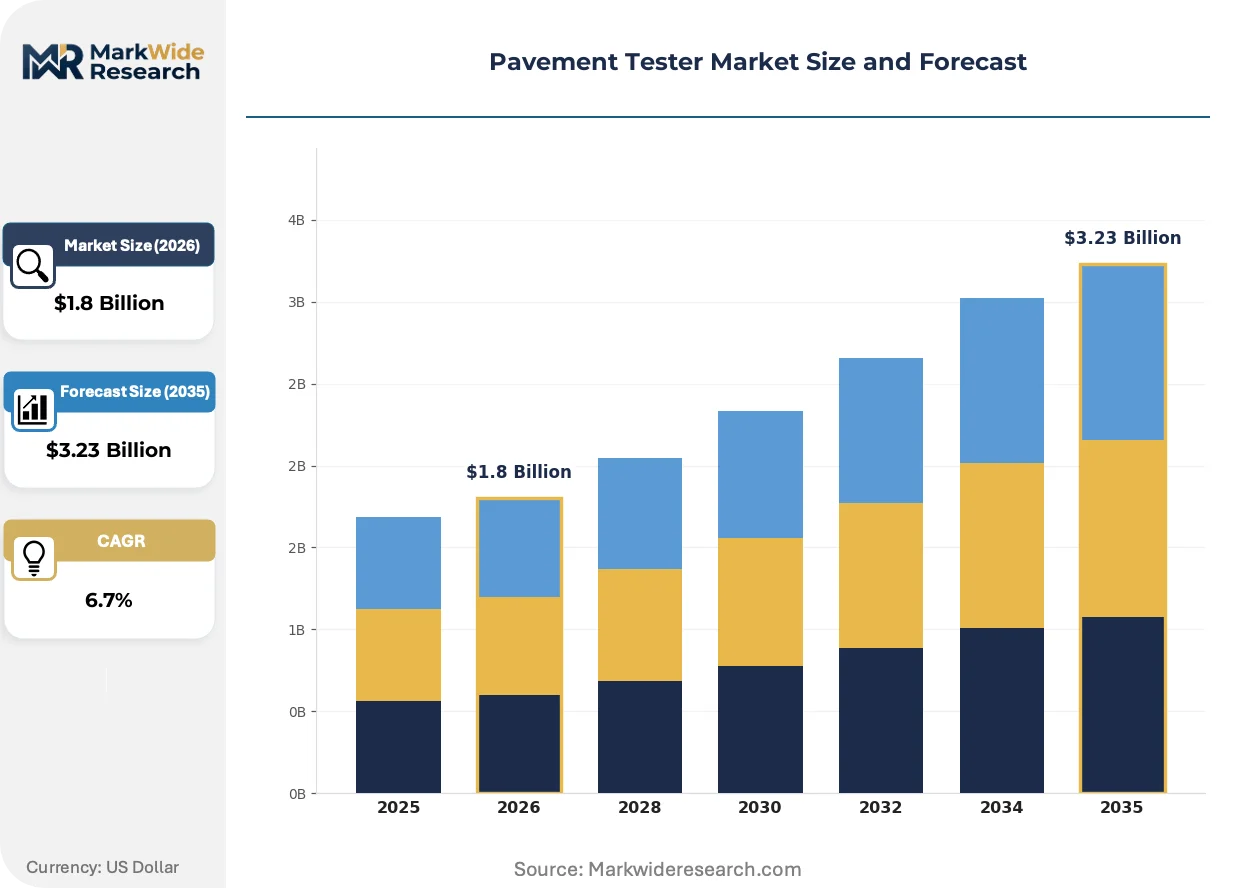
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Static Load Testers, Dynamic Load Testers, Surface Profilers, Shear Testers Application: Road Construction, Airport Runways, Parking Lots, Bridge Decks End User: Construction Companies, Civil Engineering Firms, Government Agencies, Consultants Technology: Mechanical, Electronic, Hydraulic, Pneumatic |
| Companies Covered | Controls Group, PaveTesting Ltd., Interlaken Technology Company, Cooper Research Technology Ltd., Humboldt Mfg. Co., Gilson Company, Inc., James Cox & Sons, Inc., UTEST Material Testing Equipment, Stanley Infrastructure, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pavement Tester Market Strategic Shifts
Digital instrumentation is collapsing the distinction between field testing and laboratory simulation, enabling real-time structural assessment that reshapes how pavement maintenance decisions are authorized and funded.
Wireless sensor networks embedded directly into pavement layers are digitizing continuous structural health monitoring, replacing periodic manual testing. State transportation departments in Texas and California are piloting these systems on interstate corridors with heavy freight traffic. The technology is compressing the addressable market for portable deflection measurement devices by embedding diagnostic capability into the infrastructure itself.
The European Union's CSRD disclosure requirements are mandating lifecycle carbon accounting for public infrastructure procurement, extending to testing equipment energy consumption and manufacturing footprints. Equipment vendors serving EU member state tenders must now document embodied carbon in steel frames and hydraulic systems. German and Dutch transportation authorities are incorporating these criteria into technical specifications, favoring electrically actuated testers over diesel-powered alternatives.
Rental and short-term lease arrangements are displacing traditional capital purchase models among regional construction firms facing irregular project pipelines. Equipment distributors in France and Spain are unbundling after-sales service from hardware contracts, offering calibration and software support as separate subscriptions. This restructuring is most visible in Mediterranean markets where municipal budget volatility makes multi-year capital commitments untenable for mid-sized contractors.
Pavement Tester Market Segmentation
Pavement tester procurement patterns diverge sharply across application contexts and technical specifications. Equipment specification requirements from transportation authorities create rigid segment boundaries that manufacturers must navigate through targeted certification investments.
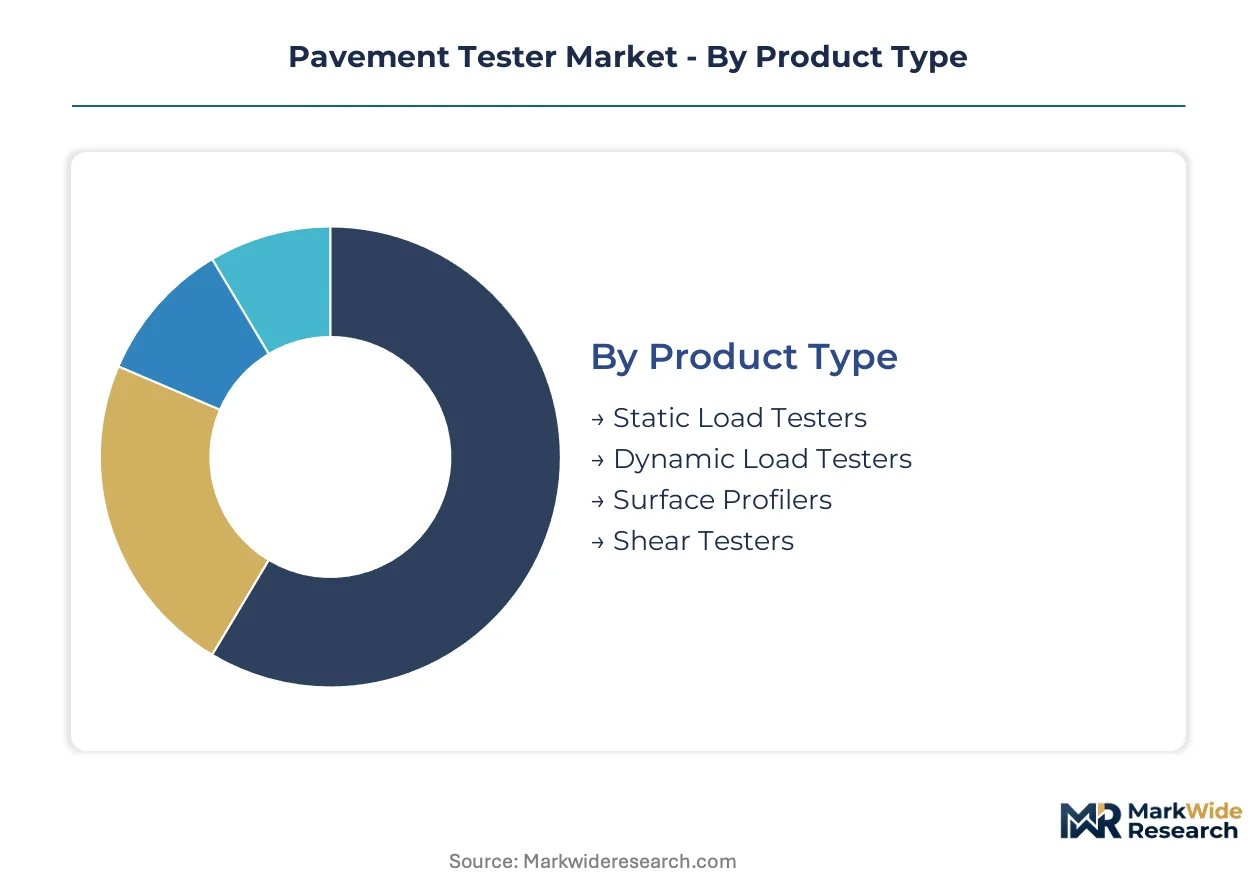
Product Type:
Cost tier differentiation separates capital-intensive dynamic simulation systems from standardized compliance equipment. Each product category serves distinct validation protocols with irreconcilable technical specifications.
- Static Load Testers:These devices apply stationary forces from 10 kN to 300 kN to measure pavement deflection under controlled loading conditions. State departments of transportation in the United States specify static testers for routine compliance verification where ASTM D4694 protocols dominate procurement specifications. Mature road construction budgets favor these proven methods despite longer test cycles.
- Dynamic Load Testers:Accelerated pavement testing equipment simulates rolling wheel loads at traffic speeds to compress years of wear into weeks of laboratory testing. Germany's KBA and Japan's highway agencies are driving replacement demand as rehabilitation projects adopt faster validation protocols. Dynamic systems command premium pricing but reduce project timeline risk for contractors.
- Surface Profilers:High-precision laser or ultrasonic devices measure longitudinal and transverse surface regularity against FAA and ICAO runway standards.
- Shear Testers:Specialized instruments evaluate horizontal stress resistance at pavement layer interfaces for airport and heavy-load applications.
Static load testers hold installed capacity. Dynamic load testers are rotating up the share rankings.
Application:
Surface regularity standards create divergent equipment performance requirements across infrastructure types. Regulatory enforcement intensity directly shapes addressable revenue per installation.
- Road Construction:Highway agencies deploy portable falling weight deflectometers and automated plate load testers for quality assurance during construction and rehabilitation. FHWA MAP-21 reporting mandates are expanding fleet sizes at state transportation departments across the United States. Equipment must demonstrate interoperability with federal pavement management databases.
- Airport Runways:FAA Part 139 and ICAO Annex 14 enforce strict surface regularity thresholds that concentrate procurement among specialized testing contractors. Surface profilers with sub-millimeter accuracy command concentrated margin pools in this application. Aviation authorities typically mandate third-party validation that limits price competition.
- Parking Lots:Municipal and commercial developers specify lighter-duty static testers for sub-base verification where traffic loads remain predictable.
- Bridge Decks:Structural engineers employ modified load testers combined with ground-penetrating radar for composite deck assessment.
Road construction anchors volume demand. Airport runways concentrate margin extraction.
End User:
Customer type determines procurement channel structure and service attachment rates. Government buyers follow rigid capital budget cycles while private firms prioritize equipment mobility.
- Construction Companies:Regional contractors facing irregular project pipelines are shifting toward rental and lease arrangements with embedded calibration services. Equipment distributors in France and Spain report unbundling trends where software support becomes a separate subscription. This customer segment prioritizes portable units compatible with multiple national standards.
- Civil Engineering Firms:Specialized infrastructure consultancies invest in high-accuracy dynamic testers to differentiate bidding positions on performance-based highway contracts. These firms absorb lifecycle risk from transportation agencies and require predictive analytics integration. Talent scarcity in embedded systems engineering constrains their in-house equipment modification capabilities.
- Government Agencies:State and federal transportation departments maintain centralized testing fleets with multi-decade replacement horizons.
- Consultants:Independent verification specialists purchase mid-range static testers for spot-check compliance services.
Civil engineering firms are expanding equipment fleets fastest. Government agencies maintain the largest installed base.
Technology:
Actuation mechanism selection involves trade-offs between precision, maintenance burden, and energy consumption. European procurement criteria are increasingly weighting embodied carbon in technology choices.
- Mechanical:Screw-jack and lever-based systems dominate entry-grade static testers where proven reliability outweighs speed considerations. These systems require minimal calibration and tolerate harsh field conditions. Mature road construction markets with constrained technical staffing favor mechanical simplicity.
- Electronic:Servo-motor actuation enables precise load control and automated data acquisition for laboratory-grade repeatability. Electronic systems integrate seamlessly with wireless sensor networks and real-time monitoring platforms. Texas and California transportation departments are piloting embedded electronic testers on interstate corridors.
- Hydraulic:High-force applications above 200 kN rely on hydraulic actuation for dynamic load simulation equipment.
- Pneumatic:Compressed air systems serve specialized shear testing configurations where rapid cycling is required.
Hydraulic systems anchor heavy-load simulation capacity. Electronic actuation is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pavement tester trade flows reveal equipment manufacturing concentration in Germany and Japan against import dependency in infrastructure expansion markets. The United States maintains near-autarky in highway testing equipment through domestic fabrication serving FHWA-mandated fleet expansion. Export volumes from European precision engineering clusters supply Middle Eastern and South Asian markets where standardization drives procurement.
United States
State transportation departments in Texas and California are expanding dynamic load tester procurement under MAP-21 pavement condition reporting mandates. The Federal Highway Administration requires interoperability with federal pavement management databases, filtering equipment specifications toward ASTM D4694 compliant systems. Midwest manufacturing clusters around Illinois and Ohio produce falling weight deflectometers for domestic highway rehabilitation programs.
Germany
KBA enforcement of DIN road surface assessment standards creates captive demand for domestically certified instrumentation. Bavaria-based engineering firms supply hydraulic dynamic load simulation equipment to Autobahn rehabilitation contractors adopting accelerated testing protocols. The country's precision sensor supply chain concentrates around Stuttgart and Munich industrial corridors serving European infrastructure tenders.
Japan
Highway agencies in Kanto and Kansai regions are replacing aging static tester fleets with dynamic simulation systems for urban expressway maintenance. METI-sponsored infrastructure resilience programs fund equipment procurement for earthquake-damaged road network assessment. Nagoya-area manufacturers dominate regional supply for JIS-compliant testing instrumentation.
India
The National Highways Authority of India is creating first-time equipment demand among regional construction consortia under the Bharatmala development program. Central government transport ministry guidelines are standardizing automated testing protocols previously absent in state-level procurement. Equipment distributors in Maharashtra and Gujarat are establishing calibration service networks for imported European and Japanese systems.
United Arab Emirates
Dubai and Abu Dhabi transportation authorities specify surface profilers with sub-millimeter accuracy for runway maintenance under ICAO Annex 14 compliance frameworks. Federal infrastructure investment programs are consolidating testing equipment procurement among specialized aviation contractors. Sharjah-based equipment leasing firms are penetrating municipal channels with embedded calibration service contracts.
Pavement Tester Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream supplying precision sensors and hydraulic actuation modules. The vendor base organizes around three structural tiers: diversified industrial conglomerates with testing divisions, dedicated pavement instrumentation specialists, and regional fabrication houses serving single-country certification requirements. Strategic differentiation centers on multi-standard certification capabilities and predictive analytics software integration. Consolidation pressure is mounting as performance-based contracting transfers lifecycle risk to equipment operators with balance sheet capacity.
Among European platform specialists, Controls Group exemplifies vertical integration across mechanical and electronic testing platforms. PaveTesting Ltd. occupies a position within the airport runway specialization tier, while Interlaken Technology Company anchors the hydraulic high-load simulation segment. These three entities represent distinct competitive archetypes: diversified systems integration, application-specific engineering, and force-generation technology leadership. Their positioning reflects how procurement authority concentrates among transportation agencies with stringent technical specifications and validation requirements.
| Leading Market Players |
|---|
| Controls Group |
| PaveTesting Ltd. |
| Interlaken Technology Company |
| Cooper Research Technology Ltd. |
| Humboldt Mfg. Co. |
| Gilson Company, Inc. |
| James Cox & Sons, Inc. |
| UTEST Material Testing Equipment |
| Stanley Infrastructure |
| Others |
Value Chain & Pricing Dynamics
Stuttgart's precision sensor manufacturing cluster anchors global supply for load cell and accelerometer components, concentrating pricing power among Japanese and German component suppliers who expose equipment manufacturers to input price volatility. This geographic concentration upstream filters through to downstream tester pricing, where ASTM D4694 compliance certification and DIN standard validation create tiered margin structures.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with dynamic load simulation systems commanding premium positioning against static compliance equipment. Price differentiation hinges on certification tier (FAA Part 139 validation versus state DOT compliance) and embedded service bundling (calibration subscriptions versus bare hardware). Cost compression in the entry-grade static tester segment is intensifying because smartphone-mounted profilometer applications capture low-accuracy spot-check demand. Municipal procurement officers exhibit highest price sensitivity, while aviation authorities mandated to ICAO Annex 14 standards demonstrate lowest sensitivity due to third-party validation requirements.
Supply Chain Analysis
Export-control restrictions on precision sensor technology limit component flows from Japanese and German suppliers to equipment fabricators in India and the United Arab Emirates. Manufacturing capacity concentrates in Germany, Japan, and the United States, with raw material dependencies spanning high-grade steel for load frames, hydraulic fluid formulations, and semiconductor components for data acquisition modules. Single-source vulnerability in precision load cell supply creates structural risk for mid-tier equipment assemblers lacking backward integration. Distribution runs through specialized industrial distributors in France and Spain who unbundle hardware from calibration service subscriptions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory entrenchment story, where multi-standard certification complexity creates switching costs that cement incumbent positions. ASTM D4694, DIN, and JIS protocol compliance requirements simultaneously extend validation timelines and deepen customer captivity.
For Market Incumbents: Build certification moats by accelerating multi-standard validation investments ahead of performance-based contracting proliferation. Prioritize predictive analytics software integration to capture subscription revenue from civil engineering firms absorbing lifecycle risk. Defend against portable handheld substitution by embedding wireless sensor network compatibility into electronic actuation platforms. Capacity addition in Maharashtra and Gujarat calibration service networks secures Indian highway expansion participation. For New Entrants and Emerging Players: Pursue white-space opportunity in Indian regional construction consortia unfamiliar with automated testing protocols, where first-mover education advantage exists. Target equipment-as-a-service models with embedded calibration subscriptions penetrating municipal procurement channels in Mediterranean markets. Aviation surface profilers present the most penetrable segment for specialized engineering entrants willing to absorb FAA and ICAO third-party validation costs. Go-to-market execution should leverage Sharjah-based leasing firm partnerships for channel access. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors platform integrators with vertical control across mechanical and electronic testing platforms over pure-play component suppliers. Long-term viability rests on predictive analytics integration capabilities and balance sheet capacity to absorb performance-based contract lifecycle risk. Acquisition target archetype: mid-cap specialists with DIN certification entrenchment and embedded systems engineering talent. Signal to watch: adoption velocity of wireless sensor networks by state transportation departments in Texas and California as inflection indicator for portable device displacement.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Analytics Integration | Enables subscription-based pavement lifecycle forecasting services for engineering firms. |
| Multi-Standard Certification Investment | Captures cross-border infrastructure project procurement under ASTM, DIN, and JIS protocols. |
| Equipment-as-a-Service Model Launch | Penetrates municipal channels with calibration-embedded leases in budget-volatile markets. |
| Wireless Sensor Network Compatibility | Aligns with Texas and California DOT pilot programs on interstate corridors. |
| Calibration Service Network Expansion | Supports imported European and Japanese systems in Maharashtra and Gujarat markets. |
Study Parameters
Cross-validation between primary interviews with state transportation department procurement officers, civil engineering firm equipment managers, and airport authority maintenance directors anchors the qualitative findings. Secondary validation draws from FHWA pavement management database disclosures, ASTM International standards documentation, KBA DIN enforcement protocols, and customs trade data for testing equipment imports. Bottom-up triangulation across equipment shipment records and top-down reconciliation against infrastructure budget allocations calibrate market sizing.
Calibration against historical replacement cycles for static and dynamic load tester fleets informs the analytical framework across the projection horizon. Segmentation dimensions modeled include product type (static, dynamic, surface profiler, shear tester), application context (road construction, airport runway, parking lot, bridge deck), end-user archetype (construction company, civil engineering firm, government agency, consultant), and actuation technology (mechanical, electronic, hydraulic, pneumatic). CAGRs derive from infrastructure budget growth trajectories and equipment replacement elasticity observed in German Autobahn and Japanese urban expressway rehabilitation programs.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by diversified industrial conglomerates would shift outcomes. Material shifts in FHWA performance-based contracting adoption velocity or EU CSRD embodied carbon enforcement stringency would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction and Engineering
Static Crane Market
Construction and Engineering
Auger Drill Bits Market
Construction and Engineering
Industrial Dryers Market
Construction and Engineering
Oman Construction Market
Construction and Engineering
Germany Residential Construction Market
Construction and Engineering
Spray Foam Market
Construction and Engineering
Latex Caulk Market
Construction and Engineering
GCC Kitchen Hood Market
Construction and Engineering
Digital Laser Levels Market
Construction and Engineering
Overhead Conveyor Systems Market
Construction and Engineering
Concrete Sealer Market
Construction and Engineering
Cement Consistency Meter Market
Construction and Engineering
Borehole Enlargement System Market
Construction and Engineering
Cold and Hot Tool Steel Market
Construction and Engineering
South America Repair and Rehabilitation Market
Construction and Engineering
Concrete Blocks and Bricks Market