
 Shaft Shredder Market | 2026-2036
Shaft Shredder Market Size, Share, and Industry Trends Forecast 2026-2036
Shaft Shredder Market Analytics
Waste management companies are redrawing competitive dynamics as they surpass manufacturers as the fastest-growing buyer archetype. WEIMA leverages its German engineering heritage to dominate precision shredding applications. UNTHA Shredding Technology GmbH anchors its position through Alpine-region manufacturing scale. SSI Shredding Systems competes across North American industrial waste contracts with heavy-duty platform specialization.
A shaft shredder employs one or more parallel rotors fitted with hardened cutting tools to shear, tear, and fracture materials against a counter-knife or screen, typically processing feedstock from 50 mm to over 1,500 mm in dimension. The equipment reduces bulk density and homogenizes output for downstream sorting, smelting, or pelletizing operations. Double shaft configurations lead installed base volumes due to their torque balance and contamination tolerance, while four shaft systems capture premium margin pools in hazardous waste applications where controlled particle sizing is mandatory. Electric drive technology dominates new order books as energy efficiency standards tighten, though hydraulic systems retain niche dominance in mobile construction-deployment scenarios.
EPA emissions guidelines and OSHA industrial safety standards shape equipment specifications in the United States, while REACH compliance and CE marking govern material contact surfaces and electrical assemblies across European supply chains. The EU Green Deal's packaging waste directives are accelerating retrofit demand at existing recycling centers. Stakeholders must weigh capital expenditure cycles against impending mechanical-biological treatment mandates that will redefine throughput requirements.
Market Dynamics
The shaft shredder market is undergoing a fundamental restructuring as municipal waste authorities displace industrial processors as the dominant procurement force, redirecting equipment specifications toward higher contamination tolerance and automated sorting integration.
Growth Catalysts
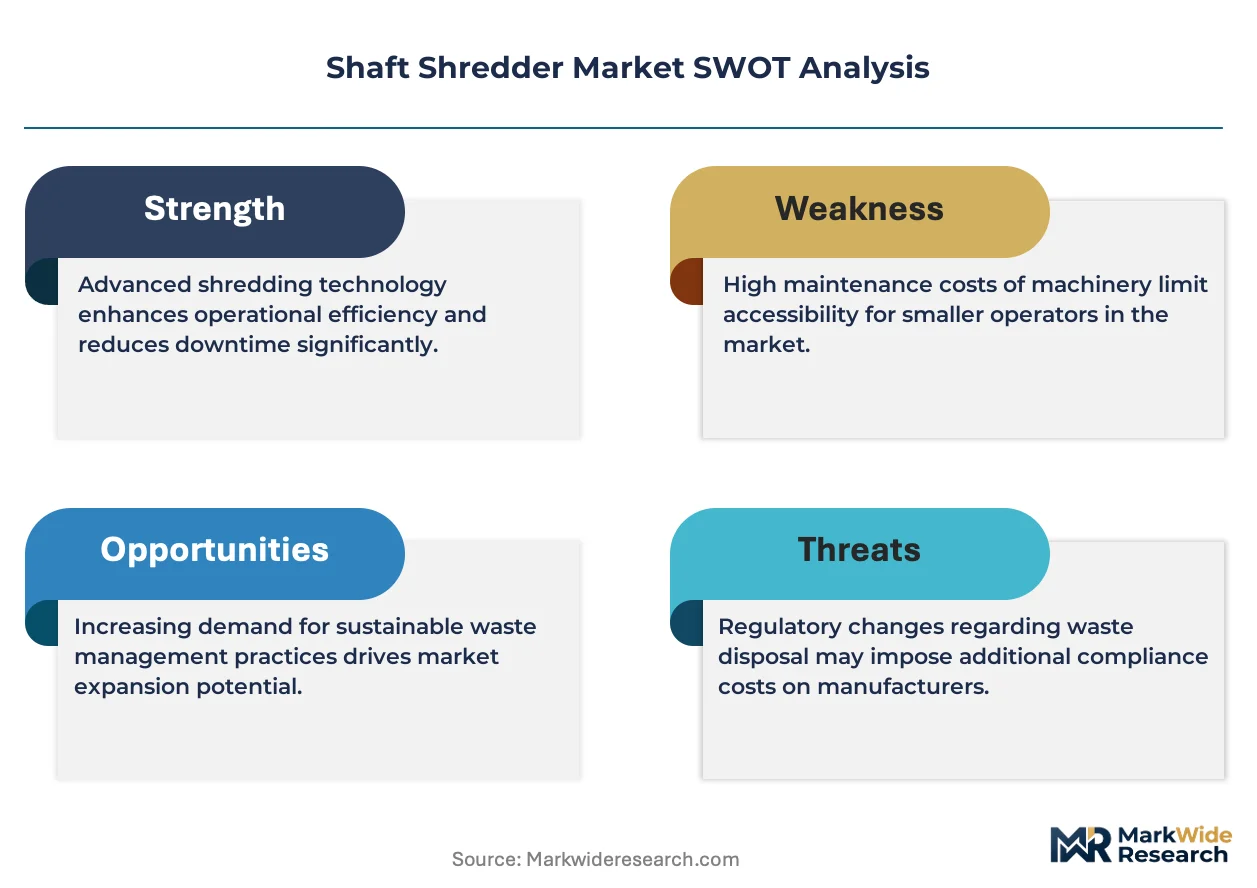
- EU Green Deal circular economy mandates:Packaging waste recovery targets are compelling recycling centers across Germany, France, and Italy to retrofit existing lines with higher-throughput shredding capacity.
- Electric drive technology maturation:Permanent magnet synchronous motors are capturing new order flows as energy efficiency regulations tighten operational cost structures for continuous-duty facilities.
- Bulky waste stream expansion:Furniture and appliance discard volumes are rising in urban cores, creating dedicated procurement channels for heavy-duty double-shaft configurations.
Market Restraints
- Hardened alloy supply concentration:Cutting tool steel production clusters in Austria and Sweden create vulnerability to raw material price volatility and extended lead times.
- Hydraulic system obsolescence risk:Mobile construction deployment scenarios retain dependency on hydraulic drives, yet tightening emissions standards threaten residual value and resale liquidity.
- REACH compliance friction:Material contact surface certification timelines for new alloy formulations extend product development cycles by 8-14 months.
Strategic Opportunities
- Mechanical-biological treatment mandates:Pre-treatment shredding requirements in German and Austrian composting facilities are opening dedicated procurement channels for fine-sizing four-shaft systems.
- Battery recycling integration:Lithium-ion preprocessing for black mass recovery is creating demand for explosion-proof shredding configurations with inert atmosphere handling.
- Service contract unbundling:Predictive maintenance telemetry is enabling OEMs to capture recurring revenue streams separate from capital equipment sales.
Industry Challenges
- Control systems integration complexity:Legacy PLC architectures in existing recycling plants resist seamless integration with modern shredder automation, extending commissioning timelines.
- Specialized technician scarcity:Rotor balancing and cutting tool geometry adjustment require skills concentrated among German and Swiss service networks, constraining geographic expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Shaft Shredder Market |
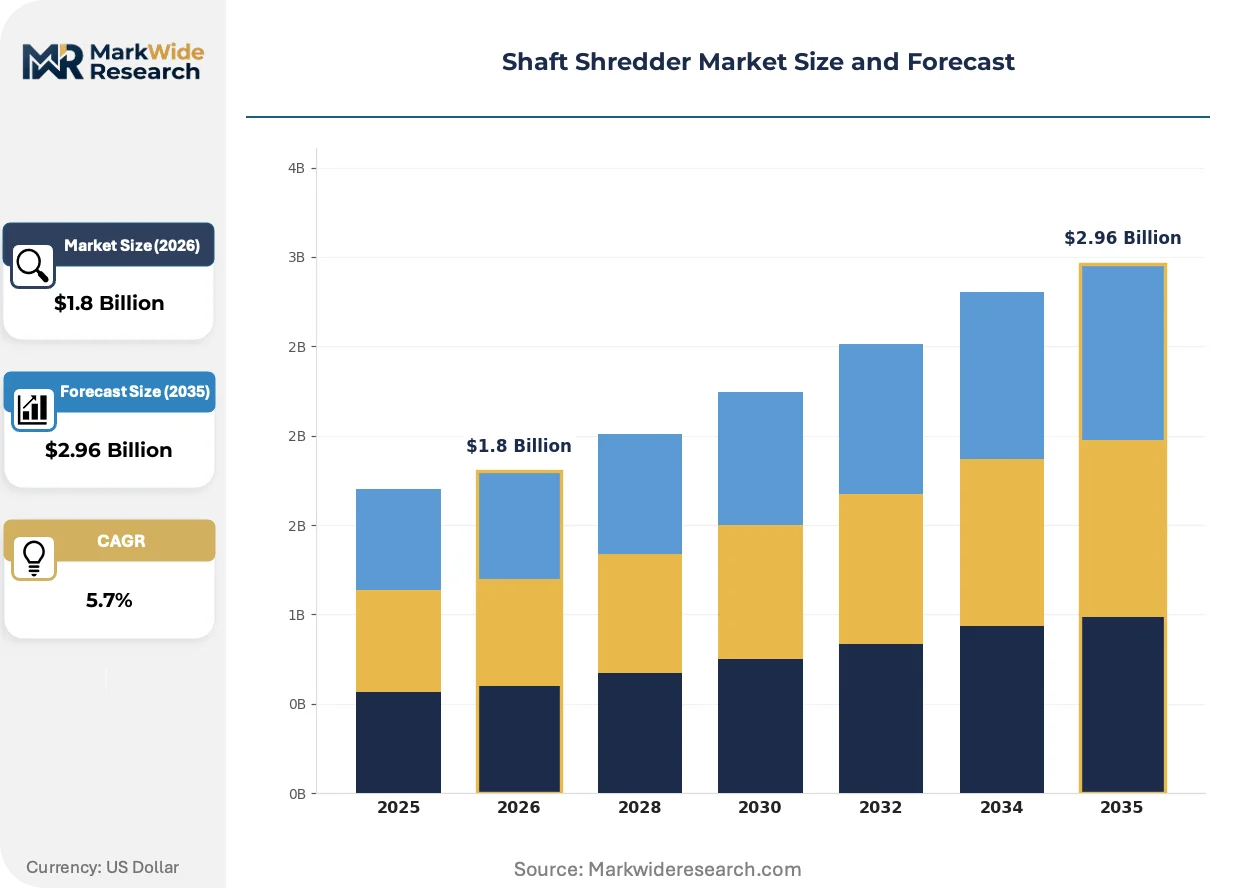
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Shaft, Double Shaft, Four Shaft, Granulators Application: Plastic Recycling, Metal Recycling, Wood Processing, E-Waste Management End User: Manufacturers, Waste Management Companies, Construction Industry, Recycling Centers Technology: Electric Drive, Hydraulic Drive, PTO Driven, Hybrid Systems |
| Companies Covered | WEIMA, UNTHA Shredding Technology GmbH, SSI Shredding Systems, Vecoplan, Lindner, LINDEMANN, Shred-Tech Corporation, Zato North America Corp., LEFORT, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Shaft Shredder Market Evolving Landscape
Equipment intelligence and energy architecture are converging to redefine competitive differentiation, with automation depth and carbon intensity becoming primary procurement screening criteria rather than throughput metrics alone.
Electric drive technology is bifurcating the installed base between grid-connected fixed facilities and stranded mobile assets. Permanent magnet motor systems now dominate new municipal contracts in Germany and the Netherlands due to operational cost advantages under EU ETS pricing. Hydraulic platforms are retreating to construction-demolition applications where grid access remains impractical, compressing margins for suppliers without electric platform development.
REACH and RoHS amendments are tightening substance restrictions on electrical assemblies and lubricants used in material contact zones. Equipment suppliers must requalify bearing seals and gearbox fluids against updated candidate substance lists, extending type-approval timelines. German engineering clusters are responding by accelerating in-house formulation development to reduce third-party dependency.
Performance-based service agreements are displacing traditional spare parts and reactive maintenance contracts among large waste management consolidators. UNTHA and WEIMA are piloting throughput-guarantee structures where payment ties to operational availability rather than equipment delivery. This model is concentrating in Benelux and Nordic markets where municipal procurement frameworks favor total-cost-of-ownership evaluation over capital expenditure minimization.
Shaft Shredder Market Segmentation
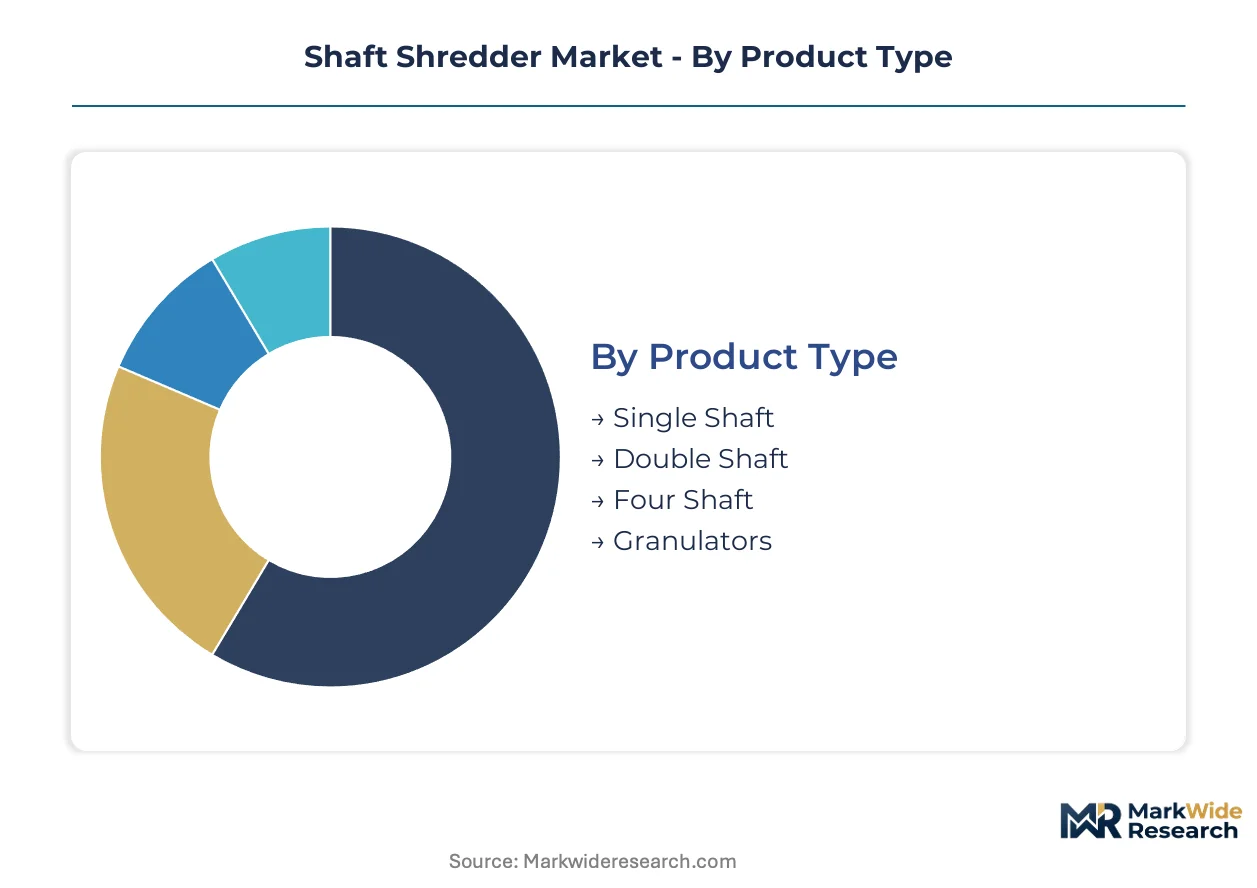
Shaft shredder procurement patterns diverge sharply across product configurations and end-use contexts, with substitution pressures from alternative size-reduction technologies reshaping investment priorities in specific segments. Understanding these fault lines enables equipment suppliers to align R&D resource allocation with defensible market positions.
Product Type:
Granulators and single-shaft systems face the most acute substitution threat from high-speed hammer mills and knife granulators in plastic preprocessing applications, forcing shredder OEMs to emphasize torque advantage and contamination tolerance as differentiation anchors.
- Double Shaft:Parallel rotors with intermeshing cutters deliver balanced torque distribution and exceptional tolerance for metallic contaminants without catastrophic damage. Municipal bulky waste contracts in Germany and the Netherlands specify these configurations for furniture and appliance processing where ferrous intrusion is routine.
- Four Shaft:Stacked rotor pairs enable controlled particle sizing through screen-based discharge, mandatory for hazardous waste streams and battery recycling preprocessing. REACH-compliant material contact surfaces extend lead times but lock in premium positioning for Austrian and German engineering clusters.
- Single Shaft:Ram-fed designs with hydraulic pusher arms optimize for homogeneous feedstocks like film and fiber. Plastic compounders in Northern Italy deploy these for in-house scrap recycling where input consistency is guaranteed.
- Granulators:High-speed rotary knife systems target post-shredder fine sizing for pelletizing feedstock. Wood processing mills in Sweden integrate these downstream of primary double-shaft reduction for boiler fuel preparation.
Double Shaft retains volume leadership; Four Shaft holds the steepest expansion curve.
Application:
Cost tier stratification separates capital-intensive preprocessing from high-volume continuous operations, with E-waste and battery streams commanding equipment premiums that plastic recycling cannot sustain.
- Metal Recycling:Heavy-duty configurations with 1,500 mm rotor widths process end-of-life vehicles and white goods for steel mill feedstock. German automotive dismantlers specify four-shaft systems for controlled aluminum fraction sizing prior to smelter delivery.
- E-Waste Management:Explosion-proof enclosures and inert atmosphere handling address lithium-ion thermal runaway risks. Black mass recovery facilities in the Benelux region drive specification tightening for shredder isolation and nitrogen purging systems.
- Plastic Recycling:Film and rigid container preprocessing demands contamination-tolerant cutting geometries. French packaging waste compliance centers retrofit existing lines with automated feed systems to handle baled post-consumer material.
- Wood Processing:Biomass fuel and particleboard feedstock applications favor high-throughput double-shaft configurations. Austrian sawmill clusters integrate these with boiler combustion systems for captive energy generation.
Metal Recycling commands the installed base; E-Waste Management climbs fastest as battery preprocessing scales.
End User:
Customer type concentration determines specification complexity, with waste management consolidators displacing industrial processors as the dominant procurement force and redirecting automation requirements.
- Waste Management Companies:Municipal contract operators demand predictive maintenance telemetry and throughput guarantees under total-cost-of-ownership frameworks. Nordic procurement authorities prioritize operational availability metrics over capital expenditure minimization.
- Recycling Centers:Dedicated material recovery facilities require flexible feedstock handling across seasonal waste stream variation. Italian consortia retrofit existing mechanical-biological treatment lines with four-shaft fine-sizing capacity.
- Manufacturers:In-house scrap recycling operations favor compact single-shaft units with minimal footprint. German automotive suppliers deploy these for sprue and purge waste recovery adjacent to injection molding cells.
- Construction Industry:Mobile deployment scenarios retain hydraulic drive dependency where grid access is impractical. Demolition contractors in Austria face residual value compression as EU ETS pricing erodes hydraulic operational economics.
Waste Management Companies anchor procurement volume; Recycling Centers gain share fastest under circular economy mandate pressure.
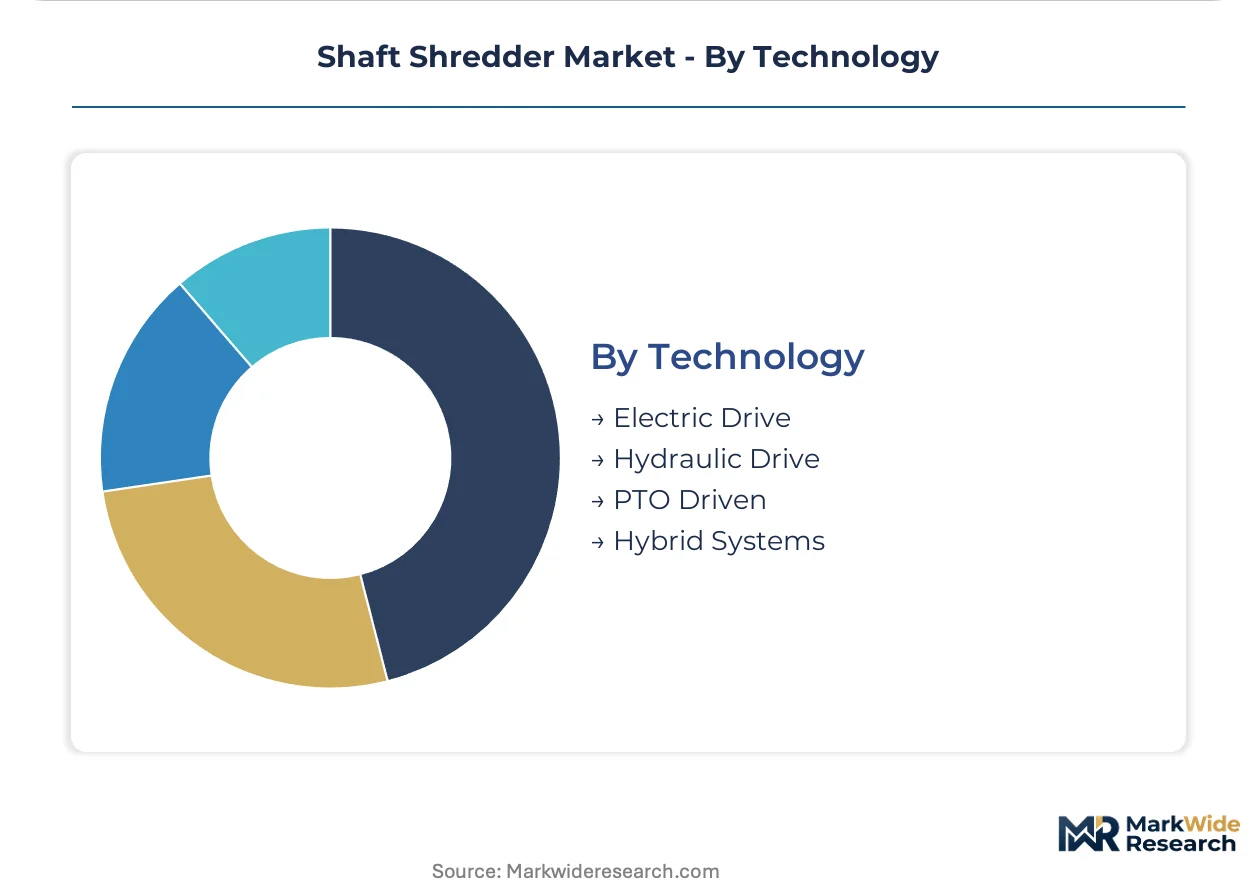
Technology:
Maturity gradients separate established electric platforms from obsolescing hydraulic architectures, with hybrid configurations attempting to bridge stranded mobile assets toward grid compatibility.
- Electric Drive:Permanent magnet synchronous motors capture municipal contracts under EU ETS carbon pricing. Dutch waste-to-energy facilities specify these for continuous-duty operation with energy recovery integration.
- Hydraulic Drive:Diesel-powered mobile units serve construction-demolition applications without electrical infrastructure. German equipment lessors face fleet write-down pressure as emissions standards tighten resale liquidity.
- Hybrid Systems:Dual-power architectures enable grid-connected base operation with diesel backup for relocation. Swiss alpine recycling cooperatives pilot these for seasonal tourist waste peaks with variable grid reliability.
- PTO Driven:Tractor-powered units serve agricultural plastic film collection in dispersed rural geographies. French cooperative networks deploy these for seasonal silage wrap recovery without dedicated power infrastructure.
Electric Drive dominates new order flows; Hybrid Systems expand most quickly as mobile operators seek compliance pathways.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German engineering clusters dominate shaft shredder supply chains, with Austrian and Swiss manufacturing networks reinforcing Central European production density. Equipment specification standards radiate from this core, shaping procurement patterns across adjacent markets. Regulatory tightening under EU Green Deal circular economy mandates is accelerating retrofit demand in municipal waste authorities.
Germany
Municipal bulky waste contracts and automotive dismantling operations drive equipment procurement volumes. The EU Green Deal's packaging waste directives compel recycling centers to upgrade shredding capacity for higher throughput. Engineering clusters in Bavaria and Baden-Württemberg manufacture precision double-shaft and four-shaft systems for hazardous waste applications.
United States
Industrial waste processors and construction-demolition contractors anchor demand for heavy-duty mobile configurations. EPA emissions guidelines and OSHA industrial safety standards dictate equipment specifications for electrical assemblies and material handling. SSI Shredding Systems competes across North American contracts with specialized platform offerings for continuous-duty operations.
France
Packaging waste compliance centers retrofit existing mechanical-biological treatment lines with automated feed systems. REACH substance restrictions on lubricants and bearing seals extend type-approval timelines for new equipment introductions. Recycling consortia in Île-de-France and Auvergne-Rhône-Alpes deploy four-shaft fine-sizing capacity for composting facility pre-treatment.
Netherlands
Waste-to-energy facilities specify permanent magnet synchronous motors under EU ETS carbon pricing frameworks. Municipal procurement authorities prioritize total-cost-of-ownership metrics over capital expenditure minimization in contract awards. Dutch engineering integrators pilot throughput-guarantee service structures linking payment to operational availability.
Austria
Alpine-region manufacturing scale supports cutting tool steel production clusters vulnerable to raw material price volatility. Sawmill and biomass fuel operations integrate double-shaft configurations with boiler combustion systems for captive energy generation. REACH-compliant material contact surface certification extends lead times but locks in premium positioning for specialized engineering networks.
Shaft Shredder Market Competitive Landscape
Concentration sits with German-Austrian engineering specialists who command premium positioning through precision manufacturing heritage and regulatory compliance depth. The vendor base stratifies across three tiers: integrated conglomerates with diversified environmental technology portfolios, mid-scale specialists focused on shredding platform refinement, and regional fabricators serving price-sensitive mobile deployment markets. Competitive dynamics revolve around electric drive platform development and predictive maintenance telemetry integration. Strategic moves center on performance-based service contract unbundling and backward integration into cutting tool alloy formulation.
Among German engineering specialists, WEIMA and UNTHA Shredding Technology GmbH occupy positions exemplifying precision-application dominance and Alpine-region manufacturing scale respectively. SSI Shredding Systems anchors the North American competitive vector with heavy-duty platform specialization. These three entities represent the archetype spectrum from heritage engineering depth to regional market anchoring, with each sitting within distinct procurement channel preferences shaped by automation requirements and contamination tolerance specifications.
| Leading Market Players |
|---|
| WEIMA |
| UNTHA Shredding Technology GmbH |
| SSI Shredding Systems |
| Vecoplan |
| Lindner |
| LINDEMANN |
| Shred-Tech Corporation |
| Zato North America Corp. |
| LEFORT |
| Others |
Value Network & Pricing Analysis
Fourteen-month lead times for REACH-compliant alloy certification concentrate pricing power with Austrian and German engineering clusters while compressing margins for downstream fabricators lacking in-house formulation capabilities. This supply-side bottleneck reinforces tiered pricing separation between premium four-shaft hazardous waste systems and standard double-shaft municipal configurations.
Pricing Analysis
REACH compliance dictates the pricing tier structure across shaft shredder procurement channels. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth, with CE-marked four-shaft systems commanding substantial premiums over unverified mobile hydraulic units. Cost compression in the hydraulic tier is intensifying because EU ETS carbon pricing erodes residual value for diesel-powered construction assets. Waste management consolidators demonstrate lowest price sensitivity under total-cost-of-ownership frameworks, while demolition contractors face acute margin pressure.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes expose raw material dependencies for cutting tool steel production. Supply concentrates in Austria, Sweden, and Germany for hardened alloy formulations, with rotor casting and precision machining feeding from Bavarian engineering networks. Single-source vulnerability sits with Alpine-region heat treatment facilities. Distribution runs through OEM-direct channels for large municipal contracts and specialized equipment lessors for mobile deployment scenarios.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Shaft shredder incumbents must defend against substitution from high-speed hammer mills in plastic preprocessing applications by emphasizing torque advantage and contamination tolerance as non-negotiable specifications.
For Market Incumbents: Compound precision manufacturing heritage with predictive maintenance telemetry integration to lock in waste management consolidators under throughput-guarantee contracts. Backward integration into cutting tool alloy formulation reduces REACH compliance friction and secures margin capture. Counter hydraulic system obsolescence risk by accelerating electric platform development for stranded mobile assets. For New Entrants and Emerging Players: CE marking fast-track for four-shaft hazardous waste configurations opens procurement channels in German and Austrian composting facilities facing mechanical-biological treatment mandates. Target battery recycling preprocessing as the most penetrable segment, where explosion-proof shredding demand outpaces established supply. Pursue service contract unbundling as the primary go-to-market angle, linking payment to operational availability rather than capital equipment delivery. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance play because circular economy mandates harden material recovery targets across EU member states. Acquisition candidates should display captive alloy formulation capabilities and established REACH certification pipelines. Watch EU ETS carbon price trajectories as the inflection signal for hydraulic fleet write-down velocity and electric conversion urgency.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alloy Formulation | REACH-compliant material contact surface certification accelerates product development timelines for German engineering clusters. |
| Electric Drive Platform Development | Permanent magnet synchronous motors capture municipal contracts under tightening EU ETS operational cost structures. |
| Predictive Maintenance Telemetry Launch | Throughput-guarantee service structures enable recurring revenue capture from Nordic waste management consolidators. |
| Four-Shaft Fine-Sizing Capacity Expansion | Mechanical-biological treatment mandates in German and Austrian composting facilities open dedicated procurement channels. |
| Battery Recycling Preprocessing Certification | Explosion-proof shredding configurations with nitrogen purging systems address lithium-ion thermal runaway risks in Benelux black mass recovery. |
Research Methodology
Desk research of EU regulatory filings, customs trade data, and OEM technical documentation preceded structured interviews with municipal waste procurement officers, recycling center operations managers, and aftermarket service heads. Primary fieldwork with plant engineers and maintenance directors validated equipment performance claims, while secondary triangulation against SEC filings and engineering cluster production data anchored bottom-up and top-down estimates.
Variance decomposition across product type, application, end user, and technology dimensions shaped analytical framework development over the projection horizon. CAGRs derived from installed base evolution and replacement cycle modeling incorporated EU Green Deal mandate timelines and ETS carbon price assumptions. Segment-level forecasts integrated rotor width specifications, drive technology adoption curves, and contamination tolerance requirements.
Decision-makers should treat outputs as directional under assumptions of sustained regulatory tightening and alloy supply concentration; material deviation would warrant model refresh. Forecasts reflect base-case scenarios excluding severe trade disruption or abrupt hydraulic technology obsolescence. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Australia and New Zealand Industrial Fasteners Market
Material Handling Equipment
Water Hose Market
Material Handling Equipment
Scissor Lift Market
Material Handling Equipment
Global Industrial Weighing Equipment Market
Material Handling Equipment
Rubber Tyre Gantry Crane Market
Material Handling Equipment
Reach Stacker Market
Material Handling Equipment
Heavy Equipment Movers Market
Material Handling Equipment
Ship Loader and Unloader Market
Material Handling Equipment
Overhead Conveyor Systems Market
Material Handling Equipment
Hydraulic Seals Market
Material Handling Equipment
Wear Plates Market
Material Handling Equipment
Global Refuse Compactor Market
Material Handling Equipment
Centrifugal Industrial Dryer Market
Material Handling Equipment
Wire Rope Sling Market
Material Handling Equipment
Dry Bulk Handling System Market
Material Handling Equipment
North America Forklift Market