
 Equine Diagnostic Services Market | 2026-2036
Equine Diagnostic Services Market Size, Share, and Industry Trends Forecast 2026-2036
Equine Diagnostic Services Market Analysis
Subscription-based genetic panel renewals is recalibrating how laboratories monetize equine health programs. IDEXX Laboratories Inc. leverages its reference laboratory network to sustain recurring revenue from racing stable clients. Neogen Corporation anchors its position through specialized equine infectious disease testing protocols. Generatio GmbH competes on pedigree verification accuracy for European warmblood registries.
Equine diagnostic services encompass laboratory analysis, imaging interpretation, and genetic profiling delivered to veterinary and commercial equine operations. Molecular diagnostics platforms detect pathogen DNA at sensitivity thresholds below traditional culture methods, enabling early intervention before outbreak spread. Genetic testing commands premium positioning within service type segmentation as breed registries mandate parentage verification. Imaging services, particularly ultrasound for soft-tissue injury assessment, represent the most mature revenue pool with established reimbursement pathways through equine insurance programs.
The USDA's National Animal Health Laboratory Network coordinates disease surveillance standards that shape testing protocols for interstate movement. FDA's Center for Veterinary Medicine oversees diagnostic kit approvals that determine market access for infectious disease assays. Kentucky's state veterinary diagnostic laboratory system and Florida's Department of Agriculture equine programs enforce additional jurisdiction-specific requirements. Stakeholders must monitor how state-level equine movement regulations and evolving insurance underwriting criteria reshape service bundling decisions.
Market Dynamics
Genetic verification mandates from breed registries are compressing service timelines while expanding laboratory throughput requirements. The European Union's MDR framework is tightening quality requirements for veterinary diagnostic devices, forcing recertification cycles that reshape competitive positioning.
Growth Catalysts
- MDR Compliance Deadlines:The European Union's Medical Device Regulation is accelerating laboratory investments in ISO 15189 accreditation to maintain market access for equine infectious disease assays.
- Thoroughbred Racing Investment:Kentucky and Florida breeding corridors are expanding diagnostic budgets as performance monitoring becomes standard protocol across high-value stables.
- PCR Platform Adoption:Molecular diagnostics platforms detect pathogen DNA at sensitivity thresholds below traditional culture methods, enabling early intervention before outbreak spread.
Market Restraints
- Reagent Supply Concentration:Specialized PCR reagents for equine pathogens concentrate among three primary suppliers, creating vulnerability to batch shortages.
- Regulatory Fragmentation:Kentucky's state veterinary diagnostic laboratory system and Florida's Department of Agriculture enforce jurisdiction-specific requirements that complicate interstate service bundling.
- Imaging Equipment Depreciation:Ultrasound and MRI systems for soft-tissue assessment require capital replacement cycles that strain independent veterinary practices.
Strategic Opportunities
- Subscription Genetic Panels:Annual renewal models for parentage verification and disease screening are recalibrating how laboratories monetize ongoing equine health programs.
- Insurance Integration:Equine insurance underwriters are mandating pre-purchase imaging documentation, creating captive demand pools for radiographic and ultrasound services.
- Warmblood Registry Expansion:European warmblood studbooks are tightening pedigree documentation requirements, opening verification service contracts for specialized laboratories.
Industry Challenges
- Veterinary Pathologist Shortage:Board-certified equine pathologists capable of interpreting complex histopathology remain scarce, extending turnaround times for necropsy services.
- Interstate Movement Documentation:USDA's National Animal Health Laboratory Network coordinates disease surveillance standards that vary by destination state, complicating logistics for mobile veterinary services.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Equine Diagnostic Services Market |
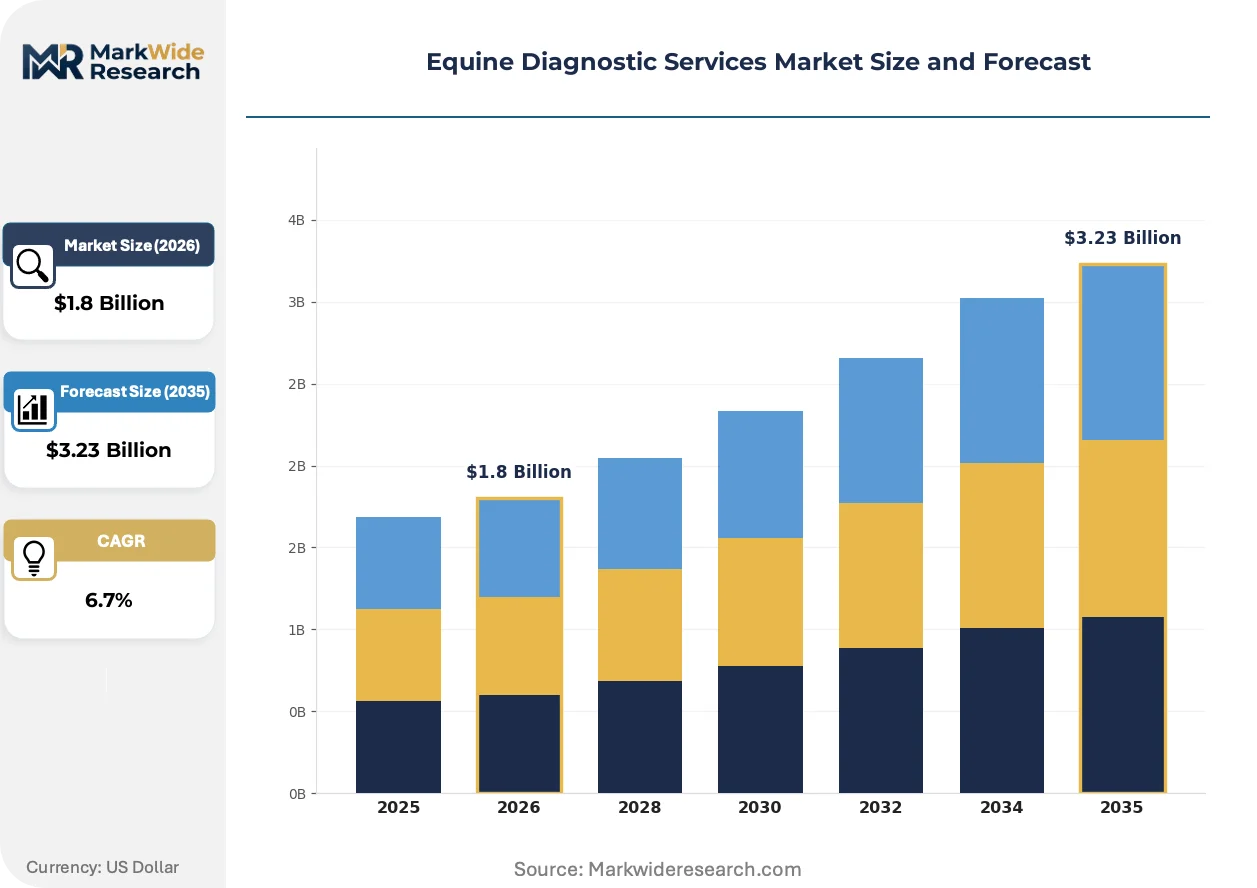
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: In-Person Examination, Blood Testing, Imaging Services, Genetic Testing End User: Veterinary Clinics, Racing Stables, Breeding Farms, Research Institutions Technology: Molecular Diagnostics, Ultrasound, Radiography, Endoscopy Application: General Health Assessment, Infectious Disease Detection, Performance Evaluation, Injury Diagnosis |
| Companies Covered | IDEXX Laboratories Inc., Neogen Corporation, Generatio GmbH, Equiseq Inc., Etalon Inc., Equine Diagnostic Solution Inc., VetGen, Animal Genetics Inc., Veterinary Genetics Laboratory, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Equine Diagnostic Services Market Emerging Trajectories
Digital pathology and artificial intelligence are compressing diagnostic interpretation timelines while raising accuracy benchmarks. Laboratories are reconfiguring workflows around automated sample processing and cloud-based result distribution.
Next-generation sequencing platforms are consolidating genetic testing workflows for parentage verification, disease carrier screening, and performance trait analysis. Thoroughbred breeding operations in Kentucky and Florida are adopting these systems at accelerated replacement cycles. The technology is consolidating previously separate laboratory contracts into single-source relationships with full-service reference laboratories.
The European Union's MDR framework is tightening quality requirements for veterinary diagnostic devices, forcing manufacturers to resubmit existing assays for enhanced clinical validation. In vitro diagnostic kit producers face extended approval timelines that delay market entry for infectious disease panels. European warmblood registries are responding by pre-qualifying laboratories with existing MDR certification, concentrating contract awards among compliant providers.
Racing stables are unbundling diagnostic services from traditional veterinary relationships, contracting directly with reference laboratories for genetic and molecular testing. This channel disintermediation is displacing the veterinary clinic as the exclusive diagnostic intermediary. The pattern is most visible across Kentucky's Bluegrass region and Florida's Ocala breeding district, where large commercial operations negotiate volume pricing directly with IDEXX and Neogen service networks.
Equine Diagnostic Services Market Segmentation
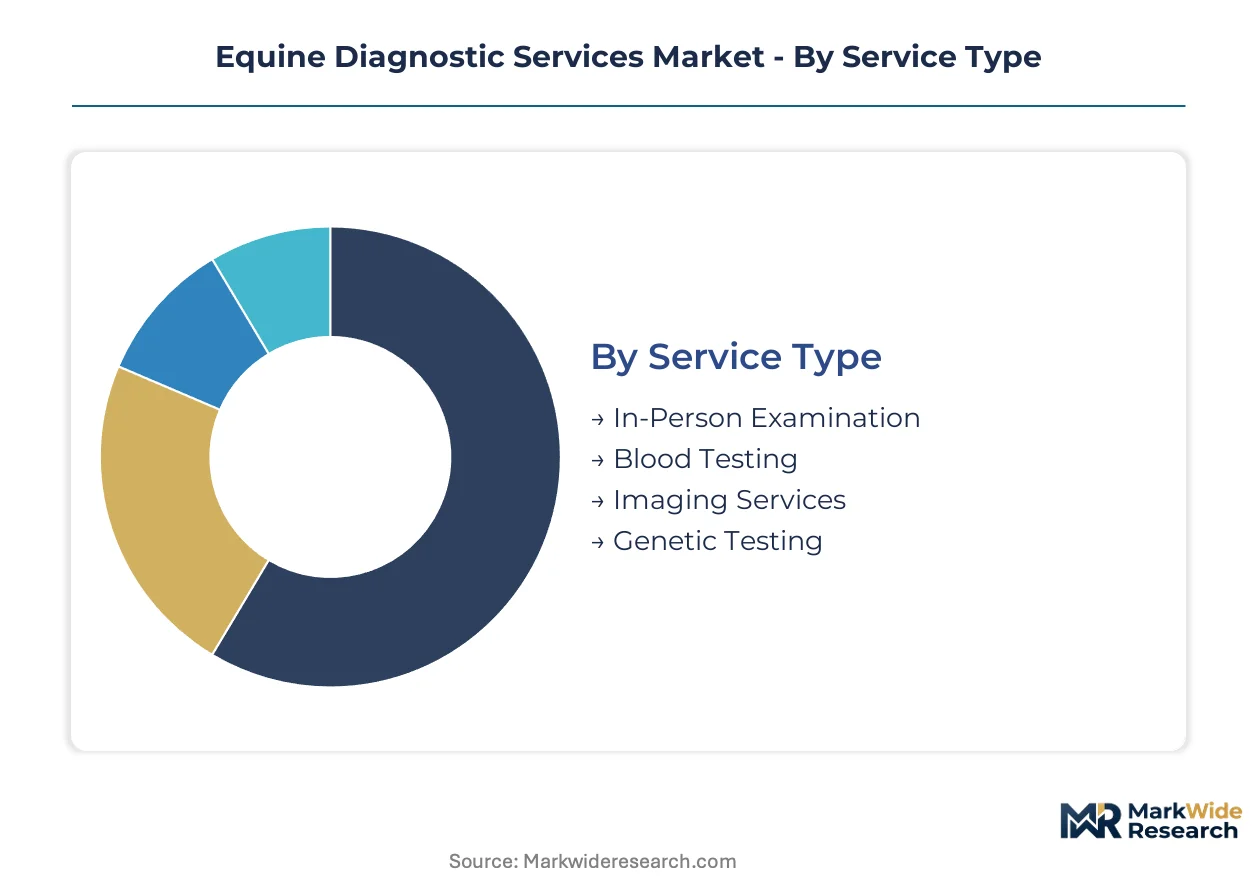
Equine diagnostic services fragment across service delivery modes, end-use sophistication, and technology platforms. Each segmentation axis reveals distinct margin structures and procurement patterns that shape competitive positioning.
Service Type:
Volume-driven routine testing commands stable margins through repeat utilization, while premium modalities extract value from high-stakes breeding and racing decisions.
- In-Person Examination:Traditional veterinary assessment combining physical palpation, auscultation, and visual lameness evaluation. Kentucky's Thoroughbred auction houses deploy these services for pre-sale certification, with veterinarians from Hagyard Equine Medical Institute and Rood & Riddle Equine Hospital dominating high-value consignment work.
- Blood Testing:Hematology, serum chemistry, and infectious disease serology processed through reference laboratories. Racing stables in Florida's Ocala corridor generate recurring panel demand for pre-race medication compliance and metabolic monitoring.
- Imaging Services:Radiographic and advanced imaging interpretation for musculoskeletal assessment.
- Genetic Testing:Parentage verification and disease carrier screening.
Mature deployment sits with Blood Testing. Newer deployment is concentrated in Genetic Testing.
End User:
Procurement authority varies sharply across customer types, with institutional buyers negotiating enterprise pricing while fragmented clinics absorb list rates.
- Veterinary Clinics:Independent and corporate practice groups serving recreational horse owners and local competitive circuits. These clinics function as diagnostic intermediaries, referring complex cases to university laboratories or commercial reference networks.
- Racing Stables:Commercial Thoroughbred operations with dedicated veterinary staff and direct laboratory contracts. Churchill Downs-associated stables and Gulfstream Park strings bypass traditional clinic channels, negotiating volume pricing for PCR respiratory panels and pre-race metabolic screens.
- Breeding Farms:Reproductive services and neonatal intensive care diagnostics.
- Research Institutions:University veterinary schools and pharmaceutical field trial operations.
Established procurement patterns dominate Veterinary Clinics. Direct contracting is expanding most quickly across Racing Stables.
Technology:
Capital intensity and technical specialization create tiered competitive barriers, with molecular platforms requiring laboratory infrastructure while imaging travels to the patient.
- Molecular Diagnostics:PCR and nucleic acid amplification for pathogen detection. Kentucky's state veterinary diagnostic laboratory processes equine infectious anemia and piroplasmosis screening under USDA National Animal Health Laboratory Network protocols, with commercial laboratories competing for supplementary respiratory pathogen panels.
- Ultrasound:Soft-tissue imaging for tendon, ligament, and reproductive assessment. Florida breeding farms deploy portable units for on-farm follicular monitoring and early pregnancy diagnosis, with board-certified radiologists interpreting images remotely through teleradiology networks.
- Radiography:Digital X-ray systems for osseous pathology.
- Endoscopy:Upper respiratory tract and gastric visualization.
Ultrasound represents the most mature installed base. Molecular Diagnostics is gaining share fastest as PCR platforms displace culture-based methods.
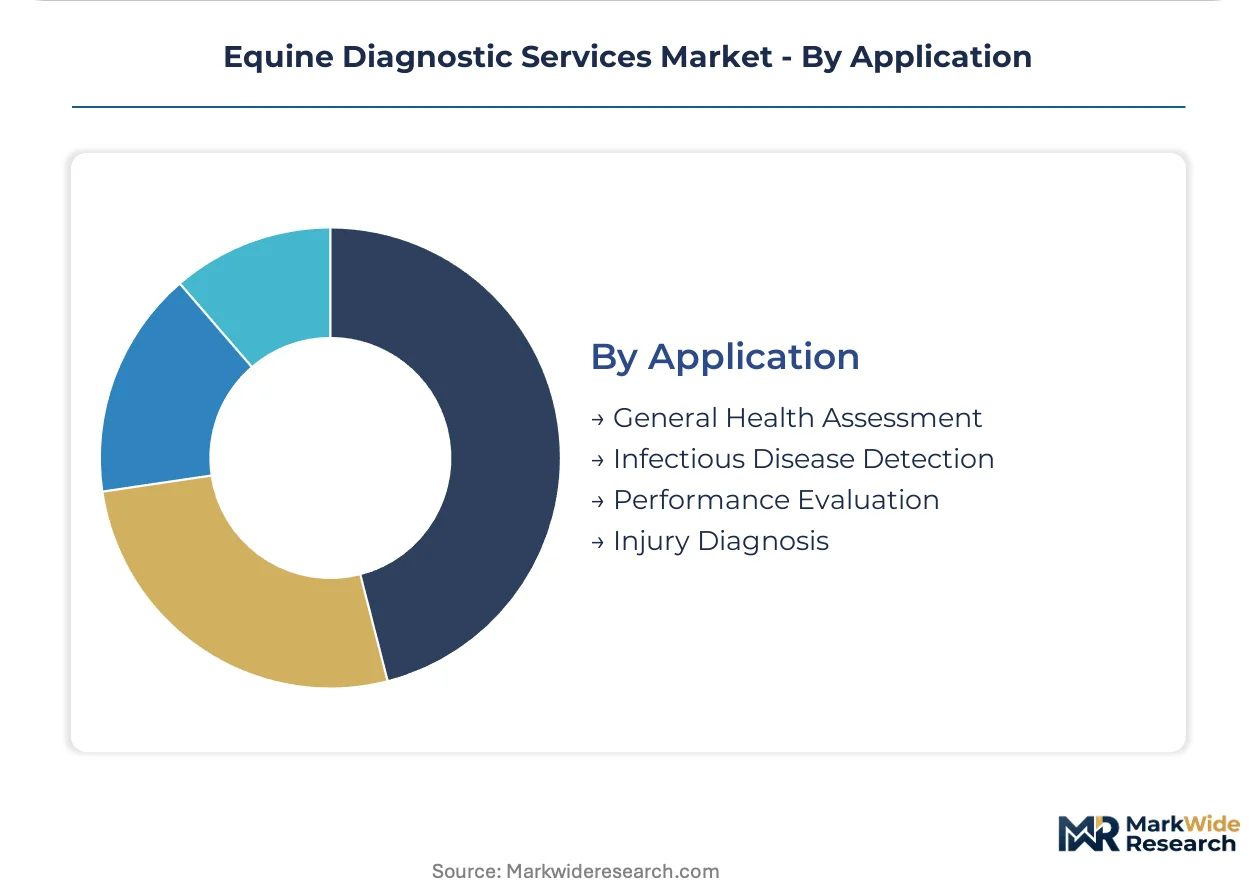
Application:
Clinical urgency and economic stakes vary dramatically across diagnostic intent, from routine wellness to career-threatening injury determination.
- Infectious Disease Detection:Regulatory compliance testing and outbreak investigation. Interstate movement requirements from the USDA's National Animal Health Laboratory Network mandate negative Coggins tests and health certificates, creating non-discretionary demand for equine infectious anemia and piroplasmosis screening.
- Performance Evaluation:Fitness assessment and respiratory function testing for racing prospects. Kentucky Derby contenders undergo treadmill endoscopy and blood gas analysis at specialized centers like the Rood & Riddle Sports Medicine program.
- General Health Assessment:Routine wellness and pre-purchase examinations.
- Injury Diagnosis:Lameness localization and soft-tissue characterization.
Regulatory-mandated screening anchors Infectious Disease Detection. Performance Evaluation is climbing the fastest as racing investment intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States generates the majority of diagnostic service consumption while European laboratories concentrate specialized genetic verification capacity. Production of advanced molecular platforms clusters in Germany and Switzerland, creating a transatlantic supply-demand asymmetry.
United States
Kentucky's Bluegrass region and Florida's Ocala corridor anchor Thoroughbred breeding density, driving demand for PCR respiratory panels and pre-race metabolic screens. The USDA's National Animal Health Laboratory Network mandates Coggins testing protocols for interstate equine movement. Churchill Downs-associated stables negotiate direct laboratory contracts, bypassing traditional veterinary intermediaries.
Germany
Warmblood registries in Lower Saxony and Bavaria enforce stringent parentage documentation, expanding verification service contracts. The EU's MDR framework requires ISO 15189 accreditation for infectious disease assay market access. Hanoverian and Holsteiner studbooks pre-qualify compliant laboratories, concentrating awards among certified providers.
United Kingdom
Newmarket's racing industry generates performance evaluation demand for treadmill endoscopy and blood gas analysis. The country's national veterinary regulator enforces diagnostic kit quality standards under retained EU MDR provisions. British Thoroughbred breeding operations in Suffolk and Cambridgeshire adopt next-generation sequencing for consolidated genetic testing workflows.
France
Normandy's equine breeding cluster supports specialized reproductive diagnostics and neonatal intensive care services. ANSM oversight of veterinary medical devices shapes approval timelines for infectious disease panels. Haras Nationaux facilities coordinate disease surveillance standards that influence regional testing protocols.
Australia
New South Wales and Victoria racing jurisdictions drive demand for regulatory compliance testing and outbreak investigation. The country's national agricultural department coordinates equine infectious anemia screening under import-export protocols. Sydney's equine hospital networks deploy portable ultrasound units for on-farm reproductive assessment.
Equine Diagnostic Services Market Vendor Landscape
Capital-heavy reference laboratory networks compete with asset-light genetic testing specialists for service contracts. The market structure fragments across three tiers: full-service diagnostic conglomerates, niche genetic verification laboratories, and regional veterinary hospital networks. Two strategic archetypes dominate—scale-driven platform operators leveraging reference laboratory density, and precision-focused boutiques competing on pedigree accuracy. Consolidation through reference laboratory acquisitions and technology licensing partnerships represents the primary competitive dynamic.
Among full-service operators, IDEXX Laboratories Inc. and Neogen Corporation occupy positions as scale-driven platform anchors, while Generatio GmbH exemplifies the specialized genetic verification boutique archetype. IDEXX leverages its reference laboratory network footprint to sustain recurring revenue relationships, Neogen anchors market presence through infectious disease testing protocol development, and Generatio competes on parentage verification accuracy for European warmblood registry contracts.
| Leading Market Players |
|---|
| IDEXX Laboratories Inc. |
| Neogen Corporation |
| Generatio GmbH |
| Equiseq Inc. |
| Etalon Inc. |
| Equine Diagnostic Solution Inc. |
| VetGen |
| Animal Genetics Inc. |
| Veterinary Genetics Laboratory |
| Others |
Supply Flow & Price Mechanics
Next-generation sequencing platform consolidation is compressing per-sample processing costs while concentrating contract awards among laboratories with captive bioinformatics pipelines. Kentucky's Thoroughbred breeding operations and Florida's Ocala corridor stables now negotiate enterprise pricing directly with reference networks, bypassing traditional veterinary intermediaries that previously extracted margin layers.
Pricing Analysis
Cost-down pressure on routine blood panels accelerates because racing stables are unbundling services from clinic intermediaries. Three-tier pricing structure across premium, standard, and economy levels separates genetic verification with MDR certification from basic serology and unaccredited parentage screening. Price differentiation hinges on ISO 15189 accreditation status and volume commitment scale. Small independent veterinarians absorb list rates; Churchill Downs-associated operations command enterprise discounts.
Supply Chain Analysis
MDR certification requirements are gating laboratory access to European warmblood registry contracts, forcing upstream reagent sourcing discipline. Specialized PCR reagents for equine pathogens concentrate among suppliers in Germany, Switzerland, and the United States. Supply chain vulnerability rests on single-source dependencies for thermostable polymerase enzymes and fluorescent probe chemistries. Distribution runs through cold-chain logistics networks serving Kentucky's Bluegrass region and Florida's breeding corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around MDR-compliant reference laboratories, with the EU's regulatory deadlines forcing subscale genetic testing boutiques toward acquisition or exit. Stakeholders must position before certification barriers harden.
For Market Incumbents: Lock in multi-year subscription renewals with Kentucky and Florida breeding operations before next-generation sequencing platforms commoditize genetic verification. Defend margin structure by securing captive supply agreements for PCR reagents, insulating against batch shortage disruptions that plague smaller competitors. Channel control through direct stable contracts displaces veterinary clinic intermediaries. For New Entrants and Emerging Players: Regional veterinary clinics without in-house molecular capabilities represent the most penetrable buyer archetype for white-label laboratory partnerships. Target mobile veterinary services operating across interstate corridors, where USDA documentation complexity creates demand for bundled testing logistics. A compliance-first go-to-market angle emphasizing rapid Coggins turnaround differentiates against incumbent reference networks. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by full-service diagnostic conglomerates seeking MDR-certified genetic verification capabilities. Long-term viability favors laboratories with installed next-generation sequencing infrastructure and warmblood registry pre-qualification. Watch for inflection when European studbooks mandate expanded disease carrier screening beyond parentage verification.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 15189 Accreditation Investment | MDR compliance unlocks European warmblood registry contracts previously closed to uncertified laboratories. |
| Direct Stable Contracting Expansion | Kentucky's Churchill Downs-associated operations bypass veterinary intermediaries for PCR respiratory panels. |
| Next-Generation Sequencing Platform Deployment | Consolidated workflows for parentage verification displace separate laboratory contracts across genetic services. |
| Cold-Chain Logistics Partnership | Reliable specimen transport sustains turnaround commitments for Florida's Ocala breeding corridor stables. |
| Bioinformatics Pipeline Development | Proprietary variant interpretation algorithms differentiate genetic testing accuracy for Thoroughbred performance traits. |
Methodological Framework
Multi-period observation of laboratory accreditation status, genetic testing volume trends, and regulatory submission timelines anchored the trend analysis, supplemented by interviews with reference laboratory directors, veterinary clinic owners, equine insurance underwriters, and warmblood registry administrators. Secondary validation drew from USDA National Animal Health Laboratory Network protocols, FDA Center for Veterinary Medicine guidance documents, EU MDR implementation notices, and state-level equine movement regulations. Bottom-up service demand modeling triangulated against top-down breeding industry investment patterns.
Input-output matrices mapped diagnostic service utilization across technology platforms, end-user sophistication tiers, and geographic breeding density clusters throughout the projection horizon. Segmentation dimensions modeled encompassed service delivery mode, technology capital intensity, application urgency, and procurement authority concentration. CAGRs emerged from logistic diffusion curves fitted to PCR platform adoption rates and genetic panel renewal frequencies, cross-referenced against Thoroughbred auction transaction volumes.
Revisions become necessary when MDR enforcement intensity shifts, reagent supply disruptions persist, or breed registry mandates expand beyond parentage verification. Forecasts reflect assumptions about regulatory stability and breeding industry investment continuity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Influenza Diagnostic Tests Market
Diagnostics
Europe Blood Screening Market
Diagnostics
Gastrointestinal Diagnostics Market
Diagnostics
Alanine Aminotransferase Reagent Market
Diagnostics
Melioidosis Diagnostic Market
Diagnostics
Diagnostic Exosome Biomarkers Market
Diagnostics
Syndromic Multiplex Diagnostic Market
Diagnostics
Treponema Pallidum Tests Market
Diagnostics
Inflammatory Markers Market
Diagnostics
India Molecular Diagnostic Controls Market
Diagnostics
India in-Vitro Diagnostics Market
Diagnostics
Global Lyme Disease Diagnostic Market
Diagnostics
Influenza Diagnostics Market
Diagnostics
Shrimps Disease Diagnostics Market
Diagnostics
Blood Grouping Reagents Market
Diagnostics
Canada Latent Tuberculosis Infection Detection Market