
 China Dental Implants Market | 2026-2036
China Dental Implants Market Size, Share, and Industry Trends Forecast 2026-2036
China Dental Implants Market Analysis
Market Context
Aftermarket service revenue from implant maintenance and prosthetic adjustments is rewriting profit allocation across the value chain. Dentsply Sirona leverages its integrated CAD/CAM workflow to capture recurring laboratory fees. Institut Straumann AG anchors premium positioning through its BLX implant interface and digital surgical planning ecosystem. Osstem Implant competes on manufacturing scale, operating one of Asia's largest dedicated implant production facilities in South Korea with deep distribution into China's provincial dental markets.
Technical Definition and Segment Structure
Dental implants are titanium or zirconia root-form fixtures, typically 3.0–6.0 mm in diameter and 6.0–16.0 mm in length, that osseointegrate with alveolar bone to support prosthetic crowns, bridges, or full-arch restorations. Endosteal implants dominate procedural volume due to established surgical protocols and broad bone-type compatibility, while zirconia material formulations are gaining traction among metal-sensitive patients seeking aesthetic anterior solutions. Dental clinics generate the highest margin pool as chairside digital scanning and same-day milling compresses traditional laboratory turnaround, though hospital-based oral surgery departments still handle complex zygomatic and transosteal cases requiring general anesthesia infrastructure.
Regulatory Framework and Outlook
NMPA Class III medical device registration mandates clinical trial data for novel implant surfaces, while GB standards govern biocompatibility testing protocols that parallel ISO 10993 frameworks. The country's national pharmaceutical regulator has tightened adverse event reporting requirements for imported implant systems, creating compliance differentiation between established multinationals and emerging domestic brands. Stakeholders must monitor provincial centralized procurement pilots that threaten to commoditize titanium implant pricing while sparing premium zirconia and immediate-loading portfolios.
Market Dynamics
Provincial centralized procurement pilots for titanium implants are compressing margins across China's dental value chain while simultaneously accelerating investment into premium zirconia and immediate-loading portfolios by domestic manufacturers seeking differentiation.
Growth Catalysts
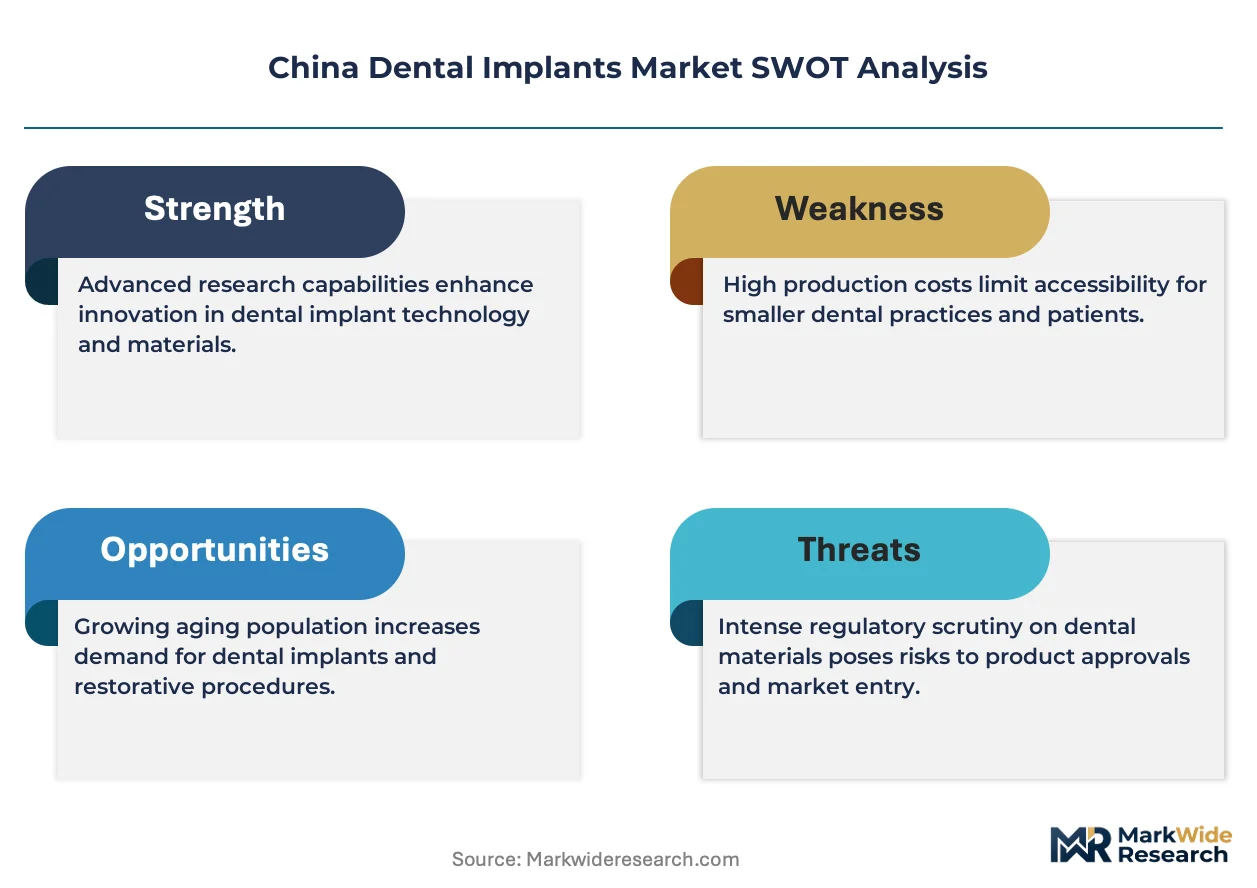
- GB Standards Harmonization:NMPA's alignment of biocompatibility testing with ISO 10993 frameworks is shortening registration timelines for domestic implant surfaces, enabling faster commercialization of innovative osseointegration coatings.
- Private Clinic Expansion:Shanghai and Beijing dental chains are scaling chairside CAD/CAM infrastructure, capturing laboratory fees that previously flowed to independent prosthetic workshops.
- Patient Payment Capacity:Out-of-pocket willingness among tier-one city consumers now exceeds national per-capita dental expenditure benchmarks by substantial multiples, funding elective anterior aesthetic procedures.
Market Restraints
- Titanium Price Volatility:Aerospace and medical-grade titanium sponge supply concentrates among a limited set of global smelters, exposing implant manufacturers to input cost swings that procurement contracts cannot fully hedge.
- Import Dependency for Precision Milling:Five-axis machining centers and laser sintering equipment for abutment fabrication remain concentrated with German and Swiss suppliers, creating capex bottlenecks for domestic scale-up.
- Adverse Event Reporting Burden:NMPA's tightened post-market surveillance requirements for imported implant systems impose documentation costs that disproportionately burden smaller foreign manufacturers with limited China-based regulatory affairs teams.
Strategic Opportunities
- Central and Western Provincial Penetration:Chengdu, Xi'an, and Wuhan dental markets exhibit implant procedure penetration rates substantially below coastal benchmarks, creating first-mover advantage for brands establishing provincial distribution before procurement centralization arrives.
- Immediate-Loading Protocol Standardization:NMPA pathway streamlining for same-day restoration indications is opening premium pricing tiers previously captured only by established multinationals with decade-long clinical dossiers.
- Digital Workflow Convergence:Integration of intraoral scanning with cloud-based surgical planning platforms is collapsing the traditional boundary between restorative dentists and oral surgeons, enabling general practitioner capture of previously specialist-referred cases.
Industry Challenges
- Prosthodontist Training Pipeline:China's dental schools produce insufficient implantology specialists relative to procedural volume growth, forcing manufacturers to subsidize continuing education programs that extend sales cycles.
- Legacy Practice Management System Integration:Provincial clinic chains operate fragmented electronic health record architectures that resist standardized integration with digital surgical planning software, complicating chairside workflow adoption.
- Surface Modification Patent Thickets:International holders of SLA and SLActive surface topography IP are aggressively enforcing licensing terms in NMPA registration proceedings, delaying domestic product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Dental Implants Market |
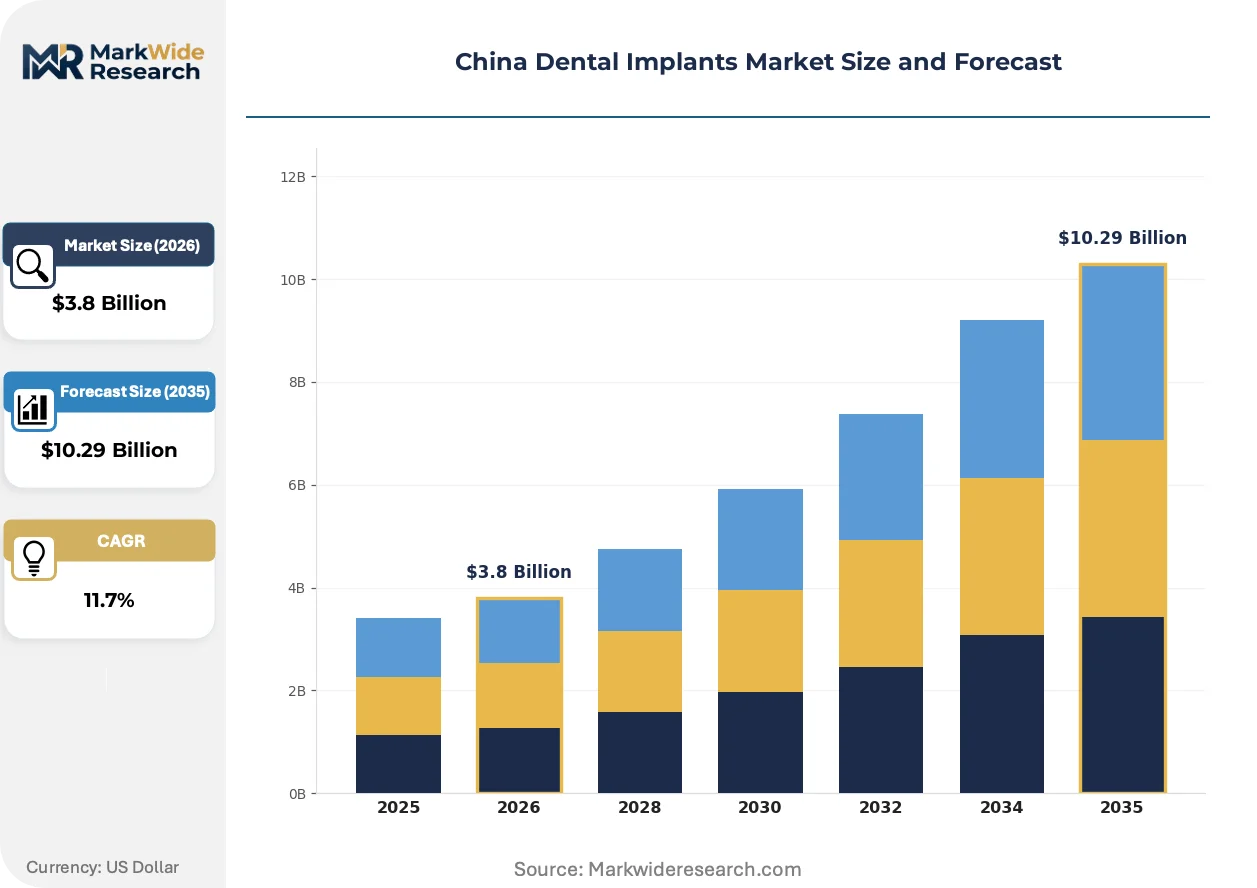
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.29 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Endosteal Implants, Subperiosteal Implants, Zygomatic Implants, Transosteal Implants Material: Titanium, Zirconia, PEEK, Stainless Steel End User: Dental Clinics, Hospitals, Research Institutions, Private Practices Application: Single Tooth Replacement, Multiple Tooth Replacement, Full Arch Restoration, Immediate Loading |
| Companies Covered | Dentsply Sirona, 3M, Institut Straumann AG, SDL DENTAL, Leadoss, Osstem Implant, Zimmer Biomet Holdings, Thommen Medical AG, Envista Holdings (Nobel Biocare), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Dental Implants Market Emerging Trajectories
Digital manufacturing workflows and regulatory pathway evolution are compressing traditional competitive moats in China's implant sector, while procurement centralization forces portfolio restructuring toward premium material categories.
Chairside milling of zirconia abutments is collapsing the traditional prosthetic laboratory intermediation that previously captured 30-40 percent of restoration value. Private dental chains in Shanghai and Shenzhen are deploying compact five-axis units that machine custom abutments within 90 minutes of implant placement. This technology is collapsing the geographic radius within which independent dental laboratories can maintain viable case volume, forcing consolidation among traditional prosthetic workshops.
NMPA's 2023 revision to Class III medical device clinical trial guidance for novel implant surfaces is reducing required enrollment periods for certain osseointegration-enhancing coatings. Domestic manufacturers with established biocompatibility dossiers are leveraging this pathway acceleration to compress the traditional 18-24 month registration timeline. Premium titanium and zirconia implant portfolios from Korean and European incumbents face heightened competitive pressure from these streamlined domestic entrants in provincial tender processes.
Patient acquisition through social media dental influencers is displacing traditional referral networks as the dominant channel for elective implant consultations. Tier-one city consumers aged 35-50 now discover providers through short-form video platforms before contacting clinics directly, collapsing the historical role of general dentist referrals. This behavioral shift is most visible in Beijing and Hangzhou, where top-performing implant centers dedicate 15-20 percent of revenue to digital marketing operations that traditional hospital-based oral surgery departments cannot replicate.
China Dental Implants Market Segmentation
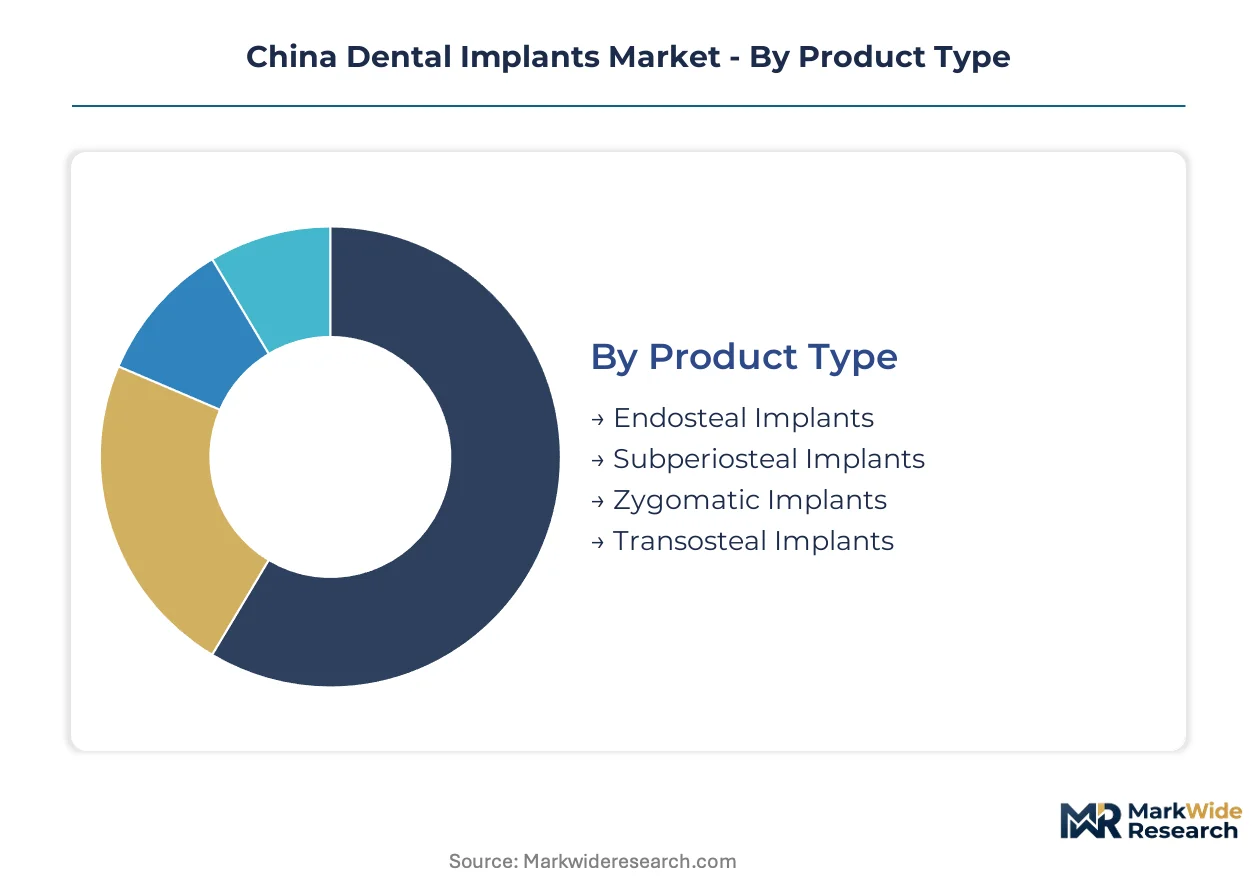
Segmentation reveals how procurement centralization, material innovation, and digital workflow adoption are fragmenting competitive positions across China's implant value chain. Each dimension exposes distinct margin pools and regulatory exposure profiles.
Product Type:
Cost tier stratification separates high-volume titanium fixtures from premium immediate-loading systems that command out-of-pocket premiums in tier-one cities.
- Endosteal Implants:Titanium root-form fixtures measuring 3.0–6.0 mm diameter dominate procedural volume through established surgical protocols and broad bone-type compatibility. Demand concentrates in Shanghai and Beijing private chains where chairside CAD/CAM infrastructure compresses laboratory turnaround.
- Zygomatic Implants:Extended-length fixtures anchor into zygomatic bone for severe maxillary atrophy cases requiring general anesthesia infrastructure. Hospital-based oral surgery departments in Guangzhou and Chengdu handle these complex procedures where NMPA Class III registration barriers limit domestic competition.
- Subperiosteal Implants:Custom-cast frameworks sit atop alveolar bone for patients with insufficient vertical bone height.
- Transosteal Implants:Plate-and-post systems penetrate the mandible in extreme resorption cases with limited applicability.
Endosteal implants hold the largest share; momentum sits with zygomatic systems as hospital infrastructure expands in central provinces.
Material:
Application requirements drive material selection — anterior aesthetics demand metal-free solutions while posterior load-bearing favors titanium strength.
- Titanium:Medical-grade alloys exhibit superior osseointegration through surface modifications like SLA and SLActive topographies. Provincial centralized procurement pilots in Jiangsu and Zhejiang are compressing margins on conventional titanium fixtures while sparing premium formulations.
- Zirconia:Ceramic formulations address metal-sensitive patients and anterior aesthetic demands with tooth-colored abutments. Tier-one city consumers in Shenzhen and Hangzhou pay substantial out-of-pocket premiums for zirconia anterior restorations that procurement frameworks exclude from price controls.
- PEEK:Polymer alternatives serve provisional restorations and specific biocompatibility requirements.
- Stainless Steel:Cost-sensitive temporary applications in budget clinic segments.
Titanium maintains volume leadership; zirconia is climbing the fastest as aesthetic dentistry expands beyond coastal metros.
End User:
Customer type determines pricing power — private chains capture laboratory fees while hospitals retain complex surgical referrals.
- Dental Clinics:Private chains in Shanghai and Beijing deploy chairside milling units that machine custom abutments within 90 minutes. These operators capture 30-40 percent of restoration value previously flowing to independent prosthetic workshops.
- Hospitals:Oral surgery departments handle zygomatic and transosteal cases requiring general anesthesia infrastructure and specialist training pipelines.
- Private Practices:Independent operators in tier-two cities face margin pressure from procurement centralization.
- Research Institutions:Academic medical centers drive clinical trial enrollment for novel surface coatings seeking NMPA registration.
Dental clinics command the highest margins; hospital volume is expanding most quickly as central and western provinces build oral surgery capacity.
Application:
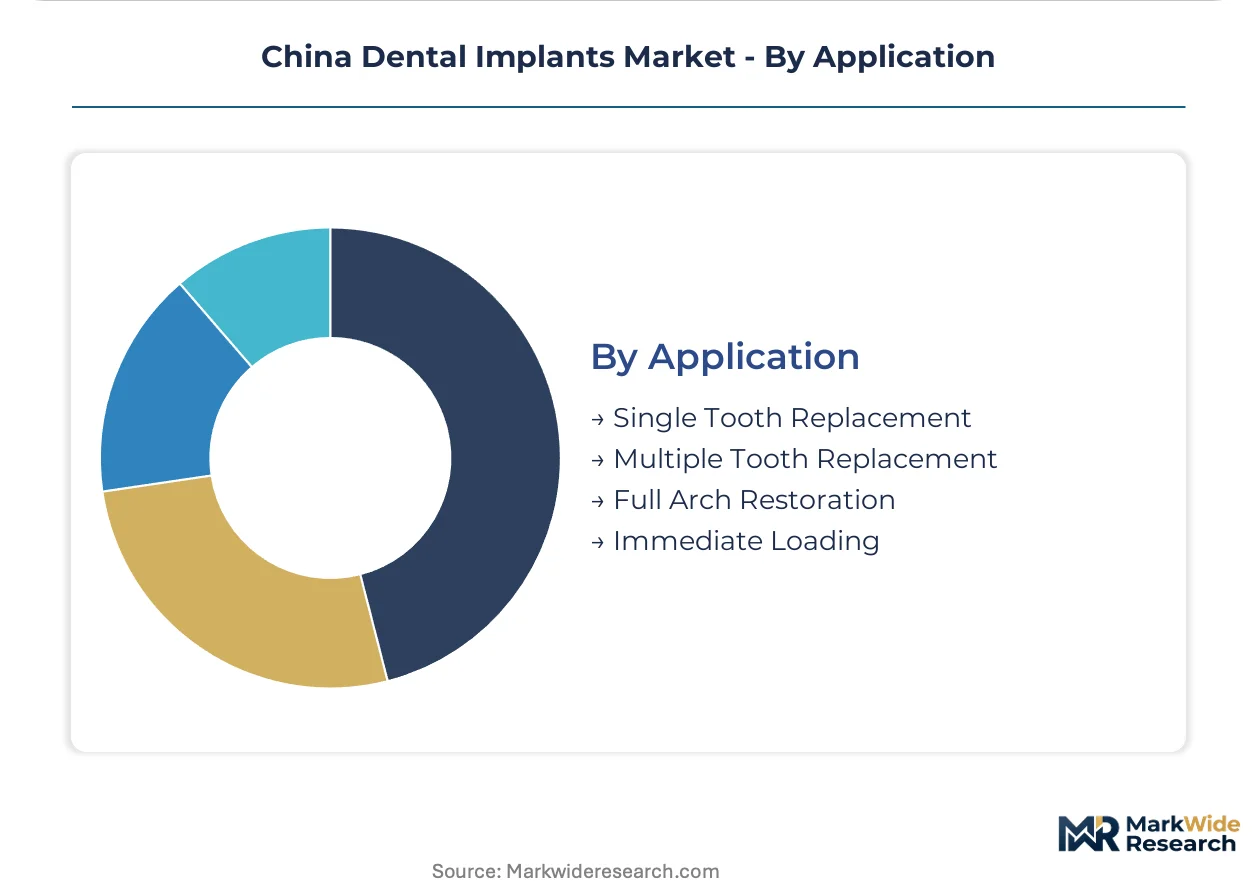
Volume distribution reflects patient payment capacity — single-tooth replacement funds elective aesthetics while full-arch cases concentrate in aging demographics.
- Single Tooth Replacement:Anterior incisor and premolar restorations drive zirconia material demand among metal-sensitive patients. Tier-one city consumers aged 35-50 discover providers through short-form video platforms before direct clinic contact.
- Immediate Loading:Same-day restoration protocols command premium pricing tiers previously captured only by multinationals with decade-long clinical dossiers. NMPA pathway streamlining is opening this segment to domestic manufacturers with streamlined registration timelines.
- Multiple Tooth Replacement:Bridge-supported restorations span partially edentulous arches.
- Full Arch Restoration:All-on-four and all-on-six protocols serve geriatric populations with substantial bone resorption.
Single tooth replacement dominates revenue; immediate loading shows the steepest expansion trajectory as digital workflows collapse traditional laboratory intermediation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tier-one coastal cities consume premium zirconia and immediate-loading systems while central and western provinces rely on conventional titanium fixtures, creating a bifurcated demand geography that procurement pilots are now flattening.
Shanghai
Private dental chains in Shanghai deploy chairside CAD/CAM infrastructure at scale, capturing laboratory fees previously flowing to independent prosthetic workshops. NMPA's streamlined registration pathways for domestic manufacturers accelerate product launches in this high-margin market. The Pudong and Xuhui districts concentrate premium implant volume where per-capita dental expenditure exceeds national benchmarks by substantial multiples.
Beijing
Beijing's hospital-based oral surgery departments handle complex zygomatic cases requiring general anesthesia infrastructure that private clinics cannot replicate. SAMR oversight of medical device pricing creates compliance differentiation between established multinationals and emerging domestic brands. The Haidian and Chaoyang districts anchor specialist referral networks for severe maxillary atrophy procedures.
Guangzhou
Guangzhou dental markets exhibit strong demand for anterior aesthetic restorations among metal-sensitive patients seeking zirconia solutions. Provincial centralized procurement pilots in neighboring Jiangsu and Zhejiang compress titanium margins while sparing premium ceramic portfolios. The Tianhe and Yuexiu districts host expanding private clinic chains investing in intraoral scanning infrastructure.
Chengdu
Chengdu exhibits implant procedure penetration rates substantially below coastal benchmarks, creating first-mover advantage for brands establishing provincial distribution. GB standards harmonization with ISO 10993 frameworks shortens registration timelines for domestic manufacturers entering this underpenetrated market. The Jinjiang and Chenghua districts concentrate emerging dental infrastructure as western China builds oral surgery capacity.
Shenzhen
Shenzhen's technology-forward dental sector leads adoption of digital workflow convergence between restorative dentists and oral surgeons. Patient acquisition through short-form video platforms displaces traditional referral networks for elective implant consultations. The Nanshan and Futian districts host clinics dedicating significant revenue shares to digital marketing operations that hospital-based departments cannot replicate.
China Dental Implants Market Vendor Landscape
Capability concentration sits with European multinationals holding decade-long clinical dossiers and surface modification IP; scale advantage sits with Korean and domestic manufacturers operating Asia's largest dedicated production facilities. The vendor base organizes into three tiers: premium integrators with digital surgical ecosystems, mid-market scale players with provincial distribution depth, and emerging domestic challengers leveraging NMPA pathway acceleration. Consolidation pressure concentrates among independent prosthetic workshops losing laboratory fees to chairside milling. Competitive moves center on M&A to capture digital workflow assets and strategic partnerships to secure five-axis machining capacity.
Within the premium integrator tier, Institut Straumann AG and Dentsply Sirona exemplify archetypes combining implant hardware with closed-loop digital planning ecosystems. Osstem Implant occupies a scale-driven position among Korean manufacturers with deep distribution into China's provincial dental markets. These three anchors illustrate how competitive positioning now depends on controlling recurring revenue streams from maintenance and prosthetic adjustments rather than fixture sales alone.
| Leading Market Players |
|---|
| Dentsply Sirona |
| 3M |
| Institut Straumann AG |
| SDL DENTAL |
| Leadoss |
| Osstem Implant |
| Zimmer Biomet Holdings |
| Thommen Medical AG |
| Envista Holdings (Nobel Biocare) |
| Others |
Supply Flow & Price Mechanics
German and Swiss five-axis machining centers for abutment fabrication concentrate upstream capability, anchoring margin pools with downstream private dental chains in Shanghai and Beijing that capture laboratory fees through chairside milling infrastructure.
Pricing Analysis
Long-term procurement contracts dominate titanium fixture supply to provincial hospital systems, while spot-market premiums attach to immediate-loading systems and zirconia anterior portfolios. Price differentiation rests on NMPA registration tier and surface modification IP licensing status, with certified multinationals commanding substantial premiums over streamlined domestic entrants. Cost compression in conventional titanium fixtures intensifies as Jiangsu and Zhejiang centralized procurement pilots expand, squeezing independent private practices least equipped to absorb margin erosion. Tier-one city dental chains exhibit lowest price sensitivity, funding elective zirconia restorations through direct patient out-of-pocket payment.
Supply Chain Analysis
Export control regimes on precision laser sintering equipment limit technology transfer from German and Swiss suppliers, constraining domestic scale-up in five-axis abutment machining. Manufacturing concentration centers on South Korea for high-volume titanium fixture production, Germany for surface modification coating systems, and Switzerland for premium immediate-loading portfolios. Raw material dependencies span medical-grade titanium sponge from limited global smelters, zirconia ceramic feedstock from Japanese suppliers, and biocompatible PEEK polymers from European chemical producers. Single-source vulnerability concentrates in precision milling equipment where replacement parts and technical service remain captive to original vendors. Distribution runs through provincial dental distributors with hospital system relationships, layered beneath direct sales forces serving premium private clinic chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as social media patient acquisition displaces traditional referral networks, creating niche positioning for digitally native clinic operators and workflow technology providers.
For Market Incumbents: Insulate premium positioning by deepening proprietary surface modification IP enforcement through NMPA registration proceedings, delaying domestic competitor launches. Secure captive five-axis machining capacity through strategic equipment financing partnerships with German and Swiss vendors, locking in technical service access before export control tightening accelerates. For New Entrants and Emerging Players: Build out provincial distribution infrastructure in Chengdu, Xi'an, and Wuhan before centralized procurement pilots arrive, establishing first-mover relationships with hospital-based oral surgery departments. Target immediate-loading protocol standardization as the most penetrable premium segment, leveraging NMPA pathway streamlining to compress registration timelines against multinational clinical dossier advantages. For Investors and Strategic Acquirers: Capital is best deployed toward digital workflow convergence platforms integrating intraoral scanning with cloud-based surgical planning, capturing general practitioner cases previously referred to specialists. Long-term viability favors assets controlling recurring laboratory fee streams rather than fixture manufacturing scale. Monitor provincial procurement pilot expansion announcements as the critical inflection signal for portfolio repositioning timing.| Strategic Initiative | Industry Significance |
|---|---|
| NMPA Registration Pathway Acceleration | Streamlined clinical trial guidance compresses domestic manufacturer time-to-market for novel implant surfaces. |
| Chairside CAD/CAM Infrastructure Deployment | Private clinic chains capture 30-40 percent of restoration value previously flowing to independent prosthetic workshops. |
| Provincial Distribution Network Expansion | First-mover positioning in Chengdu and Xi'an secures relationships before centralized procurement pilots arrive. |
| Surface Modification IP Licensing Enforcement | SLA and SLActive topography holders delay domestic competitor launches through aggressive NMPA registration proceedings. |
| Digital Workflow Platform Integration | Cloud-based surgical planning collapses boundaries between restorative dentists and oral surgeons, enabling case capture expansion. |
Methodological Framework
The analysis maps titanium fixture manufacturing, zirconia ceramic processing, surface modification coating, and digital workflow technology segments, each validated through oral surgeons, prosthodontists, hospital purchasing committee members, and provincial dental distributor principals. Primary interview intelligence triangulates against NMPA registration filings, GB standards documentation, hospital procurement database extracts, and GPO contract records. Bottom-up procedure volume estimates from tier-one through tier-three city clinics reconcile with top-down national dental expenditure benchmarks from health ministry statistical yearbooks.
Assumptions hold NMPA regulatory pathway timelines within observed historical patterns, with alternative scenarios testing accelerated domestic approval and tightened import surveillance conditions. Segmentation dimensions span product type, material formulation, end-user facility category, and application protocol complexity across the projection horizon. CAGRs derive from logistic adoption curve modeling calibrated to provincial penetration rate differentials and patient payment capacity indices. Forecast inputs incorporate chairside milling adoption velocity and social media patient acquisition channel shift rates.
The forecast holds incumbent behavior within observed patterns; aggressive pricing retaliation by established multinationals or sudden NMPA regulatory tightening would shift outcomes materially. Material shifts in provincial centralized procurement pilot scope or export control expansion on precision manufacturing equipment would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
Acrylic Teeth Market
Dental Devices
Dental Rapid Prototyping Systems Market
Dental Devices
Dental CAD Market
Dental Devices
Titanium Dental Implants Market
Dental Devices
Dental 3D Scanners Market
Dental Devices
Dental Aligners Market
Dental Devices
US Dental Splint Market
Dental Devices
Prophy Dental Handpiece Market
Dental Devices
Prophylaxis Pastes Market
Dental Devices
Saudi Arabia Dental Devices Market
Dental Devices
Dental Air Abrasion Market
Dental Devices
Dental Implants and Dental Prosthetics Market
Dental Devices
North America Dental Implants and Prosthetics Market
Dental Devices
RFID-Enabled Dental Printing Market
Dental Devices
Dental Devices and Consumables Market
Dental Devices
Electric Dental Handpieces Market