
 Neurovascular Stent Retrievers Market | 2026-2036
Neurovascular Stent Retrievers Market Size, Share, and Industry Trends Forecast 2026-2036
Neurovascular Stent Retrievers Market Analysis
Project finance and equipment leasing is fragmenting the competitive landscape for high-cost neurointerventional devices. Stryker Corporation leverages its integrated stroke care portfolio to sustain hospital system relationships. Medtronic plc anchors its position through deep R&D intensity in thrombectomy platforms. Johnson & Johnson Cerenovus competes on geographic dominance across North American and European stroke centers.
Neurovascular stent retrievers are self-expanding or balloon-expandable metallic devices, typically constructed from nitinol or stainless steel alloys, designed for endovascular mechanical thrombectomy in acute ischemic stroke. These devices deploy through microcatheters to engage and extract intracranial clots, restoring cerebral blood flow within critical therapeutic windows. Self-expanding stents dominate procedural volume due to their conformability to tortuous intracranial anatomy, while drug-eluting variants capture emerging interest for their potential to reduce restenosis. Nitinol material segments command premium positioning because of superelastic properties enabling reliable deployment in distal vasculature.
FDA breakthrough device pathways and EU MDR conformity assessments shape product development timelines and market access conditions for manufacturers. Japan's PMDA and China's NMPA impose distinct clinical evidence requirements that filter which firms can compete across Asia-Pacific jurisdictions. Stakeholders must monitor how evolving reimbursement thresholds for mechanical thrombectomy in emerging stroke networks reshape addressable patient populations and capital deployment priorities.
Market Dynamics
Mechanical thrombectomy's migration from specialized academic centers to community hospital emergency departments is compressing device procurement cycles and forcing manufacturers to restructure field service and training architectures.
Growth Catalysts
- Comprehensive Stroke Center Certification:Joint Commission accreditation requirements in the United States mandate 24/7 neurointerventional coverage, expanding the addressable hospital base for retriever deployment.
- EU MDR Streamlined Pathways:Designated expert panel reviews for breakthrough devices under the Medical Device Regulation accelerate CE marking timelines compared to legacy MDD processes.
- Nitinol Superelastic Alloys:Advanced metallurgy enables distal M2 segment navigation with reduced vessel trauma, broadening treatable anatomy and procedural indications.
Market Restraints
- Platinum-Iridium Radiopaque Marker Costs:Precious metal price volatility in marker bands squeezes gross margins on single-use devices with no reusable component recovery.
- Microcatheter Supply Concentration:Japanese and German precision extrusion houses control high-torque catheter supply, creating single-source vulnerability for retriever system integrators.
- Distal Access Tortuosity:Anatomical limitations in elderly patients with severe atherosclerotic vessel remodeling exclude approximately one-fifth of presenting cases from mechanical thrombectomy candidacy.
Strategic Opportunities
- Brazilian SUS Reimbursement Expansion:ANVISA alignment with ISO 13485 quality standards opens public health system procurement for foreign-manufactured thrombectomy platforms.
- Artificial Intelligence Triage Integration:Automated large vessel occlusion detection on non-contrast CT is converging with mobile stroke unit dispatch, compressing door-to-puncture intervals.
- Direct-to-Hospital Consignment Models:Inventory positioning at hub-and-spoke stroke networks replaces distributor warehousing, reducing carrying costs for high-value device sets.
Industry Challenges
- Neurointerventionalist Training Pipeline:Fellowship positions in endovascular surgical neuroradiology lag behind device deployment targets, constraining procedural volume growth.
- Biocompatibility Testing Backlogs:ISO 10993 cytotoxicity and sensitization studies face contracted laboratory capacity, extending pre-submission timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Neurovascular Stent Retrievers Market |
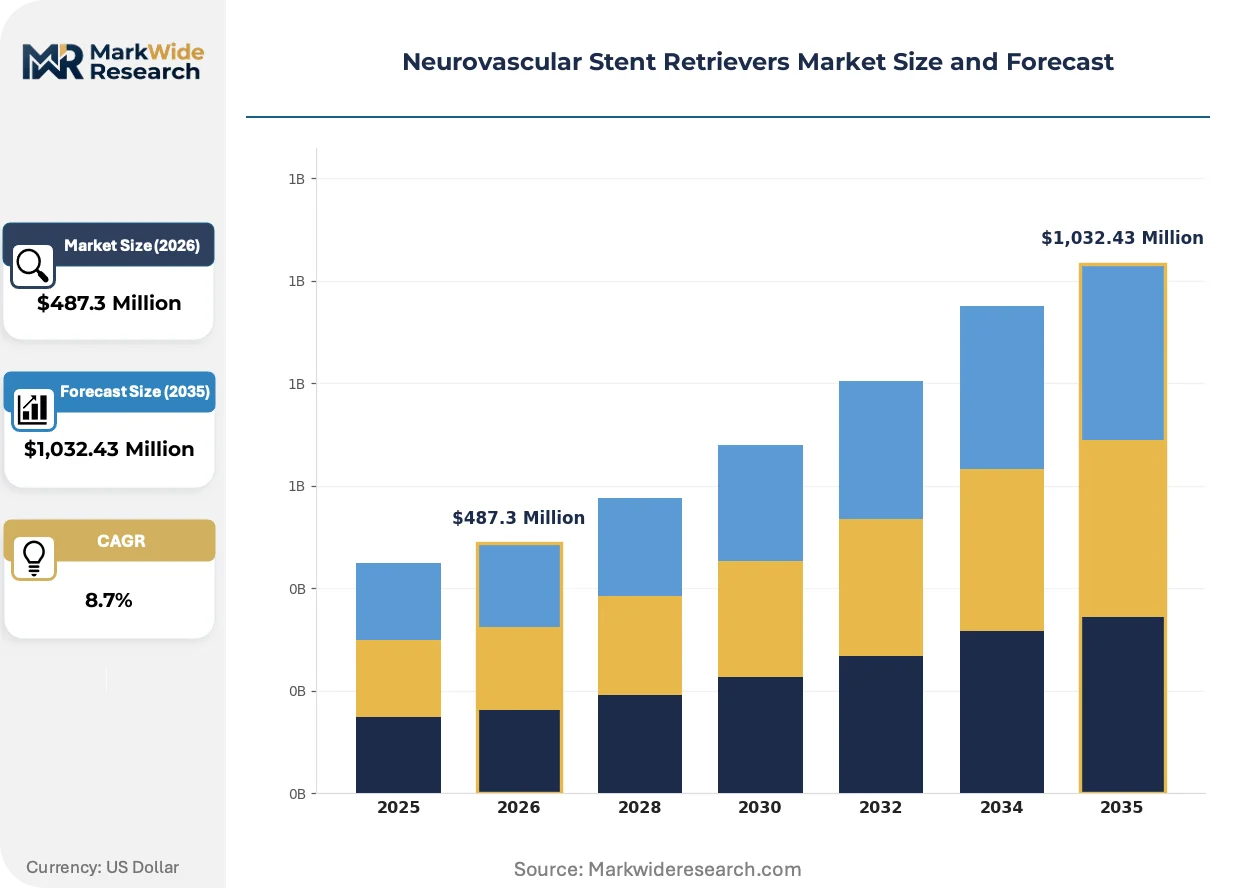
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,032.43 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Self-Expanding Stents, Balloon-Expandable Stents, Drug-Eluting Stents, Bare-Metal Stents Material: Stainless Steel, Nitinol, Polymeric, Coated Materials Delivery Method: Endovascular, Transluminal, Mechanical Retrieval, Thrombectomy System End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Research Institutions |
| Companies Covered | Terumo Corporation, Johnson & Johnson Cerenovus, Stryker Corporation, Acandis GmbH, MicroPort Scientific Corporation, Medtronic plc, Boston Scientific Corporation, Phenox GmbH, Penumbra Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Neurovascular Stent Retrievers Market Emerging Trajectories
Device architecture is pivoting from passive stent-triever designs to active aspiration-assisted systems, while regulatory science and real-world evidence frameworks accelerate post-market surveillance obligations.
Distal access catheter technology is digitizing thrombectomy workflow through integrated pressure sensing and automated clot engagement feedback. Tertiary stroke centers in Germany and Japan are adopting these platforms to reduce operator-dependent variability. The technology is digitizing procedural standardization by embedding decision support directly into device deployment sequences.
EU MDR Article 117 imposes strengthened clinical evidence requirements for class III implantable devices, compelling manufacturers to maintain post-market clinical follow-up registries. This regulatory architecture elevates burden-of-proof standards compared to predecessor directives. Medium-scale device firms are responding by consolidating notified body relationships and centralizing quality management systems in Ireland and the Netherlands.
Hospital procurement committees are unbundling device-procurement from bundled stroke care contracts, separating capital equipment from disposable device purchasing authority. This pattern disrupts traditional vendor-capture models where single-source relationships dominated. The shift is most visible in United States integrated delivery networks where value-analysis committees now independently evaluate retriever cost-per-procedure metrics.
Neurovascular Stent Retrievers Market Segmentation
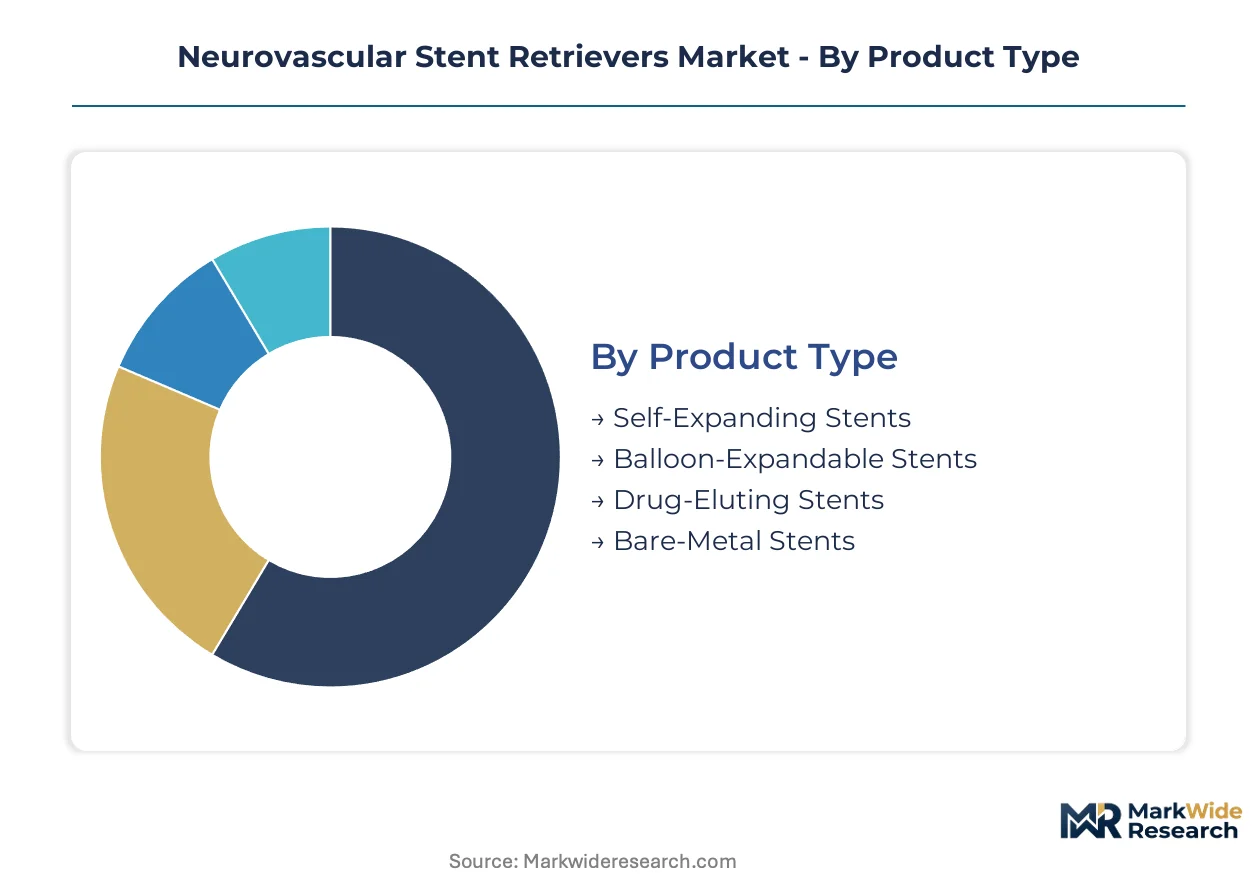
Segmentation in neurovascular stent retrievers reveals how procurement cycles, clinical workflows, and reimbursement structures create divergent velocity profiles across product categories. Understanding these turnover patterns enables manufacturers to calibrate inventory positioning and field service deployment against actual hospital consumption rhythms.
Product Type:
Cycle times vary dramatically across stent architectures, with passive retrieval designs turning over faster than active aspiration-integrated systems due to simpler restocking logistics and lower per-procedure capital commitment.
- Self-Expanding Stents:Nitinol superelastic alloys enable conformable deployment through tortuous intracranial anatomy without balloon inflation. Demand concentrates in United States comprehensive stroke centers where 24/7 neurointerventional coverage mandates reliable distal M2 segment access. These devices anchor procedural volume due to operator familiarity and established reimbursement codes.
- Balloon-Expandable Stents:Stainless steel or cobalt-chromium platforms deliver precise radial force for focal stenosis treatment rather than thrombectomy. German and Japanese stroke centers deploy these for tandem cervical carotid lesions requiring simultaneous angioplasty, though their rigidity limits distal intracranial application.
- Drug-Eluting Stents:Sirolimus or paclitaxel coatings target restenosis prevention in recurrent stroke patients. Clinical adoption trails self-expanding alternatives pending long-term vessel patency data from EU MDR-mandated post-market registries.
- Bare-Metal Stents:Uncoated nitinol or stainless steel constructions serve cost-sensitive procurement committees in emerging stroke networks. Brazilian SUS reimbursement expansion and Indian tertiary hospital purchasing favor these for mechanical thrombectomy budget allocation.
Self-expanding stents anchor the volume base while drug-eluting stents gain share at the steepest rate as long-term outcome data matures.
Material:
Cost tier stratification separates premium metallurgy from commodity alternatives, with raw material price volatility compressing margins differently across alloy categories.
- Nitinol:Nickel-titanium superelastic alloy enables kink-resistant navigation through acute vessel angles with minimal permanent deformation. United States and Japanese manufacturers command premium positioning due to proprietary melt processing and shape-setting expertise.
- Stainless Steel:316L grade provides cost-efficient radial strength for proximal vessel applications. Indian and Chinese hospital procurement favors these for high-volume thrombectomy programs with constrained capital budgets.
- Polymeric:Bioresorbable scaffolds under early clinical investigation for temporary flow restoration without permanent implant. European research institutions drive exploratory demand pending biocompatibility certification.
- Coated Materials:Hydrophilic or heparin surface modifications reduce thrombogenicity in hypercoagulable patients. German stroke centers specify these for complex cases with documented clotting disorders.
Nitinol dominates revenue concentration while polymeric alternatives expand most quickly within investigational protocols.
Delivery Method:
Application intensity varies by procedural complexity, with integrated system approaches requiring longer capital approval cycles than component-based purchasing.
- Endovascular:Transfemoral or transradial catheter-based deployment represents standard mechanical thrombectomy access. United States comprehensive stroke centers and Japanese university hospitals standardize on these platforms for large vessel occlusion protocols.
- Transluminal:Direct vessel puncture techniques for cervical carotid access in hostile aortic arch anatomy. Specialty clinics in Germany and France deploy these for elderly patients with severe peripheral vascular disease.
- Mechanical Retrieval:Stent-retriever extraction combined with aspiration catheter assistance. This hybrid approach is displacing standalone retrieval in tertiary centers seeking improved first-pass recanalization rates.
- Thrombectomy System:Integrated device-aspiration consoles with automated clot detection feedback. Japanese and German early adopters pilot these for operator-independent procedural standardization.
Endovascular delivery anchors installed base volume while thrombectomy systems climb the fastest as artificial intelligence integration matures.
End User:
Customer type determines purchasing authority structure, with capital equipment committees controlling high-value system acquisitions versus materials management handling disposable restocking.
- Hospitals:Tertiary and comprehensive stroke centers with 24/7 neurointerventional coverage. United States Joint Commission accreditation mandates drive retriever procurement across expanding hospital networks.
- Ambulatory Surgical Centers:Limited penetration due to stroke emergency time-sensitivity and required imaging infrastructure. Select German and Swiss facilities handle scheduled diagnostic angiography with standby thrombectomy capability.
- Specialty Clinics:Outpatient cerebrovascular centers focusing on elective stenting rather than emergent thrombectomy. French and Italian private clinic networks concentrate here for carotid disease management.
- Research Institutions:Academic medical centers conducting device trials and registry studies. EU MDR Article 117 post-market clinical follow-up requirements channel manufacturer investment toward these sites.
Hospitals dominate absolute consumption while ambulatory surgical centers represent the most constrained expansion trajectory given stroke emergency logistics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States maintains a net importer position for finished neurovascular stent retrievers despite domestic manufacturing capacity in nitinol processing. Germany and Japan export specialized catheter components and precision extrusion products to assembly facilities across North America and Asia-Pacific.
United States
Comprehensive stroke center certification through the Joint Commission mandates 24/7 neurointerventional coverage, expanding hospital procurement volumes. FDA breakthrough device pathways compress premarket review timelines for novel thrombectomy platforms. The Cleveland Clinic and Mayo Clinic stroke networks in Ohio and Minnesota anchor clinical trial recruitment for distal access device validation.
Germany
University hospital clusters in Bavaria and Baden-Württemberg drive adoption of integrated aspiration-assisted thrombectomy systems. EU MDR Article 117 post-market clinical follow-up requirements channel manufacturer investment toward academic medical centers in Berlin and Heidelberg. The country's precision extrusion houses in the Black Forest region supply high-torque microcatheters to global retriever system integrators.
Japan
PMDA clinical evidence requirements for class IV medical devices filter market entry to firms with established quality management systems. Tokyo and Osaka metropolitan stroke centers standardize on self-expanding nitinol retrievers for large vessel occlusion protocols. Kobe's medical device manufacturing corridor hosts catheter fabrication facilities serving domestic and export markets.
China
NMPA innovation approval pathways for breakthrough devices accelerate market access for domestic manufacturers. Shanghai and Beijing comprehensive stroke centers expand mechanical thrombectomy capacity beyond tertiary academic hospitals. The Yangtze River Delta medical device cluster scales nitinol wire processing for regional stent retriever production.
Brazil
ANVISA alignment with ISO 13485 quality standards opens public health system procurement for foreign-manufactured thrombectomy platforms. São Paulo and Rio de Janeiro stroke networks expand mechanical thrombectomy coverage through SUS reimbursement expansion. The country's private hospital groups in Minas Gerais pilot direct-to-hospital consignment models for high-value device inventory positioning.
Neurovascular Stent Retrievers Market Vendor Landscape
On the supply side, the industry is consolidating around integrated stroke care portfolios that bundle capital equipment with disposable device procurement. Large diversified medical technology conglomerates compete against specialized neurovascular pure-plays with concentrated R&D intensity. Three archetypes dominate: full-stack stroke platform providers, component-specialist sub-tier suppliers, and emerging regional challengers with cost-optimized bare-metal offerings. M&A activity targets catheter technology assets and notified body consolidation in Ireland and the Netherlands.
Among diversified medical technology conglomerates, Stryker Corporation, Medtronic plc, and Johnson & Johnson Cerenovus occupy positions that exemplify contrasting strategic postures. Stryker represents the integrated stroke care portfolio approach with hospital system relationship depth. Medtronic anchors R&D intensity in thrombectomy platform evolution. Cerenovus exemplifies geographic dominance patterns across North American and European stroke center networks. These three entities sit within a tier where scale economies in regulatory compliance and post-market surveillance create defensive positioning against mid-cap specialists.
| Leading Market Players |
|---|
| Terumo Corporation |
| Johnson & Johnson Cerenovus |
| Stryker Corporation |
| Acandis GmbH |
| MicroPort Scientific Corporation |
| Medtronic plc |
| Boston Scientific Corporation |
| Phenox GmbH |
| Penumbra Inc |
| Others |
Supply Flow & Price Mechanics
The Shanghai-Kobe maritime corridor anchors freight cost dynamics for nitinol wire shipments, compressing margins for European assemblers while amplifying price differentiation between premium superelastic alloys and commodity stainless steel alternatives. Procurement committees at United States comprehensive stroke centers exploit this logistics concentration to extract volume discounts on bare-metal retrievers, forcing manufacturers to absorb precious metal marker volatility or surrender gross margin.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels, with FDA breakthrough designation and CE marking under EU MDR serving as the primary certification-grade differentiators. Price erosion runs through economy-tier bare-metal stents as Indian and Chinese hospital procurement drives commoditization, while premium nitinol self-expanding platforms retain pricing power through proprietary shape-setting expertise. Ambulatory surgical centers exhibit acute price sensitivity due to limited procedural volumes, whereas German university hospital clusters prioritize first-pass recanalization rates over per-unit cost.
Supply Chain Analysis
Tariff exposure between United States and China dominates supply chain risk calculus for nitinol wire sourcing, compelling manufacturers to diversify melt processing partnerships. Production gravity centers on Japan for superelastic alloy expertise, Germany for precision microcatheter extrusion, and China for scaled wire drawing operations. Raw material dependencies encompass nickel-titanium ingots, platinum-iridium radiopaque markers, and high-torque polymer catheter substrates. Distribution runs through direct-to-hospital consignment models at hub-and-spoke stroke networks, displacing traditional distributor warehousing for high-value device sets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mechanical thrombectomy's migration into community hospital emergency departments signals early-cycle expansion, with comprehensive stroke center certification mandates creating installed base growth across underpenetrated hospital networks.
For Market Incumbents: Build regulatory moat depth through EU MDR Article 117 post-market clinical follow-up registry investment, securing notified body consolidation in Ireland and the Netherlands. Defend against emerging bare-metal challengers from Chinese Yangtze River Delta manufacturers by deepening backward integration into proprietary nitinol melt processing. Prioritize catheter technology acquisitions to eliminate single-source vulnerability from Japanese and German precision extrusion houses.
For New Entrants and Emerging Players: Build out Brazilian SUS reimbursement expansion as the most penetrable white-space target, leveraging ANVISA ISO 13485 alignment for public health system procurement access. Target cost-sensitive bare-metal stent demand in Indian tertiary hospitals with volume-scaled manufacturing partnerships. Pursue artificial intelligence triage integration as the differentiated go-to-market angle, embedding automated large vessel occlusion detection into mobile stroke unit dispatch protocols.
For Investors and Strategic Acquirers: Catheter fabrication specialists with precision extrusion capabilities represent the priority acquisition archetype, given supply concentration risk and vertical integration imperatives. Frame long-term viability around thrombectomy system platform consolidation over the next decade, as integrated aspiration-assisted designs displace standalone retrievers. Monitor neurointerventionalist fellowship position growth as the critical inflection signal for procedural volume ceiling expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Pathway | Accelerates premarket review timelines for novel thrombectomy platforms against standard PMA routes. |
| EU MDR Notified Body Consolidation | Centralizes quality management systems in Ireland and Netherlands to manage Article 117 clinical evidence burdens. |
| Direct-to-Hospital Consignment Models | Replaces distributor warehousing with inventory positioning at hub-and-spoke stroke networks, reducing carrying costs. |
| Artificial Intelligence Triage Integration | Embeds automated large vessel occlusion detection into non-contrast CT workflows for compressed door-to-puncture intervals. |
| Catheter Technology Acquisition | Eliminates single-source vulnerability from Japanese and German precision extrusion houses controlling high-torque supply. |
Methodological Framework
Initial hypotheses were tested against primary input from neurointerventionalists, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers, and refined through secondary validation against FDA 510(k) filings, EU MDR notified body documentation, hospital procurement databases, and CMS Medicare reimbursement schedules. Bottom-up demand modeling across product type, material, delivery method, and end user segments was cross-checked against top-down macroeconomic indicators and stroke epidemiology data to ensure triangulation integrity.
Demand-supply balance dynamics shaped the analytical framework across the projection horizon, with segmentation dimensions encompassing stent architecture, metallurgy grade, procedural access route, and facility certification tier. CAGRs were derived from procedure volume elasticity to comprehensive stroke center expansion, nitinol raw material cost trajectories, and reimbursement threshold evolution in emerging markets. Industry-specific forecast inputs incorporated neurointerventionalist training pipeline constraints and biocompatibility testing laboratory capacity bottlenecks.
Stress conditions across platinum-iridium price volatility, microcatheter supply disruption scenarios, and EU MDR regulatory enforcement intensity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding stroke center certification timelines and mechanical thrombectomy reimbursement expansion trajectories, with continuous validation against operating reality as the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Cardiogenic Shock Treatment Market
Cardiovascular Devices
Fibromuscular Dysplasia Treatment Market
Cardiovascular Devices
Cardiovascular Catheter Market
Cardiovascular Devices
Arterial Cannula Market
Cardiovascular Devices
Artificial Blood Vessels Market
Cardiovascular Devices
Drug-Coated Balloon Catheter Market
Cardiovascular Devices
Global Artificial Heart Market
Cardiovascular Devices
Saphenous Vein Grafts Market
Cardiovascular Devices
Perfusion Market
Cardiovascular Devices
MRI-Guided Cardiac Ablation Market
Cardiovascular Devices
Cardiac Catheters Market
Cardiovascular Devices
Netherlands Cardiovascular Devices Market
Cardiovascular Devices
Global Intravascular Catheters Market
Cardiovascular Devices
Endovascular Therapy Devices Market
Cardiovascular Devices
Cardiovascular Ultrasound Market
Cardiovascular Devices
Global External Ventricular Drain Market