
 Arterial Stabilization Device Market | 2026-2036
Arterial Stabilization Device Market Size, Share, and Industry Trends Forecast 2026-2036
Arterial Stabilization Device Market Analytics
Ambulatory surgery centers are redrawing the demand map for arterial stabilization hardware as outpatient vascular procedures expand faster than inpatient volumes. B. Braun Melsungen AG leverages its European manufacturing footprint to sustain catheter supply contracts across German and Swiss hospital networks. BD anchors North American distribution through integrated vascular access portfolios that span stabilization to closure. Merit Medical Systems competes on interventional cardiology specialization, particularly in balloon and stent delivery systems that require integrated arterial securement.
Arterial stabilization devices mechanically secure catheters, sheaths, and introducers within the arterial lumen or at the puncture site to prevent dislodgement, kinking, or backbleeding during endovascular procedures; most incorporate hydrophilic coatings, radiopaque markers, and variable durometer construction to balance trackability with vessel wall apposition. Stent-based stabilization dominates revenue due to permanent implantation and premium pricing in coronary interventions, while balloon stabilization represents the fastest-expanding segment as drug-coated and cutting balloon platforms multiply in peripheral artery disease. Bioadhesive methods command concentrated margin pools in hemodialysis access applications where sutureless closure reduces cannulation site complications.
FDA 510(k) clearance requirements and EU MDR technical documentation obligations are elevating barrier costs for new arterial stabilization entrants while accelerating consolidation among established manufacturers. Japan's PMDA and South Korea's MFDS impose additional clinical data requirements that filter out low-capability suppliers from East Asian procurement channels. Stakeholders must monitor how reimbursement shifts toward outpatient settings reshape specification priorities for securement force, dwell time tolerance, and removal trauma profiles.
Market Dynamics
Ambulatory surgery centers are compressing dwell-time specifications for arterial stabilization hardware as outpatient vascular volumes overtake inpatient procedures in mature markets. This demand rotation is forcing manufacturers to engineer securement devices that tolerate shorter implantation windows while maintaining hemostatic performance.
Growth Catalysts
- EU MDR conformity assessments:Elevated technical documentation requirements for Class IIa and IIb devices are filtering out marginal competitors and concentrating procurement among validated suppliers in German and Swiss hospital networks.
- Drug-coated balloon proliferation:Peripheral artery disease platforms require integrated arterial securement during extended lesion preparation, expanding addressable procedure volumes in interventional cardiology suites.
- Japan catheterization laboratory expansion:METI infrastructure subsidies are accelerating PMDA device registrations as tertiary hospitals in Tokyo and Osaka scale interventional capacity.
Market Restraints
- Polymer feedstock volatility:Specialized polyurethane and silicone durometers for variable-trackability sheaths face price instability from medical-grade resin suppliers concentrated in Belgium and Germany.
- FDA 510(k) pathway congestion:Premarket notification review timelines for stabilization accessories have lengthened, delaying commercialization of iterative device improvements.
- Suture-based closure persistence:Manual compression and figure-of-eight suturing remain default techniques in resource-constrained settings, capping premium device penetration.
Strategic Opportunities
- Hemodialysis access bioadhesives:Sutureless cannulation site closure in arteriovenous fistula maintenance commands margin premiums as nephrology clinics seek complication reduction.
- South Korea MFDS fast-track:Streamlined clinical data requirements for predicate-equivalent stabilization devices enable accelerated East Asian market entry.
- Radiopaque marker convergence:Integration of tantalum and platinum-iridium visibility bands with hydrophilic coatings is creating next-generation trackability specifications.
Industry Challenges
- Interventional cardiology technician training:Specialized deployment techniques for integrated securement-sheath systems require credentialing programs that lag device innovation cycles.
- Legacy electronic health record integration:Dwell-time monitoring and removal documentation for stabilization devices must interface with proprietary hospital information systems lacking standardized APIs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Arterial Stabilization Device Market |
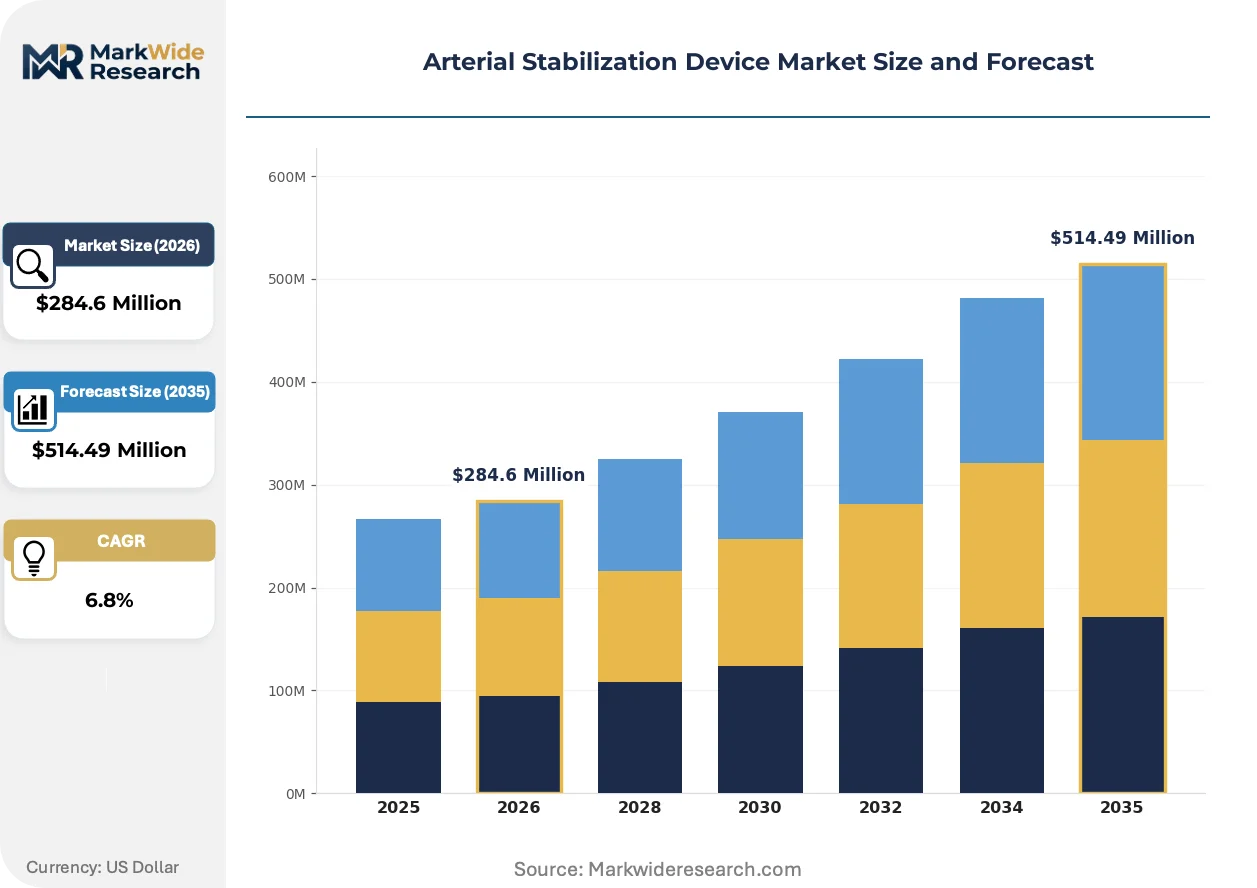
| Market Size in 2026 | $284.6 Million |
| Market Size in 2035 | $514.49 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Balloon, Stent, Catheter, Platelet Aggregation Inhibitor Application: Coronary Interventions, Peripheral Interventions, Endovascular Aneurysm Repair, Hemodialysis Access End User: Hospitals, Ambulatory Surgery Centers, Rehabilitation Clinics, Research Laboratories Technology: Mechanical Stabilization, Bioadhesive Methods, Chemical Stabilization, Electromagnetic Techniques |
| Companies Covered | 3M Company, Baxter International, B. Braun Melsungen AG, Cardinal Health, ConvaTec Inc., Merit Medical Systems, BD, Dale Medical Products, TIDI Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Arterial Stabilization Device Market Evolving Landscape
Device architecture is fragmenting across permanent implant and temporary securement paradigms, with material science and reimbursement mechanics pulling engineering investments in divergent directions. This schism is reshaping R&D allocation and manufacturing footprint decisions.
Hydrophilic coating chemistry is bifurcating between polyethylene glycol-based lubricity platforms for coronary trackability and phosphorylcholine surface treatments for hemodialysis access biocompatibility. Tertiary hospitals in the United States are adopting dual-formulation inventory strategies to cover both intervention types. This technology divergence is compressing economies of scale for coating applicators while creating specialized sub-tier suppliers.
FDA 510(k) substantial equivalence determinations are tightening for stabilization accessories marketed as predicate devices, requiring enhanced biocompatibility testing protocols for extended-dwell applications. Manufacturers must now submit supplementary bench data on coating degradation kinetics under simulated blood flow conditions. Interventional cardiology device portfolios face the steepest compliance cost escalation as coronary procedures carry the highest liability exposure.
Catheterization laboratory purchasing consortia are consolidating vendor relationships around integrated vascular access portfolios spanning introducers, sheaths, and stabilization hardware. Hospital procurement committees in Germany and Japan now evaluate total procedure cost rather than line-item device pricing. This behavioral shift favors suppliers with breadth across the access-to-closure continuum and disadvantages standalone stabilization specialists.
Arterial Stabilization Device Market Segmentation
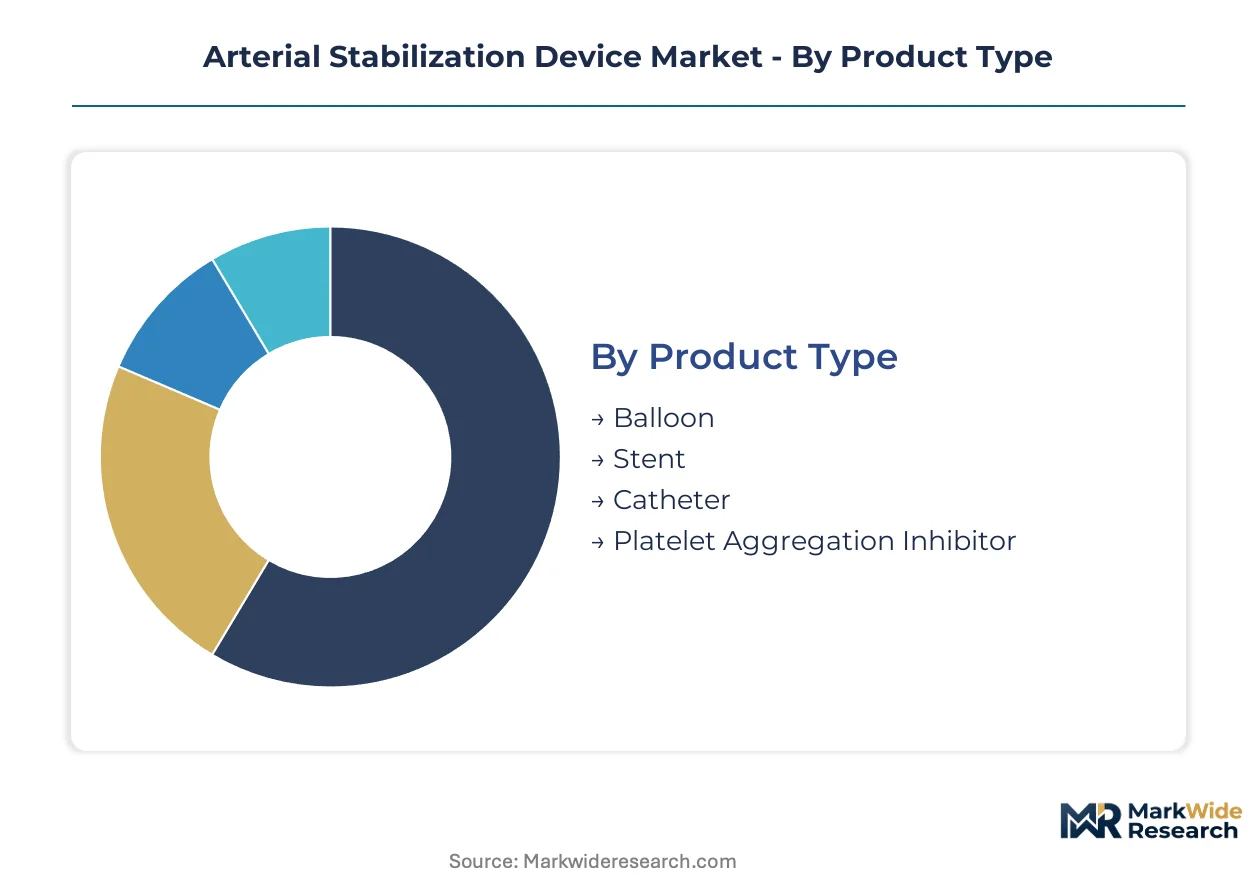
Arterial stabilization hardware fragments across four distinct taxonomies that reshape procurement patterns. Product architecture determines reimbursement coding, while technology choice dictates regulatory pathway complexity and manufacturing investment intensity.
Product Type:
Channel economics diverge sharply: stent-based systems flow through interventional cardiology consortia with bundled pricing, while balloon platforms distribute via peripheral vascular specialty distributors.
- Stent:Permanent implant constructs with nitinol or cobalt-chromium scaffolds integrate radiopaque markers for fluoroscopic visibility. Tertiary hospitals in the United States concentrate procurement through catheterization laboratory expansion programs. Coronary intervention volumes sustain premium pricing despite EU MDR documentation burdens.
- Balloon:Compliant and non-compliant inflation platforms secure sheaths during lesion preparation. German hospital networks are scaling drug-coated balloon procedures for peripheral artery disease, compressing dwell-time specifications. This segment is expanding most quickly as cutting balloon platforms multiply.
- Catheter:Variable-durometer sheath systems with hydrophilic coatings balance trackability against vessel wall apposition.
- Platelet Aggregation Inhibitor:Pharmacological adjuncts delivered via integrated lumens reduce thrombotic complications during extended procedures.
By installed base, stent systems dominate. By procedure volume acceleration, balloon platforms lead.
Application:
Cost tier stratification separates acute intervention reimbursement from chronic access maintenance, with hemodialysis applications commanding distinct procurement committees.
- Coronary Interventions:Percutaneous coronary procedures require securement during complex lesion crossing and stent deployment. Japanese PMDA registrations are accelerating as METI infrastructure subsidies expand Tokyo and Osaka catheterization capacity. Liability exposure drives FDA 510(k) compliance costs highest in this application.
- Peripheral Interventions:Femoropopliteal and below-the-knee procedures demand flexible securement for tortuous anatomy. United States outpatient migration is reshaping specification priorities toward shorter dwell tolerance. This application is gaining share fastest as ambulatory surgery center volumes overtake inpatient procedures.
- Endovascular Aneurysm Repair:Large-bore femoral access for aortic graft delivery requires robust arterial closure integration.
- Hemodialysis Access:Arteriovenous fistula maintenance prioritizes biocompatibility and sutureless closure to reduce cannulation site complications.
Coronary applications generate the highest revenue per procedure. Peripheral interventions show the steepest volume trajectory.
End User:
Customer type determines specification rigor: hospitals demand integrated portfolios while ambulatory settings prioritize rapid turnover compatibility.
- Hospitals:Tertiary catheterization laboratories procure through integrated vascular access contracts spanning introducers to closure. German and Swiss hospital networks are consolidating vendor relationships around total procedure cost evaluation. Device validation requirements intensify with EU MDR Class IIb obligations.
- Ambulatory Surgery Centers:Outpatient vascular suites compress dwell-time windows and prioritize removal trauma minimization. United States reimbursement shifts toward site-of-service neutrality are accelerating this segment's specification influence. This end user is expanding most rapidly as procedure migration outpaces inpatient growth.
- Rehabilitation Clinics:Post-interventional monitoring sites require securement for extended ambulation protocols.
- Research Laboratories:Preclinical and clinical trial sites drive iterative device refinement through controlled deployment data.
Hospitals retain the largest procurement volume. Ambulatory surgery centers are climbing the fastest.
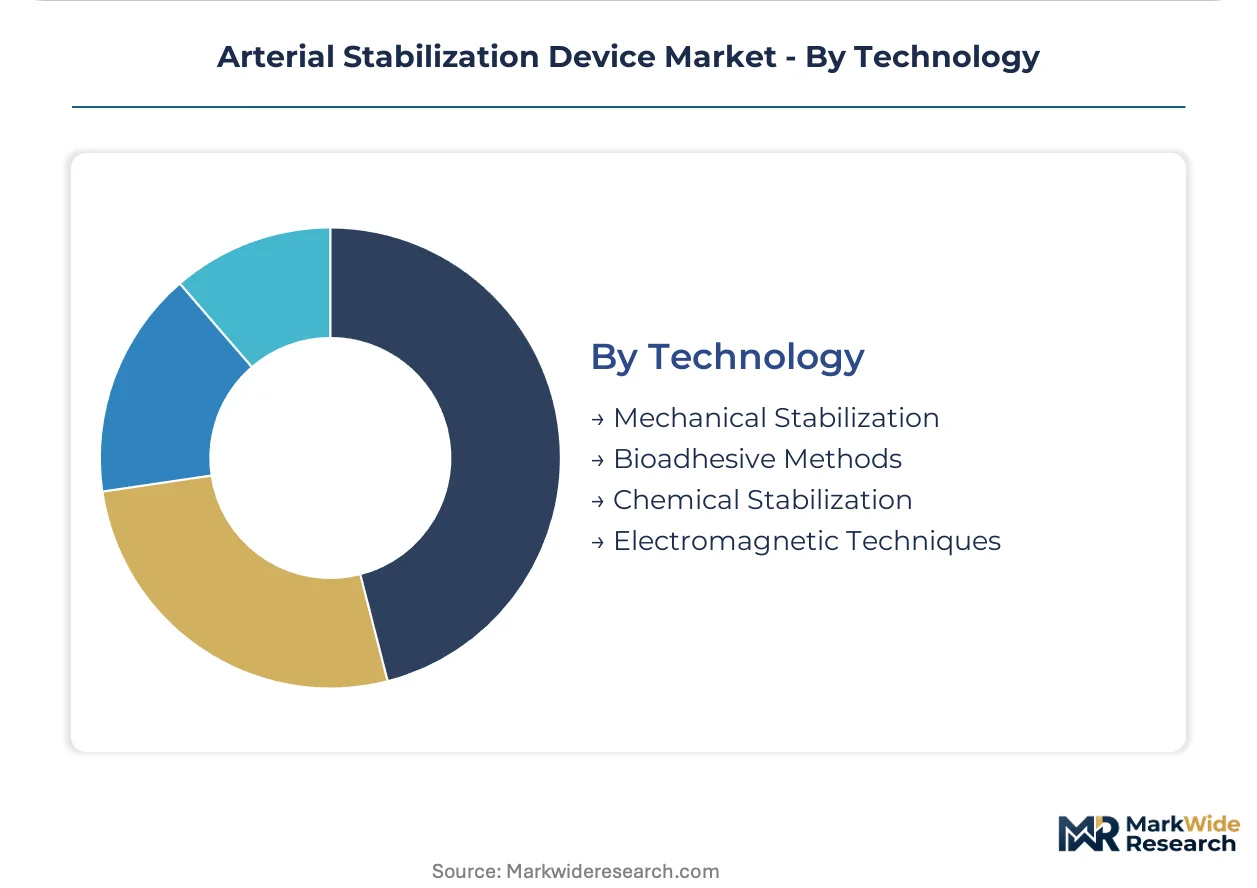
Technology:
Supply concentration clusters around mechanical platforms, while bioadhesive methods attract specialized coating chemistry investments.
- Mechanical Stabilization:Suture-based, clip-based, and friction-fit systems dominate procedural familiarity. B. Braun Melsungen AG leverages European manufacturing scale to sustain catheter supply contracts across German networks. Established reimbursement codes reinforce channel persistence despite training burdens.
- Bioadhesive Methods:Tissue-adhesive polymers and sealant matrices enable sutureless closure with reduced cannulation trauma. Hemodialysis access applications in the United States command margin premiums as nephrology clinics seek complication reduction. This technology is expanding most quickly as phosphorylcholine surface treatments advance.
- Chemical Stabilization:Topical hemostatic agents and procoagulant matrices augment mechanical securement.
- Electromagnetic Techniques:Emerging energy-based vessel approximation methods remain in precommercial validation.
Mechanical platforms anchor current procedure volume. Bioadhesive methods show the strongest growth momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers export arterial stabilization hardware to United States hospital procurement networks under long-term catheter supply contracts. Trade corridors concentrate medical-grade polyurethane feedstock flows from Belgium through Swiss distribution hubs into Japanese catheterization laboratory expansion programs.
United States
Outpatient vascular procedure migration to ambulatory surgery centers compresses dwell-time specifications for securement devices. FDA 510(k) premarket notification pathways for stabilization accessories face extended review timelines. Tertiary hospitals in Texas and California scale catheterization laboratory infrastructure through integrated vascular access contracts.
Germany
Drug-coated balloon proliferation in peripheral artery disease drives demand for integrated arterial securement during extended lesion preparation. EU MDR Class IIb conformity assessments elevate technical documentation requirements for device manufacturers. Hospital networks in Bavaria and North Rhine-Westphalia consolidate vendor relationships around total procedure cost evaluation.
Japan
METI infrastructure subsidies accelerate tertiary hospital expansion in Tokyo and Osaka catheterization laboratories. PMDA device registrations impose additional clinical data requirements that filter marginal competitors from procurement channels. Medical device clusters in Kanto and Kansai regions concentrate interventional cardiology capacity scaling.
Switzerland
Swiss hospital networks source arterial stabilization hardware through German manufacturing supply chains with premium pricing tolerance. Swissmedic conformity assessments align with EU MDR technical documentation standards for Class IIa devices. Zurich and Geneva medical centers prioritize integrated vascular access portfolios spanning introducers to closure.
South Korea
MFDS fast-track pathways for predicate-equivalent stabilization devices enable accelerated East Asian market entry. Streamlined clinical data requirements attract manufacturers seeking regulatory efficiency. Seoul Capital Area catheterization laboratory expansion concentrates procurement demand for balloon and stent-based securement systems.
Arterial Stabilization Device Market Competitive Landscape
Player mix skews toward diversified medical technology conglomerates with integrated vascular access portfolios. Market structure concentrates procurement influence among three to five suppliers with breadth across introducers, sheaths, and stabilization hardware. Strategic archetypes span European manufacturing specialists, North American distribution-integrated players, and interventional cardiology-focused device developers. Dominant competitive moves include catheterization laboratory purchasing consortia consolidation and radiopaque marker convergence with hydrophilic coating integration.
Among diversified medical technology conglomerates, 3M Company and Baxter International exemplify scale-driven archetypes with cross-category manufacturing footprints. B. Braun Melsungen AG occupies a position within the European manufacturing specialist tier, leveraging geographic proximity to German and Swiss hospital networks. BD represents the North American distribution-integrated archetype, anchoring procurement relationships through vascular access portfolio breadth. Merit Medical Systems sits within the interventional cardiology-focused tier, exemplifying specialization in balloon and stent delivery system integration.
| Leading Market Players |
|---|
| 3M Company |
| Baxter International |
| B. Braun Melsungen AG |
| Cardinal Health |
| ConvaTec Inc. |
| Merit Medical Systems |
| BD |
| Dale Medical Products |
| TIDI Products |
| Others |
Value Network & Pricing Analysis
Capacity utilization at German polyurethane resin plants shapes both supply concentration and price floors for arterial stabilization hardware, as medical-grade durometer production runs at near-full load across Belgian and German feedstock facilities. This scale constraint tightens procurement leverage for device manufacturers while elevating minimum viable order quantities for specialized sheath coatings.
Pricing Analysis
Next-generation hydrophilic coating platforms command premium positioning over legacy polyethylene glycol formulations and economy-grade uncoated sheaths. Three-tier pricing structure across premium, standard, and economy levels reflects FDA 510(k) clearance tier, EU MDR Class IIb certification status, and volume scale of catheterization laboratory contracts. Pricing pressure stems from ambulatory surgery center procurement committees demanding total procedure cost reductions. Hospital networks show least price sensitivity due to bundled vascular access contracts, while standalone rehabilitation clinics face highest budget constraints.
Supply Chain Analysis
Inventory buffers for radiopaque marker metals stretch lead times as tantalum and platinum-iridium suppliers prioritize aerospace and electronics contracts. Manufacturing concentrates in Germany, Switzerland, and the United States for finished devices, with medical-grade polyurethane feedstock drawing from Belgium and German resin specialists. Single-source vulnerability concentrates in hydrophilic coating applicators with validated FDA master files. Distribution runs through catheterization laboratory purchasing consortia and integrated vascular access distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment, where FDA 510(k) predicate chains and EU MDR technical documentation create multi-year barriers against replication.
For Market Incumbents: Secure catheterization laboratory purchasing consortia relationships through integrated vascular access portfolio breadth spanning introducers to closure. Lock in long-term supply contracts for medical-grade polyurethane resins before feedstock volatility escalates. Threat of balloon-based securement displacement in peripheral interventions demands R&D investment in drug-coated balloon integration. Backward integration into hydrophilic coating chemistry preserves margin pools against specialty applicator consolidation. For New Entrants and Emerging Players: Post-procedure monitoring service gaps in ambulatory surgery centers expose under-served dwell-time documentation needs that incumbent hardware suppliers ignore. Target hemodialysis access bioadhesive applications where phosphorylcholine surface treatment specialization commands premium positioning against mechanical stabilization incumbents. South Korea MFDS fast-track pathways offer most penetrable regulatory entry for predicate-equivalent devices. Go-to-market angle should emphasize sutureless closure training programs that accelerate clinician adoption. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors interventional cardiology-focused device developers with balloon and stent delivery system integration capabilities over diversified conglomerates with stagnant coronary portfolios. Long-term viability hinges on outpatient migration capture and reimbursement strategy execution across site-of-service neutral payment environments. Acquisition target archetype: mid-cap specialists with validated PMDA registrations and Tokyo catheterization laboratory installed base. Signal to watch is ambulatory surgery center procedure volume crossing threshold that forces specification priority shifts in GPO contract negotiations.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Accelerates market entry through predicate equivalence for next-generation hydrophilic coatings. |
| CE Marking Pathway | Unlocks German and Swiss hospital network procurement under EU MDR Class IIb obligations. |
| Hospital System Partnership | Secures integrated vascular access contracts spanning introducers through closure devices. |
| Software Companion Development | Enables dwell-time monitoring integration with proprietary hospital information systems. |
| Reimbursement Strategy | Aligns device specifications with site-of-service neutral payment shifts toward outpatient settings. |
Research Methodology
The analysis maps stent-based, balloon-based, catheter, and bioadhesive stabilization platforms, each validated through interventional cardiologists, catheterization laboratory purchasing committees, biomedical engineers, and GPO contracts managers. Primary interview intelligence triangulates against FDA 510(k) filings, EU MDR technical documentation databases, hospital procurement records, and CMS Medicare reimbursement data. Bottom-up procedure volume modeling cross-checks with top-down manufacturer revenue aggregation.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions span product architecture, application type, end-user facility category, and stabilization technology platform. CAGRs derive from procedure volume trajectories and device pricing elasticity assumptions. Forecast inputs incorporate METI infrastructure subsidy disbursement patterns and ambulatory surgery center reimbursement shift timelines.
Underlying assumptions cover regulatory pathway stability, feedstock supply continuity, and outpatient migration pace, with deviation risk concentrated in FDA 510(k) review timeline extensions and polymer resin price volatility. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Self-Expanding Stents Market
Cardiovascular Devices
Europe Cardiac Assist Devices Market
Cardiovascular Devices
Hemodynamic Monitoring Devices Market
Cardiovascular Devices
Global Nitinol Medical Devices Market
Cardiovascular Devices
Global Heart Pump Devices Market
Cardiovascular Devices
Cardiovascular CT Systems Market
Cardiovascular Devices
North America Vascular Stents Market
Cardiovascular Devices
Peripheral Vascular Stents Market
Cardiovascular Devices
Artery Compression Devices Market
Cardiovascular Devices
Asia Pacific Interventional Cardiology Market
Cardiovascular Devices
Vascular Snare Market
Cardiovascular Devices
Peripheral Vascular Interventions Market
Cardiovascular Devices
Global Embolotherapy Market
Cardiovascular Devices
Artificial Blood Vessels Market
Cardiovascular Devices
Vascular Prostheses Market
Cardiovascular Devices
Cardiac Medical Device Market