
 Global Passive Optical Network (PON) Equipment Market | 2026-2036
Global Passive Optical Network (PON) Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Passive Optical Network (PON) Equipment Market Intelligence
The large-scale replacement of legacy copper wiring with fiber optic cables is rebalancing the economic calculus for telecommunications infrastructure investment. Huawei Technologies Co., Ltd. dominates many large-scale national rollouts through its extensive portfolio. Nokia Corporation competes on its advanced XG-PON and NG-PON2 technology platforms. Calix, Inc. specializes in providing systems tailored for regional and community broadband providers in markets like the United States.
Passive Optical Network (PON) equipment comprises systems using a point-to-multipoint fiber optic architecture for last-mile connectivity. It utilizes unpowered optical splitters to distribute a single fiber's bandwidth among multiple endpoints, delivering high-speed internet, voice, and video. While GPON technology constitutes the largest installed base, higher-speed XG-PON and NG-PON2 systems represent the fastest-growing technology segments. The Fiber to the Home (FTTH) application remains the primary volume driver for both Optical Line Terminals and Optical Network Units.
Regulatory frameworks and national broadband plans are critical demand signals. In the United States, FCC funding programs incentivize rural fiber deployment, while the EU's Digital Decade policy sets ambitious gigabit connectivity targets for member states. Similarly, India's TRAI and national policies like BharatNet accelerate network build-outs. For telecom operators and Internet Service Providers, the key strategic decision revolves around the timing and capital allocation for upgrading existing GPON infrastructure to next-generation PON technologies.
Market Dynamics
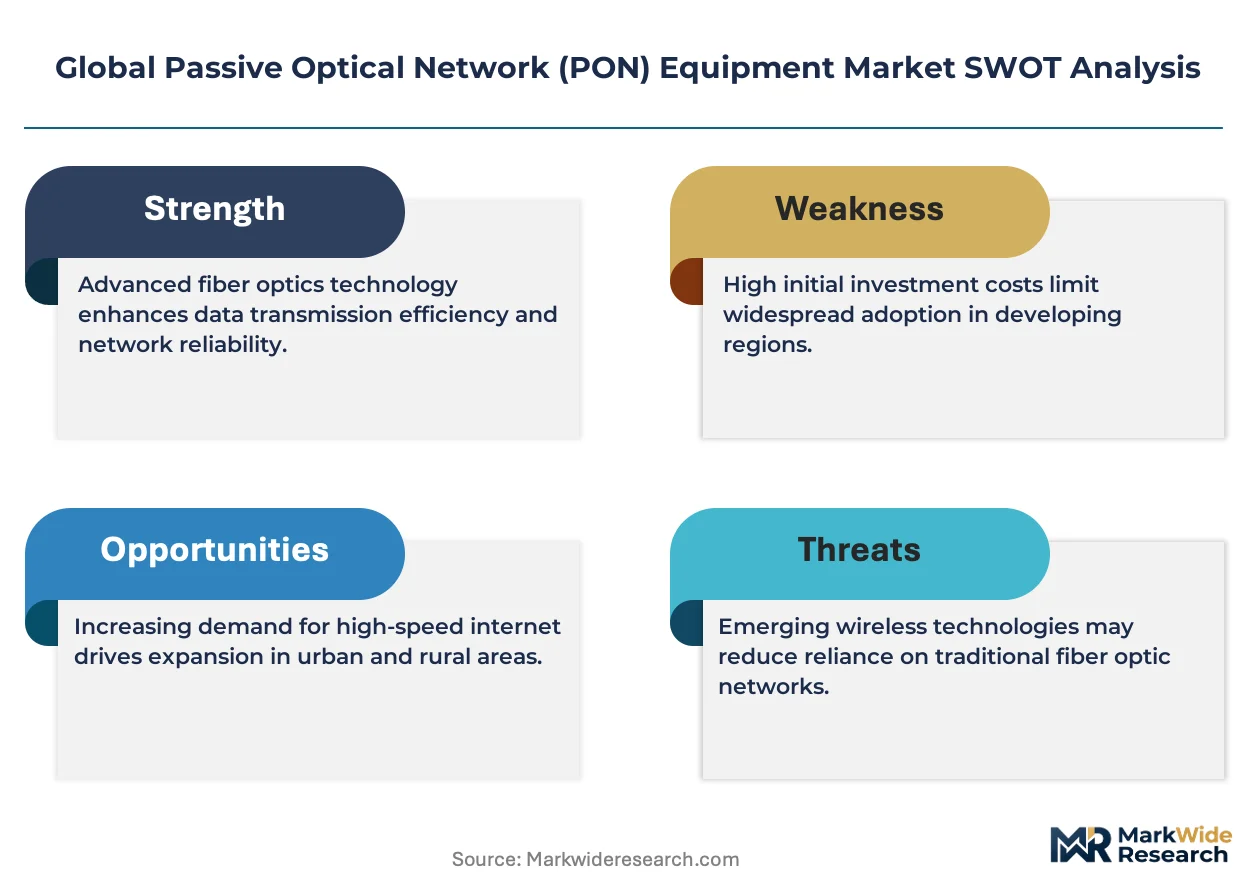
The market's core dynamic is the capital-intensive infrastructure upgrade from legacy copper and GPON systems to next-generation fiber networks. This transition is a direct response to escalating bandwidth consumption from residential streaming, cloud services, and enterprise data applications.
Growth Catalysts
- National Broadband Plans:Government mandates in India and the EU use funding and incentives to accelerate fiber deployments, creating sustained demand for PON equipment.
- Bandwidth-Intensive Applications:The growth of 4K streaming and cloud gaming drives consumer demand for multi-gigabit speeds, forcing upgrades from legacy GPON and copper systems.
- 5G Network Backhaul:Mobile operators use PON for cost-effective fiber backhaul to connect 5G small cells, expanding the market beyond residential FTTH.
Market Restraints
- High Capital Expenditure:The cost of civil works for trenching and laying fiber optic cable is a major barrier to rapid deployment, especially in less dense, rural areas.
- Vendor Interoperability Issues:A lack of full interoperability between vendors' OLT and ONU systems can create vendor lock-in, restricting procurement flexibility and increasing total cost of ownership.
- Permitting Delays:Navigating complex municipal permitting processes for rights-of-way can significantly delay network construction and increase overall project costs for operators.
Strategic Opportunities
- Rural Broadband Expansion:Targeting regional providers in markets like the United States, supported by FCC funding, presents a major growth avenue beyond large carriers.
- Smart City Infrastructure:PON can serve as the fiber backbone for connecting smart city applications like intelligent traffic systems, public Wi-Fi, and environmental sensors.
- Software-Defined PON (SD-PON):Developing software-defined networking allows for greater network automation and the creation of new virtualized services for enterprise customers.
Industry Challenges
- Skilled Labor Shortage:A deficit of trained fiber optic technicians and network engineers capable of deploying and maintaining advanced PON systems constrains the speed of rollouts.
- Legacy System Integration:Integrating new PON infrastructure with existing operational and business support systems (OSS/BSS) is a complex technical and financial challenge for incumbent operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Passive Optical Network (PON) Equipment Market |
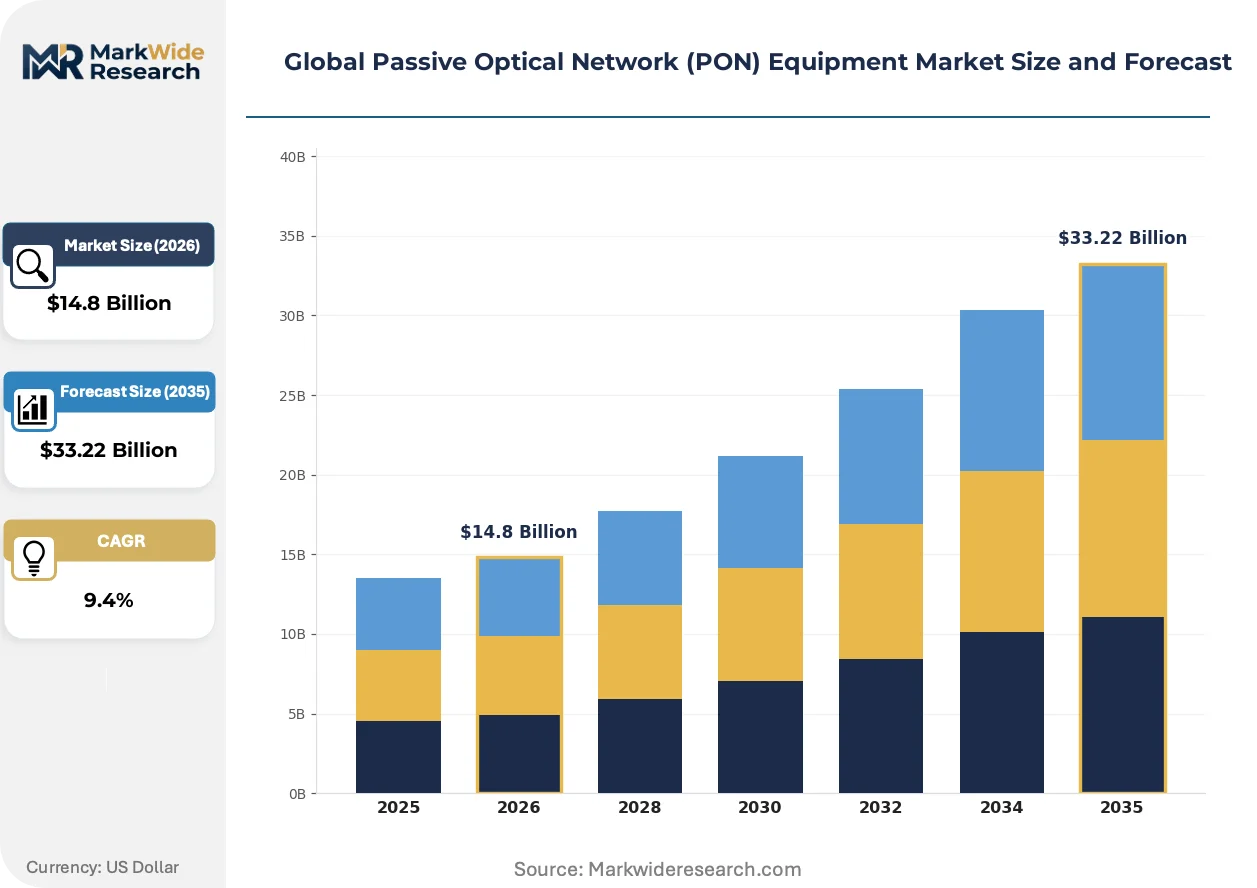
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $33.22 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Optical Line Terminal, Optical Network Unit, Optical Splitter, Media Converter Technology: GPON, EPON, XG-PON, NG-PON2, TWDM-PON Application: Fiber to the Home, Fiber to the Building, Fiber to the Curb, Business Ethernet End User: Telecom Operators, Internet Service Providers, Government Agencies, Enterprises |
| Companies Covered | Calix, Inc., Ciena Corporation, Huawei Technologies Co., Ltd., Broadcom Inc., Mitsubishi Electric Corporation, Nokia Corporation, ADTRAN, Inc., FiberHome Telecommunication Technologies Co., Ltd., ZTE Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Passive Optical Network (PON) Equipment Market Strategic Shifts & Innovations
The evolution of PON equipment is shifting focus from raw bandwidth to intelligent, software-defined network management. This transition enables greater operational efficiency, service flexibility, and new revenue streams beyond simple connectivity.
Higher-capacity standards like 25G-PON and 50G-PON are emerging to meet future bandwidth needs, offering symmetrical multi-gigabit speeds on existing fiber. Tier-1 operators are the primary early adopters planning deployments for future applications. The potential for a single fiber to serve residential, business, and mobile backhaul needs is electrifying the economic models for network convergence.
New subsidy programs, such as the FCC's Broadband Equity, Access, and Deployment (BEAD) Program in the United States, are injecting capital into network expansion. These policies target unserved areas, creating demand in regions previously considered uneconomical. This shift primarily benefits vendors with solutions tailored for smaller, regional service providers and utility cooperatives.
Service providers are shifting from selling raw bandwidth to offering curated, managed in-home experiences. This model bundles value-added services like advanced cybersecurity and managed Wi-Fi directly with the fiber connection. The trend is most visible in competitive residential markets in the United States and Europe, where operators use it to reduce churn.
Global Passive Optical Network (PON) Equipment Market Segmentation
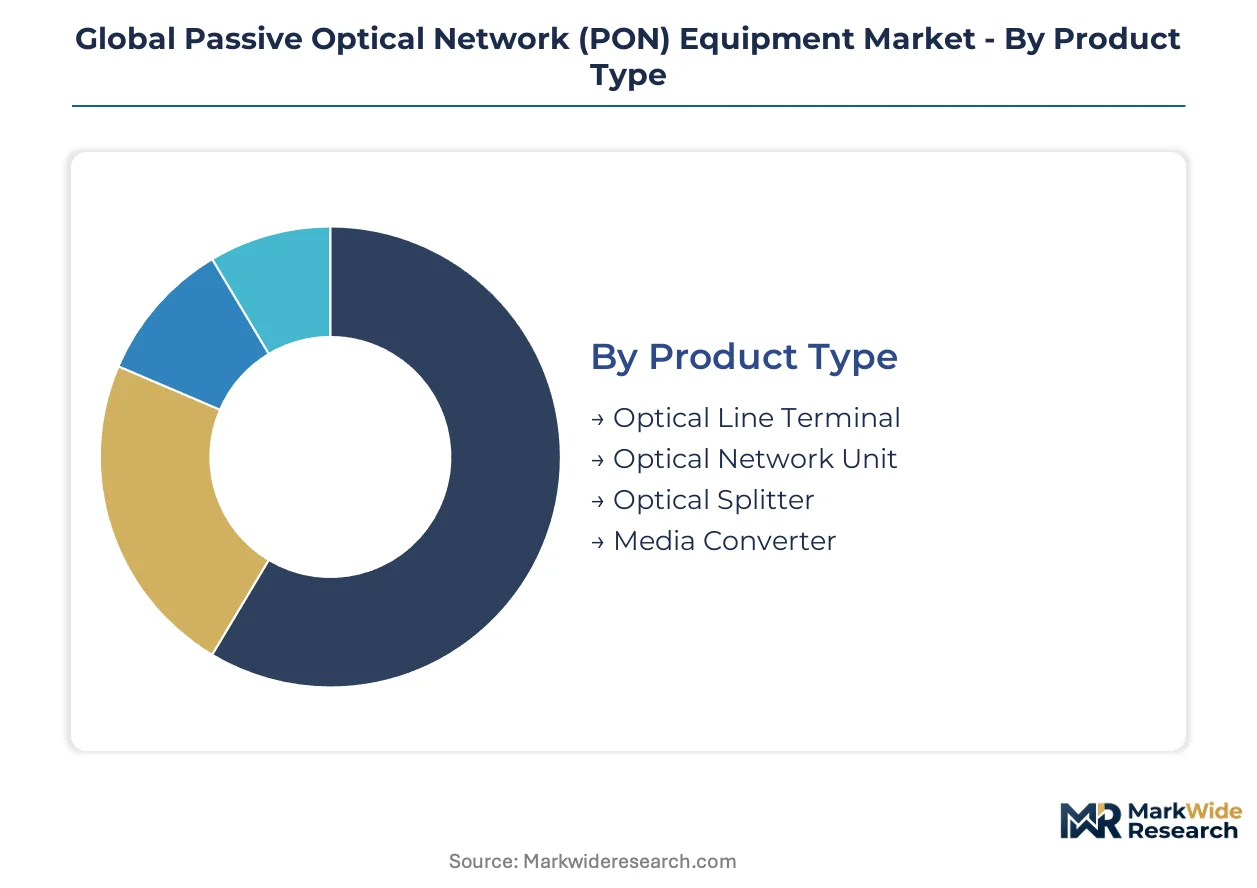
The Passive Optical Network (PON) equipment market is segmented to reflect the diverse technological requirements, deployment models, and end-user demands driving its expansion. Understanding these distinct segments provides clarity on where investment capital is flowing and which innovations are gaining traction across the global infrastructure landscape.
Technology:
The market's technological landscape is defined by distinct PON standards, each offering specific bandwidth capabilities and deployment efficiencies.
- XG-PON:This next-generation standard delivers asymmetrical speeds, typically 10 Gbps downstream and 2.5 Gbps upstream, utilizing a single fiber. Demand is concentrating among large telecom operators upgrading existing GPON infrastructure to support multi-gigabit residential services.
- NG-PON2:This advanced standard provides symmetrical 40 Gbps aggregate capacity through Time and Wavelength Division Multiplexing, allowing multiple wavelengths on a single fiber. It finds demand in competitive urban markets in the United States and Europe for delivering premium enterprise and mobile backhaul services.
- GPON:Gigabit Passive Optical Network remains the largest installed base, offering 2.5 Gbps downstream and 1.25 Gbps upstream for widespread Fiber to the Home deployments.
- EPON:Ethernet Passive Optical Network provides symmetrical 1 Gbps or 10 Gbps speeds, primarily deployed in Asian markets for cost-effective broadband access.
- TWDM-PON:Time and Wavelength Division Multiplexed PON enhances NG-PON2 by enabling flexible bandwidth allocation across multiple wavelengths for diverse service requirements.
GPON leads on scale; NG-PON2 leads on momentum.
Product Type:
Product types address distinct functional roles within the passive optical network architecture.
- Optical Line Terminal:OLTs reside at the service provider's central office, aggregating traffic from multiple Optical Network Units and connecting to the core network. Demand is driven by new fiber builds and capacity upgrades by telecom operators in India and the EU.
- Optical Network Unit:ONUs are customer-premises devices that convert optical signals back to electrical signals, providing broadband access to homes and businesses. The volume driver for ONUs remains Fiber to the Home applications in competitive residential markets.
- Optical Splitter:These unpowered devices divide a single optical fiber's signal into multiple paths, enabling point-to-multipoint network architectures.
- Media Converter:Media converters facilitate the connection between different media types, such as fiber optic and copper cabling, for specific network segments.
Volume is concentrated in Optical Line Terminal and Optical Network Unit components.
Application:
Applications categorize the primary deployment scenarios for PON equipment, reflecting diverse last-mile connectivity needs.
- Fiber to the Home:FTTH deployments extend fiber optic cable directly to individual residential properties, delivering high-speed internet, video, and voice services. This remains the primary volume driver for PON equipment, especially in national broadband programs.
- Business Ethernet:This application provides dedicated, symmetrical high-speed fiber connections for enterprises, supporting critical data, cloud services, and unified communications. Demand is growing among businesses requiring reliable multi-gigabit connectivity in urban centers.
- Fiber to the Building:FTTB extends fiber to a building's demarcation point, then uses existing in-building wiring for distribution to individual units.
- Fiber to the Curb:FTTC deployments bring fiber to a street cabinet, using copper cables for the final short distance to customer premises.
The largest installed base is in Fiber to the Home, while Business Ethernet is expanding rapidly.
End User:
End-user segments define the primary customer groups deploying and utilizing PON infrastructure.
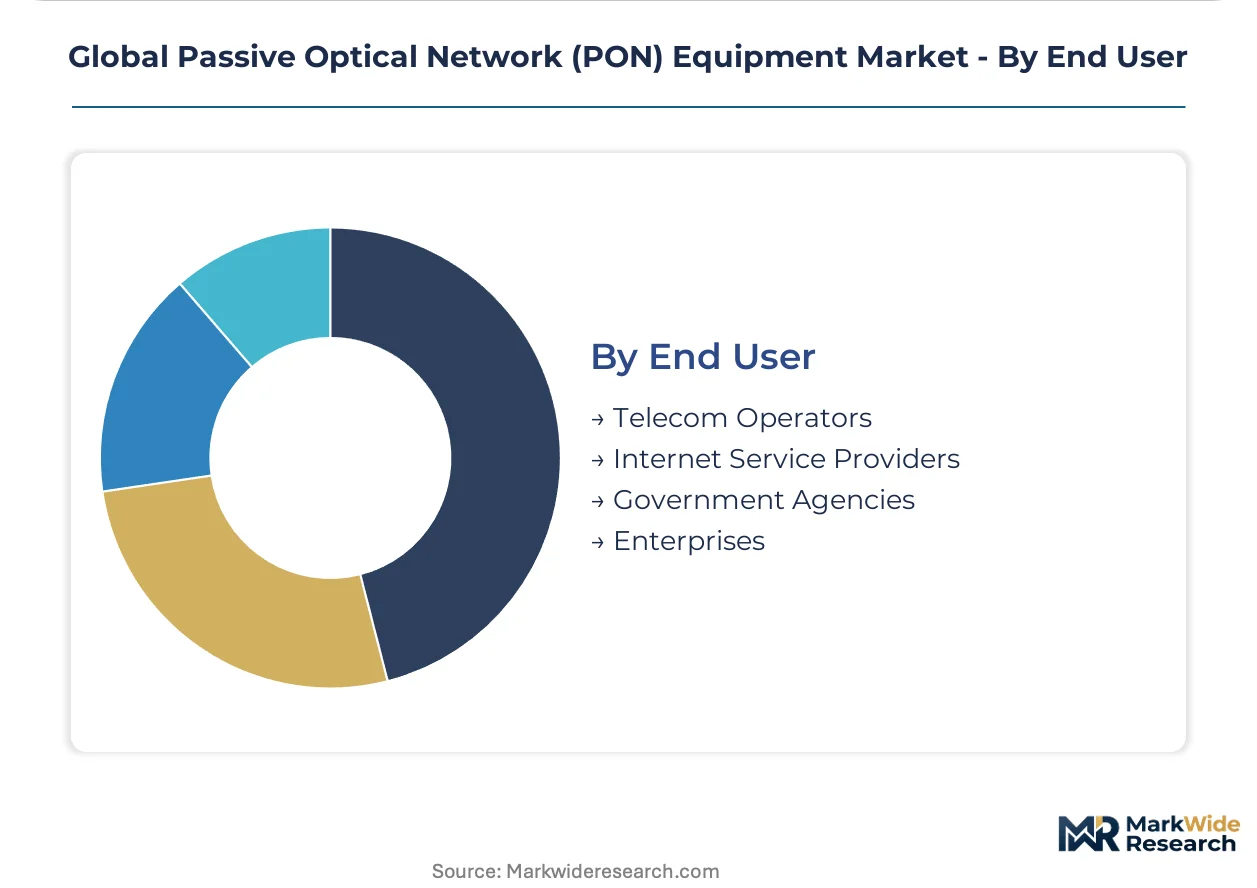
- Telecom Operators:These large-scale carriers deploy PON equipment for extensive national and regional broadband networks, including Fiber to the Home and mobile backhaul. Their demand is driven by infrastructure upgrades and expansion in competitive markets.
- Internet Service Providers:ISPs, ranging from national to regional players, utilize PON for delivering high-speed internet access to residential and business customers. Their procurement is influenced by FCC funding programs and local market competition in the United States.
- Government Agencies:Public sector entities deploy PON for smart city initiatives, public safety networks, and connecting municipal buildings and services.
- Enterprises:Businesses use PON for campus networks, data center interconnects, and high-bandwidth internal communication infrastructure.
Procurement volume is dominated by Telecom Operators, with Government Agencies representing a strategic growth area.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's national digital infrastructure programs drive significant demand for Passive Optical Network equipment. Telecom operators across various regions expand Fiber to the Home networks to meet consumer bandwidth needs. This expansion fuels upgrades to next-generation standards like XG-PON and NG-PON2.
India
National digital infrastructure programs drive substantial demand for PON equipment across India. The country's TRAI and national policies like BharatNet accelerate network build-outs. Major metropolitan areas like Delhi-NCR and Mumbai experience significant FTTH deployments to support escalating bandwidth consumption.
United States
FCC funding programs incentivize rural fiber deployment and next-generation PON upgrades across the United States. The Broadband Equity, Access, and Deployment (BEAD) Program specifically targets unserved areas. Regional providers in states like California and Texas benefit from these programs, enhancing community broadband access.
Germany
European Union's Digital Decade policy sets ambitious gigabit connectivity targets for member states, including Germany. This framework drives significant investment in fiber infrastructure. Cities such as Berlin and Hamburg are seeing upgrades to XG-PON and NG-PON2 systems for both residential and business customers.
China
Cost-effective broadband access remains a primary demand driver for PON equipment in China. The country's MIIT promotes extensive fiber optic network construction across its vast population centers. Major industrial zones in the Pearl River Delta demonstrate high volumes of EPON deployments for widespread connectivity.
Japan
Advanced multi-gigabit services and high-speed internet demand contribute to PON equipment growth in Japan. Japan's METI supports digital infrastructure development, including next-generation fiber deployments. The Kanto region, encompassing Tokyo, is an early adopter of higher-capacity standards like 25G-PON for future bandwidth needs.
Global Passive Optical Network (PON) Equipment Market Key Industry Players
Global majors compete with regional champions across technology innovation and geographic reach within the PON equipment market. The market exhibits a tiered structure, with large-scale operators and specialized vendors serving distinct segments. Strategic archetypes include integrated telecommunications solution providers, dedicated optical networking specialists, and regional broadband equipment suppliers. Companies primarily engage in strategic partnerships, portfolio diversification, and targeted M&A to enhance their market footprint and address evolving customer needs.
On the global scale, Huawei Technologies Co., Ltd. and Nokia Corporation represent integrated telecommunications solution providers, offering extensive portfolios for large-scale national rollouts and advanced XG-PON and NG-PON2 technology platforms. Calix, Inc. occupies a position as a specialized provider, tailoring systems for regional and community broadband providers in markets like the United States. These companies anchor different segments of the market, with some focusing on comprehensive network infrastructure and others on niche regional demands. Their competitive strategies often involve leveraging their existing customer bases and technological expertise to secure new contracts.
| Leading Market Players |
|---|
| Calix, Inc. |
| Ciena Corporation |
| Huawei Technologies Co., Ltd. |
| Broadcom Inc. |
| Mitsubishi Electric Corporation |
| Nokia Corporation |
| ADTRAN, Inc. |
| FiberHome Telecommunication Technologies Co., Ltd. |
| ZTE Corporation |
| Others |
Cost & Logistics Intelligence
The performance divergence between legacy GPON and next-generation PON technologies profoundly influences both pricing and supply chain configurations. This bifurcation manifests in distinct cost structures for mature versus cutting-edge optical components and specialized manufacturing capabilities.
Pricing Analysis
Input cost pass-through for optical components and specialized semiconductors directly impacts PON equipment pricing. The dominant pricing model is contract-based long-term offtake for large telecom operators, complemented by project-based pricing for regional deployments. Price differentiation stems from technology generation (GPON versus NG-PON2 performance) and the level of integrated software management. Pricing softness runs through the GPON segment due to intense competition from Chinese vendors. Regional Internet Service Providers in the United States exhibit higher price sensitivity for initial deployments compared to Tier 1 telecom operators upgrading core infrastructure.
Supply Chain Analysis
Optical fiber and semiconductor supply rests heavily on manufacturers in China, Japan, and South Korea. Key raw material dependencies include specialized glass for fiber optics and advanced chipsets for OLTs and ONUs. A structural supply chain risk involves single-source vulnerability for high-speed optical transceivers, particularly from East Asian suppliers. Distribution runs primarily through direct sales channels to major telecom operators, with specialized distributors serving regional and community broadband providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Passive Optical Network Equipment Market is shifting into a late-cycle quality story, driven by a pronounced demand-shift towards premium multi-gigabit services and intelligent network management capabilities.
For Market Incumbents: Deepen research and development investments in emerging 25G-PON and 50G-PON standards to secure long-term technological leadership. Counter the threat of specialized entrants by integrating advanced Software-Defined Networking capabilities into existing platforms. Expand vertical integration for critical optical components to mitigate supply chain disruptions and maintain cost control. Focus on robust certification investment for new standards.
For New Entrants and Emerging Players: A technology-first wedge into Software-Defined PON solutions offers significant market entry opportunities. Target underserved rural broadband expansion initiatives in the United States, leveraging FCC funding programs like BEAD. Develop cost-effective, modular solutions tailored for regional providers and utility cooperatives. A go-to-market angle emphasizing network automation and operational efficiency will resonate with smaller operators.
For Investors and Strategic Acquirers: Consolidation pressure builds where advanced technology integration and scale advantages offer significant competitive leverage. Long-term viability rests on the essential nature of fiber infrastructure and a multi-decade upgrade cycle. Target specialized software-defined networking firms or regional equipment suppliers with strong local channel presence. The acceleration of 25G-PON and 50G-PON deployments serves as a critical inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in 50G-PON R&D | Secures future market leadership for ultra-high bandwidth applications. |
| Integrate Software-Defined Networking | Enhances operational efficiency for large telecom operators. |
| Target Rural Broadband Partnerships | Expands market reach into underserved United States regions. |
| Control Key Component Manufacturing | Mitigates supply chain risks for critical optical parts. |
| Expand Managed Services Portfolio | Increases revenue per user for Internet Service Providers. |
Research Approach
Bottom-up Fiber to the Home modeling reconciled against top-down equipment manufacturer sales tracking forms the analytical core of this study. The analysis combines extensive primary interviews with network architects, procurement managers at telecom operators, and regulatory analysts. Secondary validation draws from national broadband plan documents, ITU reports, company financial filings, and industry association reports like those from the FTTH Council.
Historical trendline analysis provides the foundation for forecasting, integrating market drivers, restraints, and strategic opportunities. Segmentation dimensions modeled include technology (GPON, XG-PON), product type (OLT, ONU), application (FTTH, Business Ethernet), end-user (Telecom Operators, ISPs), and regional adoption rates. Compound annual growth rates were computed from projected market values across the analysis window, incorporating government infrastructure spending and 5G backhaul requirements as key forecast inputs.
The model holds under stable regulatory environments and consistent infrastructure investment; deviation in global trade policies or major economic downturns would shift projections. Forecasts reflect documented assumptions regarding technological adoption and capital expenditure. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Network Technology
Carrier Routing Equipment Market
Network Technology
Network Telemetry Market
Network Technology
Wi-Fi Network Equipment Market
Network Technology
Global Gigabit Wi-Fi Access Points Market
Network Technology
Network Management Systems (NMS) Market
Network Technology
Global Wireless Router Market
Network Technology
Global Internet Transit Market
Network Technology
US Private LTE and 5G Network Market
Network Technology
Gigabit Passive Optical Network (GPON) Market
Network Technology
Mobile Network Optimization Market
Network Technology
Wimax Solutions Market
Network Technology
Zero-Touch Provisioning Market
Network Technology
Passive Optical Network Market
Network Technology
Philippines Software-Defined Wide Area Network (SD-WAN) Market
Network Technology
Network Fault Monitoring Tools Market
Network Technology
Low-Power WAN Market