
 Satcom Terminal Market | 2026-2036
Satcom Terminal Market Size, Share, and Industry Trends Forecast 2026-2036
Satcom Terminal Market Analytics
Software-defined radio architectures is reconfiguring how satcom terminals integrate multi-band waveforms and adaptive modulation protocols. Viasat Inc. leverages in-house semiconductor fabrication to control modem performance across Ka and Ku frequencies. Thales Group anchors European defense contracts through sovereign supply chains for military-grade terminals. L3Harris Technologies specializes in NSA-certified encryption layers that differentiate its offerings for intelligence community end users.
A satcom terminal is a ground-based or vehicle-mounted radio frequency system that transmits and receives signals via satellite relay, typically operating across frequency bands from L-band through Ka-band with antenna apertures ranging from under one meter to multiple meters depending on throughput requirements. The device serves as the critical interface between terrestrial networks and orbital assets, enabling broadband connectivity in regions lacking fiber or cellular infrastructure. Mobile terminals lead volume shipments due to expeditionary military requirements and emergency response deployments, while maritime terminals command premium pricing from specialized stabilization and salt corrosion resistance specifications. Ka-band technology grows fastest as high-throughput satellites from LEO constellations expand coverage density and reduce cost per bit.
The FCC governs terminal type certifications and spectrum coordination for non-geostationary systems in the United States, while the EU's Radio Equipment Directive mandates CE marking for terminal electromagnetic compatibility across member states. The International Telecommunication Union coordinates orbital slot and frequency assignments that determine where terminals can legally operate without interference. Stakeholders must monitor evolving national security export controls on encryption modules and phased array components that will reshape supplier eligibility and product roadmaps.
Market Dynamics
Software-defined radio architectures are collapsing the traditional hardware-software boundary in satcom terminals, forcing suppliers to restructure R&D around firmware-centric differentiation rather than discrete component assembly.
Growth Catalysts
- FCC spectrum frameworks:The FCC's updated non-geostationary satellite service allocations are compressing terminal certification timelines, accelerating vendor qualification for LEO constellation interoperability.
- NATO defense procurement:Allied defense agencies are expanding hardened communication suite acquisitions for contested electromagnetic environments, prioritizing anti-jam waveform resilience.
- Ka-band throughput density:High-throughput satellite deployments are reducing cost-per-bit economics, pulling commercial maritime and aviation operators away from legacy Ku-band infrastructure.
Market Restraints
- Gallium nitride substrate costs:Power amplifier fabrication depends on constrained GaN-on-SiC wafer supply from specialized foundries, creating input cost volatility for phased array manufacturers.
- ITU coordination delays:Orbital slot and frequency assignment backlogs are extending terminal licensing timelines in contested spectrum bands, freezing product roadmaps.
- Optical fiber substitution:Subsea cable capacity expansion in coastal zones is eroding satellite backhaul economics for terrestrial cellular base stations.
Strategic Opportunities
- India's remote connectivity mandates:The country's BharatNet program and maritime security initiatives are opening procurement channels for portable VSAT terminals in unserved coastal districts.
- Dual-use technology convergence:Civilian LEO broadband constellations are enabling military terminal suppliers to amortize development costs across commercial and defense product lines.
- Modular antenna architectures:Flat-panel electronically steered arrays are disrupting parabolic dish installation economics, creating service bundling opportunities for integrators.
Industry Challenges
- NSA Type 1 certification timelines:Encryption module validation for intelligence community deployments requires 18-24 month approval cycles, compressing product refresh windows.
- Legacy C-band integration:Defense operators maintain extensive C-band infrastructure, forcing multi-band terminal designs that increase RF chain complexity and thermal management requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Satcom Terminal Market |
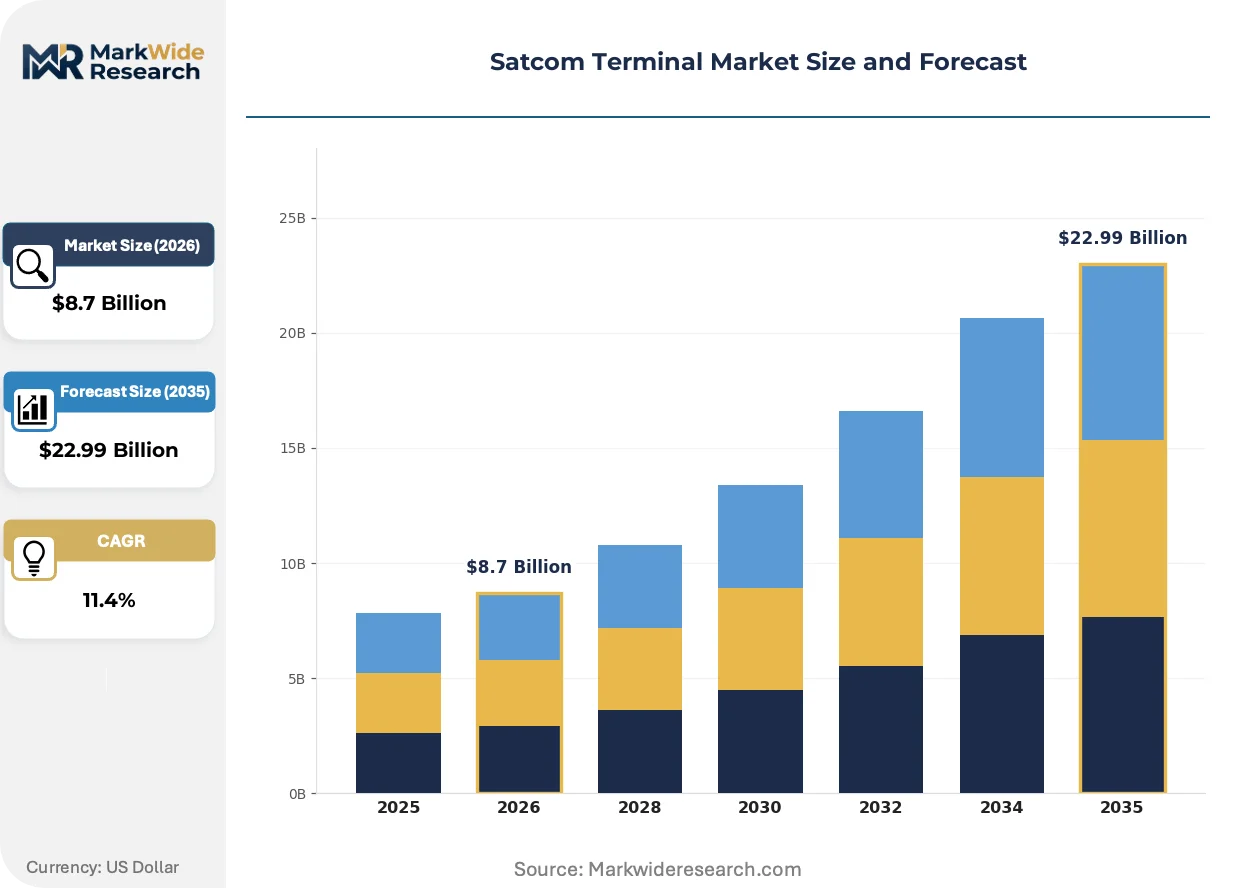
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Terminal, Mobile Terminal, Portable Terminal, Maritime Terminal Technology: Ku-band, Ka-band, C-band, L-band Application: Aerospace, Military, Energy, Broadcasting End User: Government, Telecommunications, Maritime, Aviation |
| Companies Covered | Viasat Inc., Thales Group, L3Harris Technologies, Hughes Network Systems, Gilat Satellite Networks, Intellian Technologies, Cobham Limited, General Dynamics Corporation, Honeywell International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Satcom Terminal Market Evolving Landscape
Terminal architectures are pivoting from hardware-defined to software-configurable platforms, compressing product lifecycles and shifting competitive advantage toward firmware update velocity and waveform licensing breadth.
Electronically steered flat-panel antennas are rendering obsolete mechanically steered parabolic dishes for mobile platforms. Maritime operators and expeditionary military units are adopting solid-state beam steering for acquisition speed under motion. This technology is rendering obsolete the stabilized gimbal supply chain that dominated mobile satcom for three decades.
The EU's Radio Equipment Directive mandates CE marking for electromagnetic compatibility across member states, forcing non-European suppliers to establish notified body relationships. Terminal manufacturers are redesigning power amplifiers and control interfaces to satisfy harmonized standards. Defense integrators serving NATO markets are dual-certifying products to avoid customs friction at European ports of entry.
Defense procurement officers are consolidating vendor relationships around platform-agnostic waveform licenses rather than discrete hardware purchases. System integrators are displacing standalone terminal OEMs in contract awards, bundling connectivity with managed network services. This pattern concentrates in United States Space Force modernization budgets, where service-based contracting now dominates satcom terminal acquisition strategy.
Satcom Terminal Market Segmentation
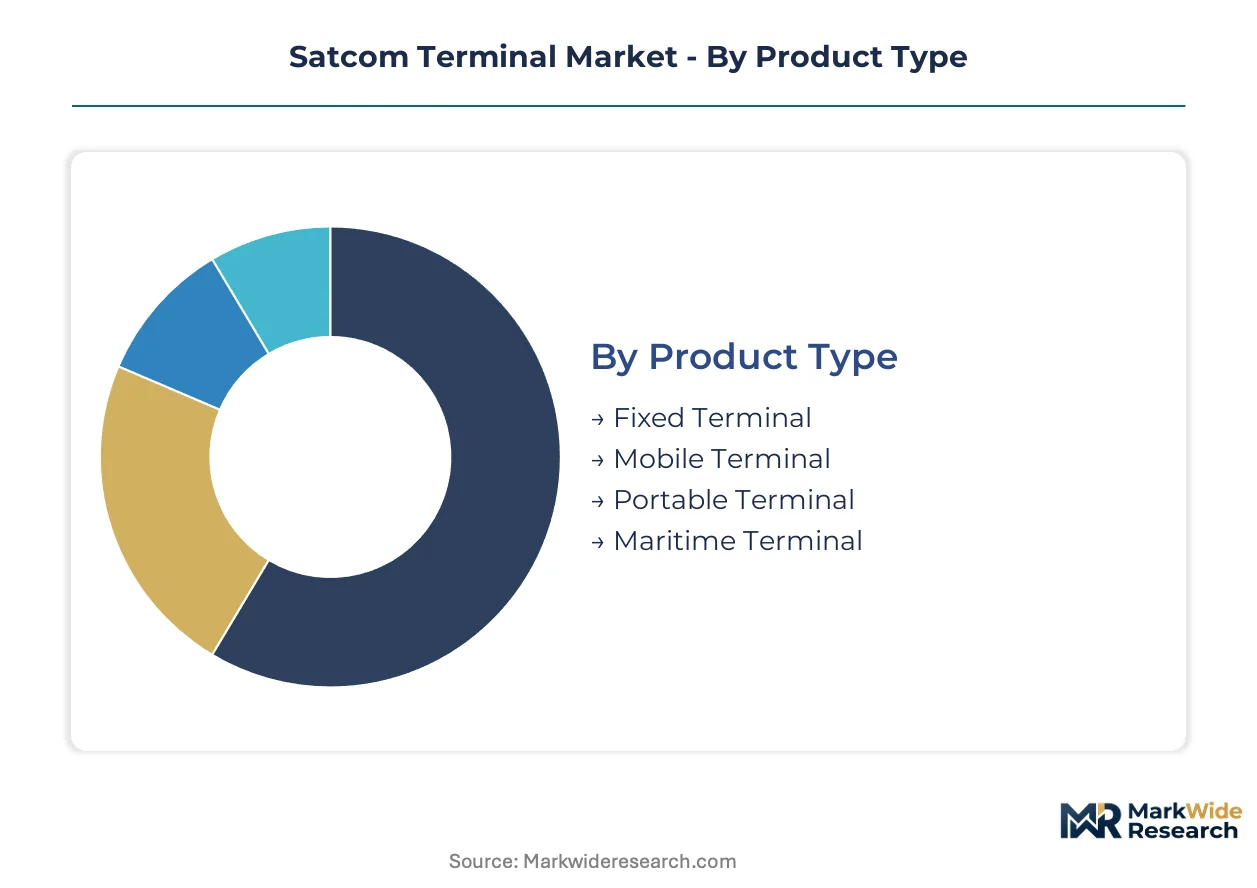
Satcom terminal segmentation reveals distinct procurement patterns across mobility requirements, frequency economics, and mission-critical use cases. Terminal specifications diverge sharply between fixed infrastructure deployments and expeditionary platforms where size, weight, and power constraints dominate vendor selection.
Product Type:
Use-case spectrum spans permanent ground stations through man-portable expeditionary units, with mobility requirements dictating antenna stabilization complexity and power amplifier thermal management.
- Fixed Terminal:Permanent ground stations employ large-aperture parabolic dishes with high-power amplifiers for hub connectivity and network aggregation. Energy sector operators in Texas and North Dakota favor these for remote drilling site backhaul where fiber deployment costs prove prohibitive.
- Mobile Terminal:Vehicle-mounted systems integrate stabilized antenna platforms for communications-on-the-move. NATO expeditionary forces in Poland and Romania are expanding procurement of these hardened suites for contested electromagnetic environments.
- Portable Terminal:Man-packable VSAT units under 25 kilograms enable rapid deployment for emergency response and special operations.
- Maritime Terminal:Stabilized platforms with salt corrosion resistance serve commercial shipping and naval vessels; premium pricing reflects gyroscopic stabilization and extended maintenance intervals.
Established volume favors Mobile Terminal; emerging adoption favors Portable Terminal.
Technology:
Frequency band selection trades propagation resilience against throughput density, with regulatory allocation frameworks determining where terminals may legally operate.
- Ku-band:Mature infrastructure with extensive satellite coverage supports broadcasting and enterprise networks. Maritime operators in the Mediterranean and North Atlantic maintain extensive Ku-band installations despite migration pressures.
- Ka-band:High-throughput spot beam architectures deliver order-of-magnitude capacity increases over legacy satellites. Commercial aviation connectivity providers over the continental United States are accelerating fleet retrofits as LEO constellations expand coverage density.
- C-band:Rain-fade resilience preserves military demand despite spectrum reallocation pressures for 5G terrestrial use.
- L-band:Narrowband services for IoT and emergency beacon applications operate in allocated spectrum with minimal interference susceptibility.
Legacy infrastructure concentration favors Ku-band; capacity expansion economics favor Ka-band.
Application:
Mission profiles determine terminal ruggedization standards, with aerospace and military segments imposing environmental qualification requirements absent in commercial deployments.
- Aerospace:In-flight connectivity terminals must satisfy FAA airworthiness certification and airline weight restrictions. Commercial aviation retrofit programs across United States carriers are driving demand for low-profile fuselage-mounted antennas.
- Military:NSA Type 1 encryption modules and anti-jam waveform resilience define procurement specifications. Space Force modernization budgets prioritize interoperable terminals across tactical and strategic echelons.
- Energy:Remote site monitoring and crew welfare communications for offshore platforms and pipeline networks.
- Broadcasting:Contribution and distribution networks for live event transmission and news gathering operations.
Procurement scale favors Military; installation growth rate favors Aerospace.
End User:
Customer type dictates contracting mechanisms, with government acquisitions emphasizing security certification and commercial buyers prioritizing service-level agreements.
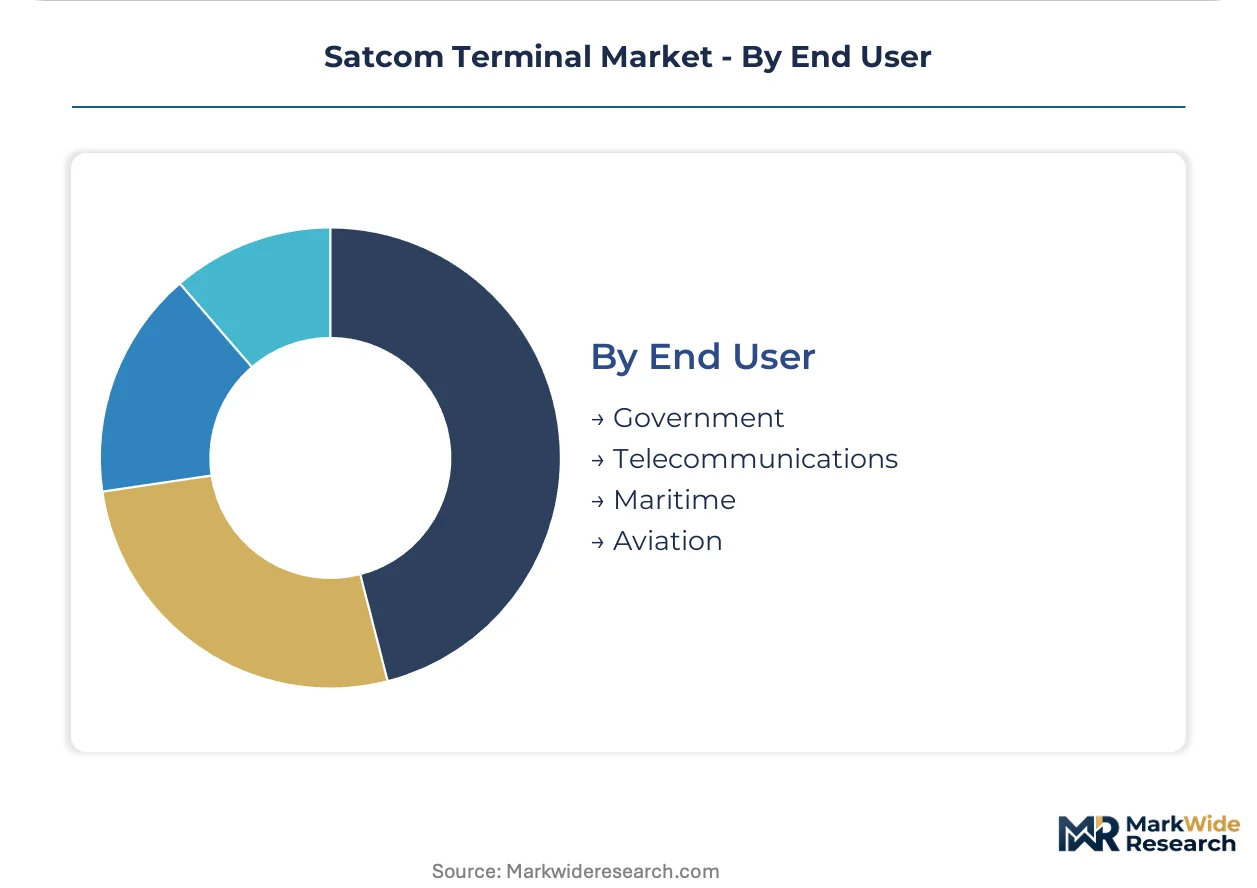
- Government:Classified program requirements drive NSA-certified encryption and sovereign supply chain mandates. Intelligence community deployments require 18-24 month validation cycles that compress product refresh windows.
- Telecommunications:Cellular backhaul and enterprise connectivity providers seek cost-optimized terminals for network extension. Rural broadband initiatives in unserved Appalachian regions are opening procurement channels for standardized VSAT platforms.
- Maritime:Commercial shipping fleets and naval operators demand stabilized terminals with global service coverage.
- Aviation:Airlines and business jet operators integrate connectivity as passenger amenity and operational tool.
Contract value concentration favors Government; volume expansion favors Telecommunications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German satcom terminal manufacturers export hardened military-grade systems to NATO member states across Eastern Europe. This trade corridor channels precision-engineered communication suites into Poland, Romania, and the Baltic states where allied defense procurement is accelerating.
United States
Space Force modernization budgets and commercial LEO constellation deployments are converging to drive terminal demand. The FCC governs terminal type certifications and spectrum coordination for non-geostationary systems. California's aerospace corridor hosts prime contractors developing interoperable tactical and strategic echelon terminals.
Germany
Defense agencies are expanding procurement of sovereign supply chain terminals for contested electromagnetic environments. The EU's Radio Equipment Directive mandates CE marking for electromagnetic compatibility. Bavaria's defense industrial base anchors European military-grade terminal production with dual-certification capabilities.
United Kingdom
Intelligence community deployments require NSA-certified encryption modules with extended validation cycles. The country's national communications regulator coordinates spectrum allocation for satellite services. London's defense procurement hub concentrates contract awards for platform-agnostic waveform licenses.
India
BharatNet program mandates and maritime security initiatives are opening procurement channels for portable VSAT terminals. TRAI governs spectrum allocation and terminal licensing frameworks. Gujarat's coastal manufacturing zones are emerging as assembly points for unserved district connectivity solutions.
Japan
Commercial aviation retrofit programs are driving demand for low-profile fuselage-mounted antennas. METI coordinates industrial policy for satellite communication equipment standards. The Kanto region's precision electronics cluster supplies RF components for next-generation terminal architectures.
Satcom Terminal Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a tiered vendor structure. The market consolidates around defense integrators bundling connectivity with managed network services, while component specialists retain positions in antenna stabilization and encryption modules. Three archetypes dominate: platform-agnostic system integrators, sovereign supply chain defense contractors, and commercial broadband terminal manufacturers. Competitive moves center on strategic partnerships for LEO constellation interoperability and backward integration into semiconductor fabrication for modem performance control.
Within the defense-contractor archetype, Thales Group and L3Harris Technologies exemplify positioning around sovereign supply chains and NSA-certified encryption layers respectively. Viasat Inc. occupies a position among vertically integrated players controlling in-house semiconductor fabrication. These three entities represent distinct strategic vectors: European defense sovereignty, intelligence community security certification, and captive modem technology development.
| Leading Market Players |
|---|
| Viasat Inc. |
| Thales Group |
| L3Harris Technologies |
| Hughes Network Systems |
| Gilat Satellite Networks |
| Intellian Technologies |
| Cobham Limited |
| General Dynamics Corporation |
| Honeywell International Inc. |
| Others |
Value Network & Pricing Analysis
Bavaria's defense industrial base concentrates phased array manufacturing capacity for NATO-hardened terminals, translating foundry bottlenecks into sustained pricing power for GaN-on-SiC power amplifier modules. This geographic concentration shapes how terminal OEMs negotiate component costs against fixed-price government contracts.
Pricing Analysis
Cost-plus contracts with gallium nitride wafer indexation dominate defense procurement, insulating prime contractors from substrate volatility while exposing commercial maritime buyers to spot-market swings. Price differentiation rests on NSA Type 1 certification grade and sovereign supply chain documentation, with intelligence community deployments commanding substantial premiums over standard enterprise tiers. Pricing pressure stems from LEO constellation operators commoditizing broadband access terminals for maritime and aviation retrofit programs. Commercial telecommunications buyers exhibit highest price sensitivity, while Space Force modernization budgets tolerate premium positioning for anti-jam waveform resilience.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from California aerospace primes are squeezing tier-two RF component suppliers, compressing working capital cycles for antenna stabilization vendors. Manufacturing concentrates in the United States, Germany, and Japan, with each hub feeding distinct certification ecosystems. Critical inputs include GaN-on-SiC wafers, precision gyroscopic stabilization mechanisms, and ITAR-restricted encryption modules. Single-source vulnerability runs through specialized foundries serving phased array fabrication. Distribution runs through system integrators bundling terminals with managed network services rather than discrete hardware channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Terminal procurement is shifting toward platform-agnostic waveform licensing, creating platform-economics dynamics where interoperability investments determine ecosystem capture. The convergence of civilian LEO constellations with military requirements is collapsing traditional hardware-software boundaries.
For Market Incumbents: Entrench firmware update velocity as the primary defensive moat against software-defined radio entrants, prioritizing backward integration into semiconductor fabrication to control modem performance across Ka and Ku frequencies. Consolidate vendor relationships with Space Force program offices around service-based contracting models that bundle connectivity with terminal hardware, neutralizing pure-play OEM competition. For New Entrants and Emerging Players: India's unserved coastal districts under BharatNet mandates offer the most penetrable white-space for portable VSAT terminal deployment, with TRAI licensing frameworks creating accessible procurement channels absent in saturated NATO markets. Target maritime retrofit programs for commercial shipping fleets seeking Ka-band migration paths from legacy Ku infrastructure, leveraging modular flat-panel architectures to bypass stabilized gimbal incumbency. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated players with captive modem development and in-house GaN fabrication capabilities, as software-defined architectures compress product lifecycles and reward firmware-centric differentiation. Long-term viability hinges on dual-use technology convergence enabling amortization across commercial and defense product lines. The signal to watch is FCC terminal certification timeline compression for LEO constellation interoperability, indicating which platform ecosystems will achieve scale.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Semiconductor Fabrication | Viasat's captive modem production controls performance across Ka and Ku frequencies. |
| Platform-Agnostic Waveform Licensing | Defense integrators are displacing standalone OEMs through service-based contracting models. |
| Dual-Certification for NATO Markets | Thales leverages Bavarian production to satisfy CE marking and sovereign supply mandates. |
| LEO Constellation Interoperability Partnerships | Terminal vendors bundling Starlink or OneWeb access capture maritime retrofit demand. |
| NSA Type 1 Encryption Module Development | L3Harris differentiates through intelligence community validation cycles competitors cannot replicate. |
Research Methodology
Desk research of FCC spectrum allocation filings, NATO procurement databases, and ITU coordination records preceded structured interviews with Space Force program officers, terminal OEM product managers, GaN foundry operations directors, and maritime fleet connectivity managers. Primary fieldwork with defense integrators and commercial constellation operators was cross-validated against secondary sources including SEC 10-K disclosures, EU Radio Equipment Directive implementation guidance, and customs trade data for satellite communication equipment. Bottom-up terminal shipment estimates were triangulated against top-down addressable market calculations derived from LEO constellation deployment schedules.
Assumptions held fixed include current FCC non-geostationary satellite service frameworks, NATO defense procurement continuity, and gallium nitride substrate supply constraints from specialized foundries across the analysis window. Segmentation modeling incorporated product type mobility requirements, frequency band economics, application ruggedization standards, and end-user contracting mechanisms. CAGRs were derived from regression analysis of historical procurement patterns against projected constellation coverage expansion. Forecast inputs included Space Force modernization budget trajectories and commercial aviation retrofit program announcements.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by commercial LEO operators or sudden GaN foundry capacity expansion would shift outcomes beyond modeled ranges. Macroeconomic defense budget contraction, ITU spectrum reallocation, or breakthrough optical ground station technology would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Diameter Signaling Market
Telecommunications
5G MVNO Market
Telecommunications
Turkey Telecom Market
Telecommunications
Kuwait Telecom Market
Telecommunications
US Voice-Over LTE (Volte) Market
Telecommunications
Middle East and Africa Telecom Expense Management Market
Telecommunications
Germany Critical Communication Market
Telecommunications
TV White Space Spectrum Market
Telecommunications
Vietnam ICT Market
Telecommunications
DECT System Market
Telecommunications
Belgium Telecom Market
Telecommunications
Poland Telecom Market
Telecommunications
Russia ICT Market
Telecommunications
Oman Telecom Market
Telecommunications
Global IP Phone Market
Telecommunications
Promotional Sms Market