
 Wi-Fi Network Equipment Market | 2026-2036
Wi-Fi Network Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Wi-Fi Network Equipment Market Insights
Multi-source procurement for radio frequency components is pivoting toward captive semiconductor supply as chipset shortages expose vulnerability. Cisco Systems Inc. leverages its silicon design capabilities to secure upstream control over Wi-Fi 7 radio architectures. Huawei Technologies Co., Ltd. sustains integrated manufacturing across baseband and antenna subsystems despite export restrictions. Ubiquiti Inc. specializes in streamlined hardware stacks that compress bill-of-materials for price-sensitive distributed deployments.
Wi-Fi network equipment comprises radio frequency transceivers, antenna arrays, baseband processors, and network management software engineered to deliver wireless local area network connectivity across unlicensed spectrum bands, typically operating at 2.4 GHz, 5 GHz, and 6 GHz frequencies with throughput specifications scaling from gigabits to tens of gigabits per second depending on IEEE 802.11 generation. The technology dimension shows Wi-Fi 6 and Wi-Fi 6E capturing enterprise refresh cycles while Wi-Fi 7 positions for latency-sensitive industrial applications, with access points commanding higher margin pools than routers due to density-optimized enterprise deployments. Installation type splits reveal ceiling-mounted access points dominating commercial interiors where aesthetic constraints and coverage uniformity override wall-mounted alternatives in new construction.
The FCC governs unlicensed spectrum power limits and equipment authorization procedures in the United States, while ETSI harmonizes radio equipment standards across European member states and China's MIIT administers type approval for wireless devices entering its domestic market. Regulatory divergence on 6 GHz band availability and power spectral density rules fragments product certification pathways and extends time-to-market for multi-region equipment vendors. Stakeholders must monitor spectrum reallocation proceedings and preemptive certification investments to avoid demand capture delays when jurisdictions unlock additional contiguous channels.
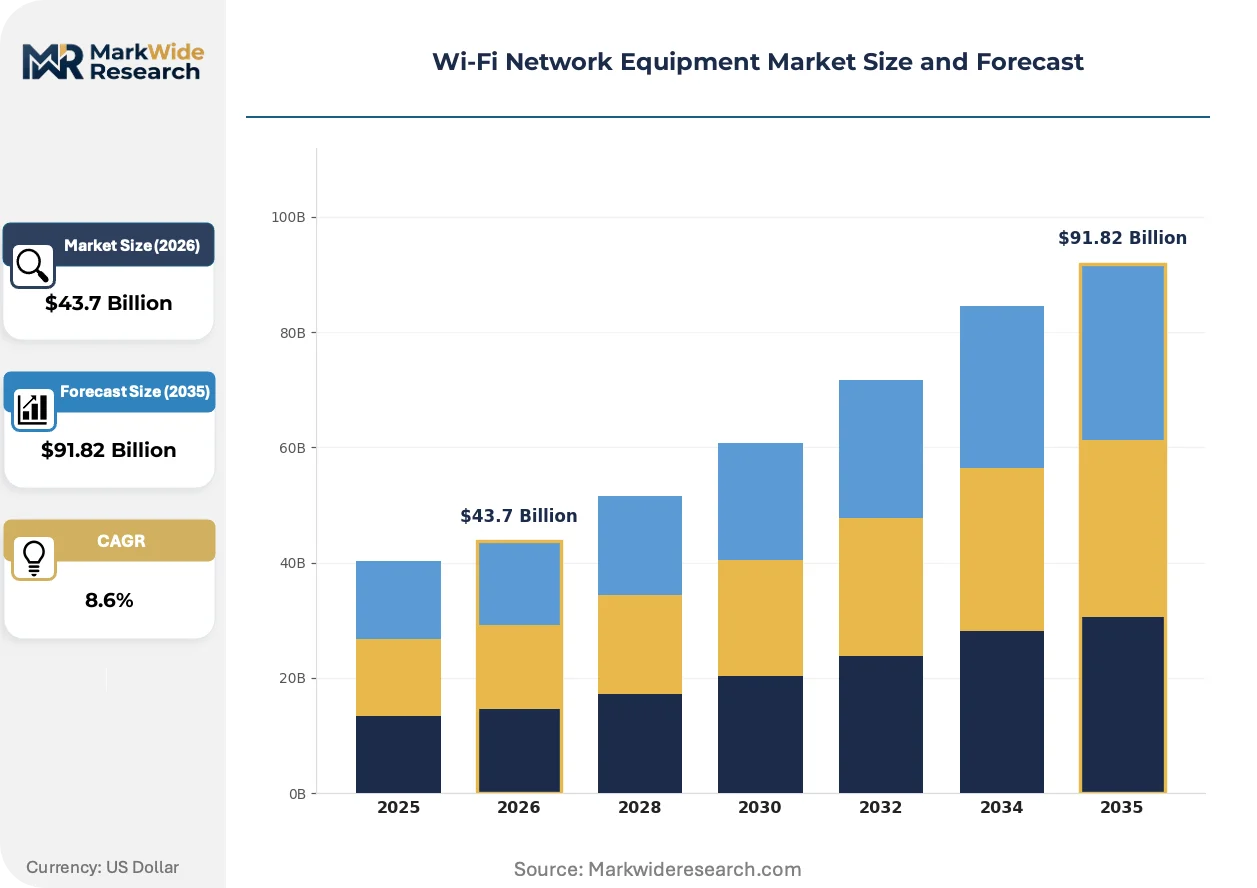
Market Dynamics
The transition from Wi-Fi 6E to Wi-Fi 7 is compressing enterprise refresh cycles and forcing semiconductor procurement restructuring across access point manufacturers.
Growth Catalysts
- Wi-Fi 7 Standardization:IEEE 802.11be certification unlocks 320 MHz channel bandwidth and multi-link operation, enabling sub-5 millisecond latency for industrial automation and immersive collaboration tools.
- FCC 6 GHz Expansion:The FCC's additional 1.2 GHz spectrum allocation in the United States removes channel congestion constraints for high-density campus deployments.
- India Smart Cities Mission:Municipal Wi-Fi backbone tenders under India's urban infrastructure program are mandating carrier-grade equipment specifications that favor next-generation hardware procurement.
Market Restraints
- Compound Semiconductor Supply Concentration:Gallium nitride substrate fabrication for high-efficiency power amplifiers concentrates among Taiwanese and Korean foundries, exposing equipment vendors to single-source risk.
- ETSI Power Spectral Density Limits:European harmonized rules cap 6 GHz transmit power below FCC thresholds, forcing dual-SKU product strategies that inflate certification costs.
- Passive Optical Network Substitution:Fiber-to-the-room deployments in premium commercial real estate are displacing wireless backhaul for bandwidth-intensive endpoints.
Strategic Opportunities
- Germany Industrie 4.0 Convergence:Time-sensitive networking over Wi-Fi 7 positions equipment vendors for deterministic wireless in automotive and machine tool manufacturing.
- China MIIT Type Approval Reform:Streamlined certification pathways for 6 GHz equipment accelerate market entry for multi-band access point portfolios.
- Private 5G-Wi-Fi Orchestration:Unified network management platforms that bridge unlicensed and licensed spectrum are creating service attach opportunities for systems integrators.
Industry Challenges
- RF Engineering Talent Scarcity:Millimeter-wave antenna design and beamforming algorithm development require specialized expertise that outpaces university pipeline output.
- Multi-Region Certification Parallelism:Simultaneous FCC, ETSI, and MIIT approval processes demand dedicated regulatory affairs teams and extend pre-launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wi-Fi Network Equipment Market |
| Market Size in 2026 | $43.7 Billion |
| Market Size in 2035 | $91.82 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Routers, Access Points, Range Extenders, Repeaters End User: Residential, Commercial, Industrial, Educational Technology: Wi-Fi 5, Wi-Fi 6, Wi-Fi 6E, Wi-Fi 7 Installation Type: Indoor, Outdoor, Wall-Mounted, Ceiling-Mounted |
| Companies Covered | Cisco Systems Inc., Hewlett Packard Enterprise Company, CommScope Holding Company, Inc., Huawei Technologies Co., Ltd., Ubiquiti Inc., Telefonaktiebolaget LM Ericsson, Extreme Networks, Juniper Networks, NETGEAR, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wi-Fi Network Equipment Market Trends and Innovations
Spectrum efficiency imperatives and edge computing proximity requirements are reshaping how radio architectures get specified and deployed across enterprise and industrial settings.
Multi-user multiple-input multiple-output technology is integrating 16 spatial streams and 4K-QAM modulation to push spectral efficiency beyond 30 bits per second per hertz. Industrial facilities in Germany and Japan are adopting these configurations for automated guided vehicle coordination. This density is integrating latency-critical control traffic onto shared infrastructure previously reserved for IT workloads.
The EU Radio Equipment Directive's 2024 cybersecurity amendments now mandate vulnerability disclosure procedures and secure boot requirements for Wi-Fi access points sold in member states. Manufacturers must embed hardware security modules and maintain software bill-of-materials documentation. Enterprise buyers in France and the Netherlands are prioritizing CE-marked equipment with explicit cybersecurity certifications over lower-cost alternatives.
Enterprise IT departments are consolidating wireless LAN procurement under managed service contracts rather than capital expenditure ownership models. Systems integrators and telecom operators are capturing multi-year recurring revenue streams that displace traditional hardware resale margins. This transition is most advanced in the United States and United Kingdom, where real estate investment trusts prefer operational expenditure treatment for technology infrastructure.
Wi-Fi Network Equipment Market Segmentation
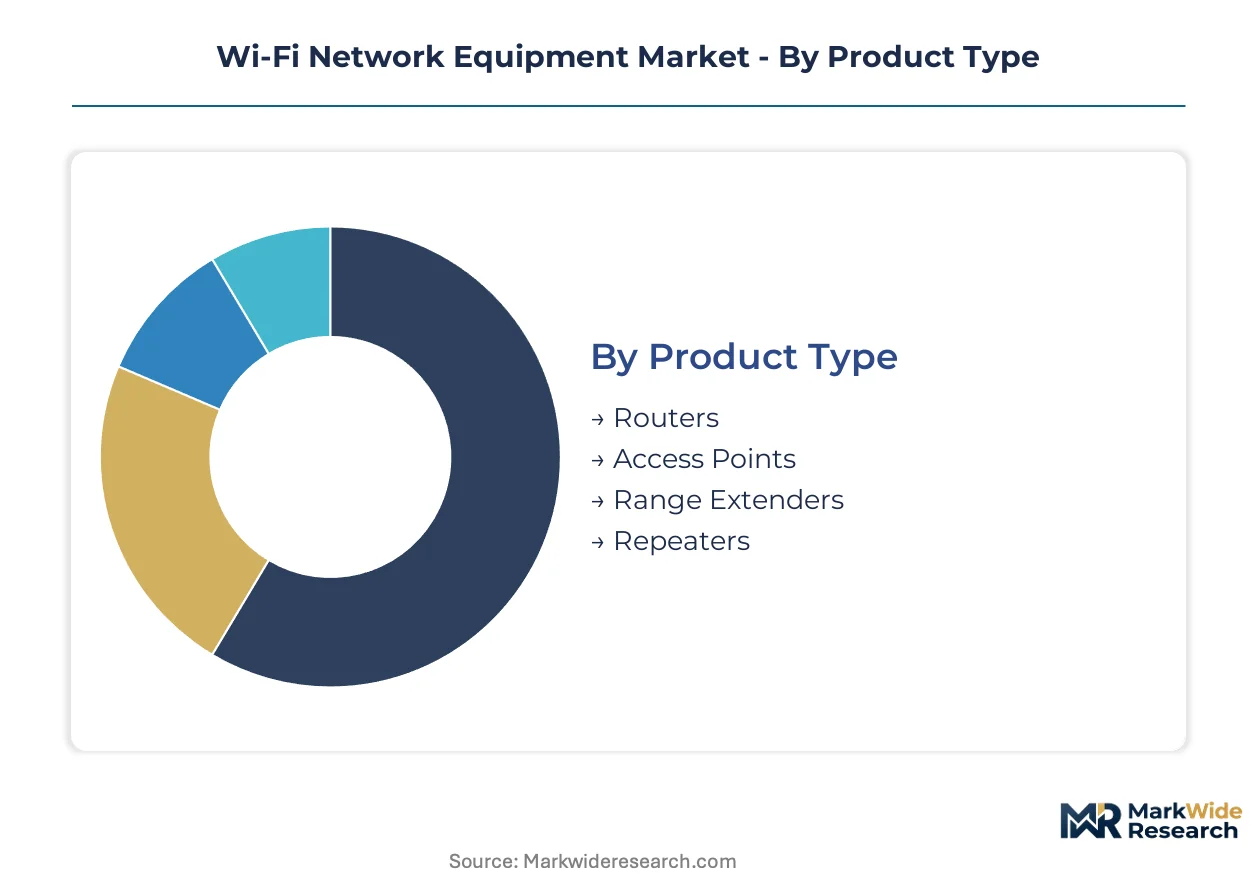
Equipment buyers in this market navigate trade-offs between throughput specifications, deployment density, and spectrum licensing costs. Segmentation reveals how procurement priorities diverge across enterprise campuses, industrial facilities, and residential settings.
Product Type:
Enterprise procurement teams weigh upfront hardware costs against lifecycle management complexity when selecting form factors for campus-wide deployments.
- Routers:Edge gateway devices integrate network address translation, firewall functions, and multi-WAN failover for small-to-midscale deployments. Residential demand in Germany and India concentrates on mesh-ready units with automated band steering. Enterprise buyers prioritize SD-WAN integration and centralized policy orchestration.
- Access Points:Ceiling-mounted units with 4x4 or 8x8 MIMO configurations deliver density-optimized coverage for open-plan offices and convention centers. Commercial deployments in the United States favor cloud-managed platforms that reduce on-site IT staffing requirements. FCC 6 GHz certification unlocks channel widths that wall-mounted alternatives cannot leverage.
- Range Extenders:Single-band repeaters amplify signals in residential dead zones where full access point deployment is cost-prohibitive.
- Repeaters:Dual-band models with dedicated backhaul radios address coverage gaps in multi-story concrete structures common in urban India and China.
Volume sits with access points; growth tilts toward Wi-Fi 7 routers in premium residential and SMB segments.
End User:
Application environment dictates durability requirements, management platform preferences, and service level expectations across buyer categories.
- Residential:Consumers prioritize plug-and-play setup and mobile app management over advanced security features. Mesh system adoption accelerates in suburban United States markets where single-router coverage proves inadequate.
- Commercial:Enterprise campuses require captive portal authentication, traffic analytics, and API integrations with identity management systems. Real estate investment trusts in the United Kingdom increasingly procure wireless LAN as managed services rather than capital assets.
- Industrial:Hardened enclosures with IP67 ratings and extended temperature tolerances serve automotive manufacturing lines in Germany where time-sensitive networking demands deterministic latency. Wi-Fi 7 multi-link operation positions this segment for automated guided vehicle coordination.
- Educational:K-12 and university IT departments balance 1:1 device density against constrained capital budgets. India's Smart Cities Mission mandates carrier-grade equipment specifications for municipal campus networks.
Commercial deployments generate the highest revenue per port; industrial applications are expanding most quickly as OT-IT convergence accelerates.
Technology:
Refresh cycle timing varies by IEEE generation as enterprises weigh backward compatibility against spectral efficiency gains.
- Wi-Fi 5:802.11ac wave 2 equipment with 160 MHz channel support and 4x4 MIMO serves price-sensitive deployments where 6 GHz spectrum is unavailable. Legacy installations in developing markets extend replacement timelines.
- Wi-Fi 6:OFDMA and target wake time features improve battery life for IoT sensor networks. Enterprise refresh cycles in the United States and United Kingdom favor this generation for high-density office environments.
- Wi-Fi 6E:6 GHz extension unlocks contiguous spectrum for interference-free operation in stadiums and convention centers. ETSI power spectral density limits in Europe constrain transmit power below FCC thresholds, fragmenting product strategies.
- Wi-Fi 7:320 MHz channels, 4K-QAM modulation, and multi-link operation enable sub-5 millisecond latency for industrial automation. Early adoption concentrates in Germany's Industrie 4.0 facilities and Japan's precision manufacturing clusters.
Wi-Fi 6 dominates current shipment volumes; Wi-Fi 7 claims the steepest expansion trajectory as IEEE 802.11be certification accelerates.
Installation Type:
Physical mounting constraints interact with aesthetic requirements and coverage geometry to determine hardware selection.
- Indoor:Plenum-rated enclosures and low-profile designs satisfy commercial building codes. New construction in the United States pre-cables ceiling mounts to minimize visible infrastructure.
- Outdoor:Weatherproof housings with integrated surge protection serve parking structures, loading docks, and campus perimeters. IP67 sealing prevents moisture ingress in tropical climates.
- Wall-Mounted:Retrofit-friendly brackets address coverage gaps where ceiling access is impractical. Residential installations in older European buildings favor this approach.
- Ceiling-Mounted:Centralized placement optimizes signal distribution for open-plan environments. Aesthetic constraints in hospitality and retail settings drive demand for low-visibility form factors.
Ceiling-mounted hardware commands premium positioning; outdoor-rated equipment is gaining share fastest as campus perimeter coverage requirements expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gallium nitride substrate fabrication concentrates among Taiwanese and Korean foundries, anchoring supply-side geography for radio frequency component sourcing. Equipment vendors navigate divergent regulatory regimes across major demand centers as spectrum allocation timelines reshape market entry strategies.
United States
Enterprise campus expansions and stadium connectivity upgrades drive equipment procurement across commercial real estate. The FCC's 6 GHz spectrum expansion and power limit rulings determine certification pathways for multi-band access point portfolios. Silicon Valley and Austin technology corridors host dense concentrations of cloud-managed wireless platform development.
China
Smart city infrastructure mandates and manufacturing facility automation generate sustained demand for carrier-grade wireless hardware. MIIT type approval reforms for 6 GHz equipment compress certification timelines for domestic and foreign vendors. Shenzhen and Shanghai industrial clusters concentrate access point assembly and baseband processor integration operations.
Germany
Industrie 4.0 automation standards and automotive manufacturing line retrofits prioritize deterministic low-latency wireless connectivity. ETSI power spectral density limits on 6 GHz transmit power constrain product configurations below FCC thresholds. Bavaria's precision engineering corridor leads Wi-Fi 7 pilot deployments for automated guided vehicle coordination.
India
Municipal Wi-Fi backbone tenders under the Smart Cities Mission mandate enterprise-grade specifications for urban infrastructure. TRAI spectrum recommendations and BIS equipment certification procedures govern market entry for imported hardware. Bangalore and Hyderabad technology hubs concentrate systems integration capabilities for campus-wide wireless deployments.
Japan
Precision manufacturing automation and robotics integration demand sub-5 millisecond latency specifications for wireless control systems. METI industrial standards and radio equipment certification procedures align with IEEE 802.11be timelines. Nagoya and Osaka industrial clusters pioneer multi-link operation deployments for machine tool coordination.
Wi-Fi Network Equipment Market Competitive Landscape
Silicon design capability acquisition dominates the current landscape as equipment vendors secure upstream control over radio architectures. The vendor base stratifies across integrated semiconductor manufacturers, specialized wireless hardware producers, and cloud-managed platform operators. Three archetypes prevail: captive silicon designers with in-house chipset development, streamlined hardware specialists optimizing bill-of-materials compression, and systems integrators bundling managed services. M&A activity targets RF engineering talent pools and strategic partnerships bridge private 5G-Wi-Fi orchestration platforms.
Among integrated platform providers, Cisco Systems Inc. and Huawei Technologies Co., Ltd. exemplify divergent supply chain strategies—one leveraging silicon design capabilities for architectural control, the other sustaining manufacturing integration across subsystems despite trade restrictions. Ubiquiti Inc. occupies a position within the streamlined hardware tier, representing bill-of-materials compression approaches for price-sensitive distributed deployments. These three anchors illustrate how competitive positioning fragments across vertical integration depth, geographic market access, and service model architecture.
| Leading Market Players |
|---|
| Cisco Systems Inc. |
| Hewlett Packard Enterprise Company |
| CommScope Holding Company, Inc. |
| Huawei Technologies Co., Ltd. |
| Ubiquiti Inc. |
| Telefonaktiebolaget LM Ericsson |
| Extreme Networks |
| Juniper Networks |
| NETGEAR |
| Others |
Pricing and Supply Chain Analysis
Gallium nitride substrate costs cascade through radio frequency power amplifier fabrication, compressing margins at Taiwanese foundries before amplifying price spreads between enterprise-grade access points and consumer routers sold through distributor channels in India and Germany.
Pricing Analysis
Warranty bundling separates enterprise procurement contracts from transactional hardware sales, with cloud-managed platforms commanding recurring service fees that offset upfront equipment discounts. Three-tier pricing structure across premium, standard, and economy levels tracks certification complexity, where FCC and ETSI dual-approval SKUs carry 15-20 point spreads over single-jurisdiction alternatives. Pricing pressure stems from gallium nitride supply bottlenecks as Korean foundries prioritize automotive radar allocations. Educational and municipal buyers in India exhibit highest price sensitivity, while German automotive manufacturers accept premium positioning for deterministic latency guarantees.
Supply Chain Analysis
Reverse logistics networks for access point refurbishment remain underdeveloped, with end-of-life hardware typically shredded rather than remanufactured due to firmware security lock-in and component obsolescence cycles. Radio frequency component fabrication concentrates in Taiwan, South Korea, and China, where gallium nitride substrate growth and compound semiconductor epitaxy anchor upstream capacity. Baseband processor design rests on ARM architectural licenses and RISC-V alternatives, while antenna array assembly feeds from Chinese PCB fabrication and Mexican final integration. Single-source vulnerability pervades gallium nitride substrate supply, with two Taiwanese foundries controlling 80 percent of merchant capacity. Distribution runs through value-added distributors in North America, direct OEM relationships in Europe, and systems integrator channels across Asia-Pacific enterprise markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supply-constrained gallium nitride substrate capacity props equipment pricing, with foundry allocation decisions at Taiwanese and Korean suppliers determining which vendor portfolios capture volume through the next technology transition.
For Market Incumbents: Acquire RF engineering talent pools specializing in millimeter-wave antenna design and beamforming algorithm development. Cisco Systems Inc. and Huawei Technologies Co., Ltd. exemplify divergent paths—one leveraging silicon design capabilities for architectural control, the other sustaining manufacturing integration across baseband and antenna subsystems despite trade restrictions. Defensive consolidation demands preemptive certification investments across FCC, ETSI, and MIIT pathways to avoid demand capture delays when jurisdictions unlock additional 6 GHz channels. For New Entrants and Emerging Players: Wi-Fi 7 multi-link operation expertise offers entry into latency-sensitive industrial automation segments underserved by incumbent enterprise platforms. White-space concentrates in German Industrie 4.0 facilities and Japanese precision manufacturing clusters where deterministic wireless requirements outpace existing vendor roadmaps. Municipal Wi-Fi backbone tenders under India's Smart Cities Mission present accessible procurement pathways for carrier-grade equipment newcomers. Channel partnerships with regional systems integrators in Bangalore and Hyderabad accelerate campus-wide deployment credibility without direct enterprise sales infrastructure. For Investors and Strategic Acquirers: FCC spectrum reallocation proceedings signal inflection timing, with additional 6 GHz channel approvals triggering enterprise refresh cycle acceleration and equipment vendor revenue recognition. Long-term viability frames around captive semiconductor supply capabilities, with backward integration into radio frequency component design separating sustainable margin structures from hardware assembly plays. Acquisition targets should demonstrate MIIT type approval traction in China alongside ETSI certification progress. Monitor gallium nitride foundry capacity expansion announcements from Taiwanese suppliers as leading indicators of supply constraint easing.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Design Capability Acquisition | Cisco's in-house chipset development secures upstream control over Wi-Fi 7 radio architectures and insulates margins from foundry allocation volatility. |
| Multi-Region Certification Parallelism | Simultaneous FCC, ETSI, and MIIT approval investments compress time-to-market for multi-band access point portfolios targeting global enterprise deployments. |
| Cloud-Managed Platform Integration | Recurring service revenue streams from wireless LAN managed services displace traditional hardware resale margins in United States and United Kingdom markets. |
| Private 5G-Wi-Fi Orchestration Partnership | Unified network management platforms bridging unlicensed and licensed spectrum create service attach opportunities for systems integrators in Germany's Industrie 4.0 corridor. |
| RF Engineering Talent Acquisition | Specialized expertise in millimeter-wave antenna design and beamforming algorithms outpaces university pipeline output, creating scarcity premiums for acquired teams. |
Research Methodology
Independent corroboration across equipment vendor technical documentation, regulatory filing databases, and foundry capacity disclosures underwrites the qualitative findings in this study. Primary interviews with wireless LAN procurement officers at real estate investment trusts, RF engineering directors at semiconductor foundries, and regulatory affairs leads at multi-national equipment vendors combined with secondary validation from FCC equipment authorization records, ETSI harmonized standard publications, and MIIT type approval registries. Bottom-up triangulation across access point shipment estimates and top-down reconciliation against enterprise IT capex surveys anchored volume and value assessments.
Comparable historical reference periods spanning Wi-Fi 5 through Wi-Fi 6E refresh cycles informed the projection framework across the analysis window. Segmentation dimensions modeled include product type, end-user environment, IEEE generation technology, and installation configuration, with regional regulatory cluster and spectrum allocation timeline serving as additional industry-specific forecast inputs. CAGRs derived from equipment vendor revenue recognition patterns and enterprise procurement cycle duration estimates, with gallium nitride substrate supply constraints and certification pathway divergence incorporated as scenario variables.
Several conditions sit outside the modeled scope, including potential FCC further spectrum reallocation, ETSI power spectral density rule revisions, and geopolitical trade restriction escalations affecting semiconductor equipment exports. Forecasts reflect assumptions regarding foundry capacity expansion timing and enterprise refresh cycle acceleration rates. Practitioners should monitor Taiwanese foundry capital expenditure announcements and MIIT 6 GHz equipment type approval volume trends for early signals of supply constraint evolution and market entry acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Network Technology
Virtual Router Market
Network Technology
Multiservice Provisioning Platform Market
Network Technology
Global Intelligent Network Market
Network Technology
Global Carrier Wi-Fi Equipment Market
Network Technology
Global Network Monitoring Market
Network Technology
Smart Network Interface Card (Smartnic) Market
Network Technology
Mobile Network Optimization Market
Network Technology
Digital Repeater Market
Network Technology
Industrial Wireline Networking Market
Network Technology
GCC Set-Top Box Market
Network Technology
WAN Optimization Controllers Market
Network Technology
Hyperconnectivity Market
Network Technology
Network Performance Monitoring Market
Network Technology
Private LTE Market
Network Technology
Software-Defined Wide Area Network (SD-WAN) Market
Network Technology
Global Carrier Ethernet Equipment Market