
 Global in-Building Wireless Market | 2026-2036
Global in-Building Wireless Market Size, Share, and Industry Trends Forecast 2026-2036
Global in-Building Wireless Market Foresight
Carrier-grade reliability standards is bifurcating the competitive landscape between premium infrastructure vendors and cost-optimized challengers. CommScope Holding Company leverages its deep cable and connectivity heritage to dominate North American stadium and arena deployments. Nokia Corporation anchors European private wireless momentum through its Digital Automation Cloud platform for manufacturing and logistics campuses. Ericsson differentiates in Asia-Pacific through integrated radio and baseband portfolios purpose-built for dense urban commercial complexes.
In-building wireless denotes distributed radio frequency infrastructure engineered to deliver seamless cellular and data connectivity across structurally complex indoor environments, typically operating between 600 MHz and 6 GHz with power budgets calibrated to overcome signal attenuation from concrete, low-emissivity glass, and metallic building materials. Distributed Antenna Systems retain the largest installed base across legacy commercial real estate, though 5G small cells are capturing the fastest growth trajectory as building owners prioritize low-latency edge capacity over passive coaxial architectures. Wi-Fi and LTE coexistence defines current technology procurement, with NB-IoT emerging as a specialized layer for smart building sensor backhaul in government and educational facilities.
The FCC governs spectrum allocation and device certification for in-building systems across the United States, while the EU AI Act and GDPR impose data governance obligations on connected building platforms processing user location and behavioral analytics. ETSI standards harmonize radio equipment compliance across European member states, reducing fragmentation for multi-national facility operators. Stakeholders must monitor evolving national spectrum auctions and building code mandates to anticipate where private network deployment timelines will compress or elongate.
Market Dynamics
The transition from passive Distributed Antenna Systems to active 5G small cell architectures is compressing deployment timelines and forcing infrastructure vendors to recalibrate hardware margins against software-defined radio value capture.
Growth Catalysts
- CBRS Spectrum Framework:The FCC's three-tiered priority access system in the United States unlocks licensed 3.5 GHz deployments for private industrial networks without carrier intermediation.
- Healthcare Campus Connectivity:Hospital systems across Germany and the United States are commissioning dedicated 5G infrastructure to support surgical robotics and real-time patient monitoring.
- Industrial IoT Convergence:Manufacturing facilities in Japan are converging Wi-Fi 6E and private 5G under unified network management platforms.
Market Restraints
- Semiconductor Supply Concentration:RF front-end module fabrication concentrates in Taiwan, exposing infrastructure vendors to geopolitical disruption risk.
- Copper and Coaxial Cable Cost Volatility:Legacy DAS retrofits remain tethered to copper pricing swings that compress project margins.
- Building Code Fragmentation:Fire safety and RF exposure regulations vary across municipal jurisdictions, elongating permitting timelines.
Strategic Opportunities
- India Smart City Mandates:The country's urban renewal programs specify in-building wireless as mandatory infrastructure for commercial and transit hubs.
- Neutral Host Model Expansion:Third-party infrastructure operators in the United Kingdom are capturing multi-tenant office and retail deployments.
- AI-Driven Network Optimization:Machine learning-based RF planning tools are reducing site survey costs for stadium and arena projects.
Industry Challenges
- RF Engineering Talent Scarcity:Specialized small cell deployment expertise concentrates among legacy carrier engineering teams, constraining vendor scaling.
- Multi-Vendor Integration Complexity:Interoperability testing between radio units, baseband controllers, and building management systems extends commissioning cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global in-Building Wireless Market |
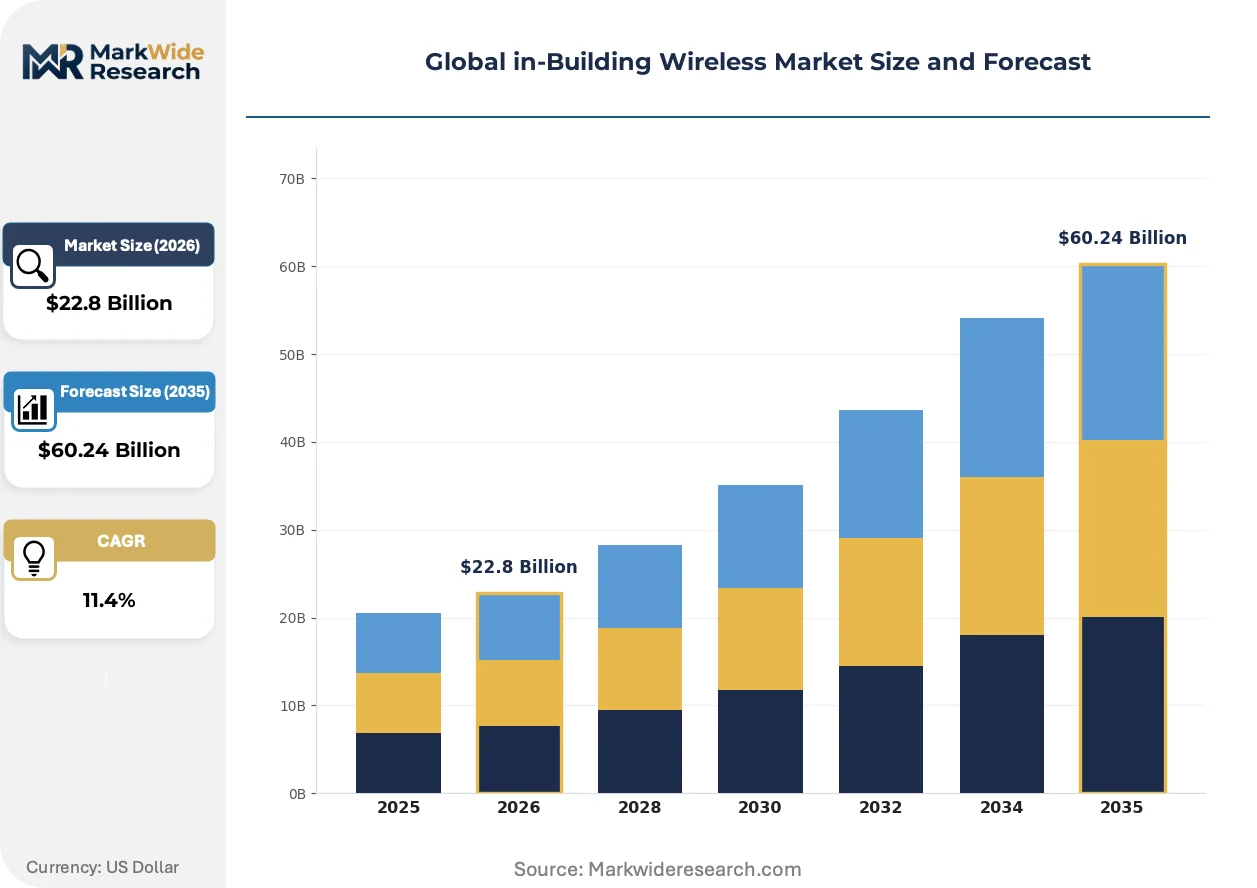
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $60.24 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Distributed Antenna Systems, Small Cells, Repeaters, Signal Boosters, Antenna Systems Technology: Wi-Fi, LTE, 5G, ZigBee, Bluetooth, NB-IoT Application: Commercial Buildings, Educational Institutions, Government Facilities, Sports Arenas, Transportation Hubs End User: Telecommunication Providers, Facility Management Companies, Network Integrators, Event Organizers |
| Companies Covered | CommScope Holding Company, Nokia Corporation, Huawei Technologies Co., Ltd., Ericsson, Corning Incorporated, Samsung Electronics Co., Ltd., Airspan Networks, ZTE Corporation, Comba Telecom Systems Holdings Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global in-Building Wireless Market Shifts & Advancements
Open RAN architectures are decoupling hardware and software procurement, enabling building owners to source radio units and network management layers from separate vendors rather than locked integrated stacks.
Passive coaxial infrastructure is fragmenting the installed base of legacy commercial real estate as property managers prioritize fiber-fed active antenna nodes. Large-format retail and logistics warehouse operators in the United States are accelerating replacement cycles. The shift compresses maintenance revenue for incumbent DAS specialists while opening systems integration contracts.
The EU AI Act imposes algorithmic transparency requirements on connected building platforms processing occupant location analytics. Facility operators deploying behavioral tracking for space optimization must now document automated decision-making logic. German and French commercial real estate investment trusts are front-loading compliance costs into 2025 procurement budgets.
Building owners are unbundling network infrastructure ownership from carrier service contracts, electing to self-finance private 5G deployments and lease neutral host capacity to multiple mobile operators. This capital expenditure shift concentrates in United States healthcare and university campuses. The model transfers operational risk from carriers to property developers while preserving quality-of-service guarantees through SLA-backed roaming agreements.
Global in-Building Wireless Market Segmentation
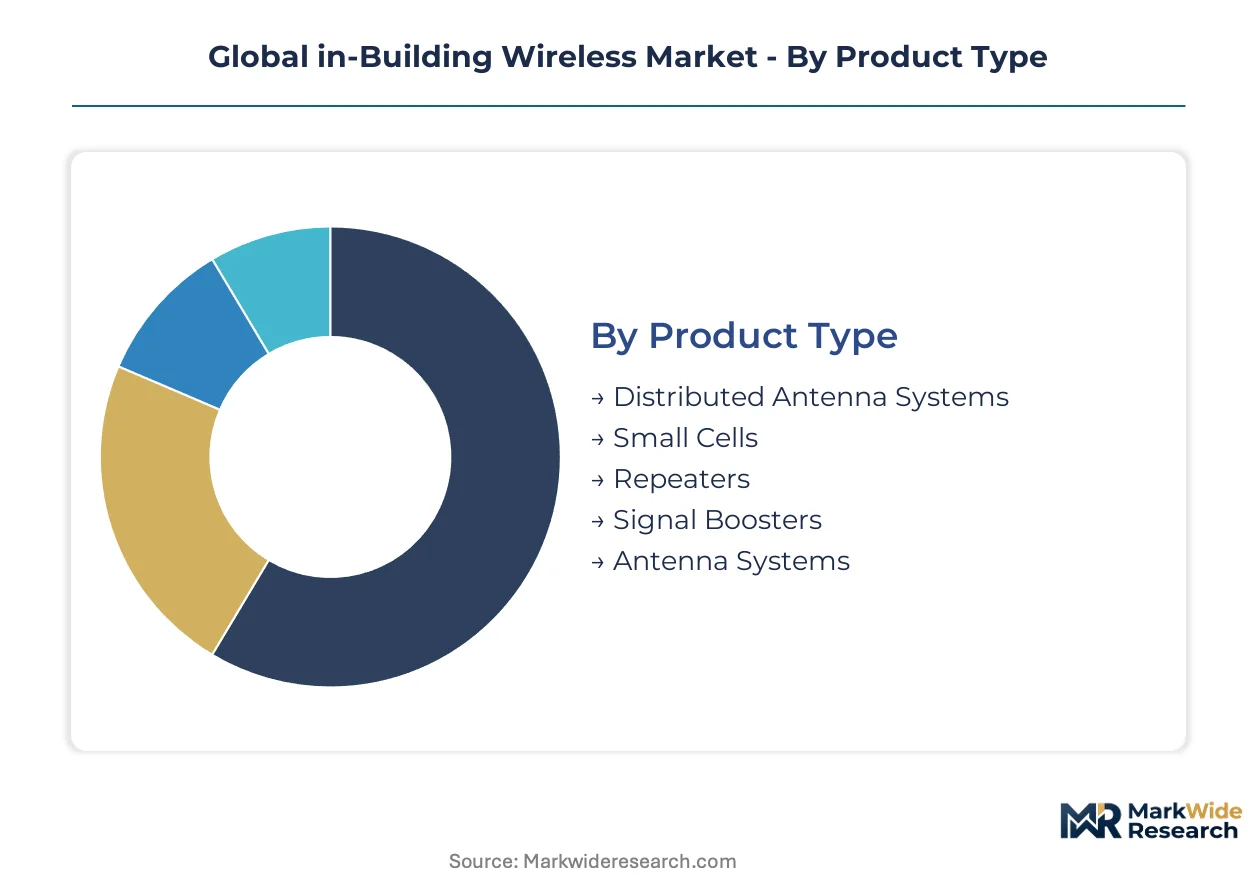
Segmentation in the in-building wireless market reveals how procurement channels, technology maturity, and facility-specific requirements shape vendor go-to-market strategies. Understanding these divides clarifies where infrastructure investments concentrate and which deployment models capture margin.
Product Type:
Channel flow differs sharply: DAS and small cells move through carrier-integrator partnerships, while repeaters and signal boosters reach end-users via direct-to-facility distributors and e-commerce platforms.
- Distributed Antenna Systems:Passive coaxial fiber-fed architectures distribute RF signals through ceiling-mounted antennas. Hospital systems in Germany and the United States commission DAS retrofits for basement-to-roof coverage where concrete and metallic shielding blocks macro signals.
- Small Cells:Active radio nodes with integrated baseband processing deliver targeted capacity in high-density zones. Industrial manufacturing campuses across Japan and Germany deploy private 5G small cells under unified network management platforms for sub-10 millisecond latency.
- Repeaters:Bi-directional amplifiers extend donor cell signals into coverage shadows without fiber backhaul. Retail chains in suburban United States markets source repeaters through facility management procurement channels.
- Signal Boosters:Consumer-grade and enterprise amplifiers strengthen weak outdoor signals for indoor redistribution. Small commercial buildings in India source boosters through TRAI-certified installation contractors.
- Antenna Systems:Discrete radiating elements including panel, dome, and directional configurations mount to structural elements. Stadium projects in the United Kingdom specify multi-band antenna arrays from systems integrators.
By volume, Distributed Antenna Systems leads installed base. By growth pace, Small Cells is expanding most quickly as building owners prioritize edge capacity over passive architectures.
Technology:
Cost tiering separates premium licensed spectrum deployments from unlicensed alternatives, with 5G and LTE commanding hardware premiums against Wi-Fi and short-range protocols.
- Wi-Fi:Unlicensed 2.4 GHz and 5 GHz connectivity for general data offload and guest access. Educational institutions in the United States bundle Wi-Fi 6E with private 5G under converged procurement.
- LTE:Licensed 4G cellular for mission-critical voice and guaranteed quality-of-service data. Healthcare campuses retain LTE as fallback layer during 5G transition phases.
- 5G:New radio interfaces across sub-6 GHz and millimeter-wave bands enable ultra-reliable low-latency communication. Manufacturing facilities in Japan and Germany commission standalone 5G for automated guided vehicle coordination.
- ZigBee:Low-power mesh protocol for building automation sensor networks. Government facilities deploy ZigBee alongside cellular for segregated operational technology traffic.
- Bluetooth:Short-range protocol for indoor positioning and asset tracking beacons. Retail environments in the United Kingdom integrate Bluetooth Low Energy with neutral host cellular.
- NB-IoT:Narrowband cellular for low-data-rate sensor backhaul in smart building deployments. Municipal transit hubs specify NB-IoT for environmental monitoring under ETSI harmonized standards.
LTE dominates current procurement spend. 5G is climbing the fastest as private network mandates accelerate.
Application:
Customer type dictates sales cycle length and technical complexity, with sports arenas and transportation hubs requiring longest commissioning timelines against standardized commercial building templates.
- Commercial Buildings:Multi-tenant office and retail complexes requiring neutral host capacity. Property developers in the United States self-finance infrastructure and lease to multiple carriers.
- Educational Institutions:University campuses with distributed dormitory, classroom, and research facilities. Indian smart city mandates specify in-building wireless as compulsory for transit-adjacent academic hubs.
- Government Facilities:Secure installations with classified and unclassified network segregation requirements. EU AI Act compliance costs front-load into procurement budgets for behavioral analytics platforms.
- Sports Arenas:High-density venues with burst capacity demands during events. Stadium projects in North America source carrier-grade DAS through CommScope integrator relationships.
- Transportation Hubs:Airports, rail terminals, and multimodal transit centers with continuous mobility requirements. German industrial regions retrofit legacy rail infrastructure with converged Wi-Fi and 5G.
Commercial Buildings leads by deployment count. Sports Arenas shows steepest expansion trajectory as venue operators monetize fan connectivity.
End User:
Supply concentration varies: telecommunication providers aggregate demand for standardized equipment, while event organizers and facility managers fragment procurement across project-specific integrators.
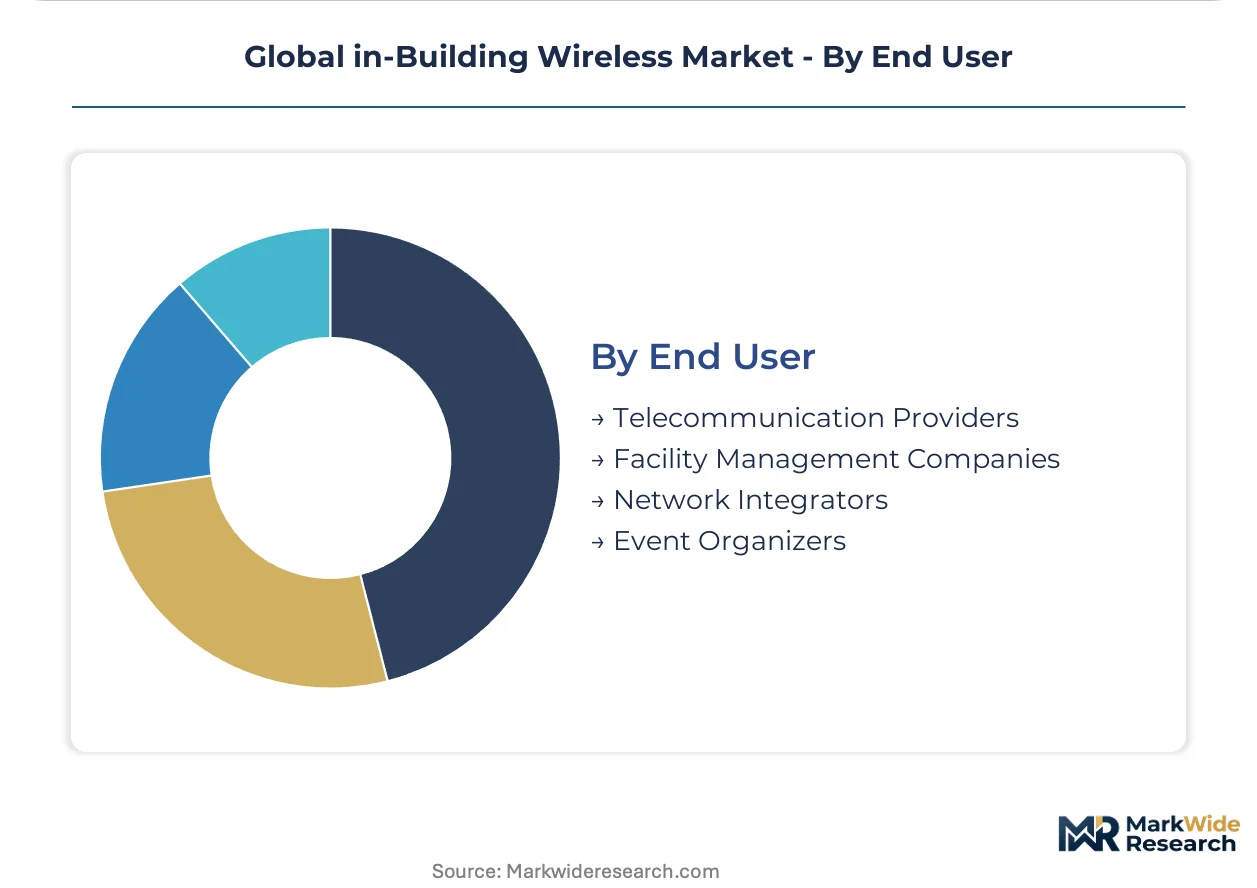
- Telecommunication Providers:Mobile network operators specifying carrier-grade infrastructure for subscriber retention. Verizon and AT&T in the United States drive CBRS small cell specifications.
- Facility Management Companies:Third-party operators maintaining multi-tenant building systems. UK-based neutral host operators capture retail and office deployments.
- Network Integrators:Systems contractors delivering turnkey design-build-commission services. Ericsson-anchored integrators dominate Asia-Pacific dense urban projects.
- Event Organizers:Temporary infrastructure specialists serving single-venue or roaming deployments. Festival operators in Germany lease modular small cell trailers for seasonal capacity.
Telecommunication Providers lead by contract value. Facility Management Companies is gaining share fastest as ownership unbundles from carrier service agreements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
RF front-end module fabrication concentrates in Taiwan, exposing infrastructure vendors to geopolitical disruption risk. Equipment assembly and systems integration cluster in China, Germany, and the United States. Demand dispersion follows private 5G deployment timelines across industrial corridors and healthcare campuses.
United States
Hospital systems commission dedicated 5G infrastructure for surgical robotics and real-time patient monitoring. The FCC's three-tiered CBRS priority access system unlocks licensed 3.5 GHz deployments for private industrial networks without carrier intermediation. Verizon and AT&T drive small cell specifications across Texas and California industrial zones.
Germany
Industrial manufacturing facilities retrofit legacy infrastructure with converged Wi-Fi and 5G systems for automated guided vehicle coordination. ETSI standards harmonize radio equipment compliance across European member states, reducing fragmentation for multi-national facility operators. The Ruhr industrial corridor anchors private network deployments for automotive and chemical processing plants.
Japan
Manufacturing campuses converge Wi-Fi 6E and private 5G under unified network management platforms for sub-10 millisecond latency. METI industrial policy prioritizes Industry 4.0 infrastructure investments in smart factory conversions. The Chubu/Nagoya region concentrates automotive supplier deployments for connected production lines.
India
Urban renewal programs specify in-building wireless as mandatory infrastructure for commercial and transit-adjacent academic hubs. TRAI-certified installation contractors channel signal booster procurement for small commercial buildings. Maharashtra and Karnataka smart city mandates compress deployment timelines for multi-tenant office complexes.
United Kingdom
Third-party infrastructure operators capture multi-tenant office and retail deployments through neutral host ownership models. EU AI Act algorithmic transparency requirements impose documentation obligations on connected building platforms processing occupant location analytics. London commercial real estate investment trusts front-load compliance costs into procurement budgets.
Global in-Building Wireless Market Competitive Landscape
Concentration sits with integrated radio-baseband portfolio vendors and cable-connectivity heritage specialists. The competitive landscape bifurcates between premium infrastructure vendors meeting carrier-grade reliability standards and cost-optimized challengers serving facility-direct procurement. Three archetypes dominate: telecom equipment conglomerates with end-to-end wireless portfolios, cable and connectivity specialists leveraging DAS heritage, and neutral host operators unbundling infrastructure ownership from carrier service contracts. M&A activity targets systems integration capabilities, while geographic expansion focuses on India smart city mandates and UK neutral host opportunities.
Within the telecom equipment tier, CommScope Holding Company, Nokia Corporation, and Ericsson exemplify distinct geographic anchoring strategies. CommScope leverages its cable and connectivity heritage across North American stadium and arena deployments. Nokia anchors European private wireless momentum through manufacturing and logistics campus platforms. Ericsson differentiates across Asia-Pacific dense urban commercial complexes through integrated radio and baseband portfolios.
| Leading Market Players |
|---|
| CommScope Holding Company |
| Nokia Corporation |
| Huawei Technologies Co., Ltd. |
| Ericsson |
| Corning Incorporated |
| Samsung Electronics Co., Ltd. |
| Airspan Networks |
| ZTE Corporation |
| Comba Telecom Systems Holdings Ltd. |
| Others |
Supply & Pricing Matrix
Scale economies at RF front-end module fabrication facilities in Taiwan establish minimum viable production thresholds that compress margins for second-tier vendors while elevating price floors for carrier-grade equipment. Active antenna node assembly in China, Germany, and the United States concentrates procurement leverage among integrated portfolio vendors, forcing cost-optimized challengers toward modular component sourcing.
Pricing Analysis
The FCC's CBRS three-tiered priority access system dictates the pricing tier structure across private 5G deployments, separating premium licensed spectrum access from generalized authorized and opportunistic tiers. Hardware margins stratify across carrier-grade reliability certification, ETSI harmonized compliance, and uncertified economy alternatives. Cost compression in passive DAS retrofits intensifies as copper and coaxial cable volatility squeezes project margins. Healthcare campuses demonstrate lowest price sensitivity due to mission-critical connectivity requirements, while small commercial buildings in India exhibit highest sensitivity through TRAI-certified contractor channels.
Supply Chain Analysis
Just-in-time inventory strategies dominate active small cell procurement, while strategic stockpiling persists for RF front-end modules exposed to Taiwan semiconductor fabrication concentration. Component sourcing draws from Taiwan for RF modules, China for antenna assembly, and Germany for precision baseband controllers. Gallium nitride substrates, copper coaxial cable, and fiber optic backhaul constitute critical input dependencies. Single-source vulnerability at Taiwan semiconductor foundries presents structural risk. Distribution runs through carrier-integrator partnerships for DAS and small cells, direct-to-facility distributors for repeaters, and e-commerce platforms for signal boosters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics in this market hinge on Open RAN decoupling of hardware and software procurement, creating interoperability ecosystems that unbundle integrated vendor stacks and redistribute margin capture toward systems integrators.
For Market Incumbents: Secure carrier-grade certification moats against Open RAN commoditization by embedding software-defined radio value capture into long-term service contracts. Defend margin position through backward integration into RF front-end module sourcing, reducing Taiwan fabrication exposure. Prioritize ETSI harmonized compliance investments to streamline multi-national facility operator procurement. For New Entrants and Emerging Players: Lead with AI-driven RF planning tools to reduce site survey costs for stadium and arena projects, capturing systems integration contracts as incumbent DAS specialists lose maintenance revenue. Target India smart city mandates specifying mandatory in-building wireless for transit-adjacent academic hubs. Deploy neutral host ownership models unbundling infrastructure from carrier service agreements. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors systems integration specialists with Open RAN software layers over hardware-centric legacy vendors. Long-term viability rests on capturing recurring software revenue streams rather than one-time equipment sales. Monitor CBRS spectrum auction participation rates as inflection indicator for private network deployment acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Open RAN Platform Integration | Decouples hardware-software procurement, enabling multi-vendor interoperability for building owners. |
| Private 5G Network Deployment | Captures healthcare campus demand for surgical robotics and real-time patient monitoring connectivity. |
| AI-Driven RF Planning Tools | Reduces site survey costs for stadium and arena projects through machine learning optimization. |
| Neutral Host Infrastructure Ownership | Transfers operational risk from carriers to property developers while preserving SLA-backed roaming. |
| ETSI Harmonized Certification Investment | Streamlines radio equipment compliance across European member states for multi-national operators. |
Research Methodology
Initial hypotheses were tested against primary input from RF engineering directors, hospital IT infrastructure leads, commercial real estate procurement managers, and neutral host operators, then refined through secondary validation against FCC spectrum allocation records, ETSI standards documentation, TRAI certification databases, and CBRS deployment registries. Bottom-up equipment shipment analysis triangulated with top-down facility investment tracking across healthcare, manufacturing, and educational segments.
Variance decomposition across product type, technology, application, and end user dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level growth trajectory modeling incorporating private 5G deployment timelines, CBRS adoption curves, and smart city infrastructure mandates. Forecast inputs included semiconductor fabrication capacity utilization, copper commodity pricing indices, and municipal permitting velocity for building code compliance.
The analysis sits within stated boundaries; outcomes outside sustained CBRS spectrum availability, stable Taiwan semiconductor supply, or continued ETSI harmonization would require recalibration. Forecasts reflect documented assumptions regarding technology transition pacing from passive DAS to active small cell architectures. Revision becomes warranted when geopolitical disruption risk at Taiwan RF module foundries crosses operational contingency thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wireless Technologies
Mobile WLAN Access Points Market
Wireless Technologies
Industrial 5G Market
Wireless Technologies
Mobile Hotspot Device Market
Wireless Technologies
Base Transceiver Station (BTS) Market
Wireless Technologies
Wireless LAN Controller Market
Wireless Technologies
Global WLAN Market
Wireless Technologies
Outdoor Wi-Fi Market
Wireless Technologies
Distributed Antenna System Market
Wireless Technologies
Wireless Access Point Market
Wireless Technologies
Fixed Wireless Access (5G/Wttx/LTE) Market
Wireless Technologies
Global Wireless Mesh Network Market
Wireless Technologies
Visible Light Communication (VLC) Market
Wireless Technologies
5G Small Cell Market
Wireless Technologies
Light Fidelity Market
Wireless Technologies
Global Mobile and Wireless Backhaul Market
Wireless Technologies
Voice Over Wifi Market