
 Carrier Routing Equipment Market | 2026-2036
Carrier Routing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Carrier Routing Equipment Market Analysis
Buyer concentration among telecom operators is expanding as tier-one carriers consolidate network spending while cloud providers and enterprises fragment demand across edge locations. Cisco Systems Inc. leverages its installed base in service provider cores to sustain recurring upgrade cycles. Nokia anchors European supply relationships through its IP routing portfolio. Huawei Technologies Co. Ltd. dominates domestic Chinese deployments despite access restrictions elsewhere.
Carrier routing equipment comprises high-capacity packet-forwarding systems engineered for throughput exceeding multiple terabits per second, utilizing custom ASICs and merchant silicon architectures to direct traffic across autonomous system boundaries in telecommunications networks. Modular routers command the largest revenue pool due to chassis-based scalability for core networks, while edge routers represent the fastest structural expansion as 5G fronthaul and mobile edge computing disaggregate traffic closer to subscribers. IP/MPLS technology leads installed capacity, though SD-WAN integration is reshaping how enterprises and service providers architect branch-to-cloud connectivity.
The FCC governs spectrum allocation and network reliability standards in the United States, while the European Union's CE marking and Cybersecurity Act impose conformity requirements on equipment sold across member states. China's MIIT enforces domestic GB standards and indigenous innovation mandates that privilege local vendors in state-controlled infrastructure tenders. Stakeholders must monitor how Open RAN interoperability specifications and sovereign cloud policies redirect procurement flows across major economies.
Market Dynamics
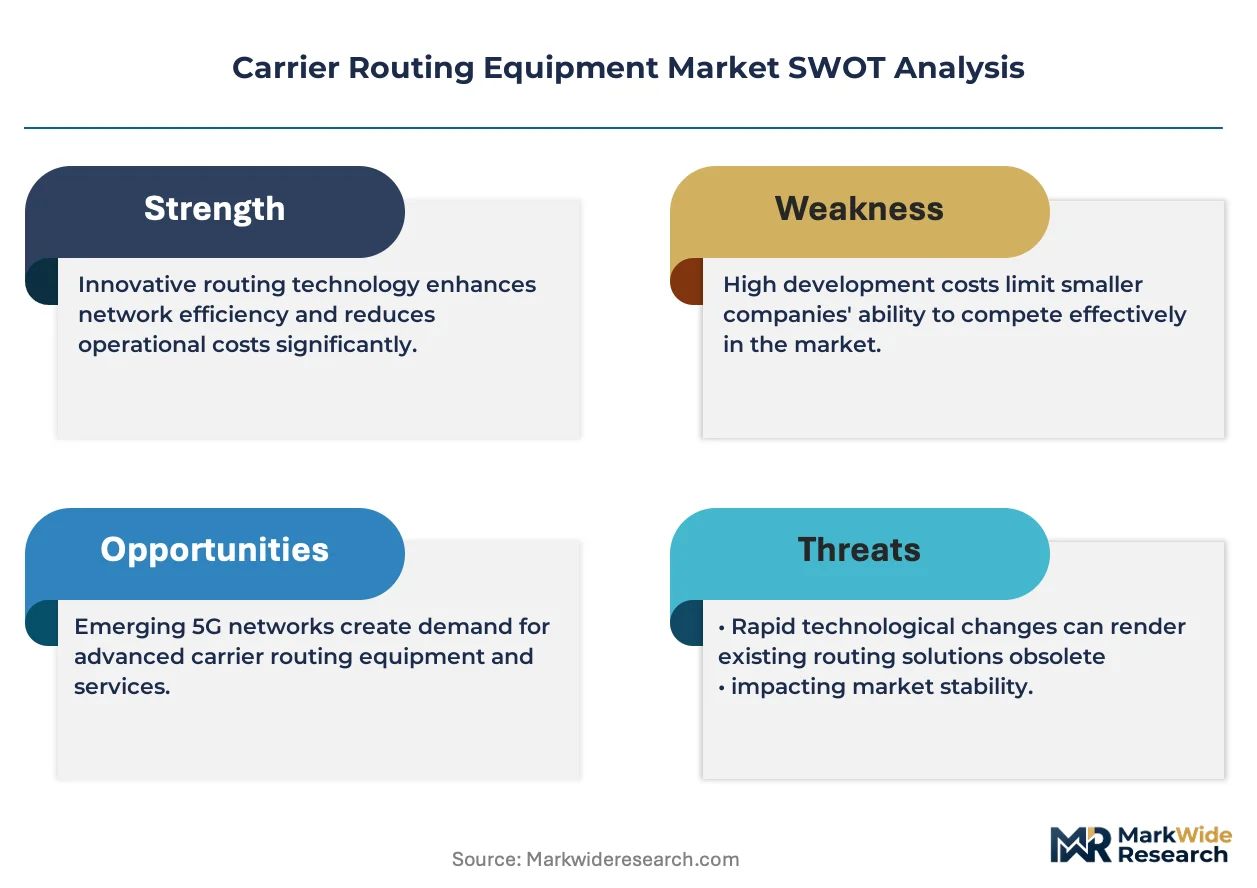
The Carrier Routing Equipment Market is undergoing a structural transformation driven by the disaggregation of mobile core networks and the shift toward merchant silicon architectures that challenge proprietary ASIC dominance in service provider infrastructure.
Growth Catalysts
- 5G Standalone Core Deployments:Telecom operators in India and Brazil are scaling backbone capacity to handle exponential mobile data traffic growth, requiring terabit-scale router upgrades at aggregation points.
- Open RAN Mandates:The European Union's interoperability specifications are reshaping procurement criteria, forcing incumbent vendors to expose interfaces and enabling multi-vendor routing stacks.
- State-Led Infrastructure Buildouts:China's MIIT-directed 5G expansion mandates domestic router deployments across provincial networks, creating concentrated demand for core-to-edge systems.
Market Restraints
- Merchant Silicon Supply Concentration:Advanced 7nm and 5nm fabrication for routing ASICs depends on a limited foundry base in Taiwan, creating geopolitical exposure for equipment vendors.
- FCC Net-Neutrality Compliance Costs:Traffic management restrictions in the United States impose engineering overhead that complicates quality-of-service implementations in edge routers.
- Optical Transport Substitution:Coherent optical pluggables with integrated switching are absorbing functions previously performed by discrete routing layers in metro networks.
Strategic Opportunities
- Mobile Edge Computing Integration:5G fronthaul disaggregation is creating demand for compact, high-density edge routers at baseband hotel locations and distributed RAN sites.
- SD-WAN Convergence:Enterprise branch-to-cloud traffic patterns are pulling service providers toward unified IP/MPLS and SD-WAN platforms that collapse historical product silos.
- EU Cybersecurity Act Certification:The common criteria framework for network equipment creates first-mover advantages for vendors achieving CC-EAL4+ ratings before mandatory deadlines.
Industry Challenges
- Legacy Protocol Integration:Migration from traditional MPLS to SRv6 segment routing requires maintaining backward compatibility with installed base systems, complicating software architecture.
- Specialized Talent Scarcity:VLSI design expertise for custom forwarding chips and control-plane software engineering concentrates at a handful of semiconductor firms and academic programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carrier Routing Equipment Market |
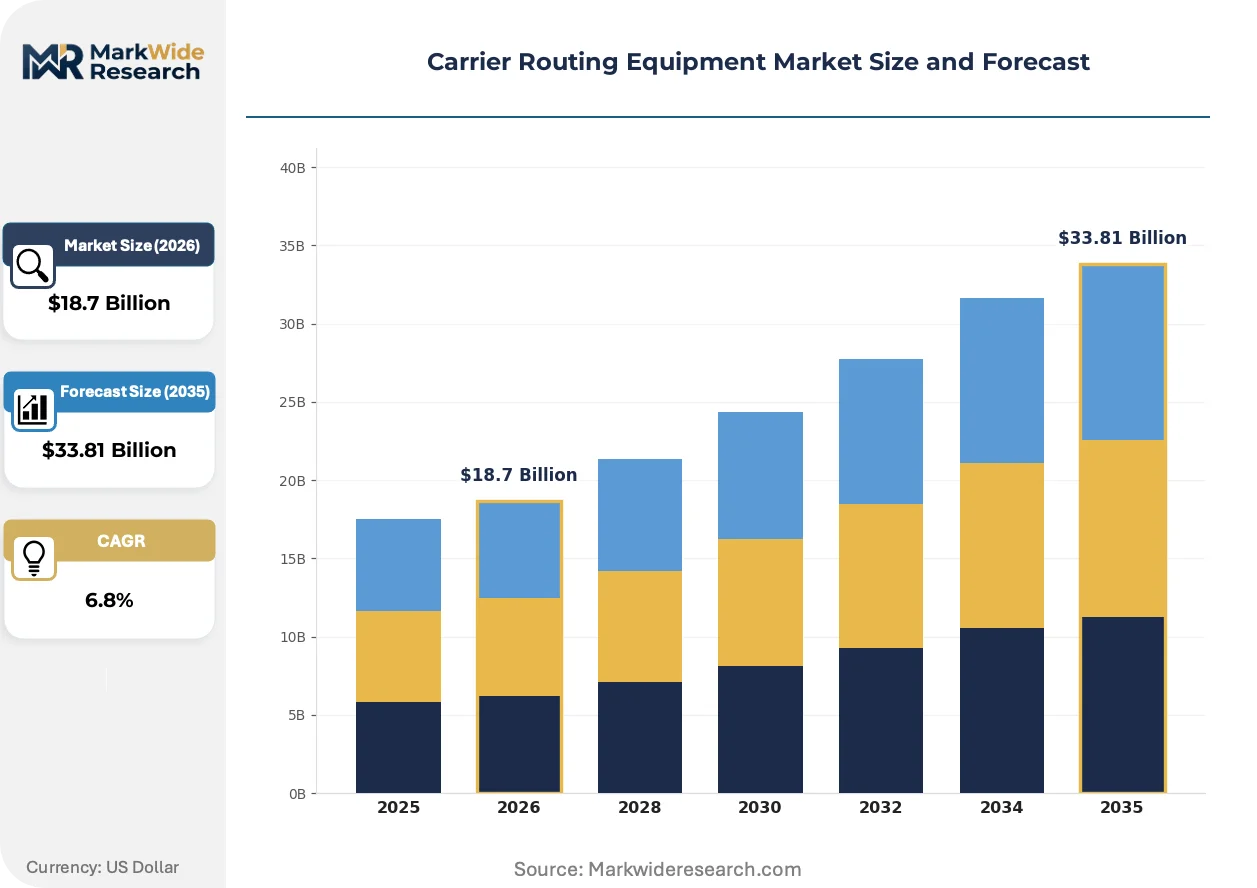
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Routers, Modular Routers, Virtual Routers, Edge Routers End User: Telecom Operators, Internet Service Providers, Data Centers, Enterprises Deployment: Cloud, On-Premises, Hybrid, Edge Technology: IP/MPLS, SD-WAN, Ethernet, Optical Networking |
| Companies Covered | Ericsson, ADTRAN Inc, Cisco Systems Inc., ZTE Corporation, Nokia, Juniper Networks Inc., Alcatel-Lucent S.A., Telco Systems, Huawei Technologies Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carrier Routing Equipment Market Emerging Trajectories
Merchant silicon architectures are actively reshaping competitive dynamics in carrier routing, compressing the historical advantage of custom ASIC development and enabling new entrants to challenge established vendors with faster innovation cycles.
White-box routing platforms built on Broadcom and Intel silicon are overtaking proprietary chassis systems in hyperscale data center interconnect and cloud provider edge deployments. Amazon Web Services and Microsoft Azure are deploying these disaggregated systems at massive scale. This shift is compressing R&D timelines for traditional vendors who must now compete on software differentiation rather than hardware performance alone.
The European Union's Cybersecurity Act and accompanying EN 303 645 standards are mandating security-by-design certification for network equipment sold across member states. Hardware vendors must submit to third-party evaluation and maintain vulnerability disclosure programs. Core router portfolios face the steepest compliance burden given their position in critical national infrastructure.
Enterprise procurement patterns are fragmenting as distributed workforces and multi-cloud architectures displace centralized IT spending. Mid-market buyers are bypassing traditional carrier-managed service bundles in favor of direct SD-WAN appliance purchases through distributor channels. This behavioral shift is most pronounced in North American and Western European markets where IT autonomy carries organizational priority.
Carrier Routing Equipment Market Segmentation
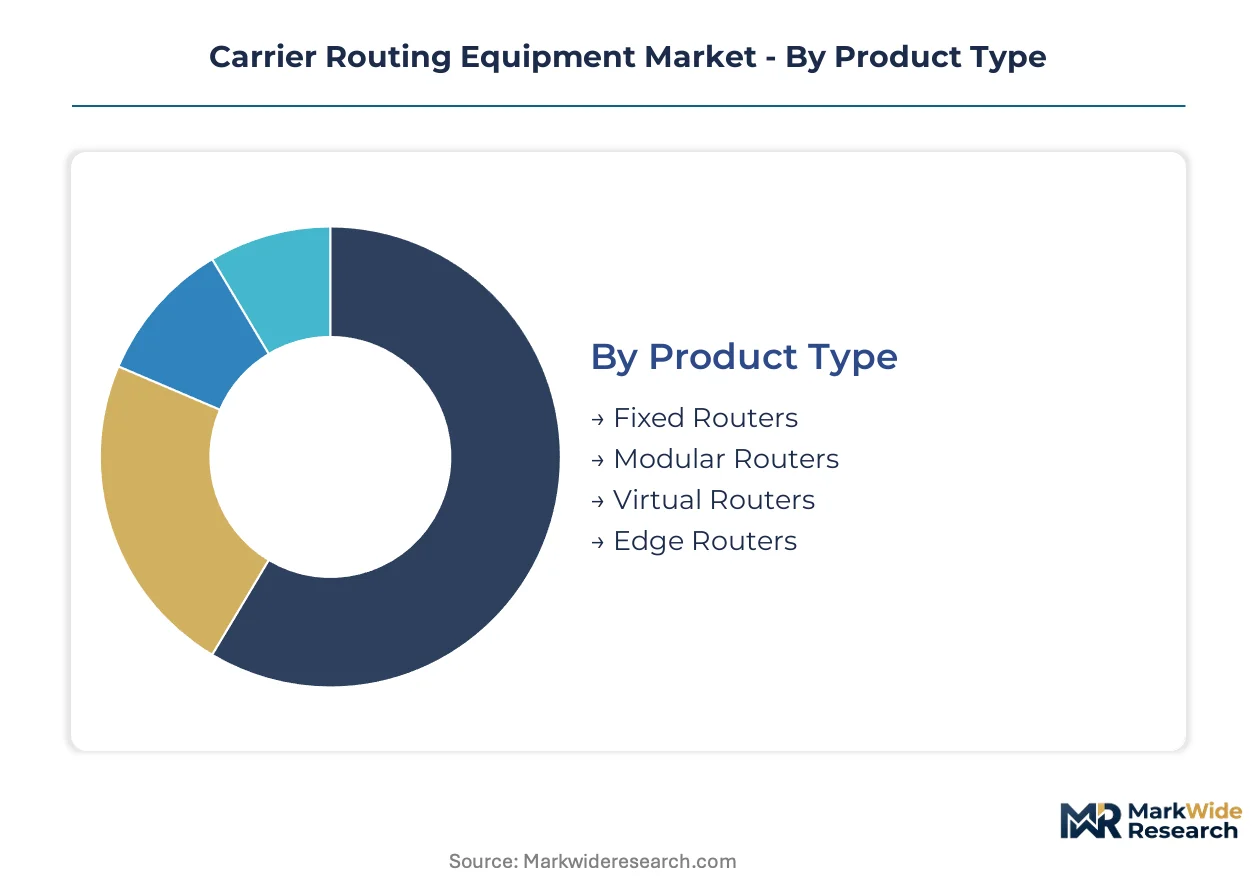
Carrier routing equipment segments diverge sharply by capital intensity, operational complexity, and buyer procurement authority. Understanding these fault lines clarifies where vendor R&D investments concentrate and which deployment models reshape network architectures fastest.
Product Type:
Buyers in this category separate by scale of traffic aggregation and chassis upgrade flexibility versus fixed-configuration simplicity.
- Modular Routers:Chassis-based systems with line-card modularity enable terabit-scale throughput expansion without forklift replacements. Telecom operators in India and Brazil deploy these at backbone aggregation points to absorb 5G traffic surges while preserving slot reserves for future capacity.
- Edge Routers:Compact form factors with high-density 100G/400G interfaces address disaggregated RAN sites and mobile edge computing locations. China's provincial 5G buildouts are concentrating procurement here as MIIT mandates push core-to-edge flattening.
- Fixed Routers:Non-upgradable appliances serve cost-constrained branch offices and small-scale enterprise WAN termination points.
- Virtual Routers:Software instances running on commodity x86 hardware enable cloud-native network functions and rapid service instantiation.
Modular routers lead volumes today; edge routers are gaining share fastest.
End User:
Procurement scale and technical specification authority vary enormously across this buyer spectrum, from centralized carrier capital committees to distributed enterprise IT budgets.
- Telecom Operators:Tier-one carriers consolidate multi-billion-dollar network refresh cycles with custom ASIC requirements and five-year depreciation horizons. Their RFQs drive merchant silicon adoption timelines and Open RAN interoperability roadmaps.
- Data Centers:Hyperscale cloud providers disaggregate routing stacks with white-box hardware and in-house software, compressing margins for traditional chassis vendors.
- Internet Service Providers:Regional broadband operators balance MPLS legacy support against SD-WAN convergence pressures at metro aggregation layers.
- Enterprises:Mid-market buyers increasingly bypass carrier-managed services for direct SD-WAN appliance procurement through distributor channels.
Telecom operators dominate absolute spending; data centers are climbing the fastest as cloud egress traffic multiplies.
Deployment:
Operational control preferences and latency requirements split buyers between fully managed cloud instances and captive infrastructure ownership.
- On-Premises:Physical router deployments in carrier central offices and enterprise headquarters maintain deterministic performance for regulated services.
- Edge:Distributed compute locations at baseband hotels and RAN aggregation points demand ruggedized, space-constrained routing platforms.
- Cloud:Network functions virtualization enables elastic capacity scaling without hardware procurement cycles.
- Hybrid:Split-control architectures combine on-premises policy enforcement with cloud-orchestrated traffic engineering.
On-premises retains the largest installed base; edge deployments show the steepest expansion trajectory.
Technology:
Protocol maturity and migration complexity determine upgrade cadence, with legacy MPLS estates constraining how aggressively buyers adopt segment routing.
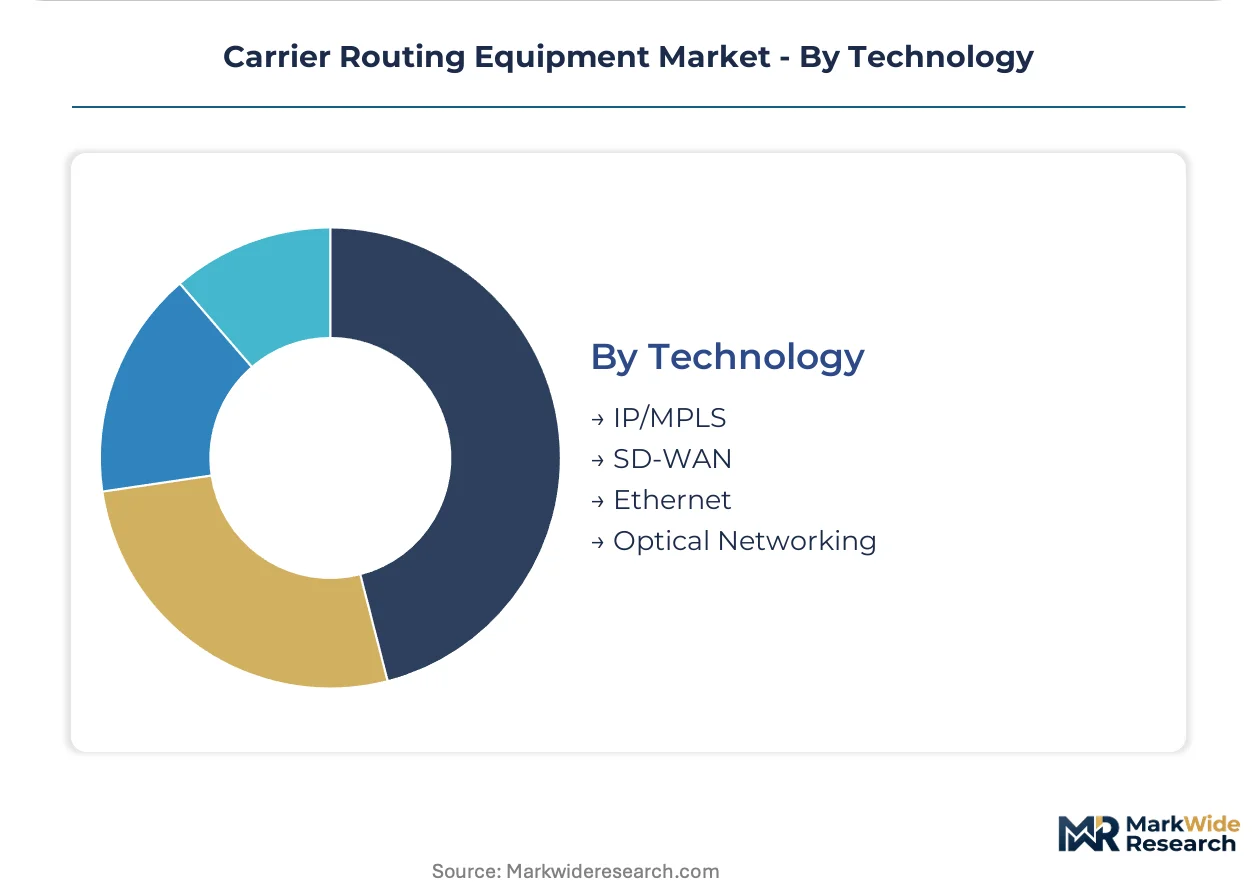
- IP/MPLS:The dominant installed protocol stack for service provider VPNs and traffic engineering, now evolving toward SRv6 to simplify header processing and improve scalability.
- SD-WAN:Overlay architectures abstract underlying transport, enabling enterprise branch-to-cloud connectivity with centralized policy management.
- Ethernet:Layer-2 switching fabrics dominate data center interconnect and metro aggregation for cost-sensitive, high-volume traffic.
- Optical Networking:Coherent pluggables with integrated switching absorb routing functions previously performed by discrete packet platforms.
IP/MPLS carries the most installed capacity; SD-WAN is expanding most quickly as enterprise procurement fragments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's state-directed 5G buildouts generate router demand volumes that dwarf Brazil's carrier consolidation cycles, while India's mobile data surge and Germany's Open RAN compliance mandates create divergent procurement patterns across major economies.
China
Provincial network flattening and MIIT-mandated indigenous innovation drive massive core-to-edge router deployments. GB standards enforcement privileges domestic vendors in state-controlled infrastructure tenders. Beijing-Tianjin-Hebei and Yangtze River Delta clusters concentrate manufacturing and systems integration capacity for nationwide 5G backhaul.
United States
Hyperscale cloud providers disaggregate routing stacks with white-box hardware at massive scale. FCC net-neutrality frameworks impose traffic management restrictions that complicate quality-of-service engineering. Northern Virginia and Dallas-Fort Worth data center corridors absorb the highest concentration of terabit-scale edge router installations.
Germany
Telecom operators balance MPLS legacy estates against SRv6 migration timelines in Europe's most protocol-conservative market. CE marking and Cybersecurity Act certification requirements reshape procurement criteria toward security-by-design hardware. Munich and Stuttgart anchor vendor R&D partnerships for Open RAN interoperability testing.
India
Reliance Jio and Bharti Airtel expand backbone capacity to serve exponential mobile data traffic growth from 5G standalone rollouts. TRAI spectrum allocation frameworks and CEA reliability standards govern equipment qualification for national networks. Bangalore and Hyderabad host systems integration labs for multi-vendor routing stack validation.
Brazil
Carrier consolidation concentrates capital spending among fewer tier-one operators with extended depreciation horizons. ANVISA-equivalent telecom regulator Anatel enforces network reliability standards for critical infrastructure. São Paulo anchors Latin America's largest metro aggregation router deployments for mobile backhaul expansion.
Carrier Routing Equipment Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across a market structure that rewards installed base leverage in carrier cores while punishing hardware-only vendors at the cloud edge. Consolidation pressure concentrates among chassis-based incumbents defending service provider relationships against merchant silicon challengers. Three archetypes dominate: vertically integrated systems houses with custom ASIC programs, software-centric disrupters on merchant silicon, and regional champions capturing state-protected domestic tenders. Competitive intensity manifests through strategic partnerships for Open RAN interoperability and portfolio diversification into adjacent optical transport layers.
Within the diversified systems tier, Cisco Systems Inc. and Nokia occupy positions that exemplify incumbent resilience through recurring upgrade cycles with tier-one carriers. Juniper Networks Inc. sits within the specialist camp, representing the pure-play routing vendor archetype that competes on software differentiation rather than hardware scale. ZTE Corporation and Huawei Technologies Co. Ltd. anchor the state-affiliated tier, capturing protected demand in domestic Chinese deployments where MIIT procurement preferences override commercial competition.
| Leading Market Players |
|---|
| Ericsson |
| ADTRAN Inc |
| Cisco Systems Inc. |
| ZTE Corporation |
| Nokia |
| Juniper Networks Inc. |
| Alcatel-Lucent S.A. |
| Telco Systems |
| Huawei Technologies Co. Ltd. |
| Others |
Supply Flow & Price Mechanics
Core-to-edge performance bifurcation between chassis-based modular systems and fixed-configuration edge appliances manifests in divergent pricing architectures and supply chain sourcing patterns across merchant silicon and custom ASIC tiers.
Pricing Analysis
Capacity additions in Taiwan are reshaping price floors for merchant silicon-based edge routers as foundry output expands. Three-tier pricing structure across premium chassis systems, mid-range modular platforms, and economy fixed appliances reflects certification grade differentiation under EU Cybersecurity Act and FCC reliability frameworks. Cost compression in the edge router tier intensifies because hyperscale cloud providers disaggregate routing stacks with white-box alternatives. Enterprise mid-market buyers exhibit highest price sensitivity as they bypass carrier-managed services for direct SD-WAN procurement.
Supply Chain Analysis
Specialized VLSI design talent scarcity in Taiwan, South Korea, and the United States constrains advanced 7nm and 5nm routing ASIC production ramps. Supply chains draw from concentrated merchant silicon foundry output, custom ASIC design houses, and optical component specialists in Shenzhen and Dongguan. Single-source vulnerability in Taiwan-based advanced node fabrication exposes equipment vendors to geopolitical disruption. Distribution runs through tier-one carrier procurement committees, hyperscale cloud direct sourcing teams, and enterprise distributor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Carrier routing equipment functions as a geographic-arbitrage play where EU Cybersecurity Act compliance costs in Germany and France exceed India's TRAI-equipment qualification burden by a factor reflecting certification complexity differentials.
For Market Incumbents: Anticipate merchant silicon challengers compressing hardware margin pools by accelerating software differentiation investments in SRv6 control planes and cloud-native routing stacks. Defensive consolidation moves center on acquiring optical transport specialists to collapse routing and switching layers, plus deepening backward integration into merchant silicon supply through strategic foundry partnerships. White-box disaggregation by Amazon Web Services and Microsoft Azure represents the primary margin threat vector. For New Entrants and Emerging Players: Enter via India's 5G standalone backbone expansion where Reliance Jio and Bharti Airtel procurement cycles favor cost-disruptive alternatives to incumbent chassis vendors. White-space targets concentrate on mobile edge computing integration at baseband hotel locations and distributed RAN aggregation points. Go-to-market leverage rests on Open RAN interoperability certification to unlock European Union operator RFQs. For Investors and Strategic Acquirers: Consolidation pressure builds where merchant silicon commoditization erodes proprietary ASIC returns below sustainable R&D reinvestment thresholds. Long-term viability favors software-centric routing specialists with cloud-native architectures over hardware-dependent chassis incumbents. Acquisition target archetypes include segment routing software houses and edge router specialists with EU Cybersecurity Act pre-certification. Watch hyperscale cloud capex deceleration as inflection signal for merchant silicon demand contraction.| Strategic Initiative | Industry Significance |
|---|---|
| Open RAN Interoperability Certification | EU Cybersecurity Act mandates create first-mover qualification advantages for multi-vendor routing stacks. |
| Merchant Silicon Platform Migration | Broadcom and Intel silicon adoption enables faster innovation cycles against proprietary ASIC incumbents. |
| Edge Router Portfolio Expansion | China MIIT-directed 5G buildouts concentrate procurement for compact 400G-capable RAN aggregation systems. |
| SD-WAN Convergence Investment | Enterprise branch-to-cloud traffic patterns pull service providers toward unified IP/MPLS and overlay platforms. |
| Optical Transport Layer Integration | Coherent pluggable absorption of routing functions collapses historical product silos in metro networks. |
Methodological Framework
Multiple input streams — executive interviews with tier-one carrier network architects, hyperscale cloud procurement officers, and semiconductor supply chain managers; secondary validation through FCC equipment authorization filings, EU CE marking databases, and MIIT tender announcements; plus customs trade data for routing equipment imports — were reconciled through bottom-up deployment tracking and top-down market sizing triangulation.
Historical shipment volumes were cross-referenced against panel input from vendor sales operations and carrier capital expenditure disclosures. Segmentation dimensions modeled span product type, end-user archetype, deployment model, and technology protocol stack. CAGRs were derived from unit shipment trajectories and average selling price evolution across the projection horizon. Industry-specific forecast inputs include 5G standalone core deployment timelines and Open RAN interoperability specification adoption curves.
Inputs from carrier procurement committees and cloud provider infrastructure teams were available through the study window; gaps in real-time merchant silicon foundry utilization data introduce uncertainty bands around edge router supply forecasts. Forecasts reflect documented assumptions regarding spectrum allocation timelines and regulatory certification deadlines. Material deviation in MIIT infrastructure tender pacing or Taiwan foundry capacity allocation warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Network Technology
Global Wi-Fi Range Extender Market
Network Technology
2.4GHz Router Market
Network Technology
Smart Network Interface Card (Smartnic) Market
Network Technology
Wi-Fi 6E Router Market
Network Technology
Global Active Network Management Market
Network Technology
DHCP and IP Address Management Market
Network Technology
Fiber to the Home (FTTH) Market
Network Technology
Network Fault Monitoring Tools Market
Network Technology
Global Ethernet Switch and Routers Market
Network Technology
Global Home Networking Device Market
Network Technology
Zero-Touch Provisioning Market
Network Technology
Global Network Switches Market
Network Technology
Global 5G Smart Antenna Market
Network Technology
Wi-Fi Extender Market
Network Technology
Virtual Router Market
Network Technology
GCC Set-Top Box Market