
 Global Wireless Router Market | 2026-2036
Global Wireless Router Market Size, Share, and Industry Trends Forecast 2026-2036
Global Wireless Router Market Outlook
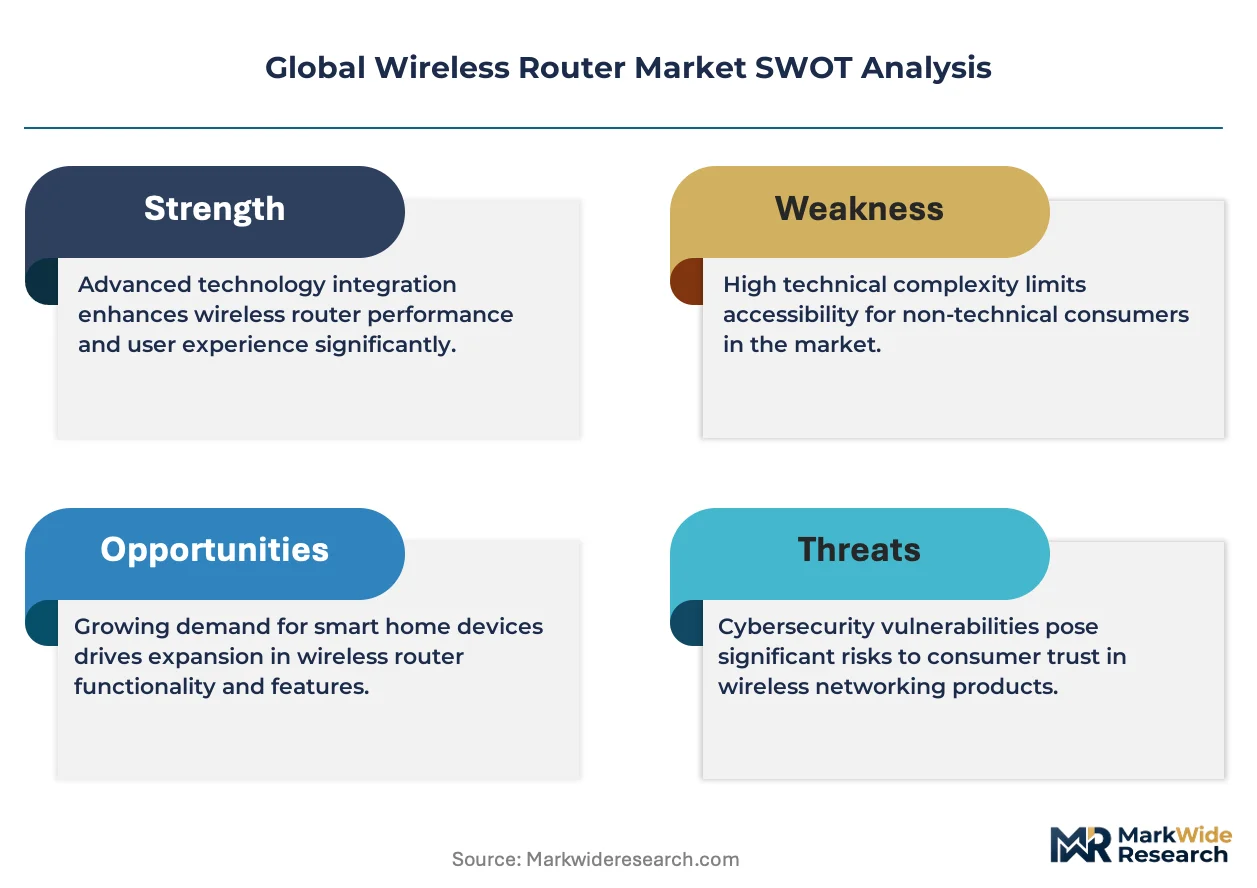
The gap between premium enterprise-grade hardware and commodity consumer units is consolidating around chipset architecture and software-defined networking capabilities. Cisco Systems, Inc. leverages its Meraki cloud platform to anchor recurring revenue in mid-market offices. Huawei Technologies Co., Ltd. sustains vertical integration from baseband silicon to antenna design, dominating carrier-grade deployments across Asia. TP-Link Technologies Co., Ltd. competes on manufacturing scale, occupying the volume tier through direct-to-consumer channels and retail partnerships.
A wireless router is a network device that forwards data packets between computer networks using radio frequency bands, typically operating at 2.4 GHz and 5 GHz with newer models adding 6 GHz under Wi-Fi 6E standards, and serves as the central access point enabling multiple devices to share a single internet connection within a defined coverage area. Mesh routers are capturing margin pools as whole-home coverage replaces single-point hardware in residential settings. Enterprise demand for Wi-Fi 6 technology leads technology transitions, while Wi-Fi 5 sustains volume in price-sensitive small business installations across developing markets.
The FCC governs unlicensed spectrum allocation and power limits in the United States, directly shaping which frequency bands manufacturers can activate. ETSI harmonizes radio equipment standards across France, Germany, and Italy, creating a unified certification pathway for vendors seeking European market access. China's MIIT mandates domestic cybersecurity review for networked devices, adding compliance layers for foreign suppliers. Stakeholders must monitor spectrum auction outcomes and regional certification reciprocity agreements to anticipate hardware refresh cycles and geographic expansion feasibility.
Market Dynamics
Wi-Fi 6E spectrum allocation is compressing hardware refresh cycles as enterprise campuses and residential mesh networks simultaneously upgrade to capture 6 GHz performance gains.
Growth Catalysts
- FCC unlicensed spectrum rules:The United States regulator's expanded 6 GHz access is accelerating certification timelines for tri-band hardware across North American distribution channels.
- Fiber-to-the-home penetration:Deepening optical infrastructure in Japan and China is creating throughput bottlenecks that only Wi-Fi 6E routers can resolve at the premises edge.
- Smart home device density:Rising connected appliance counts in residential settings are forcing whole-home coverage architectures that obsolete single-point legacy hardware.
Market Restraints
- Silicon supply concentration:Advanced baseband chipset fabrication concentrates among Taiwan-based foundries, exposing hardware vendors to geopolitical disruption risk.
- ETSI certification complexity:Harmonized European standards across France, Germany, and Italy create multi-jurisdictional testing burdens that delay product launches by quarters.
- Copper and rare earth input volatility:Antenna substrate materials and power management components face commodity price swings that compress assembly margins unpredictably.
Strategic Opportunities
- India's PLI scheme for networking equipment:Production-linked incentives are attracting contract manufacturers to establish local assembly for price-sensitive South Asian markets.
- Convergence of Wi-Fi 6E with IoT security frameworks:Integrated threat detection silicon is opening premium tiers in healthcare and financial services verticals.
- Direct-to-consumer channel expansion:Bypassing retail intermediaries through manufacturer storefronts is capturing margin in upgrade-heavy North American and Japanese markets.
Industry Challenges
- RF engineering talent scarcity:Specialized antenna design and spectrum optimization expertise pools concentrate among a handful of geographies, constraining R&D velocity.
- Legacy Wi-Fi 5 integration friction:Backward compatibility requirements for existing enterprise infrastructure are complicating firmware architecture and extending validation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Wireless Router Market |
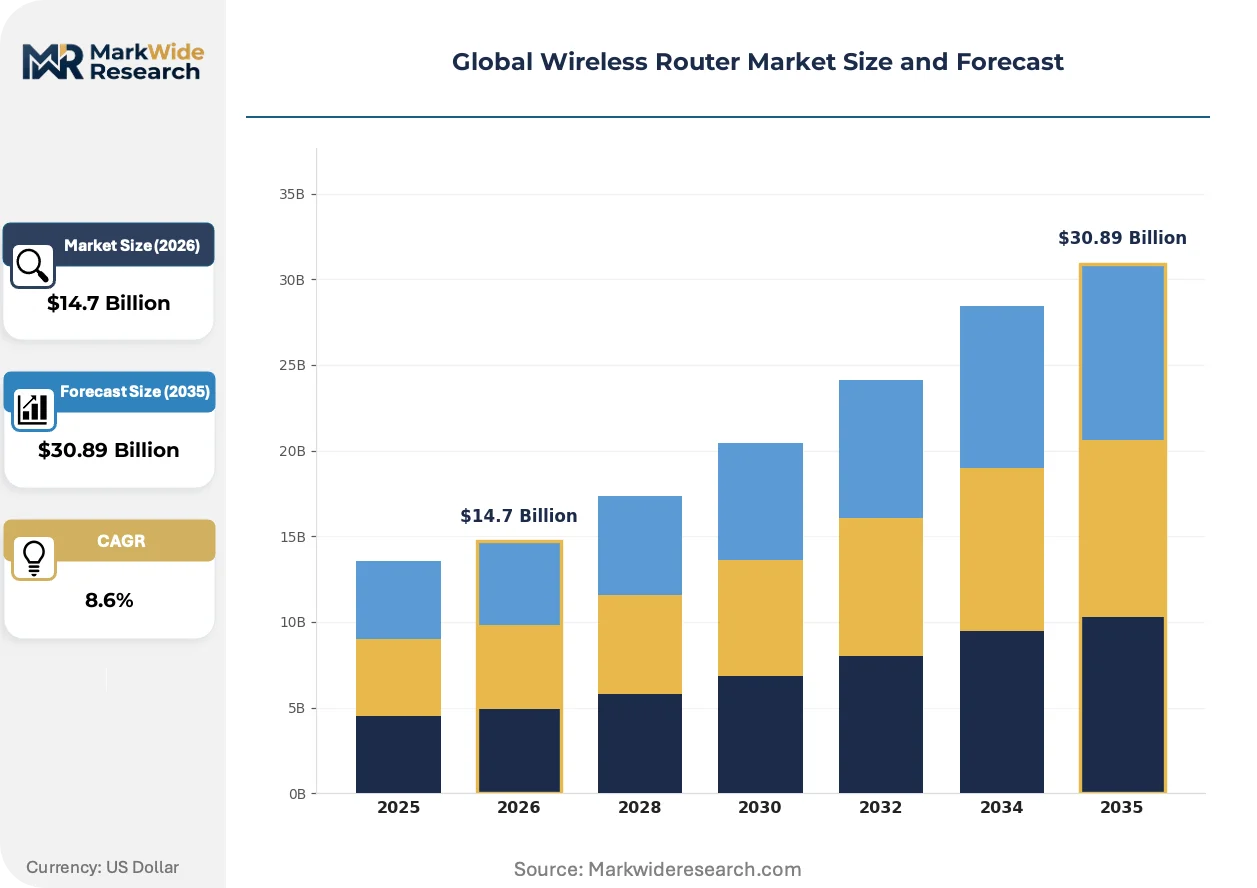
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $30.89 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone Routers, Mesh Routers, Wireless Range Extenders, Dual-Band Routers Application: Homes, Offices, Retail Stores, Public Spaces End User: Consumers, Small Businesses, Enterprises, Service Providers Technology: Wi-Fi 5, Wi-Fi 6, 4G LTE, 5G |
| Companies Covered | TP-Link Technologies Co., Ltd., NETGEAR, Inc., ASUSTeK Computer Inc., D-Link Corporation, Huawei Technologies Co., Ltd., Cisco Systems, Inc., Ubiquiti Inc., Shenzhen Tenda Technology Co., Ltd., Linksys, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Wireless Router Market Strategic Shifts
Software-defined radio architectures are decoupling hardware from feature roadmaps, allowing over-the-air capability expansion that is compressing traditional replacement cycles.
Wi-Fi 7 (802.11be) silicon is electrifying early enterprise adoption despite limited client device availability. Corporate IT departments in the United States and Japan are pre-positioning infrastructure to capture 320 MHz channel bonding and multi-link operation capabilities. This forward deployment is electrifying vendor R&D roadmaps and collapsing the typical generational transition window from thirty-six to eighteen months.
The EU AI Act's risk classification framework is reshaping how router firmware handles automated traffic management. Vendors serving European markets must now document algorithmic decision-making processes for network optimization features. German and French enterprise buyers are prioritizing suppliers with pre-certified transparency documentation, creating procurement friction for Asian manufacturers lacking European compliance infrastructure.
Subscription-based network management is displacing perpetual license models in mid-market offices. Cisco's Meraki cloud platform and comparable offerings from competitors are converting capital expenditure into recurring revenue relationships. This shift concentrates most visibly in United States healthcare and education verticals where IT staffing constraints favor fully managed connectivity services over on-premise administration.
Global Wireless Router Market Segmentation
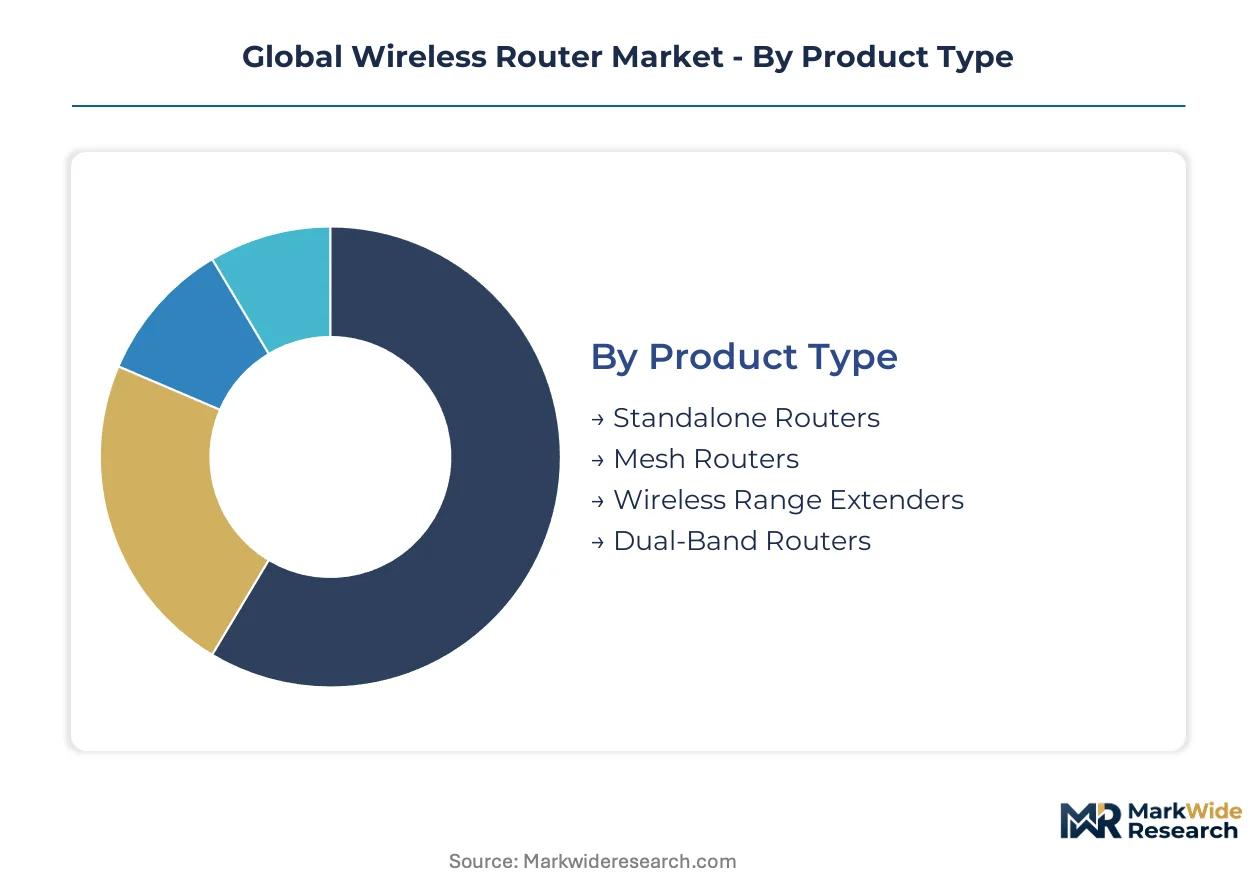
Wireless router segmentation reveals how supply-side specialization maps to divergent margin structures. Component sourcing strategies and certification requirements vary sharply across product architectures, creating distinct competitive arenas.
Product Type:
Supply concentration in radio frequency chipsets funnels manufacturing scale toward specific form factors, with foundry capacity allocation determining which designs reach market volume.
- Mesh Routers:Multi-node systems synchronize through dedicated backhaul channels to eliminate dead zones across distributed coverage areas. Enterprise campuses in the United States and Japan are replacing legacy single-point hardware as smart home device density rises and whole-home coverage becomes non-negotiable.
- Standalone Routers:Single-unit devices integrate baseband processing, RF amplification, and antenna arrays in compact enclosures. Price-sensitive small business installations across developing markets sustain volume demand for Wi-Fi 5 variants while Wi-Fi 6E transitions concentrate in fiber-to-the-home deployments.
- Wireless Range Extenders:Signal repeaters amplify existing coverage without routing intelligence. Budget residential upgrades in India and Southeast Asia favor these units for incremental network expansion.
- Dual-Band Routers:Hardware simultaneously broadcasts 2.4 GHz and 5 GHz signals for device compatibility. Retail channel inventory in Europe and North America still carries significant stock of these transitional designs.
Standalone routers absorb the bulk of installed capacity; mesh routers are expanding most quickly.
Application:
Cost tier differentiation separates enterprise-grade deployments from mass-market residential hardware, with firmware capabilities and management interfaces driving price stratification.
- Offices:Mid-market workplaces demand cloud-managed platforms with zero-touch provisioning and security policy enforcement. Subscription-based network management from vendors like Cisco's Meraki cloud platform is displacing perpetual license models in United States healthcare and education verticals where IT staffing constraints favor fully managed connectivity services.
- Homes:Residential installations prioritize ease of setup and mobile app control over advanced features. China's deepening fiber-to-the-home penetration and Japan's smart home device density are forcing whole-home coverage architectures that obsolete single-point legacy hardware.
- Retail Stores:Commercial environments require guest access segmentation and point-of-sale reliability. ETSI harmonized standards across France, Germany, and Italy create unified certification pathways for vendors seeking European retail market access.
- Public Spaces:Municipal Wi-Fi and transportation hubs need weatherized hardware with centralized authentication. FCC unlicensed spectrum rules in the United States govern power limits and frequency activation for these deployments.
Office deployments command premium pricing; residential home applications generate the steepest volume expansion trajectory.
End User:
Customer type determines procurement channel and service attachment rates, with direct-to-consumer storefronts capturing margin in upgrade-heavy markets while carrier relationships dominate service provider segments.
- Enterprises:Large organizations require centralized policy management and threat detection integration. Wi-Fi 7 silicon is electrifying early adoption in the United States and Japan despite limited client device availability, with corporate IT departments pre-positioning infrastructure for 320 MHz channel bonding capabilities.
- Service Providers:Telecom carriers bundle router hardware with subscription services and demand carrier-grade reliability. Huawei Technologies sustains vertical integration from baseband silicon to antenna design, dominating these deployments across Asia.
- Consumers:Individual purchasers prioritize price-to-performance ratios and retail availability. TP-Link Technologies competes on manufacturing scale, occupying this volume tier through direct-to-consumer channels and retail partnerships.
- Small Businesses:Limited IT staff favor plug-and-play solutions with basic guest networking. Wi-Fi 5 sustains volume in this price-sensitive segment across developing markets while Wi-Fi 6 technology leads enterprise transitions.
Enterprise accounts absorb the bulk of installed capacity; service provider segments are climbing the fastest.
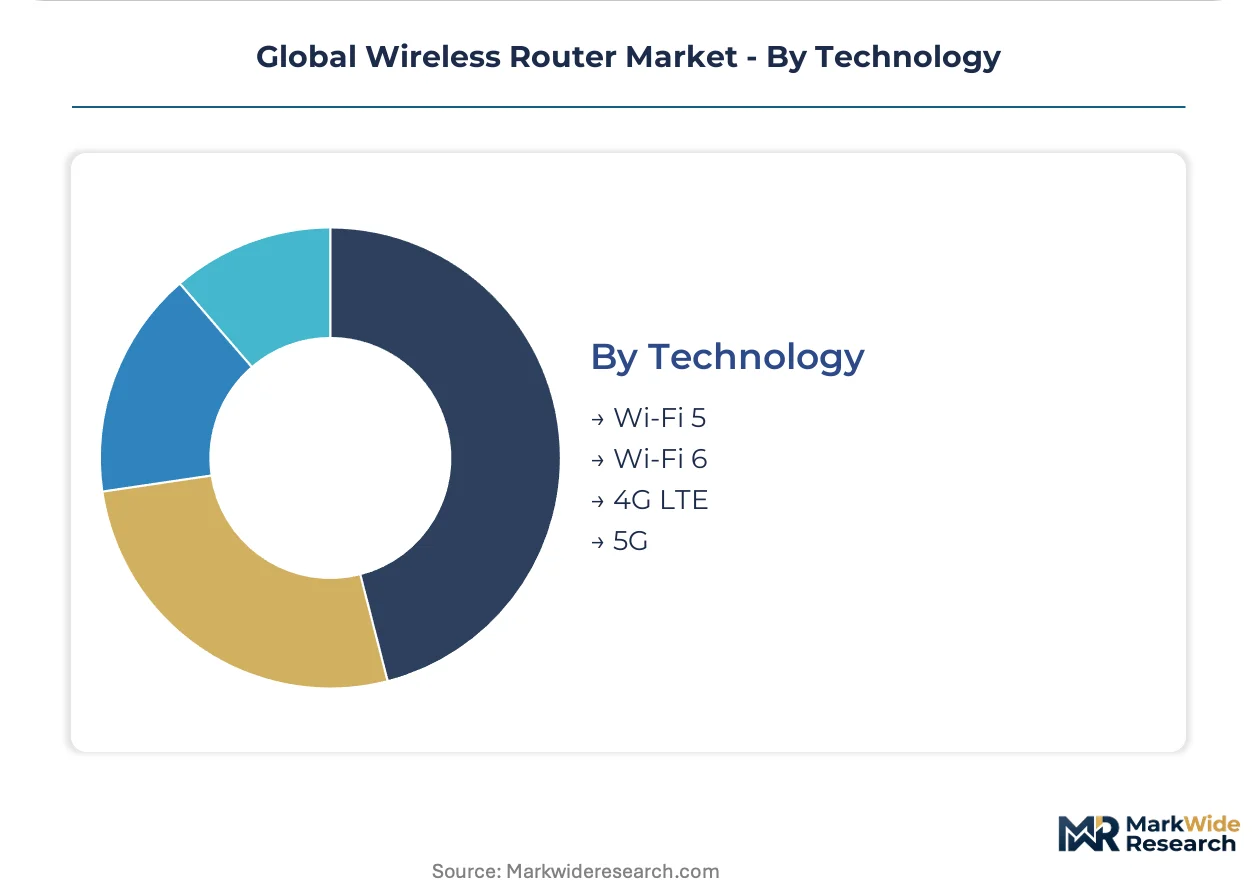
Technology:
Maturity curves and certification timelines segment the technology landscape, with spectrum allocation decisions by national regulators compressing or extending hardware refresh cycles.
- Wi-Fi 6:OFDMA and MU-MIMO architectures improve spectral efficiency in dense environments. Enterprise campuses are scaling deployments to replace aging Wi-Fi 5 infrastructure as FCC expanded 6 GHz access accelerates certification timelines for tri-band hardware.
- Wi-Fi 5:802.11ac wave 2 remains prevalent in cost-constrained installations. Small business demand across developing markets sustains volume while backward compatibility requirements complicate firmware architecture for mixed-environment enterprises.
- 5G:Cellular backhaul integration enables wireless primary connectivity for remote locations. Fixed wireless access routers are gaining traction where fiber deployment lags.
- 4G LTE:Mature cellular fallback technology supports failover and rural connectivity. Embedded modules in industrial routers maintain steady replacement demand.
Wi-Fi 5 retains the bulk of installed capacity; Wi-Fi 6 is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen's electronics corridor anchors wireless router manufacturing density, with component clusters radiating across the Pearl River Delta into Dongguan and Huizhou. This concentration shapes procurement patterns for vendors serving North American and European distribution channels.
United States
Enterprise campuses in Austin and Raleigh-Durham are accelerating Wi-Fi 6E mesh deployments to replace aging infrastructure. The FCC's expanded 6 GHz unlicensed spectrum access compresses certification timelines for tri-band hardware. Seattle's cloud computing corridor influences software-defined networking feature roadmaps for mid-market office segments.
China
Deepening fiber-to-the-home penetration in Shanghai and Beijing creates throughput bottlenecks demanding Wi-Fi 6E premises equipment. MIIT mandates domestic cybersecurity review for networked devices, adding compliance layers for foreign suppliers. Shenzhen's vertically integrated component ecosystem dominates baseband silicon through antenna design for carrier-grade Asian deployments.
Germany
Industrial automation hubs in Stuttgart and Munich drive demand for deterministic low-latency wireless in factory settings. ETSI harmonized standards create unified certification pathways across France and Italy, though multi-jurisdictional testing burdens delay launches. Bavaria's automotive clusters are pre-positioning Wi-Fi 7 infrastructure for connected manufacturing floors.
Japan
Smart home device density in Tokyo and Osaka metropolitan areas forces whole-home coverage architectures that obsolete single-point legacy hardware. METI spectrum allocation policies favor early 6 GHz commercialization. Nagoya's industrial corridor integrates wireless backhaul into precision manufacturing quality control systems.
India
Price-sensitive residential upgrades in Bengaluru and Hyderabad sustain volume demand for dual-band transitional designs. The PLI scheme for networking equipment attracts contract manufacturers to establish local assembly for South Asian markets. Delhi-NCR's IT services corridor drives cloud-managed platform adoption among mid-market enterprises with constrained IT staffing.
Global Wireless Router Market Competitive Environment
Premium-margin players sit above commodity-margin players across software-defined networking capabilities and certification depth. The vendor base stratifies into three tiers: cloud-platform specialists capturing recurring revenue relationships, vertically integrated fabricators controlling silicon-to-antenna supply chains, and scale-driven manufacturers competing through direct-to-consumer distribution. Consolidation pressures concentrate among mid-market participants lacking either platform differentiation or captive component supply. Dominant competitive moves include strategic partnerships with fiber carriers and portfolio diversification into mesh system architectures.
Within the cloud-platform tier, Cisco Systems, Inc. exemplifies recurring revenue conversion in healthcare and education verticals. TP-Link Technologies Co., Ltd. and NETGEAR, Inc. occupy positions across the volume-driven consumer segment, with the former representing manufacturing scale advantages and the latter anchoring North American retail channel presence. Huawei Technologies Co., Ltd. sits within the vertically integrated archetype, sustaining carrier-grade deployment dominance across Asian markets through upstream control over baseband silicon design.
| Leading Market Players |
|---|
| TP-Link Technologies Co., Ltd. |
| NETGEAR, Inc. |
| ASUSTeK Computer Inc. |
| D-Link Corporation |
| Huawei Technologies Co., Ltd. |
| Cisco Systems, Inc. |
| Ubiquiti Inc. |
| Shenzhen Tenda Technology Co., Ltd. |
| Linksys |
| Others |
Value Chain & Pricing Dynamics
Enterprise procurement teams in United States healthcare and education verticals are consolidating vendor relationships around cloud-managed platforms, forcing contract manufacturers to absorb firmware integration costs and compressing assembly margins for commodity hardware tiers.
Pricing Analysis
Throughput-based value anchors dominate enterprise negotiations, with buyers benchmarking cost per connected device and uptime guarantees rather than unit hardware cost. Three-tier pricing structure across premium, standard, and economy levels separates cloud-platform subscriptions from transactional hardware sales and bare-bones retail units. Pricing pressure stems from silicon supply concentration among Taiwan-based foundries exposing vendors to input cost volatility. Small business installations across developing markets exhibit highest price sensitivity, while carrier-grade deployments in Asia show lowest sensitivity due to long-term service bundling.
Supply Chain Analysis
Trans-Pacific freight cost fluctuations and port congestion at Los Angeles-Long Beach complicate inventory positioning for North American distribution channels. Component sourcing concentrates in China, Taiwan, and South Korea for baseband silicon, RF amplifiers, and antenna substrates. Rare earth magnet dependencies for power management modules and copper laminate substrates for PCB fabrication create commodity price exposure. Single-source vulnerability in advanced chipset fabrication represents the dominant structural risk. Distribution runs through Shenzhen's electronics corridor into direct-to-consumer storefronts and carrier bundling partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance story where ETSI harmonized standards across France, Germany, and Italy erect certification barriers that favor incumbents with established European testing infrastructure.
For Market Incumbents: Lock in recurring revenue relationships by deepening cloud-platform subscriptions in United States healthcare and education verticals where IT staffing constraints favor fully managed connectivity. Defend against white-label entrants from India's PLI-attracted contract manufacturers by accelerating Wi-Fi 7 certification timelines and pre-positioning 320 MHz channel bonding capabilities. Certification investment in ETSI harmonized standards represents the critical lever for European market retention. For New Entrants and Emerging Players: India's PLI scheme for networking equipment opens a window for local assembly targeting price-sensitive South Asian residential markets. White-space concentration sits with mesh system architectures for fiber-to-the-home deployments in China and Japan where whole-home coverage demand outpaces incumbent supply. Direct-to-consumer storefronts bypassing retail intermediaries offer the most penetrable go-to-market angle in upgrade-heavy North American markets. For Investors and Strategic Acquirers: Re-rating potential sits with cloud-platform specialists given the displacement of perpetual license models by subscription-based network management across mid-market offices. Long-term viability favors vendors controlling software-defined networking roadmaps decoupled from hardware refresh cycles. Acquisition target archetype: mid-scale manufacturers lacking platform differentiation but holding carrier relationships in Asia. Signal to monitor: FCC spectrum auction outcomes and 6 GHz commercialization pace as inflection indicators for hardware refresh velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Wi-Fi 7 Silicon Pre-Positioning | Early enterprise adoption in United States and Japan compresses generational transition windows from thirty-six to eighteen months. |
| Cloud Platform Integration | Subscription-based network management displaces perpetual licenses in United States healthcare verticals with constrained IT staffing. |
| ETSI Certification Investment | Harmonized standards across France, Germany, and Italy create procurement friction for Asian manufacturers lacking European compliance infrastructure. |
| Direct-to-Consumer Channel Expansion | Manufacturer storefronts bypass retail intermediaries to capture margin in upgrade-heavy North American and Japanese markets. |
| India PLI Localization | Production-linked incentives attract contract manufacturers establishing local assembly for price-sensitive South Asian markets. |
Study Parameters
Multi-period observation of FCC spectrum allocation decisions, ETSI certification timelines, and fiber-to-the-home penetration rates anchored the trend analysis, supplemented by interviews with router platform engineering directors, enterprise IT procurement officers, carrier network planning leads, and retail channel category managers. Secondary validation drew from FCC unlicensed spectrum filings, MIIT cybersecurity review disclosures, SEC 10-K hardware segment reporting, and ETSI harmonized standards documentation. Bottom-up unit shipment modeling triangulated against top-down service provider capex analysis.
Segment-weighting across product type, application, end user, and technology dimensions structured the analytical framework over the projection horizon. Wi-Fi 6E adoption curves, mesh system replacement rates, and enterprise cloud-platform attachment rates served as industry-specific forecast inputs. CAGRs were derived from installed base turnover modeling and generational transition velocity assumptions.
The model assumes a particular technology adoption path; alternative pathways for Wi-Fi 7 commercialization ahead of client device availability would alter the outlook. Forecasts reflect assumptions about spectrum allocation continuity, foundry capacity expansion, and tariff regime stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Network Technology
Global Home Networking Device Market
Network Technology
US Private LTE and 5G Network Market
Network Technology
Wimax Solutions Market
Network Technology
Enterprise Routers Market
Network Technology
IT Connector Market
Network Technology
Mobile Network Optimization Market
Network Technology
Global Managed Wi-Fi Solutions Market
Network Technology
Radio Modem Market
Network Technology
Virtual Customer Premises Equipment Market
Network Technology
Europe Private 5G Network Market
Network Technology
Multiservice Provisioning Platform Market
Network Technology
Gigabit Ethernet Market
Network Technology
Network Telemetry Market
Network Technology
Self-Healing Networks Market
Network Technology
Managed Switches Market
Network Technology
Global GPS Market