
 Wimax Solutions Market | 2026-2036
Wimax Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Wimax Solutions Market Analysis
Multi-source procurement for baseband chipsets is broadening vendor participation across Wimax infrastructure programs. Huawei Technologies leverages its integrated equipment portfolio to anchor large-scale public network deployments across multiple continents. Fujitsu competes through specialized rural access point designs that sustain margin pools in low-density coverage zones. ZTE Corporation extends its position via cost-optimized router lines that dominate price-sensitive community network tenders.
Wimax solutions encompass fixed and mobile wireless broadband systems operating in licensed and unlicensed spectrum bands, utilizing orthogonal frequency-division multiple access and scalable channel bandwidths from 1.25 MHz to 20 MHz to deliver last-mile connectivity where fiber deployment proves economically prohibitive. Wimax equipment and access points constitute the mature revenue core, while Wimax antennas represent the fastest-growing product category as operators upgrade sector coverage for higher-order MIMO configurations. The hybrid network deployment model captures expanding enterprise interest by blending public infrastructure with private campus controls, whereas community networks remain concentrated in municipal and cooperative ownership structures with distinct procurement rhythms.
The FCC governs spectrum licensing and equipment authorization for Wimax deployments in the United States, while the ETSI framework shapes interoperability mandates across European member states and the ITU-R coordinates global frequency allocations that determine market access for cross-border equipment vendors. Regulatory pressure on spectrum efficiency and coexistence protocols is forcing equipment redesign cycles that favor vendors with in-house RF engineering capabilities. Stakeholders must monitor pending mid-band spectrum auctions and corresponding power-limit adjustments that will determine viable coverage economics for next-generation fixed wireless rollouts.
Market Dynamics
Spectrum reallocation mandates from the FCC and parallel regulatory bodies are compressing deployment timelines for Wimax operators while forcing equipment redesign cycles that favor vendors with captive RF engineering capabilities.
Growth Catalysts
- Rural Broadband Mandates:India's universal service obligation programs channel public funding into last-mile wireless infrastructure for unserved gram panchayats.
- Licensed Spectrum Access:Brazil's Anatel spectrum auctions for 3.5 GHz bands enable municipal networks to secure protected frequencies for fixed wireless deployments.
- Massive MIMO Adoption:Higher-order antenna configurations are expanding sector capacity without requiring additional tower infrastructure.
Market Restraints
- Input Cost Volatility:Gallium nitride substrate prices fluctuate with power electronics demand from electric vehicle inverters.
- Supply Concentration Risk:Baseband processor fabrication concentrates at three foundry complexes in Taiwan.
- Substitution Threat:5G fixed wireless access equipment from Ericsson and Nokia is capturing enterprise connectivity tenders previously served by Wimax.
Strategic Opportunities
- Underserved Municipal Networks:Brazil's interior cities lack fiber backhaul and represent captive demand for wireless middle-mile solutions.
- Technology Convergence:Integration of Wimax access points with IoT sensor gateways creates bundled smart city offerings.
- Regulatory Tailwind:The FCC's Rural Digital Opportunity Fund prioritizes fixed wireless for census blocks where fiber costs exceed viability thresholds.
Industry Challenges
- RF Engineering Talent Scarcity:Microwave circuit design expertise pools concentrate at legacy telecom equipment vendors and defense contractors.
- Certification Timeline Compression:Equipment authorization cycles at the FCC's Office of Engineering and Technology lag deployment schedules.
- Legacy System Integration:Hybrid networks require protocol translation between Wimax MAC layers and Ethernet backhaul standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wimax Solutions Market |
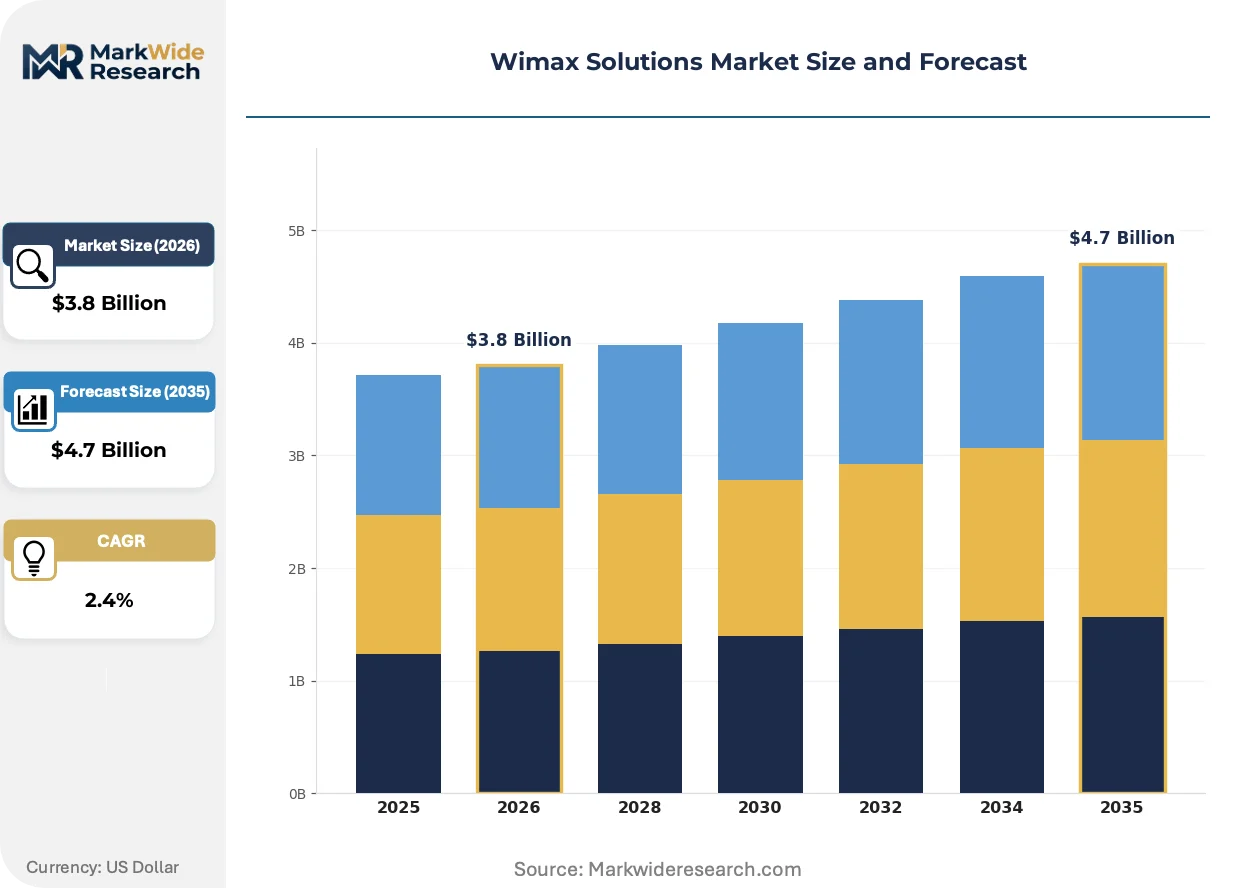
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $4.7 Billion |
| CAGR (2026 – 2036) | 2.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wimax Equipment, Wimax Access Points, Wimax Antennas, Wimax Routers End User: Telecommunications, Residential, Enterprises, Government Deployment Model: Public Network, Private Network, Hybrid Network, Community Network Application: Broadband Internet, VoIP Services, Video Streaming, Data Transfer |
| Companies Covered | Huawei Technologies, Fujitsu, Airspan Networks, Alvarion, ZTE Corporation, Intel Corporation, Samsung Electronics, Cisco Systems, Motorola Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wimax Solutions Market Emerging Trajectories
Equipment vendors are reconfiguring product architectures around software-defined radio platforms that compress hardware refresh cycles while enabling multi-protocol operation through firmware updates.
Beamforming antenna arrays are overtaking sectorized panel designs in new base station deployments. These active antenna systems dynamically steer energy toward subscriber locations rather than broadcasting across fixed azimuths. Utilities and railway operators in India are adopting beamforming for trackside connectivity where terrain obstacles disrupt line-of-sight propagation.
ETSI's harmonized standards for 3.5 GHz coexistence protocols are mandating listen-before-talk mechanisms that protect incumbent satellite earth stations. Equipment vendors must redesign RF front ends to detect and avoid licensed satellite uplink frequencies. This regulatory pressure most affects European operators planning rural fixed wireless overlays in bands adjacent to C-band satellite services.
Enterprise buyers are unbundling network equipment procurement from managed service contracts that previously locked them to single-vendor ecosystems. Municipal utilities in Brazil now source access points through open tenders while contracting network operations to regional system integrators. This purchasing pattern shift concentrates price pressure on hardware margins while expanding recurring software license revenue for network management platforms.
Wimax Solutions Market Segmentation
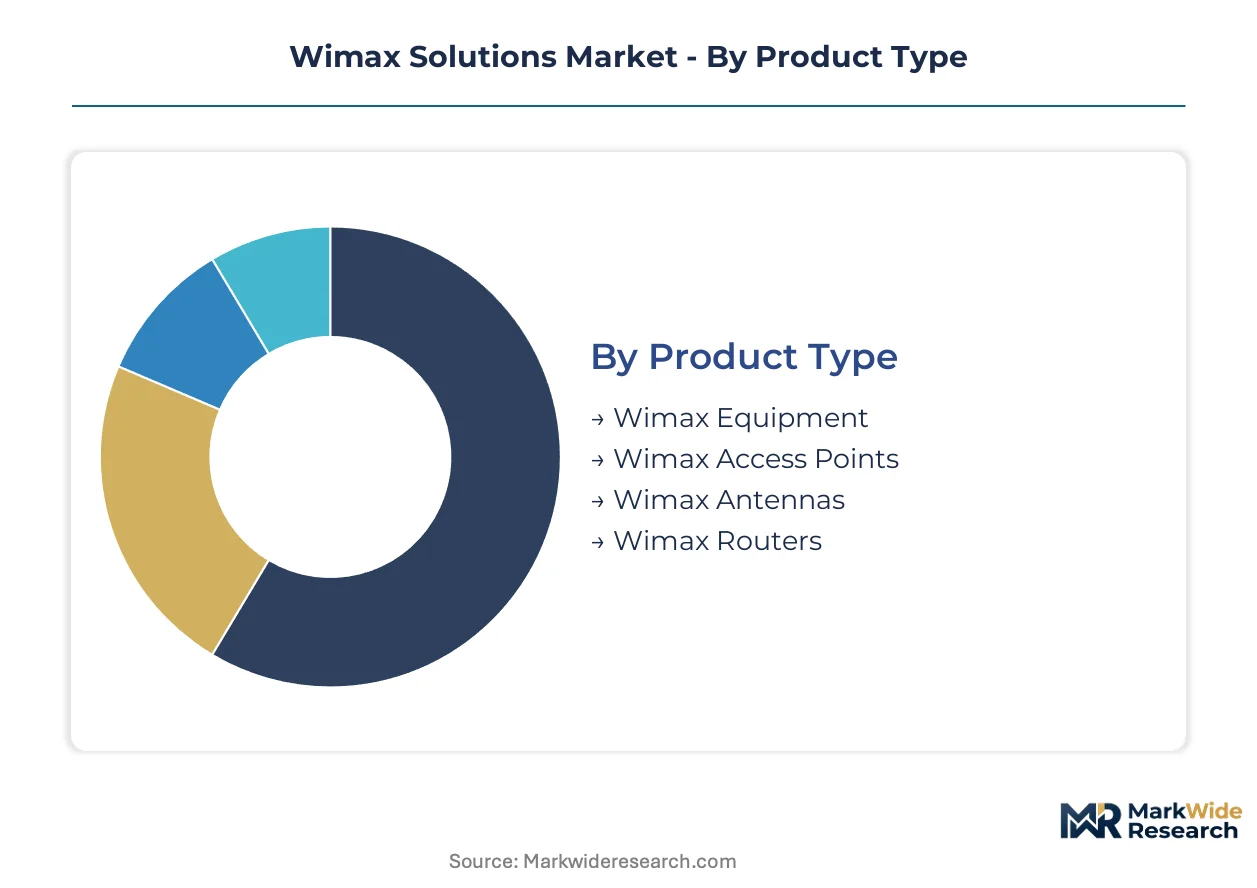
Wimax market segmentation reveals distinct procurement patterns across equipment categories, buyer types, and deployment architectures. Understanding these divisions enables vendors to align R&D investment with where purchasing decisions actually concentrate.
Product Type:
Cost tier separates buyers seeking integrated system bundles from those prioritizing modular component upgrades.
- Wimax Equipment:Base stations and core network infrastructure form the revenue foundation, with integrated radio and baseband units dominating carrier procurement in India's rural broadband programs. Operators favor single-vendor stacks to minimize interoperability testing overhead.
- Wimax Antennas:Active antenna systems with beamforming capabilities are displacing passive sector panels as operators pursue higher spectral efficiency. India's railway operators drive specialized demand for trackside configurations that overcome terrain obstacles.
- Wimax Access Points:Compact subscriber units serve fixed wireless termination points in municipal network deployments.
- Wimax Routers:Customer premises equipment bridges last-mile radio links with local area networks.
Wimax Equipment leads volumes today; Wimax Antennas is gaining share fastest.
End User:
Application maturity determines whether buyers prioritize proven reliability or experimental feature sets.
- Telecommunications:Licensed carriers dominate procurement volume, deploying macro-cell infrastructure under universal service obligations. India's TRAI-mandated rural coverage targets channel public funding into gram panchayat connectivity programs.
- Enterprises:Manufacturing campuses and logistics hubs adopt private Wimax overlays where fiber trenching disrupts operations. Brazil's industrial zones in Minas Gerais represent concentrated demand for licensed-spectrum campus networks.
- Government:Municipal utilities and public safety agencies procure through cooperative purchasing agreements.
- Residential:Individual subscribers access service through retail distribution of customer premises equipment.
Telecommunications leads volumes today; Enterprises is expanding most quickly.
Deployment Model:
Ownership structure shapes procurement rhythm and vendor relationship intensity.
- Public Network:Commercial carriers operate licensed infrastructure with standardized equipment certification cycles. Brazil's Anatel spectrum auctions enable protected-frequency deployments across underserved interior cities.
- Hybrid Network:Blended architectures combine carrier backhaul with private campus controls, attracting enterprise buyers seeking SLA flexibility. Municipal utilities in Brazil increasingly unbundle hardware procurement from managed service contracts.
- Community Network:Cooperative ownership structures concentrate in rural municipalities with distinct tender timelines.
- Private Network:Single-organization deployments serve campuses and industrial facilities.
Public Network leads volumes today; Hybrid Network is climbing the fastest.
Application:
Bandwidth requirements and latency sensitivity segment buyers by technical specification priorities.
- Broadband Internet:General connectivity represents the foundational use case, with throughput specifications scaling from residential tiers to enterprise-grade symmetrical service. India's rural digital inclusion programs prioritize this application for unserved gram panchayats.
- Data Transfer:Machine-to-machine and backhaul applications demand deterministic latency for utility grid monitoring and railway signaling. India's trackside connectivity deployments favor Wimax over unlicensed alternatives for interference protection.
- VoIP Services:Voice-over-IP requires jitter-controlled transport for acceptable call quality.
- Video Streaming:Downlink-heavy consumption patterns shape traffic engineering and caching strategies.
Broadband Internet leads volumes today; Data Transfer is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment certification costs and spectrum licensing timelines vary sharply across jurisdictions, creating arbitrage opportunities where vendors prioritize markets with streamlined approval processes. India's TRAI-mandated rural coverage targets and Brazil's municipal network tenders attract disproportionate vendor attention relative to their market size due to predictable procurement rhythms.
United States
The FCC's Rural Digital Opportunity Fund channels subsidies toward fixed wireless deployments in census blocks where fiber costs exceed viability thresholds. Equipment authorization cycles at the FCC's Office of Engineering and Technology lag deployment schedules, compressing vendor margins. Tower companies in rural Texas and Montana expand Wimax backhaul for underserved communities.
India
TRAI-mandated universal service obligation programs direct public funding into gram panchayat connectivity for unserved rural administrative units. The Department of Telecommunications coordinates spectrum allocation for BharatNet Phase III wireless middle-mile extensions. Railway operators in Maharashtra and Karnataka adopt beamforming access points for trackside connectivity where terrain disrupts line-of-sight propagation.
Brazil
Anatel spectrum auctions for 3.5 GHz bands enable municipal networks to secure protected frequencies for fixed wireless deployments. Industrial zones in Minas Gerais generate concentrated demand for licensed-spectrum campus networks. Municipal utilities in interior cities unbundle hardware procurement from managed service contracts, shifting price pressure toward equipment margins.
Germany
ETSI harmonized standards for 3.5 GHz coexistence protocols mandate listen-before-talk mechanisms protecting incumbent satellite earth stations. The Federal Network Agency enforces RF front-end redesign requirements for rural fixed wireless overlays adjacent to C-band satellite services. Equipment integrators in Bavaria specialize in protocol translation between Wimax MAC layers and Ethernet backhaul standards.
Japan
METI coordinates industrial spectrum policy for private wireless deployments in manufacturing campuses and logistics hubs. The Ministry of Internal Affairs and Communications governs equipment certification timelines that vendors navigate for enterprise connectivity tenders. Railway operators in the Chubu region evaluate Wimax alternatives for deterministic latency in signaling applications.
Wimax Solutions Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized rural access configurations and cost-optimized router lines. The vendor base clusters around three strategic archetypes: integrated equipment portfolios anchoring large-scale public networks, specialized designs sustaining margin pools in low-density coverage zones, and cost-optimized lines dominating price-sensitive community tenders. Dominant competitive moves include geographic expansion into underserved municipal markets and technology licensing partnerships for multi-protocol software-defined radio platforms.
Within the integrated portfolio tier, Huawei Technologies and ZTE Corporation exemplify vendors leveraging captive RF engineering capabilities to compress equipment redesign cycles. Fujitsu occupies a position among specialized rural access point designers. Samsung Electronics represents the diversified electronics conglomerate archetype with cross-sector wireless expertise. These company positions reflect procurement patterns where single-vendor stacks minimize interoperability testing overhead for carrier buyers, while modular component sourcing expands options for municipal utilities unbundling hardware from managed services.
| Leading Market Players |
|---|
| Huawei Technologies |
| Fujitsu |
| Airspan Networks |
| Alvarion |
| ZTE Corporation |
| Intel Corporation |
| Samsung Electronics |
| Cisco Systems |
| Motorola Solutions |
| Others |
Supply Flow & Price Mechanics
Gallium nitride substrate costs transmit directly from power electronics demand through baseband chipset fabrication to equipment pricing tiers downstream. Input cost volatility in Taiwan's foundry complexes compresses margins for mid-tier router vendors serving Brazil's municipal tenders while premium beamforming antenna systems sustain pricing power through captive RF engineering.
Pricing Analysis
Input-cost pass-through from gallium nitride substrates and Taiwan foundry capacity constraints shapes contract-based long-term equipment procurement. Price differentiation separates certified FCC authorization tiers from uncertified community network alternatives, with volume scale and after-sales service bundling as secondary drivers. Cost compression in economy-tier access points intensifies as ZTE's cost-optimized router lines force price erosion through open tender participation. Municipal utilities in Brazil's interior cities exhibit highest price sensitivity, while India's licensed carriers under TRAI mandates prioritize reliability over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan's concentrated baseband processor fabrication at three foundry complexes. Geographic supply concentration extends to China's gallium nitride substrate production and Japan's specialized RF component manufacturing. Raw material dependencies encompass silicon wafers, ceramic substrates, and rare-earth magnet materials for antenna positioning systems. Tariff exposure on semiconductor equipment imports threatens cost structures for European vendors redesigning RF front ends under ETSI coexistence mandates. Distribution runs through carrier-direct procurement for public networks and regional system integrators for hybrid deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Equipment vendors can arbitrage certification timeline differentials between the FCC's lagging Office of Engineering and Technology cycles and India's streamlined TRAI equipment approval pathways, capturing margin premiums in faster-to-market deployments.
For Market Incumbents: Extend software-defined radio platform development to compress hardware refresh cycles against 5G fixed wireless access substitution from Ericsson and Nokia. Deepen backward integration into gallium nitride substrate sourcing to defend margin pools from power electronics demand competition. Prioritize in-house RF engineering certification investment to maintain equipment authorization velocity under FCC timeline compression.
For New Entrants and Emerging Players: Capture underserved municipal network tenders in Brazil's interior cities where fiber backhaul absence creates captive demand for wireless middle-mile solutions. Target India's gram panchayat connectivity programs under BharatNet Phase III extensions as the most penetrable geography. Deploy cost-optimized router lines through open tender participation alongside regional system integrator partnerships for network operations contracting.
For Investors and Strategic Acquirers: Consolidation pressure builds where RF engineering talent scarcity concentrates at legacy telecom equipment vendors and defense contractors. Long-term viability hinges on multi-protocol software-defined radio capabilities spanning Wimax and 5G fixed wireless access migration paths. Acquisition target archetypes include specialized rural access point designers with beamforming expertise and captive supply relationships. Watch FCC mid-band spectrum auction outcomes as the inflection signal for coverage economics viability.
| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Radio Platform Development | Enables firmware-based multi-protocol operation that compresses hardware redesign cycles under FCC mandate pressure. |
| Beamforming Antenna Array Deployment | Expands sector capacity without tower infrastructure addition for India's railway trackside connectivity programs. |
| Backward Integration into GaN Substrates | Secures supply chain resilience against power electronics demand volatility from electric vehicle inverter production. |
| Open Tender Participation in Municipal Networks | Unlocks Brazil's interior city demand where hardware procurement unbundling from managed services concentrates price pressure. |
| RF Engineering Talent Acquisition | Addresses certification timeline compression at FCC's Office of Engineering and Technology through captive design expertise. |
Methodological Framework
Bottom-up rural broadband deployment modeling reconciled against top-down equipment vendor shipment tracking forms the analytical core of this study. Primary interviews with carrier procurement directors, municipal utility network engineers, RF engineering specialists at equipment vendors, and TRAI regulatory affairs officers combined with secondary validation from FCC equipment authorization databases, Anatel spectrum auction records, ETSI harmonized standards filings, and BharatNet program disbursement reports. Triangulation across these sources ensures cross-verified volume and value estimates.
Historical trendline analysis of rural fixed wireless deployment trajectories in India, Brazil, and the United States established baseline growth patterns across the projection horizon. The analytical framework models segmentation across product type, end user, deployment model, and application with equipment certification tier as an industry-specific dimension. CAGRs derive from regression analysis of spectrum allocation timelines, universal service obligation funding disbursements, and equipment shipment correlations. Forecast inputs incorporate FCC Rural Digital Opportunity Fund subsidy allocation patterns and TRAI-mandated gram panchayat coverage targets.
Spectrum reallocation mandates, gallium nitride substrate price volatility, and 5G fixed wireless access substitution acceleration are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions regarding regulatory timeline adherence and funding program continuity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Network Technology
Global Network Monitoring Market
Network Technology
Optical Network Equipment Market
Network Technology
North America Network Management Solutions Market
Network Technology
Industrial Wireline Networking Market
Network Technology
ISP Management Systems Market
Network Technology
Philippines Software-Defined Wide Area Network (SD-WAN) Market
Network Technology
UK Fixed Connectivity Market
Network Technology
BYOD Market
Network Technology
CPE Router Market
Network Technology
Middle East & Africa Video Conferencing Hardware Market
Network Technology
Network Telemetry Market
Network Technology
Europe Structured Cabling Market
Network Technology
Wi-Fi Router Market
Network Technology
Gigabit Ethernet Market
Network Technology
2.4GHz Router Market
Network Technology
Hyperconnectivity Market