
 Passive Optical Network Market | 2026-2036
Passive Optical Network Market Size, Share, and Industry Trends Forecast 2026-2036
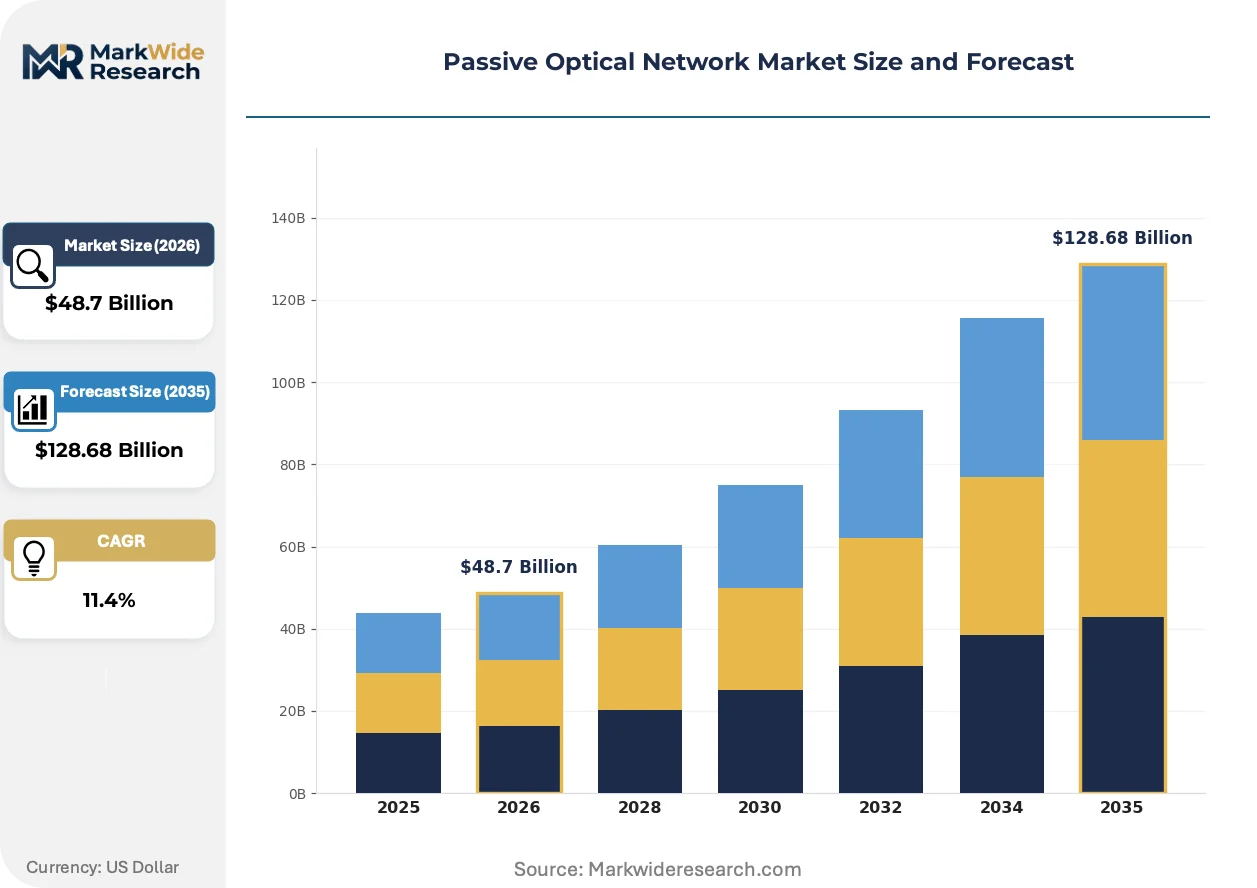
Passive Optical Network Market Outlook
Project finance tied to municipal broadband bonds is narrowing the competitive field for PON infrastructure deployment. Huawei Technologies Co., Ltd. leverages integrated optical-electrical supply chains to dominate turnkey FTTH deployments across multiple continents. Nokia Corporation anchors its position through Bell Labs-driven silicon photonics R&D that sustains product differentiation in XGS-PON and NG-PON2 segments. Calix, Inc. specializes in software-defined access platforms that extend cloud-native management to rural and regional service providers.
A passive optical network is a fiber-to-the-premises architecture that uses unpowered optical splitters to enable a single optical fiber to serve multiple endpoints, typically operating at wavelengths of 1490 nm downstream and 1310 nm upstream with split ratios up to 1:128. Its primary purpose is to deliver high-bandwidth voice, video, and data services to residential, commercial, and institutional subscribers without requiring active electronic components in the outside plant. FTTH network type leads in value contribution as fiber-deep strategies displace legacy copper and coaxial last-mile infrastructure across developed markets. Optical Line Terminal components capture concentrated margin pools due to centralized chassis complexity and software licensing attach rates. Municipal deployment models represent the fastest-growing demand category as cities issue green bonds to fund open-access fiber infrastructure.
The FCC in the United States mandates broadband mapping accuracy that steers BEAD program funding toward PON-ready projects, while the EU Green Deal and F-Gas Regulation push member states to favor passive, energy-efficient fiber architectures over powered alternatives. China's MIIT enforces GB standards for gigabit city construction that directly specify GPON and XGS-PON equipment specifications. Stakeholders must monitor how subsidy program design and spectrum allocation for fixed wireless access alternatives reshape the addressable market for fiber overbuild strategies.
Market Dynamics
The migration from GPON to XGS-PON and NG-PON2 architectures is compressing equipment refresh cycles while municipal bond financing reshapes competitive access to deployment capital. This technology transition, layered with national broadband mandates across multiple continents, is restructuring vendor-customer relationships and procurement timelines.
Growth Catalysts
- South Korea's national broadband mandate:Government targets for universal gigabit connectivity are accelerating fiber-to-the-home deployments and forcing incumbent carriers to upgrade splitter networks and terminal equipment.
- China's MIIT GB standards for gigabit cities:Mandatory equipment specifications for GPON and XGS-PON are standardizing procurement volumes and reducing interoperability friction across provincial deployments.
- Municipal green bond issuance:Cities in North America and Europe are funding open-access fiber infrastructure through sustainability-linked debt instruments, creating dedicated capital pools for PON deployment.
Market Restraints
- Optical component supply concentration:Laser diode and transceiver manufacturing clusters in East Asia create vulnerability to regional logistics disruptions and export control friction.
- Fixed wireless access substitution:Mid-band spectrum allocation for 5G FWA is enabling competitive broadband delivery without fiber trenching in suburban and exurban markets.
- Copper infrastructure stranded asset risk:Incumbent carriers face balance sheet pressure from accelerated depreciation of legacy DSL and HFC networks during fiber overbuild cycles.
Strategic Opportunities
- Rural cooperative utility models:Electric cooperatives in the United States are leveraging existing pole infrastructure and USDA Rural Utilities Service financing to deploy PON in underserved counties.
- EU Green Deal energy efficiency mandates:The F-Gas Regulation and building decarbonization frameworks are directing public subsidy toward passive, unpowered optical architectures over active electronics.
- Convergence of PON with 5G fronthaul:XGS-PON wavelength allocation is converging with mobile network timing requirements, enabling shared fiber infrastructure for residential and cellular traffic.
Industry Challenges
- Fiber splicing technician scarcity:Specialized fusion splicing and optical time-domain reflectometry skills are concentrated among aging workforces in developed markets, constraining deployment velocity.
- Multi-vendor interoperability certification:Open RAN-inspired disaggregation in access networks is extending testing timelines for optical network terminal and line terminal compatibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Passive Optical Network Market |
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $128.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Network Type: FTTH, FTTB, FTTN, FTTP Component: Optical Line Terminal, Splitters, Optical Network Units, Passive Optical Components Deployment Model: Residential, Commercial, Industrial, Municipal End User: Telecom Providers, Internet Service Providers, Enterprises, Government |
| Companies Covered | Huawei Technologies Co., Ltd., Nokia Corporation, Cisco Systems, Inc., ZTE Corporation, ADTRAN, Inc., Calix, Inc., Ciena Corporation, Infinera Corporation, Broadcom Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Passive Optical Network Market Strategic Shifts
Silicon photonics integration and software-defined access platforms are converging to compress hardware costs while extending cloud-native management to network edges. These developments are redrawing competitive boundaries between optical component suppliers and systems integrators.
Co-packaged silicon photonics transceivers are integrating laser sources directly onto switch ASIC substrates, eliminating discrete optical sub-assembly costs. Tier-one carriers in Japan and Germany are qualifying these modules for central office deployment. This integration is rendering obsolete traditional pluggable transceiver form factors that dominated 10G PON generations.
The EU F-Gas Regulation is banning hydrofluorocarbon-based cooling in active network equipment, redirecting subsidy eligibility toward passive optical architectures. Equipment vendors are redesigning thermal profiles for outdoor plant electronics. XGS-PON optical line terminals with passive cooling are capturing preference in municipal procurement across France and the Netherlands.
Service providers are unbundling network operations software from hardware chassis, purchasing access platforms as disaggregated layers. Regional carriers in the United States are adopting cloud-native network operating systems from independent software vendors. This procurement pattern is most visible among electric cooperatives and municipal utilities building fiber networks with BEAD program support.
Passive Optical Network Market Segmentation
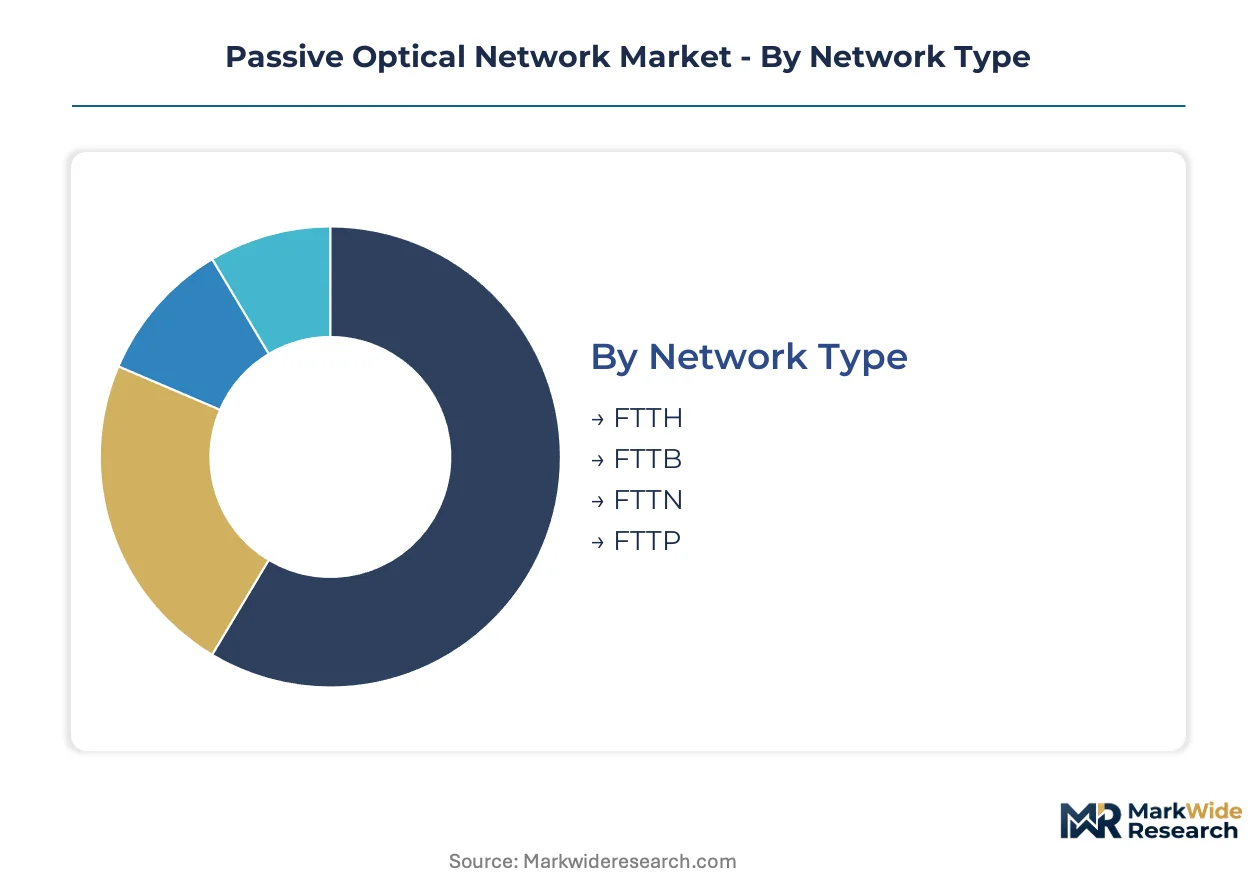
PON market segmentation reveals how fiber architecture choices, equipment hierarchies, and customer procurement patterns concentrate margin pools. Vendors must align product roadmaps with the specific technical and financing requirements of each deployment category.
Network Type:
Mature fiber-to-the-premises architectures dominate current deployment volumes, while emerging configurations address density and cost constraints in specific build environments.
- FTTH:Fiber reaches individual subscriber premises with dedicated optical network terminals. South Korea's national broadband mandate accelerates FTTH deployment as carriers replace legacy copper with full-fiber drops to apartment complexes and single-family homes.
- FTTB:Fiber terminates at building basements with existing in-building copper or coaxial distribution. China's municipal smart city initiatives favor FTTB in high-rise residential zones where in-building rewiring costs would exceed fiber penetration budgets.
- FTTN:Fiber extends to neighborhood nodes with copper completing the last segment. Rural electric cooperatives in the United States deploy FTTN as an interim bridge where full fiber trenching exceeds USDA Rural Utilities Service financing thresholds.
- FTTP:Fiber reaches premises without specifying residential or commercial endpoint type. European open-access network operators standardize on FTTP terminology in municipal green bond prospectuses to preserve service flexibility.
FTTH handles the majority of throughput; FTTP is the fastest mover on share as procurement language standardizes across subsidy programs.
Component:
Cost tier differentiation separates high-complexity centralized equipment from commodity edge devices with thinner margin structures.
- Optical Line Terminal:Central office chassis aggregate upstream traffic from multiple PON ports with integrated switching and management functions. Software licensing attach rates for cloud-native orchestration platforms sustain vendor margins in this segment.
- Splitters:Passive optical devices divide downstream signals across 32 to 128 endpoints without electrical power. Planar lightwave circuit manufacturing in East Asia concentrates supply for 1:64 and 1:128 split ratios now specified in China's MIIT GB standards.
- Optical Network Units:Subscriber-side terminals convert optical signals to Ethernet or POTS interfaces. Multi-vendor interoperability certification extends deployment timelines as carriers qualify third-party ONUs for open-access networks.
- Passive Optical Components:Wavelength division multiplexers, filters, and connectors complete fiber distribution networks. EU F-Gas Regulation compliance requirements favor passive cooling designs that eliminate active thermal management in outdoor plant housing.
Optical Line Terminal captures the steepest margin concentration; Passive Optical Components are climbing the fastest as wavelength division multiplexing density increases.
Deployment Model:
Customer type determines procurement channel structure, with municipal and industrial buyers following distinct financing and technical specification pathways from residential and commercial segments.
- Residential:Single-family and multi-dwelling unit deployments prioritize cost-per-subscriber metrics. Incumbent carriers in Japan bundle residential PON with mobile service convergence to improve customer lifetime value calculations.
- Commercial:Small and medium enterprise connections require symmetric bandwidth guarantees and service level agreements. German Mittelstand manufacturing clusters drive commercial PON demand for Industry 4.0 connectivity requirements.
- Industrial:Factory floor and logistics hub deployments integrate PON with operational technology networks. South Korean automotive and semiconductor facilities specify XGS-PON for deterministic latency in automated quality control systems.
- Municipal:City-owned open-access infrastructure separates physical layer from retail service provision. French and Dutch cities issue sustainability-linked bonds that mandate passive cooling and energy-efficient equipment specifications.
Residential accounts for the largest subscriber base; Municipal is expanding most quickly as green bond issuance accelerates.
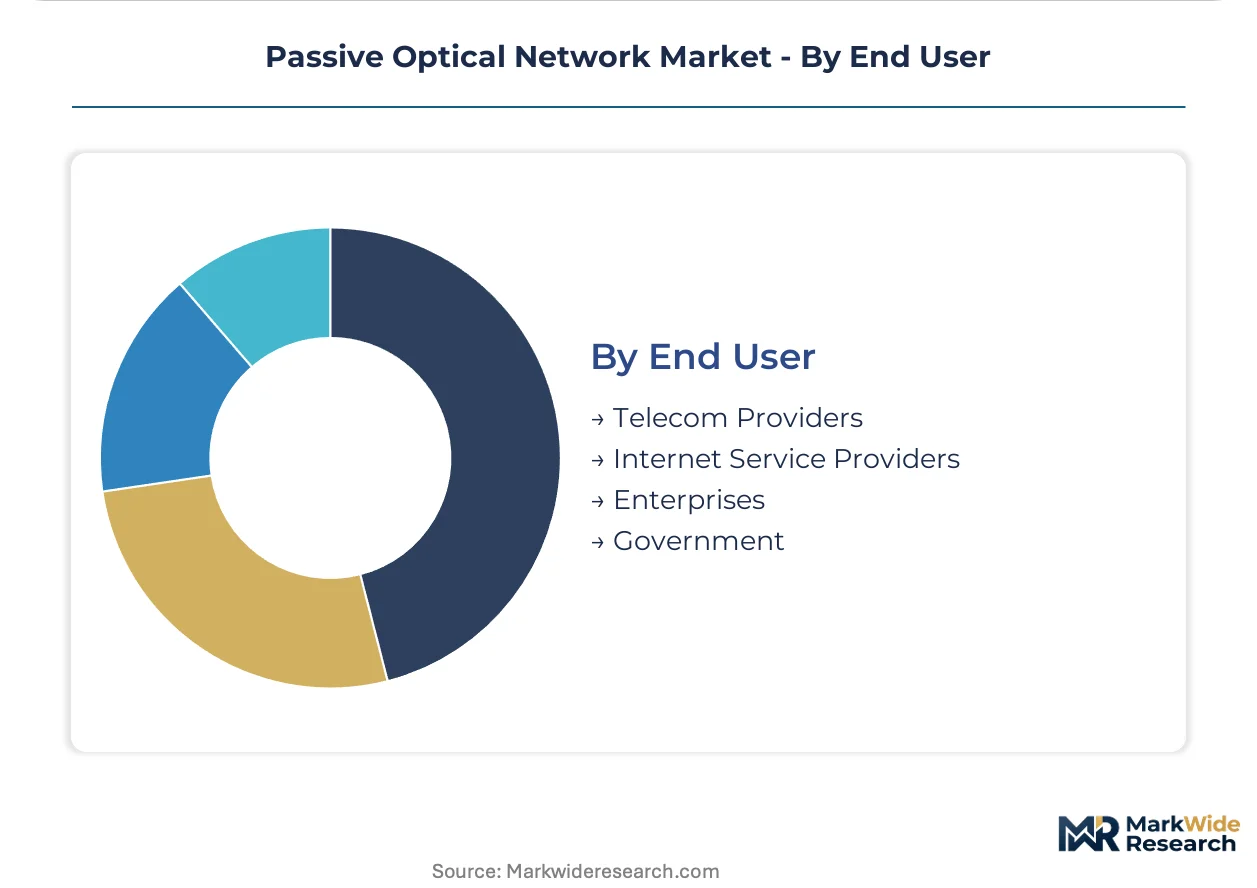
End User:
Volume concentration sits with large-scale infrastructure owners, while enterprise and government buyers introduce procurement complexity through specialized security and interoperability requirements.
- Telecom Providers:Incumbent and competitive carriers build PON as core access infrastructure. Verizon and AT&T in the United States steer BEAD program funding toward XGS-PON-ready projects that satisfy FCC broadband mapping accuracy mandates.
- Internet Service Providers:Competitive retail providers lease municipal or utility fiber infrastructure. Regional ISPs in the United States adopt software-defined access platforms to unbundle network operations from hardware procurement.
- Enterprises:Large corporations deploy private PON for campus and distributed site connectivity. Japanese automotive manufacturers qualify co-packaged silicon photonics transceivers for central office deployment in proprietary fiber networks.
- Government:Federal, state, and local agencies fund or directly operate fiber infrastructure. The FCC's BEAD program and China's MIIT gigabit city construction standards directly shape equipment procurement specifications for government-backed deployments.
Telecom Providers carry the dominant deployment volume; Government is gaining share fastest as national broadband mandates expand subsidy pools.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
National broadband mandates and municipal green bond programs are steering deployment capital toward fiber-deep architectures across key markets. The FCC's BEAD program, China's MIIT gigabit city standards, and the EU Green Deal are reshaping procurement specifications and vendor access.
United States
Electric cooperatives and municipal utilities are deploying PON infrastructure using USDA Rural Utilities Service financing and BEAD program subsidies. The FCC mandates broadband mapping accuracy that directs funding toward XGS-PON-ready projects. Deployment concentrates in the Southeast and Midwest where rural fiber overbuilds displace legacy copper networks.
China
Municipal smart city initiatives and gigabit city construction standards are standardizing GPON and XGS-PON equipment specifications across provincial deployments. MIIT enforces GB standards that reduce interoperability friction and concentrate procurement volumes. Yangtze River Delta cities including Shanghai and Hangzhou anchor the densest fiber penetration rates globally.
South Korea
Government targets for universal gigabit connectivity are accelerating fiber-to-the-home deployments and forcing incumbent carriers to upgrade splitter networks. The national broadband mandate compresses equipment refresh cycles for terminal equipment. Seoul Capital Area carriers are migrating from GPON to XGS-PON architectures ahead of regulatory deadlines.
Germany
The EU Green Deal and F-Gas Regulation are directing public subsidy toward passive, energy-efficient fiber architectures over powered alternatives. Building decarbonization frameworks favor PON with passive cooling designs. Industrial clusters in Bavaria and Baden-Württemberg are specifying XGS-PON for Mittelstand manufacturing connectivity requirements.
Japan
Tier-one carriers are qualifying co-packaged silicon photonics transceivers for central office deployment as they migrate from 10G PON generations. METI policies support fiber-deep strategies in preparation for 2025 digital infrastructure targets. Kanto region operators including Tokyo-based carriers are converging residential PON with 5G fronthaul wavelength allocation.
Passive Optical Network Market Competitive Environment
On the supply side, the industry is consolidating around integrated optical-electrical supply chains and silicon photonics capabilities. Tier-one equipment vendors and component specialists occupy distinct margin tiers. Strategic archetypes include turnkey FTTH deployers, Bell Labs-driven R&D anchors, and software-defined access platforms. Competitive moves center on municipal bond financing access and cloud-native orchestration licensing attach rates.
Within the integrated supply chain tier, Huawei Technologies Co., Ltd. and Nokia Corporation exemplify divergent positioning strategies. Huawei leverages captive optical-electrical manufacturing to dominate turnkey deployments across multiple continents. Nokia anchors its market presence through Bell Labs-driven silicon photonics research that sustains product differentiation in next-generation PON segments. Calix, Inc. occupies a specialist position in software-defined access platforms that extend cloud-native management to regional service providers and electric cooperatives.
| Leading Market Players |
|---|
| Huawei Technologies Co., Ltd. |
| Nokia Corporation |
| Cisco Systems, Inc. |
| ZTE Corporation |
| ADTRAN, Inc. |
| Calix, Inc. |
| Ciena Corporation |
| Infinera Corporation |
| Broadcom Inc. |
| Others |
Value Chain & Pricing Dynamics
Shanghai-Ningbo port freight corridors govern landed cost differentials for optical transceivers entering European and North American markets, compressing margins for vendors without captive East Asian manufacturing while amplifying price spreads between certified and uncertified equipment tiers.
Pricing Analysis
Certification level creates the primary spread between equipment tiers, with CE-marked and MIIT GB-compliant XGS-PON terminals commanding substantial premiums over non-certified alternatives in municipal procurement channels. Pricing stratifies across three tiers: premium chassis with cloud-native orchestration licensing, standard GPON hardware with basic management, and economy splitters for volume residential builds. Cost compression in the standard tier is intensifying as Chinese vendors expand planar lightwave circuit capacity. Electric cooperatives and rural utilities exhibit the highest price sensitivity, while tier-one carriers in Japan and South Korea prioritize performance guarantees over unit economics.
Supply Chain Analysis
Indium phosphide and silicon-on-insulator wafers feed concentrated laser diode manufacturing in Taiwan, South Korea, and Japan, with planar lightwave circuit splitters drawing primarily from Chinese foundries in Jiangsu and Guangdong provinces. Raw material dependencies center on rare earth elements for optical amplification, high-purity silica for fiber preforms, and specialized photoresists for photonic chip fabrication. Single-source vulnerability concentrates in 25G+ electro-absorption modulated laser packaging, where two Japanese vendors anchor global supply. Distribution runs through tier-one systems integrators for carrier deployments and direct procurement channels for municipal utilities accessing BEAD program funding.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of fusion splicing technicians with OTDR certification constrains deployment velocity across North American and European markets, creating bottlenecks that favor vendors with embedded training programs and automated installation tooling.
For Market Incumbents: Build switching-cost moats through cloud-native orchestration platform stickiness and multi-year software licensing attach. Defensive priorities center on securing MIIT GB pre-certification for next-generation NG-PON2 equipment ahead of Chinese provincial procurement waves, while adding captive silicon photonics capacity in Taiwan or Japan to reduce transceiver cost exposure. For New Entrants and Emerging Players: Build out software-defined access platform specialization targeting electric cooperatives and municipal utilities underserved by tier-one vendors. The most penetrable white-space sits in USDA Rural Utilities Service-financed counties where incumbent carriers have deferred fiber overbuilds. Go-to-market traction requires BEAD program compliance documentation and passive-cooled OLT thermal profiles matching EU F-Gas Regulation mandates. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with undermonetized optical component divisions, particularly those holding planar lightwave circuit or silicon photonics patents without dedicated PON product lines. Long-term viability hinges on wavelength convergence with 5G fronthaul requirements and energy efficiency certification trajectories. The signal to watch is municipal green bond issuance velocity as a proxy for open-access infrastructure capital formation.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Photonics Integration | Co-packaged transceivers eliminate discrete optical sub-assembly costs for Japanese tier-one carriers. |
| Cloud-Native Orchestration Licensing | Software attach rates sustain vendor margins as hardware commoditizes in GPON segments. |
| MIIT GB Pre-Certification | Early compliance secures provincial procurement slots under China's gigabit city construction mandates. |
| Passive Cooling Redesign | Thermal profile optimization captures EU municipal preference under F-Gas Regulation restrictions. |
| Technician Training Program Deployment | Embedded certification pipelines accelerate rural build velocity for BEAD-funded cooperatives. |
Study Parameters
Initial hypotheses were tested against primary input from optical network architects at tier-one carriers, procurement directors at municipal utilities, fusion splicing technicians in the field, and regulatory affairs leads at equipment vendors, then refined through secondary validation against FCC broadband deployment databases, MIIT GB standard filings, EU Green Deal implementation reports, and SEC 10-K disclosures from listed optical component suppliers. Bottom-up equipment shipment tallies triangulated against top-down infrastructure spending estimates derived from national broadband mandate budget allocations.
Demand-supply balance modeling across the analysis window segmented volumes by network type, component category, deployment model, and end-user archetype, with wavelength division multiplexing density and software licensing attach rates as industry-specific forecast inputs. CAGRs were derived from S-curve penetration modeling calibrated to historical GPON-to-XGS-PON migration patterns in South Korea and Japan.
Sensitivities concentrate around export control friction affecting laser diode shipments, fixed wireless access spectrum allocation decisions, and municipal bond market liquidity conditions. Cross-checking against NTIA BEAD funding disbursement rates and MIIT provincial procurement announcements is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Network Technology
Germany Residential Gateway Market
Network Technology
Mobile Backhaul Market
Network Technology
Power Over Ethernet (Poe) Solutions Market
Network Technology
Cloud Gateway Module Market
Network Technology
Global Carrier Wi-Fi Equipment Market
Network Technology
Mobile Accelerator Market
Network Technology
Small Cell Networks Market
Network Technology
Network Management Solutions Market
Network Technology
Global Network Probe Market
Network Technology
Sand Lane Systems Market
Network Technology
North America Enterprise WLAN Market
Network Technology
United States and European Fiber Optic Cable Market
Network Technology
Mobile Network Optimization Market
Network Technology
Protocol Analyzer Market
Network Technology
Global Enterprise Session Border Controller (SBC) Market
Network Technology
Data Center Switches Market