
 Global Gigabit Wi-Fi Access Points Market | 2026-2036
Global Gigabit Wi-Fi Access Points Market Size, Share, and Industry Trends Forecast 2026-2036
Global Gigabit Wi-Fi Access Points Market Foresight
Equipment leasing and managed-network-as-a-service models are reconfiguring capital deployment for mid-market buyers who previously deferred gigabit upgrades. Cisco Systems leverages its channel density to bundle access points with security subscriptions, while Aruba Networks anchors campus contracts through cloud-managed switching integration. Ubiquiti Networks competes on price-performance for distributed small-office deployments across emerging markets.
Gigabit Wi-Fi Access Points are radio hardware devices transmitting at or above one gigabit per second aggregate throughput, utilizing 802.11ax or 802.11be chipsets with 160 MHz channel bonding and OFDMA scheduling to minimize latency in dense client environments. Indoor access points dominate volume shipments for enterprise retrofits, though outdoor units command premium pricing for IP-rated thermal resilience in transportation and stadium settings. Wi-Fi 6E segments are capturing margin pools where 6 GHz greenfield spectrum justifies immediate hardware replacement, while Wi-Fi 7 positions for throughput-intensive applications in broadcast and immersive collaboration venues.
The FCC's 6 GHz framework, the EU's Radio Equipment Directive with CE marking requirements, and Japan's MIC spectrum certifications collectively shape product validation timelines and regional launch sequencing. Compliance with ETSI EN 303 687 in Europe and FCC Part 15 subpart E in the United States forces dual-sku strategies that fragment inventory management. Stakeholders must monitor spectrum auction outcomes in India and Brazil to calibrate regional product roadmaps against local channel availability and power regulations.
Market Dynamics
Radio frequency spectrum reallocation by regulators in the United States, Germany, and Japan is compressing enterprise hardware refresh cycles and forcing simultaneous multi-standard chipset development.
Growth Catalysts
- 6 GHz spectrum liberalization:The FCC's Part 15 subpart E framework and BNetzA's 6 GHz implementation in Germany unlock greenfield channels for Wi-Fi 6E and Wi-Fi 7 deployments in dense urban offices.
- Immersive collaboration venues:Broadcast studios and esports arenas in Singapore and South Korea demand sub-10ms latency that OFDMA scheduling on 160 MHz channels delivers.
- Transportation infrastructure:Metro systems across Japan and stadium corridors in the United States require IP-rated outdoor units with thermal resilience for uninterrupted passenger connectivity.
Market Restraints
- Dual-sku inventory fragmentation:ETSI EN 303 687 in Europe and FCC Part 15 subpart E in the United States force separate product variants that complicate supply chain planning.
- GaN and RF frontend cost volatility:Gallium nitride substrate prices fluctuate with compound semiconductor foundry capacity concentrated in Taiwan.
- Legacy 802.11n/ac substitution inertia:Mid-market enterprises in Brazil and India extend depreciation schedules on existing infrastructure rather than absorbing immediate replacement capex.
Strategic Opportunities
- Managed-network-as-a-service channel expansion:Equipment leasing models penetrate mid-market buyers in Germany who previously deferred gigabit upgrades due to capital constraints.
- Wi-Fi 7 and 320 MHz channel bonding:The IEEE 802.11be standard converges with 6 GHz spectrum availability to enable 10 Gbps throughput for 8K video distribution in Japanese broadcast facilities.
- India's delayed 6 GHz auction:Underpenetrated spectrum allocation creates first-mover positioning for vendors who pre-certify hardware with TRAI and BIS frameworks.
Industry Challenges
- RF engineer talent scarcity:Compound semiconductor design expertise for mmWave frontend integration concentrates in South Korea and the United States, constraining R&D scaling.
- Multi-regulatory certification timelines:Simultaneous FCC, CE marking, and MIC validation cycles extend product launch windows by eight to fourteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Gigabit Wi-Fi Access Points Market |
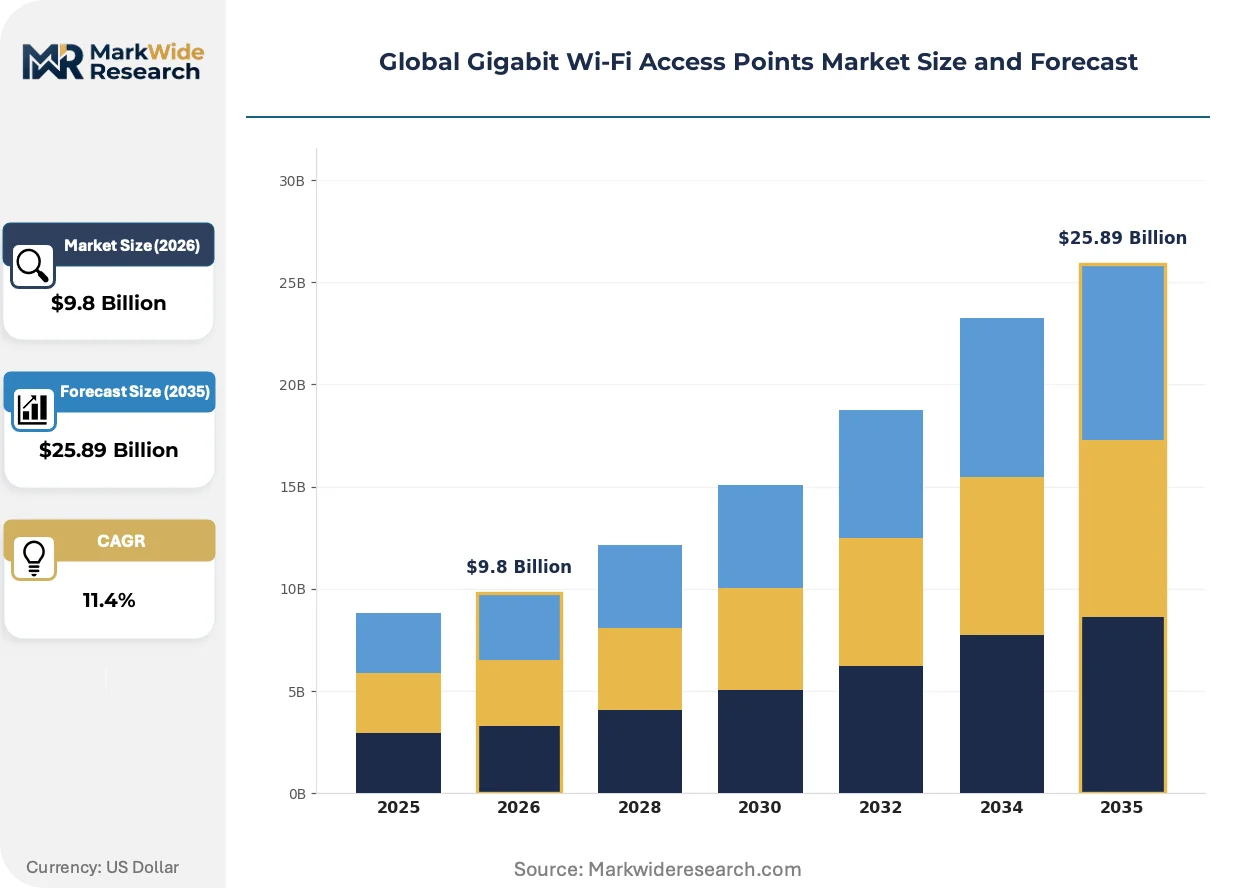
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $25.89 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Indoor, Outdoor, Wall-Mounted, Ceiling-Mounted, Desktop, Industrial Technology: Wi-Fi 5, Wi-Fi 6, Wi-Fi 6E, Wi-Fi 7, MU-MIMO, Beamforming Application: Enterprise Networks, Hospitality, Education Campuses, Government Facilities, Transportation Hubs, Event Venues End User: Small Office, Large Corporate, Co-Working Spaces, Data Centers, Retail Chains, Public Libraries |
| Companies Covered | Cisco Systems, Aruba Networks, Hewlett Packard Enterprise, NETGEAR, Ubiquiti Networks, Ruckus Wireless, Fortinet, D-Link Systems, TP-Link, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Gigabit Wi-Fi Access Points Market Shifts & Advancements
Network function virtualization is dissolving the boundary between hardware-centric radio access and software-defined traffic management, enabling new deployment economics across enterprise verticals.
Cloud-native access point management is virtualizing controller functions that previously required on-premises appliances. Large campus buyers in the United States and Germany are migrating to subscription-based orchestration platforms that reduce operational headcount. This architecture is virtualizing traditional value capture from hardware margins toward recurring software revenue streams.
The EU's Radio Equipment Directive with updated CE marking requirements for 6 GHz equipment is mandating stricter electromagnetic compatibility testing. Manufacturers must redesign thermal management systems to meet ETSI EN 303 687 power-density limits. European enterprise distributors are prioritizing pre-certified SKUs to avoid customs detention at Rotterdam and Hamburg ports.
Enterprise buyers are consolidating vendor relationships and demanding bundled security subscriptions with access point procurement. Value-added distributors in Japan are displacing pure hardware resellers by offering managed detection and response services alongside Aruba and Cisco deployments. This consolidation is most visible in financial services verticals across Singapore and South Korea where CISOs refuse multi-vendor wireless architectures.
Global Gigabit Wi-Fi Access Points Market Segmentation
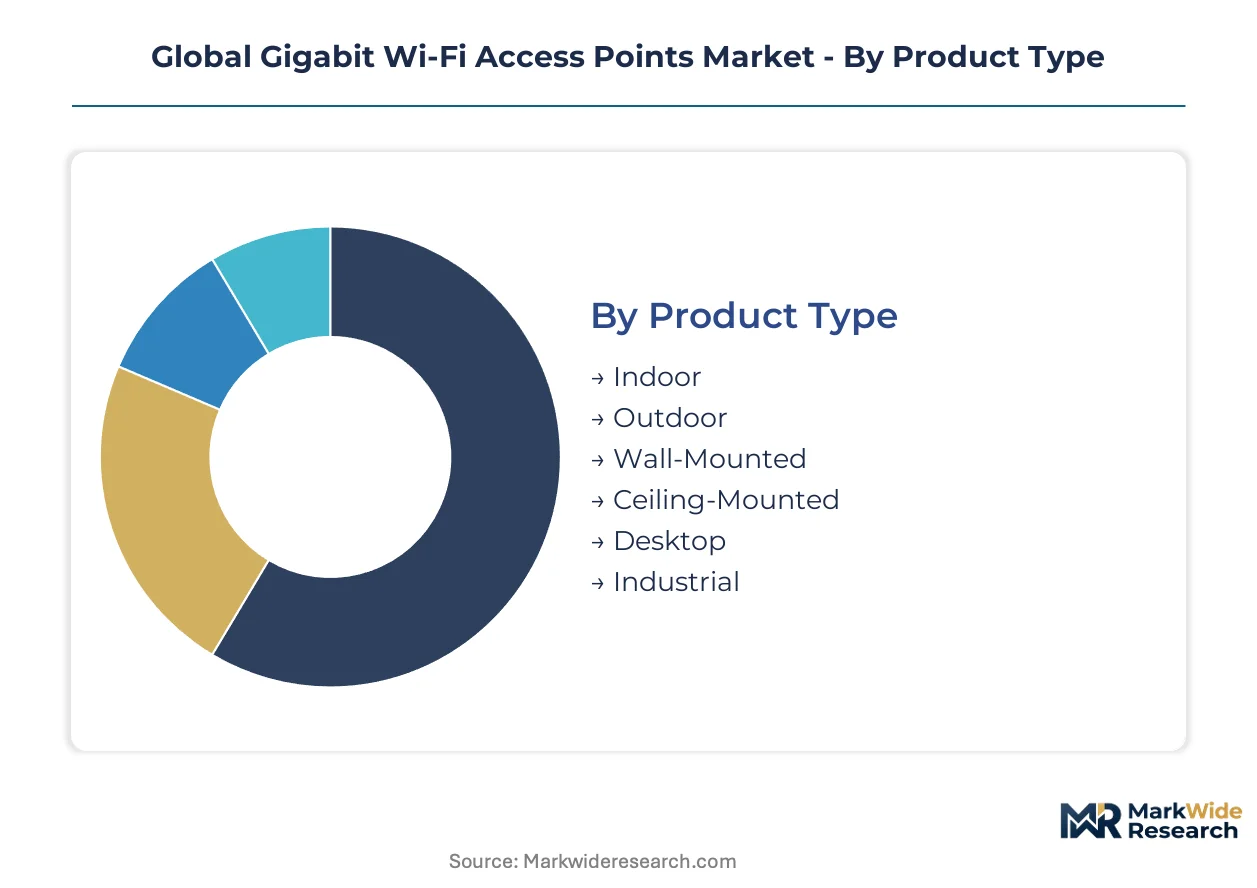
Segmentation in the Gigabit Wi-Fi Access Points Market reveals how deployment environments, spectrum capabilities, and organizational scale dictate hardware specifications and procurement patterns. Vendors must align product roadmaps across multiple orthogonal dimensions to capture divergent buyer requirements.
Product Type:
Mature form factors dominate enterprise retrofit volumes while emerging designs address thermal and mounting constraints in specialized environments.
- Indoor:Standard enterprise-grade enclosures with integrated antennas serve carpeted offices and conference facilities across the United States and Germany. Dense cubicle layouts in financial services verticals drive demand for ceiling-mounted density with PoE++ power delivery.
- Outdoor:IP67-rated housings with extended temperature tolerances withstand monsoon humidity in Singapore transit corridors and winter conditions in Japanese stadium perimeters. These units command manufacturing premiums due to conformal coating and sealed connector assemblies.
- Wall-Mounted:Low-profile enclosures suit hospitality corridors and classroom retrofits where ceiling infrastructure is inaccessible.
- Ceiling-Mounted:Discreet dome designs integrate with suspended tile grids across corporate campuses in South Korea.
- Desktop:Standalone units address small-office deployments and temporary event infrastructure.
- Industrial:Hardened enclosures meet vibration and electromagnetic interference specifications for manufacturing floors in Germany.
Indoor access points retain volume leadership; outdoor units hold the steepest expansion curve.
Technology:
Cost tier stratification separates legacy refresh cycles from premium greenfield deployments as spectrum allocation timelines diverge across regulatory jurisdictions.
- Wi-Fi 5:802.11ac Wave 2 chipsets with 160 MHz channel support address budget-constrained retrofits in Brazilian mid-market enterprises extending depreciation schedules.
- Wi-Fi 6:OFDMA and 1024-QAM capabilities dominate current enterprise procurement in the United States as IT departments standardize on 802.11ax infrastructure.
- Wi-Fi 6E:6 GHz radio modules unlock contiguous spectrum blocks in FCC and BNetzA jurisdictions, justifying immediate hardware replacement in dense urban offices. Greenfield 6 GHz availability positions this segment for margin capture where regulatory clarity exists.
- Wi-Fi 7:320 MHz channel bonding and 4K-QAM modulation target 8K video distribution in Japanese broadcast studios and esports arenas demanding sub-10ms latency.
- MU-MIMO:Multi-user spatial streaming remains standard across all modern chipsets for high-density client environments.
- Beamforming:Explicit beamforming protocols optimize signal directionality in stadium and transportation hub deployments.
Wi-Fi 6 maintains installed base dominance; Wi-Fi 6E is climbing the fastest as spectrum liberalization accelerates replacement cycles.
Application:
Customer type differentiation separates capital-intensive infrastructure projects from operational expenditure models as managed service penetration deepens.
- Enterprise Networks:Campus-wide deployments across Fortune 500 headquarters in the United States require centralized orchestration platforms with integrated security policy enforcement. These contracts anchor vendor revenue through multi-year refresh cycles.
- Hospitality:Guest-facing networks in Singapore and Dubai hotel portfolios prioritize seamless roaming and captive portal integration over raw throughput metrics.
- Education Campuses:K-12 and university networks in Japan balance density requirements against constrained IT operational budgets.
- Government Facilities:Classified and unclassified network segmentation drives FIPS 140-2 compliance requirements in federal buildings.
- Transportation Hubs:Metro systems in Seoul and airport terminals in Frankfurt demand outdoor-rated units with passenger flow analytics integration.
- Event Venues:Temporary high-density configurations for concert halls and convention centers in Las Vegas utilize mesh failover architectures.
Enterprise networks command the largest revenue pool; transportation hubs are expanding most quickly as smart city investments accelerate.
End User:
Volume concentration versus margin opportunity splits the addressable market between price-sensitive distributed sites and integrated campus contracts.
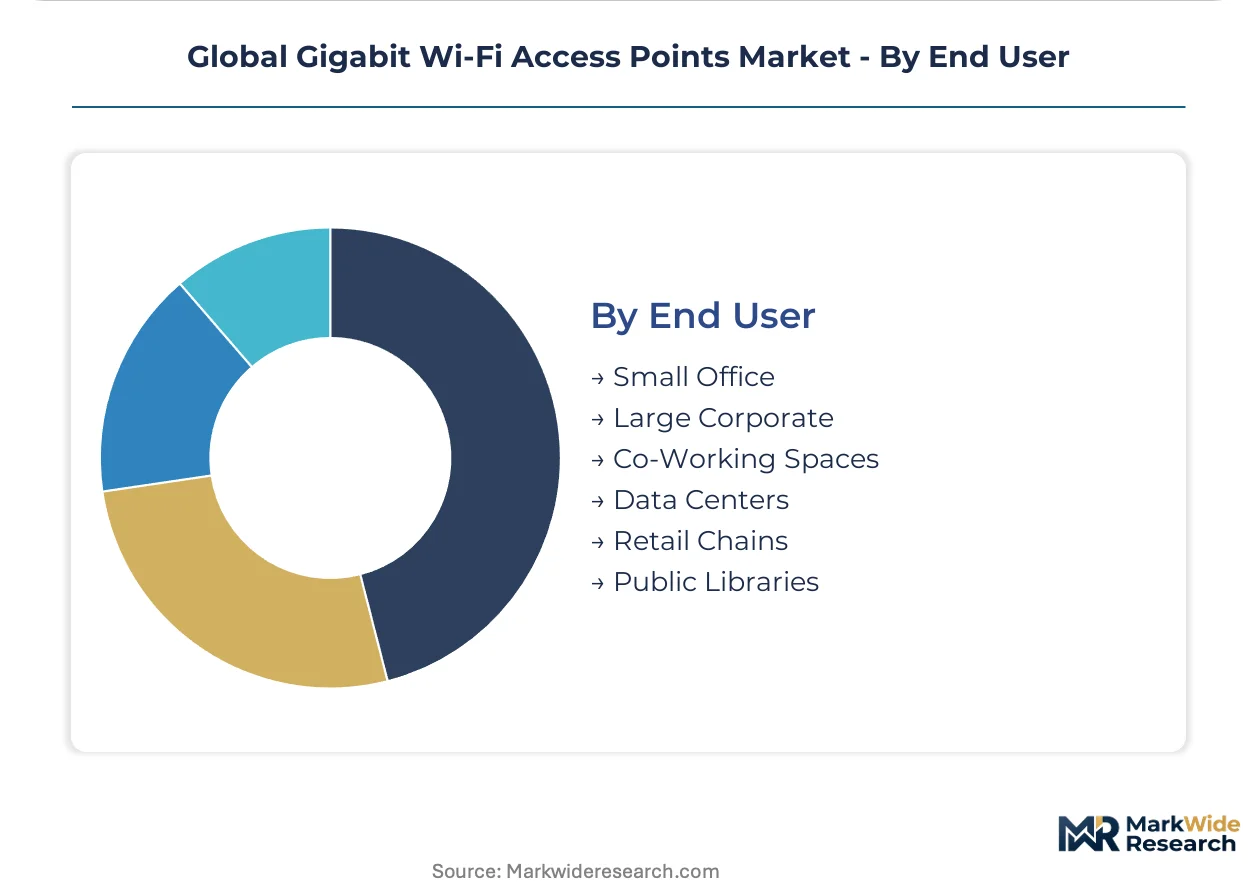
- Small Office:Sub-50 employee deployments across India and Southeast Asia prioritize unmanaged or cloud-simplified configurations with minimal IT staffing.
- Large Corporate:Global headquarters and regional offices in Germany and the United States drive demand for unified wired-wireless policy management at scale.
- Co-Working Spaces:WeWork-style operators in London and New York require tenant-isolated network slices with usage-based billing integration.
- Data Centers:Out-of-band management networks and edge compute connectivity in Ashburn and Frankfurt facilities demand deterministic latency.
- Retail Chains:Thousands of franchise locations in Brazil require zero-touch provisioning for distributed deployment velocity.
- Public Libraries:Municipal funding cycles in Japan and Canada extend procurement timelines despite universal service mandates.
Large corporate deployments generate the highest average contract value; co-working spaces are gaining share fastest as flexible workspace models proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States maintains a structural trade surplus in enterprise networking hardware while importing consumer-grade chipsets from Taiwanese foundries. Germany and Japan balance domestic manufacturing of industrial-grade access points with reliance on South Korean RF component supplies. India's delayed spectrum liberalization creates import dependency for Wi-Fi 6E and Wi-Fi 7 equipment.
United States
FCC Part 15 subpart E regulations accelerated 6 GHz equipment certification timelines for enterprise campus deployments. Fortune 500 headquarters in Chicago and Dallas drive concentrated demand for cloud-managed access point infrastructure. Silicon Valley vendors anchor R&D investment in multi-gigabit OFDMA scheduling technologies.
Germany
BNetzA's 6 GHz implementation compresses hardware refresh cycles across automotive and industrial verticals. ETSI EN 303 687 electromagnetic compatibility requirements force thermal management redesigns for European market entry. Bavarian manufacturing clusters around Munich prioritize IP-rated industrial access points for smart factory deployments.
Japan
MIC spectrum certifications for Wi-Fi 6E and Wi-Fi 7 enable broadcast studio upgrades in Tokyo and Osaka. Dense urban transit corridors in the Greater Tokyo Area concentrate demand for outdoor-rated units with passenger flow analytics. Japanese enterprises exhibit strong preference for domestic-integrated security policy enforcement.
South Korea
Seoul Capital Area metro systems and Incheon airport terminals deploy multi-gigabit throughput for immersive passenger connectivity. Esports arenas in Busan and Gwangju demand sub-10ms latency that 160 MHz channel bonding delivers. Domestic semiconductor foundries supply RF frontends reducing import dependency for local network equipment assemblers.
Singapore
Smart nation infrastructure investments accelerate procurement of stadium and transit corridor access points with environmental resilience ratings. Hospitality portfolios in Marina Bay and Orchard Road prioritize seamless roaming over raw throughput metrics. The city-state functions as a regional distribution hub for Southeast Asian enterprise deployments.
Global Gigabit Wi-Fi Access Points Market Competitive Landscape
On the supply side, the industry is consolidating around three distinct capability tiers. Tier-one vendors bundle access points with security subscriptions and cloud orchestration platforms. Tier-two specialists compete on price-performance for distributed small-office deployments. Tier-three regional assemblers serve price-constrained emerging markets with simplified management interfaces. Dominant competitive moves include strategic partnerships for RF frontend supply security and portfolio diversification into managed-network-as-a-service delivery models.
Within the integrated-platform tier, Cisco Systems and Aruba Networks exemplify vendors anchoring enterprise campus contracts through unified wired-wireless policy management. Ubiquiti Networks occupies a distinct position serving distributed small-office deployments across emerging markets with cloud-simplified configurations. These three companies collectively represent the spectrum of competitive positioning from premium integrated stacks to price-optimized distributed coverage.
| Leading Market Players |
|---|
| Cisco Systems |
| Aruba Networks |
| Hewlett Packard Enterprise |
| NETGEAR |
| Ubiquiti Networks |
| Ruckus Wireless |
| Fortinet |
| D-Link Systems |
| TP-Link |
| Others |
Supply & Pricing Matrix
Foundry undercapacity in Taiwan concentrates GaN substrate supply for RF frontends, compressing component availability while elevating pricing power among compound semiconductor suppliers serving access point manufacturers in the United States and Germany.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Certification tier under FCC Part 15 subpart E and ETSI EN 303 687 frameworks drives price differentiation, with CE-marked variants commanding manufacturing premiums over baseline SKUs. Cost compression in economy tiers is intensifying because mid-market enterprises in Brazil and India extend depreciation schedules on legacy 802.11n/ac infrastructure. Small-office deployments across Southeast Asia exhibit highest price sensitivity, while Japanese broadcast studios purchasing Wi-Fi 7 equipment for 8K video distribution demonstrate lowest.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculations for access point vendors sourcing PCB assemblies and power management ICs. Manufacturing concentrates in Taiwan for RF chipsets, South Korea for GaN substrates, and China for final assembly and enclosure fabrication. Raw material dependencies span gallium nitride wafers, high-frequency laminates, and PoE++ magnetic components. Distribution runs through value-added distributors in Rotterdam, Singapore, and Dallas who bundle security subscriptions with hardware procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Managed-network-as-a-service attach rates are expanding faster than hardware unit growth, converting capital expenditure buyers into recurring-revenue relationships that improve lifetime value metrics across enterprise verticals.
For Market Incumbents: Build switching-cost moats through cloud-managed orchestration platform stickiness. Deepen backward integration into RF frontend design to reduce GaN substrate cost volatility exposure. Anchor campus contracts through unified wired-wireless policy management that raises substitution costs for competitors targeting Aruba Networks and Cisco Systems installed bases.
For New Entrants and Emerging Players: Mid-market commercial buildings in Southeast Asia represent the most penetrable entry point where IT staffing constraints favor cloud-simplified configurations. India's delayed 6 GHz spectrum auction creates pre-certification positioning opportunities against TRAI and BIS frameworks. Pursue zero-touch provisioning partnerships with retail chain distributors in Brazil to achieve deployment velocity without direct enterprise sales infrastructure.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vendors bundling security subscriptions with access point hardware, indicating superior cash-flow quality for portfolio allocation. Long-term viability over the next decade hinges on IEEE 802.11be standard adoption velocity and 320 MHz channel bonding certification timelines. Monitor India's TRAI spectrum auction announcements as the critical inflection signal for regional market entry timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Management Platform Launch | Virtualizes controller functions previously requiring on-premises appliances, reducing operational headcount for Fortune 500 campus deployments. |
| RF Frontend Supply Agreement | Secures GaN substrate allocation from South Korean foundries, insulating margin structures against Taiwan capacity constraints. |
| Managed-Network-as-a-Service Expansion | Converts mid-market German buyers from deferred refresh cycles into recurring subscription relationships with higher lifetime value. |
| Pre-Certification Investment in India | Positions hardware readiness against TRAI 6 GHz auction outcomes, enabling first-mover deployment velocity upon spectrum liberalization. |
| Security Subscription Bundling | Captures value-added distributor relationships in Japan by displacing pure hardware resellers with integrated detection and response services. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FCC equipment authorization databases, ETSI harmonized standards publications, and semiconductor foundry capacity disclosures. Interviews with enterprise IT procurement officers, value-added distributor channel managers, RF engineering directors, and cloud platform integration specialists informed demand-side validation. Regulatory filings from the FCC Office of Engineering and Technology, BNetzA frequency management bulletins, and Japan MIC radio equipment certifications anchored supply-side triangulation. Bottom-up unit shipment estimates and top-down enterprise networking expenditure analysis were cross-referenced for convergence.
Forecast inputs incorporate spectrum allocation timelines across regulatory jurisdictions, chipset development roadmaps from IEEE 802.11 working groups, and enterprise refresh cycle surveys. Segmentation dimensions span deployment environment, technology generation, organizational scale, and regional regulatory cluster. CAGRs were derived from slope analysis of replacement cycle compression and greenfield adoption curves. Wi-Fi 6E and Wi-Fi 7 penetration assumptions hinge on 6 GHz channel availability and 320 MHz bonding certification progress.
Stress conditions across GaN substrate pricing volatility, multi-regulatory certification delays, and mid-market depreciation extension were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding spectrum liberalization sequencing and foundry capacity expansion. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Network Technology
Global LWAN Market
Network Technology
Low-Power WAN Market
Network Technology
Global Intelligent Network Market
Network Technology
CPE Router Market
Network Technology
Global Optical Transport Network (OTN) Market
Network Technology
Zero-Touch Provisioning Market
Network Technology
Global 5G Smart Antenna Market
Network Technology
Fiber to the Premises Market
Network Technology
Global GPS Market
Network Technology
Network Packet Broker Market
Network Technology
GPON WIFI6 Home Gateway Market
Network Technology
Wi-Fi 6E Router Market
Network Technology
Cloud Managed Access Points Market
Network Technology
Lit Fiber Market
Network Technology
SP Routing and Ethernet Switching Market
Network Technology
Gigabit Ethernet Market