
 Low-Power WAN Market | 2026-2036
Low-Power WAN Market Size, Share, and Industry Trends Forecast 2026-2036
Low-Power WAN Market Outlook
The EU Green Deal is shifting procurement criteria across European utilities toward energy-efficient IoT infrastructure. Semtech Corporation leverages its LoRa semiconductor portfolio to dominate chip supply for LoRaWAN networks. Actility anchors European network server deployments with carrier-grade infrastructure. Qualcomm Technologies competes through integrated NB-IoT modem platforms that reduce device power consumption.
Low-Power WAN denotes wireless communication networks optimized for long-range transmission at minimal energy draw, typically operating in sub-GHz unlicensed or licensed spectrum with data rates below 50 kbps and battery life extending ten years for endpoint devices. These networks serve industrial telemetry, utility monitoring, and supply chain visibility where cellular power budgets prove prohibitive. LoRaWAN occupies the largest installed base among unlicensed technologies, while NB-IoT captures carrier-led deployments through 3GPP standardization and existing mobile infrastructure. Smart agriculture represents the fastest-expanding application segment as precision farming mandates intensify water and fertilizer optimization.
FCC Part 15 rules govern unlicensed spectrum access in the United States, while ETSI EN 300 220 harmonizes short-range device parameters across Europe. CE marking requirements under the Radio Equipment Directive shape product compliance costs and market entry timelines for hardware vendors. Stakeholders must weigh spectrum licensing commitments against unlicensed network autonomy as regulatory frameworks for IoT device certification diverge across jurisdictions.
Market Dynamics
EU Green Deal mandates are restructuring utility procurement toward energy-efficient IoT infrastructure, compressing deployment timelines for LoRaWAN and NB-IoT networks across European industrial corridors.
Growth Catalysts
- Smart Metering Mandates:Utility regulators in Germany, France, and the Netherlands require granular energy monitoring, driving endpoint device volume for sub-GHz networks.
- CE Marking Harmonization:ETSI EN 300 220 standardization reduces compliance fragmentation, accelerating hardware vendor market entry across the continent.
- Precision Agriculture Intensification:Water-stressed farming regions deploy soil moisture telemetry, expanding the fastest-growing application segment for LPWAN connectivity.
Market Restraints
- Semiconductor Supply Concentration:LoRa chipset production clusters in East Asian foundries, exposing European network operators to single-source vulnerability.
- Spectrum Licensing Friction:NB-IoT deployment requires carrier spectrum commitments that conflict with unlicensed network autonomy preferences among industrial users.
- Cellular Cost Structure:Licensed module pricing remains prohibitive for high-density endpoint scenarios in smart city and agricultural monitoring.
Strategic Opportunities
- Poland and Czech Industrial Zones:Manufacturing automation lags Western Europe, creating whitespace for private LoRaWAN network deployment in automotive supply chains.
- EU AI Act Convergence:Edge AI inference requirements on telemetry devices favor LPWAN architectures with local processing capability, opening silicon design partnerships.
- Direct-to-Enterprise Channel Models:Bypassing carrier intermediaries through private network server licensing captures margin from security-conscious utilities.
Industry Challenges
- RF Engineering Talent Scarcity:Sub-GHz antenna design and propagation modeling expertise concentrates in legacy telecom vendors, constraining in-house network planning.
- Multi-Protocol Certification Burden:Devices requiring both LoRaWAN and NB-IoT compatibility face extended CE marking timelines under Radio Equipment Directive testing protocols.
- Legacy SCADA Integration Complexity:Industrial telemetry systems built on proprietary radio links resist migration to standards-based LPWAN without gateway bridge investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low-Power WAN Market |
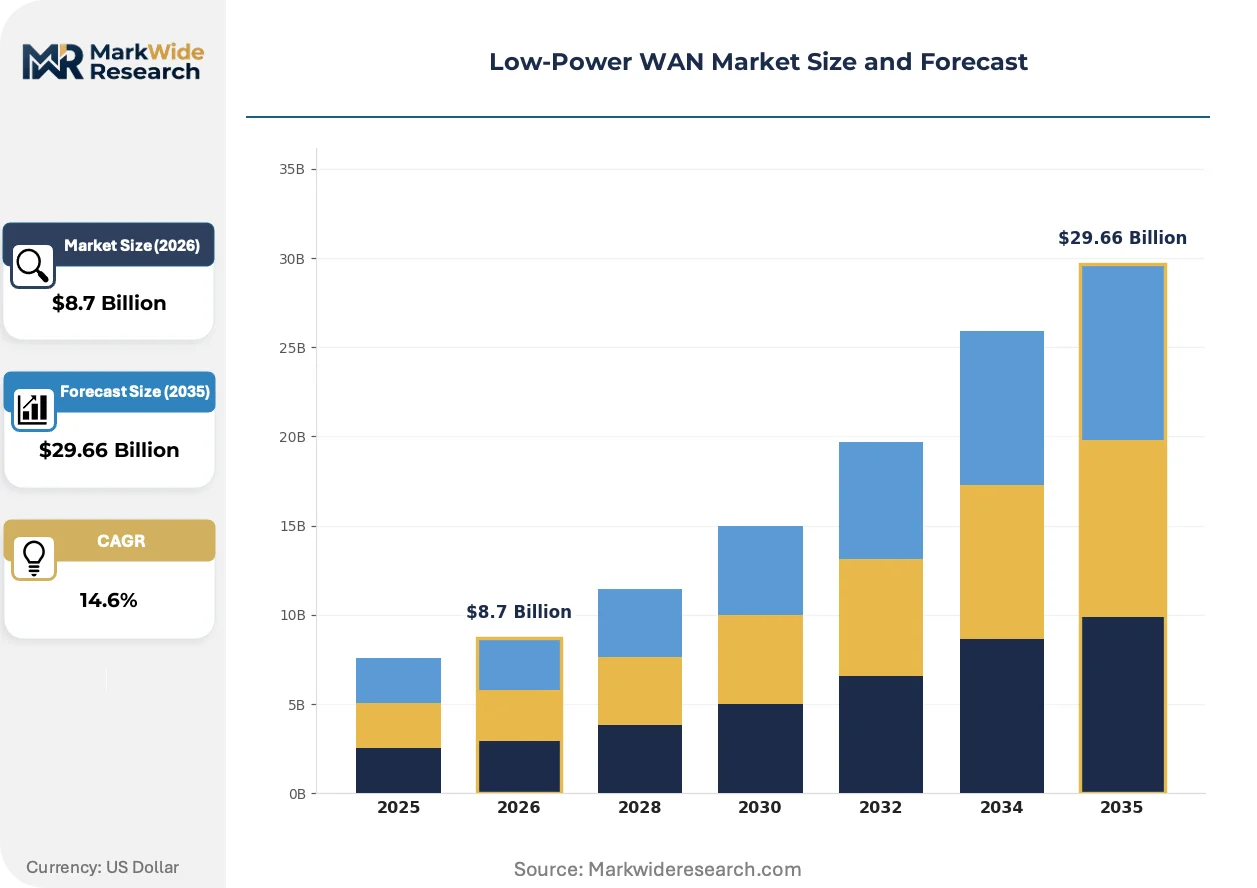
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $29.66 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: LoRaWAN, Sigfox, NB-IoT, RPMA Application: Smart Metering, Asset Tracking, Smart Agriculture, Industrial Automation End User: Utilities, Transportation, Healthcare, Retail Deployment: Public, Private, Hybrid, Managed |
| Companies Covered | Semtech Corporation, SIGFOX, WAVIoT, LORIOT, NWave Technologies, Actility, Senet, Qualcomm Technologies, Vodafone Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low-Power WAN Market Strategic Shifts
Chipset integration and regulatory harmonization are compressing hardware cost curves while edge computing requirements reshape endpoint architecture across European deployments.
LoRa Edge geolocation silicon is consolidating position-fixing capability directly onto telemetry endpoints, eliminating separate GNSS module cost and power draw. Agricultural fleet operators in the Netherlands adopt this architecture for livestock and equipment tracking, collapsing the traditional multi-vendor location stack into single-chip designs. The structural consequence is margin compression for standalone GPS module suppliers.
EU Green Deal digital infrastructure mandates are tightening energy efficiency requirements for connected devices, forcing hardware redesigns toward sub-milliamp sleep states. ETSI certification labs report testing queue lengthening as vendors race to meet utility procurement deadlines. Industrial metering OEMs respond by pre-certifying platform designs across multiple European national variants.
Buyer consolidation among European water utilities is concentrating procurement authority, displacing fragmented municipal purchasing. Suez and Veolia framework agreements now specify LPWAN interoperability requirements that exclude single-protocol vendors. This pattern is most visible in France, where regional water authority mergers accelerated through 2024.
Low-Power WAN Market Segmentation
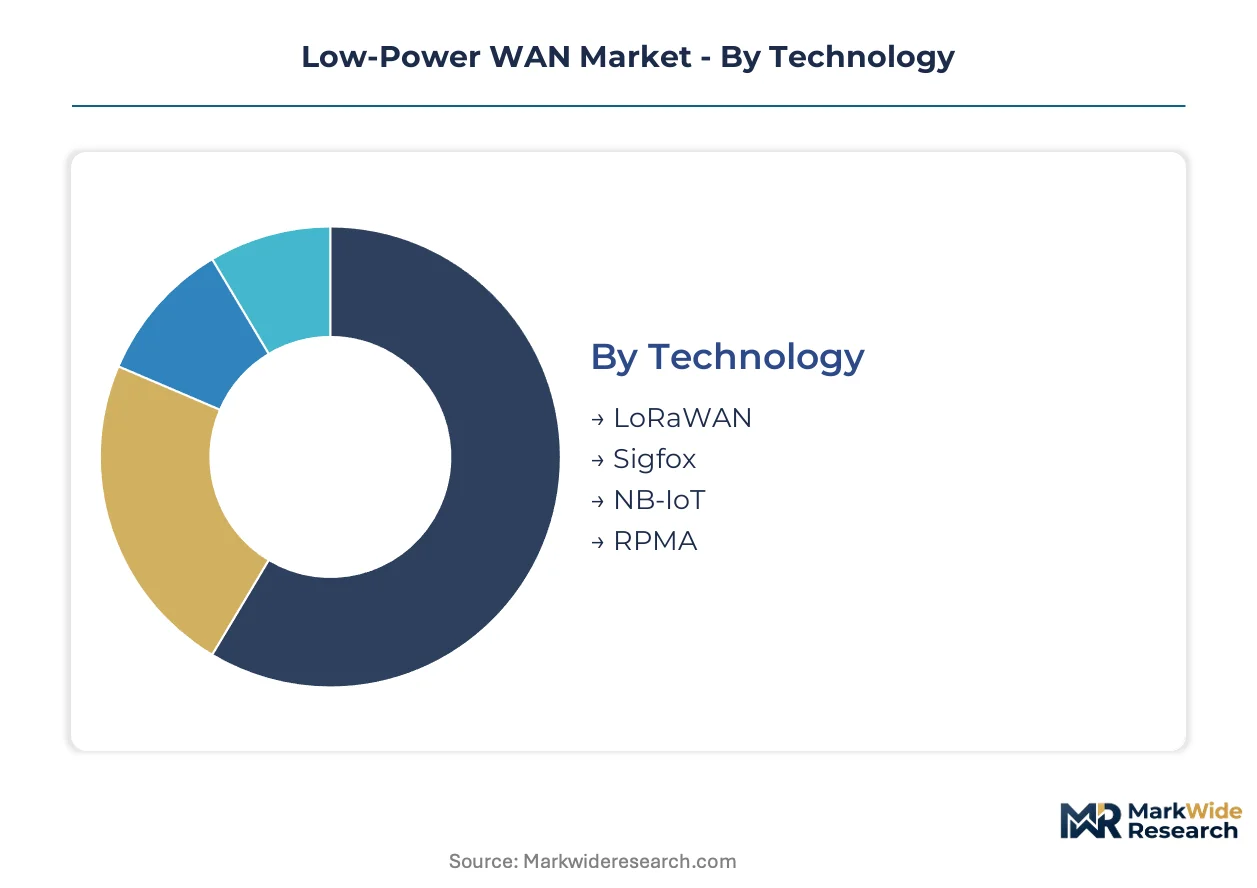
Technology choice determines integration architecture across European utility and industrial deployments, with standalone modules serving pilot projects while embedded chipsets dominate volume manufacturing. Procurement patterns diverge sharply between carrier-managed services and privately operated infrastructure, creating distinct margin pools for hardware vendors and network operators.
Technology:
Standalone gateway architectures suit pilot deployments and retrofitted industrial sites, while embedded baseband integration dominates OEM volume manufacturing for smart meters and agricultural sensors.
- LoRaWAN:Unlicensed sub-GHz modulation enables private network autonomy without carrier spectrum commitments. German industrial corridors and Dutch agricultural cooperatives concentrate demand here, driven by EU Green Deal mandates for energy-efficient telemetry infrastructure.
- NB-IoT:Licensed 3GPP standard leverages existing cellular infrastructure for wide-area coverage in dense urban metering. French and Dutch utilities favor this for smart city deployments where carrier service-level agreements satisfy regulatory reliability requirements.
- Sigfox:Ultra-narrowband proprietary protocol optimized for low-message-count sensor networks.
- RPMA:Random phase multiple access technology from Ingenu serving specialized industrial telemetry in licensed 2.4 GHz spectrum.
LoRaWAN leads volumes today; NB-IoT is gaining share fastest in utility procurement frameworks.
Application:
Cost tier separation distinguishes high-value asset tracking from commoditized environmental monitoring, with price per endpoint varying tenfold across these use cases.
- Smart Metering:Granular electricity and gas consumption telemetry mandates across EU member states drive the largest endpoint volumes. Germany's Bundesnetzagentur requirements and France's Linky rollout concentrate demand for sub-GHz modules with ten-year battery life specifications.
- Smart Agriculture:Soil moisture, livestock tracking, and irrigation control systems serve water-stressed farming regions. Dutch greenhouse operators and French vineyard cooperatives deploy precision agriculture networks, expanding most quickly among all application segments.
- Asset Tracking:Fleet and equipment location services for logistics and construction sectors.
- Industrial Automation:Machine condition monitoring and predictive maintenance telemetry in manufacturing facilities.
Smart metering dominates current deployment value; smart agriculture shows the steepest expansion trajectory.
End User:
Customer type determines procurement authority concentration, with consolidated utilities wielding framework agreement power versus fragmented transportation fleets.
- Utilities:Electricity, water, and gas distribution operators with centralized purchasing functions. Suez and Veolia framework agreements in France now mandate multi-protocol interoperability, reshaping vendor qualification requirements.
- Transportation:Fleet operators and logistics providers tracking vehicle and container assets.
- Healthcare:Medical device connectivity and patient monitoring applications.
- Retail:Supply chain visibility and cold chain monitoring for perishable goods.
Utilities anchor current revenue concentration; transportation end users are expanding device volumes most rapidly.
Deployment:
Maturity stage separates established public network services from emerging private infrastructure models, with hybrid architectures capturing security-conscious industrial users.
- Public:Carrier-operated network services with subscription-based device connectivity. KPN in the Netherlands and Orange in France operate national LoRaWAN coverage, serving municipalities and small utilities without capital for private infrastructure.
- Private:Enterprise-owned network servers and gateway infrastructure. Polish and Czech automotive suppliers deploy these for supply chain telemetry, bypassing carrier intermediaries to satisfy information security requirements.
- Hybrid:Combination of private core networks with public roaming for geographic extension.
- Managed:Outsourced network operations with dedicated spectrum or unlicensed band management.
Public deployment retains the largest installed base; private networks are climbing fastest in industrial manufacturing zones.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Low-Power WAN industry traces its commercial origins to French and Dutch deployments in the early 2010s, where unlicensed spectrum experimentation first proved viable for utility-scale telemetry networks.
Germany
Industrial automation corridors in North Rhine-Westphalia and Bavaria drive concentrated demand for private LoRaWAN infrastructure. The Bundesnetzagentur mandates granular energy monitoring for electricity distribution, accelerating smart meter endpoint deployment. Manufacturing clusters around Stuttgart and Munich are retrofitting legacy SCADA systems with sub-GHz telemetry to satisfy EU Green Deal efficiency requirements.
France
Water utility consolidation under Suez and Veolia framework agreements is standardizing multi-protocol procurement specifications. The national Linky smart meter program, administered under Enedis, anchors NB-IoT volume commitments with carrier service-level agreements. Regional water authority mergers in Provence-Alpes-Côte d'Azur are displacing fragmented municipal purchasing with centralized LPWAN interoperability mandates.
Netherlands
Dutch greenhouse operators and agricultural cooperatives represent the fastest-expanding endpoint segment for precision farming telemetry. KPN operates national LoRaWAN coverage serving municipalities without private infrastructure capital. The Randstad urban corridor concentrates smart city deployments where carrier-managed services satisfy regulatory reliability thresholds for environmental monitoring.
Poland
Automotive supply chain manufacturers in the Silesian and Greater Poland voivodeships are deploying private network servers to bypass carrier intermediaries. CE marking harmonization under ETSI EN 300 220 reduces compliance fragmentation for hardware vendors entering the market. Industrial zones around Łódź and Kraków lag Western European automation penetration, creating whitespace for private LoRaWAN infrastructure investment.
United States
FCC Part 15 rules governing unlicensed spectrum access enable utility pilot programs in California and Texas without carrier licensing commitments. The EPA drives environmental monitoring mandates for water-stressed agricultural regions in the Central Valley. Industrial telemetry deployments in the Permian Basin leverage unlicensed sub-GHz networks for remote equipment monitoring where cellular power budgets prove prohibitive.
Low-Power WAN Market Competitive Environment
Capital-heavy semiconductor foundries compete with asset-light network software designers for margin capture across the value chain. The vendor base clusters into three tiers: integrated chipset manufacturers, carrier-grade infrastructure providers, and specialized network server operators. Strategic archetypes include spectrum-agnostic platform vendors, carrier-aligned modem suppliers, and private-network autonomy specialists. Competitive positioning hardens around M&A activity consolidating network server capabilities and strategic partnerships bridging silicon-to-cloud integration.
Within the semiconductor tier, Semtech Corporation and Qualcomm Technologies exemplify divergent architectural bets on unlicensed versus licensed spectrum dominance. Actility anchors European network server deployments with carrier-grade infrastructure positioning. Among specialized protocol vendors, SIGFOX occupies a position representing ultra-narrowband proprietary alternatives to standards-based competition.
| Leading Market Players |
|---|
| Semtech Corporation |
| SIGFOX |
| WAVIoT |
| LORIOT |
| NWave Technologies |
| Actility |
| Senet |
| Qualcomm Technologies |
| Vodafone Group |
| Others |
Value Chain & Pricing Dynamics
EU Green Deal procurement deadlines for energy-efficient telemetry infrastructure are compressing vendor certification timelines and forcing supply chain reconfiguration toward pre-certified platform designs that streamline pricing negotiations.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates module procurement, with CE marking tier and volume scale as primary differentiation drivers. Cost compression in economy-tier chipsets is intensifying because agricultural cooperatives in the Netherlands and Germany consolidate purchasing through cooperative frameworks. Utilities under Suez and Veolia agreements exhibit lowest price sensitivity due to framework security requirements, while municipal pilot projects show highest elasticity.
Supply Chain Analysis
RF engineering talent scarcity in Taiwan and South Korean foundries constrains LoRa chipset production scaling. Sub-GHz silicon wafers, battery cells, and antenna substrates draw from concentrated East Asian suppliers. Single-source vulnerability in LoRa baseband production exposes European network operators to allocation risk. Distribution runs through carrier-managed service contracts and direct enterprise licensing for private network servers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Low-Power WAN market functions as a regulatory compounder where EU Green Deal digital infrastructure mandates create irreversible demand inflection for energy-efficient telemetry networks.
For Market Incumbents: Cement carrier-grade positioning through backward integration into network server software stacks. Pre-certify hardware platforms across multiple ETSI national variants to compress procurement cycles. Counter Sigfox residual presence and emerging private LoRaWAN specialists by locking multi-year framework agreements with consolidating water utilities. For New Entrants and Emerging Players: Polish automotive suppliers in Silesian manufacturing zones represent the most penetrable buyer archetype for private network infrastructure. Target Czech industrial corridors lagging Western European automation penetration with direct-to-enterprise channel models bypassing carrier intermediaries. Lead with security architecture and local data sovereignty as primary go-to-market differentiation. For Investors and Strategic Acquirers: Asymmetric upside sits with edge AI silicon designers capable of consolidating geolocation and inference capability onto single-chip telemetry endpoints. Five-to-ten year viability hinges on LoRaWAN-NB-IoT protocol convergence rather than winner-take-all outcomes. Watch for EU AI Act enforcement timelines as inflection indicator for edge compute demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| LoRa Edge Silicon Integration | Consolidates GNSS and telemetry functions, collapsing multi-vendor location stack margins for agricultural fleet operators. |
| Private Network Server Licensing | Captures margin from security-conscious utilities in Poland and Czech automotive supply chains bypassing carriers. |
| Multi-Protocol Certification Investment | Pre-qualifies vendors for Suez and Veolia framework agreements excluding single-protocol suppliers. |
| ETSI EN 300 220 Harmonization | Reduces compliance fragmentation, accelerating hardware market entry across German and Dutch procurement deadlines. |
| Edge AI Partnership Development | Positions silicon vendors for EU AI Act convergence requiring local inference on telemetry endpoints. |
Study Parameters
Bottom-up utility metering and agricultural sensor deployment modeling reconciled against top-down semiconductor foundry output tracking forms the analytical core. Primary interviews with network operations directors at European carriers, procurement leads at Suez and Veolia, RF engineering heads at industrial OEMs, and smart meter program managers at Enedis validated segment assumptions. Secondary sources include ETSI certification databases, Bundesnetzagentur regulatory filings, EU Green Deal implementation progress reports, and CE marking timeline disclosures from notified bodies.
Historical trendline analysis of LoRaWAN and NB-IoT module shipments across technology type, application segment, deployment model, and end-user category established baseline growth trajectories. CAGRs derive from regression-adjusted endpoint volume projections and average selling price erosion curves. Forecast inputs incorporate EU member state smart meter mandate compliance schedules, regional water utility consolidation patterns, and precision agriculture subsidy allocation trajectories.
Underlying measurement precision varies by segment; smart metering carries tighter precision than emerging smart agriculture applications due to published regulatory targets. Forecasts reflect documented assumptions regarding CE marking queue lengths and foundry allocation priorities. Material deviation in EU AI Act enforcement timelines or ETSI testing capacity expansion warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Network Technology
WAN Optimization Controllers Market
Network Technology
Network Fault Monitoring Tools Market
Network Technology
Session Border Controller (SBC) Market
Network Technology
Asia Pacific Structured Cabling Market
Network Technology
Wi-Fi As a Service (Waas) Market
Network Technology
Global Passive Optical Network (PON) Equipment Market
Network Technology
Global Network Management Market
Network Technology
5G CPE Device Market
Network Technology
ISP Management Systems Market
Network Technology
Industrial Wireline Networking Market
Network Technology
MENA Wireless Routers Market
Network Technology
Zero-Touch Provisioning Market
Network Technology
Managed MPLS Market
Network Technology
Self-Healing Networks Market
Network Technology
Wi-Fi 6E Router Market
Network Technology
Virtual Router Market