
 Philippines Software-Defined Wide Area Network (SD-WAN) Market | 2026-2036
Philippines Software-Defined Wide Area Network (SD-WAN) Market Size, Share, and Industry Trends Forecast 2026-2036
Philippines Software-Defined Wide Area Network (SD-WAN) Market Insights
The capital-intensity divergence between integrated security-platform vendors and pure-play connectivity specialists is bifurcating competitive dynamics in the Philippine SD-WAN landscape. Cisco Systems, Inc. leverages its unified security and networking stack to anchor premium enterprise deployments across Manila's financial district. Fortinet, Inc. differentiates through embedded threat intelligence and converged firewall-SD-WAN appliances that sustain margin advantages in security-conscious verticals.
Software-Defined Wide Area Network (SD-WAN) is a virtualized network architecture that decouples control plane intelligence from physical transport hardware, enabling policy-driven traffic steering across MPLS, broadband internet, and LTE/5G links with sub-50 millisecond failover. Its primary commercial purpose is to replace expensive legacy WAN circuits with intelligent, cost-optimized multipath connectivity while centralizing orchestration. Cloud-based deployment models are capturing the fastest growth trajectory as Philippine enterprises prioritize operational simplicity and rapid site provisioning over capital-intensive on-premises controller installations. Managed services within the service-type dimension concentrate margin pools, reflecting enterprise willingness to outsource complexity to providers with local NTT Limited or Vodafone Group plc operations.
The National Telecommunications Commission governs spectrum allocation and interconnection rules that shape last-mile options available to SD-WAN underlays, while the National Privacy Commission enforces data-localization standards affecting cloud-gateway placement and encryption requirements. The Department of Information and Communications Technology's broadband expansion mandates are compressing deployment timelines for branch-connectivity use cases in secondary cities. Stakeholders must weigh vendor cloud-gateway proximity against emerging cyber-insurance requirements that tie policy pricing to demonstrated segmentation capabilities.
Market Dynamics
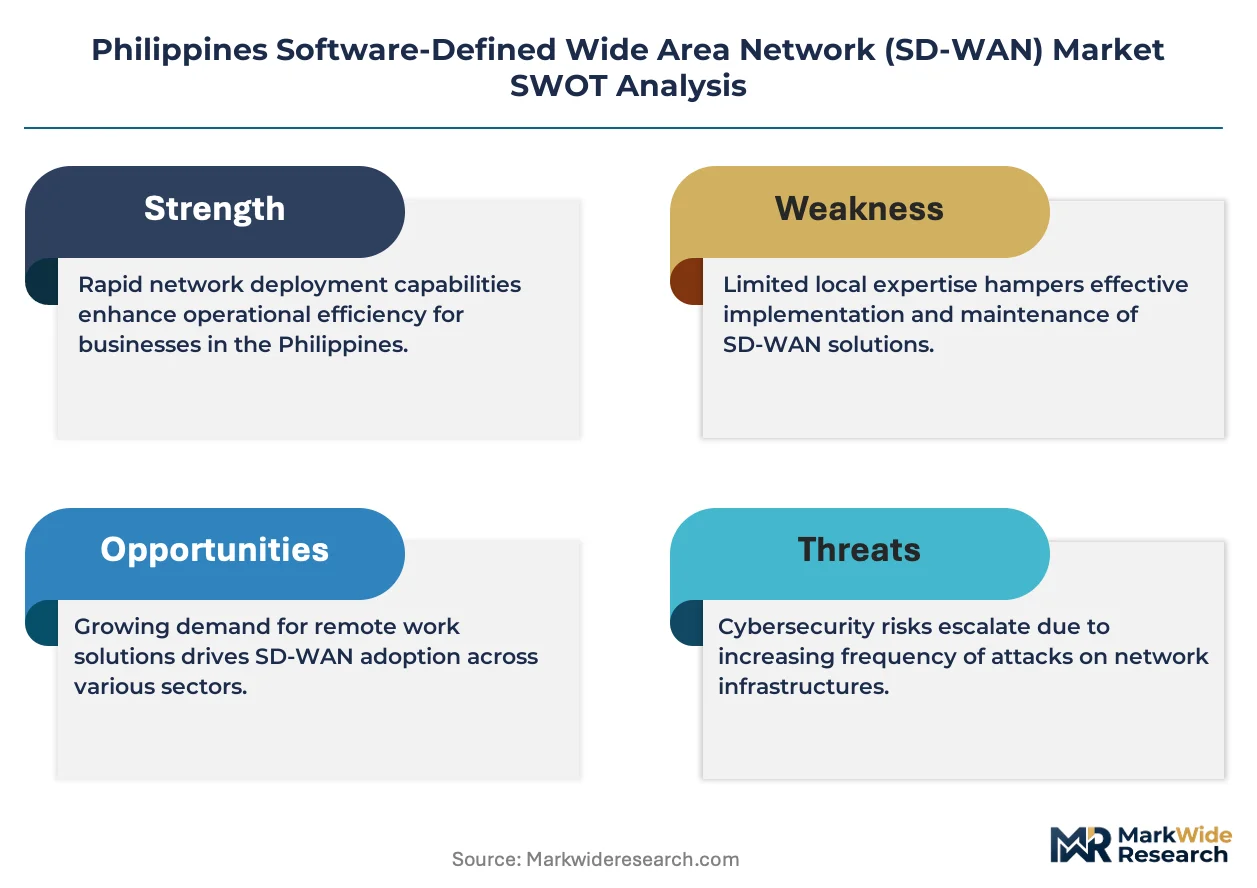
The National Telecommunications Commission's broadband infrastructure mandates are compressing deployment timelines while fragmenting last-mile provider options, forcing enterprises to reassess vendor cloud-gateway proximity against operational complexity trade-offs.
Growth Catalysts
- DICT Broadband Expansion:The Department of Information and Communications Technology's nationwide connectivity programs are extending fiber and wireless reach into secondary cities, creating addressable branch sites previously unreachable by MPLS.
- Financial Services Modernization:Philippine banks are retiring legacy frame-relay circuits at metro branches, replacing them with intelligent multipath SD-WAN underlays that aggregate broadband and LTE for cost-optimized resilience.
- Cloud Gateway Localization:Vendor investments in Manila-based points of presence are reducing latency to SaaS applications, making cloud-managed SD-WAN deployments viable for latency-sensitive trading and payment systems.
Market Restraints
- Last-Mile Provider Concentration:Metro Manila's fiber infrastructure remains dominated by two incumbent carriers, creating vendor lock-in risk for enterprises seeking diverse underlay options.
- Skills Pipeline Constraints:Certified network engineers with production SD-WAN deployment experience command premium compensation, inflating total cost of ownership for self-managed implementations.
- Data Localization Requirements:National Privacy Commission encryption and residency standards complicate cloud-gateway architectures, requiring additional in-country infrastructure investment.
Strategic Opportunities
- Mindanao Branch Expansion:Davao and Cagayan de Oro commercial centers remain underserved by managed SD-WAN providers, offering first-mover advantage for localized service delivery.
- Converged Security-Networking:SASE architecture adoption creates cross-sell potential for vendors embedding zero-trust network access with SD-WAN fabric in single-vendor stacks.
- 5G Fixed Wireless Integration:NTC spectrum releases enable wireless-only branch connectivity for remote mining and agricultural operations lacking fiber access.
Industry Challenges
- Multi-Vendor Orchestration Complexity:Enterprises mixing best-of-breed security appliances with SD-WAN controllers face policy synchronization failures requiring specialized integration labor.
- Legacy MPLS Contract Rollovers:Existing carrier agreements with termination penalties delay migration timelines, forcing hybrid WAN architectures that increase operational overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Philippines Software-Defined Wide Area Network (SD-WAN) Market |
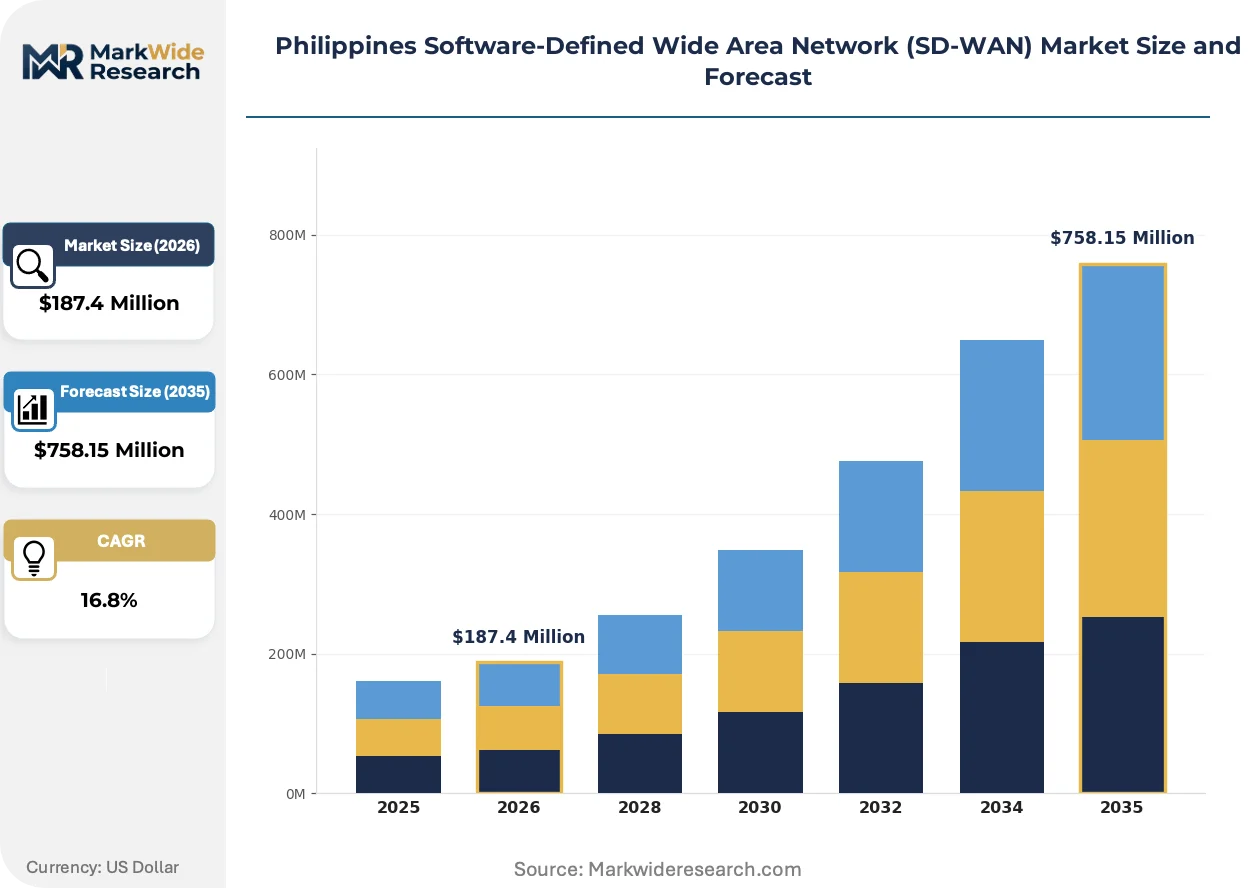
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $758.15 Million |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: Cloud-Based, On-Premises, Hybrid, Managed Use Case: Branch Connectivity, Data Center Connectivity, Cloud Application, Network Optimization Service Type: Consulting, Integration, Managed Services, Support End User: SMEs, Large Enterprises, Government, Telecommunications |
| Companies Covered | Cisco Systems, Inc., Palo Alto Networks, Fortinet, Inc., Oracle Corporation, NTT Limited, Vodafone Group plc, VMware, Inc., Juniper Networks, Inc., Versa Networks, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Philippines Software-Defined Wide Area Network (SD-WAN) Market Trends and Innovations
Artificial intelligence is embedding into traffic engineering algorithms, enabling predictive path selection that responds to application performance degradation before user impact manifests.
AI-driven application recognition is fragmenting traditional traffic classification methods, replacing static port-based rules with behavioral fingerprinting that identifies encrypted flows without decryption. Philippine financial institutions are piloting these engines for real-time trading application prioritization. The technology is fragmenting procurement patterns, separating vendors with native AI stacks from those dependent on third-party classification feeds.
NTC's revised interconnection frameworks are mandating transparent wholesale pricing for last-mile fiber access, dismantling historical carrier exclusivity arrangements in commercial districts. This regulatory pressure is commoditizing transport underlays while elevating the strategic value of overlay intelligence and management platforms. Enterprise IT teams in Cebu and Clark Freeport Zone are leveraging this access diversity to negotiate shorter-term contracts.
Subscription-based consumption models are displacing perpetual licensing for SD-WAN edge appliances, aligning vendor compensation with active site counts rather than upfront hardware shipments. Systems integrators with Manila-based network operations centers are capturing margin pools previously held by hardware distributors. This shift concentrates in mid-market enterprises lacking capital expenditure approval velocity for refresh cycles.
Philippines Software-Defined Wide Area Network (SD-WAN) Market Segmentation
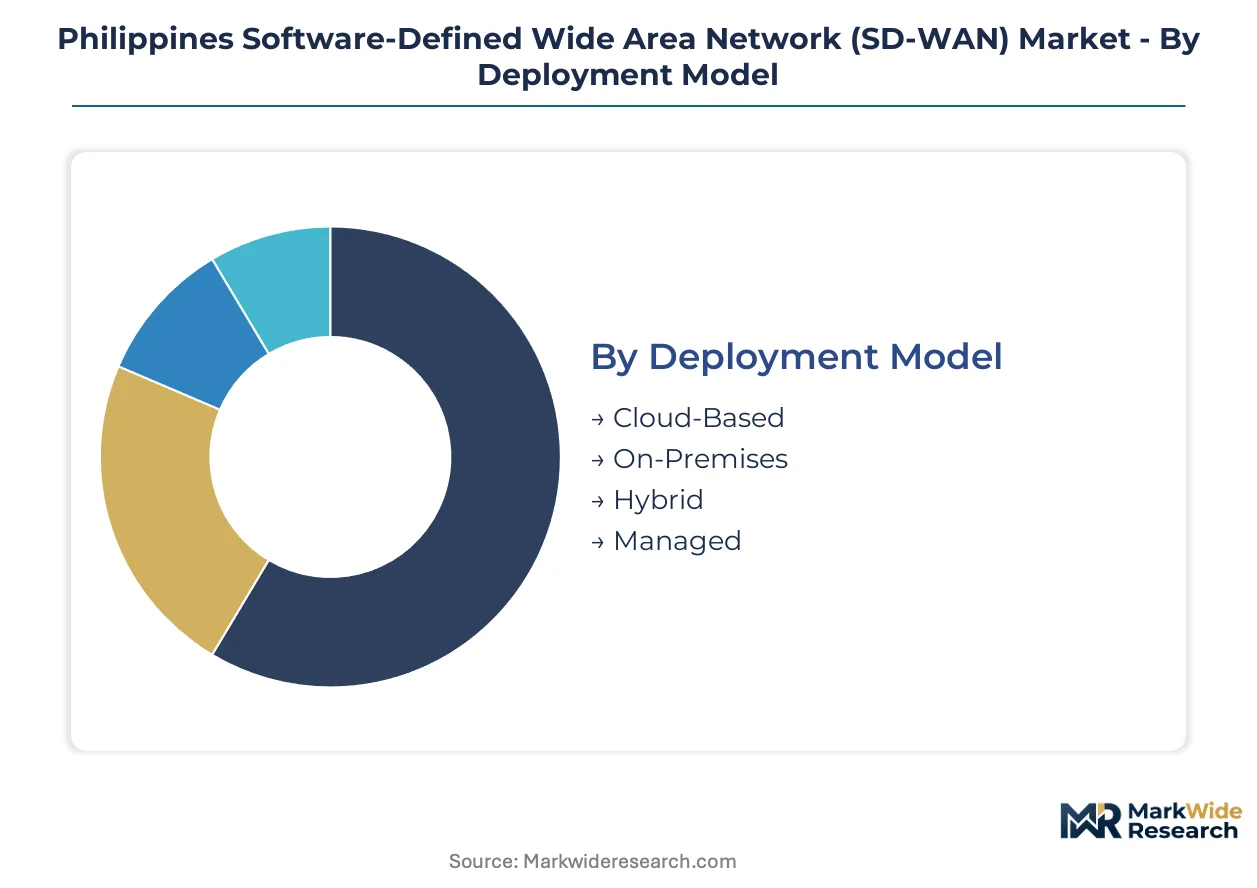
Philippine SD-WAN procurement patterns fragment across deployment preferences, operational use cases, service engagement models, and organizational scale. Each segmentation dimension reveals distinct margin concentration points and vendor competitive positioning strategies.
Deployment Model:
Managed and cloud-based deployments capture the deepest margin pools, reflecting enterprise willingness to outsource operational complexity rather than build in-house controller expertise.
- Cloud-Based:Centralized controller infrastructure hosted in vendor or third-party data centers eliminates capital expenditure for controller hardware. Metro Manila financial institutions favor this model for rapid branch provisioning without local IT staffing.
- Managed:Service providers assume full lifecycle responsibility for edge appliance deployment, policy orchestration, and ongoing optimization. This segment commands premium pricing in Cebu and Davao where certified engineering talent remains scarce.
- On-Premises:Enterprises retain physical controller appliances within owned data centers.
- Hybrid:Mixed architecture combining cloud-managed edges with on-premises policy engines for compliance-sensitive workloads.
Managed holds installed capacity. Cloud-Based is rotating up the share rankings.
Use Case:
Branch connectivity applications dominate volume, though cloud application acceleration is climbing fastest as SaaS dependency deepens across Philippine enterprises.
- Branch Connectivity:Aggregates multiple transport links—fiber, LTE, satellite—into unified WAN fabric with intelligent failover. Philippine banks deploy this across provincial branch networks to retire expensive MPLS circuits while maintaining transaction reliability.
- Cloud Application:Optimizes path selection for Microsoft 365, Salesforce, and proprietary SaaS platforms through localized cloud gateways. Latency-sensitive trading platforms in Makati's financial district drive specialized demand here.
- Data Center Connectivity:Extends SD-WAN fabric to co-location and hyperscale cloud regions.
- Network Optimization:Application-aware traffic engineering without full WAN replacement.
Branch Connectivity holds installed capacity. Cloud Application is rotating up the share rankings.
Service Type:
Managed services concentrate recurring revenue streams, while integration services capture project-based margin from complex multi-vendor deployments.
- Managed Services:Continuous monitoring, policy updates, and performance optimization delivered through provider network operations centers. Philippine mid-market enterprises lacking internal SD-WAN expertise outsource entirely to Manila-based specialists.
- Integration:Design and deployment of SD-WAN fabric alongside legacy MPLS transition, security appliance integration, and cloud gateway provisioning. Complex hybrid WAN architectures in Clark Freeport Zone manufacturing clusters require extensive integration labor.
- Consulting:Architecture assessment and vendor selection advisory.
- Support:Break-fix and technical assistance for self-managed deployments.
Managed Services holds installed capacity. Integration is rotating up the share rankings.
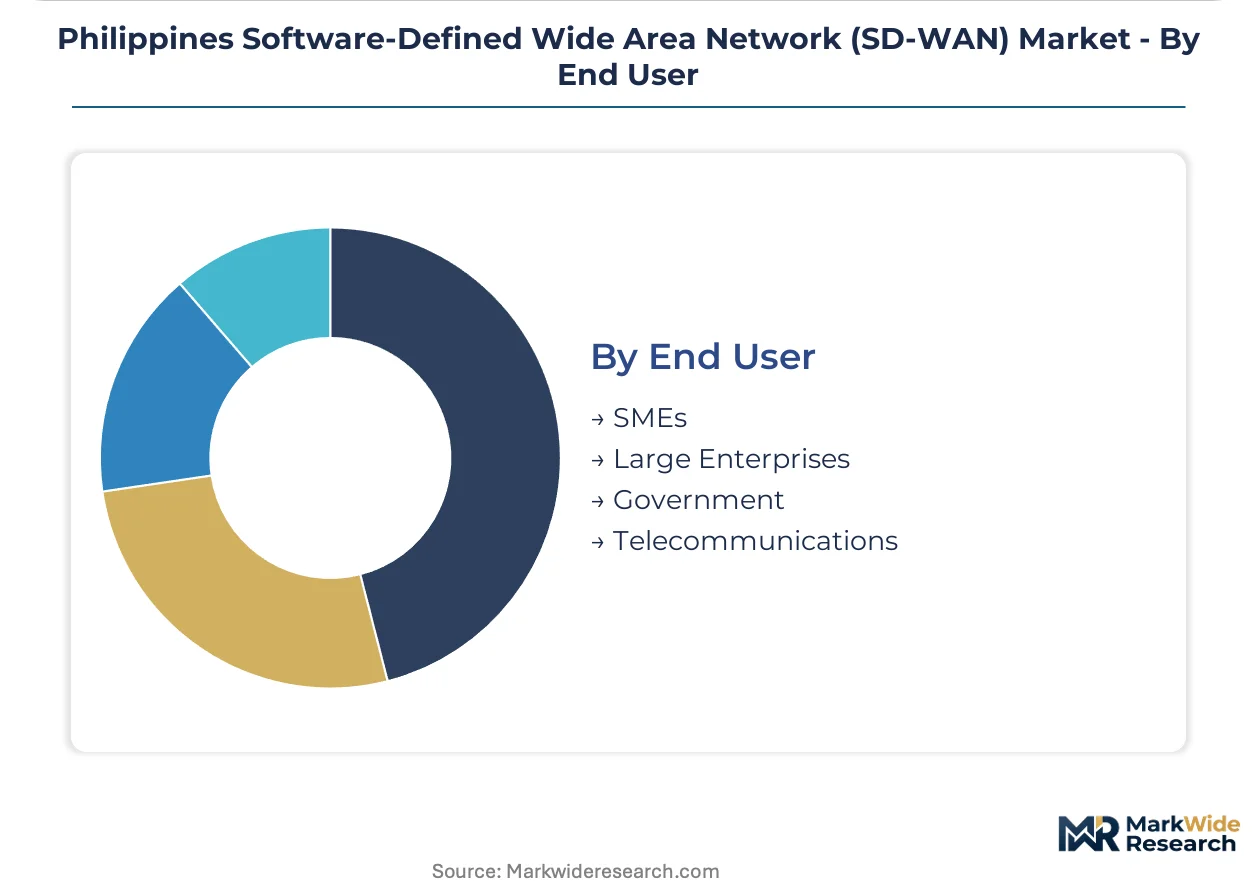
End User:
Large enterprises anchor current spending, though SME segment expansion accelerates as subscription pricing models reduce entry barriers.
- Large Enterprises:Multi-site organizations with 50+ branch locations requiring centralized policy governance. Philippine universal and commercial banks dominate this segment with nationwide branch modernization programs.
- SMEs:Mid-sized enterprises with 5-20 sites adopting SD-WAN through managed service bundles. Davao and Cagayan de Oro commercial centers show emerging demand as regional business process outsourcing operations expand.
- Government:National agencies and local government units modernizing inter-office connectivity.
- Telecommunications:Carriers deploying SD-WAN as managed service offerings to enterprise customers.
Large Enterprises holds installed capacity. SMEs is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Metro Manila's financial district exceeds provincial secondary cities by substantial margins, reflecting infrastructure maturity and enterprise density differentials across the Philippine archipelago.
Metro Manila
Makati and Ortigas central business districts concentrate banking headquarters and data center operations driving premium SD-WAN deployments. The Department of Information and Communications Technology's Free Wi-Fi for All program complements private fiber buildouts. Bonifacio Global City hosts cloud gateway points of presence reducing latency for SaaS-dependent trading platforms.
Central Luzon
Clark Freeport Zone manufacturing clusters generate hybrid WAN demand as multinational firms modernize legacy MPLS contracts. DICT's National Broadband Plan mandates fiber extension into Pampanga and Tarlac industrial corridors. Subic Bay Freeport Zone logistics operators pilot 5G fixed wireless as primary SD-WAN underlay where fiber remains uneconomical.
Visayas
Cebu City's business process outsourcing expansion creates mid-market SD-WAN opportunity among 50-200 seat operations. National Telecommunications Commission interconnection rules are dismantling carrier exclusivity in Cebu IT Park and Mactan Newtown. Iloilo City's emerging tech workforce supports managed service provider network operations center placement.
Mindanao
Davao Region commercial centers remain underserved by managed SD-WAN providers despite accelerating branch banking expansion. DICT's Pipol Konek barangay Wi-Fi initiative extends baseline connectivity enabling wireless SD-WAN underlays. Cagayan de Oro's port and logistics activity generates demand from agribusiness exporters requiring resilient multi-site connectivity.
Southern Tagalog
Laguna and Batangas industrial zones host automotive and electronics manufacturing requiring segmented OT-IT network fabrics. The National Privacy Commission's data localization standards complicate cloud gateway placement for Batangas Port customs operations. Calamba and Santa Rosa special economic zones attract managed service providers seeking manufacturing vertical specialization.
Philippines Software-Defined Wide Area Network (SD-WAN) Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with converged security-networking stacks commanding premium positioning against connectivity-focused alternatives. The Philippine SD-WAN market exhibits tiered concentration where integrated platform vendors anchor enterprise financial services deployments while managed service providers capture provincial mid-market expansion. Three archetypes dominate: unified security-networking stack vendors, pure-play connectivity specialists, and telecommunications-managed service hybrids. Competitive dynamics center on cloud gateway localization investments and subscription pricing model displacement of perpetual licensing.
Among security-integrated platform vendors, Cisco Systems, Inc., Fortinet, Inc., and Palo Alto Networks exemplify the premium-tier archetype embedding threat intelligence with WAN orchestration. These firms occupy positions where enterprise procurement teams prioritize single-vendor accountability over best-of-breed component assembly. NTT Limited and Vodafone Group plc represent the managed service provider archetype, leveraging regional network operations infrastructure to deliver operational outsourcing for Philippine mid-market enterprises lacking internal SD-WAN engineering depth.
| Leading Market Players |
|---|
| Cisco Systems, Inc. |
| Palo Alto Networks |
| Fortinet, Inc. |
| Oracle Corporation |
| NTT Limited |
| Vodafone Group plc |
| VMware, Inc. |
| Juniper Networks, Inc. |
| Versa Networks |
| Others |
Pricing and Supply Chain Analysis
Ninety-day edge appliance lead times from contract signature to Manila data center delivery compress procurement flexibility and amplify pricing power for vendors holding localized inventory. This inventory constraint tightens vendor-customer negotiation leverage while forcing Philippine enterprises toward longer-term subscription commitments that smooth working capital requirements.
Pricing Analysis
The customization-premium spread between configured-to-order policy engines and standard cloud-managed deployments widens as financial institutions demand compliance-tailored orchestration stacks. Subscription-based SaaS-tiered pricing dominates, with price differentiation resting on security certification tier and vertical specialization depth. Pricing pressure stems from NTC-mandated wholesale fiber access commoditizing transport underlays. Mid-market enterprises exhibit highest price sensitivity, while Makati-headquartered universal banks absorb premium single-vendor stacks without material procurement friction.
Supply Chain Analysis
Inbound logistics costs through Manila Port congestion and container availability constraints on Trans-Pacific lanes elevate landed costs for specialized security appliances. Hardware sourcing concentrates in Taiwan, China, and Malaysia for edge device fabrication, with software control planes drawing from US and Singapore development centers. Supply chain risk centers on single-source vulnerability for converged firewall-SD-WAN chipsets. Distribution runs through Manila-based systems integrators with certified engineering benches, bypassing traditional hardware distributor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in switching costs that cement incumbent positions once SD-WAN fabric penetrates branch networks and integrates with core banking systems.
For Market Incumbents: Fortify cloud gateway localization investments in Bonifacio Global City and Cebu IT Park to preempt latency arbitrage by challengers. Deepen backward integration into threat intelligence feeds that embed differentiation beyond commodity connectivity. The priority lever sits with NTT Limited and Vodafone Group plc managed service partnerships that extend reach into engineering-scarce provincial markets. For New Entrants and Emerging Players: Mindanao branch expansion gaps, particularly Davao and Cagayan de Oro commercial centers, offer white-space penetration where incumbent managed service coverage remains thin. Target SME manufacturing clusters in Laguna and Batangas special economic zones with subscription bundles that eliminate capital expenditure approval barriers. The most penetrable segment comprises 50-200 seat business process outsourcing operations seeking rapid provisioning without internal engineering hires. For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue infrastructure play because subscription pricing models align vendor compensation with customer success metrics and generate predictable cash flow visibility. Acquisition target archetype centers on Manila-based managed service providers with existing NOC infrastructure and vertical certifications in financial services or manufacturing. The signal to watch is DICT broadband expansion milestone achievement that suddenly renders previously unreachable branch sites addressable.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud Gateway Localization | Manila-based points of presence reduce SaaS latency for Makati trading platforms. |
| Managed Service Partnership | NTT Limited and Vodafone Group plc NOC infrastructure extends provincial market reach. |
| Converged Security-Networking Stack | Embedded Fortinet threat intelligence sustains margin advantages in compliance-conscious verticals. |
| 5G Fixed Wireless Integration | NTC spectrum releases enable wireless-only branch connectivity for remote mining operations. |
| SME Subscription Bundle Launch | Operational expenditure pricing eliminates capital approval barriers for Davao mid-market expansion. |
Research Methodology
A spread of perspectives from network architects at Philippine universal banks, procurement officers at manufacturing multinationals, managed service provider engineering directors, and National Telecommunications Commission regulatory staff converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation through SEC filings of listed technology vendors, DICT broadband expansion program disclosures, and hyperscaler capex announcements. Bottom-up branch-count modeling and top-down enterprise IT spending triangulation anchored volume estimates.
Segmentation dimensions modeled span deployment model, service type, use case, and organization size across the analysis window. Value outputs reflect unit economics derived from subscription pricing disclosures and managed service contract structures. CAGRs incorporate technology refresh cycle assumptions, regulatory mandate timelines, and cloud adoption trajectory inputs specific to Philippine financial services modernization.
Underlying assumptions cover sustained DICT infrastructure investment execution and stable NTC interconnection framework enforcement, with deviation risk concentrated in skills pipeline constraints and legacy MPLS contract rollover delays. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Network Technology
Global Deep Packet Inspection and Processing Market
Network Technology
Global Internet Transit Market
Network Technology
Hyperconnectivity Market
Network Technology
Intelligent Network Management Market
Network Technology
Global Self-Organizing Network Market
Network Technology
US Private 5G Network Market
Network Technology
Wireless Infrastructure Monitoring Market
Network Technology
Network Management Solutions Market
Network Technology
Smart Network Interface Card (Smartnic) Market
Network Technology
Global LWAN Market
Network Technology
Application Delivery Controller (ADC) Market
Network Technology
Europe Video Conferencing Hardware Market
Network Technology
Industrial Ethernet Market
Network Technology
Network Telemetry Market
Network Technology
Mobile Network Optimization Market
Network Technology
Mobile Accelerator Market