
 Optical Network Equipment Market | 2026-2036
Optical Network Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Optical Network Equipment Market Analytics
Telecom operator procurement is broadening across Internet service providers and hyperscale cloud builders as distributed edge architectures multiply access points. Huawei Technologies Co., Ltd. leverages vertically integrated photonic component manufacturing to dominate submarine and terrestrial line systems. Nokia Corporation anchors European supply through its Bell Labs coherent DSP roadmap and metro packet-optical convergence. Ciena Corporation differentiates via WaveLogic programmable modulation and multi-haul software automation.
Optical network equipment comprises routers, switches, amplifiers, and transceivers engineered to transmit data as light pulses across single-mode and multimode fiber at wavelengths typically spanning 1260 nm to 1625 nm, with coherent detection enabling 800 Gb/s per lambda in long-haul configurations. Dense Wavelength Division Multiplexing technology leads installed capacity due to spectral efficiency demands on submarine and intercity routes, while optical switching gains traction in data center interconnects seeking reduced electronic buffering. Transceivers represent the fastest-growing product category as pluggable coherent optics displace embedded line cards.
The Federal Communications Commission governs spectrum and broadband subsidy programs shaping US carrier capex cycles, while the European Telecommunications Standards Institute drives open optical interface specifications that reduce vendor lock-in. China's Ministry of Industry and Information Technology mandates domestic sourcing ratios under GB standards that reshape competitive access. Stakeholders must monitor open line system interoperability certifications and national security screening regimes for submarine cable participation.
Market Dynamics
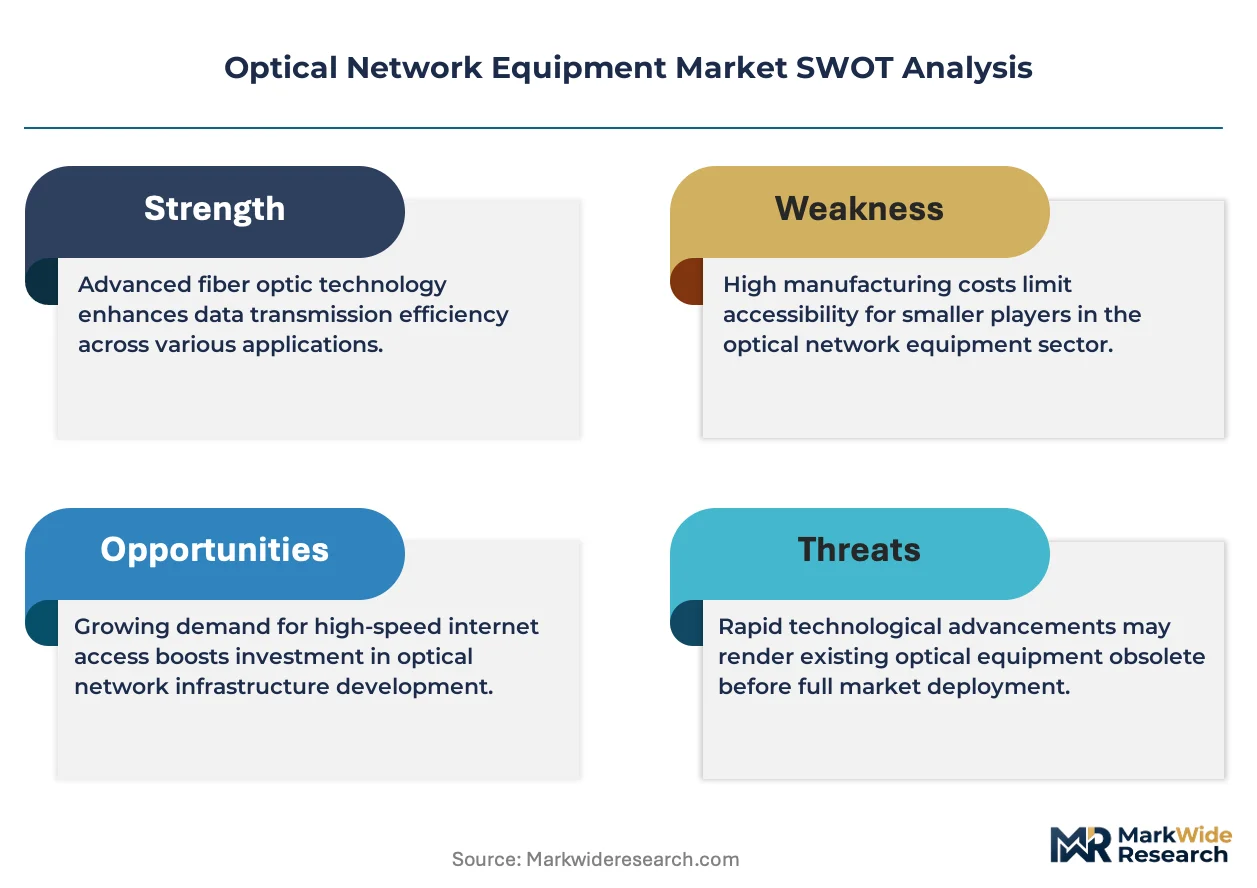
Coherent optical transmission architectures are compressing capital intensity per bit while multiplying deployment scale, forcing incumbents to restructure R&D roadmaps around programmable silicon photonics and open line system interoperability.
Growth Catalysts
- 800G coherent pluggable optics:Cloud service providers are retrofitting data center interconnects with QSFP-DD and OSFP form factors that slash power consumption per gigabit. Metro and long-haul operators follow as transceiver density becomes the binding constraint in fiber-limited routes.
- Open RAN interoperability mandates:The European Union's framework for disaggregated radio access networks is cascading into transport layer procurement specifications, compelling traditional vendors to expose optical control interfaces and enabling multi-vendor line systems.
- BharatNet Phase III and 5G backhaul:India's rural broadband expansion and mobile network densification are generating concentrated demand for coherent transceivers and WDM line systems, with state-led tenders prioritizing domestic assembly partnerships.
Market Restraints
- Indium phosphide and silicon germanium wafer concentration:Foundry capacity for photonic integrated circuits clusters in Taiwan and the United States, creating single-source vulnerability for coherent DSP and modulator production during supply shocks.
- Submarine cable security screening:National security review regimes in Australia, the United States, and Japan are elongating project approval timelines and restricting vendor participation in critical undersea routes, compressing addressable market scope for non-domestic suppliers.
- Copper cable persistence in last-mile:G.fast and enhanced DSL technologies continue to satisfy bandwidth requirements in cost-constrained multi-dwelling units, delaying fiber-to-the-home conversion and muting access optical equipment pull-through.
Strategic Opportunities
- Edge computing optical switching:Hyperscale operators are deploying reconfigurable optical add-drop multiplexers at metropolitan edge nodes to bypass electronic switching for latency-sensitive workloads, opening greenfield chassis opportunities outside traditional central office footprints.
- L-band spectrum expansion:Ciena Corporation and Nokia Corporation are commercializing extended C+L-band amplifiers that nearly double fiber capacity without new cable lays, targeting trans-Pacific and trans-Atlantic routes where conduit scarcity is acute.
- Domestic sourcing incentives under China's GB standards:The Ministry of Industry and Information Technology procurement ratios are redirecting state-owned carrier spending toward indigenous coherent DSP and amplifier designs, creating captive demand pools for local supply chains.
Industry Challenges
- Coherent DSP algorithm engineering talent:The intersection of optical physics and advanced modulation coding requires specialized skill sets concentrated in Bell Labs, Huawei Research, and select academic programs, constraining product development velocity for mid-tier vendors.
- Multi-generational network interoperability:Operators must integrate 400G, 800G, and emerging 1.6T line rates across common fiber plant without service disruption, complicating upgrade scheduling and sparing strategies.
- Open line system certification complexity:Third-party transceiver validation against disaggregated amplifier and switching platforms extends qualification timelines and fragments technical support accountability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Optical Network Equipment Market |
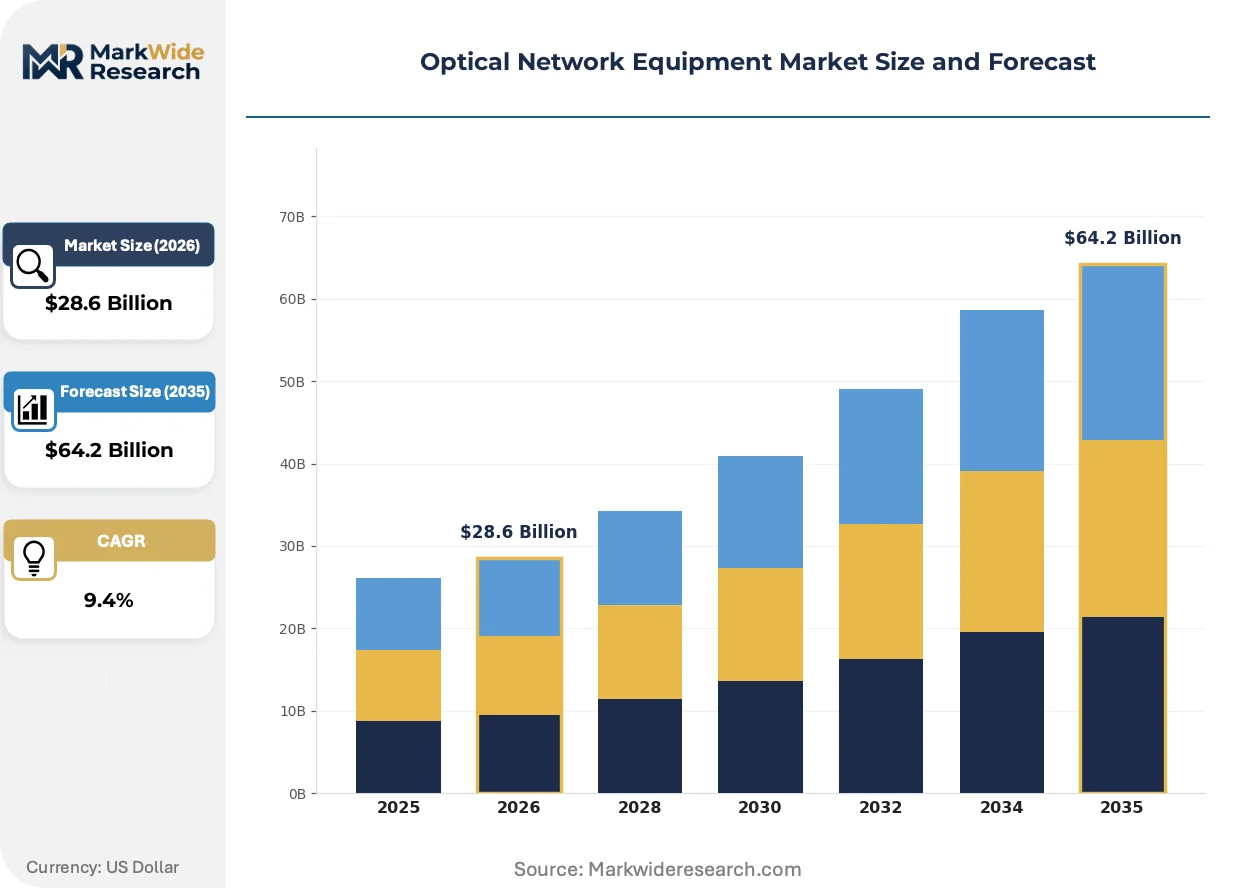
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $64.2 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Routers, Switches, Amplifiers, Transceivers Technology: Wavelength Division Multiplexing, Dense Wavelength Division Multiplexing, Optical Switching, Fiber Optic Application: Telecommunications, Data Centers, Enterprise Networks, Cloud Services End User: Telecom Operators, Internet Service Providers, Enterprises, Government |
| Companies Covered | ZTE Corporation, Infinera Corporation, Huawei Technologies Co., Ltd., Corning Inc., Fujitsu Limited, Nokia Corporation, Cisco Systems, FiberHome Telecommunication Technologies Co., Ltd., Ciena Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Optical Network Equipment Market Evolving Landscape
Silicon photonics fabrication is collapsing cost curves for coherent optical engines while software-defined control planes are dissolving hardware-software binding, enabling procurement patterns that favor component modularity over integrated system stacks.
Coherent pluggable transceivers are integrating DSP, modulator, and receiver functions into standardized form factors that plug directly into router and switch faceplates. Hyperscale cloud builders are adopting these modules at volume to eliminate standalone optical transport shelves. The structural consequence is that embedded line card revenue is compressing while merchant transceiver suppliers capture incremental value.
The European Telecommunications Standards Institute's open optical interface specifications are mandating interoperability between transceivers and line systems from different vendors. This industrial consequence fragments procurement decisions and erodes long-term maintenance contract lock-in. Metro and regional network operators across Germany, France, and the Netherlands are most affected, responding with multi-vendor trial programs that stress-test certification timelines.
Consumption patterns among telecom operators are fragmenting from centralized capex cycles toward distributed edge infrastructure spending. Traditional system integrators are losing primacy to direct procurement relationships between cloud builders and component suppliers. This behavioral shift is most visible in India and the United States, where BharatNet and rural broadband subsidy programs are channeling funds through state agencies rather than incumbent carrier engineering departments.
Optical Network Equipment Market Segmentation
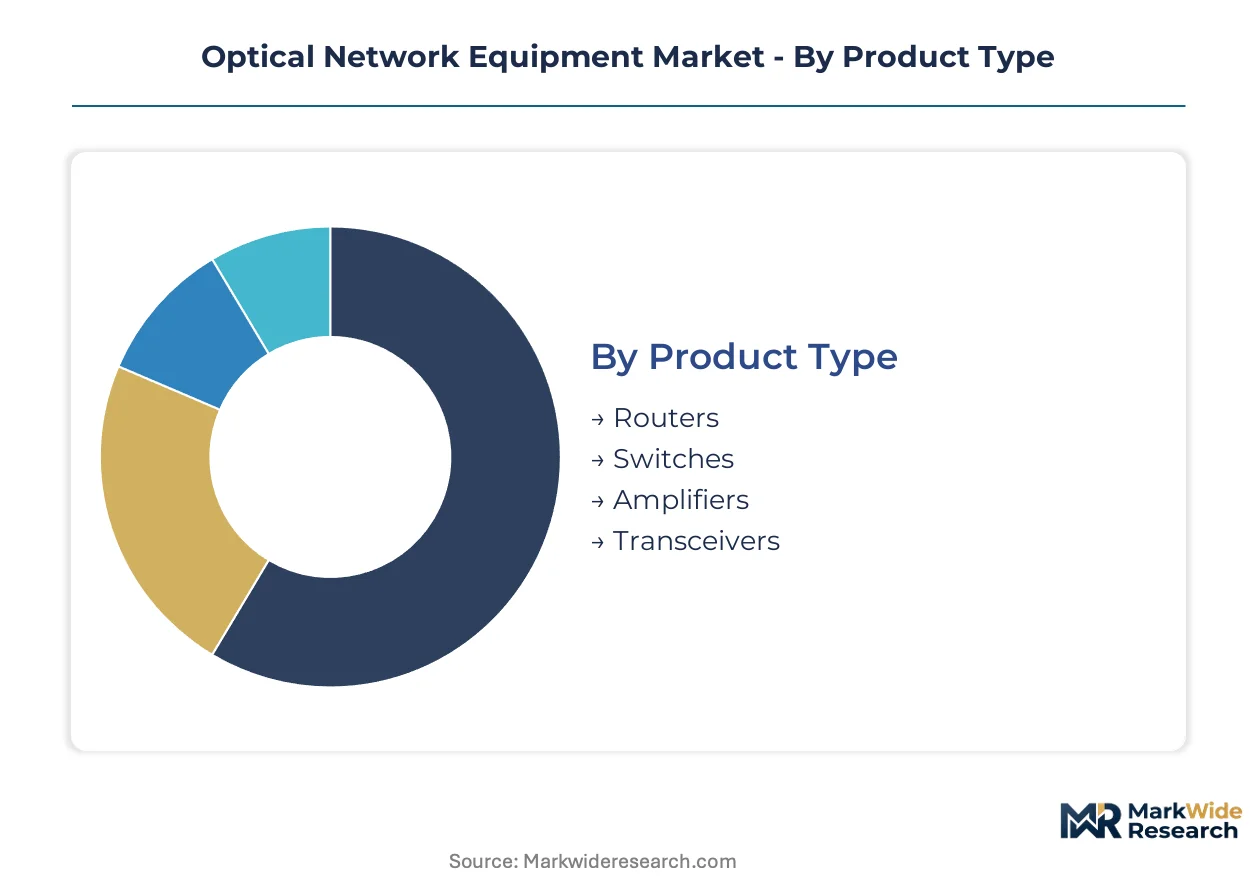
Optical network equipment segmentation reveals how procurement decisions fragment across technical specifications, deployment contexts, and buyer types. Each axis carries distinct margin profiles and vendor qualification requirements that reshape competitive positioning.
Product Type:
Product architecture determines power budgets, form factor constraints, and integration depth with IP layer equipment.
- Transceivers:Pluggable coherent optics integrate DSP, modulator, and receiver functions into QSFP-DD and OSFP packages. Cloud service providers in the United States and India are retrofitting data center interconnects and 5G backhaul routes, with coherent pluggable demand accelerating as embedded line cards face displacement.
- Routers:Carrier-grade platforms combine packet forwarding with optical transport interfaces, enabling converged IPoDWDM deployments. Telecom operators across Germany and France prioritize programmable silicon supporting 400G and 800G line rates as traffic engineering complexity mounts.
- Switches:Data center fabric switches with native optical ports reduce electronic buffering latency in hyperscale facilities.
- Amplifiers:Erbium-doped and Raman amplification modules extend reach on submarine and long-haul terrestrial routes without regeneration.
Transceivers lead on scale; amplifiers lead on momentum as C+L-band extensions nearly double fiber capacity.
Technology:
Spectral efficiency and switching granularity define performance hierarchies across distance and density requirements.
- Dense Wavelength Division Multiplexing:DWDM compresses multiple 100G-800G lambdas onto single fiber pairs through tight channel spacing. Submarine cable operators on trans-Pacific routes and intercity carriers in India deploy these systems where conduit scarcity demands maximum spectral exploitation.
- Optical Switching:Reconfigurable optical add-drop multiplexers and photonic cross-connects enable wavelength-level bypass without electronic conversion. Hyperscale operators at metropolitan edge nodes in the Netherlands and Japan deploy these to reduce latency for distributed computing workloads.
- Wavelength Division Multiplexing:Coarser channel spacing serves metro and regional networks with moderate density requirements.
- Fiber Optic:Passive cabling and connectivity infrastructure underpins all active equipment deployments.
DWDM leads on scale; optical switching gains share fastest as edge computing architectures proliferate.
Application:
Deployment context dictates reliability tiers, latency specifications, and procurement channel structures.
- Cloud Services:Hyperscale builders operate private optical interconnects between data center regions, driving volume for coherent pluggable optics and open line systems. Microsoft, Amazon, and Google infrastructure teams in the United States and Ireland specify disaggregated components bypassing traditional system integrators.
- Telecommunications:Incumbent carriers maintain hierarchical transport networks with stringent availability requirements. State-owned operators in China under MIIT procurement mandates favor domestic coherent DSP designs, redirecting supply chain flows toward indigenous manufacturers.
- Data Centers:Colocation and enterprise facilities require high-density interconnects with minimal operational complexity.
- Enterprise Networks:Private fiber deployments for campus and industrial connectivity favor standardized, low-touch equipment.
Telecommunications leads on scale; cloud services expand most quickly as capex shifts from carriers to hyperscalers.
End User:
Buyer sophistication and sourcing authority fragment pricing power and technical support models.
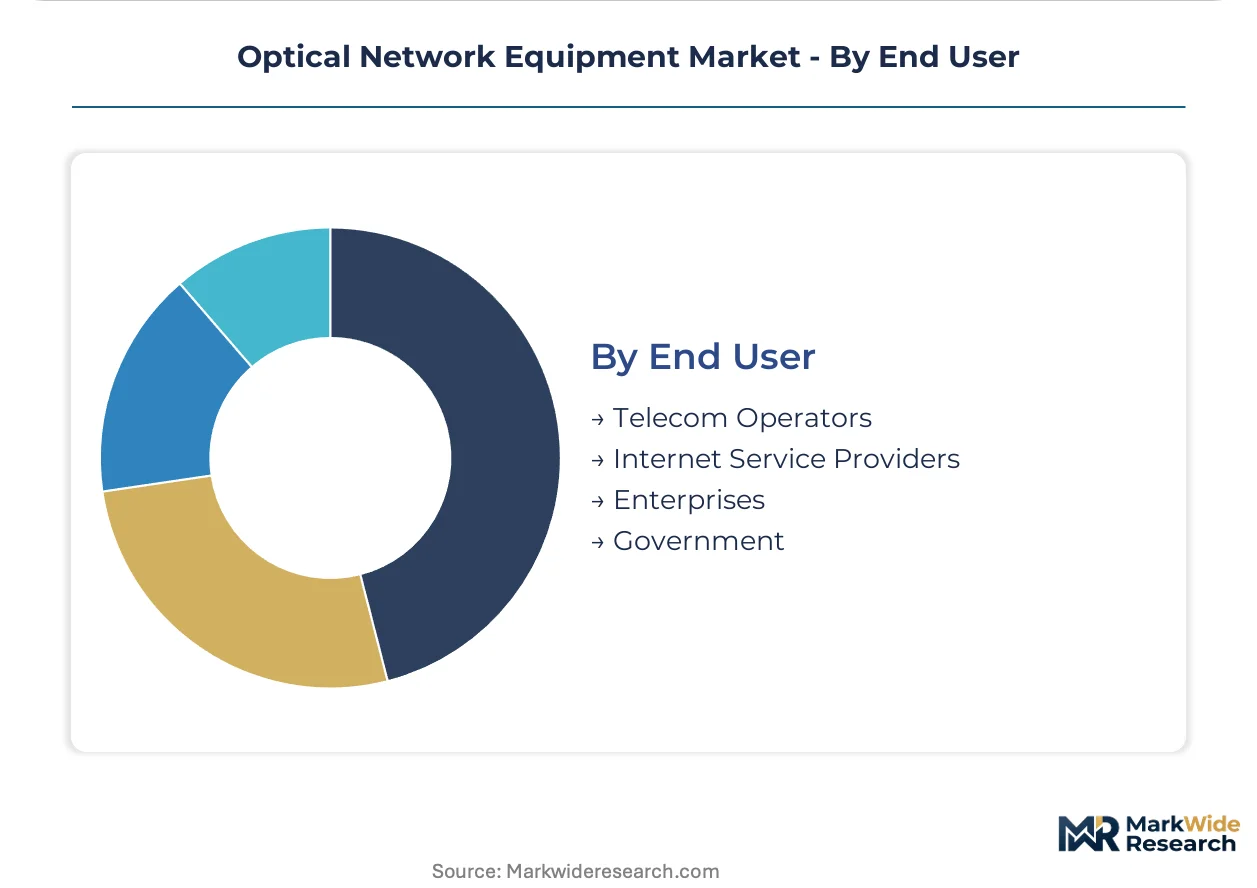
- Telecom Operators:Incumbent carriers with centralized engineering organizations negotiate multi-year framework agreements for integrated optical transport systems. Deutsche Telekom and Orange procurement teams in Europe stress-test open optical interoperability certifications through multi-vendor trials.
- Internet Service Providers:Regional and competitive ISPs procure disaggregated components directly, favoring merchant transceivers and white-box switching platforms. Indian ISPs participating in BharatNet Phase III tenders prioritize domestic assembly partnerships for coherent transceiver sourcing.
- Enterprises:Large corporations with private fiber infrastructure purchase through systems integrators or value-added resellers.
- Government:National research networks and defense communications specify security-hardened equipment with restricted vendor pools.
Telecom operators lead on scale; Internet service providers climb the fastest as distributed edge procurement bypasses traditional carrier hierarchies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Photonics engineering talent clusters in Shenzhen, Espoo, and Ottawa anchor regional supply chains for coherent DSP and silicon photonics fabrication.
United States
Hyperscale cloud builders in Northern Virginia and Oregon retrofit data center interconnects with 800G coherent pluggable optics. The Federal Communications Commission governs spectrum allocation and rural broadband subsidy programs under the Rural Digital Opportunity Fund. Microsoft's infrastructure teams in Seattle specify disaggregated open line systems bypassing traditional system integrators.
China
State-owned carriers accelerate domestic procurement of coherent transceivers under Ministry of Industry and Information Technology sourcing mandates. GB standards require indigenous content ratios that redirect supply chains toward local photonic integrated circuit foundries. Huawei Technologies anchors vertically integrated manufacturing in Shenzhen for submarine and terrestrial line systems.
India
BharatNet Phase III tenders and 5G backhaul densification drive concentrated orders for WDM line systems and coherent optics. Telecom Regulatory Authority of India governs spectrum auctions and infrastructure sharing frameworks. State-led procurement in Maharashtra and Karnataka prioritizes domestic assembly partnerships for transceiver sourcing.
Germany
Deutsche Telekom and regional carriers stress-test open optical interoperability certifications through multi-vendor trial programs. The European Telecommunications Standards Institute drives interface specifications that reduce vendor lock-in across transport layer procurement. Nokia Corporation's Bell Labs coherent DSP roadmap anchors European supply through Espoo and Munich engineering centers.
Japan
Ministry of Economy, Trade and Industry oversees national broadband targets and submarine cable security screening regimes. NTT and KDDI deploy reconfigurable optical add-drop multiplexers at metropolitan edge nodes for latency-sensitive distributed computing. Yokohama and Osaka host concentrated photonics research clusters advancing silicon photonics fabrication.
Optical Network Equipment Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across coherent DSP, silicon photonics, and open line system segments. The vendor base organizes around three strategic archetypes: vertically integrated system houses with captive component manufacturing, merchant silicon photonics specialists supplying pluggable transceivers, and open networking software vendors disaggregating hardware-software stacks. Competitive moves concentrate on strategic partnerships for interoperability certification and geographic expansion through state-led procurement channels.
Within the vertically integrated tier, Huawei Technologies Co., Ltd. and Nokia Corporation exemplify system houses controlling upstream photonic component supply. Ciena Corporation occupies a position among programmable modulation specialists. ZTE Corporation and FiberHome Telecommunication Technologies Co., Ltd. represent Chinese-origin vendors capturing domestic sourcing incentives. Infinera Corporation and Ciena Corporation sit within the merchant coherent DSP segment. Fujitsu Limited and Corning Inc. anchor specialized substrate and fiber connectivity supply. Cisco Systems exemplifies converged IP-optical platform vendors.
| Leading Market Players |
|---|
| ZTE Corporation |
| Infinera Corporation |
| Huawei Technologies Co., Ltd. |
| Corning Inc. |
| Fujitsu Limited |
| Nokia Corporation |
| Cisco Systems |
| FiberHome Telecommunication Technologies Co., Ltd. |
| Ciena Corporation |
| Others |
Value Network & Pricing Analysis
Photonic integrated circuit design engineers clustering in Taiwan and the United States create labor-cost differentials that widen pricing-tier spreads between merchant coherent DSP suppliers and vertically integrated system houses.
Pricing Analysis
The bundled-versus-unbundled service split distinguishes pricing architectures across the optical equipment landscape. Integrated system vendors command premium positioning through multi-year maintenance contracts and embedded line card solutions, while merchant transceiver suppliers compete on per-unit transactional models for hyperscale cloud builders. Price differentiation hinges on certification grade—ETSI open optical interoperability tiers versus proprietary closed systems—and volume scale from concentrated hyperscale procurement. Pricing pressure stems from coherent pluggable optics displacing embedded line cards, compressing margins in traditional transport shelf categories. Cloud service providers exhibit the least price sensitivity due to total cost of ownership optimization, whereas regional Internet service providers in India and Europe demonstrate acute sensitivity to upfront capital expenditure.
Supply Chain Analysis
Warehouse-distribution layer configurations favor hub-and-spoke patterns anchored in regional distribution centers across Germany, Singapore, and the United States. Geographic supply concentration centers on Taiwan for indium phosphide and silicon germanium wafer foundry capacity, the United States for coherent DSP design, and China for amplifier assembly under GB standards mandates. Raw material dependencies include rare earth elements for erbium-doped fiber amplifiers, specialized substrates for silicon photonics, and high-purity gases for semiconductor fabrication. Single-source vulnerability for photonic integrated circuit foundry capacity constitutes the dominant structural risk, with Taiwan Semiconductor Manufacturing and select U.S. facilities representing critical bottlenecks. Distribution runs through direct procurement relationships between hyperscale operators and component suppliers, bypassing traditional systems integrator channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, with the European Union's Open RAN interoperability mandates cascading into transport layer procurement specifications and accelerating demand for disaggregated optical hardware.
For Market Incumbents: Cement control over coherent DSP algorithm engineering talent concentrated in Bell Labs, Huawei Research, and select academic programs to defend against merchant silicon photonics specialists. Deepen backward integration into indium phosphide wafer supply through long-term foundry partnerships in Taiwan and the United States, mitigating single-source vulnerability during supply shocks. Prioritize certification investment for ETSI open optical interoperability to maintain relevance as Deutsche Telekom and Orange procurement teams stress-test multi-vendor line systems.
For New Entrants and Emerging Players: Enter via edge computing optical switching at metropolitan nodes, where hyperscale operators seek reconfigurable optical add-drop multiplexers outside traditional central office footprints. Target Internet service providers participating in BharatNet Phase III tenders, as state-led procurement channels prioritize domestic assembly partnerships over incumbent carrier hierarchies. Pursue merchant coherent transceiver supply relationships with Microsoft, Amazon, and Google infrastructure teams specifying disaggregated components.
For Investors and Strategic Acquirers: Hyperscale cloud builders are the most active acquirers in this space, seeking vertical control over optical interconnect supply chains between data center regions. Long-term viability favors merchant silicon photonics specialists with programmable modulation roadmaps and open line system interoperability certifications. Watch for inflection signals in C+L-band amplifier commercialization timelines from Ciena Corporation and Nokia Corporation, as extended spectrum deployment indicates fiber capacity expansion without new cable lays.
| Strategic Initiative | Industry Significance |
|---|---|
| Open Line System Interoperability Certification | ETSI specifications reduce vendor lock-in and fragment procurement decisions across European carriers. |
| Coherent Pluggable Optics Product Launch | QSFP-DD and OSFP form factors displace embedded line cards in hyperscale data center interconnects. |
| Silicon Photonics Fabrication Scale-Up | Merchant foundry expansion collapses cost curves for coherent optical engines and DSP integration. |
| Strategic Partnership for L-Band Amplification | C+L-band extensions nearly double fiber capacity on trans-Pacific routes where conduit scarcity constrains expansion. |
| Domestic Sourcing Compliance Program | MIIT procurement ratios under GB standards redirect Chinese state-owned carrier spending toward indigenous supply chains. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary engagement with optical transport engineering directors, hyperscale infrastructure procurement managers, regulatory affairs specialists at ETSI and FCC, and photonic component foundry operations leads. Secondary validation drew from SEC filings of listed equipment vendors, ETSI technical specification releases, TRAI spectrum auction records, and hyperscaler capital expenditure disclosures. Bottom-up transceiver shipment modeling and top-down carrier capex cycle analysis were triangulated against foundry capacity utilization indicators.
Segment-weighting approaches distributed value estimates across product type, technology, application, and end user dimensions, with additional granularity for open versus proprietary system architectures. Growth trajectories across the analysis window were derived from elasticity modeling against bandwidth demand drivers including 5G backhaul densification, cloud data center expansion, and submarine cable upgrade cycles. Forecast inputs incorporated coherent DSP roadmap timelines from Bell Labs and Huawei Research, alongside silicon photonics yield improvement curves from merchant foundry disclosures.
Inputs from primary stakeholder interviews and secondary regulatory filings were available through the study window; gaps in real-time foundry capacity utilization data and confidential hyperscale procurement contract terms introduce uncertainty bands around transceiver volume estimates. Forecasts reflect documented assumptions regarding Open RAN mandate implementation timelines and MIIT domestic sourcing ratio enforcement. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Network Technology
Lit Fiber Market
Network Technology
Fiber to the Home (FTTH) Market
Network Technology
US Private 5G Network Market
Network Technology
Private LTE Market
Network Technology
Wireless Infrastructure Monitoring Market
Network Technology
Session Border Controller (SBC) Market
Network Technology
GCC Set-Top Box Market
Network Technology
Intelligent Network Management Market
Network Technology
Application Delivery Controller (ADC) Market
Network Technology
Network Devices Market
Network Technology
Europe Self-Healing Networks Market
Network Technology
Fiber to the Premises Market
Network Technology
North America Structured Cabling Market
Network Technology
Ethernet Backhaul Equipment Market
Network Technology
Global Intelligent Network Market
Network Technology
Residential Routers Market