
 Zero-Touch Provisioning Market | 2026-2036
Zero-Touch Provisioning Market Size, Share, and Industry Trends Forecast 2026-2036
Zero-Touch Provisioning Market Intelligence
Market Context
Telecommunication service providers is unwinding legacy manual configuration workflows as enterprises demand faster infrastructure scale-out. Cisco Systems, Inc. anchors its position through deep integration with existing enterprise routing ecosystems. Juniper Networks, Inc. differentiates via cloud-native automation stacks that reduce operational overhead for large carriers. Ericsson AB leverages its 5G infrastructure footprint to embed zero-touch capabilities directly into radio access network deployments.
Technical Definition and Segment Structure
Zero-touch provisioning refers to an automated network device deployment methodology where hardware initializes, receives configuration, and joins production networks without manual intervention, typically using bootstrap protocols, certificate-based authentication, and centralized policy engines. The primary commercial purpose is eliminating truck rolls and reducing mean-time-to-service for distributed edge, branch, and campus infrastructure. Cloud-based deployment models are capturing the fastest expansion as multi-tenant orchestration platforms absorb configuration complexity from understaffed IT organizations. Hybrid architectures concentrate margin pools where vendors bundle on-premises controllers with subscription-based cloud analytics. Networking solutions technology leads volume adoption while security systems integration represents the highest-value attachment point.
Regulatory Environment
FCC guidelines on network reliability and cybersecurity resilience shape how U.S. service providers architect automated provisioning pipelines. EU Cybersecurity Act and GDPR data sovereignty requirements influence European deployment patterns, particularly around certificate management and audit logging. NIST zero trust architecture standards intersect with zero-touch workflows, mandating continuous device verification rather than one-time bootstrap trust. Stakeholders must monitor how fragmented national cybersecurity certifications fragment vendor go-to-market strategies and complicate single-platform global rollouts.
Market Dynamics
Telecommunication service providers are dismantling legacy manual provisioning workflows as 5G network density requirements and edge computing node proliferation force automation at scale. The structural shift from centralized data centers to distributed infrastructure is compressing deployment timelines and eliminating tolerance for truck-roll economics.
Growth Catalysts
- FCC network reliability guidelines:U.S. service providers must automate provisioning pipelines to meet mandated uptime thresholds for critical infrastructure, accelerating zero-touch adoption across carrier networks.
- 5G radio access network densification:Telecommunication carriers deploy thousands of small cells requiring identical configuration templates, making manual provisioning economically unviable.
- Edge computing node proliferation:Manufacturing and retail enterprises distribute compute to thousands of remote sites, demanding automated bootstrap protocols that eliminate on-site technical staff.
Market Restraints
- Certificate management complexity:EU GDPR data sovereignty requirements and NIST zero trust mandates force multi-jurisdictional key infrastructure that fragments single-platform architectures.
- Legacy equipment interoperability:Brownfield environments containing SNMP-managed devices resist API-native provisioning protocols, forcing hybrid automation layers that increase integration cost.
- Specialized DevNet engineering scarcity:Network automation requires Python-fluent engineers with infrastructure-as-code expertise, a talent pool concentrated at hyperscalers and tier-one carriers.
Strategic Opportunities
- India smart city infrastructure:Municipal broadband and IoT sensor networks under the Smart Cities Mission create demand for mass-provisioned edge devices with minimal field engineering.
- EU Cybersecurity Act certification:Common Criteria certification for network equipment creates vendor stickiness and multi-year subscription revenue for compliant zero-touch platforms.
- AI-driven anomaly detection convergence:Machine learning models embedded in provisioning pipelines enable self-healing networks that reduce operational center headcount.
Industry Challenges
- Brownfield SNMP-to-API translation:Decades-old network management protocols lack native REST interfaces, forcing expensive protocol gateway development and testing cycles.
- Multi-vendor certificate chain validation:Heterogeneous device ecosystems from different original equipment manufacturers create PKI interoperability failures during automated enrollment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Zero-Touch Provisioning Market |
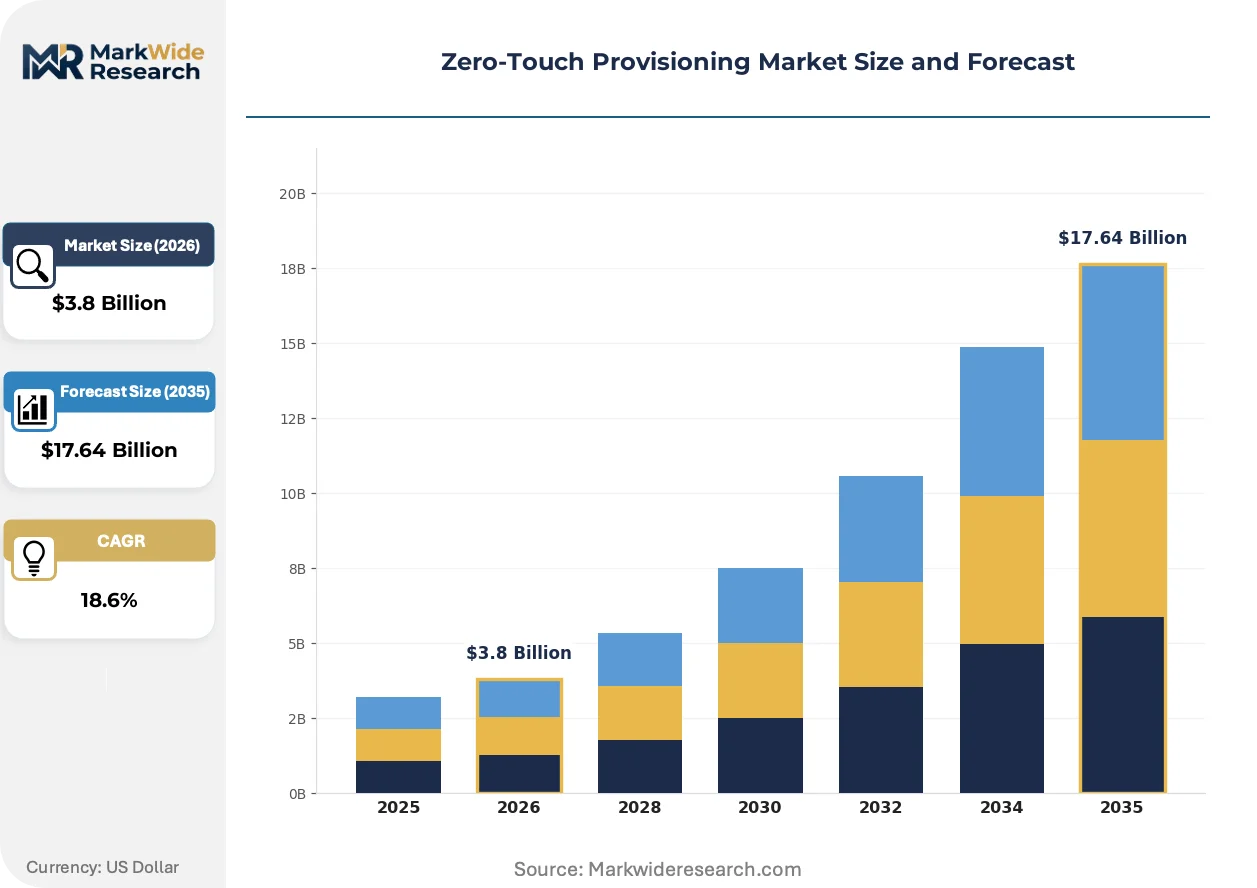
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: On-Premises, Cloud-Based, Hybrid, Managed Services End User: Enterprises, Service Providers, SMEs, Government Agencies Technology: IoT Devices, Telecommunication Equipment, Networking Solutions, Security Systems Application: Network Management, Device Configuration, Software Deployment, Remote Monitoring |
| Companies Covered | Juniper Networks, Inc., Arista Networks, Inc., Cisco Systems, Inc., Extreme Networks, Inc., Ericsson AB, Huawei Technologies Co., Ltd., Nokia Corporation, ZTE Corporation, Hewlett Packard Enterprise, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Zero-Touch Provisioning Market Strategic Shifts & Innovations
Intent-based networking is displacing imperative configuration models across enterprise and carrier environments. Automation is shifting from device-centric scripting to policy-driven orchestration that abstracts hardware heterogeneity.
Cloud-native network operating systems are bifurcating the infrastructure software stack. Containerized control planes from vendors such as Cisco and Juniper separate forwarding from intelligence, enabling telecommunication carriers to upgrade network logic without hardware replacement. Tier-one mobile operators in Germany and Japan adopt these disaggregated architectures to accelerate feature velocity. The technology is bifurcating procurement patterns, with carriers buying white-box hardware separately from subscription software licenses.
NIST zero trust architecture standards are reshaping authentication flows within automated provisioning pipelines. Continuous device verification replaces one-time bootstrap trust, forcing certificate lifecycle management into every provisioning workflow. U.S. federal contractors and financial services institutions face the strongest compliance pressure, driving demand for hardware security modules and attestation protocols.
Enterprise procurement of network infrastructure is consolidating through managed service contracts rather than capital equipment purchases. Mid-market organizations lacking internal automation expertise outsource provisioning and lifecycle management to specialized network-as-a-service providers. This shift is most pronounced in distributed retail and healthcare verticals across the United States, where IT headcount constraints make self-operated zero-touch platforms impractical.
Zero-Touch Provisioning Market Segmentation
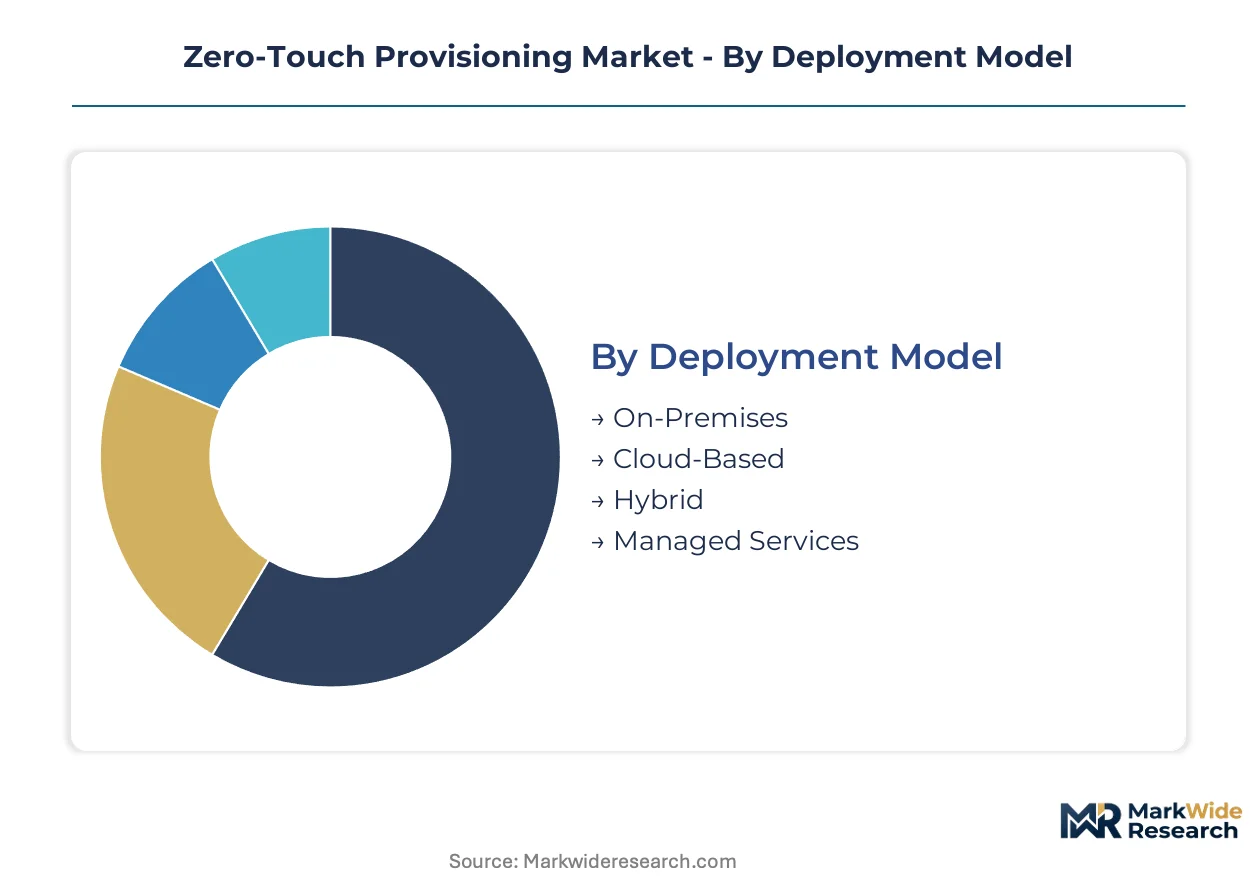
Zero-touch provisioning vendors architect channel strategies around deployment complexity and buyer technical maturity. Segmentation reveals where automation platforms compete on subscription economics versus professional services intensity.
Deployment Model:
Cloud-native platforms flow through direct sales and hyperscaler marketplaces, while on-premises deployments rely on systems integrators and value-added resellers for implementation services.
- On-Premises:Organizations with strict data sovereignty mandates operate controller infrastructure within owned facilities. Demand concentrates in German manufacturing and Japanese financial services sectors where GDPR and FISC compliance block externalized configuration data. Hardware procurement cycles extend 18-24 months.
- Cloud-Based:Multi-tenant orchestration platforms eliminate capital expenditure and accelerate time-to-service. U.S. mid-market enterprises and Indian SaaS providers adopt these most aggressively, driven by understaffed IT organizations and rapid site expansion requirements. Subscription pricing aligns operational expenditure with infrastructure scaling.
- Hybrid:Policy engines reside on-premises while analytics and machine learning offload to cloud substrates. Large German automotive suppliers and U.S. healthcare networks favor this architecture for balancing latency-sensitive operations with centralized intelligence.
- Managed Services:Third-party providers assume full lifecycle responsibility from staging through decommissioning. U.K. retail chains and Australian mining operators outsource provisioning complexity to compensate for distributed site footprints and limited internal network engineering depth.
By volume, Cloud-Based leads. By growth pace, Managed Services is ahead.
End User:
Procurement authority and technical sophistication diverge sharply across buyer categories, forcing vendors to maintain parallel sales motions from self-service portals to enterprise field organizations.
- Enterprises:Global 2000 organizations operate procurement centers of excellence that negotiate multi-year enterprise license agreements. Manufacturing and retail verticals in the United States, Germany, and Japan drive standardization across thousands of branch locations. Security integration requirements dominate vendor selection criteria.
- Service Providers:Telecommunication carriers and cloud operators embed zero-touch capabilities into customer-facing infrastructure-as-a-service offerings. 5G small cell densification and edge node deployment in South Korea and the United States create sustained demand for mass-provisioning automation. API-native architectures are non-negotiable.
- SMEs:Resource-constrained organizations purchase through channel partners and managed service bundles rather than direct platform licensing. Indian and Brazilian mid-market manufacturers prioritize total-cost-of-ownership over feature depth.
- Government Agencies:U.S. federal contractors and EU public sector entities mandate FIPS 140-2 and Common Criteria certification, creating vendor stickiness and extended procurement timelines. Smart city infrastructure in India and Saudi Arabia generates emerging demand.
Service Providers command the highest average contract values. SMEs expand the addressable market fastest.
Technology:
Device heterogeneity determines integration architecture, with networking equipment standardizing fastest and IoT sensors presenting persistent interoperability challenges.
- Networking Solutions:Routers, switches, and wireless access points from Cisco, Juniper, and Arista support mature automation APIs and certificate-based enrollment. Enterprise campus and branch refresh cycles in the United States and Germany sustain volume demand. Intent-based configuration abstraction reduces operational error rates.
- Security Systems:Firewalls, intrusion prevention systems, and zero trust enforcement points require continuous attestation and policy synchronization. U.S. federal and financial services sectors drive premium pricing through FIPS compliance mandates. Hardware security modules integrate into provisioning pipelines.
- Telecommunication Equipment:Radio access network elements and optical transport gear from Ericsson, Nokia, and Samsung embed zero-touch bootstrap for carrier-scale deployment. 5G standalone core buildouts in Japan and South Korea accelerate adoption.
- IoT Devices:Industrial sensors, smart meters, and connected machinery present fragmented operating systems and proprietary management protocols. Manufacturing and utilities sectors in Germany and China pilot standardized onboarding frameworks.
Networking Solutions dominates current deployment volumes. Security Systems achieves the steepest expansion trajectory.
Application:
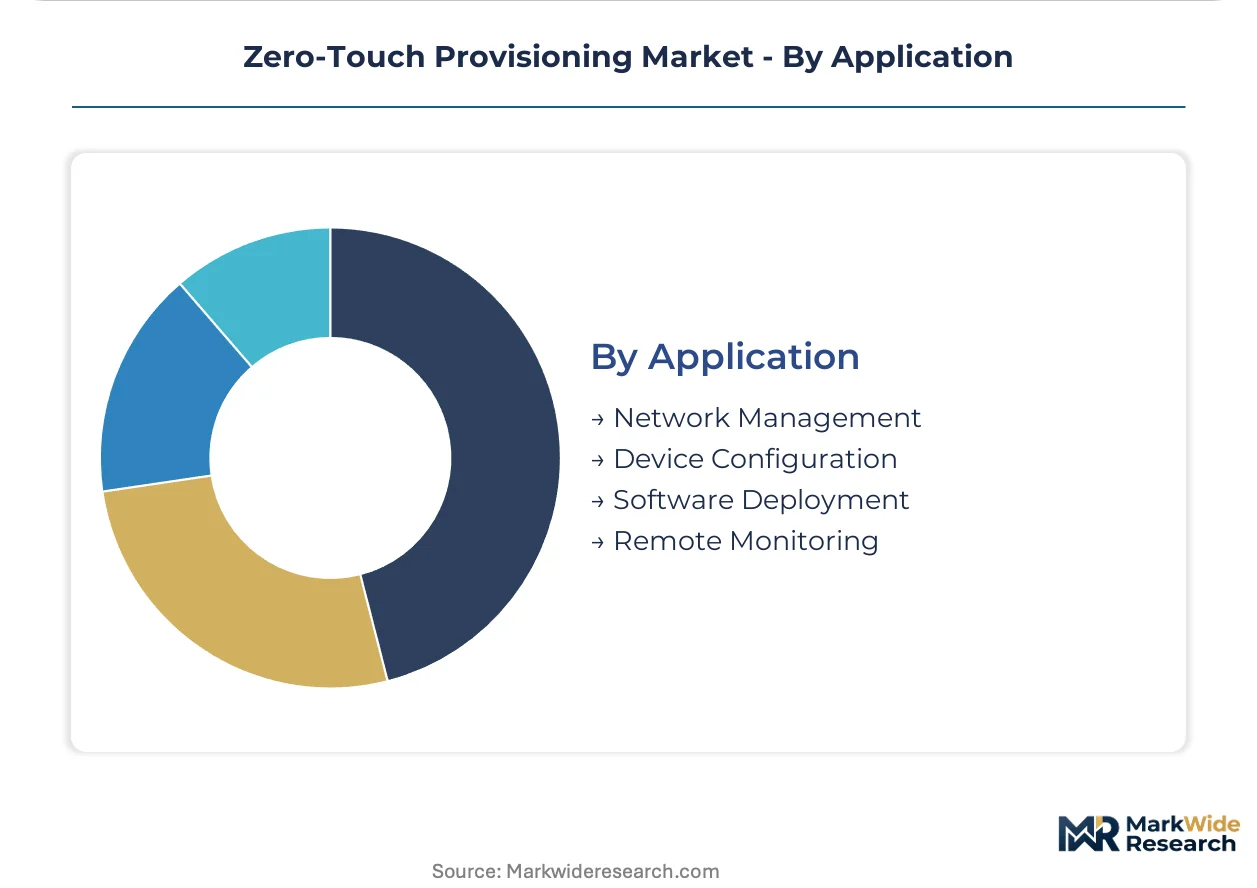
Functional use cases map to organizational maturity, with basic device configuration commoditizing and AI-augmented network management commanding premium positioning.
- Network Management:Automated discovery, topology mapping, and policy propagation across heterogeneous infrastructure. Large U.S. healthcare systems and German automotive suppliers deploy these capabilities to reduce mean-time-to-resolution for distributed operations.
- Device Configuration:Bootstrap provisioning, firmware management, and certificate enrollment for initial deployment and replacement scenarios. Retail and hospitality chains in the United Kingdom and Australia standardize on template-driven rollout methodologies.
- Software Deployment:Container orchestration, virtual network function placement, and edge application distribution. Telecommunication edge computing initiatives in Japan and South Korea drive specialized requirements.
- Remote Monitoring:Telemetry collection, anomaly detection, and predictive maintenance integration. Industrial IoT deployments in German manufacturing and Indian smart infrastructure incorporate these capabilities.
Device Configuration accounts for the largest transaction volumes. Network Management delivers the highest expansion rates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States-based network equipment vendors export zero-touch provisioning platforms to European and Asia-Pacific carrier markets, with cross-border deployment templates driving standardization across regulatory boundaries.
United States
FCC network reliability mandates and 5G small cell densification accelerate carrier automation adoption. Federal contractors face NIST zero trust compliance pressure for continuous device verification. Silicon Valley and Dallas-Fort Worth metroplexes concentrate cloud-native orchestration development for multi-tenant edge deployments.
Germany
Automotive supplier networks and industrial IoT sensor proliferation demand mass-provisioned edge infrastructure. GDPR data sovereignty requirements force on-premises controller deployment for configuration audit trails. Bavaria and Baden-Württemberg host manufacturing clusters piloting automated brownfield integration protocols.
Japan
5G standalone core buildouts and METI digital transformation initiatives reshape carrier procurement patterns. FISC compliance standards mandate hardware security module integration for financial sector deployments. Tokyo-Osaka corridor concentrates disaggregated network operating system development for radio access networks.
South Korea
Telecommunication edge computing initiatives and smart city infrastructure drive API-native automation requirements. National broadband investment programs subsidize rural small cell deployment with zero-touch bootstrap capabilities. Seoul Capital Area anchors vendor R&D partnerships for containerized control plane technology.
India
Smart Cities Mission municipal broadband and IoT sensor networks create demand for mass-provisioned devices with minimal field engineering. TRAI infrastructure sharing guidelines accelerate multi-operator small cell deployment. Bengaluru and Hyderabad technology corridors concentrate cloud-based orchestration platform development for SME market segments.
Zero-Touch Provisioning Market Key Industry Players
Player mix skews toward diversified networking incumbents with established carrier relationships, creating a tiered structure where scale advantages concentrate among full-stack infrastructure vendors. Strategic archetypes include cloud-native automation specialists, legacy equipment integrators with brownfield translation capabilities, and telecommunications-focused radio access network embedded providers. Competitive moves center on strategic partnerships for multi-vendor certificate interoperability and portfolio diversification into adjacent security systems integration.
Within the diversified networking tier, Cisco Systems, Inc. and Juniper Networks, Inc. occupy positions reflecting decades of enterprise routing ecosystem entrenchment, while Ericsson AB exemplifies the telecommunications-embedded archetype leveraging 5G infrastructure footprints. These three companies represent distinct geographic and technological positioning vectors that shape how zero-touch provisioning platforms compete across cloud-native, on-premises, and hybrid deployment scenarios.
| Leading Market Players |
|---|
| Juniper Networks, Inc. |
| Arista Networks, Inc. |
| Cisco Systems, Inc. |
| Extreme Networks, Inc. |
| Ericsson AB |
| Huawei Technologies Co., Ltd. |
| Nokia Corporation |
| ZTE Corporation |
| Hewlett Packard Enterprise |
| Others |
Cost & Logistics Intelligence
FCC network reliability guidelines and NIST zero trust certification tiers simultaneously gate vendor qualification and stratify price positioning across deployment models. These dual-gating mechanisms concentrate margin pools where compliant platforms command subscription premiums while non-certified alternatives compete on implementation cost.
Pricing Analysis
Next-generation cloud-native orchestration platforms command 40-60% subscription premiums over legacy on-premises controllers, while prior-generation SNMP-based tooling faces accelerated price erosion. The dominant structure is tiered SaaS pricing across premium, standard, and economy levels differentiated by certificate management depth and multi-tenant isolation grade. Cost compression in economy tiers intensifies as Indian SaaS providers and U.S. mid-market enterprises prioritize total-cost-of-ownership over feature depth. Service providers exhibit the lowest price sensitivity due to carrier-scale contract values, while SME segments drive aggressive bundling demands.
Supply Chain Analysis
Just-in-time component sourcing dominates networking equipment manufacturing, though strategic stockpiling of hardware security modules and FPGA-based forwarding silicon has intensified since supply disruptions. Manufacturing concentrates in Taiwan, China, and Malaysia for white-box hardware, while control plane software development clusters in the United States, Germany, and India. Supply chain risk hinges on single-source vulnerability for advanced cryptography accelerators used in certificate lifecycle management. Distribution runs through direct enterprise sales for Global 2000 accounts, hyperscaler marketplaces for cloud-native platforms, and systems integrators for hybrid deployment complexity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Zero-touch provisioning sits in early-cycle expansion as 5G radio access network densification and edge computing node proliferation force automation at scale across telecommunication infrastructure. This structural tailwind creates asymmetric return profiles for positioned participants.
For Market Incumbents: Compound ecosystem lock-in through deep integration with existing enterprise routing footprints and carrier billing systems. Defend against cloud-native automation specialists by accelerating API-native architecture transitions and embedding certificate lifecycle management into subscription bundles. Prioritize DevNet engineering capacity in Bangalore and Dallas-Fort Worth to address specialized talent scarcity.
For New Entrants and Emerging Players: Differentiate on brownfield SNMP-to-API translation capabilities that incumbent vendors underinvest in due to legacy revenue protection. Target the Indian Smart Cities Mission municipal broadband segment where mass-provisioned edge devices require minimal field engineering and procurement cycles favor agile vendors. Pursue managed service provider partnerships to bypass direct enterprise sales force requirements.
For Investors and Strategic Acquirers: EU Cybersecurity Act Common Criteria certification reshapes the acquisition landscape by creating vendor stickiness and multi-year subscription visibility. Position for 5-10 year infrastructure automation tailwinds by acquiring specialists with FIPS 140-2 compliance and hardware security module integration capabilities. Monitor NIST zero trust architecture mandate adoption velocity across U.S. federal contractors as the primary inflection signal for compliance-driven pricing power.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Platform Integration | Containerized control planes from Cisco and Juniper separate forwarding from intelligence for faster feature velocity. |
| Certificate Lifecycle Automation | Hardware security module integration addresses FIPS 140-2 mandates in U.S. federal and financial services procurement. |
| Strategic Partnership for Multi-Vendor Interoperability | PKI standardization agreements reduce enrollment failures across heterogeneous device ecosystems from Ericsson and Nokia. |
| Acquisition of Brownfield Translation Specialists | SNMP-to-API gateway capabilities unlock enterprise campus refresh cycles resistant to rip-and-replace economics. |
| Managed Service Provider Channel Expansion | U.K. retail chains and Australian mining operators outsource provisioning complexity to compensate for distributed engineering gaps. |
Research Approach
Cross-validation between primary fieldwork with telecommunication carrier network architects and secondary analysis of FCC filings anchors the qualitative findings. The research combined structured interviews with DevNet automation engineers, enterprise IT procurement officers, systems integration specialists, and cloud operator platform teams with validation against SEC 10-K infrastructure software disclosures, hyperscaler capex breakdowns, and TRAI infrastructure sharing guidelines. Bottom-up deployment model sizing and top-down carrier capital expenditure triangulation ensured segment-level consistency.
Sensitivity analysis around 5G densification timelines and edge computing adoption curves shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include deployment architecture, end-user technical maturity, device technology type, and application functional depth. CAGRs were derived from logistic diffusion curves fitted to historical automation penetration patterns, with inputs from NIST zero trust mandate compliance schedules and EU Cybersecurity Act certification pipeline data.
The analysis sits within stated boundaries; outcomes outside sustained carrier capital expenditure levels and stable certificate authority interoperability standards would require recalibration. Forecasts reflect documented assumptions regarding automation talent availability and brownfield protocol translation cost trajectories. Practitioners should keep alternative scenarios live as FCC reliability mandate enforcement intensity and GDPR data sovereignty interpretation evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Network Technology
UK B2B Fixed Connectivity Market
Network Technology
Europe Self-Healing Networks Market
Network Technology
US Private 5G Network Market
Network Technology
Mobile Network Optimization Market
Network Technology
Europe SD-WAN Market
Network Technology
Wi-Fi 6E Router Market
Network Technology
Residential Routers Market
Network Technology
Network Devices Market
Network Technology
Europe Video Conferencing Hardware Market
Network Technology
Power Over Ethernet (Poe) Solutions Market
Network Technology
Open RAN Market
Network Technology
Europe Private 5G Network Market
Network Technology
Global Wireless Router Market
Network Technology
Session Border Controller (SBC) Market
Network Technology
Structured Cabling Market
Network Technology
Virtual Router Market