
 Mobile Network Optimization Market | 2026-2036
Mobile Network Optimization Market Size, Share, and Industry Trends Forecast 2026-2036
Mobile Network Optimization Market Analysis
Project finance for open RAN infrastructure is narrowing the competitive field to operators with balance-sheet capacity for multi-year network builds. T-Mobile leverages its nationwide 5G footprint to anchor optimization investments across macro and small-cell layers. Verizon differentiates through millimeter-wave spectrum deployment, sustaining premium network performance metrics in dense urban zones. AT&T competes by integrating AI-driven traffic prediction into its core optimization stack, controlling latency-sensitive enterprise workloads.
Mobile network optimization encompasses the systematic tuning of radio access networks, core networks, and transport layers to maximize spectral efficiency, minimize latency, and ensure quality of service across heterogeneous infrastructure. The discipline employs machine learning algorithms, software-defined networking controllers, and real-time performance telemetry to automate parameter adjustments in multi-vendor environments. Managed services and implementation segments lead current revenue pools as carriers outsource complex multi-vendor integration and ongoing performance tuning to specialized vendors. AI and machine learning categories within the technology dimension represent the fastest-expanding margin pools, displacing rule-based optimization engines with predictive models that anticipate congestion before subscriber experience degrades.
The FCC enforces spectrum efficiency and interference standards that directly shape carrier capital allocation toward advanced optimization platforms, while the ITU-R framework for 5G performance benchmarks creates compliance-driven demand for quality assurance and network performance analysis applications. GDPR and emerging national data sovereignty laws in Europe and Asia constrain how optimization platforms process subscriber location and usage telemetry, forcing architectural redesigns toward edge-resident analytics engines. Stakeholders must monitor whether open RAN standardization accelerates vendor diversification or reconcentrates optimization intelligence among a handful of AI-native platform providers.
Market Dynamics
AI-driven automation is compressing optimization cycles from hours to milliseconds, forcing carriers to rebuild operational workflows around real-time inference engines rather than scheduled parameter sweeps.
Growth Catalysts
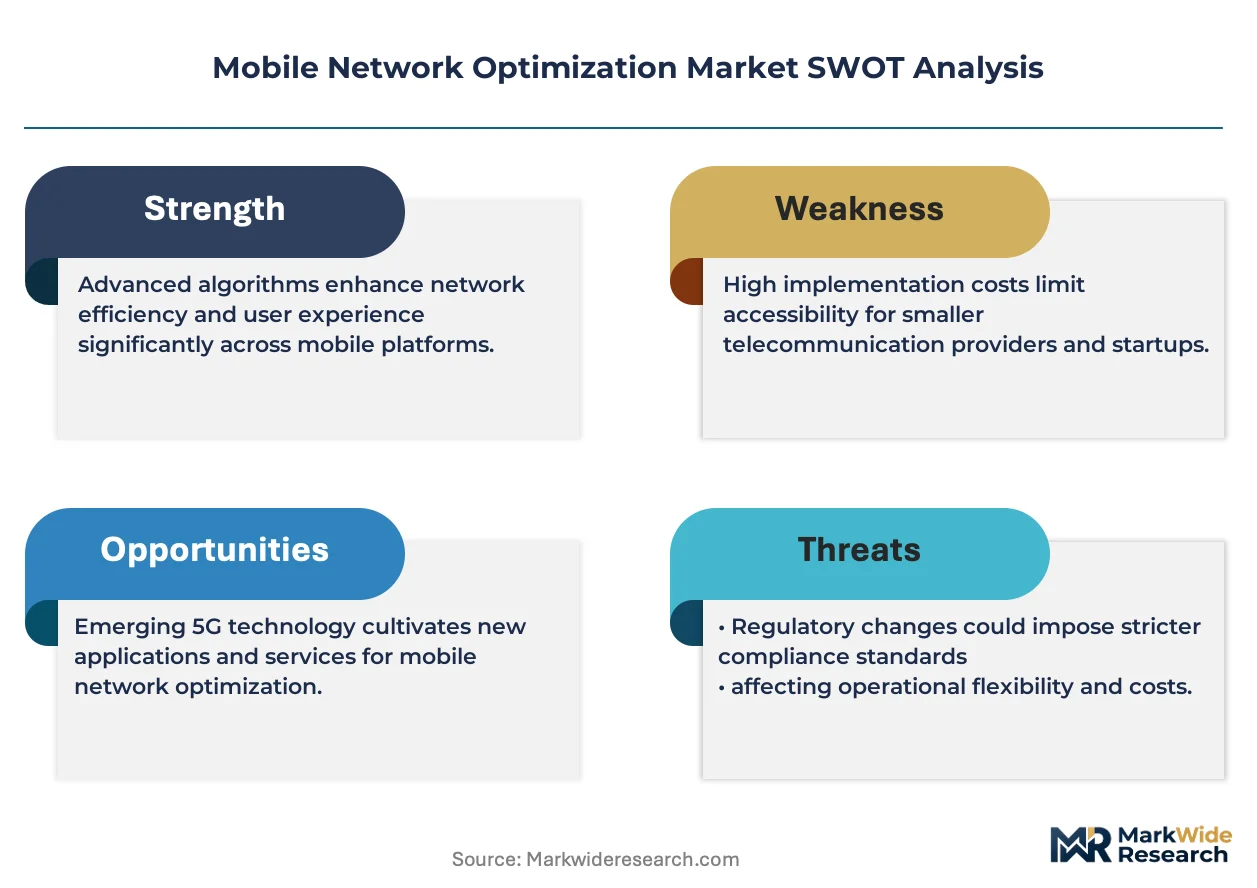
- 5G Spectrum Efficiency Mandates:The FCC's interference standards compel carriers to deploy advanced radio resource management platforms that maximize spectral throughput in congested bands.
- Video Streaming Traffic Surge:OTT platforms now account for the majority of mobile data consumption, requiring predictive congestion algorithms that pre-allocate bandwidth before quality degradation occurs.
- IoT Device Density:Massive machine-type communications in smart city deployments generate heterogeneous traffic patterns that rule-based optimization cannot accommodate.
Market Restraints
- Multi-Vendor Integration Complexity:Open RAN architectures fragment optimization intelligence across incompatible radio units, central units, and distributed units from different suppliers.
- GDPR-Driven Telemetry Constraints:European data sovereignty rules restrict subscriber location data processing, forcing architectural compromises that degrade model accuracy for mobility prediction.
- Specialized Talent Scarcity:The intersection of radio frequency engineering and machine learning operations remains critically under-supplied across carrier engineering teams.
Strategic Opportunities
- Edge-Resident Analytics:GDPR compliance requirements are accelerating deployment of on-premise inference engines that process subscriber data without cross-border transfer.
- Private 5G Networks:Manufacturing campuses and logistics hubs require dedicated optimization stacks tuned for ultra-reliable low-latency rather than consumer throughput metrics.
- Open RAN Standardization:The O-RAN Alliance's interface specifications create openings for AI-native vendors to displace incumbent radio access network optimizers.
Industry Challenges
- Legacy 4G Core Interoperability:Non-standalone 5G deployments require optimization platforms to maintain dual-stack parameter coherence across evolved packet cores and 5G cores simultaneously.
- Real-Time Model Retraining:Sub-second inference requirements conflict with the computational cost of continuous neural network updates on live traffic streams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobile Network Optimization Market |
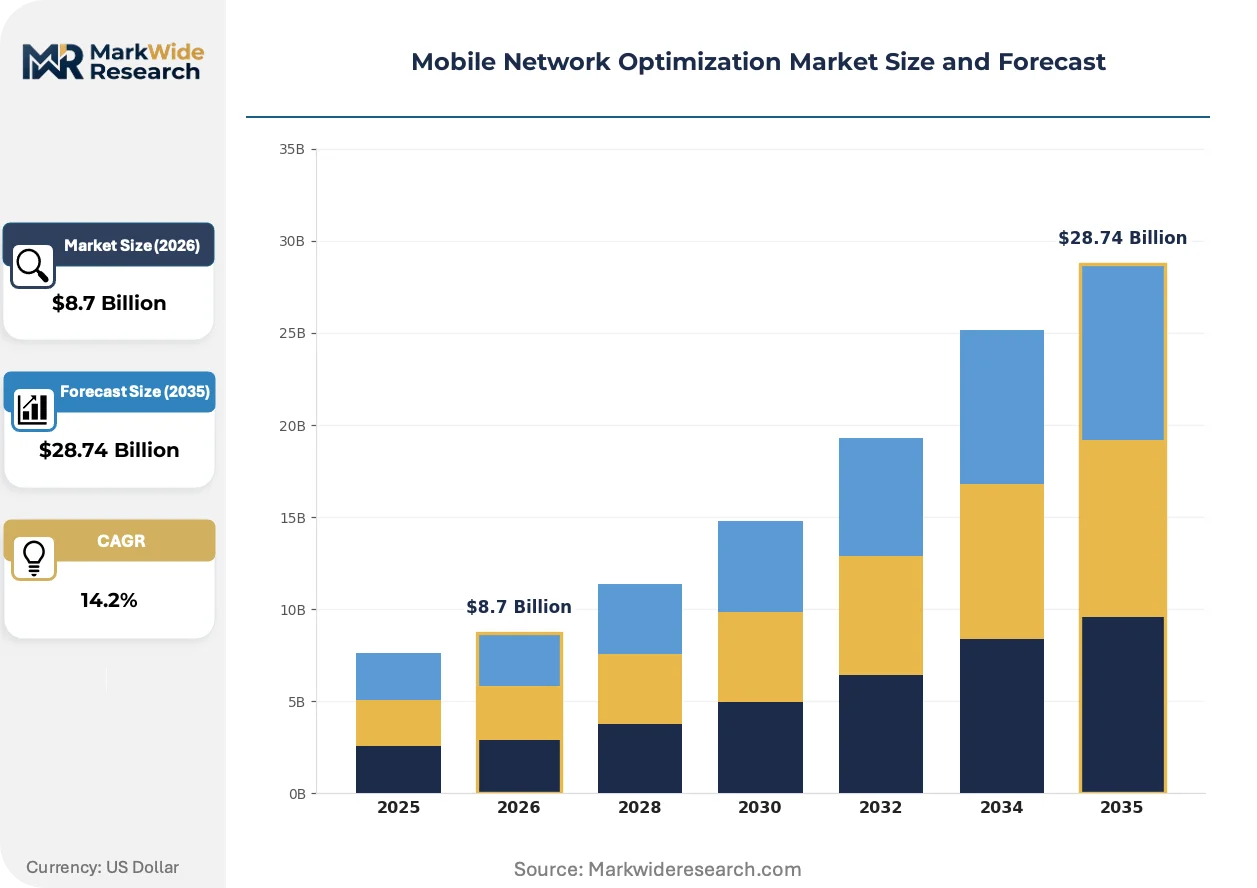
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: SDN, NFV, AI, Machine Learning Service Type: Consulting, Implementation, Managed Services, Optimization End User: Telecommunication Operators, Enterprises, Government Agencies, MVNOs Application: Data Traffic Management, Network Performance Analysis, Troubleshooting, Quality Assurance |
| Companies Covered | Lutris, monogoto, T-Mobile, Pente Networks, LitePoint, Verizon, OneLayer, wefi, AT&T, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobile Network Optimization Market Emerging Trajectories
Intelligent automation is dissolving the boundary between network planning and live operations, compressing what were sequential phases into continuous closed-loop systems that self-correct without human intervention.
Cloud-native network functions are virtualizing optimization workloads that previously required dedicated hardware appliances. Tier-1 carriers in North America and Western Europe are migrating radio access network intelligent controllers to Kubernetes-orchestrated environments, enabling elastic scaling that matches computational resources to traffic spikes. This shift is virtualizing the economics of network densification, allowing operators to deploy optimization capacity as operational expenditure rather than capital-intensive fixed infrastructure.
The EU AI Act's risk classification framework is imposing documentation and audit requirements on automated network decision systems that affect subscriber quality of service. Carriers deploying self-optimizing networks must now maintain algorithmic impact assessments and human oversight protocols for parameters affecting emergency service connectivity. European operators are responding by segmenting their optimization stacks into explainable rule-based modules for critical functions and black-box neural networks for routine traffic management.
Enterprise buyers are unbundling optimization services from infrastructure procurement contracts, creating standalone managed service agreements with specialized vendors. Manufacturing and logistics verticals in Germany and Japan now contract directly for quality-of-service guarantees rather than accepting carrier-standard service level agreements. This disintermediation is fragmenting the buyer landscape and forcing infrastructure vendors to certify their platforms for multi-tenant optimization environments where enterprise customers retain direct control over performance parameters.
Mobile Network Optimization Market Segmentation
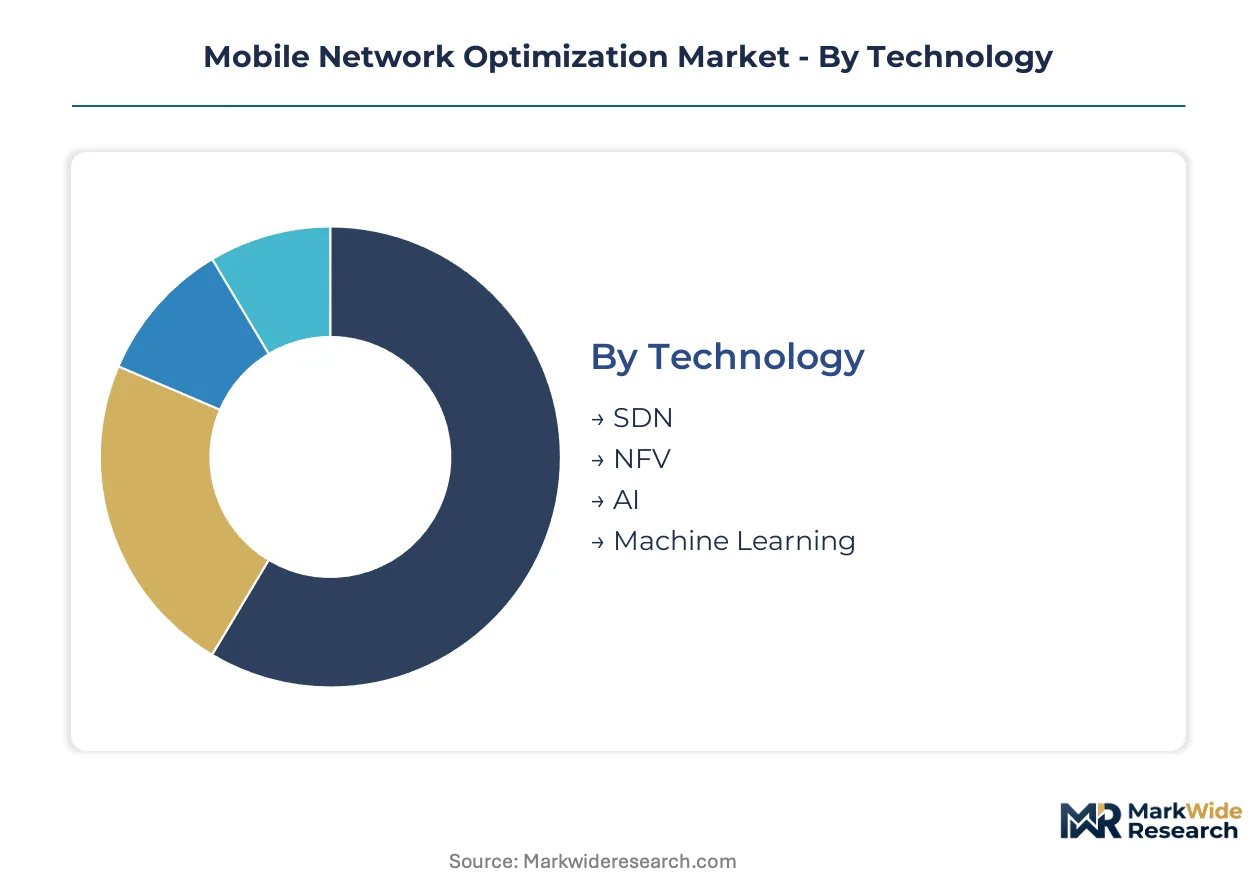
Segmentation reveals how optimization value pools concentrate across technology maturity curves and buyer sophistication levels. Distinct deployment patterns emerge between carriers modernizing legacy infrastructure and enterprises building private 5G environments.
Technology:
Use-case spectrum spans programmable control planes through predictive intelligence layers, with each technology tier addressing different latency and automation requirements.
- AI:Neural architectures process real-time telemetry from radio access networks to anticipate congestion events before subscriber experience degrades. Demand concentrates in India where Reliance Jio and Bharti Airtel deploy predictive models across dense urban 5G corridors to manage video streaming surges.
- Machine Learning:Supervised and reinforcement learning algorithms automate parameter tuning in multi-vendor radio access networks without explicit programming of every scenario. European carriers under GDPR constraints favor edge-resident ML inference engines that process subscriber data without cross-border transfer.
- SDN:Software-defined networking controllers centralize routing decisions across transport layers, enabling dynamic bandwidth allocation in response to traffic spikes.
- NFV:Network functions virtualization decouples optimization workloads from proprietary hardware, allowing elastic scaling on commodity compute infrastructure.
Established volume favors SDN infrastructure controllers; emerging adoption favors AI predictive engines.
Service Type:
Buyer sophistication determines whether carriers internalize optimization expertise or outsource complexity to specialized vendors.
- Managed Services:Third-party providers assume continuous performance tuning, multi-vendor integration, and SLA accountability for carrier networks. North American operators with lean engineering teams contract managed services to address the critical shortage of RF-machine learning hybrid talent.
- Implementation:Project-based deployment of optimization platforms including system integration, parameter baseline establishment, and operational handover. Demand clusters around 5G non-standalone deployments requiring dual-stack coherence between 4G evolved packet cores and 5G cores.
- Consulting:Advisory engagements on network architecture strategy, vendor selection, and migration roadmapping for greenfield 5G builds.
- Optimization:Discrete tuning engagements addressing specific performance bottlenecks without ongoing operational commitment.
Implementation services capture the largest current revenue pool; managed services are climbing the fastest as carriers prioritize operational expenditure models.
End User:
Buyer type shapes whether optimization prioritizes mass-market quality of service or specialized enterprise reliability metrics.
- Telecommunication Operators:Tier-1 and Tier-2 carriers constitute the foundational demand base, deploying end-to-end optimization across macro cells, small cells, and core networks. FCC spectrum efficiency mandates in the United States directly shape capital allocation toward advanced radio resource management platforms.
- Enterprises:Manufacturing campuses, logistics hubs, and mining operations contract for private 5G networks with optimization stacks tuned for ultra-reliable low-latency rather than consumer throughput. German automotive facilities and Japanese precision manufacturing plants lead enterprise adoption.
- Government Agencies:Public sector networks prioritize security-hardened optimization with domestic data residency requirements and audit trails for emergency service connectivity.
- MVNOs:Mobile virtual network operators rely on host carrier infrastructure but procure overlay optimization analytics to differentiate subscriber experience within wholesale capacity agreements.
Telecommunication operators dominate current procurement volumes; enterprises are gaining share fastest as private network deployments accelerate.
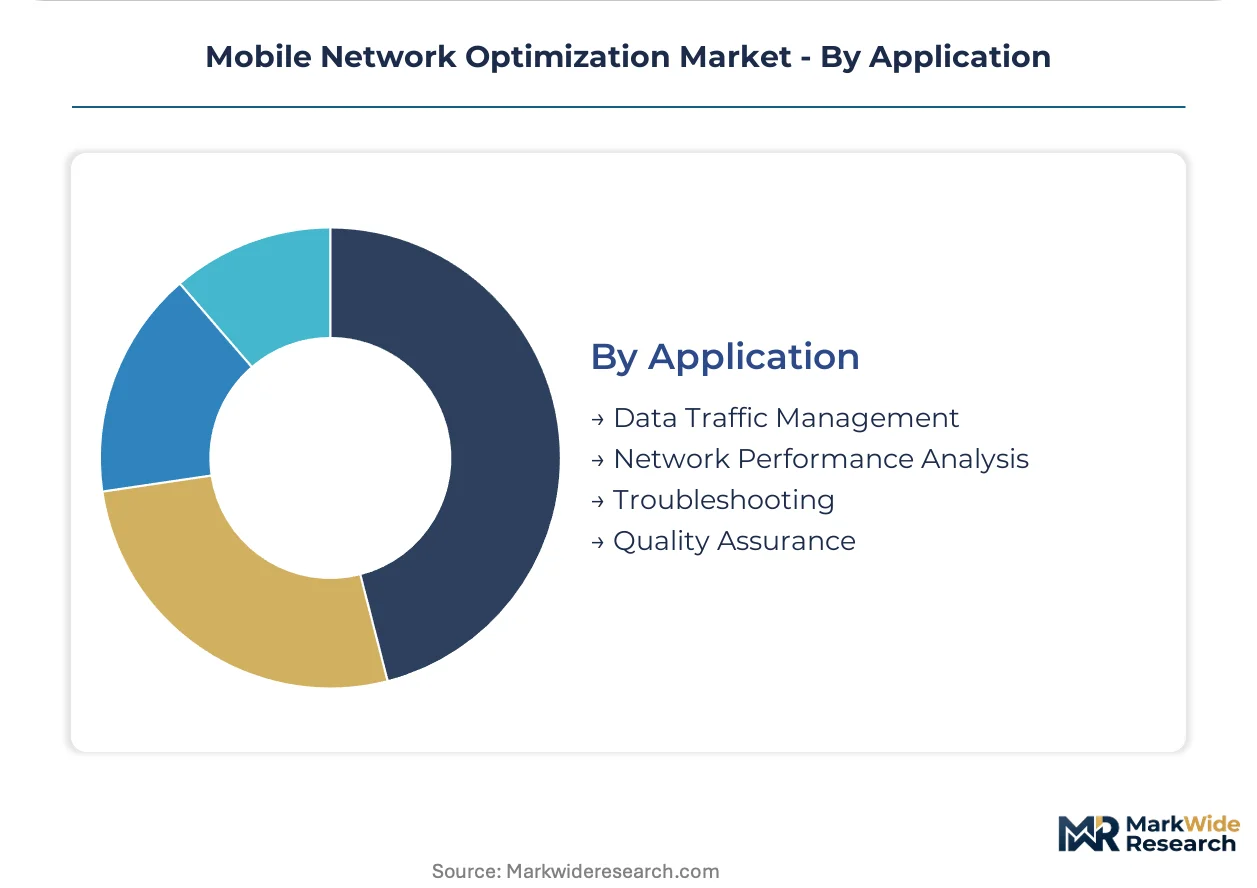
Application:
Functional purpose determines whether optimization investments target reactive problem resolution or proactive experience assurance.
- Data Traffic Management:Real-time bandwidth allocation and congestion control mechanisms prioritize latency-sensitive flows over background data. OTT video platforms now drive the majority of mobile data consumption, forcing predictive pre-allocation algorithms in Indian and United States urban corridors.
- Quality Assurance:Continuous monitoring against ITU-R 5G performance benchmarks with automated remediation when key performance indicators breach thresholds. EU AI Act compliance requirements impose documentation and human oversight protocols on automated quality decisions affecting emergency connectivity.
- Network Performance Analysis:Telemetry aggregation and root-cause identification across multi-vendor infrastructure to guide capacity planning and capital deployment.
- Troubleshooting:Reactive diagnostic tools for rapid isolation of subscriber-reported degradation events in live network operations.
Data traffic management commands the largest installed base; quality assurance platforms are expanding most quickly under regulatory compliance pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States where FCC spectrum efficiency mandates drive premium optimization spend, while Indian operators extract value through volume-driven deployment economics at lower unit prices.
United States
T-Mobile anchors nationwide 5G optimization investments across macro and small-cell layers, while Verizon sustains millimeter-wave deployment in dense urban zones. FCC interference standards compel carriers toward advanced radio resource management platforms. AT&T integrates AI-driven traffic prediction in Dallas-Fort Worth and Chicago corridors to manage enterprise latency workloads.
India
Reliance Jio and Bharti Airtel aggressively roll out 5G infrastructure requiring real-time radio access network optimization. TRAI spectrum allocation frameworks shape capital deployment toward dense urban corridors. Mumbai and Delhi-NCR clusters lead predictive model deployment for video streaming surge management.
Germany
Automotive manufacturing campuses drive private 5G network optimization demand for ultra-reliable low-latency communications. EU AI Act documentation requirements impose algorithmic impact assessments on self-optimizing networks. Stuttgart and Wolfsburg industrial zones contract directly for quality-of-service guarantees separate from carrier-standard agreements.
Japan
Precision manufacturing plants and logistics hubs generate enterprise optimization procurement outside traditional carrier channels. METI industrial digitalization programs subsidize private network deployment in manufacturing corridors. Nagoya and Osaka industrial clusters lead edge-resident analytics adoption under data sovereignty constraints.
United Kingdom
Ofcom spectrum efficiency mandates compel carriers toward network densification and interference management investments. GDPR telemetry constraints force architectural redesigns toward edge-resident analytics engines. London and Manchester urban corridors concentrate predictive congestion algorithm deployment for OTT video traffic management.
Mobile Network Optimization Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream supplying discrete optimization modules. The vendor base organizes around three archetypes: carrier-affiliated platforms leveraging captive network data, independent software vendors selling cross-carrier solutions, and hardware-originated players virtualizing legacy appliances. Consolidation pressure favors scale in AI training data access and multi-vendor integration expertise. Dominant competitive moves include strategic partnerships with open RAN consortiums and portfolio diversification into edge analytics.
Among carrier-integrated platforms, T-Mobile, Verizon, and AT&T exemplify the vertical-capture archetype where optimization intelligence stays within operator-controlled stacks. These entities represent the demand-side integration pattern, embedding optimization directly into network infrastructure procurement rather than treating it as a standalone vendor category. Their position illustrates how balance-sheet capacity for multi-year network builds narrows the competitive field in open RAN infrastructure finance.
| Leading Market Players |
|---|
| Lutris |
| monogoto |
| T-Mobile |
| Pente Networks |
| LitePoint |
| Verizon |
| OneLayer |
| wefi |
| AT&T |
| Others |
Supply Flow & Price Mechanics
Undercapacity in AI-native optimization platform engineering across North America and Western Europe is driving supplier backlog accumulation and sustaining premium pricing for configured-to-order deployments. Carrier procurement teams face extended lead times for multi-vendor integration specialists, compressing negotiation leverage and locking in cost structures for multi-year network builds.
Pricing Analysis
The customization-premium spread in mobile network optimization separates standard SaaS-tiered subscriptions for routine traffic management from project-based implementation pricing for multi-vendor open RAN integration. Price differentiation hinges on certification level under O-RAN Alliance specifications and geographic delivery cost for edge-resident analytics deployment. Cost compression in the managed services tier is intensifying because carrier engineering teams are outsourcing complexity to address RF-machine learning talent scarcity. Enterprise buyers in German automotive facilities demonstrate the lowest price sensitivity due to ultra-reliable low-latency requirements, while MVNOs relying on wholesale capacity agreements face the highest price sensitivity with limited optimization budgets.
Supply Chain Analysis
Export-control regime restrictions on GPU and AI accelerator technology flows from the United States are constraining optimization platform training infrastructure access for vendors serving certain geographies. Geographic supply concentration centers on the United States for cloud-native orchestration software, India for RF engineering talent pools, and Taiwan for specialized semiconductor components powering edge inference engines. Raw material dependencies include high-bandwidth memory modules, programmable logic devices, and precision timing synchronization hardware. Single-source vulnerability in GPU supply chains poses structural risk for AI-driven optimization platform vendors. Distribution runs through direct enterprise sales teams for private 5G deployments and carrier procurement frameworks for telecommunication operator contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity is expanding as enterprise buyers unbundle optimization services from infrastructure procurement, creating standalone vendor relationships outside traditional carrier channels. This demand-side shift generates niche openings for specialized AI-native platform providers.
For Market Incumbents: Entrench market position through backward integration into edge-resident analytics hardware and captive supply of RF-machine learning hybrid engineering talent. Capacity addition in Indian optimization engineering hubs addresses the critical talent shortage threatening service delivery timelines. Certification investment under EU AI Act documentation requirements creates switching costs against emerging software-only competitors. For New Entrants and Emerging Players: Private 5G network optimization for Japanese precision manufacturing plants represents the most penetrable entry point, with direct quality-of-service contracting bypassing established carrier relationships. Mid-market logistics hubs in Southeast Asia offer secondary white-space targeting as METI-subsidized deployment models diffuse regionally. Go-to-market execution should anchor on outcome-based performance guarantees rather than infrastructure procurement bundling. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among managed service providers with multi-year SLA accountability and operational expenditure contracting structures. Long-term viability across the analysis window favors acquisition targets with demonstrated multi-vendor open RAN integration expertise and proprietary training data from live carrier deployments. The signal to watch is carrier capital expenditure reallocation toward AI-driven automation platforms versus legacy rule-based optimization engine maintenance.| Strategic Initiative | Industry Significance |
|---|---|
| Edge-Resident Analytics Deployment | GDPR compliance and EU AI Act documentation requirements accelerate on-premise inference engine adoption. |
| Open RAN Consortium Partnership | O-RAN Alliance interface specifications create vendor diversification openings against incumbent radio access network optimizers. |
| AI-Native Platform Acquisition | Training data access from live carrier networks constitutes defensible competitive moat in predictive congestion modeling. |
| Private 5G Managed Service Launch | German automotive facilities and Japanese manufacturing plants contract directly for ultra-reliable low-latency guarantees. |
| RF-Machine Learning Talent Pipeline | Engineering scarcity across carrier teams sustains premium pricing for specialized optimization service providers. |
Methodological Framework
A spread of perspectives from network planning executives at tier-1 carriers, RF engineering directors, open RAN procurement leads, and enterprise IT infrastructure managers converged on the working assumptions underlying this analysis. Primary interview intelligence combined with secondary validation from FCC spectrum allocation filings, TRAI regulatory notices, O-RAN Alliance technical specifications, and carrier capital expenditure disclosures. Bottom-up deployment tracking across urban corridor clusters triangulated against top-down market sizing from infrastructure vendor revenue segmentation.
Demand-supply balance modeling anchored the forecast framework, with carrier 5G densification timelines and enterprise private network adoption curves as primary demand inputs against AI platform engineering capacity and semiconductor component availability as supply constraints. Segmentation dimensions modeled include technology maturity tier, service delivery model, end-user archetype, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted adoption curves across the projection horizon, incorporating ITU-R performance benchmark compliance deadlines and spectrum efficiency mandate enforcement schedules as industry-specific forecast inputs.
Practitioners should monitor open RAN standardization velocity, GPU export-control regime adjustments, and carrier balance-sheet capacity for multi-year network builds as early signals of forecast revision triggers. Forecasts reflect assumptions about regulatory enforcement continuity and semiconductor supply normalization. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Network Technology
Smart Network Interface Card (Smartnic) Market
Network Technology
Industrial Ethernet Market
Network Technology
Mobile Backhaul Market
Network Technology
Europe Self-Healing Networks Market
Network Technology
Network Management Systems (NMS) Market
Network Technology
Global Home Networking Device Market
Network Technology
CPE Router Market
Network Technology
Router and Switch Market
Network Technology
RTP Market
Network Technology
Global Enterprise Session Border Controller (SBC) Market
Network Technology
Global Network Probe Market
Network Technology
Indoor Distributed Antenna Systems Market
Network Technology
North America Network Management Solutions Market
Network Technology
Global Passive Optical Network (PON) Equipment Market
Network Technology
US Private LTE and 5G Network Market
Network Technology
Global Private 5G Network Market