
 Network Fault Monitoring Tools Market | 2026-2036
Network Fault Monitoring Tools Market Size, Share, and Industry Trends Forecast 2026-2036
Network Fault Monitoring Tools Market Foresight
Managed service providers are unwinding legacy enterprise self-managed contracts as cloud-native buyers gain procurement authority. SolarWinds sustains channel density across mid-market IT services through extensive partner certification programs. Datadog leverages deep telemetry integration to anchor premium positioning among DevOps-centric organizations.
Network fault monitoring tools detect, diagnose, and alert on infrastructure anomalies using packet inspection, SNMP polling, and flow analysis with sub-second detection thresholds to preserve service-level agreements. Cloud-based solutions are capturing the fastest expansion as hybrid architectures proliferate, while on-premise deployments retain dominance in financial institutions with air-gapped compliance requirements. Real-time monitoring features command the deepest margin pools due to their direct linkage to revenue-protecting uptime guarantees.
FCC network reliability mandates in the United States and the EU AI Act's algorithmic transparency requirements in Europe are elevating audit-grade logging and explainable fault correlation to baseline procurement criteria. ISO 27001 and IEC 62368-1 standards further constrain vendor architectures for cross-border data handling. Stakeholders must weigh sovereign cloud deployment obligations against the operational velocity of centralized SaaS platforms when architecting procurement roadmaps.
Market Dynamics
Hybrid cloud migration is fragmenting procurement authority between infrastructure teams and DevOps units, forcing vendors to serve dual buying committees with conflicting technical requirements and contracting preferences.
Growth Catalysts
- FCC reliability mandates:US telecommunications carriers must maintain 99.999% uptime under federal rules, mandating fault detection investments that cascade through supplier ecosystems.
- Industrial automation clusters:Germany's manufacturing density creates concentrated demand for millisecond-latency monitoring in automotive and chemical processing facilities.
- eBPF kernel instrumentation:Extended Berkeley Packet Filter technology enables zero-overhead telemetry collection that eliminates agent deployment friction in containerized environments.
Market Restraints
- Specialized engineering talent scarcity:Packet-level analysis expertise concentrates in telecom vendor hubs, inflating implementation costs for enterprise buyers outside these clusters.
- Air-gapped compliance architecture:Financial institutions in Switzerland and Singapore require on-premise deployments that forefeit SaaS operational efficiencies.
- SNMP protocol obsolescence:Legacy polling infrastructure in established accounts resists API-native replacement, extending sales cycles.
Strategic Opportunities
- EU AI Act explainability requirements:Algorithmic transparency mandates create first-mover advantage for vendors embedding correlation reasoning into alert workflows.
- Edge computing deployments:Manufacturing sites in Vietnam and Mexico lack mature monitoring infrastructure, presenting greenfield installation potential.
- Channel partner certification programs:Structured enablement of regional systems integrators unlocks mid-market accounts without direct sales expansion.
Industry Challenges
- Multi-cloud correlation complexity:Engineers must normalize telemetry across AWS, Azure, and GCP native formats without standardization frameworks.
- ISO 27001 audit preparation:Certification timelines extend 12-18 months for vendors serving cross-border data handling requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Network Fault Monitoring Tools Market |
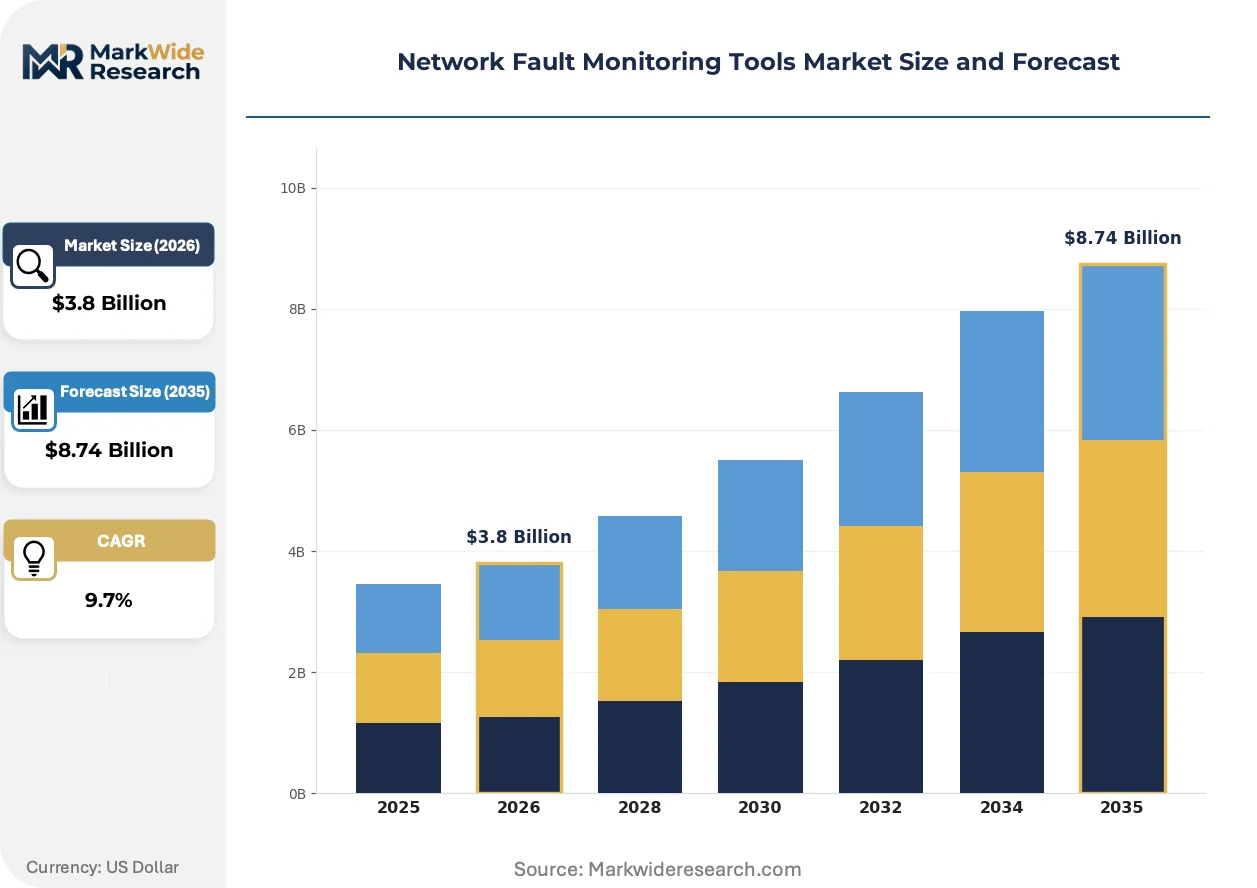
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software, Hardware, Cloud-based Solutions, On-premise Solutions Feature: Real-time Monitoring, Alerting Systems, Analytics, Reporting Tools Deployment: On-premise, Hybrid, Cloud, SaaS End User: Telecommunications, IT Services, Financial Institutions, Education |
| Companies Covered | LogicMonitor, PathSolutions, SolarWinds, Zabbix, Nagios, Paessler (PRTG), Domotz, Datadog, Auvik, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Network Fault Monitoring Tools Market Shifts & Advancements
Observability pipelines are absorbing fault monitoring functionality, collapsing the distinction between infrastructure health and application performance management into unified telemetry architectures.
eBPF-based kernel instrumentation is decomposing the agent deployment model that dominated enterprise network monitoring for two decades. Cloud-native platform teams at SaaS providers and fintechs are adopting eBPF for zero-touch visibility into container traffic without sidecar overhead. This technology is decomposing the traditional agent licensing revenue structure and compressing vendor differentiation toward analytics layers rather than data collection.
GDPR Article 32 security processing requirements and the EU AI Act's algorithmic transparency provisions are elevating audit-grade logging to baseline procurement criteria. Vendors must now provide immutable evidence trails for fault correlation decisions. European financial services and critical infrastructure operators are prioritizing platforms with built-in compliance documentation over pure performance specifications.
Managed detection and response contracts are displacing perpetual license purchases in mid-market accounts. Security operations centers prefer bundled network visibility with threat hunting services rather than standalone fault tools. This preference shift concentrates most visibly in UK and Netherlands markets where MSP consolidation has reduced direct procurement authority among IT departments.
Network Fault Monitoring Tools Market Segmentation
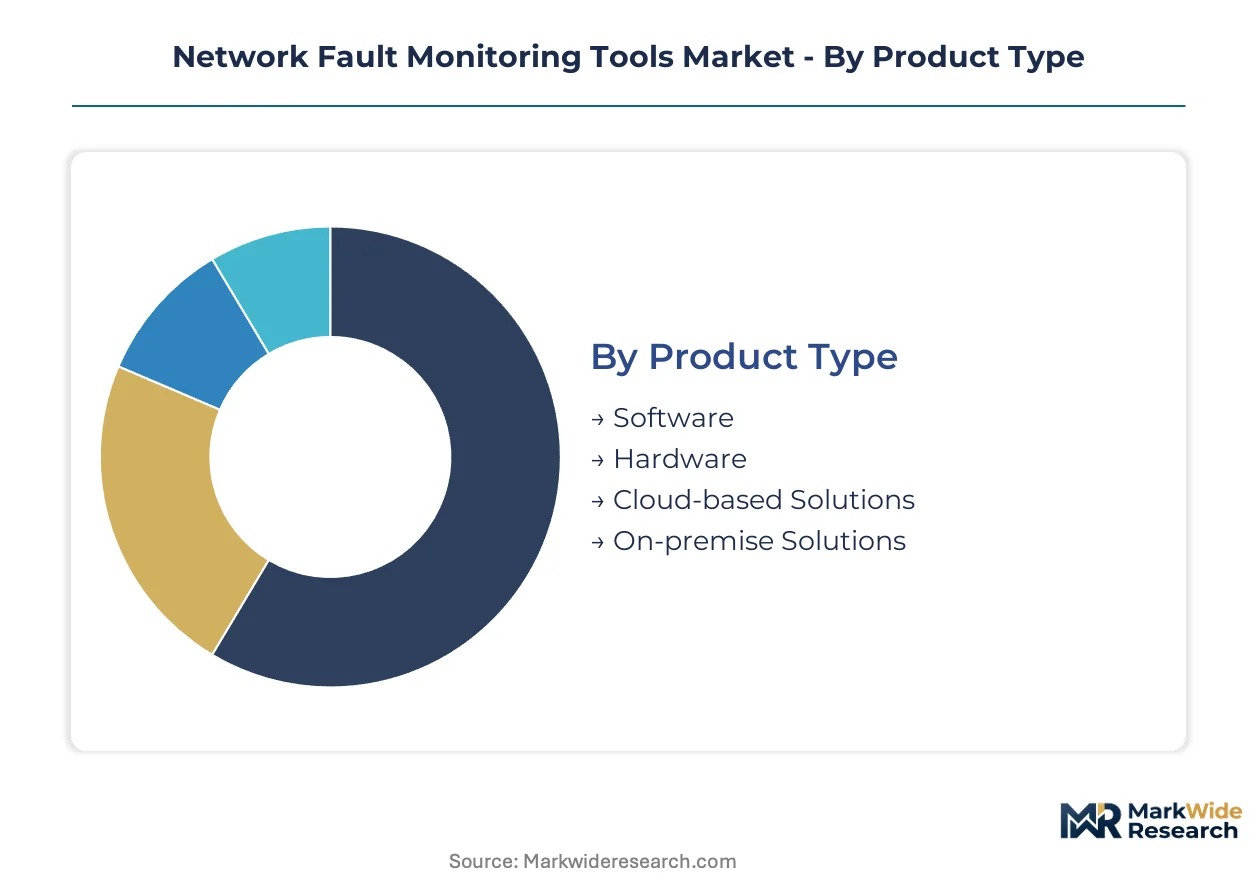
Network fault monitoring tools fragment across four critical dimensions that determine procurement authority and technical architecture. Product type and deployment mode define infrastructure investment profiles, while feature sets and end-user verticals shape margin structures and compliance requirements.
Product Type:
Software solutions dominate domestic procurement in North American enterprise accounts, while hardware appliances retain export strength into regulated Asian financial hubs. Cloud-based offerings concentrate in European SaaS-native organizations seeking rapid elasticity.
- Software:Agent-based and agentless code packages deploy across virtualized infrastructure with API-native integration into ITSM platforms. Demand concentrates among mid-market IT services firms in the United States and Germany seeking configurable correlation engines without hardware refresh cycles.
- Hardware:Dedicated appliance form factors with specialized packet capture ASICs process multi-gigabit traffic at line rate. Swiss and Singaporean financial institutions mandate these deployments for air-gapped compliance, accepting higher capital intensity for sovereign data control.
- Cloud-based Solutions:Multi-tenant SaaS architectures with consumption-based metering eliminate infrastructure ownership. European manufacturing clusters in Bavaria and the Netherlands adopt these for distributed site coverage without on-premise engineering.
- On-premise Solutions:Perpetually licensed software with local data retention satisfies audit requirements in French healthcare and German automotive sectors where GDPR Article 32 documentation obligations apply.
Software holds the largest share; momentum sits with cloud-based solutions.
Feature:
Real-time capabilities command premium pricing tiers, while analytics layers differentiate vendor positioning in competitive evaluations. Alerting sophistication separates procurement winners in regulated verticals.
- Real-time Monitoring:Sub-second detection thresholds using flow analysis and synthetic transaction probing preserve carrier SLA commitments. United States telecommunications operators under FCC reliability mandates represent the core demand concentration for millisecond-latency correlation.
- Alerting Systems:Multi-channel notification engines with escalation workflows and on-call rotation integration reduce mean-time-to-resolution. DevOps-centric organizations in UK fintech clusters prioritize these for incident response automation.
- Analytics:Pattern recognition and predictive degradation modeling transform telemetry into capacity planning intelligence. German industrial automation facilities leverage these for predictive maintenance integration.
- Reporting Tools:Compliance-ready documentation generators with immutable audit trails satisfy EU AI Act explainability requirements. French and Italian critical infrastructure operators mandate these for regulatory submission.
Real-time monitoring commands the deepest margins; analytics layers are expanding most quickly.
Deployment:
Deployment architecture determines operational velocity versus compliance posture, with hybrid configurations capturing the steepest expansion trajectory as multi-cloud fragmentation accelerates.
- On-premise:Complete infrastructure control with local data sovereignty satisfies Swiss banking and Saudi petrochemical requirements. These deployments sacrifice elasticity for audit-grade isolation.
- Hybrid:Split telemetry processing with edge collection and cloud analytics balances latency sensitivity with operational scale. German automotive and Netherlands logistics operators adopt these for factory-floor-to-cloud visibility.
- Cloud:Fully managed SaaS consumption eliminates capacity planning and patch management overhead. United States SaaS providers and UK digital banks standardize on these for velocity.
- SaaS:Subscription-based delivery with automatic feature updates and shared security responsibility models. Mid-market accounts in Australia and Canada prefer these for predictable opex structures.
Hybrid deployments anchor the largest installed base; pure SaaS delivery is gaining share fastest.
End User:
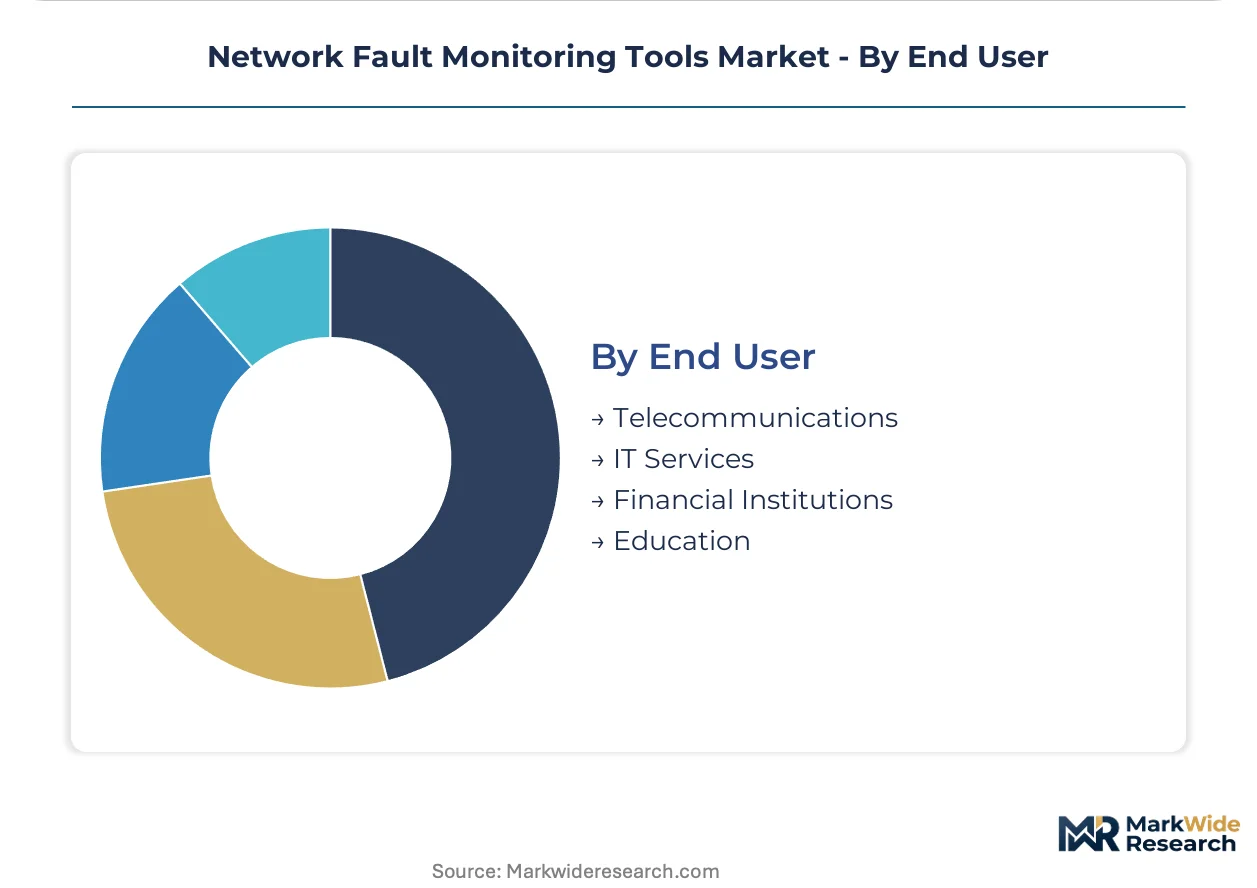
Telecommunications carriers drive the highest performance specifications, while financial institutions impose the most stringent compliance documentation requirements. Education represents the most price-sensitive procurement segment.
- Telecommunications:Carrier-grade fault detection with five-nines uptime enforcement under FCC mandates. United States and Japanese network operators invest most heavily in packet-level instrumentation.
- IT Services:Multi-tenant monitoring platforms supporting managed service provider consolidation. UK and Netherlands MSPs bundle these with security operations for mid-market accounts.
- Financial Institutions:Immutable audit trails and explainable correlation reasoning under EU AI Act and GDPR Article 32. German and French banks lead procurement of compliance-embedded platforms.
- Education:Cost-optimized visibility for campus network resilience without specialized engineering staff. State university systems in the United States and technical colleges in India represent volume concentration.
Telecommunications holds the largest share; financial institutions are expanding procurement most aggressively.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Telecommunications carriers and financial institutions anchor procurement authority across major economies, with regulatory mandates fragmenting deployment preferences between cloud-native velocity and air-gapped compliance.
United States
FCC reliability mandates enforce 99.999% uptime for telecommunications carriers, cascading fault detection investments through supplier ecosystems. HIPAA and SEC audit requirements constrain data handling architectures for healthcare and financial operators. Dallas-Fort Worth and Northern Virginia data center clusters concentrate demand for millisecond-latency monitoring among cloud-native SaaS providers.
Germany
Industrial automation density in automotive and chemical processing drives premium tool adoption with stringent uptime requirements. EU AI Act algorithmic transparency provisions and GDPR Article 32 security processing obligations elevate audit-grade logging to baseline procurement criteria. Bavarian manufacturing clusters and Baden-Württemberg automotive hubs standardize on hybrid deployments balancing factory-floor latency with cloud analytics scale.
United Kingdom
DevOps-centric fintech organizations prioritize alerting sophistication for incident response automation, displacing legacy enterprise self-managed contracts. Financial Conduct Authority operational resilience requirements mandate comprehensive visibility documentation. London and Manchester MSP consolidation concentrates managed detection and response contract growth.
Switzerland
Air-gapped compliance architecture requirements from FINMA and the Swiss Federal Data Protection Act mandate on-premise deployments forfeiting SaaS operational efficiencies. Banking secrecy traditions reinforce sovereign data control preferences among Zurich and Geneva financial institutions. Hardware appliance procurement dominates despite higher capital intensity.
Singapore
Monetary Authority of Singapore technology risk management guidelines impose stringent uptime documentation for financial infrastructure. Maritime logistics and petrochemical processing clusters demand real-time correlation for revenue-protecting guarantees. Jurong Island industrial zone and Marina Bay financial district anchor concentrated procurement.
Network Fault Monitoring Tools Market Competitive Landscape
Player mix skews toward specialized monitoring vendors with deep telemetry integration capabilities. Mid-market channel density competes against enterprise-grade platform consolidation. Three archetypes dominate: DevOps-centric observability platforms, legacy infrastructure specialists with certification-heavy partner ecosystems, and MSP-focused streamlined deployment tools. Competitive moves concentrate on hybrid cloud feature parity and compliance-embedded documentation automation.
Within the observability-integrated tier, Datadog exemplifies deep telemetry anchoring among cloud-native buyers. SolarWinds occupies a position representing channel-dependent mid-market penetration through extensive partner certification structures. Paessler anchors the streamlined deployment archetype with PRTG's accessibility-focused positioning. These three represent divergent responses to procurement authority fragmentation between infrastructure teams and DevOps units.
| Leading Market Players |
|---|
| LogicMonitor |
| PathSolutions |
| SolarWinds |
| Zabbix |
| Nagios |
| Paessler (PRTG) |
| Domotz |
| Datadog |
| Auvik |
| Others |
Supply & Pricing Matrix
Capacity utilization at specialized ASIC foundries in Taiwan and South Korea shapes both supply concentration and price floors for hardware appliances, while SaaS delivery models decouple pricing from component scarcity through subscription economics.
Pricing Analysis
Cost-plus contracts with semiconductor price indexation dominate hardware procurement for financial institutions in Switzerland and Singapore. Three-tier pricing structure across premium, standard, and economy levels separates carrier-grade real-time correlation from mid-market alerting bundles. Cost compression in the hardware tier is intensifying because eBPF-based agentless architectures reduce proprietary ASIC dependency. Education sector buyers exhibit highest price sensitivity, while telecommunications carriers under FCC mandates show lowest sensitivity due to SLA enforcement requirements.
Supply Chain Analysis
Strategic stockpiling of packet capture ASICs persists among Swiss and Singaporean financial institutions despite just-in-time preferences among cloud-native SaaS providers. Component manufacturing concentrates in Taiwan, South Korea, and Germany. Supply chains draw from specialized silicon foundries, optical transceiver modules, and kernel instrumentation libraries. Single-source vulnerability in advanced node semiconductor fabrication creates structural exposure. Distribution runs through certified systems integrators and direct enterprise sales teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The acute shortage of packet-level analysis engineers concentrated in telecom vendor hubs creates persistent capability gaps that reshape competitive dynamics and vendor selection criteria.
For Market Incumbents: Consolidate channel certification programs to lock in mid-market MSP relationships before cloud-native observability platforms displace standalone fault tools. SolarWinds' partner density model offers a template for defensive positioning. Invest in eBPF analytics layers to offset compression in agent licensing revenue. Prioritize ISO 27001 certification acceleration to satisfy cross-border data handling requirements.
For New Entrants and Emerging Players: Managed detection and response service bundling represents a service-layer gap where incumbents under-serve mid-market security operations centers. Target UK and Netherlands MSP consolidation zones with streamlined deployment tools. Greenfield manufacturing sites in Vietnam and Mexico offer penetrable edge computing infrastructure without entrenched vendor relationships. Lead with consumption-based SaaS pricing to bypass capital-intensive hardware procurement cycles.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors observability-integrated platforms over standalone fault specialists as telemetry pipelines collapse functional boundaries. Five-to-ten year viability hinges on hybrid cloud feature parity and compliance-embedded documentation automation. Acquisition targets should demonstrate EU AI Act explainability capabilities and eBPF instrumentation expertise. Monitor FCC mandate enforcement intensity as inflection indicator for carrier-side procurement acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies fault monitoring with application performance management for DevOps-centric buyers. |
| Strategic Partnership | Certifies regional systems integrators to unlock mid-market accounts without direct sales expansion. |
| Acquisition of Specialist Firm | Captures eBPF kernel instrumentation expertise for zero-overhead container visibility. |
| Geographic Expansion | Establishes sovereign cloud deployments to satisfy GDPR Article 32 documentation obligations. |
| Product Launch | Introduces explainable correlation reasoning to meet EU AI Act algorithmic transparency mandates. |
Research Methodology
A standing panel of network operations directors, DevOps platform engineers, MSP procurement leads, and telecommunications infrastructure planners provided ongoing calibration across primary fieldwork. Secondary validation drew from FCC enforcement filings, EU AI Act implementation guidance, hyperscaler capex disclosures, and ITSM platform integration documentation. Bottom-up demand modeling triangulated against top-down market sizing across deployment modes and vertical segments.
Consistency checks against external benchmarks validated volume and value outputs across the analysis window. Segmentation dimensions modeled include deployment architecture, organization size, vertical compliance intensity, and regional regulatory cluster. CAGRs were derived from fitted growth curves incorporating eBPF adoption velocity, MSP contract displacement rates, and sovereign cloud deployment obligations. Forecast inputs included industrial automation facility expansion timelines and telecommunications carrier infrastructure refresh cycles.
Material uncertainties — regulatory enforcement intensity, semiconductor supply disruptions, and talent migration patterns — sit outside the modeled envelope. Forecasts reflect documented assumptions about hybrid cloud migration velocity and compliance deadline adherence. Revision becomes warranted when eBPF instrumentation penetration crosses thresholds that structurally compress agent-based revenue models.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Network Technology
Global Gigabit Wi-Fi Access Points Market
Network Technology
North America Enterprise WLAN Market
Network Technology
Europe Structured Cabling Market
Network Technology
Radio Modem Market
Network Technology
Mobile Network Optimization Market
Network Technology
Wi-Fi As a Service (Waas) Market
Network Technology
Wimax Solutions Market
Network Technology
Router and Switch Market
Network Technology
Europe Private 5G Network Market
Network Technology
Unified Network Management Market
Network Technology
Zero-Touch Provisioning Market
Network Technology
Small Cell Networks Market
Network Technology
GCC Set-Top Box Market
Network Technology
DHCP and IP Address Management Market
Network Technology
Converged Cable Access Platform (CCAP) Market
Network Technology
Cloud Managed Access Points Market