
 Global Quartz Countertops Market | 2026-2036
Global Quartz Countertops Market Size, Share, and Industry Trends Forecast 2026-2036
Global Quartz Countertops Market Foresight
Residential kitchen specification is hardening as the dominant installation site, while hospitality venues recover renovation budgets post-pandemic. Cambria sustains its position through captive manufacturing in the United States, controlling raw material sourcing from Minnesota mines. Caesarstone competes through design-forward collections targeting interior designer channels. LX Hausys anchors Asia-Pacific distribution with localized production facilities in South Korea and Vietnam.
Quartz countertops are engineered stone surfaces comprising approximately 90-93% ground natural quartz aggregate bound with polymer resins and pigments, then cast under vacuum vibration and cured to achieve hardness ratings exceeding 7 on the Mohs scale. Their primary purpose is to deliver non-porous, scratch-resistant work surfaces for food preparation and high-traffic commercial environments. Engineered quartz dominates volume due to consistent color matching and slab dimensional stability, while sintered quartz captures premium positioning through heat resistance superior to resin-bound alternatives. Recycled quartz remains nascent but attracts sustainability-focused property developers seeking LEED contribution points.
FDA food-contact surface standards and EPA formaldehyde emission protocols shape product formulation requirements for US-bound manufacturers, while REACH chemical restrictions in Europe constrain resin additive portfolios. OSHA silica exposure limits are forcing fabrication shop investments in wet-cutting infrastructure, altering downstream cost structures. Stakeholders must monitor evolving silica classification debates across multiple jurisdictions, as regulatory reclassification would cascade through mining, manufacturing, and installation liability frameworks.
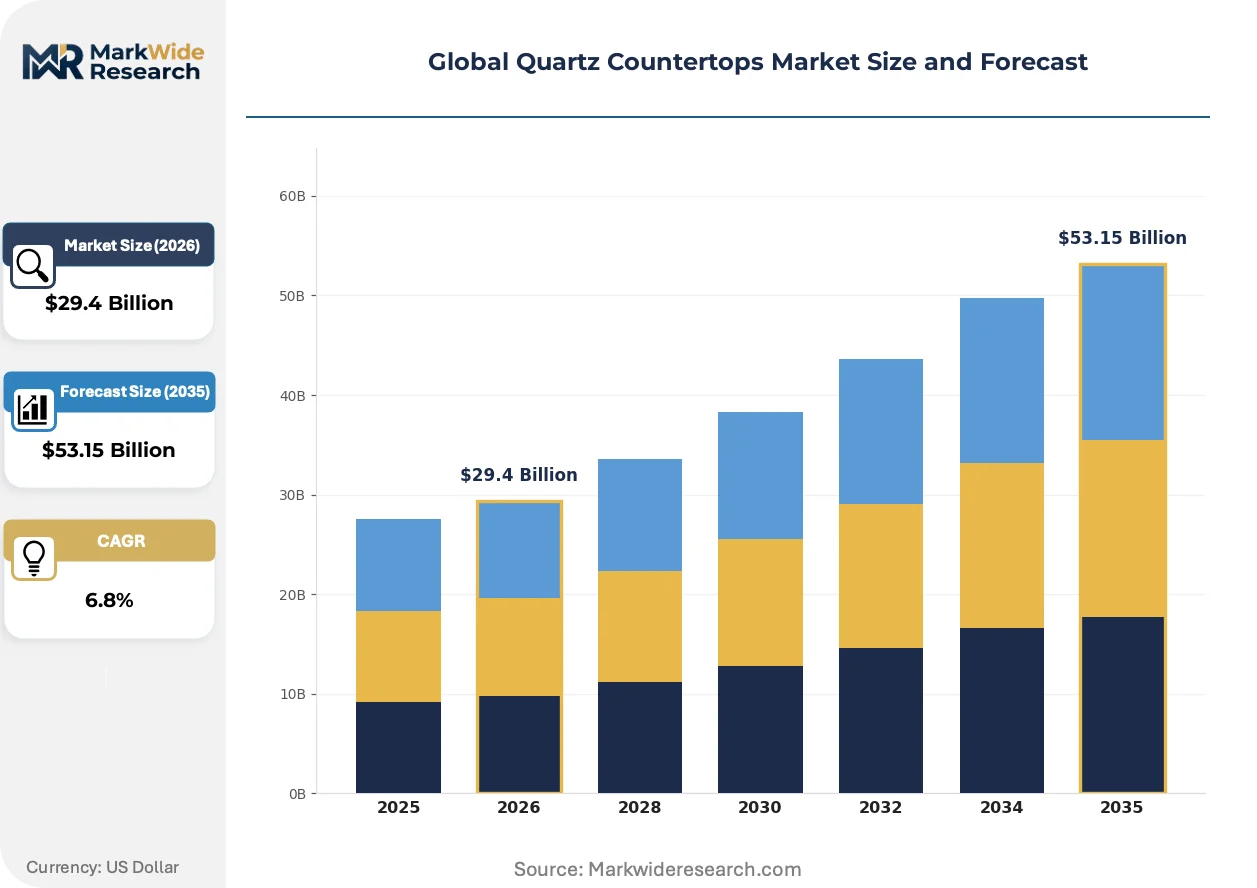
Market Dynamics
OSHA silica exposure limits are compressing fabrication economics across North America, forcing wet-cutting infrastructure investments that alter downstream cost structures and reshape competitive positioning among regional fabricators.
Growth Catalysts
- EMA and REACH compliance pressure:European chemical restrictions are accelerating low-silica formulation R&D among resin suppliers, creating first-mover advantages for compliant manufacturers.
- Hospitality renovation cycles:Post-pandemic budget recoveries in lodging and foodservice sectors are hardening demand for stain-resistant, high-traffic surfaces.
- India's urban residential corridors:Middle-income housing stock expansion in Mumbai, Bangalore, and Delhi NCR concentrates specification demand for engineered stone kitchens.
Market Restraints
- Petrochemical resin volatility:Polymer binder costs fluctuate with crude oil derivatives, compressing margin stability for slab producers.
- Quartz mining concentration:High-purity silica deposits cluster in limited geographies, creating raw material security risks for non-integrated manufacturers.
- Sintered stone substitution:Heat-resistant ceramic alternatives capture premium positioning in outdoor kitchen and commercial cooking applications.
Strategic Opportunities
- Recycled content certification:LEED contribution point systems reward post-consumer quartz incorporation, attracting sustainability-focused property developers.
- Direct-to-fabricator digital platforms:B2B marketplaces bypass traditional distributor layers, compressing lead times for mid-size installation contractors.
- EU Green Deal alignment:Carbon border adjustment mechanisms favor localized European production over long-haul Asian imports.
Industry Challenges
- Fabrication workforce respiratory training:OSHA compliance demands certified wet-cutting technicians, creating skilled labor bottlenecks in high-growth construction markets.
- Slab dimensional standardization delays:Inconsistent thickness tolerances between Asian and North American producers complicate cross-border specification workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Quartz Countertops Market |
| Market Size in 2026 | $29.4 Billion |
| Market Size in 2035 | $53.15 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engineered Quartz, Natural Quartz, Sintered Quartz, Recycled Quartz Design Style: Modern, Classic, Rustic, Minimalist, Contemporary Installation Site: Residential Kitchens, Commercial Spaces, Hospitality Venues, Institutional Facilities End User: Homeowners, Interior Designers, Contractors, Property Developers |
| Companies Covered | Cosentino, Caesarstone, Cambria, Vicostone, LX Hausys, Hanwha Group, Compac, DuPont, Fletcher Building, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Quartz Countertops Market Shifts & Advancements
Formulation chemistry and surface engineering are overtaking aesthetic differentiation as the primary competitive battleground, with regulatory compliance and performance certification now driving specification decisions ahead of color matching.
Low-silica engineered stone is overtaking conventional high-quartz formulations in specification-intensive segments. These polymer-rich surfaces reduce respirable crystalline silica exposure during fabrication. Commercial contractors in California and New York are mandating compliant materials for hospitality and healthcare projects. The shift is compressing demand for legacy formulations while rewarding captive resin production capabilities.
REACH chemical restrictions are constraining resin additive portfolios across European manufacturing. ECHA substance evaluations are phasing out specific hardeners and UV stabilizers previously standard in quartz binding systems. German and Italian slab producers are reformulating with bio-based alternatives, accepting modest hardness trade-offs for regulatory continuity.
Certification-driven procurement now dominates large-scale commercial specification. Food-contact surface validation under FDA protocols and formaldehyde emission testing per EPA standards are becoming mandatory bid prerequisites. Multi-family residential developers in Texas and Florida are prioritizing pre-certified suppliers to accelerate project approval timelines.
Global Quartz Countertops Market Segmentation
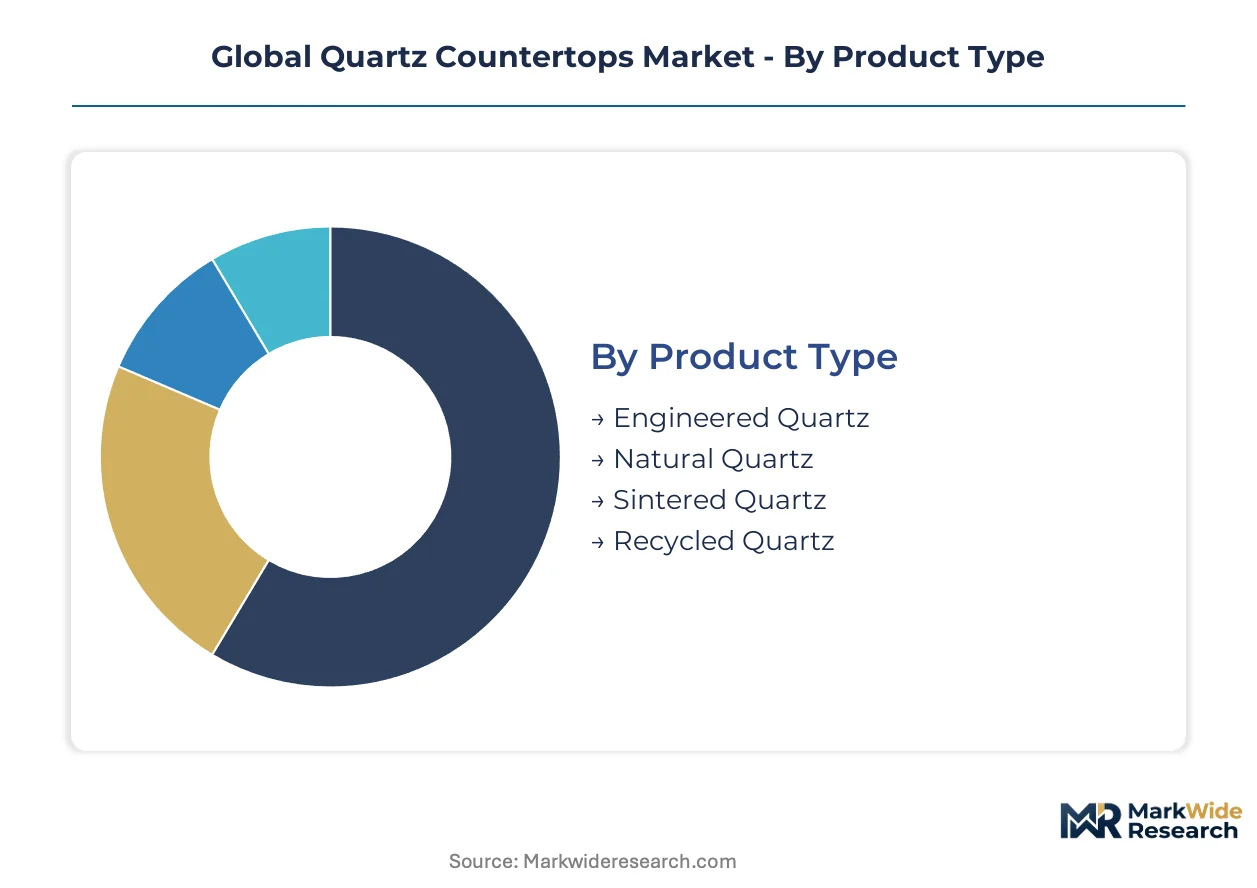
Segmentation in the quartz countertops market reveals how regulatory pressure and specification requirements concentrate demand across distinct product tiers. Certification burdens vary sharply by segment, with commercial and hospitality applications demanding FDA food-contact validation and EPA formaldehyde compliance while residential specifications prioritize aesthetic flexibility.
Product Type:
FDA food-contact surface standards and EPA formaldehyde emission protocols apply differentially across these material categories, with resin-bound formulations facing stricter scrutiny than sintered alternatives.
- Engineered Quartz:Comprising 90-93% ground natural quartz aggregate bound with polymer resins, this segment dominates specification volume through consistent color matching and slab dimensional stability. Demand concentrates in India's urban residential construction corridors as middle-income housing stock expands in Mumbai, Bangalore, and Delhi NCR.
- Sintered Quartz:Ceramic-based surfaces formed under extreme heat and pressure without resin binders, achieving superior thermal resistance for outdoor kitchen and commercial cooking applications. Hospitality renovation cycles in the United States and United Arab Emirates are hardening demand for these heat-resistant surfaces in high-traffic foodservice environments.
- Natural Quartz:Solid stone surfaces cut from mineral deposits, prized for unique veining patterns but constrained by supply inconsistency and higher maintenance requirements.
- Recycled Quartz:Post-consumer and post-industrial quartz aggregate incorporated into new binding matrices, attracting sustainability-focused property developers seeking LEED contribution points.
Leading the category by volume: Engineered Quartz. Expanding most quickly: Sintered Quartz.
Design Style:
Cost tier stratification separates premium designer collections from specification-grade standard offerings, with fabrication complexity and pigment technology driving price differentiation.
- Modern:Clean lines, bold geometric patterns, and high-contrast color schemes characterize this specification-intensive segment. Interior designer channels in California and New York specify these surfaces for multi-family residential and boutique hospitality projects.
- Classic:Marble-veined aesthetics and neutral palettes dominate mass-market residential replacement cycles, particularly in suburban United States housing stock.
- Rustic:Textured finishes and earth-tone pigments appeal to vacation property and agritourism venue specifications in Colorado and Tuscany.
- Minimalist:Ultra-matte surfaces and near-monochrome palettes command premium positioning in Scandinavian-influenced commercial interiors.
- Contemporary:Fluid patterns and metallic accents target luxury residential developments in Dubai and Singapore.
Modern and Classic styles together account for the majority of specification volume, with Minimalist designs gaining share fastest in commercial segments.
Installation Site:
Application-specific performance requirements dictate resin formulation choices, with high-traffic commercial environments demanding enhanced scratch resistance and stain repellency.
- Residential Kitchens:The dominant installation site for engineered quartz, driven by renovation cycles in owner-occupied housing. Homeowners in Texas and Florida prioritize pre-certified suppliers to accelerate project approval timelines.
- Commercial Spaces:Corporate foodservice and retail environments specify surfaces meeting stringent durability standards. EMA and REACH compliance in Europe is pushing manufacturers toward low-silica formulations for these high-liability installations.
- Hospitality Venues:Hotels and restaurants recovering post-pandemic renovation budgets demand stain-resistant surfaces for bars, buffets, and guest room vanities.
- Institutional Facilities:Healthcare and educational buildings require antimicrobial surface treatments and enhanced impact resistance, particularly in Germany and Japan.
Residential Kitchens lead by installation volume. Hospitality Venues are climbing the fastest as lodging sector capital expenditure recovers.
End User:
Procurement authority and specification influence vary sharply across customer types, with professional intermediaries controlling access to premium project channels.
- Homeowners:Direct purchasers in replacement and renovation markets, typically price-sensitive and influenced by retail showroom presentation. Big-box retail channels in the United States serve this volume base.
- Interior Designers:Specification gatekeepers for high-end residential and commercial projects, commanding design-forward collections and exclusive colorways. Caesarstone competes through dedicated designer channel programs.
- Contractors:Installation professionals managing procurement for mid-market developments, increasingly accessing direct-to-fabricator digital platforms to compress lead times.
- Property Developers:Volume purchasers for multi-unit residential and mixed-use projects, prioritizing LEED contribution points and certification documentation for sustainability mandates.
Contractors and Property Developers together drive the majority of volume procurement, with Interior Designers controlling the steepest margin tier.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's Special Economic Zones for construction materials are channeling foreign direct investment into Gujarat and Maharashtra, accelerating domestic slab production capacity.
United States
Post-pandemic hospitality renovation budgets in Las Vegas and Miami are hardening demand for stain-resistant surfaces. OSHA silica exposure limits are forcing wet-cutting infrastructure investments across fabrication shops in California and Texas. Cambria's captive Minnesota mining operations supply raw material security for domestic producers.
Germany
REACH chemical restrictions are phasing out specific hardeners and UV stabilizers in quartz binding systems. ECHA substance evaluations are constraining resin additive portfolios for slab producers in North Rhine-Westphalia. German fabricators in the Ruhr region are reformulating with bio-based alternatives to maintain regulatory continuity.
India
Middle-income housing stock expansion in Mumbai, Bangalore, and Delhi NCR concentrates specification demand for engineered stone kitchens. BIS certification requirements are tightening for imported slab materials entering through Mundra and Hazira ports. LX Hausys anchors Asia-Pacific distribution with localized production facilities in South Korea and Vietnam serving Indian contractors.
China
Yangtze River Delta manufacturing clusters in Jiangsu and Zhejiang provinces dominate engineered quartz export volume. GB standards for building materials are aligning with international food-contact surface protocols. Ningbo and Foshan fabrication hubs are investing in automated cutting lines to reduce silica exposure compliance costs.
United Arab Emirates
Hospitality venue construction in Dubai and Abu Dhabi demands heat-resistant sintered surfaces for outdoor kitchen applications. MOHAP building material regulations are converging with European REACH frameworks for commercial installations. Jebel Ali free zone concentration of regional distribution centers accelerates slab import logistics for Saudi and Egyptian contractors.
Global Quartz Countertops Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with design-forward collections commanding premium positioning in designer channels while volume producers compete on slab dimensional consistency and certification documentation. The vendor base organizes around three strategic archetypes: captive miners controlling upstream quartz supply, resin-integrated formulators managing formulation chemistry, and pure-play fabricators focusing on installation speed. Consolidation pressure is accelerating through M&A activity targeting regional distribution networks, while capacity expansion concentrates in low-cost manufacturing zones with favorable trade access.
Among North American integrated producers, Cambria and Caesarstone exemplify divergent competitive positioning—Cambria through captive Minnesota mining and domestic manufacturing, Caesarstone through design-forward collections targeting interior designer channels. LX Hausys anchors Asia-Pacific distribution with localized production facilities, representing the regional-scale archetype that balances cost proximity with specification-grade quality.
| Leading Market Players |
|---|
| Cosentino |
| Caesarstone |
| Cambria |
| Vicostone |
| LX Hausys |
| Hanwha Group |
| Compac |
| DuPont |
| Fletcher Building |
| Others |
Supply & Pricing Matrix
Certified wet-cutting technicians in California and Texas fabrication hubs command wage premiums that widen spreads between premium certified-installer tiers and uncertified economy-tier competitors. OSHA silica compliance investments compress margins at the low end while resin-integrated formulators capture pricing power through captive supply security.
Pricing Analysis
Short lead-time premiums for just-in-time slab delivery separate expedited project pricing from spot-inventory discount tiers. Three-tier pricing structure across premium designer collections, specification-grade standard offerings, and economy-grade builder slabs reflects certification grade and brand positioning. Pricing pressure stems from petrochemical resin volatility compressing margin stability for non-integrated slab producers. Property developers in multi-family residential segments exhibit highest price sensitivity, while interior designer channels show lowest sensitivity to per-square-foot premiums.
Supply Chain Analysis
Container freight rates from Yangtze River Delta ports to North American distribution centers directly impact landed cost competitiveness for Asian producers. Supply concentrates in China, South Korea, and Vietnam for engineered slab manufacturing, drawing from high-purity silica deposits in Minnesota, Brazil, and India. Single-source vulnerability runs through polymer resin suppliers concentrated in Gulf Coast petrochemical corridors. Distribution runs through regional fabricator networks with localized cutting and edge-finishing capabilities serving metro construction markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where OSHA silica exposure limits and REACH chemical restrictions erect barrier-to-entry moats favoring resin-integrated incumbents with captive formulation capabilities.
For Market Incumbents: Anticipate sintered stone substitution threats in outdoor kitchen and commercial cooking segments by accelerating low-silica formulation R&D investments. Backward integration into Minnesota quartz mining or Gulf Coast resin production secures raw material continuity against petrochemical volatility. Certification documentation investments defend specification-grade positioning against emerging low-cost Asian entrants. For New Entrants and Emerging Players: Direct-to-fabricator digital platforms offer the most penetrable route for mid-market contractors seeking compressed lead times. White-space targets include recycled content certification for LEED-focused property developers and localized production in India's Gujarat Special Economic Zones. Go-to-market positioning should emphasize wet-cutting infrastructure partnerships to bypass OSHA compliance bottlenecks. For Investors and Strategic Acquirers: Re-rating potential sits with resin-integrated formulators given EMA and REACH compliance acceleration creating first-mover valuation premiums. Long-term viability favors manufacturers with captive quartz supply and bio-based resin alternatives. The signal to watch is regulatory reclassification debates across multiple jurisdictions that would cascade through mining, manufacturing, and installation liability frameworks.| Strategic Initiative | Industry Significance |
|---|---|
| Low-Silica Formulation R&D | OSHA and REACH compliance investments capture specification-intensive hospitality and healthcare project demand. |
| Captive Quartz Mining Integration | Minnesota deposit control secures raw material security against high-purity silica supply concentration risks. |
| Wet-Cutting Infrastructure Deployment | California and Texas fabrication shop investments reduce respiratory liability exposure while compressing regional competitor economics. |
| Recycled Content Certification | LEED contribution point systems attract sustainability-focused property developers in Texas and Florida multi-family segments. |
| Direct-to-Fabricator Digital Platforms | B2B marketplace bypass of distributor layers accelerates lead times for mid-size installation contractors. |
Research Methodology
Trade association filings, customs import records, and SEC 10-K disclosures formed the secondary backbone, cross-referenced against primary interviews with slab fabrication shop owners, resin supplier technical directors, and commercial contractor procurement leads. Bottom-up volume estimates from regional construction permit data triangulated against top-down market sizing from building materials distribution channels.
Historical trendline analysis of engineered stone specification rates across residential renovation cycles anchored the projection framework. Segmentation modeling spanned product type, installation site, and end-user procurement authority across the analysis window. CAGR derivation incorporated petrochemical resin price elasticity, silica regulatory compliance cost curves, and hospitality capital expenditure recovery patterns.
The model holds under stable OSHA enforcement intensity and REACH substance evaluation timelines; deviation in regulatory reclassification or resin supply disruption would shift volume and value trajectories. Stakeholders should weight assumptions against their own operating context and regional construction market exposure.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Alloys
Aramid Prepreg Market
Advanced Alloys
Global Shape Memory Alloys Market
Advanced Alloys
Prepreg Market
Advanced Alloys
Nitinol Market
Advanced Alloys
Oxide Dispersion Strengthened (ODS) Alloys Market
Advanced Alloys
Nickel Alloy Market
Advanced Alloys
Global Aluminum Foams Market
Advanced Alloys
Asia-Pacific Metal Casting Market
Advanced Alloys
Ultra High Strength Steel Market
Advanced Alloys
Nickel Superalloy Market
Advanced Alloys
Polymer Blends Alloys Market
Advanced Alloys
Automotive Aluminum Alloy (OE) Market
Advanced Alloys
Global High Performance Alloys Market
Advanced Alloys
Tungsten Alloy Market
Advanced Alloys
Europe Ceramic Ball Bearings Market
Advanced Alloys
Asia-Pacific Green Steel Market