
 Global High Performance Alloys Market | 2026-2036
Global High Performance Alloys Market Size, Share, and Industry Trends Forecast 2026-2036
Global High Performance Alloys Market Intelligence
The proliferation of metal additive manufacturing, specifically powder bed fusion, is rewriting the design and production of complex, high-stress components. Sandvik AB leverages its expertise in metal powders to supply materials optimized for 3D printing applications. Precision Castparts Corp sustains its market position through proprietary casting and forging technologies for critical aerospace parts. Carpenter Technology Corporation specializes in the development of custom alloy chemistries for niche, high-performance requirements.
High performance alloys are metallic materials engineered to exhibit superior mechanical strength, corrosion resistance, and stability at extreme temperatures. These alloys, often based on nickel, cobalt, or titanium, are essential for components operating in harsh environments where conventional metals would fail. Nickel alloys command the largest share due to their versatile use in power generation and chemical processing. Titanium alloys represent the fastest-growing product segment, driven by lightweighting initiatives in aerospace and defense applications.
Material certification and traceability are governed by stringent standards, including those from the US Federal Aviation Administration (FAA) and the EU's REACH regulations on chemical substances. These frameworks mandate rigorous testing and documentation, influencing material selection and supply chain management for critical applications. Producers must now balance the pursuit of enhanced material properties with the growing pressure to reduce the carbon footprint of their energy-intensive manufacturing processes.
Market Dynamics
The central dynamic shaping the market is the tension between achieving unprecedented material performance for extreme environments and reducing the carbon intensity of alloy production. This dual mandate impacts everything from raw material sourcing to final component certification for end-users in aerospace and power generation.
Growth Catalysts
- Additive Manufacturing Adoption:Powder bed fusion's use in aerospace creates demand for specialized metal powders for complex turbine components.
- Aerospace Lightweighting Mandates:Fuel efficiency initiatives in the US and France drive the specification of titanium alloys for new aircraft programs.
- Power Generation Upgrades:The push for higher efficiency in gas turbines necessitates nickel-based superalloys to withstand more extreme operating conditions.
Market Restraints
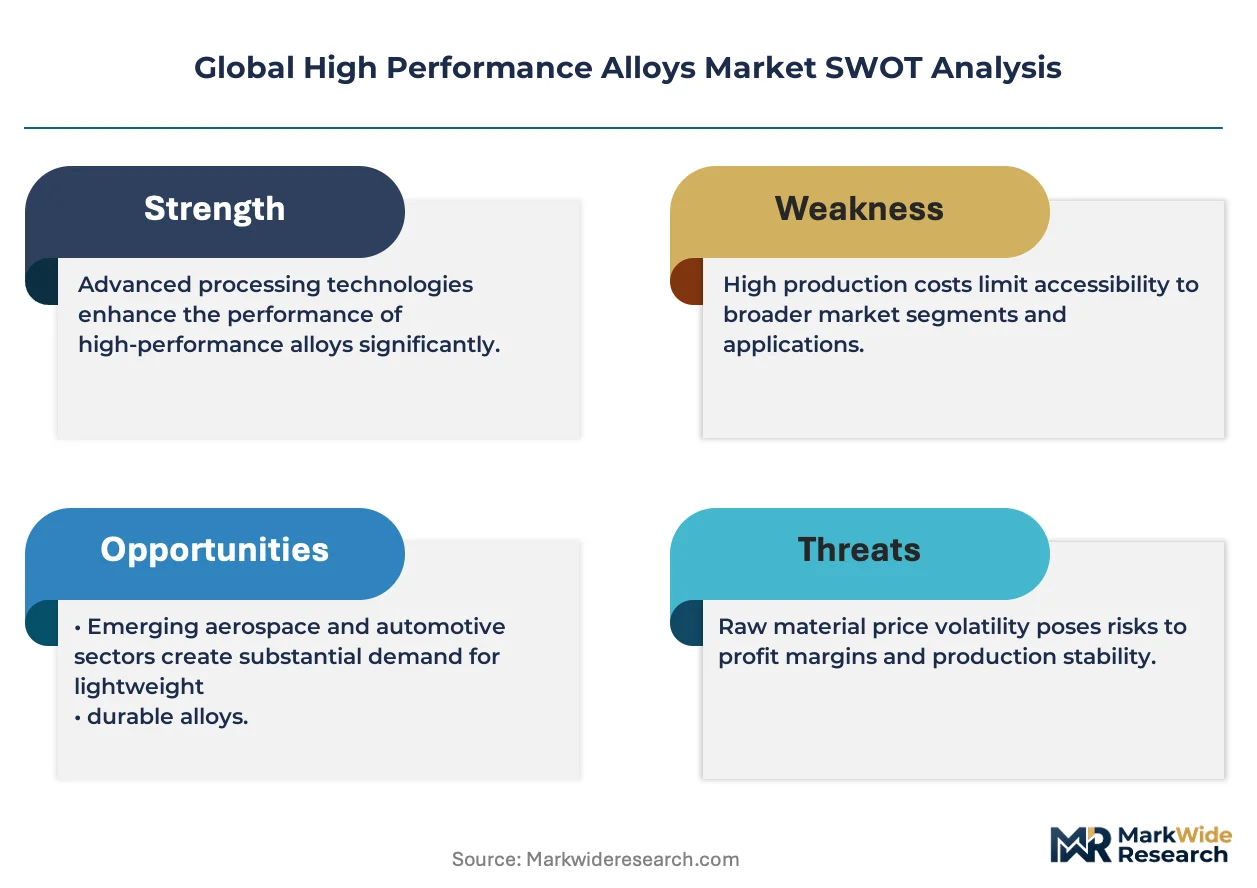
- Raw Material Volatility:The market faces price instability and supply concentration risk for key inputs like cobalt, nickel, and titanium ore.
- Energy-Intensive Production:High energy use in melting and forging increases operational costs and complicates compliance with emissions reduction targets.
- Prolonged Certification Cycles:Lengthy material qualification timelines from regulators like the FAA delay the adoption of new alloy formulations in aerospace.
Strategic Opportunities
- Medical Implant Market:Demand for orthopedic and dental implants creates an opening for biocompatible titanium and cobalt-chromium alloys.
- Alloys for Additive Manufacturing:Developing powders with tailored properties for 3D printing represents a key growth area beyond traditional mill products.
- Electric Vehicle Components:The automotive shift to EVs provides opportunities for lightweight alloys in battery casings, motor components, and vehicle frames.
Industry Challenges
- Talent and Skill Gaps:A shortage of metallurgists and process engineers with expertise in both traditional metallurgy and digital manufacturing techniques limits innovation and operational efficiency.
- Navigating Decarbonization and Compliance:Producers must make capital-intensive investments to reduce the carbon footprint of their operations while ensuring strict traceability for regulations like REACH.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global High Performance Alloys Market |
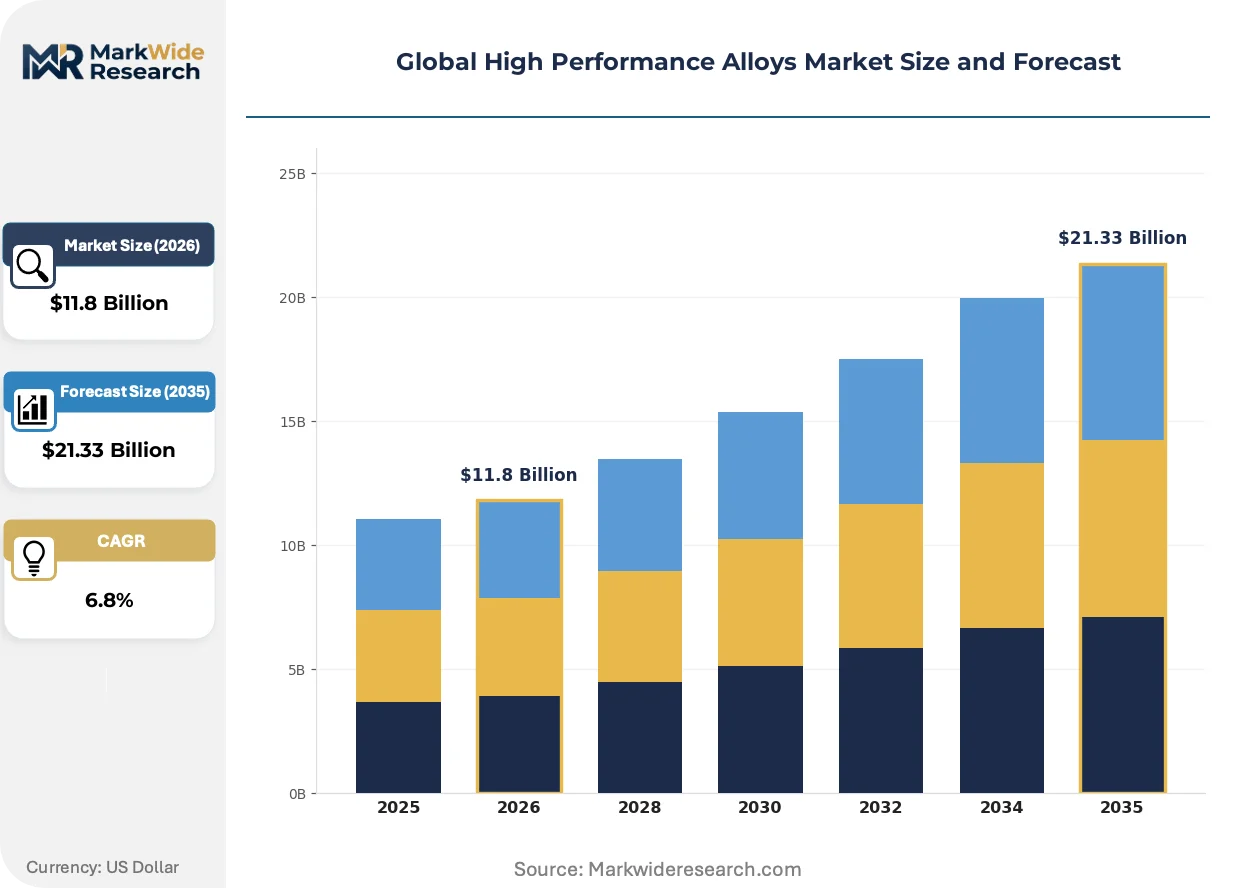
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $21.33 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nickel Alloys, Titanium Alloys, Cobalt Alloys, Aluminum Alloys, Iron-Based Alloys, Copper Alloys Form: Powder, Wire, Sheet, Plate, Tube, Bar Application: Aerospace & Defense, Power Generation, Chemical Processing, Marine Engineering, Electronics Manufacturing, Oilfield Equipment End User: Fabricators, Foundries, Machining Workshops, Component Manufacturers |
| Companies Covered | Sandvik AB, Precision Castparts Corp, Special Metals Corporation, Aperam, VSMPO-AVISMA Corporation, Allegheny Technologies Incorporated, Outokumpu Oyj, Thyssenkrupp AG, Carpenter Technology Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global High Performance Alloys Market Strategic Shifts & Innovations
The intersection of materials science and data-driven process control is redefining alloy development and production. This shift moves beyond empirical testing toward predictive modeling, accelerating the creation of materials with precisely engineered properties for demanding applications.
Integrated Computational Materials Engineering (ICME) uses physics-based models to predict alloy behavior from its chemical composition and processing history. Aerospace and defense firms increasingly use ICME to shorten development timelines for new materials. This methodology is virtualizing the costly and time-consuming physical experimentation phase, enabling faster material qualification and innovation for critical components.
European Union regulations like the Corporate Sustainability Reporting Directive (CSRD) compel producers to provide detailed environmental disclosures. This mandate requires alloy manufacturers to track and report the full lifecycle carbon footprint of their products. Consequently, producers of energy-intensive nickel and titanium alloys are investing in cleaner production technologies and improved data systems to maintain access to the European market.
A preference for circular economy models is altering material sourcing within the aerospace sector. Buyers are prioritizing long-term agreements with suppliers who manage closed-loop recycling, reclaiming valuable scrap from machining operations. This shift is most visible in the United States and France, where engine manufacturers seek to secure supply chains and recover the value of titanium and nickel alloy waste.
Global High Performance Alloys Market Segmentation
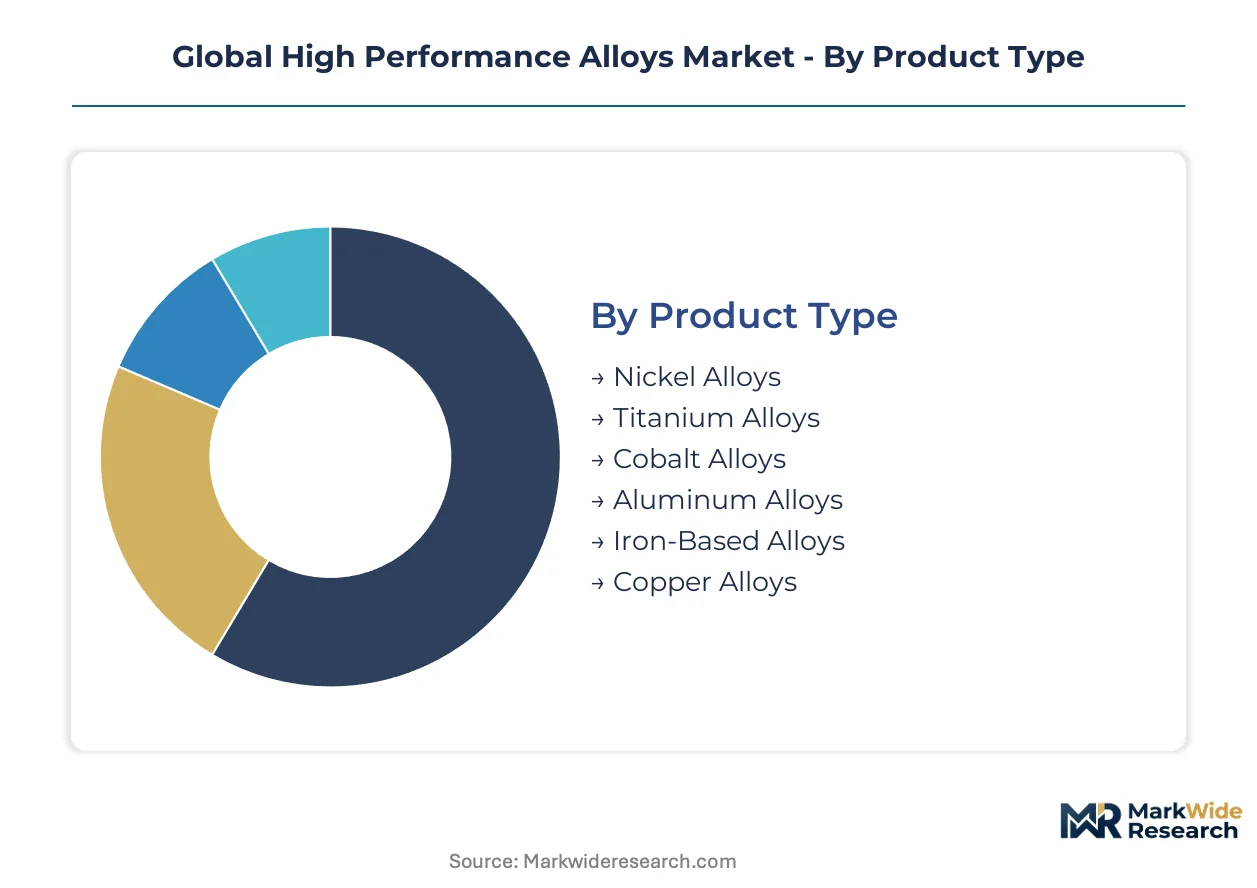
Understanding the distinct segments within the global high performance alloys market is crucial for identifying areas of concentrated demand and technological advancement. This granular breakdown reveals how material properties, processing forms, end-use applications, and customer types collectively shape market dynamics and value creation.
Product Type:
The product type segment illustrates a market with both established, mature alloy chemistries and rapidly evolving material innovations.
- Nickel Alloys:These materials are characterized by exceptional strength, corrosion resistance, and thermal stability, making them indispensable in extreme environments. Demand is concentrated in power generation and chemical processing sectors across the United States and Germany, driven by the need for components that withstand high temperatures and aggressive media.
- Titanium Alloys:Known for their high strength-to-weight ratio and excellent biocompatibility, titanium alloys are critical for lightweighting initiatives and medical applications. Specification is accelerating in aerospace and defense programs in France and China, as well as in the global orthopedic implant market.
- Cobalt Alloys:These alloys offer superior wear resistance and high-temperature strength, often used in medical devices and industrial gas turbines.
- Aluminum Alloys:Valued for their light weight and good strength, these alloys see extensive use in aerospace and automotive structures where fuel efficiency is paramount.
- Iron-Based Alloys:Offering a balance of strength, cost-effectiveness, and corrosion resistance, they are fundamental in various industrial applications.
- Copper Alloys:These materials provide excellent electrical and thermal conductivity, alongside good corrosion resistance, making them vital for electronics and marine environments.
Nickel Alloys retains volume leadership; Titanium Alloys holds the steepest expansion curve.
Form:
The form segment reflects the diverse manufacturing processes and component geometries required by end-use industries, from raw materials to semi-finished products.
- Powder:This form is increasingly critical for additive manufacturing processes, enabling the creation of complex geometries with high material utilization. Aerospace and medical implant manufacturers in the US and Germany are driving demand for specialized metal powders with precise particle size distribution and chemical purity.
- Sheet:High performance alloy sheets are essential for fabricating structural components and heat shields that require high strength and formability. Automotive and aerospace applications, particularly in Japan and the UK, specify alloy sheets for lightweight chassis and airframe elements.
- Wire:Used in welding, springs, and fasteners, high performance alloy wire offers properties like corrosion resistance and high tensile strength.
- Plate:Thick sections of alloy plate are utilized in heavy industrial equipment, pressure vessels, and armor applications requiring robust structural integrity.
- Tube:High performance alloy tubes are critical for heat exchangers, fluid transport systems, and structural elements in corrosive or high-temperature environments.
- Bar:This form serves as a foundational material for machining into shafts, fasteners, and other precision components across various industries.
Powder forms are gaining share fastest; Sheet and Plate products maintain significant volume.
Application:
The application segment highlights the specific end-use sectors where high performance alloys are indispensable due to their unique properties.
- Aerospace & Defense:This sector demands alloys capable of withstanding extreme temperatures, high stress, and corrosive environments for jet engines, airframes, and missile components. Fuel efficiency mandates in the US and France directly influence the specification of advanced titanium and nickel alloys for new aircraft programs.
- Power Generation:High performance alloys are vital for gas turbines, nuclear reactors, and other energy infrastructure where materials must endure high heat, pressure, and corrosive gases. The push for higher efficiency in gas turbines, particularly in Germany and China, necessitates advanced nickel-based superalloys.
- Chemical Processing:Alloys with superior corrosion resistance are essential for reactors, pipes, and vessels handling aggressive chemicals and high temperatures.
- Marine Engineering:This application requires materials resistant to saltwater corrosion and biofouling for shipbuilding, offshore platforms, and subsea equipment.
- Electronics Manufacturing:High-purity alloys are used in semiconductor fabrication, connectors, and electronic packaging for their specific electrical and thermal properties.
- Oilfield Equipment:Alloys capable of resisting high pressure, high temperature, and corrosive downhole conditions are critical for drilling and extraction tools.
Aerospace & Defense applications command the largest market share; Electronics Manufacturing shows strong potential for future expansion.
End User:
The end user segment categorizes the direct customers who purchase high performance alloys for further processing or component manufacturing.
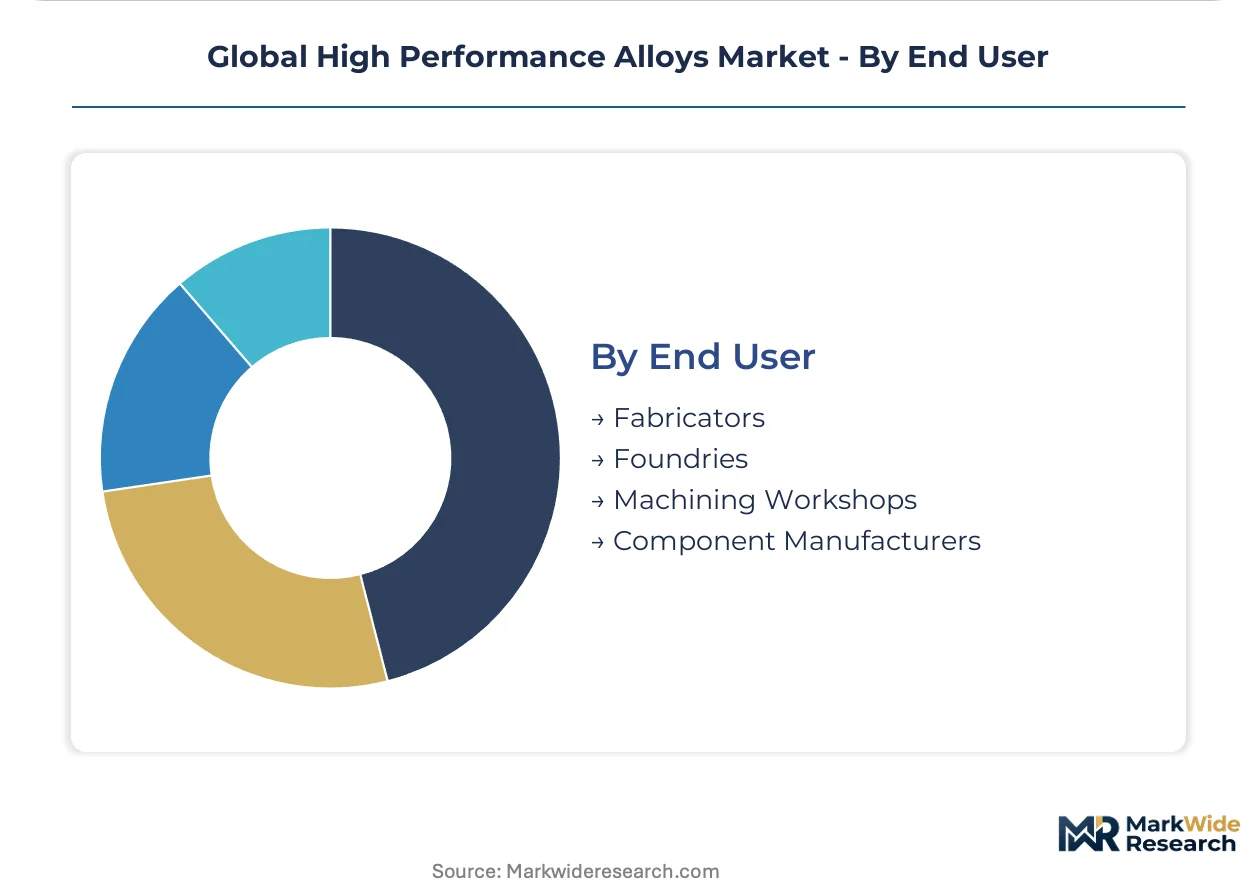
- Component Manufacturers:These entities procure alloys to produce finished parts for various industries, often requiring specific material certifications and tight tolerances. Aerospace engine component manufacturers in the US and UK represent a significant portion of this segment, demanding highly specialized nickel and titanium alloys.
- Foundries:Foundries specialize in casting complex alloy shapes, providing near-net-shape components that reduce subsequent machining and material waste. Investment casting foundries serving the power generation sector globally are key customers for high performance alloy ingots and master alloys.
- Fabricators:Fabricators transform semi-finished alloy forms into structures, assemblies, and custom parts through processes like welding, bending, and cutting.
- Machining Workshops:These workshops process alloy bars, plates, and tubes into precision components using advanced machining techniques.
Component Manufacturers drive the largest volume; Foundries are critical for specialized component production.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global high performance alloys market exhibits a complex export-import balance, with established production hubs supplying specialized materials to diverse manufacturing sectors worldwide. Demand for advanced alloys often outstrips local production capabilities in rapidly industrializing economies, driving international trade flows. Specific regulatory frameworks and industrial concentrations shape material specification and procurement patterns across different regions.
United States
Aerospace and defense programs, alongside power generation upgrades, drive significant demand for nickel and titanium alloys in the United States. The US Federal Aviation Administration (FAA) mandates stringent material certification, influencing alloy development and supply chain practices. Major aerospace manufacturing clusters in Seattle, Washington, and Wichita, Kansas, actively procure specialized high performance alloys for critical components.
Germany
Germany's robust power generation and chemical processing sectors create consistent demand for nickel alloys, known for their thermal stability and corrosion resistance. European Union regulations like REACH and the Corporate Sustainability Reporting Directive (CSRD) compel manufacturers to prioritize sustainable production and traceability. The industrial region of North Rhine-Westphalia, with its strong engineering base, represents a key consumption area for these advanced materials.
France
Aerospace lightweighting initiatives in France strongly influence the specification of titanium alloys for new aircraft designs. French engine manufacturers, adhering to EU environmental standards, seek materials with enhanced fuel efficiency properties. Toulouse, a primary hub for aerospace manufacturing, actively integrates advanced high performance alloys into airframe and engine production.
China
China's expanding aerospace industry and ambitious power generation projects fuel the demand for both titanium and nickel-based superalloys. The country's dual carbon goals promote the adoption of more efficient gas turbines, requiring high-temperature resistant materials. Industrial zones around Shanghai and Xi'an are becoming significant centers for high performance alloy consumption in critical applications.
Japan
Japanese automotive and aerospace manufacturers demand high performance alloy sheets for lightweight structures and high-stress components. METI initiatives encourage material innovation and process optimization within the country's advanced manufacturing sector. The Chubu region, home to major automotive and aerospace suppliers, concentrates significant demand for these specialized materials.
Global High Performance Alloys Market Key Industry Players
On the supply side, the industry is characterized by a mix of large, diversified materials companies and specialized alloy producers. These entities often compete through technological differentiation and proprietary processing capabilities. Strategic archetypes include integrated producers focusing on raw material conversion, specialized powder manufacturers for additive manufacturing, and custom alloy developers. Competitive moves frequently involve capacity expansion to meet aerospace demand and strategic partnerships for material certification.
Specialized alloy developers, such as Carpenter Technology Corporation, focus on creating custom chemistries for niche, high-performance requirements across various industries. Integrated materials companies like Sandvik AB leverage their expertise in metal powders to supply materials optimized for advanced manufacturing processes. Precision Castparts Corp exemplifies a major player sustaining its market position through proprietary casting and forging technologies essential for critical aerospace parts.
| Leading Market Players |
|---|
| Sandvik AB |
| Precision Castparts Corp |
| Special Metals Corporation |
| Aperam |
| VSMPO-AVISMA Corporation |
| Allegheny Technologies Incorporated |
| Outokumpu Oyj |
| Thyssenkrupp AG |
| Carpenter Technology Corporation |
| Others |
Cost & Logistics Intelligence
Raw material volatility for cobalt, nickel, and titanium creates upstream concentration that directly influences margin pools for high performance alloy producers. Geopolitical factors and energy-intensive production methods further shape the cost structure and material availability for critical applications.
Pricing Analysis
Industrial OEM buyers anchor contract-based pricing in the high performance alloys market. Price differentiation stems from stringent material certification levels, such as FAA approval, and the degree of custom alloy development required. Pricing softness runs through standard industrial grades due to increased competition and cost pressures from end-users pursuing efficiency. Aerospace and defense manufacturers demonstrate the least price sensitivity, prioritizing performance and reliability over cost for critical components.
Supply Chain Analysis
Upstream feedstock for high performance alloys faces significant geographic concentration, particularly for key inputs like cobalt from the Democratic Republic of Congo, nickel from Indonesia, and titanium ore from Australia. The market relies heavily on specialized raw material suppliers and refiners. Commodity price volatility for these critical inputs presents a structural supply chain risk. Distribution runs through a mix of direct sales to large component manufacturers and specialized distributors serving niche applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The high performance alloys market is experiencing a buyer-power shift, driven by consolidating aerospace engine component manufacturers demanding greater supply chain transparency and material performance guarantees.
For Market Incumbents: Insulate core market positions through continuous investment in advanced processing technologies like powder bed fusion. Develop proprietary alloy chemistries that meet evolving regulatory standards, such as EU's REACH. Invest in cleaner production technologies to mitigate carbon footprint pressure from directives like CSRD. Deepen relationships with key aerospace and power generation OEMs through long-term supply agreements and joint R&D initiatives.
For New Entrants and Emerging Players: Underpenetration in emerging medical and electric vehicle applications offers significant growth avenues. Target the specialized metal powder segment for additive manufacturing, focusing on tailored properties for orthopedic implants or EV battery casings. A go-to-market angle focused on rapid prototyping and custom small-batch alloy development can penetrate niche, high-value segments. Leverage material science expertise to address specific lightweighting and biocompatibility requirements.
For Investors and Strategic Acquirers: Capital is best deployed toward specialized alloy developers with a strong intellectual property portfolio in advanced material chemistries or unique processing capabilities. Prioritize companies with established certifications for critical industries like aerospace and medical devices for long-term viability. A signal to watch is the accelerated adoption of new alloy formulations in next-generation aircraft programs or electric vehicle platforms.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for Titanium Alloys | Increases supply for lightweighting initiatives in aerospace and defense programs. |
| Green Manufacturing Transition | Reduces carbon footprint of energy-intensive nickel alloy production for European market access. |
| R&D in Advanced Alloy Chemistries | Accelerates material development for additive manufacturing and extreme environment applications. |
| Long-term Supply Agreements for Raw Materials | Mitigates commodity price volatility and secures critical input availability for producers. |
| Certification Investment for New Materials | Ensures compliance with stringent regulatory frameworks like FAA for aerospace components. |
Research Approach
A spread of perspectives from metallurgists, aerospace engineers, procurement managers, and regulatory specialists converged on the working assumptions for the high performance alloys market. This involved combining insights from primary interviews with extensive secondary validation. Data sources included FAA guidelines, REACH regulations, corporate sustainability reports, and industry association publications, triangulated using both bottom-up and top-down approaches.
Demand-supply balance projections inform the quantitative framework applied across the analysis window. The model incorporates segmentation dimensions such as product type, form, end-use application, customer type, and regional market penetration. CAGRs were derived from historical trends and projected technological adoption rates, with key inputs including new aircraft program schedules and electric vehicle production forecasts.
Practitioners should monitor raw material price fluctuations and geopolitical trade policies for early signals of market shifts. Forecasts reflect assumptions regarding technological advancements and regulatory stability. Cross-checking against independent aerospace and defense spending reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Alloys
Powder Metallurgy Components Market
Advanced Alloys
North America Green Steel Market
Advanced Alloys
North America Braze Alloys Market
Advanced Alloys
Plastic-Metal Hybrids Market
Advanced Alloys
Middle East and Africa Aluminum Casting Market
Advanced Alloys
Global Ti-6Al-4V Titanium Alloy Market
Advanced Alloys
Global Aluminum Alloys Market
Advanced Alloys
Iron Gallium Alloy (Galfenol) Market
Advanced Alloys
Tungsten Alloy Market
Advanced Alloys
Green Steel Market
Advanced Alloys
Global Metal Foams Market
Advanced Alloys
Welding Alloys Market
Advanced Alloys
Cermet Market
Advanced Alloys
Europe Aluminum Casting Market
Advanced Alloys
Thulium Silicide Market
Advanced Alloys
Nickel Superalloy Market